
 Fatty Alcohol Alkoxylates Market | 2026-2036
Fatty Alcohol Alkoxylates Market Size, Share, and Industry Trends Forecast 2026-2036
Fatty Alcohol Alkoxylates Market Analysis
Specialty chemical distribution channels in emerging economies is rewriting how fatty alcohol alkoxylates reach end users. BASF SE leverages its integrated ethylene oxide feedstock position to sustain cost advantages across Asian markets. Croda International Plc anchors its competitiveness through biotechnology-derived alcohol feedstocks that differentiate its product portfolio. Huntsman Corporation navigates regional regulatory complexity by operating dedicated formulation labs in key consumption clusters.
Fatty alcohol alkoxylates are nonionic surfactants synthesized by reacting fatty alcohols with alkylene oxides, typically yielding ethoxylates or propoxylates with hydrophilic-lipophilic balance values between 10 and 16, designed to reduce surface tension in aqueous systems. Their primary commercial purpose spans detergency, wetting, emulsification, and dispersion across formulated consumer and industrial products. Alcohol ethoxylates occupy the largest volume position due to decades of proven performance in laundry and dish formulations, while branched alcohol alkoxylates represent the fastest-expanding category as manufacturers seek cold-water solubility and hard-surface cleaning efficacy. The liquid form dominates operational logistics for industrial cleaning and textile processing applications where bulk handling infrastructure already exists.
EPA regulations on 1,4-dioxane content in cleaning products and REACH restrictions on hazardous surfactant precursors are reshaping formulation specifications and raw material qualification protocols in North America and Europe. India's BIS standards for household cleaning chemicals and China's GB standards for industrial surfactants add compliance layers that favor producers with multi-regional certification capabilities. Stakeholders must monitor how biobased feedstock certification schemes and carbon border adjustments alter cost structures for petrochemical-derived versus oleochemical-derived alkoxylate supply chains.
Market Dynamics
EPA standards on 1,4-dioxane residuals and REACH restrictions on hazardous surfactant precursors are forcing manufacturers toward catalytic process redesigns that eliminate ethoxylation byproducts without sacrificing throughput economics.
Growth Catalysts
- Cold-water laundry detergency:Branched alcohol alkoxylates enable effective soil removal below 20°C, aligning with household energy conservation mandates across Northern European markets.
- REACH Annex XVII amendments:Restrictions on NPEO (nonylphenol ethoxylate) surfactants are redirecting formulators toward fatty alcohol ethoxylates as drop-in replacements in textile wetting applications.
- India's PLI scheme for specialty chemicals:Domestic manufacturers are qualifying for production-linked incentives that offset capital costs for alkoxylation capacity expansion.
Market Restraints
- Ethylene oxide feedstock volatility:Price swings in C2 derivatives compress margin predictability for integrated producers and merchant alkoxylators alike.
- Specialty catalyst supply concentration:Narrow-spectrum magnesium oxide catalysts for low-dioxane processes originate from a limited supplier base in East Asia.
- Propylene oxide substitution economics:Propoxylated alcohols face cost disadvantages versus ethoxylates in standard detergency applications, constraining category expansion.
Strategic Opportunities
- Vietnam personal care manufacturing:Contract manufacturers serving ASEAN brands lack local alkoxylate supply, creating white space for toll production arrangements.
- Biobased carbon-14 certification:ASTM D6866 verification enables premium positioning of oleochemical-derived ethoxylates for cosmetics brands with net-zero commitments.
- Supercritical CO2 ethoxylation:This solvent-free process technology converges with continuous-flow reactor design to eliminate pressure vessel scaling constraints.
Industry Challenges
- Process safety engineering talent:Alkylene oxide handling expertise has atrophied in Western chemical engineering programs, complicating plant commissioning.
- Multi-regional dossier compilation:Simultaneous EPA PMN notification, REACH registration, and BIS conformity assessment stretch regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fatty Alcohol Alkoxylates Market |
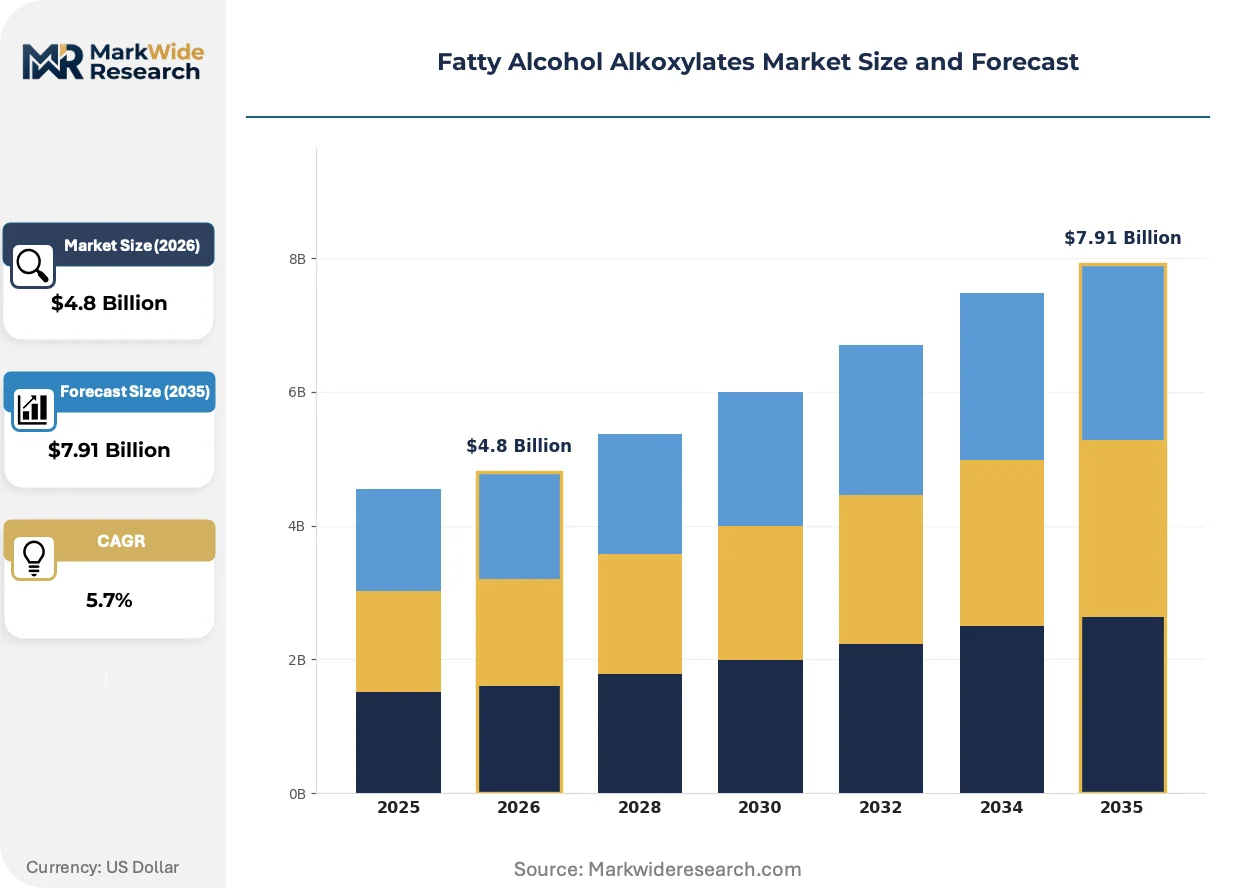
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Alcohol Alkoxylates, Branched Alcohol Alkoxylates, Alcohol Ethoxylates, Alcohol Propoxylates Application: Personal Care, Household Cleaning, Industrial Cleaning, Textile Processing End User: Cosmetics Industry, Cleaning Products Manufacturers, Textile Industry, Food Processing Form: Liquid, Powder, Granules, Emulsions |
| Companies Covered | SASOL, Huntsman Corporation, BASF SE, Procter and Gamble Chemicals, Clariant International AG, Croda International Plc, Stepan Company, Ineos, KLK OLEO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fatty Alcohol Alkoxylates Market Emerging Trajectories
Formulation science is pivoting toward molecular precision—tailored ethylene oxide distribution profiles and narrow-range alkoxylation—replacing commodity surfactant specifications with performance-guaranteed grades.
Membrane-based ethylene oxide purification is virtualizing traditional distillation trains in new alkoxylation facilities. Personal care compounders in South Korea are specifying narrow-cut ethoxylates with polydispersity indices below 1.1, paying 15-20% premiums for batch-to-batch consistency. This precision chemistry is virtualizing the specification sheets that once governed commodity surfactant procurement.
REACH restrictions on substances of very high concern are tightening impurity thresholds for 1,4-dioxane in cleaning products sold across EU member states. Manufacturers must now validate sub-10 ppm residuals through third-party testing protocols recognized by ECHA. The industrial and institutional cleaning segment is responding fastest, reformulating hard-surface cleaners ahead of consumer product deadlines.
Brand procurement teams are consolidating surfactant suppliers to reduce qualification overhead, reversing the multi-sourcing strategies of the past decade. Specialty chemical distributors in Southeast Asia are capturing this consolidation by offering bundled alkoxylate-cosolvent packages with technical service attachments. This supplier rationalization is most visible in Thailand's household cleaning manufacturing corridor, where formulators have halved their approved vendor lists since 2022.
Fatty Alcohol Alkoxylates Market Segmentation
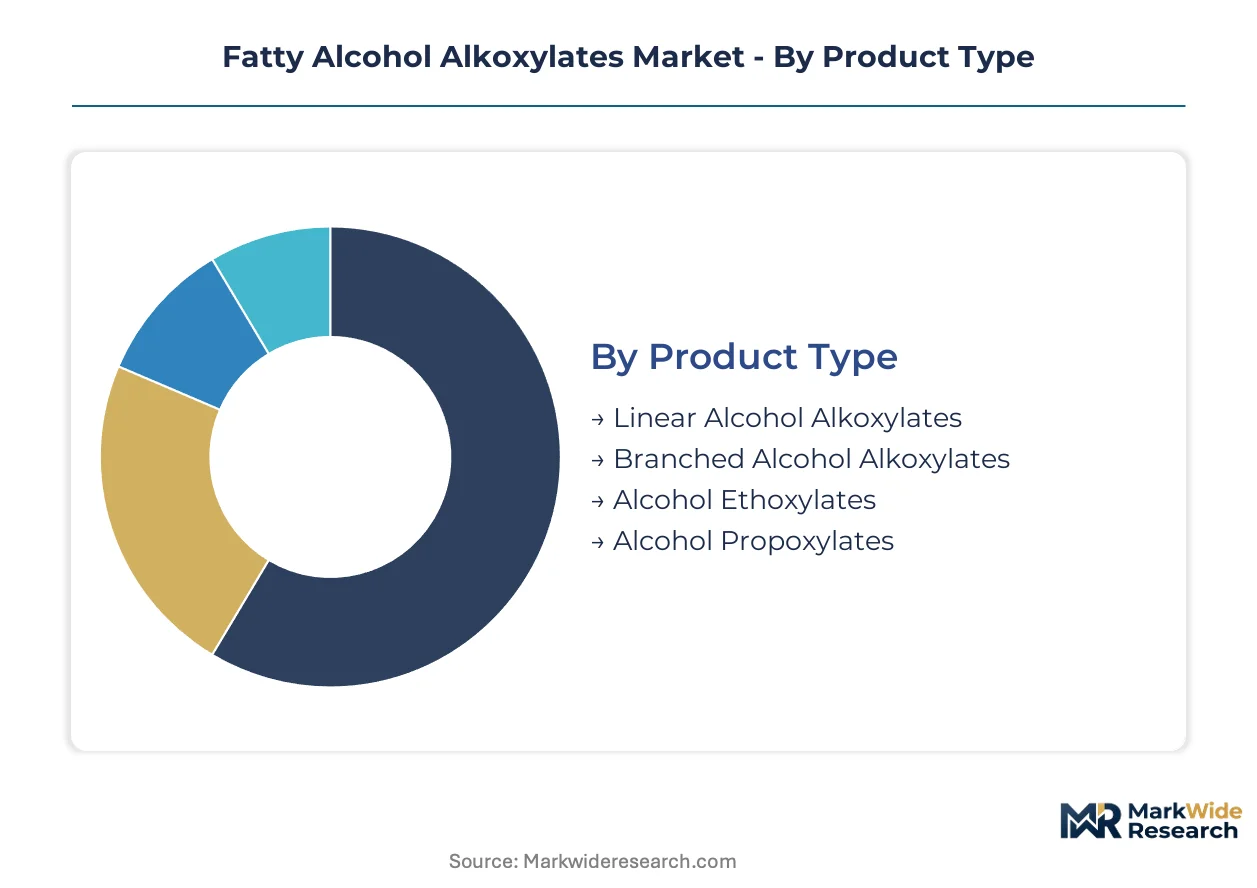
Fatty alcohol alkoxylates serve distinct performance requirements across formulation chemistries, procurement cycles, and regulatory compliance tiers. Understanding segment turnover velocity and margin architecture enables suppliers to align capacity investments with demand patterns that vary significantly by end-use specification.
Product Type:
Inventory velocity diverges sharply across this category—commodity ethoxylates turn monthly while specialty propoxylates and narrow-cut grades operate on quarterly procurement cycles.
- Alcohol Ethoxylates:These ethylene oxide adducts of C12-C18 fatty alcohols deliver the workhorse surfactancy for laundry and dish formulations, with hydrophilic-lipophilic balance values tunable between 12 and 14. Procurement concentrates among Indian household cleaning manufacturers localizing supply chains under BIS standards, though REACH Annex XVII restrictions on NPEO surfactants are accelerating qualification timelines for European textile wetting applications.
- Branched Alcohol Alkoxylates:Guerbet and oxo-alcohol derived structures achieve superior cold-water solubility below 20°C through steric disruption of crystalline packing. Northern European formulators specify these grades for energy-conserving laundry mandates, paying formulation premiums that reflect their hard-surface cleaning efficacy in institutional applications.
- Linear Alcohol Alkoxylates:Straight-chain C12-C14 feedstocks from oleochemical or petrochemical sources provide predictable biodegradation profiles for eco-label compliance.
- Alcohol Propoxylates:Propylene oxide derivatives offer lower foam and enhanced oil solubility for metalworking fluid and agrochemical emulsion applications.
Alcohol ethoxylates anchor the volume base while branched alcohol alkoxylates gain share at the steepest rate.
Application:
Margin tiers separate dramatically here—personal care commands specification premiums while industrial cleaning operates on cost-plus contracts with annual renegotiation cycles.
- Household Cleaning:Laundry detergents, dishwashing liquids, and hard-surface cleaners consume standardized ethoxylate grades where EPA 1,4-dioxane thresholds and REACH SVHC restrictions are forcing process redesign investments. India's domestic manufacturers are expanding alkoxylation capacity under PLI scheme incentives to capture this demand locally.
- Personal Care:Shampoos, facial cleansers, and bath products require narrow-range ethoxylates with polydispersity indices below 1.1 for batch-to-batch sensory consistency. South Korean compounders specify these precision grades, paying 15-20% premiums that reflect cosmetic brand procurement consolidation and reduced vendor qualification overhead.
- Industrial Cleaning:Degreasers, metal finishing formulations, and transportation cleaners prioritize cost efficiency over molecular precision.
- Textile Processing:Scouring, dyeing, and finishing applications favor low-foam alkoxylates for continuous processing equipment.
Household cleaning commands the largest absolute volume while personal care delivers the highest margin per kilogram.
End User:
Customer concentration patterns define this segmentation—multinational cosmetics houses consolidate suppliers while fragmented textile processors maintain spot-market purchasing flexibility.
- Cleaning Products Manufacturers:Formulators of laundry detergents, surface disinfectants, and institutional sanitation products drive standard-grade ethoxylate demand with specifications governed by GB standards in China and BIS norms in India. Thailand's manufacturing corridor has halved approved vendor lists since 2022, consolidating procurement around distributors offering bundled alkoxylate-cosolvent packages.
- Cosmetics Industry:Multinational beauty brands and ASEAN contract manufacturers specify biobased carbon-14 certified grades for net-zero commitments, requiring ASTM D6866 verification that oleochemical-derived feedstocks provide. Vietnam's personal care manufacturing sector lacks local alkoxylation capacity, creating toll production opportunities for regional suppliers.
- Textile Industry:Fabric processors and garment finishers operate on thinner margins with price-sensitive procurement.
- Food Processing:Equipment cleaners and processing aids require regulatory clearances for incidental contact applications.
Cleaning products manufacturers represent the deepest demand pool while cosmetics industry qualification requirements create the stickiest supplier relationships.
Form:
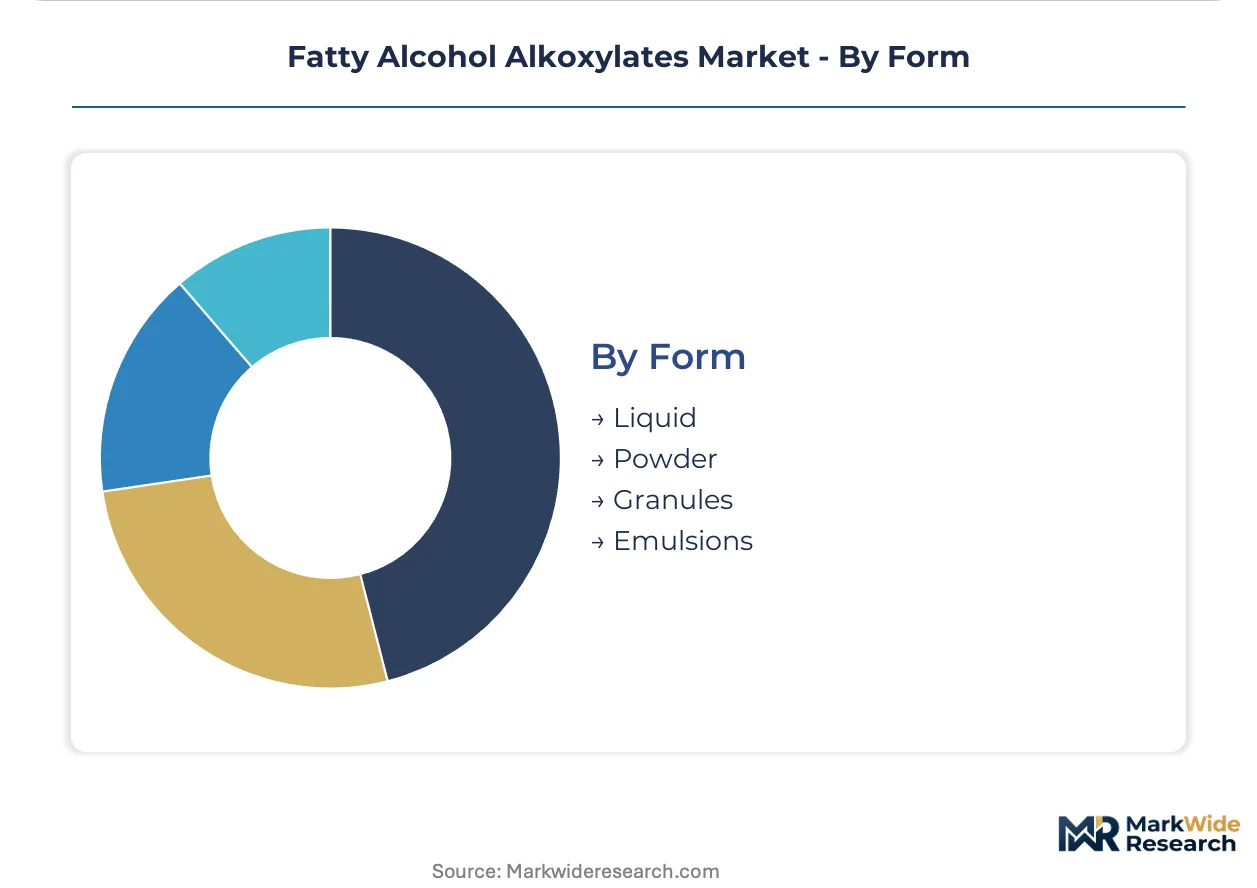
Supply chain infrastructure investments have locked in format preferences—liquid handling systems dominate established manufacturing corridors while powder formats serve emerging markets with limited bulk storage.
- Liquid:Bulk tanker delivery of aqueous ethoxylate solutions minimizes handling costs for industrial cleaning and textile processing operations with established pumping and storage infrastructure. Southeast Asian distributors capture value through technical service attachments for liquid formulation optimization.
- Powder:Spray-dried and agglomerated grades enable long-haul distribution to regions lacking alkoxylation capacity, with packaging flexibility for small-batch compounders.
- Granules:Low-dust handling characteristics suit automated dosing systems in large-scale detergent manufacturing.
- Emulsions:Pre-dispersed formats reduce formulation complexity for personal care compounders with limited heating capabilities.
Liquid formats dominate established manufacturing clusters while powder grades expand most quickly in infrastructure-constrained emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's integrated chemical handling infrastructure anchors Europe's alkoxylate import and distribution architecture, while Singapore's Jurong Island petrochemical cluster serves as the primary blending and re-export hub for Southeast Asian formulations.
United States
EPA enforcement of sub-10 ppm 1,4-dioxane thresholds in household cleaning products drives catalytic process retrofits among Gulf Coast alkoxylators. The Toxic Substances Control Act Section 5 pre-manufacture notification requirements extend qualification timelines for new ethoxylate grades. Houston's specialty chemical corridor concentrates toll manufacturing capacity serving institutional cleaning formulators.
Germany
REACH Annex XVII restrictions on NPEO surfactants redirect textile wetting demand toward fatty alcohol ethoxylates with documented biodegradation profiles. ECHA's dossier evaluation protocols enforce rigorous substance identity verification for imported alkoxylate blends. Ludwigshafen's integrated chemical parks sustain cost-competitive ethoxylation through captive ethylene oxide supply.
China
GB standards for industrial surfactants mandate compliance testing for alkoxylates used in textile processing and metal cleaning applications. The country's dual carbon goals pressure oleochemical feedstock sourcing toward sustainable palm oil certification schemes. Yangtze River Delta detergent manufacturers expand alkoxylation capacity to reduce import dependence for narrow-cut ethoxylates.
India
BIS standards for household cleaning chemicals create domestic qualification barriers that favor local alkoxylate production under the PLI scheme for specialty chemicals. Maharashtra's chemical manufacturing belt attracts capacity investments from multinational surfactant suppliers seeking tariff-advantaged supply to South Asian markets. Mumbai-Pune corridor formulators consolidate procurement around distributors offering bundled technical service packages.
Vietnam
ASEAN contract manufacturers for personal care brands lack indigenous alkoxylation infrastructure, creating toll production opportunities for regional suppliers. The country's national chemical safety regulator enforces registration requirements for imported surfactant raw materials. Ho Chi Minh City's manufacturing zone concentrates cosmetic compounders specifying biobased carbon-14 certified grades for export markets.
Fatty Alcohol Alkoxylates Market Vendor Landscape
On the supply side, the industry is consolidating around integrated petrochemical majors and specialized oleochemical processors with backward integration into fatty alcohol feedstocks. Three archetypes dominate: integrated ethylene oxide producers with captive alkoxylation, biotechnology-derived alcohol specialists, and toll manufacturers serving regional formulation clusters. Competitive moves center on catalytic process licensing for low-dioxane production and multi-regional certification dossier compilation.
Among European-headquartered multinationals, BASF SE and Croda International Plc occupy distinct positioning archetypes—BASF exemplifying integrated petrochemical scale while Croda represents biotechnology-derived feedstock differentiation. Huntsman Corporation anchors North American capability with dedicated formulation laboratories in key consumption clusters. These three entities collectively illustrate the strategic segmentation between commodity ethoxylate supply and specialty alkoxylate qualification.
| Leading Market Players |
|---|
| SASOL |
| Huntsman Corporation |
| BASF SE |
| Procter and Gamble Chemicals |
| Clariant International AG |
| Croda International Plc |
| Stepan Company |
| Ineos |
| KLK OLEO |
| Others |
Supply Flow & Price Mechanics
East Asian magnesium oxide catalyst suppliers anchor the upstream cost structure for low-dioxane ethoxylation processes, concentrating margin capture among integrated petrochemical majors with captive ethylene oxide supply. This feedstock-catalyst interdependence shapes how specialty alkoxylate grades achieve premium positioning against commodity alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement contracts in this market. Premium narrow-cut ethoxylates with polydispersity indices below 1.1 command formulation premiums from South Korean personal care compounders, while standard-grade alcohol ethoxylates face cost compression from Indian domestic manufacturers scaling under PLI incentives. Price differentiation hinges on certification grade and volume scale. Margins are tightening due to ethylene oxide feedstock volatility. Industrial cleaning formulators exhibit highest price sensitivity; cosmetics brands demonstrate lowest.
Supply Chain Analysis
Extended payment terms from specialty chemical distributors in Southeast Asia are restructuring working capital requirements for alkoxylate procurement. Manufacturing concentrates in Germany, China, and India, with Ludwigshafen's integrated chemical parks, Yangtze River Delta detergent corridors, and Maharashtra's manufacturing belt serving as primary production nodes. The supply chain draws from fatty alcohol feedstocks, ethylene oxide, and narrow-spectrum catalysts. Single-source vulnerability around East Asian catalyst suppliers poses structural risk. Distribution runs through regional distributors offering bundled technical service packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where multi-regional certification dossiers function as interoperability tokens, determining supplier access to formulation ecosystems across EPA, REACH, and BIS jurisdictions.
For Market Incumbents: Harden catalytic process positions through licensing low-dioxane technologies to merchant alkoxylators facing EPA enforcement deadlines. Consolidate formulation laboratory capabilities in Vietnam and Thailand to capture ASEAN contract manufacturing demand before regional capacity emerges. Vertical integration into biobased carbon-14 certification systems defends margin pools against oleochemical feedstock competitors. For New Entrants and Emerging Players: Build out toll production arrangements serving Vietnam's personal care manufacturing corridor, where indigenous alkoxylation infrastructure remains absent. Target India's domestic cleaning product manufacturers localizing supply chains under BIS standards and PLI incentives. Narrow-range ethoxylate qualification for South Korean cosmetics compounders offers the most penetrable entry vector. For Investors and Strategic Acquirers: Capital is best deployed toward biotechnology-derived alcohol specialists with ASTM D6866 verification capabilities and established REACH registration dossiers. Long-term viability across the analysis window favors producers with backward integration into sustainable palm oil certification schemes. Watch for carbon border adjustment mechanism announcements as the critical inflection signal for petrochemical versus oleochemical feedstock economics.| Strategic Initiative | Industry Significance |
|---|---|
| Catalytic Process Licensing | Low-dioxane technology transfers capture EPA compliance-driven retrofit demand from merchant alkoxylators. |
| Backward Integration | In-house ethylene oxide production insulates margin predictability from C2 derivative price volatility. |
| Biobased Certification | ASTM D6866 verification unlocks premium positioning for cosmetics brands with net-zero commitments. |
| Regional Formulation Labs | Dedicated facilities in Ho Chi Minh City and Bangkok reduce qualification timelines for ASEAN contract manufacturers. |
| Long-term Supply Agreement | Multi-year offtake contracts with Indian PLI-qualified producers secure tariff-advantaged South Asian access. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with plant managers at integrated alkoxylation facilities, procurement leads at downstream cleaning product manufacturers, specialty chemical distribution channel partners, and technical R&D directors; and secondary validation through customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed surfactant suppliers, and regulatory dossiers submitted to EPA and ECHA. Bottom-up capacity and demand modeling triangulated against top-down market sizing from feedstock consumption patterns.
Forecast inputs considered grade tier segmentation across commodity and specialty alkoxylates, end-use industry concentration in household cleaning versus personal care, packaging format preferences between liquid bulk and powder, and regional production hub economics across Germany, China, and India. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements. Ethylene oxide feedstock pricing trajectories and REACH Annex XVII amendment timelines served as industry-specific forecast inputs across the projection horizon.
Stress conditions across ethylene oxide price volatility bands, catalyst supply disruption scenarios, and regulatory timeline acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding PLI scheme continuation and carbon border adjustment implementation pace. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Cyclomethicone Market
Specialty Chemicals
Octocrylene Market
Specialty Chemicals
Security Ink Market
Specialty Chemicals
Silicone Acrylate Market
Specialty Chemicals
Alkoxide Market
Specialty Chemicals
Microcrystalline Wax Market
Specialty Chemicals
Sodium Ascorbyl Phosphate (SAP) Market
Specialty Chemicals
Superoxide Dismutase Market
Specialty Chemicals
Free-From Titanium Dioxide Market
Specialty Chemicals
Global Anti-Static Agents Market
Specialty Chemicals
Natural Insect Repellent Market
Specialty Chemicals
4-Propyl-1,3,2-Dioxathiolane 2,2-Dioxid Market
Specialty Chemicals
Propyl Isovalerate Market
Specialty Chemicals
Global Vacuum Grease Market
Specialty Chemicals
Acesulfame K Market
Specialty Chemicals
Phenoxycycloposphazene Market