
 Dipentene (Limonene) Market | 2026-2036
Dipentene (Limonene) Market Size, Share, and Industry Trends Forecast 2026-2036
Dipentene (Limonene) Market Analysis
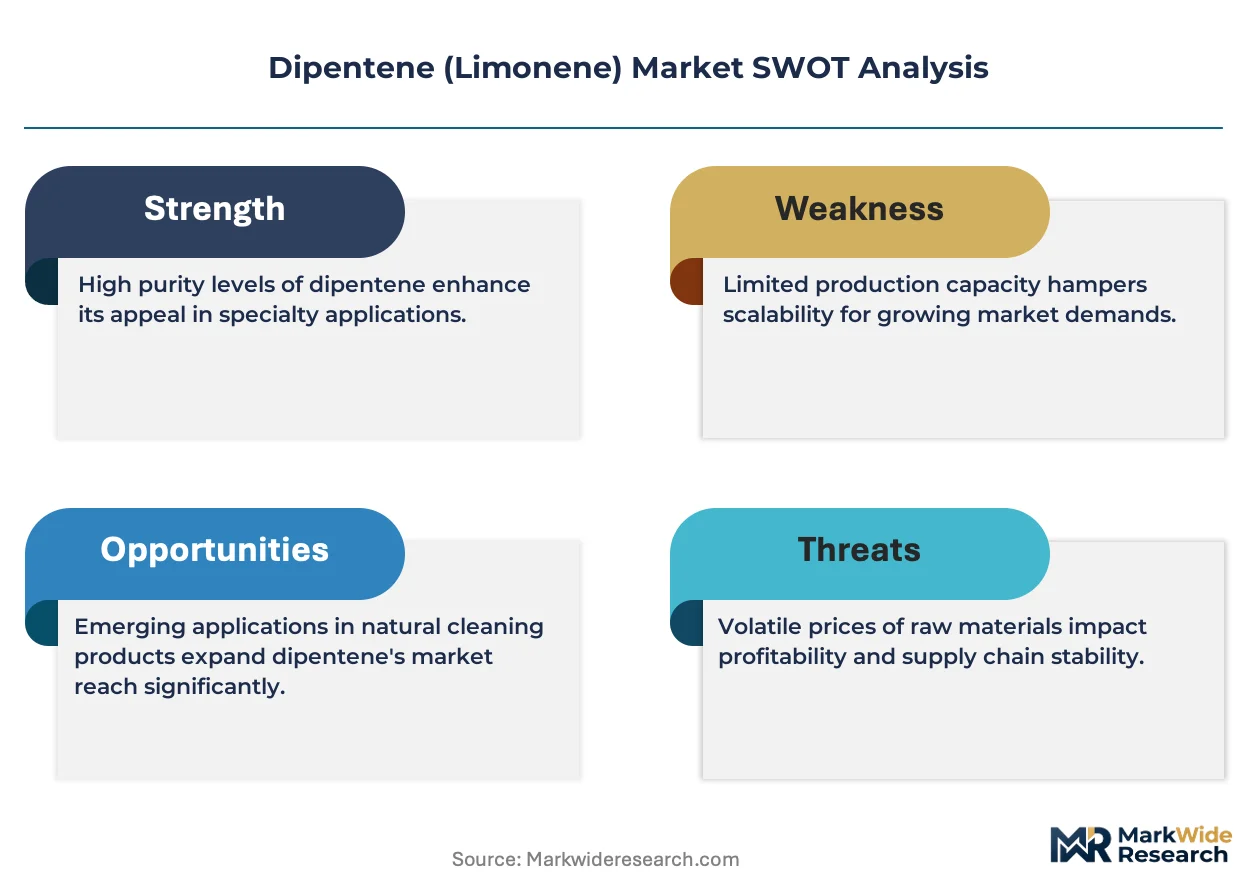
Modular packaging configurations for limonene are shifting buyer procurement patterns across the value chain. Florida Chemical Company leverages its citrus-belt proximity to sustain cost-advantaged feedstock access. Takasago International Corp. anchors premium fragrance-grade supply through specialized distillation capabilities. DSM-Firmenich competes on backward integration into flavor and fragrance portfolios.
Dipentene (limonene) is a monocyclic monoterpene hydrocarbon with the molecular formula C10H16, typically extracted via steam distillation of citrus peels or synthesized from pinene; it functions primarily as a versatile solvent, fragrance precursor, and intermediate for resins and adhesives. The natural product type segment dominates volume owing to consumer preference for plant-derived labeling, while bio-derived grades command margin premiums from cosmetics and pharmaceutical end users. Application demand in cleaning agents leads absolute consumption, though fragrance applications capture higher per-unit value across formulation supply chains.
EPA registration requirements and REACH substance restrictions shape product specifications for limonene entering North American and European formulations. FDA food additive classifications and FEMA GRAS listings determine eligibility for flavor applications in the United States. China's GB standards and MEE environmental compliance protocols govern synthetic production emissions and wastewater discharge. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs and market access barriers.
Market Dynamics
Modular packaging configurations for limonene are shifting buyer procurement patterns across the value chain, forcing suppliers to reconfigure logistics networks around flexible batch sizing rather than bulk commodity contracts.
Growth Catalysts
- REACH substance restrictions:Tightening purity standards in Europe are pulling cosmetic formulators toward certified fragrance-grade limonene, displacing synthetic alternatives in personal care formulations.
- Citrus peel valorization:Food processing waste streams in Florida and Brazil are expanding feedstock availability for steam-distilled natural grades, lowering unit costs for solvent applications.
- China's bio-derived production scaling:Domestic chemical manufacturers are building dedicated limonene extraction capacity to serve export markets, concentrating supply-side investment in Shandong and Jiangsu provinces.
Market Restraints
- Citrus crop volatility:Weather-driven fluctuations in Florida and Mediterranean orange harvests create feedstock cost instability for natural extraction routes.
- Synthetic pinene substitution:Petrochemical-derived limonene from turpentine fractionation competes on price in industrial solvent applications where natural labeling carries no premium.
- EPA registration timelines:New active ingredient approvals for pesticide-grade limonene formulations face multi-year review cycles, delaying market entry for biocidal applications.
Strategic Opportunities
- Pharmaceutical chiral separation:Enantiopure limonene demand for drug synthesis intermediates remains underserved, with only specialized distillation houses currently serving this specification tier.
- India's natural cosmetics export push:Formulators targeting Ayurveda-positioned personal care lines are sourcing terpene inputs for fragrance and preservative functions.
- EU Green Deal bio-based mandates:Public procurement guidelines favoring renewable content in cleaning products create preferential market access for certified bio-derived grades.
Industry Challenges
- Fractionation expertise scarcity:Operating specialized distillation columns for fragrance-grade separation requires skilled technicians that suppliers in emerging production regions struggle to recruit.
- Cross-jurisdictional specification divergence:Reconciling FDA food additive classifications with REACH purity thresholds forces parallel inventory management and reformulation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dipentene (Limonene) Market |
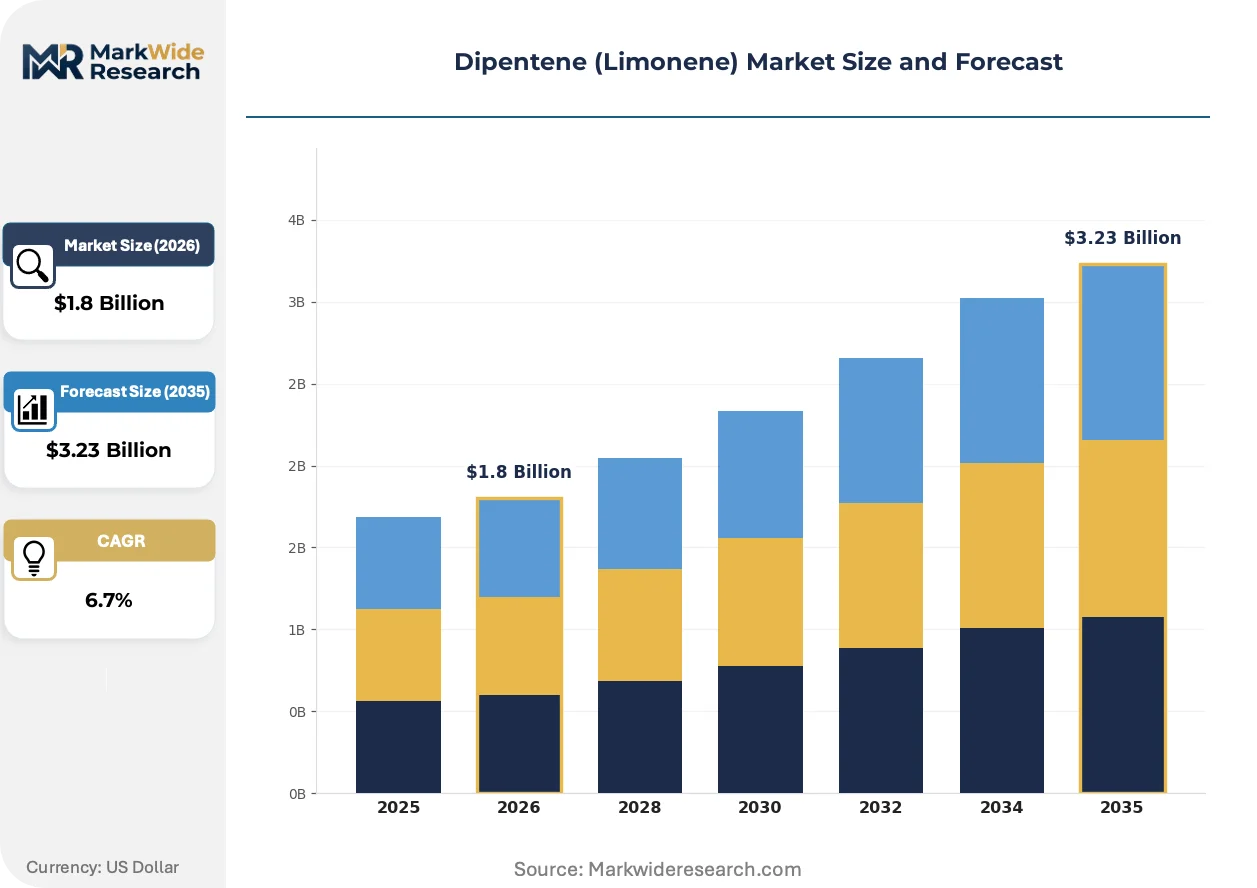
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Bio-derived, Modified Application: Fragrance, Cleaning Agents, Food Additives, Pharmaceuticals End User: Cosmetics, Food Industry, Chemical Manufacturers, Household Products Packaging Type: Drums, Bottles, Pails, Bulk Containers |
| Companies Covered | Takasago International Corp., Lemonconcentrate S.L.U, Florida Chemical Company, Shree Bankey Behari Lal Aromatics, SILVERLINE CHEMICALS LTD, Symrise AG, Merck KGaA, Arora Aromatics Inc, DSM-Firmenich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dipentene (Limonene) Market Emerging Trajectories
Continuous processing technology is displacing batch distillation in limonene extraction, reshaping capital deployment patterns and unit economics across the supply base. Three developments are compressing competitive timelines.
Supercritical CO2 extraction is consolidating technical leadership among suppliers serving fragrance and pharmaceutical grades. Premium cosmetic houses in France and Switzerland are adopting CO2-derived limonene for "solvent-free" labeling claims. This technology is consolidating quality-tier differentiation by enabling sub-ppm residual control that steam distillation cannot match.
REACH Annex XIV authorization requirements for certain terpene impurities are forcing reformulation investments across European industrial cleaning applications. Manufacturers must demonstrate substance safety or substitute inputs, compressing margins for commodity-grade suppliers. The adhesives and coatings segment is responding fastest, with formulators pre-qualifying alternative supply chains ahead of sunset dates.
Direct contracting between citrus processors and fragrance houses is shortening traditional distributor channels. Large Brazilian and Florida cooperatives now negotiate multi-year supply agreements with DSM-Firmenich and Takasago, bypassing merchant traders. This pattern is most visible in North America, where vertical integration into captive citrus supply is displacing spot market purchasing for premium grades.
Dipentene (Limonene) Market Segmentation
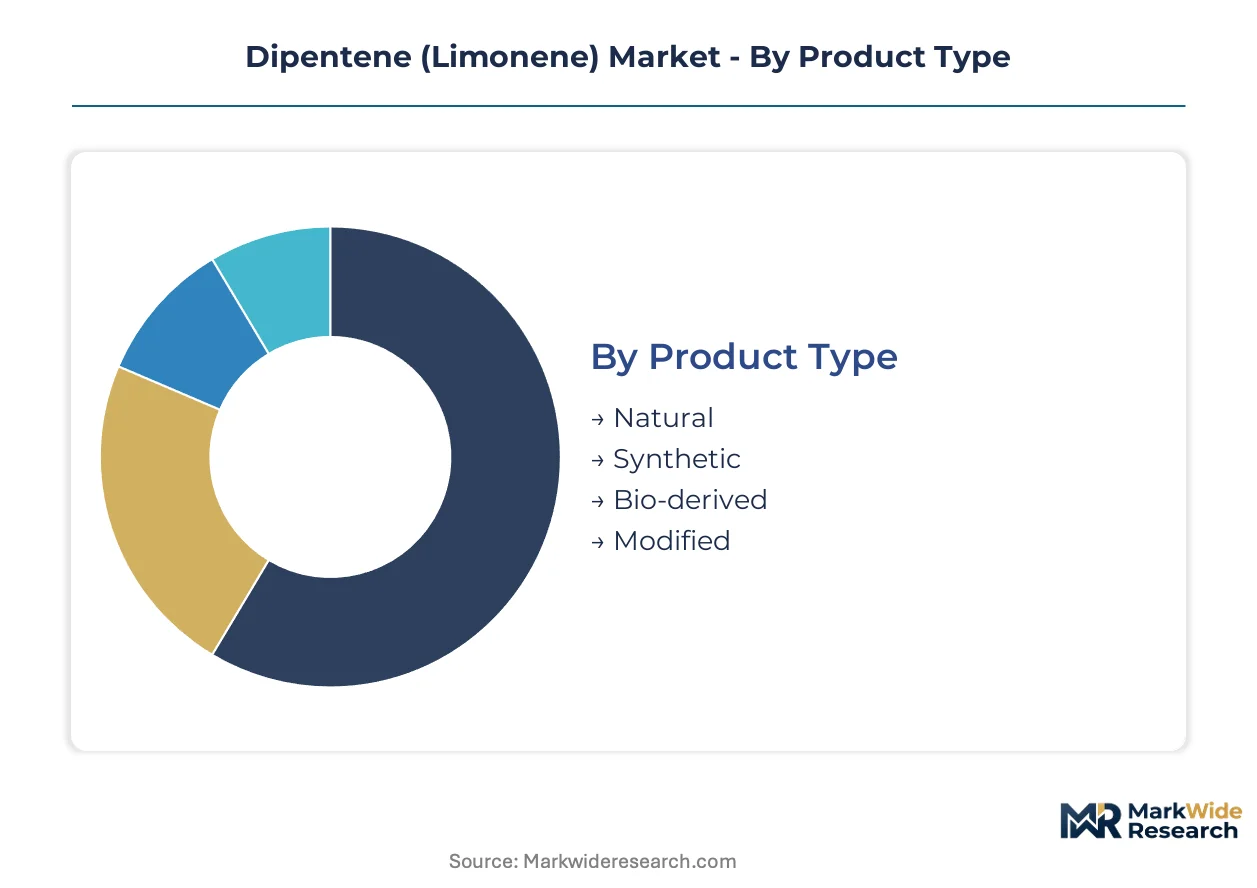
Limonene's molecular versatility creates divergent value pools across extraction methods and purity grades. Segmentation reveals where capital deployment concentrates and which specification tiers command sustainable margin premiums.
Product Type:
Steam distillation infrastructure demands the heaviest upfront investment, while synthetic routes leverage existing petrochemical assets.
- Natural:Extracted via steam distillation of citrus peels with C10H16 purity typically ranging 90-95%. Demand concentrates in French and Swiss cosmetic houses seeking "solvent-free" labeling claims, constrained by Florida and Mediterranean harvest volatility.
- Bio-derived:Fermentation-based production from sugar feedstocks achieves REACH-compliant purity thresholds without citrus crop dependency. Chinese manufacturers in Shandong and Jiangsu provinces are scaling capacity to serve EU Green Deal procurement mandates.
- Synthetic:Turpentine fractionation yields cost-competitive material for industrial solvent applications where natural certification carries no price premium.
- Modified:Hydrogenated or oxidized derivatives serve specialized adhesive and resin intermediate functions with higher per-unit value than parent terpene.
Most installed capacity flows through Natural extraction. Expansion is steepest in Bio-derived.
Application:
Volume concentration sits with commodity solvents, while value capture favors fragrance-grade specifications.
- Fragrance:Enantiopure separation for fine perfumery requires supercritical CO2 extraction achieving sub-ppm residual control. DSM-Firmenich and Takasago anchor premium supply through specialized distillation columns.
- Cleaning Agents:Industrial and household formulations consume the largest absolute volumes, particularly in EU member states where public procurement guidelines favor bio-based content.
- Food Additives:FDA FEMA GRAS listings and EFSA approvals govern eligibility for flavor applications, with purity thresholds exceeding industrial grades.
- Pharmaceuticals:Chiral separation for drug synthesis intermediates remains underserved, with only specialized houses currently serving this specification tier.
Cleaning Agents absorb the majority of volume throughput. Fragrance applications are climbing the fastest.
End User:
Customer sophistication determines specification stringency and contract structure flexibility.
- Cosmetics:Formulators in France, Switzerland, and India demand certified fragrance-grade material with full supply chain traceability for Ayurveda-positioned and clean-label product lines.
- Food Industry:Flavor houses require FDA and EFSA-compliant grades with documented absence of pesticide residues and heavy metals.
- Chemical Manufacturers:Resin and adhesive producers prioritize unit cost over provenance, sourcing commodity grades through spot markets.
- Household Products:Brand owners balance bio-based marketing claims against formulation cost targets, driving hybrid procurement strategies.
Chemical Manufacturers represent the largest volume destination. Cosmetics is gaining share fastest.
Packaging Type:
Logistics configuration shapes working capital requirements and customer switching costs.
- Bulk Containers:Tank trucks and ISO tanks serve high-volume chemical manufacturers with dedicated supply agreements and lowest per-kilogram logistics cost.
- Drums:Standard 200-liter steel drums dominate mid-scale fragrance and cleaning agent procurement, balancing handling efficiency with batch flexibility.
- Pails:20-25 liter polyethylene containers serve specialty chemical and small-batch cosmetic formulators requiring frequent rotation.
- Bottles:Laboratory and pilot-scale quantities for pharmaceutical R&D and quality control reference standards.
Bulk Containers handle the majority of tonnage. Pails show the steepest expansion trajectory among smaller formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Citrus terpene extraction originated in Mediterranean and subtropical growing belts during the early twentieth century. Industrial limonene production subsequently concentrated near Florida and Brazilian orange processing centers. Contemporary supply chains now span fermentation-based manufacturing clusters in East Asia.
United States
Florida's citrus belt supplies feedstock for steam-distilled natural grades serving fragrance and cleaning agent formulators. EPA registration requirements govern biocidal applications, while FDA FEMA GRAS listings determine food additive eligibility. Orlando-area processors negotiate direct contracts with DSM-Firmenich and Takasago, bypassing traditional merchant channels.
Brazil
São Paulo state cooperatives dominate global orange juice production, generating peel waste streams for terpene extraction. ANVISA pharmaceutical regulations and Ministry of Agriculture export certifications shape quality specifications. Campinas and Ribeirão Preto house the largest citrus processing infrastructure outside the United States.
China
Shandong and Jiangsu provinces host expanding bio-derived limonene capacity targeting EU Green Deal procurement mandates. MEE environmental compliance protocols govern synthetic production emissions and wastewater discharge. Qingdao chemical manufacturers are scaling dedicated extraction facilities for export markets.
Germany
REACH substance restrictions and Annex XIV authorization requirements pull cosmetic formulators toward certified fragrance-grade material. ECHA purity thresholds exceed industrial specifications, forcing parallel inventory management. Hamburg and Frankfurt serve as distribution hubs for European fragrance compounders.
India
Maharashtra and Gujarat processors supply terpene inputs for Ayurveda-positioned personal care exports. FSSAI food safety standards and BIS quality certifications determine eligibility for domestic and international shipments. Mumbai fragrance houses source natural grades for clean-label product lines targeting European and North American markets.
Dipentene (Limonene) Market Vendor Landscape
The competitive structure tilts toward geographic specialization rather than scale consolidation. Florida Chemical Company leverages citrus-belt proximity for cost-advantaged feedstock access, while Takasago International Corp. anchors premium fragrance-grade supply through specialized distillation capabilities. DSM-Firmenich competes on backward integration into flavor and fragrance portfolios. Capacity expansion and direct contracting with citrus processors represent the dominant competitive moves across the value chain.
Within the premium fragrance-grade tier, Takasago International Corp. and DSM-Firmenich exemplify specialized distillation houses serving cosmetic and pharmaceutical specifications. Florida Chemical Company occupies a position among North American feedstock-integrated suppliers. Lemonconcentrate S.L.U represents Mediterranean-origin citrus processors with proximity to French and Swiss fragrance compounders. These archetypes reflect divergent capital deployment strategies: captive supply integration versus technical specification leadership versus geographic feedstock control.
| Leading Market Players |
|---|
| Takasago International Corp. |
| Lemonconcentrate S.L.U |
| Florida Chemical Company |
| Shree Bankey Behari Lal Aromatics |
| SILVERLINE CHEMICALS LTD |
| Symrise AG |
| Merck KGaA |
| Arora Aromatics Inc |
| DSM-Firmenich |
| Others |
Supply Flow & Price Mechanics
Captive citrus supply integration anchors both feedstock security and margin sustainability for processors in Florida and São Paulo. This backward control over peel waste streams insulates natural-grade producers from spot volatility while synthetic competitors from turpentine fractionation pressuring industrial solvent tiers.
Pricing Analysis
Three-tier pricing structure across fragrance-grade, technical-grade, and industrial-grade levels stratifies the market by purity certification and end-use application. Price differentiation hinges on REACH-compliant thresholds versus FDA FEMA GRAS listings, with cosmetic formulators absorbing premiums for traceability documentation. Cost compression in industrial grades intensifies as Chinese bio-derived capacity expands export availability. Chemical manufacturers spot-purchasing commodity solvents exhibit highest price sensitivity; fragrance houses contracting multi-year direct agreements show lowest elasticity.
Supply Chain Analysis
Citrus peel feedstock rests on Florida, Brazil, and Mediterranean harvest cycles for steam-distilled natural production, while Chinese fermentation facilities draw from corn and sugar substrates. Synthetic routes hinge on turpentine supply from Southeast Asian pine tapping operations. Single-source vulnerability concentrates in fragrance-grade distillation expertise, where Takasago and DSM-Firmenich operate specialized columns. Distribution runs through direct processor-to-compounder contracts for premium tiers, with merchant traders handling industrial spot volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dipentene functions as a stable compounder underpinned by regulatory mandates for bio-based content in European cleaning products and personal care formulations.
For Market Incumbents: Cement feedstock security through long-term peel supply contracts with Florida and São Paulo citrus cooperatives, insulating natural-grade margins from harvest volatility. Deepen distillation capabilities for enantiopure pharmaceutical specifications before specialized houses capture chiral separation demand. Prioritize REACH Annex XIV pre-compliance investments to avoid reformulation costs in adhesives and coatings segments. For New Entrants and Emerging Players: Fragrance compounders in India represent the most penetrable channel partner type for Ayurveda-positioned terpene sourcing, with Maharashtra and Gujarat processors seeking certified natural grades for export markets. Target white-space in pharmaceutical chiral intermediates where incumbent capacity remains constrained. Pursue EU Green Deal certification as a go-to-market wedge for bio-derived grades entering public procurement channels. For Investors and Strategic Acquirers: Consolidation pressure builds where fractionation expertise scarcity intersects with geographic feedstock concentration, favoring acquisition of mid-scale Brazilian processors with installed distillation infrastructure. Frame long-term viability around bio-derived production scalability decoupled from citrus crop cycles. Monitor EPA registration timeline acceleration for biocidal limonene formulations as an inflection signal for pesticide-grade market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Citrus Supply | Orlando-area processors negotiating direct contracts with cooperatives bypass merchant traders and secure feedstock cost advantage. |
| Supercritical CO2 Capacity Addition | Shandong manufacturers deploying CO2 extraction achieve sub-ppm residual control required by Swiss cosmetic houses. |
| REACH Annex XIV Pre-Qualification | European formulators in adhesives segment accelerate alternative supply chain validation ahead of sunset dates. |
| Pharmaceutical Chiral Separation Investment | Specialized distillation houses serving drug synthesis intermediates capture unserved demand from generic API manufacturers. |
| EU Green Deal Certification Program | Chinese bio-derived producers securing renewable content verification gain preferential access to public procurement mandates. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with citrus processing plant managers, fragrance house procurement directors, cosmetic formulator R&D leads, and chemical distributor channel partners with secondary validation. Customs trade data, ECHA substance registration databases, FDA FEMA GRAS listings, and SEC filings from integrated flavor and fragrance houses anchored supply-side sizing. Bottom-up capacity modeling and top-down end-use consumption estimates were cross-referenced for triangulation.
Comparable historical periods spanning complete citrus harvest cycles anchored the projection horizon to account for feedstock seasonality. The analytical framework modeled grade tier, end-use industry, packaging format, and regional production hub segmentation throughout the forecast period. CAGRs were derived from regression analysis against citrus processing volumes, REACH regulatory phase-in schedules, and bio-derived capacity buildout announcements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Florida citrus greening disease progression and Chinese fermentation yield improvements. Forecasts reflect documented assumptions around EU Green Deal procurement adoption rates and EPA registration pathway timelines. Material deviation in citrus crop yields or REACH authorization enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Homosalate Market
Specialty Chemicals
5-Hydroxymethylfurfural Market
Specialty Chemicals
Octocrylene Market
Specialty Chemicals
Multimodal Chromatography Columns Market
Specialty Chemicals
Polyglycolic Acid (PGA) Market
Specialty Chemicals
North America Non-Phthalate Plasticizers Market
Specialty Chemicals
Anhydroxylitol Market
Specialty Chemicals
Silicone Derivative Market
Specialty Chemicals
Cloud Emulsions Market
Specialty Chemicals
Polyimide Varnish Market
Specialty Chemicals
Global Tattoo Inks Market
Specialty Chemicals
Europe Non-Phthalate Plasticizers Market
Specialty Chemicals
Phosphonate Market
Specialty Chemicals
Cellulose Acetate Phthalate Market
Specialty Chemicals
Copper (I) Hexafluoroacetylacetonate 1, 5- Cyclooctadiene Market
Specialty Chemicals
Optical Whitening Agents Market