
 United States Aerosol Cans Market | 2026-2036
United States Aerosol Cans Market Size, Share, and Industry Trends Forecast 2026-2036
United States Aerosol Cans Market Analytics
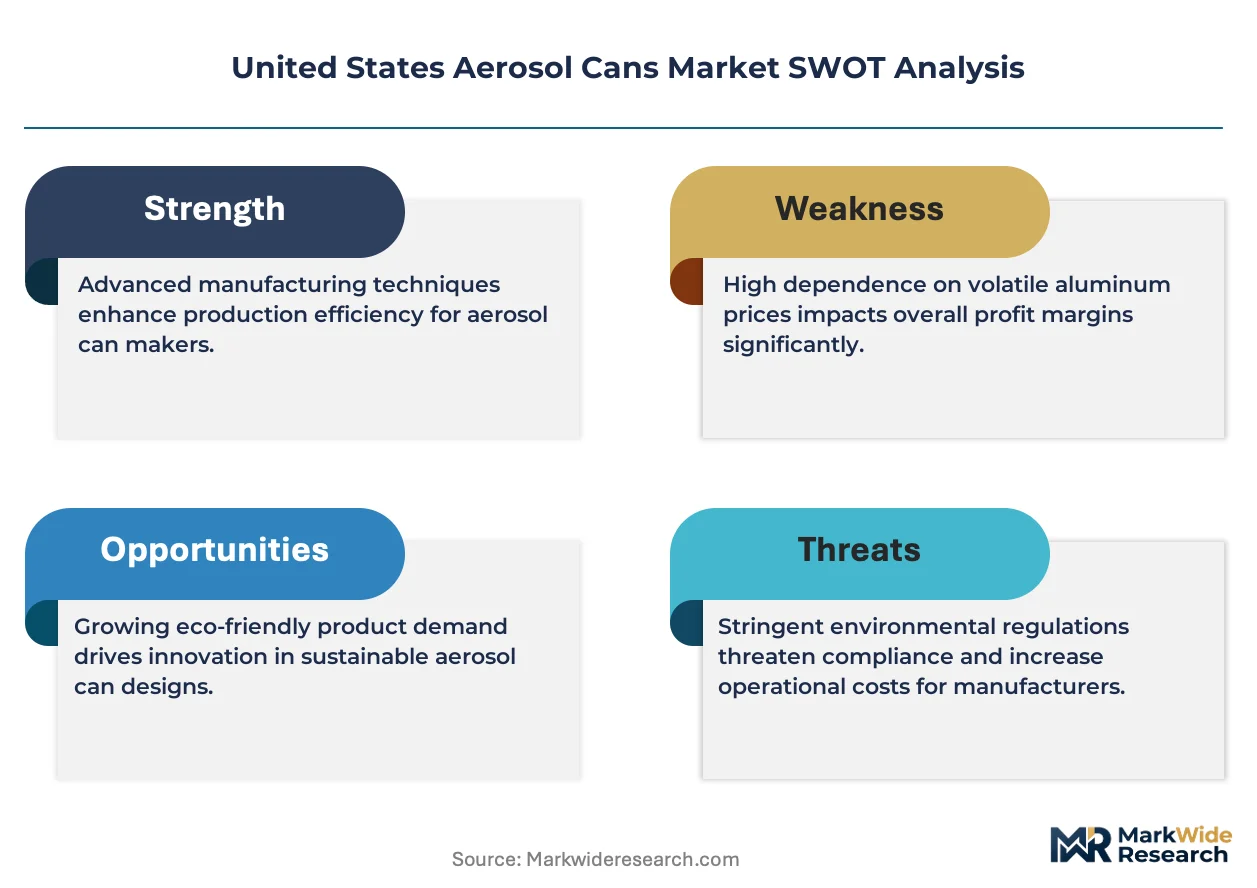
Direct-to-retail supply routes is narrowing as national distributors consolidate shelf-space negotiations with big-box chains. Ball Corporation leverages its aluminum rolling capacity to secure long-term contracts with personal care brands. Crown Holdings Inc. anchors its position through steel can specialization for industrial solvents and automotive coatings. Trivium Packaging competes by extending recycled-content aluminum offerings that meet emerging sustainability procurement standards.
United States aerosol cans are pressurized metal or composite containers, typically fabricated from aluminum or tinplate steel with internal coatings resistant to propellant corrosion, designed to dispense products as fine sprays or foams through precision-engineered valves. These containers serve consumer convenience, industrial coating application, and food preservation functions across manufacturing and retail channels. Aluminum dominates material selection due to its lightweight properties and infinite recyclability, while steel retains cost advantages in bulk industrial applications. Personal care and household applications command stable volume, though automotive maintenance and food packaging segments are attracting reformulation investment as propellant chemistry evolves.
EPA regulates volatile organic compound emissions under Clean Air Act provisions, while California Air Resources Board imposes stricter state-level limits that de facto shape national product formulations; DOT oversees hazardous materials transport classification affecting logistics networks and regional distribution hub placement. OSHA workplace exposure standards influence industrial aerosol specification for manufacturing facilities. Stakeholders must monitor state-level preemption battles and propellant innovation pipelines to anticipate which formulations will retain market access.
Market Dynamics
EPA VOC limits and California Air Resources Board thresholds are forcing simultaneous propellant reformulation and coating chemistry changes across domestic manufacturing footprints.
Growth Catalysts
- Automotive aftermarket concentration:Midwest automotive hubs sustain solvent-based aerosol demand for undercoating and touch-up applications despite electrification headwinds.
- REACH-aligned state procurement:California and New York public purchasing mandates now require recycled-content aluminum thresholds that pull national supply chains toward circular material flows.
- Propellant innovation pipelines:Hydrofluoroolefin and compressed gas alternatives are achieving commercial scale in personal care formulations previously dependent on hydrocarbon propellants.
Market Restraints
- Aluminum ingot price volatility:Midwest premium volatility above LME benchmarks compresses canmaker margins and constrains long-term contract pricing flexibility.
- Gulf Coast propellant concentration:Petrochemical corridor dependency creates hurricane-season supply interruption exposure for national aerosol production.
- Steel can corrosion limitations:Water-based formulation compatibility gaps restrict steel substrate penetration in household cleaner segments.
Strategic Opportunities
- Refillable aerosol infrastructure:Texas and California pilot programs demonstrate consumer willingness to adopt returnable aluminum systems for premium personal care brands.
- Food-grade barrier coatings:Epoxy-phenolic replacement technologies open whipped cream and cooking spray segments to modified atmosphere packaging requirements.
- Industrial IoT integration:Connected valve systems enable usage-tracking for B2B maintenance chemical distributors serving fleet and facility management clients.
Industry Challenges
- Coating chemist talent scarcity:Internal lining formulation expertise concentrates among retiring technical workforces at legacy canmaking facilities.
- Valve assembly automation capex:Precision crimping and gassing equipment upgrades require eight-figure capital commitments for mid-tier contract manufacturers.
- Propellant compatibility certification:Reformulated product qualification cycles stretch eighteen to twenty-four months under EPA SNAP program timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Aerosol Cans Market |
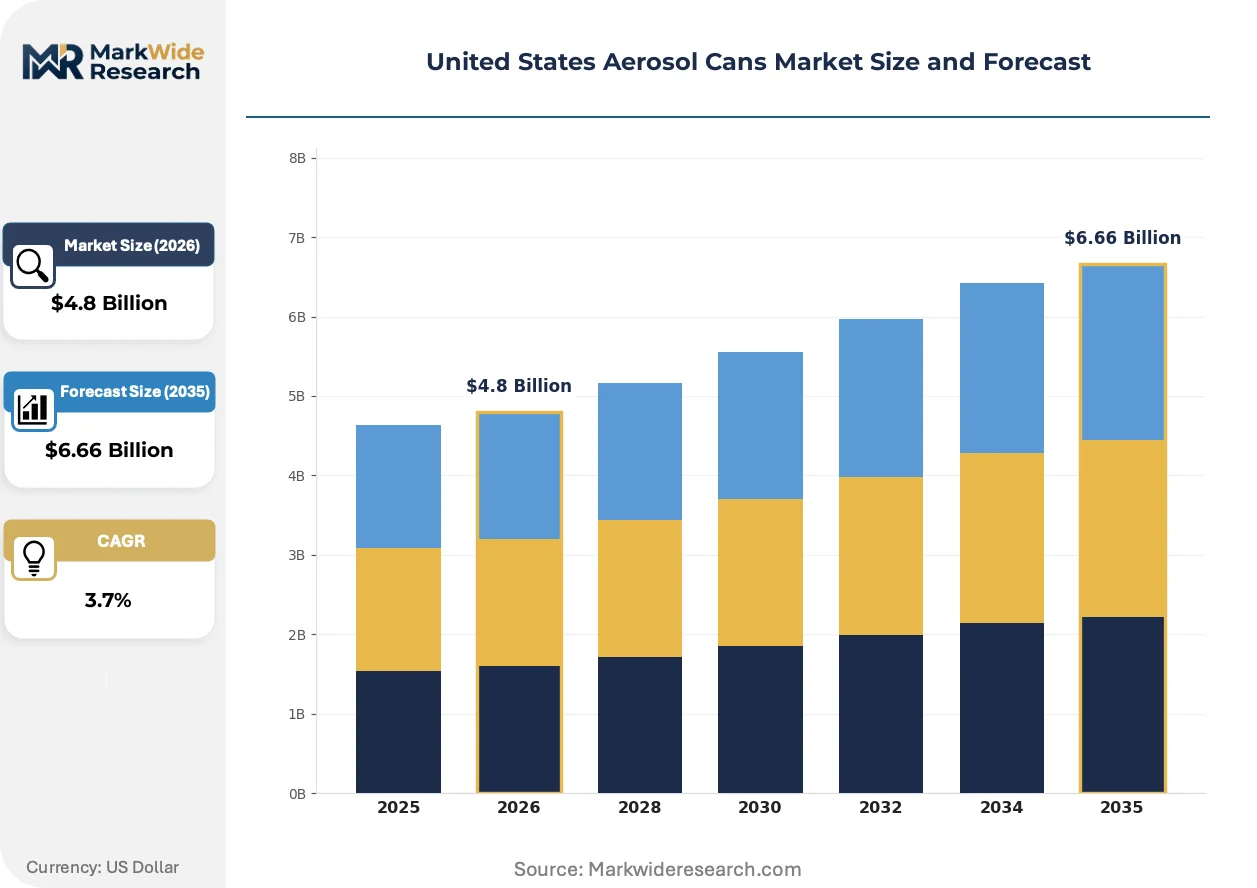
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Personal Care, Household, Automotive, Industrial Material: Aluminum, Steel, Plastic, Composite End User: Households, Manufacturers, Retailers, Service Providers Application: Cleaning, Personal Hygiene, Automotive Maintenance, Food Packaging |
| Companies Covered | Ball Corporation, Crown Holdings Inc., MAUSER Packaging Solutions, Exal Corporation, CCL Container Inc., Ardagh Group, BWAY Corporation, Trivium Packaging, Silgan Dispensing Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Aerosol Cans Market Evolving Landscape
Material science convergence and regulatory chemistry mandates are redefining competitive advantage away from scale economies toward formulation agility and coating customization capabilities.
Barrier coating technology is hybridizing. Sol-gel ceramic-organic hybrid linings now replace conventional epoxy-phenolic systems in acidic personal care formulations. Premium cosmetic brands in California are qualifying these coatings for retinol and vitamin C products that degrade standard barriers. This hybridizing approach is compressing the traditional coating supplier base as chemical firms without sol-gel capabilities lose qualification access.
California Air Resources Board Consumer Products Regulation amendments are tightening volatile organic compound limits for antiperspirants and hair sprays effective 2027. Formulators must reduce hydrocarbon propellant fractions or shift to compressed nitrogen systems. Personal care contract manufacturers in Texas and New Jersey are accelerating qualification timelines for water-based and dry spray alternatives to maintain shelf placement.
Direct-store-delivery networks are fragmenting as regional distributors consolidate negotiating leverage with big-box retailers. National grocery and home improvement chains now demand vendor-managed inventory systems that transfer working capital burden upstream to canmakers. This concentration is most visible in the Midwest, where automotive chemical distributors face margin compression from consolidated farm-and-fleet retail buyers.
United States Aerosol Cans Market Segmentation
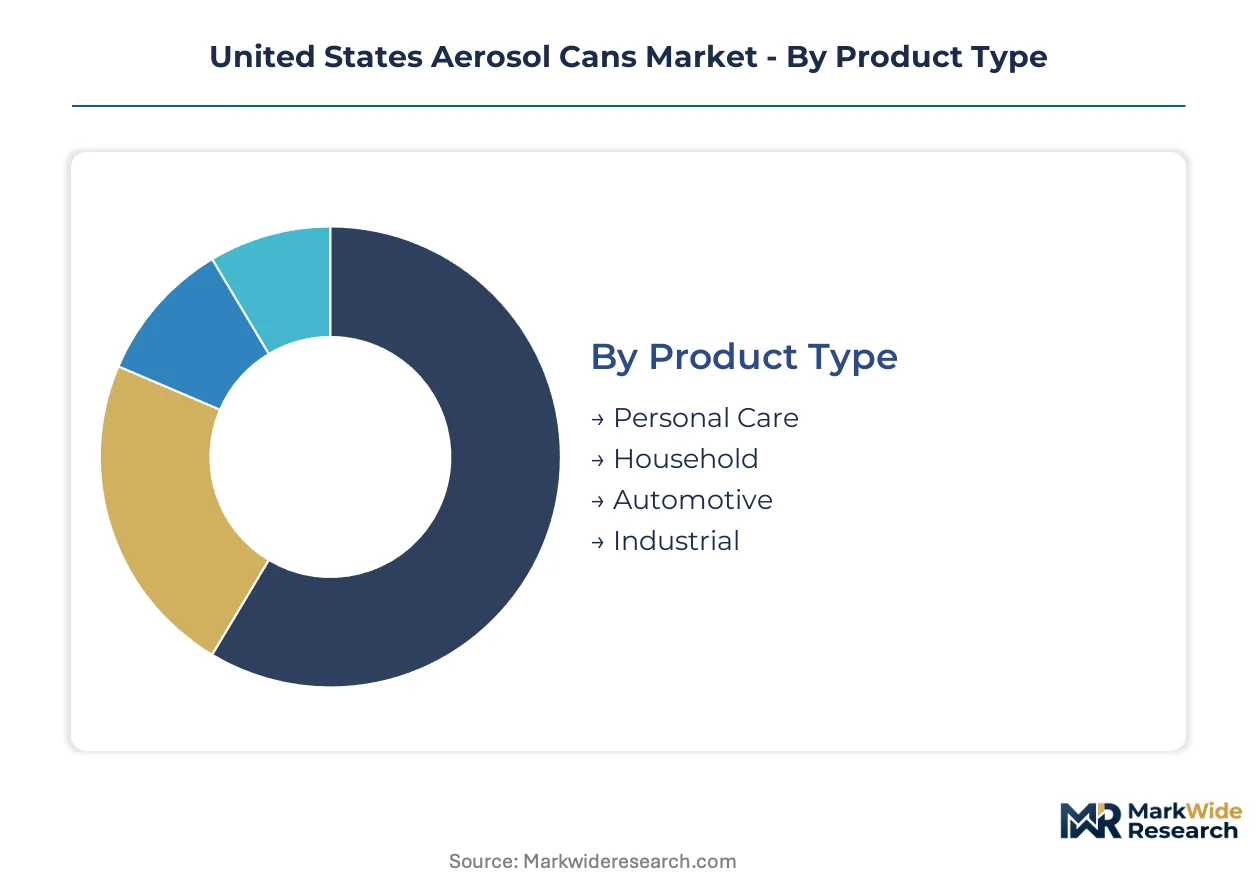
Segmentation in the United States aerosol cans market reveals how regulatory chemistry mandates and material substitution pressures fragment manufacturing capabilities across distinct product categories. Understanding these divisions exposes where formulation expertise concentrates and where coating technology gaps create competitive vulnerability.
Product Type:
Mature applications dominate volume while emerging segments force propellant innovation investments.
- Personal Care:Antiperspirants, hair sprays, and dry shampoos utilize precision-engineered valves with hydrocarbon or compressed gas propellant systems. California Air Resources Board VOC thresholds are compressing hydrocarbon fractions, forcing Texas and New Jersey contract manufacturers to accelerate water-based and dry spray qualification timelines.
- Household:Surface cleaners, disinfectants, and air fresheners deploy corrosion-resistant internal linings for aggressive chemical formulations. Water-based compatibility gaps restrict steel substrate penetration here, preserving aluminum dominance despite Midwest premium volatility above LME benchmarks.
- Automotive:Undercoating, brake cleaners, and touch-up sprays sustain solvent-based demand in Midwest automotive hubs despite electrification headwinds.
- Industrial:Lubricants, mold releases, and protective coatings serve manufacturing facilities under OSHA workplace exposure standards.
Household retains volume leadership; personal care holds the steepest expansion curve as refillable pilot programs scale.
Material:
Cost tier stratification separates premium recyclable substrates from industrial bulk applications.
- Aluminum:Lightweight, infinitely recyclable metal dominates personal care and food packaging through Ball Corporation's rolling capacity and Trivium Packaging's recycled-content offerings. California and New York public purchasing mandates now require recycled-content thresholds that pull national supply chains toward circular material flows.
- Steel:Tinplate substrates retain cost advantages in bulk industrial solvents and automotive coatings where Crown Holdings Inc. anchors market position through specialization.
- Plastic:Polymer containers serve niche applications with reduced pressure requirements and chemical compatibility needs.
- Composite:Hybrid material systems address specialized barrier requirements in emerging food-grade applications.
Aluminum commands premium positioning; composite materials are gaining share fastest in barrier-coating replacement segments.
End User:
Customer type determines order scale, customization depth, and inventory management burden allocation.
- Households:Individual consumers purchase through retail channels where direct-store-delivery fragmentation and vendor-managed inventory systems transfer working capital burden upstream to canmakers.
- Manufacturers:Industrial facilities specify aerosol systems for in-house maintenance, fleet management, and production-line applications under OSHA compliance frameworks.
- Retailers:National grocery and home improvement chains consolidate shelf-space negotiations, compressing margins for regional distributors serving consolidated farm-and-fleet buyers in the Midwest.
- Service Providers:Automotive repair shops, janitorial contractors, and facility maintenance operators purchase through B2B chemical distributors exploring connected valve systems for usage-tracking.
Retailers concentrate procurement leverage; service providers are expanding most quickly through IoT-enabled distribution models.
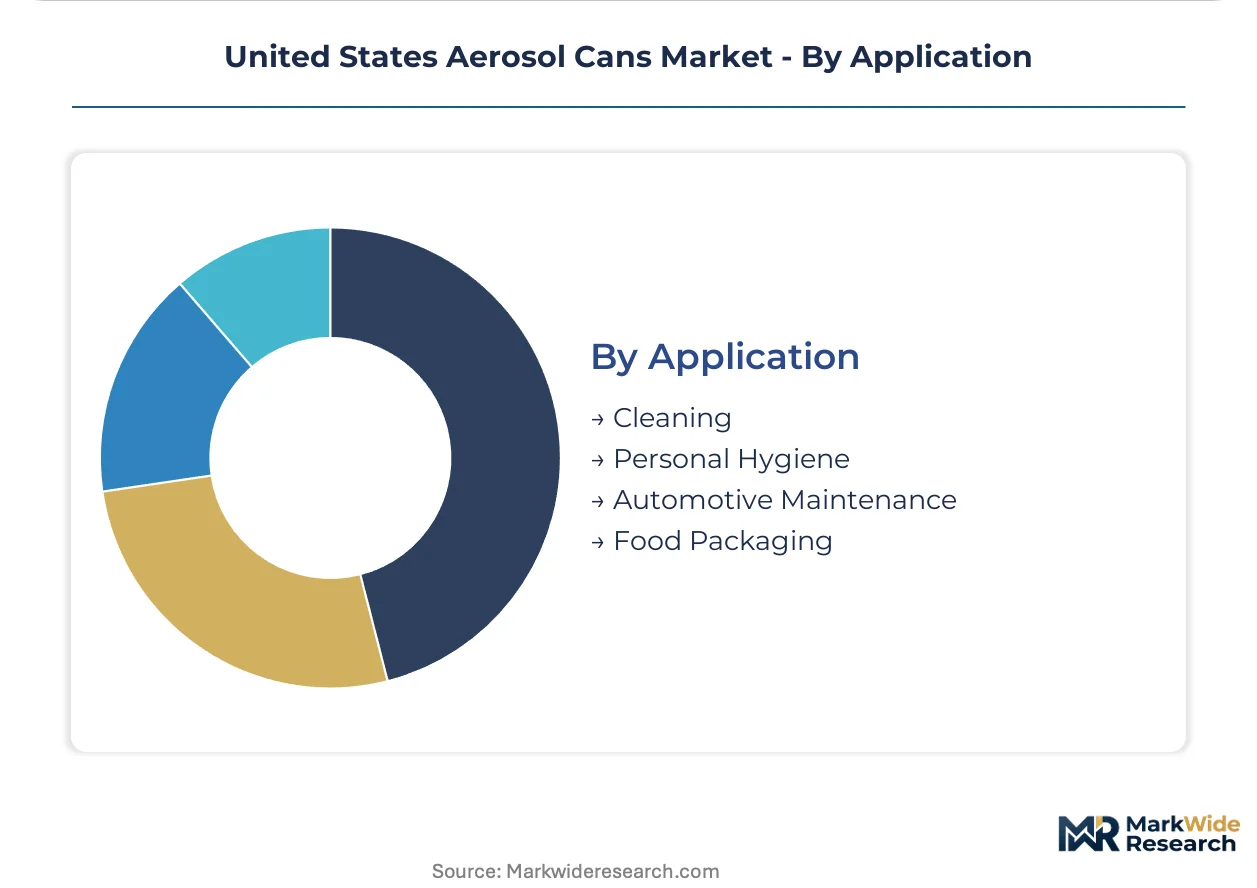
Application:
Geography shapes application demand through regional industrial specialization and regulatory intensity variation.
- Cleaning:Surface disinfection and degreasing formulations concentrate in Gulf Coast petrochemical corridors vulnerable to hurricane-season supply interruption exposure.
- Personal Hygiene:Deodorants and shaving products drive California Air Resources Board compliance investments, with Texas and California refillable pilot programs demonstrating consumer willingness to adopt returnable aluminum systems.
- Automotive Maintenance:Undercoating and touch-up demand anchors in Midwest automotive hubs, sustaining solvent-based formulations despite electrification pressures on long-term volume.
- Food Packaging:Whipped cream and cooking spray segments are opening to modified atmosphere packaging through epoxy-phenolic replacement technologies qualifying sol-gel ceramic-organic hybrid linings.
Cleaning applications retain volume leadership; food packaging holds the steepest expansion curve as barrier coating innovation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Clean Air Act enforcement and California Air Resources Board thresholds anchor regulatory intensity across domestic manufacturing footprints, compressing formulation timelines and reshaping regional production strategies.
California
Personal care brands accelerate dry spray and water-based antiperspirant qualification to meet 2027 VOC limits. CARB Consumer Products Regulation amendments force simultaneous propellant reformulation and coating chemistry investments. Los Angeles and San Diego pilot refillable aluminum programs demonstrating consumer adoption of returnable systems for premium cosmetics.
Texas
Gulf Coast petrochemical corridors concentrate propellant supply chains vulnerable to hurricane-season interruption exposure. Houston-area contract manufacturers expand compressed gas and hydrofluoroolefin qualification capacity. Dallas-Fort Worth distribution hubs serve national personal care brands navigating EPA SNAP program certification timelines.
Midwest
Detroit and Chicago automotive hubs sustain solvent-based aerosol demand for undercoating and touch-up applications despite electrification headwinds. Ohio and Michigan manufacturing facilities face OSHA workplace exposure standard compliance costs. Farm-and-fleet retail consolidation in Illinois compresses margins for regional chemical distributors.
Northeast
New York public purchasing mandates require recycled-content aluminum thresholds pulling supply chains toward circular material flows. New Jersey contract manufacturers accelerate barrier coating qualification for corrosive household formulations. Boston-area technical talent scarcity constrains internal lining formulation expertise at legacy canmaking facilities.
Southeast
Florida and Georgia logistics corridors fragment direct-store-delivery networks as regional distributors consolidate negotiating leverage with big-box retailers. Atlanta distribution hubs transfer vendor-managed inventory burdens upstream to canmakers. Carolina manufacturing footprints expand food-grade barrier coating capacity for whipped cream and cooking spray segments.
United States Aerosol Cans Market Competitive Landscape
Integrated metal rollers and specialized canmakers split the market along material substrate lines. Three strategic archetypes dominate: aluminum rolling conglomerates securing long-term personal care contracts, steel specialists anchoring industrial solvent segments, and recycled-content challengers meeting emerging sustainability procurement standards. Competitive moves concentrate on captive aluminum supply agreements and sol-gel ceramic-organic hybrid lining qualification.
Within the integrated aluminum tier, Ball Corporation and Trivium Packaging exemplify scale-driven positions leveraging rolling capacity and recycled-content offerings respectively. Crown Holdings Inc. occupies the steel specialization archetype for bulk industrial applications. These three anchors represent the material substrate divergence reshaping contract negotiations with national grocery and home improvement chains.
| Leading Market Players |
|---|
| Ball Corporation |
| Crown Holdings Inc. |
| MAUSER Packaging Solutions |
| Exal Corporation |
| CCL Container Inc. |
| Ardagh Group |
| BWAY Corporation |
| Trivium Packaging |
| Silgan Dispensing Systems |
| Others |
Value Network & Pricing Analysis
Gulf Coast propellant capacity utilization running above 85% compresses pricing flexibility for national aerosol brands while forcing contract manufacturers toward longer-term offtake commitments. This tightness propagates through Midwest automotive chemical distributors and California personal care formulators alike, embedding regional cost disparities into national product strategies.
Pricing Analysis
Midwest-to-California aluminum can spreads now exceed 12% as LME premium volatility and freight differentials stratify regional procurement costs. Pricing stratifies across premium, standard, and economy tiers, with CARB-compliant formulations commanding certification-grade premiums and steel-based industrial solvents anchoring the economy band. Cost compression in standard-tier household cleaners is intensifying because water-based formulation investments compress contract manufacturer margins. Retail chains exhibit highest price sensitivity through vendor-managed inventory demands, while premium cosmetic brands absorb elevated aluminum costs for recycled-content positioning.
Supply Chain Analysis
Ball Corporation, Crown Holdings, and Trivium Packaging concentrate two-thirds of domestic canmaking capacity across Ohio, Texas, and Florida manufacturing footprints. Aluminum ingot draws from Quebec smelters and domestic rolling mills, while hydrocarbon propellants hinge on Gulf Coast petrochemical complexes and imported HFO alternatives. Single-source vulnerability concentrates in Louisiana propellant corridors exposed to hurricane-season disruption. Distribution runs through consolidated national grocery and home improvement chains that have displaced regional direct-store-delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is cycling through a regulatory-driven recovery as EPA SNAP program timelines and CARB VOC amendments force simultaneous propellant and coating reformulation investments across domestic manufacturing footprints.
For Market Incumbents: Insulate core aluminum supply agreements through captive rolling capacity or long-term tolling arrangements with Quebec smelters to offset Midwest premium volatility. Prioritize sol-gel ceramic-organic hybrid lining qualification to defend personal care contracts against emerging barrier-coating specialists. This defensive posture counters Trivium Packaging's recycled-content challenge and preserves shelf-space negotiations with consolidated retail buyers. For New Entrants and Emerging Players: Establish a beachhead in food-grade barrier coating segments where epoxy-phenolic replacement technologies have fragmented incumbent qualification timelines. Target Carolina and Southeast manufacturing corridors for whipped cream and cooking spray applications, leveraging lower regulatory compliance burdens than California personal care markets. A technical partnership with sol-gel chemical suppliers accelerates qualification timelines against legacy canmakers. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier contract manufacturers with compressed valuations but intact EPA SNAP program certification pipelines. The five-to-ten year viability window favors assets with demonstrated propellant compatibility testing infrastructure over pure-play canmaking capacity. Monitor CARB enforcement intensity as the inflection signal—accelerated VOC rulemaking would strand hydrocarbon-dependent formulation assets and revalue compressed-gas qualification capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Rolling | Captive supply from Quebec smelters insulates Ball Corporation against Midwest premium volatility. |
| CARB-Compliant Formulation Qualification | Texas contract manufacturers accelerate dry spray timelines to secure California shelf placement. |
| Sol-Gel Barrier Coating Partnership | Chemical firms without ceramic-organic hybrid capabilities lose personal care qualification access. |
| Refillable Aerosol Infrastructure Pilot | Los Angeles and Dallas programs demonstrate consumer willingness for returnable aluminum systems. |
| Compressed Gas Propellant Scale-Up | Hydrofluoroolefin alternatives achieve commercial viability in antiperspirant segments ahead of 2027 limits. |
Research Methodology
Desk research of EPA enforcement records, CARB regulatory filings, and aluminum trade data preceded structured interviews with canmaking plant managers, personal care procurement leads, automotive chemical distributors, and barrier-coating R&D directors. Secondary validation drew from SEC 10-K disclosures, customs import records, and American Chemistry Council production surveys. Bottom-up capacity estimates triangulated against top-down consumption models derived from retail channel audits.
Assumptions held fixed include current EPA SNAP program certification timelines and existing CARB VOC threshold trajectories, while aluminum LME premium volatility and hurricane-season disruption frequency were varied across scenarios. Segmentation modeling spanned material substrate, end-use application, propellant chemistry, and regional regulatory cluster. CAGRs were derived from production capacity expansion announcements cross-referenced with downstream demand elasticity estimates for personal care and automotive maintenance segments.
Sensitivities concentrate around CARB enforcement acceleration, Gulf Coast propellant supply interruption, and sol-gel coating qualification timeline compression. Forecasts embed these assumptions without projecting specific regulatory rulemaking dates. Quarterly review of aluminum premium spreads, SNAP program approval backlogs, and refillable pilot program adoption metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Salicylate Market
Specialty Chemicals
Bemotrizinol Market
Specialty Chemicals
Europe Squalene Market
Specialty Chemicals
Global Acrylic Processing Aid Market
Specialty Chemicals
Global Chemical Vapor Deposition (CVD) Market
Specialty Chemicals
Marula Oil Market
Specialty Chemicals
Alkylene Carbonates Market
Specialty Chemicals
Allantoin Market
Specialty Chemicals
Asia Pacific Aerosol Cans Market
Specialty Chemicals
Polyether Modified Silicone Market
Specialty Chemicals
Barium Sulfate Market
Specialty Chemicals
Calcium D-Pantothenate Market
Specialty Chemicals
North America Sulfonylureas Market
Specialty Chemicals
Octocrylene Market
Specialty Chemicals
PEG and PPG Esters Market
Specialty Chemicals
North America Non-Phthalate Plasticizers Market