
 Sophorolipids Market | 2026-2036
Sophorolipids Market Size, Share, and Industry Trends Forecast 2026-2036
Sophorolipids Market Outlook
Specialty chemical distribution is fragmenting as biosurfactant suppliers bypass traditional bulk distributors to serve cosmetic and agricultural formulators directly. Holiferm S.à r.l. leverages continuous fermentation technology to anchor European supply of high-purity lactonic grades. Evonik Industries AG competes through backward integration into rapeseed oil feedstock networks across Germany. BASF SE extends its position by embedding sophorolipids into existing personal care ingredient portfolios.
Sophorolipids are glycolipid biosurfactants produced by yeast fermentation of hydrophobic substrates, typically comprising a sophorose disaccharide linked to a long-chain hydroxy fatty acid with critical micelle concentrations ranging from 40 to 100 mg/L depending on lactonic or acidic form. These compounds function as surface-active agents in formulations requiring biodegradability and low aquatic toxicity. Acidic sophorolipids dominate industrial cleaning applications where hard-water tolerance determines formulation value, while lactonic variants command premium positioning in personal care products due to superior foaming and antimicrobial synergy. The food industry segment remains nascent with EFSA Novel Food authorization pathways constraining near-term volume.
REACH registration requirements under ECHA enforce comprehensive toxicity dossiers for biosurfactant commercialization across EU member states. EPA Safer Choice program criteria in the United States steer institutional procurement toward sophorolipid-based cleaners in federal facilities. Stakeholders must monitor evolving biodegradability test protocols under OECD guidelines as regulatory divergence between jurisdictions reshapes formulation standardization requirements.
Market Dynamics
REACH compliance is forcing cosmetic formulators across Europe to replace petrochemical surfactants with ECHA-registered biosurfactants, redirecting procurement budgets toward fermentation-derived alternatives and rewiring supplier relationships.
Growth Catalysts
- REACH tightening:ECHA registration requirements for petrochemical surfactants are elevating sophorolipid priority in personal care formulations across Germany and France.
- Yeast fermentation advances:Continuous fermentation technology is reducing batch-to-batch variability and enabling lactonic grade consistency for high-end cosmetic applications.
- North Rhine-Westphalia cluster:Concentrated personal care manufacturing in this German industrial zone is creating localized demand pull for rapeseed oil-derived sophorolipids.
Market Restraints
- Feedstock volatility:Rapeseed oil price swings tied to EU agricultural policy are compressing margin predictability for fermentation-based producers.
- EFSA pathway delays:Novel Food authorization timelines for food-grade sophorolipids are extending commercialization horizons beyond typical investment cycles.
- Hard-water performance gaps:Acidic sophorolipid variants exhibit inferior calcium tolerance versus synthetic alternatives in industrial cleaning segments.
Strategic Opportunities
- EPA Safer Choice tailwind:Federal procurement criteria for institutional cleaning products are opening institutional volume in US government facilities.
- Agricultural adjuvant white space:Biosurfactant compatibility with biological crop protection agents is creating formulation partnerships with agrochemical distributors.
- Direct-to-formulator channels:Bypassing bulk chemical distributors is capturing margin and shortening technical service response times for specialty cosmetic producers.
Industry Challenges
- Fermentation scale-up talent scarcity:Industrial microbiology expertise for high-cell-density yeast cultivation remains concentrated among limited specialist personnel pools.
- OECD biodegradability protocol divergence:Inconsistent test methodologies across jurisdictions are complicating multi-regional product registration dossiers.
- Downstream processing capex intensity:Chromatographic separation equipment for lactonic-acidic fractionation demands substantial capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sophorolipids Market |
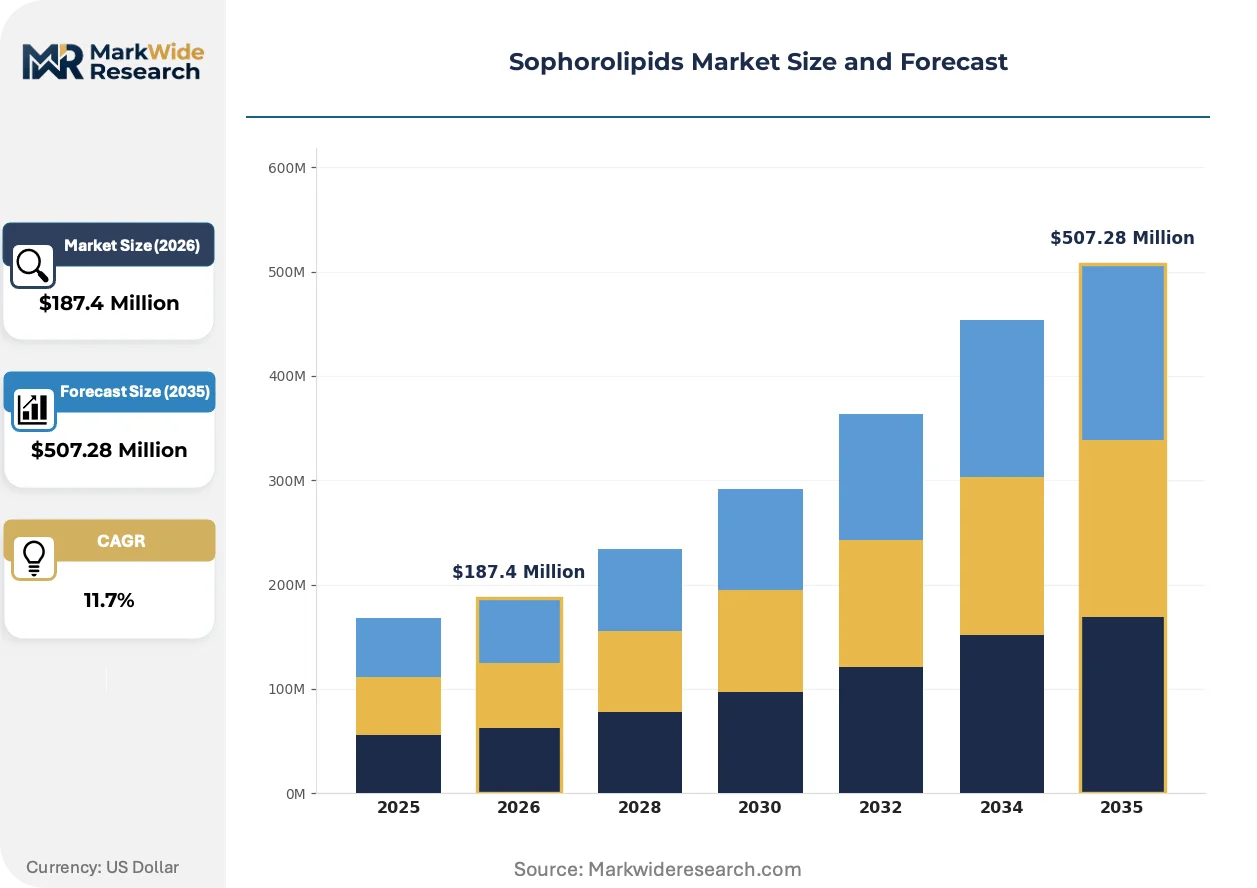
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Sophorolipids, Acidic Sophorolipids, Neutral Sophorolipids, Lactonic Sophorolipids Application: Personal Care Products, Household Cleaners, Agricultural Chemicals, Food Industry End User: Cosmetic Manufacturers, Cleaning Agents Producers, Agricultural Providers, Food Processing Companies Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Holiferm S.à r.l., Clariant AG, Evonik Industries AG, Biotensidon GmbH, BRAIN AG, Saraya Co., Ltd., Jeneil Biotech, Inc., Locus Bio-Energy Solutions, Inc., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sophorolipids Market Strategic Shifts
Fermentation technology and regulatory chemistry are converging to reshape how biosurfactants enter formulated products, with purity grades and certification pathways becoming primary competitive differentiators.
Continuous fermentation systems are hybridizing traditional batch yeast cultivation with real-time metabolite monitoring, enabling producers to modulate lactonic-to-acidic ratios during active growth phases rather than post-hoc separation. Cosmetic formulators in Germany are adopting these precision-grade outputs for antimicrobial synergy applications. The technology is hybridizing quality tiers, collapsing the historical premium gap between industrial and personal care grades.
REACH registration dossiers under ECHA now mandate comprehensive aquatic toxicity data for surfactant commercialization across EU member states, extending compliance timelines and elevating documentation costs for new market entrants. Industrial cleaning segments face the steepest compliance burden due to volume-based exposure assessments. Formulators are responding by consolidating supplier relationships around ECHA-registered producers with existing toxicity portfolios.
Buyer concentration among North Rhine-Westphalia personal care clusters is compressing supplier negotiation leverage and accelerating specification lock-in around preferred fermentation partners. Direct technical service engagements are displacing traditional distributor-mediated relationships for formulation support. This pattern is most visible in German cosmetic manufacturing, where procurement teams prioritize registered alternatives with embedded regulatory compliance.
Sophorolipids Market Segmentation
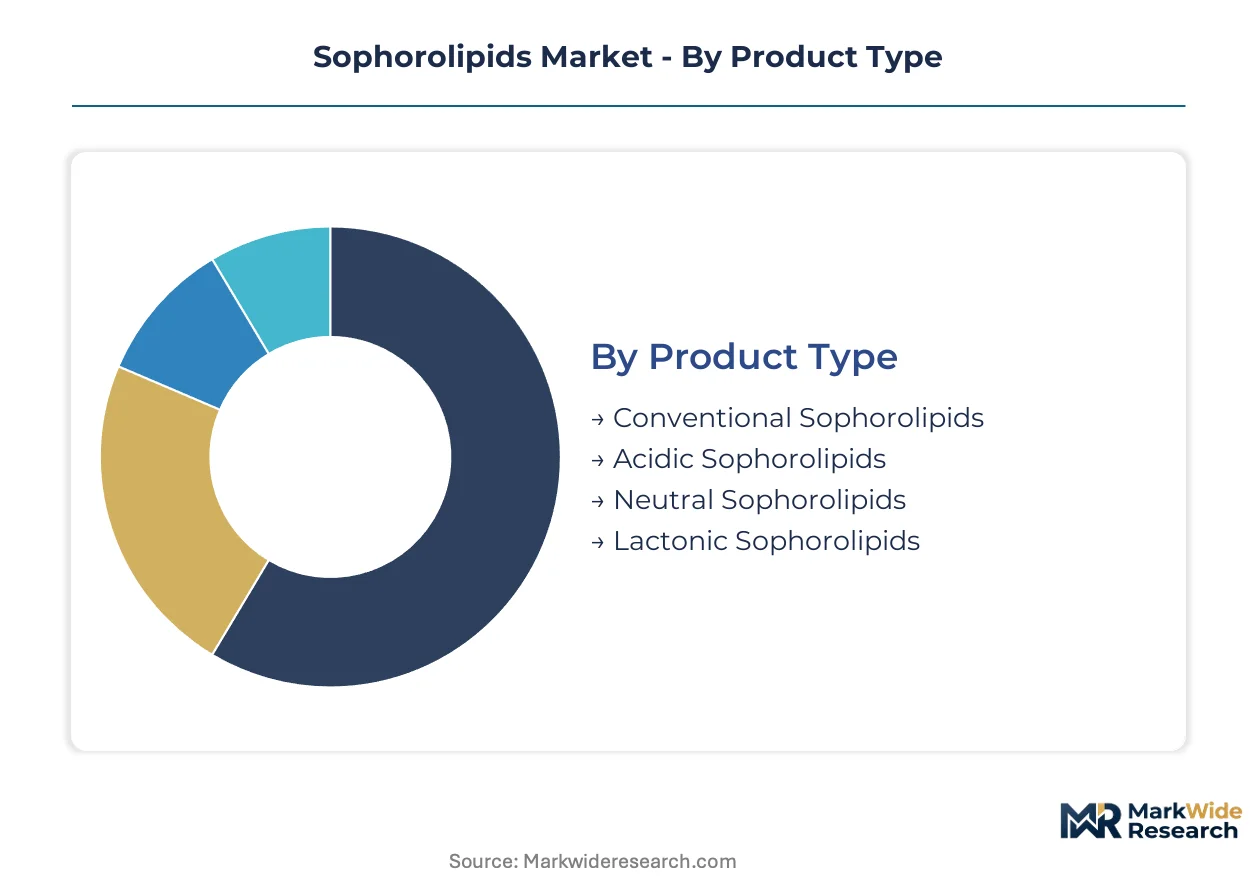
Sophorolipid commercialization hinges on precise matching between structural variants and regulatory-grade requirements. Formulators navigate lactonic-acidic polarity differences alongside REACH certification tiers when specifying procurement.
Product Type:
Lactonic sophorolipids command the longest production cycles due to downstream chromatographic separation, while conventional grades turn over fastest through standardized fermentation batches.
- Conventional Sophorolipids:Mixed lactonic-acidic compositions produced through unoptimized fermentation without fractionation. Demand concentrates in industrial cleaning applications across Germany where cost minimization outweighs purity requirements.
- Acidic Sophorolipids:Carboxyl-terminated variants with superior water solubility and hard-water tolerance. Cleaning agents producers in North Rhine-Westphalia specify these for institutional formulations where calcium compatibility determines performance.
- Neutral Sophorolipids:Chemically modified derivatives balancing hydrophilic-lipophilic properties for intermediate applications. Agricultural providers evaluate these for adjuvant compatibility with biological crop protection.
- Lactonic Sophorolipids:Intramolecular ester-bonded structures exhibiting enhanced foaming and antimicrobial synergy. Cosmetic manufacturers in France prioritize ECHA-registered lactonic grades for premium personal care formulations.
Conventional sophorolipids dominate installed base. Lactonic sophorolipids are where expansion concentrates.
Application:
Margin structures diverge sharply across use cases, with personal care commanding formulation premiums and agricultural applications driving volume scale.
- Personal Care Products:High-purity lactonic grades specified for antimicrobial and emulsification functions in skincare and haircare. REACH-registered alternatives from rapeseed oil fermentation anchor procurement in German cosmetic clusters.
- Household Cleaners:Acidic variants formulated for hard-surface detergency and biodegradability compliance. EPA Safer Choice criteria steer federal procurement toward sophorolipid-based institutional products in US government facilities.
- Agricultural Chemicals:Biosurfactant adjuvants enhancing biological pesticide spreading and penetration. Compatibility testing with microbial inoculants determines adoption timelines among European crop protection distributors.
- Food Industry:Novel Food authorization pathways under EFSA constrain near-term commercialization. Fermentation-derived emulsifiers await toxicity dossier completion for bakery and beverage applications.
Household cleaners represent the largest addressable volume. Personal care products generate the steepest expansion trajectory.
End User:
Technical service intensity varies by customer sophistication, with cosmetic formulators demanding specification support and agricultural buyers prioritizing logistics reliability.
- Cosmetic Manufacturers:Sophisticated procurement teams in North Rhine-Westphalia specify lactonic grades with embedded regulatory compliance. Direct supplier relationships displace distributor intermediaries for formulation troubleshooting.
- Cleaning Agents Producers:Volume purchasers of acidic variants for private-label and institutional product lines. Hard-water performance benchmarking drives supplier selection in German industrial zones.
- Agricultural Providers:Distributors and cooperatives evaluating biosurfactant adjuvants for biological crop protection compatibility. Field trial data requirements extend qualification cycles.
- Food Processing Companies:Prospective adopters awaiting EFSA Novel Food authorization completion. Early engagement focuses on emulsification performance in plant-based formulations.
Cleaning agents producers dominate current offtake. Cosmetic manufacturers concentrate expansion investment.
Distribution Channel:
Channel economics reflect order fragmentation, with bulk direct sales capturing margin and specialty stores serving small-batch formulators.
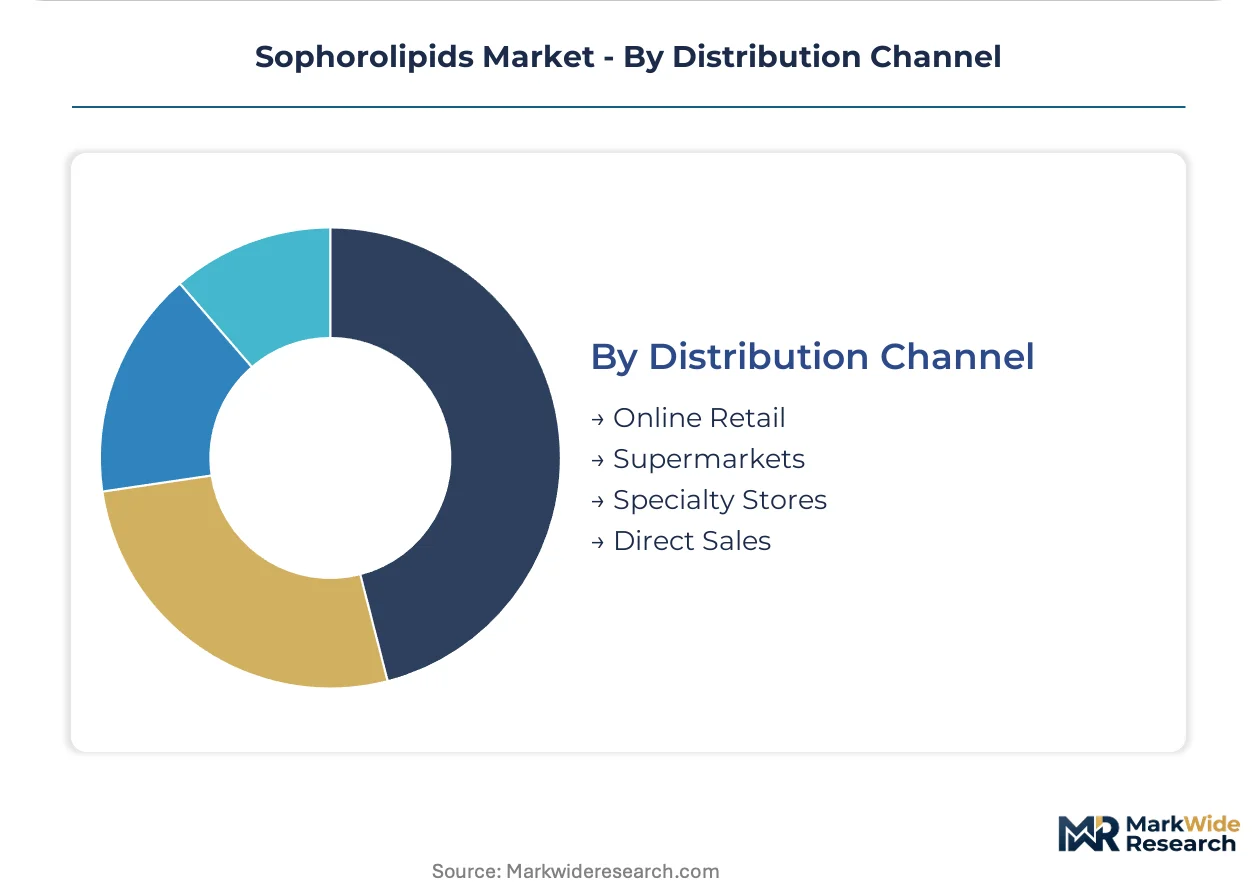
- Direct Sales:Technical service-embedded relationships with major cosmetic and cleaning formulators. Producers bypass bulk distributors to capture margin and accelerate specification lock-in.
- Online Retail:Sample and small-volume procurement for R&D laboratories and independent formulators. Digital channels reduce minimum order friction for novel grade evaluation.
- Specialty Stores:Regional chemical distributors serving mid-tier agricultural and industrial accounts. Local inventory buffers address just-in-time formulation requirements.
- Supermarkets:Limited presence for consumer-facing biosurfactant products. Shelf placement constraints restrict this channel to finished goods rather than raw materials.
Direct sales anchor producer margins. Online retail is gaining share fastest among emerging formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's North Rhine-Westphalia cluster, where REACH-registered lactonic grades command formulation premiums. Producers in France and the United States face compressed margins as regulatory compliance costs diverge across jurisdictions.
Germany
North Rhine-Westphalia's personal care manufacturing cluster drives concentrated demand for rapeseed oil-derived sophorolipids. ECHA registration requirements under REACH enforce comprehensive aquatic toxicity dossiers for surfactant commercialization. Cologne-Düsseldorf formulators prioritize ECHA-registered lactonic grades for premium cosmetic applications.
France
Cosmetic manufacturers in Île-de-France specify high-purity lactonic variants for antimicrobial synergy in skincare formulations. ANSM oversight aligns with REACH standards for biosurfactant safety documentation. Lyon-based formulators are consolidating supplier relationships around registered fermentation partners.
United States
EPA Safer Choice program criteria steer federal procurement toward sophorolipid-based institutional cleaners. Institutional buyers in government facilities specify biodegradable alternatives for hard-surface applications. Midwest agricultural distributors evaluate biosurfactant adjuvants for biological crop protection compatibility.
Japan
METI guidelines on chemical substance management shape biosurfactant commercialization timelines for personal care applications. Osaka-Kobe industrial zones house cosmetic formulators seeking fermentation-derived surfactants for export-oriented production. PMDA consultation pathways influence novel ingredient adoption in premium skincare.
India
BIS standards for surfactant quality create compliance benchmarks for imported biosurfactant grades. Maharashtra's personal care manufacturing corridor attracts technical service engagements from fermentation specialists. CDSCO regulatory clarity remains pending for cosmetic-grade sophorolipid incorporation.
Sophorolipids Market Competitive Environment
Specialized fermentation houses and diversified chemical conglomerates split the market into distinct capability tiers. The structure consolidates around producers with captive yeast cultivation expertise and those with backward integration into agricultural feedstock networks. Three archetypes dominate: continuous fermentation specialists, integrated oleochemical processors, and research-stage biotechnology ventures. Capacity expansion and direct-to-formulator channel development represent the primary competitive moves reshaping supplier relationships.
Among European fermentation specialists, Holiferm S.à r.l. and Biotensidon GmbH occupy positions emphasizing high-purity lactonic production. Evonik Industries AG exemplifies the integrated chemical major archetype with upstream control over rapeseed oil supply chains. These three entities represent contrasting strategic postures: specialized biotechnology scale-up, mid-cap fermentation focus, and diversified industrial chemical positioning.
| Leading Market Players |
|---|
| Holiferm S.à r.l. |
| Clariant AG |
| Evonik Industries AG |
| Biotensidon GmbH |
| BRAIN AG |
| Saraya Co., Ltd. |
| Jeneil Biotech, Inc. |
| Locus Bio-Energy Solutions, Inc. |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Antwerp barge freight corridors shape cost dynamics for rapeseed oil feedstock deliveries, concentrating supply leverage among North Rhine-Westpharia fermentation houses while forcing downstream price differentiation between REACH-registered lactonic grades and unregistered acidic variants.
Pricing Analysis
Customization-premium spreads separate ECHA-registered lactonic sophorolipids from conventional mixed-grade outputs. Contract-based long-term offtake dominates, with price differentiation driven by certification level and volume scale. Cost compression in conventional grades intensifies because rapeseed oil volatility feeds directly into fermentation economics. Cleaning agents producers exhibit highest price sensitivity, while cosmetic manufacturers absorb premiums for regulatory embeddedness.
Supply Chain Analysis
Extended payment terms from German cosmetic formulators are compressing working capital cycles for fermentation specialists. Supply concentrates in Germany, France, and Belgium, with raw material dependencies on rapeseed oil, yeast biomass, and chromatographic resins. Single-source vulnerability around continuous fermentation engineering talent constrains capacity expansion. Distribution runs through direct technical service relationships that bypass traditional bulk chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic alkyl polyglucosides and petrochemical surfactant incumbents threaten biosurfactant substitution timelines, forcing sophorolipid producers to defend formulation lock-in through regulatory certification and performance benchmarking.
For Market Incumbents: Harden specification lock-in by embedding ECHA-registered lactonic grades into cosmetic formulator R&D pipelines. Deepen backward integration into rapeseed oil crushing capacity across Germany to insulate margin from agricultural policy volatility. Synthetic surfactant price erosion in industrial cleaning demands defensive certification investment to maintain REACH-compliant positioning. For New Entrants and Emerging Players: US agricultural adjuvant applications remain underpenetrated relative to personal care saturation in Europe. Target Midwest crop protection distributors with compatibility data packages for biological pesticide formulations. A technical service-heavy go-to-market angle differentiates against established European suppliers lacking US field trial infrastructure. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical majors with dormant fermentation assets and stranded yeast cultivation expertise. Long-term viability hinges on regulatory tailwinds persisting across REACH and EPA jurisdictions. Watch EFSA Novel Food authorization timelines as the inflection signal for food-grade volume expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Fermentation Scale-Up | Holiferm's technology reduces batch variability for lactonic grade consistency in cosmetic applications. |
| Backward Integration into Feedstock | Evonik's rapeseed oil networks secure margin predictability against EU agricultural policy swings. |
| Direct-to-Formulator Channel Development | Bypassing bulk distributors captures technical service margin and accelerates specification lock-in. |
| EFSA Novel Food Dossier Investment | Early toxicity documentation positions producers for food emulsifier commercialization upon authorization. |
| EPA Safer Choice Certification | Federal procurement criteria open institutional volume in US government cleaning contracts. |
Study Parameters
A spread of perspectives from fermentation plant managers, cosmetic procurement leads, agricultural adjuvant distributors, and ECHA regulatory consultants converged on the working assumptions. Primary interviews combined with secondary validation from REACH registration databases, EU customs trade data, and SEC filings from listed chemical majors. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use industry, and regional regulatory cluster. CAGRs derived from installed fermentation capacity expansion schedules and formulator substitution timelines. Industry-specific inputs incorporated rapeseed oil price elasticity and EFSA authorization probability assessments.
Practitioners should monitor feedstock volatility, regulatory divergence between jurisdictions, and fermentation scale-up execution for early signals. Forecasts reflect assumptions about REACH enforcement continuity and biosurfactant performance parity with synthetics. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Tetrabromobisphenol a (TBBPA) Market
Specialty Chemicals
Perfluoroalkoxy Alkane (PFA) Market
Specialty Chemicals
Global Baking Soda Substitute Market
Specialty Chemicals
Perms and Relaxants Market
Specialty Chemicals
Stable Isotopes Market
Specialty Chemicals
Octofluoropropane Market
Specialty Chemicals
GLDA Market
Specialty Chemicals
AEA Salicylic Acid Market
Specialty Chemicals
Natural Phytosphingosine Market
Specialty Chemicals
Phytosphingosine Market
Specialty Chemicals
Sodium Adipate Market
Specialty Chemicals
Hydroxypropionic Acid Market
Specialty Chemicals
Releasing Agents Market
Specialty Chemicals
Global Water Based Acrylates Copolymer Rheology Modifiers Market
Specialty Chemicals
Global 28-Homobrassinolide Market
Specialty Chemicals
Asia Pacific Methyl Glucose Market