
 Global Blowing Agent Market | 2026-2036
Global Blowing Agent Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blowing Agent Market Foresight
Hydrofluorocarbon chemistry is shifting toward hydrocarbon and carbon dioxide alternatives as manufacturers recalibrate cost-performance equations under environmental compliance. Honeywell International Inc leverages its fluorine technology heritage to sustain patent-protected positions in next-generation low-GWP formulations. BASF anchors European supply through integrated polyol-blowing agent systems that lock in specification control with rigid foam processors. Arkema competes in azodicarbonamide specialties where thermal decomposition kinetics determine cell structure quality in vinyl foams.
A blowing agent is a substance that generates gas cells within polymer matrices during processing, typically decomposing thermally between 150°C and 220°C or volatilizing under heat-and-pressure conditions to yield controlled foam expansion. These agents reduce material density, improve thermal insulation performance, and enable cushioning or structural lightweighting across industrial applications. Hydrocarbon blowing agents dominate volume in refrigerator insulation and construction panels where lambda values below 20 mW/m·K justify flammability management costs. Carbon dioxide systems gain fastest in automotive seating and packaging where water-blown or liquid CO2 injection supports thinner-wall molding cycles. Azodicarbonamide retains mature positions in footwear manufacturing and PVC plastisol applications where fine cell structures and predictable decomposition profiles sustain processor loyalty.
The US EPA enforces phasedown schedules under the American Innovation and Manufacturing Act that restrict HFC imports and drive domestic reformulation investments. EMA and ECHA frameworks in Europe classify certain blowing agent residues under REACH evaluation protocols, forcing substitution timelines and toxicology dossier investments. China's MEE implements dual carbon goals that tighten emissions accounting for fluorochemical production chains. Stakeholders must monitor how regulatory phase-in calendars across these jurisdictions create supply discontinuities that favor early movers with certified alternative chemistries and backward-integrated raw material positions.
Market Dynamics
The F-Gas Regulation and EPA AIM Act are forcing simultaneous chemistry transitions across three continents, compressing reformulation timelines while suppliers race to certify hydrocarbon and carbon dioxide alternatives before phasedown deadlines.
Growth Catalysts
- Building Energy Codes:Tightening thermal performance mandates in Germany and the United States are specifying lambda values below 20 mW/m·K for construction panels, locking in polyurethane foam demand.
- REACH Evaluation Protocols:ECHA frameworks are accelerating substitution timelines for legacy blowing agent residues, creating pull-through for certified low-GWP formulations.
- Automotive Lightweighting:Water-blown and liquid CO2 injection systems are displacing heavier structural materials in seating and interior components across Chinese and German OEM supply chains.
Market Restraints
- Propane Cost Volatility:Hydrocarbon blowing agent economics track n-butane and isobutane feedstock swings, compressing margins for rigid foam processors without backward-integrated supply.
- Flammability Management Costs:Hydrocarbon systems require explosion-proof equipment and ventilation infrastructure that adds 15-25% to capital outlays versus HFC alternatives.
- Technical Limitation in Thin-Wall Molding:Carbon dioxide kinetics struggle to maintain cell structure integrity below 40mm wall thickness, constraining adoption in automotive interior trim.
Strategic Opportunities
- India Construction Growth:Bureau of Indian Standards energy efficiency mandates are emerging for commercial building envelopes, opening specification windows for polyurethane insulation systems.
- Electronics Packaging Convergence:Microcellular foam structures from supercritical CO2 processing are merging with anti-static additive technologies for semiconductor shipping applications.
- EU Green Deal Chemistry Incentives:Innovation fund allocations for fluorinated gas alternatives are subsidizing pilot-scale hydrocarbon and HFO production investments.
Industry Challenges
- Fluorine Chemistry Expertise Gap:Formulation chemists with HFO synthesis experience are concentrated at legacy fluorochemical majors, constraining talent mobility for mid-tier entrants.
- Dual Certification Burden:Suppliers must simultaneously satisfy EPA SNAP approvals and EU F-Gas quota allocations, stretching regulatory affairs bandwidth across divergent timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blowing Agent Market |
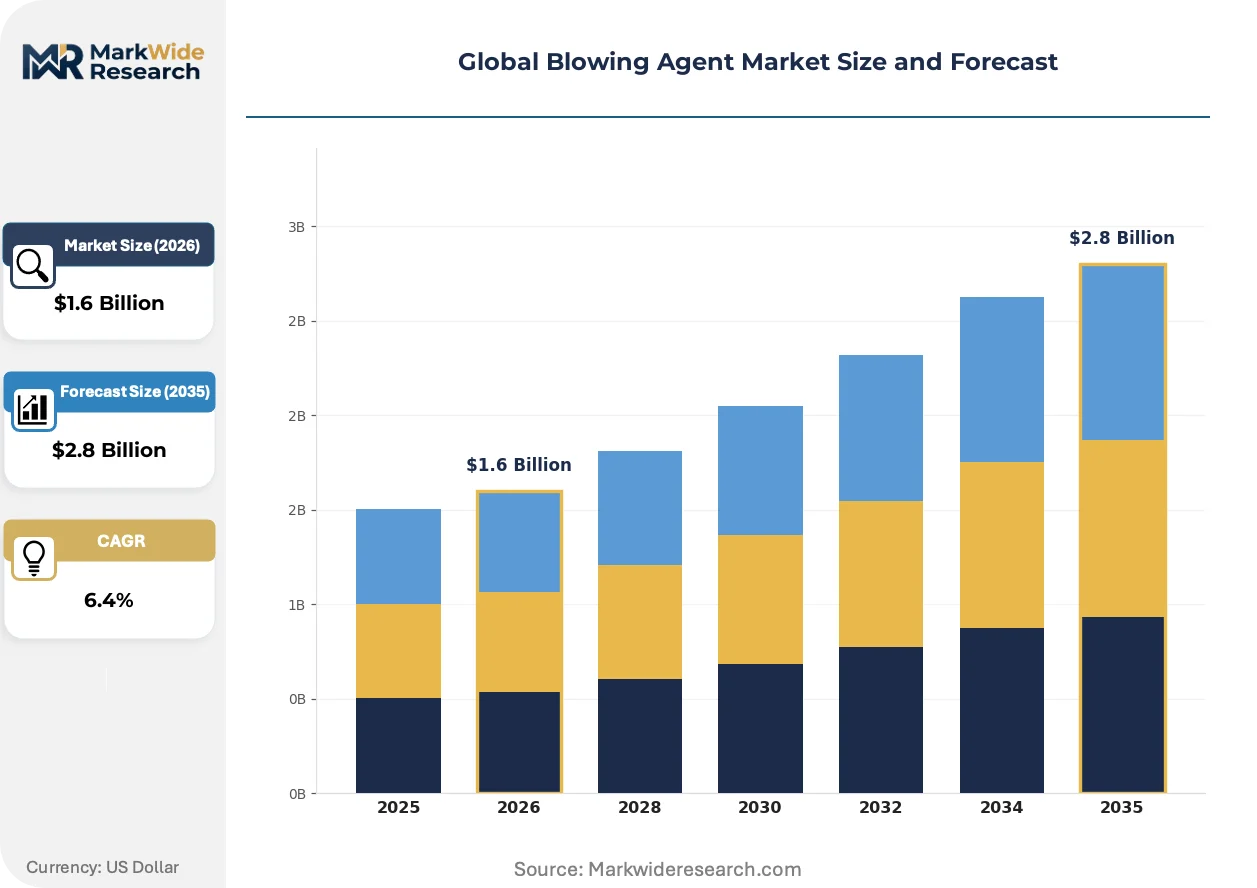
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $2.8 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Azodicarbonamide, Hydrofluorocarbons, Carbon Dioxide, Hydrocarbons, Nitrogen Application: Foam Insulation, Packaging, Automotive Seats, Shoe Soles, Construction Panels End User Industry: Construction, Footwear Manufacturing, Automotive OEMs, Consumer Goods, Electronics Form: Granules, Powder, Liquid, Pelletized, Emulsion |
| Companies Covered | The Chemours Company, BASF, Honeywell International Inc, Zeon Corporation, Huntsman International LLC, Arkema, Solvay, Sinochem Group Co Ltd, Nouryon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blowing Agent Market Shifts & Advancements
Formulation automation and real-time cell-structure monitoring are compressing development cycles, while regulatory phasedowns force chemistry pivots faster than historical replacement rates.
Supercritical CO2 injection systems are automating density control in automotive seating production. Tier-1 suppliers in Germany and the United States are retrofitting existing polyurethane lines with precision mass-flow controllers that adjust blowing agent ratios millisecond-by-millisecond. This compression of process variance is enabling thinner-wall designs without sacrificing insulation performance.
The EU F-Gas Regulation's quota allocation mechanism is reallocating fluorochemical production capacity toward metered-dose inhalers and semiconductor etching, squeezing blowing agent supply. Refrigerator manufacturers in Poland and Italy are accelerating hydrocarbon line conversions ahead of 2027 quota cuts. This regulatory compression is fragmenting supply chains as processors dual-source HFO and hydrocarbon alternatives.
Specification control is migrating upstream to integrated polyol-blowing agent systems. Rigid foam processors in China and the United States are accepting locked formulations from chemical suppliers rather than blending in-house, transferring technical risk and inventory burden. This consolidation of formulation authority favors suppliers with captive polyol production and certified low-GWP agent supply.
Global Blowing Agent Market Segmentation
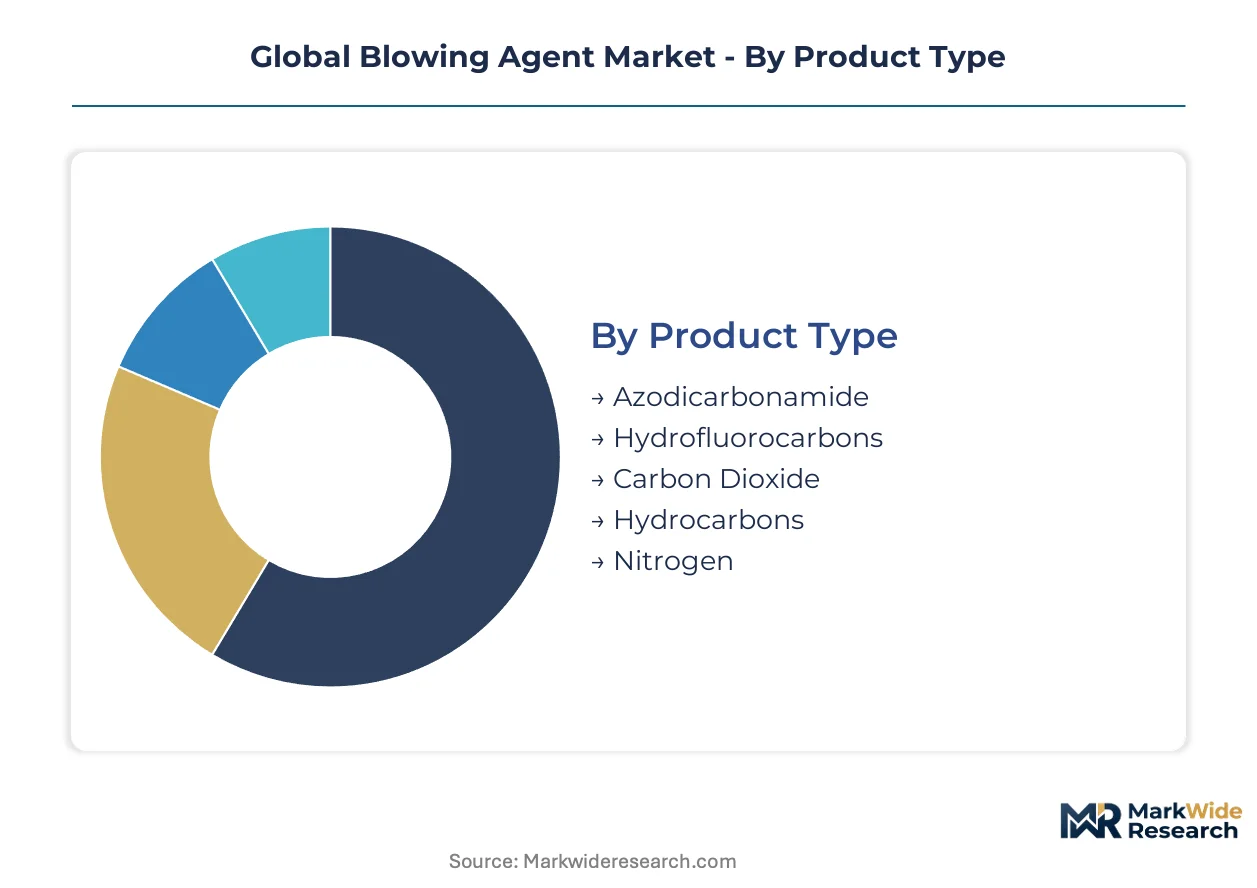
Blowing agent selection cascades through polymer compatibility, thermal kinetics, and regulatory compliance. Each segment category reflects distinct trade-offs between lambda performance, flammability profiles, and capital intensity that processors must navigate.
Product Type:
Volume concentration sits with hydrocarbon systems, while premium positioning clusters around next-generation low-GWP fluorinated alternatives.
- Hydrocarbons:Isobutane and n-butane formulations deliver lambda values below 20 mW/m·K in rigid polyurethane construction panels. Demand concentrates in Germany and China where building energy codes mandate thermal performance that justifies explosion-proof equipment investments.
- Hydrofluorocarbons:Legacy HFC-245fa and HFC-365mfc chemistries retain installed-base positions in appliance insulation. The US EPA AIM Act phasedown and EU F-Gas quota cuts are forcing accelerated substitution timelines across refrigerator manufacturing clusters in Poland and Italy.
- Carbon Dioxide:Water-blown and liquid CO2 injection systems dominate automotive seating applications where thinner-wall molding cycles support lightweighting targets.
- Azodicarbonamide:Thermal decomposition between 150°C and 220°C yields fine cell structures for PVC plastisol footwear applications.
- Nitrogen:Physical blowing via gas injection supports microcellular foam structures in electronics packaging where dimensional stability is critical.
Today's leader: Hydrocarbons. Tomorrow's challenger: Carbon Dioxide.
Application:
Construction and automotive applications split the market between thermal insulation mandates and structural lightweighting programs.
- Construction Panels:Rigid polyurethane foam systems anchor volume consumption. Germany's EnEV thermal regulations and comparable US IECC code tiers specify lambda performance that locks in hydrocarbon and HFO demand.
- Foam Insulation:Appliance and building envelope applications span refrigerator cabinets to spray foam roofing. China's dual carbon goals under MEE oversight are tightening emissions accounting for fluorochemical production chains serving this segment.
- Automotive Seats:Water-blown polyurethane systems from supercritical CO2 injection displace heavier structural materials across German and Chinese OEM supply chains.
- Packaging:Microcellular structures protect semiconductor and consumer electronics shipments.
- Shoe Soles:Azodicarbonamide-based PVC and EVA foams serve mass-market footwear manufacturing.
Construction Panels command current volume. Automotive Seats are climbing the fastest as OEM lightweighting accelerates.
End User Industry:
Construction sector procurement dominates absolute volume, while automotive and electronics verticals drive specification innovation.
- Construction:Commercial and residential building envelopes consume rigid foam insulation at scale. India's Bureau of Indian Standards is emerging with energy efficiency mandates that will open specification windows for polyurethane systems.
- Automotive OEMs:Tier-1 seating and interior component suppliers in Germany and the United States are retrofitting lines with precision mass-flow controllers for CO2 injection.
- Footwear Manufacturing:Azodicarbonamide demand concentrates in mass-market shoe production where cell structure consistency determines processor loyalty.
- Consumer Goods:Appliance manufacturers face simultaneous EPA SNAP and EU F-Gas compliance deadlines.
- Electronics:Anti-static microcellular foams merge with supercritical CO2 processing for semiconductor shipping applications.
Construction holds installed-base dominance. Electronics represents the steepest expansion trajectory as packaging convergence accelerates.
Form:
Physical form selection tracks handling automation, dispersion uniformity, and downstream processing temperature windows.
- Liquid:Hydrocarbon and HFO formulations enable precision metering in continuous panel production. German and US rigid foam processors favor liquid delivery for locked polyol-blowing agent systems that transfer technical risk upstream.
- Powder:Azodicarbonamide powders dominate footwear and PVC plastisol applications where thermal decomposition kinetics must integrate with processing temperatures between 150°C and 220°C.
- Granules:Solid physical blowing agents support controlled release profiles in extruded polystyrene applications.
- Pelletized:Masterbatch formats simplify handling in compounding operations.
- Emulsion:Water-based dispersions serve specialty applications requiring uniform cell nucleation.
Liquid leads on automation compatibility. Powder defends mature positions in thermal decomposition applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's rigid polyurethane cluster anchors global blowing agent specification development. Construction panel manufacturers in Bavaria and North Rhine-Westphalia set thermal performance benchmarks that cascade through European supply chains. Regulatory compression across three continents is fragmenting procurement patterns as processors dual-source hydrocarbon and HFO alternatives ahead of phasedown deadlines.
United States
Building envelope retrofits and appliance insulation drive hydrocarbon and HFO demand across the Midwest and Southeast manufacturing belts. The EPA enforces phasedown schedules under the AIM Act that restrict HFC imports and accelerate domestic reformulation investments. Tier-1 automotive seating suppliers in Michigan and Ohio are retrofitting lines with precision mass-flow controllers for supercritical CO2 injection.
Germany
Construction panel manufacturers and refrigerator OEMs concentrate blowing agent procurement in the Rhine-Ruhr and Bavarian industrial corridors. The EU F-Gas Regulation's quota allocation mechanism squeezes blowing agent supply while redirecting fluorochemical capacity toward pharmaceutical and semiconductor applications. Rigid foam processors in Leverkusen and Ludwigshafen are accepting locked polyol-blowing agent systems that transfer technical risk upstream to chemical suppliers.
China
Dual carbon goals under MEE oversight tighten emissions accounting for fluorochemical production chains serving construction and automotive sectors. The country's building energy code expansion and automotive lightweighting programs expand polyurethane foam consumption. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta are integrating hydrocarbon blowing agent capacity with captive polyol production.
India
Commercial building envelope expansion and emerging appliance manufacturing drive specification windows for polyurethane insulation systems. The Bureau of Indian Standards is developing energy efficiency mandates that will open procurement channels for low-GWP formulations. Construction material processors in Maharashtra and Gujarat are evaluating hydrocarbon system conversions ahead of anticipated regulatory phase-ins.
Poland
Refrigerator cabinet manufacturing anchors blowing agent demand as OEMs accelerate hydrocarbon line conversions ahead of 2027 EU quota cuts. The F-Gas Regulation's compression is fragmenting supply chains across the Central European appliance belt. Manufacturing facilities in Wrocław and Poznań are dual-sourcing HFO and hydrocarbon alternatives to manage discontinuity risk.
Global Blowing Agent Market Competitive Landscape
Global majors compete with regional champions across formulation integration and regulatory certification bandwidth. The supplier base organizes around three tiers: integrated chemical conglomerates with captive polyol production, fluorochemical specialists with HFO synthesis heritage, and regional hydrocarbon distributors serving construction panel processors. Strategic moves concentrate on backward integration into raw material positions and simultaneous dual-certification investments for EPA SNAP and EU F-Gas compliance.
Within the integrated chemical tier, BASF and Honeywell International Inc occupy positions that exemplify divergent competitive approaches to low-GWP transition. BASF anchors European supply through formulation systems that lock in specification control with rigid foam processors. Honeywell International Inc leverages fluorine technology heritage to sustain patent-protected positions in next-generation formulations. Arkema represents the specialty chemical archetype where azodicarbonamide thermal decomposition expertise defends mature positions in footwear and vinyl foam applications.
| Leading Market Players |
|---|
| The Chemours Company |
| BASF |
| Honeywell International Inc |
| Zeon Corporation |
| Huntsman International LLC |
| Arkema |
| Solvay |
| Sinochem Group Co Ltd |
| Nouryon |
| Others |
Supply & Pricing Matrix
Formulation chemists with HFO synthesis expertise cluster in Germany and the United States, creating labor-cost differentials that widen pricing spreads between premium fluorinated formulations and commodity hydrocarbon alternatives. This concentration of technical talent allows integrated suppliers to command specification premiums while regional distributors compete on feedstock arbitrage.
Pricing Analysis
Input-cost pass-through from isobutane and n-butane feedstock volatility dominates pricing dynamics for hydrocarbon blowing agents, with contract-based long-term offtake structures common among rigid foam processors seeking margin stability. Price differentiation separates EPA SNAP-certified low-GWP formulations from uncertified alternatives, while volume scale and after-sales technical service anchor tier positioning. Cost compression in standard-grade hydrocarbons is intensifying because backward-integrated Chinese suppliers are expanding export capacity. Small and mid-tier construction panel processors exhibit highest price sensitivity, whereas refrigerator OEMs prioritize certification compliance over unit cost.
Supply Chain Analysis
Certification gating through EPA SNAP approvals and EU F-Gas quota allocations fragments supplier eligibility, concentrating compliant production in Germany, China, and the United States. Raw material dependencies span fluorochemical feedstocks, petroleum-derived alkanes, and azodicarbonamide precursors. Single-source vulnerability runs through European HFO production capacity as quota reallocations divert fluorochemical output toward pharmaceutical applications. Distribution runs through locked polyol-blowing agent systems that transfer formulation authority upstream to integrated chemical suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Blowing Agent Market functions as a geographic-arbitrage play where regulatory phase-in calendars between the US EPA AIM Act and EU F-Gas Regulation create timing windows for early movers with dual-certified alternative chemistries.
For Market Incumbents: Extend formulation automation investments to compress development cycles for hydrocarbon and carbon dioxide alternatives ahead of phasedown deadlines. Deepen backward integration into captive polyol production to lock in specification control with rigid foam processors facing simultaneous EPA and EU compliance burdens. Threat substitution from Chinese suppliers with state-subsidized capacity buildouts demands defensive capacity positioning in India and Poland. For New Entrants and Emerging Players: Mid-tier automotive seating suppliers in China's Yangtze River Delta represent an underserved buyer archetype seeking precision CO2 injection systems without legacy HFC conversion baggage. White-space targets include supercritical CO2 processing equipment for electronics packaging and hydrocarbon system retrofits for India's emerging construction panel market. A technical-partnership go-to-market angle with German Tier-1 seating suppliers accelerates credibility transfer. For Investors and Strategic Acquirers: Integrated chemical conglomerates with captive fluorochemical production are the most active acquirer in this space, seeking HFO synthesis expertise to fill capability gaps. Long-term viability across the projection horizon hinges on regulatory certification bandwidth rather than feedstock cost position. Acquisition target archetypes include regional hydrocarbon distributors with EPA SNAP approval progress and azodicarbonamide specialists with thermal decomposition IP. The signal to monitor is EU F-Gas quota auction clearing prices as inflection indicator for HFO supply economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Production | Captive supply of polyol-blowing agent systems locks specification control with BASF and Huntsman processors in Germany. |
| Dual Certification Investment | Simultaneous EPA SNAP and EU F-Gas compliance stretches regulatory bandwidth but secures procurement eligibility across Atlantic supply chains. |
| Hydrocarbon Line Conversion | Refrigerator OEMs in Poland and Italy accelerate equipment retrofitting ahead of 2027 quota cuts under EU F-Gas Regulation. |
| Supercritical CO2 Automation | Precision mass-flow controllers enable Tier-1 automotive seating suppliers in Michigan and Ohio to achieve thinner-wall designs. |
| Regional Capacity Expansion | Manufacturing footprint additions in India and Poland capture construction growth and appliance cluster demand respectively. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with plant managers at rigid foam processing facilities, procurement leads at appliance OEMs, distribution channel partners in construction chemicals, and technical R&D directors at fluorochemical majors. Secondary validation draws from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA SNAP approval databases. Bottom-up volume modeling triangulates against top-down regulatory quota allocations and building energy code adoption timelines.
Rate-of-change decomposition separates volume growth into construction panel thermal mandate expansion, automotive lightweighting program acceleration, and appliance insulation replacement cycles across the analysis window. Segmentation dimensions span chemistry type, physical form, application, and regional production hub. CAGRs derive from regression against historical phasedown substitution patterns and correlated construction spending indices. Industry-specific inputs include EU F-Gas quota auction data and MEE emissions accounting protocols for fluorochemical production chains.
Underlying measurement precision varies by segment; hydrocarbon blowing agents carry tighter precision than emerging carbon dioxide systems where adoption curves remain uncertain. Forecasts reflect assumptions around regulatory phase-in calendars and feedstock cost trajectories. A model refresh is warranted upon material change in EPA SNAP approval timelines or EU F-Gas quota allocation mechanics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Myrcene Market
Specialty Chemicals
Specialty Chemicals Market
Specialty Chemicals
Zinc Methionine Chelates Market
Specialty Chemicals
Global Prepacked Chromatography Columns Market
Specialty Chemicals
4-Benzoylbutyric Acid Market
Specialty Chemicals
Naphthol AS-IRG Market
Specialty Chemicals
L-Ergothioneine Market
Specialty Chemicals
Protein Purification Resin Market
Specialty Chemicals
Rosin Press Market
Specialty Chemicals
Shikimic Acid Market
Specialty Chemicals
Titanium Fluoride Phosphate Market
Specialty Chemicals
Organosilicon Electrolyte Market
Specialty Chemicals
United States Aerosol Cans Market
Specialty Chemicals
Salicylate Market
Specialty Chemicals
Immunochemistry Products Market
Specialty Chemicals
Prils Market