
 Eitelite Market | 2026-2036
Eitelite Market Size, Share, and Industry Trends Forecast 2026-2036
Eitelite Market Analysis
ISO 9001 quality management certification is unwinding the competitive landscape for mineral suppliers serving precision industries. Imerys leverages its integrated quarry-to-mill operations across European deposits to sustain consistent feedstock quality. Huber Engineering Materials anchors North American supply through specialized precipitation and classification assets.
Eitelite is a naturally occurring carbonate mineral composed of equimolar magnesium carbonate and sodium carbonate, typically processed to controlled particle sizes between 5 and 50 microns for industrial use. Pure Eitelite commands premium positioning in electronics-grade applications where thermal stability and low iron content prove critical. Composite Eitelite formulations lead construction sector volumes, while Eitelite Powder dominates coatings demand due to superior dispersion characteristics in waterborne systems.
REACH registration requirements in Europe, EPA mining oversight in the United States, and China's GB standards for industrial mineral purity collectively shape product specifications and market access conditions. The EU Green Deal carbon border adjustments are redirecting sourcing decisions toward lower-emission processing routes. Stakeholders must monitor evolving chemical hazard classifications and align certification investments with end-user qualification protocols.
Market Dynamics
Specialty coatings manufacturers in Germany and Japan are consolidating procurement around ISO 9001-certified mineral suppliers, compressing supplier qualification timelines and elevating feedstock purity requirements across precision industrial applications.
Growth Catalysts
- Semiconductor packaging expansion:South Korean fabrication facilities are scaling advanced interconnect substrates, driving specification-grade Eitelite consumption for thermal management compounds. This end-use vertical commands premium purity thresholds.
- REACH chemical registration:Stricter ECHA documentation requirements in Europe are redirecting formulation strategies toward certified mineral sources with pre-validated hazard profiles, advantaging established quarry-to-mill operators.
- Carbon border adjustments:EU Green Deal mechanisms are penalizing high-emission processing routes, creating sourcing advantages for deposits with integrated low-carbon beneficiation infrastructure.
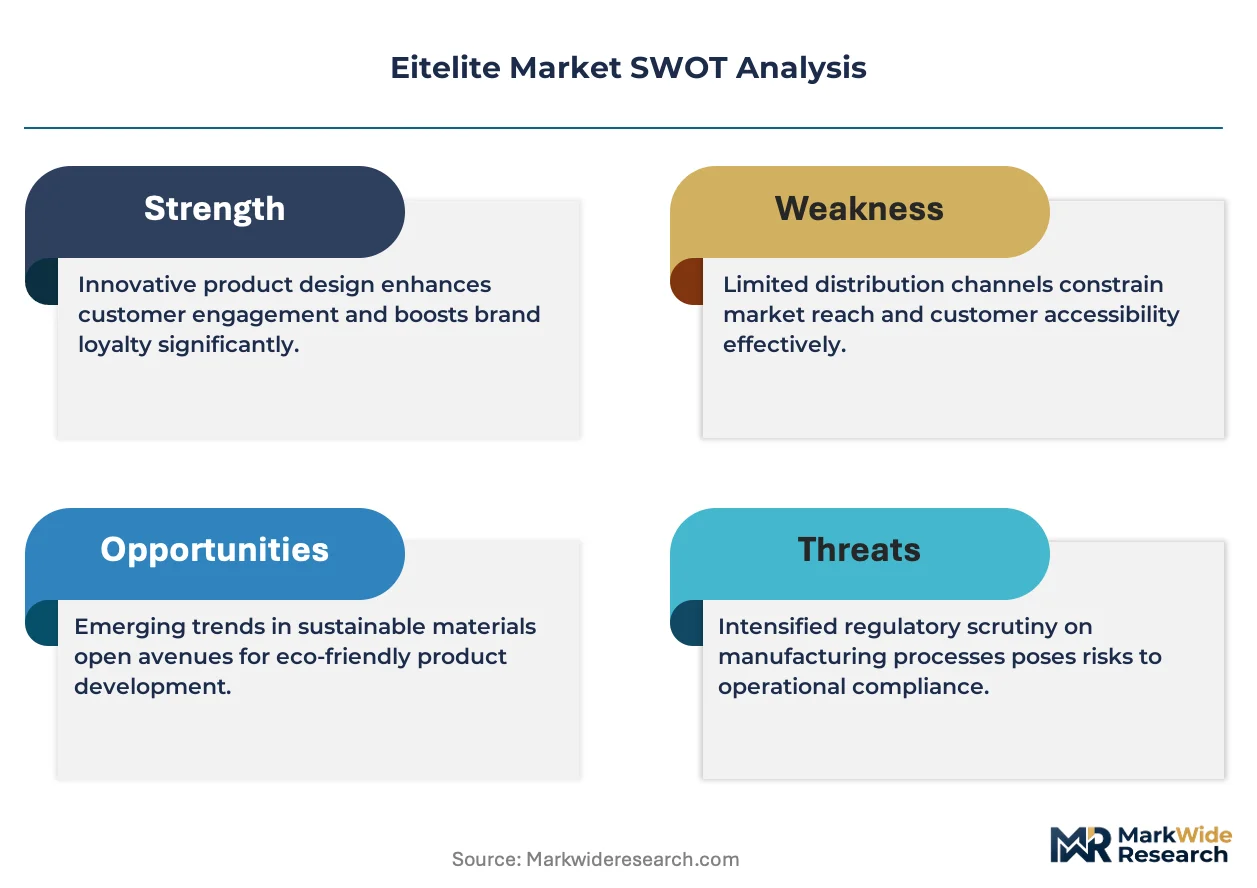
Market Restraints
- Deposit concentration risk:Commercial-grade Eitelite sourcing concentrates in limited European and North American mining districts, exposing supply chains to localized geological or permitting disruptions.
- Iron contamination thresholds:Electronics-grade applications demand sub-50 ppm iron content, a technical limitation that rejects substantial raw ore volumes and compresses effective yield rates.
- Substitute mineral competition:Synthetic magnesium carbonate and precipitated calcium carbonate formulations compete in cost-sensitive construction applications, capping price realization in volume segments.
Strategic Opportunities
- East Asian electronics corridors:Chinese and South Korean semiconductor packaging operations represent underpenetrated demand centers for high-purity Eitelite thermal interface materials.
- Waterborne coatings transition:Formulation houses are reformulating solvent-based systems to meet VOC regulations, creating specification openings for Eitelite Powder with superior aqueous dispersion characteristics.
- Dual carbon policy alignment:China's MIIT industrial mineral purity standards and carbon intensity targets are converging, rewarding processors with verified low-emission quarry-to-mill operations.
Industry Challenges
- Metallurgical assay specialization:Precise quantification of trace element distributions requires inductively coupled plasma mass spectrometry capabilities scarce outside major industrial mineral testing laboratories.
- REACH registration timelines:Full substance dossier preparation for ECHA submission demands 18-24 month certification cycles, delaying market access for new deposit developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eitelite Market |
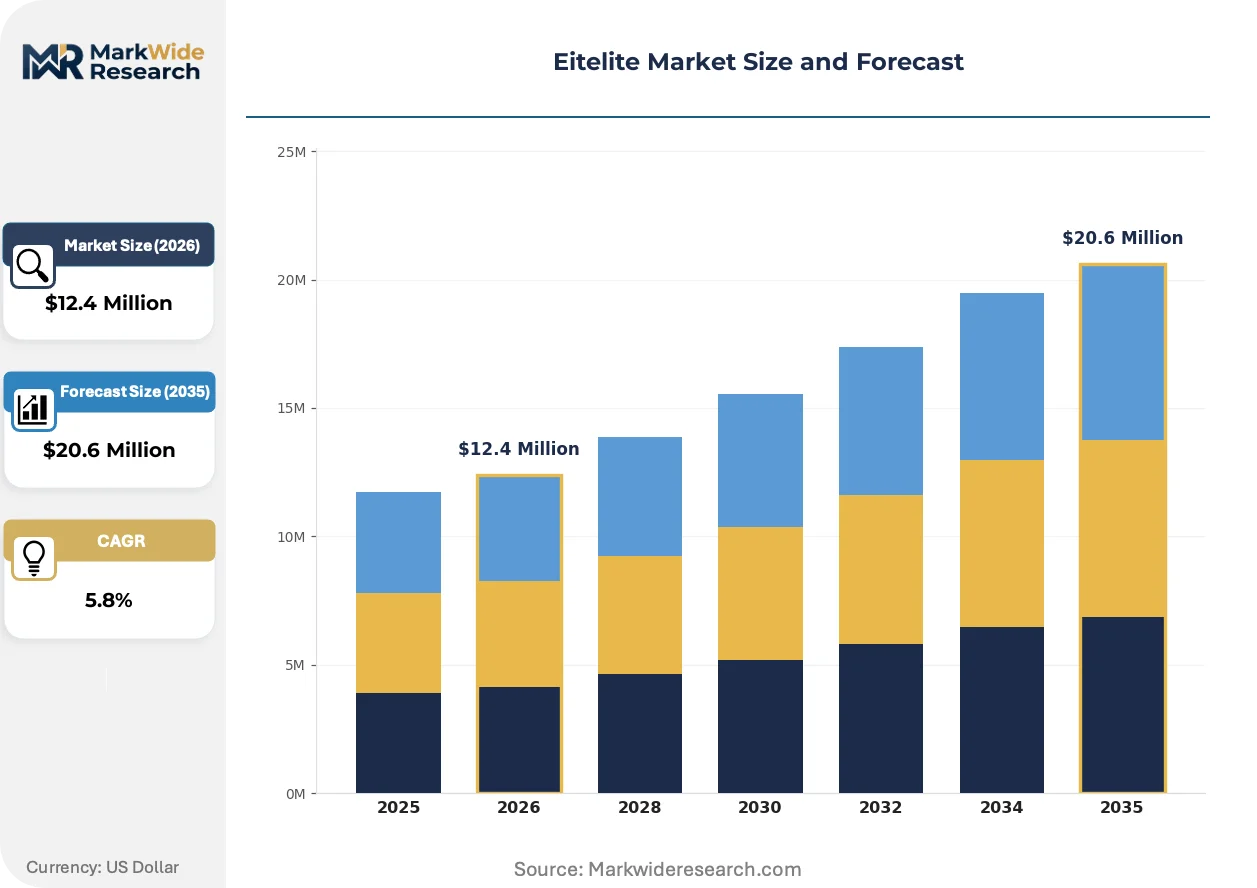
| Market Size in 2026 | $12.4 Million |
| Market Size in 2035 | $20.6 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite Eitelite, Pure Eitelite, Eitelite Powder, Eitelite Granules Application: Construction, Electronics, Coatings, Aerospace End User: Manufacturers, Contractors, R&D Institutions, Retailers Packaging Type: Bags, Bulk Containers, Drums, Cartons |
| Companies Covered | Imerys, Sibelco, Huber Engineering Materials, Schaefar Kalk GmbH & Co. KG, Excalibar Minerals LLC, Franklin Minerals, Mississippi Lime Company, Eitelite Corp., Global Eitelite Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eitelite Market Emerging Trajectories
Particle engineering and regulatory chemistry are converging to redefine mineral qualification protocols, with downstream industries imposing stricter compositional boundaries on carbonate feedstocks.
Controlled precipitation synthesis is decomposing traditional reliance on naturally variable quarry outputs. Korean semiconductor packaging manufacturers are adopting engineered Eitelite with sub-10 micron particle distributions and guaranteed thermal expansion coefficients. This specification discipline is compressing acceptable feedstock variance and disqualifying unprocessed mineral concentrates from precision thermal management applications.
ECHA REACH authorization requirements are tightening substance volume thresholds and expanding safety data sheet obligations. Specialty coatings formulators must now document full supply chain provenance for carbonate minerals, accelerating third-party certification adoption. German automotive coating operations are responding by mandating ISO 9001 and ISO 14001 dual certification from all mineral suppliers.
Direct mill-to-formulator contracting is displacing layered mineral trading networks in high-purity segments. Japanese electronics chemical distributors are ceding procurement authority to semiconductor packaging houses with dedicated raw material qualification teams. This channel compression is most visible in South Korean and Taiwanese fabrication corridors where vertical integration into mineral sourcing is strengthening buyer negotiating position.
Eitelite Market Segmentation
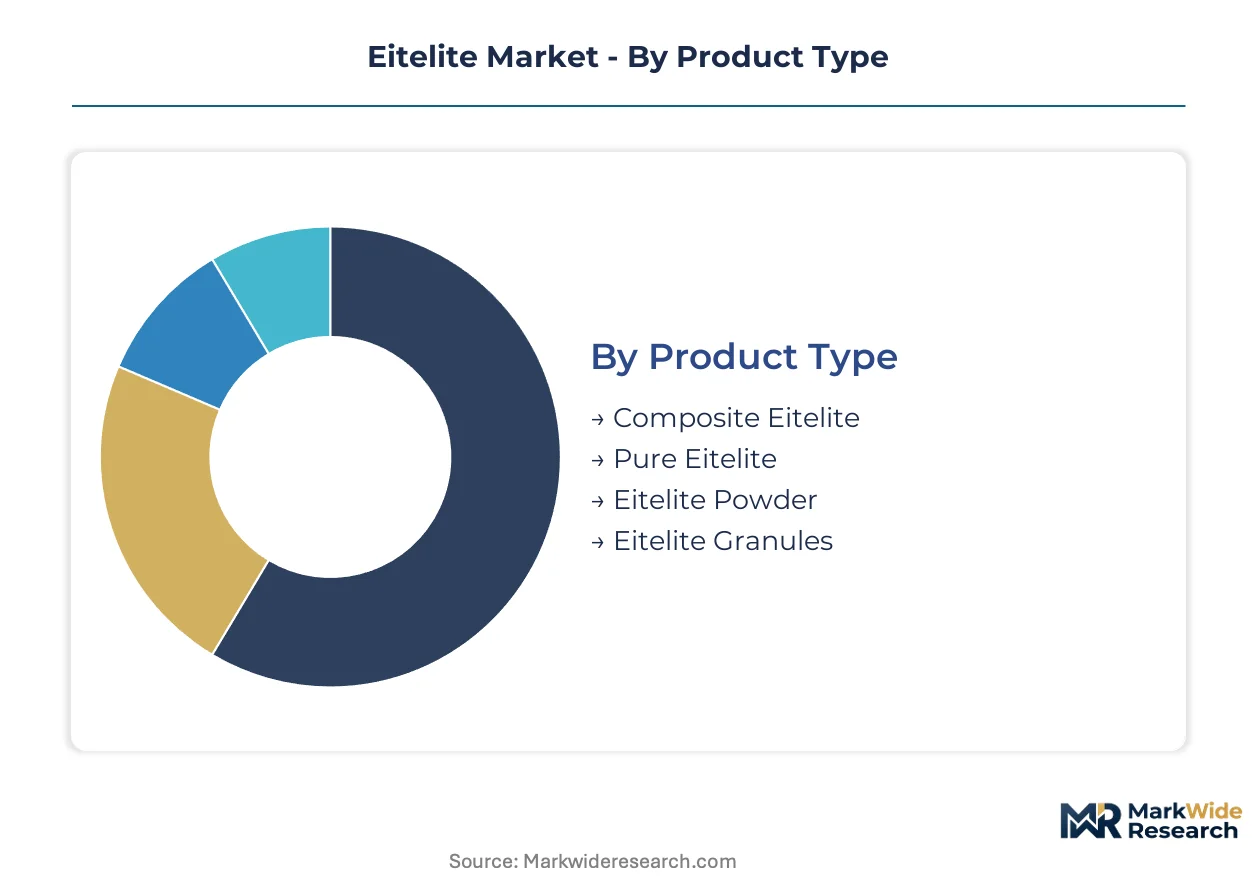
Eitelite segmentation reveals divergent supply chain architectures across product grades and end-use verticals. Specification-grade streams serve export-intensive electronics corridors, while construction-grade volumes anchor domestic industrial mineral networks. Understanding these segment boundaries clarifies procurement positioning and margin capture opportunities.
Product Type:
Pure Eitelite and Eitelite Powder dominate cross-border trade flows into East Asian semiconductor packaging operations, while Composite Eitelite and Granules largely serve regional construction material suppliers with shorter logistics loops.
- Pure Eitelite:Naturally occurring equimolar magnesium-sodium carbonate mineral processed to sub-50 ppm iron content for electronics-grade thermal management compounds. South Korean semiconductor packaging facilities are scaling advanced interconnect substrate production, tightening purity qualification protocols and compressing supplier pools to ISO 9001-certified quarry-to-mill operators.
- Eitelite Powder:Finely milled carbonate with controlled 5-50 micron particle distributions engineered for superior aqueous dispersion in waterborne coating systems. German automotive coating formulators are mandating REACH-registered supply sources with pre-validated hazard profiles, redirecting procurement toward established European mineral processors.
- Composite Eitelite:Blended formulations with controlled impurity profiles serving volume construction applications where cost efficiency outweighs premium purity thresholds.
- Eitelite Granules:Coarse particulate grades optimized for bulk handling in cementitious systems and industrial flooring compounds.
Composite Eitelite holds the largest share; momentum sits with Pure Eitelite.
Application:
Margin structures diverge sharply across application verticals, with electronics and aerospace commanding specification premiums while coatings and construction compete on throughput efficiency.
- Electronics:Thermal interface materials for semiconductor packaging and advanced interconnect substrates demand sub-10 micron particle engineering with guaranteed thermal expansion coefficients. Korean fabrication facilities are disqualifying unprocessed mineral concentrates from precision thermal management applications.
- Coatings:Waterborne and solvent-based formulation systems leverage Eitelite's dispersion characteristics and chemical inertness. VOC regulatory pressures in Germany and Japan are accelerating solvent-to-water transitions, expanding specification openings for certified powder grades.
- Construction:Cement additives, industrial flooring, and specialty concrete applications consume volume-grade carbonate with relaxed iron thresholds.
- Aerospace:Lightweight composite fillers and high-temperature insulation systems require trace-element documentation and full supply chain provenance.
Construction commands current volume leadership; electronics exhibits the steepest expansion trajectory.
End User:
Procurement authority is concentrating in direct manufacturer relationships, with layered distributor networks losing ground in specification-grade segments.
- Manufacturers:Specialty coatings and electronics chemical producers with dedicated raw material qualification teams are compressing supplier tiers. Japanese semiconductor packaging houses are ceding procurement authority from traditional mineral distributors.
- Contractors:Construction sector volume buyers prioritize logistics reliability and bulk pricing over certification depth.
- R&D Institutions:Materials science laboratories and applied research centers source small-lot specification grades for prototype development and process validation.
- Retailers:Specialty chemical distributors and industrial mineral traders serve fragmented regional demand with limited technical support capabilities.
Manufacturers represent the dominant procurement channel; R&D Institutions are expanding most quickly as product development cycles accelerate.
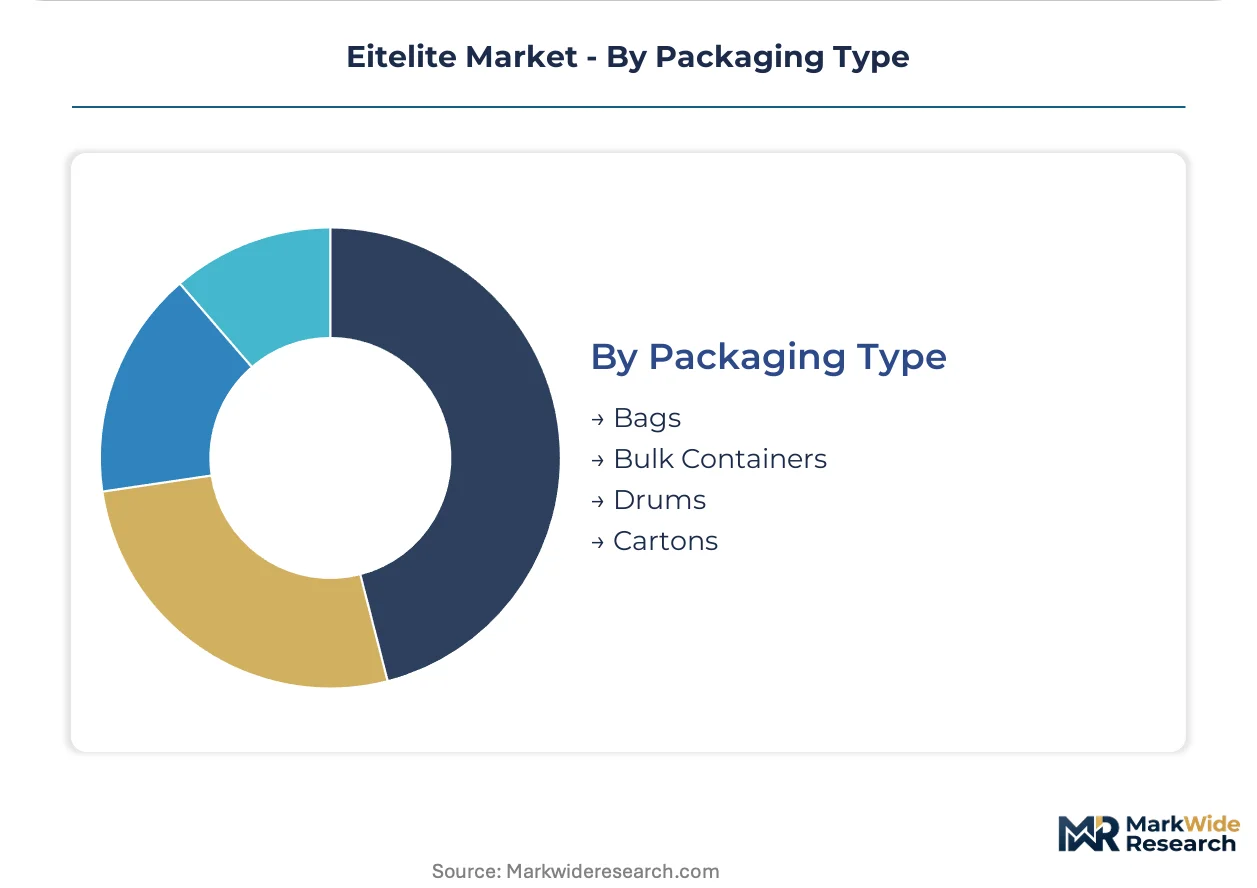
Packaging Type:
Packaging selection tracks customer scale and handling infrastructure, with bulk systems dominating integrated manufacturing sites and unitized formats serving distributed networks.
- Bulk Containers:Intermodal tank systems and pneumatic discharge units serve high-volume coatings manufacturers with dedicated unloading infrastructure.
- Bags:Multi-wall paper and woven polypropylene units balance handling convenience with moisture protection for mid-scale industrial users.
- Drums:Steel and fiber containers protect high-purity grades from contamination during extended storage and precision dispensing operations.
- Cartons:Corrugated units with inner liners support laboratory-scale procurement and specialty retail distribution.
Bulk Containers capture the largest volume; Bags are gaining share fastest in waterborne coatings reformulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal carbon border adjustments are redirecting procurement decisions toward lower-emission processing routes. German and Japanese specialty coatings manufacturers are consolidating supply chains around certified mineral sources. South Korean semiconductor packaging corridors are scaling specification-grade consumption for thermal management compounds.
Germany
Automotive coating formulators in Stuttgart and Wolfsburg are mandating REACH-registered Eitelite supply sources with pre-validated hazard profiles. ECHA documentation requirements are compressing supplier qualification timelines to 18-month cycles. The Ruhr industrial corridor anchors mineral processing infrastructure serving precision industrial applications.
Japan
Electronics chemical distributors in Tokyo and Osaka are ceding procurement authority to semiconductor packaging houses with dedicated raw material qualification teams. METI industrial standards are tightening trace-element documentation requirements for thermal interface materials. The Kyushu fabrication corridor is scaling advanced interconnect substrate production.
South Korea
Semiconductor packaging facilities in Suwon and Pyeongtaek are disqualifying unprocessed mineral concentrates from precision thermal management applications. MFDS industrial mineral purity standards are converging with carbon intensity targets under national dual carbon policy frameworks. The Seoul Capital Area dominates specification-grade Eitelite consumption for electronics-grade compounds.
United States
Specialty coatings manufacturers in Michigan and Ohio are responding to EPA mining oversight by anchoring procurement around ISO 9001-certified quarry-to-mill operators. Stricter emissions disclosure requirements under evolving federal frameworks are elevating feedstock provenance documentation. The Great Lakes mineral belt sustains construction-grade volume distribution networks.
China
MIIT industrial mineral purity standards are redirecting formulation strategies toward certified sources with verified low-emission beneficiation infrastructure. Yangtze River Delta processors are expanding precipitation synthesis capabilities for sub-10 micron particle engineering. The Pearl River Delta electronics assembly corridor represents underpenetrated demand for high-purity thermal interface materials.
Eitelite Market Vendor Landscape
Player mix skews toward integrated quarry-to-mill operators and specialized precipitation processors. Market structure concentrates around established European and North American mineral houses with pre-validated REACH dossiers. Three archetypes dominate: vertically integrated deposit owners, contract precipitation specialists, and regional trading distributors. Competitive moves center on M&A for deposit access and strategic partnerships for East Asian electronics corridor penetration.
Within the integrated operator tier, Imerys and Huber Engineering Materials exemplify quarry-to-mill positioning with European and North American infrastructure respectively. Schaefar Kalk GmbH & Co. KG represents the specialized precipitation archetype with German GmbH structure. These three anchors demonstrate how certification depth and geographic deposit control determine qualification status for specification-grade segments.
| Leading Market Players |
|---|
| Imerys |
| Sibelco |
| Huber Engineering Materials |
| Schaefar Kalk GmbH & Co. KG |
| Excalibar Minerals LLC |
| Franklin Minerals |
| Mississippi Lime Company |
| Eitelite Corp. |
| Global Eitelite Solutions |
| Others |
Supply Flow & Price Mechanics
Synthetic magnesium carbonate substitution in construction-grade thermal management compounds is redrawing procurement geography toward Chinese precipitation facilities while compressing margin capture in European quarry-to-mill operations.
Pricing Analysis
Certification level creates the primary spread between electronics-grade and construction-grade Eitelite, with ISO 9001-validated quarry-to-mill operators commanding substantial premia over uncertified mineral traders. Three-tier pricing structure across premium, standard, and economy levels stratifies by iron content thresholds and REACH dossier completeness. Cost compression in construction-grade tiers is intensifying because synthetic carbonate alternatives undercut natural mineral pricing. Contractors exhibit highest price sensitivity, while South Korean semiconductor packaging houses prioritize specification compliance over unit economics.
Supply Chain Analysis
Strategic stockpiling dominates electronics-grade procurement as semiconductor packaging houses buffer against 18-24 month REACH registration timelines, while construction buyers favor just-in-time bulk delivery. Commercial-grade Eitelite sourcing concentrates in Germany, the United States, and select Chinese processing corridors. Beneficiation infrastructure draws from specialized grinding media, flotation reagents, and inductively coupled plasma mass spectrometry calibration standards. Single-source vulnerability pervades high-purity segments where sub-50 ppm iron qualification eliminates most deposit developers. Distribution runs through direct mill-to-formulator contracting in specification-grade tiers, bypassing traditional mineral trading networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern this market as semiconductor packaging houses consolidate procurement authority and impose unified qualification protocols across dispersed supplier bases.
For Market Incumbents: Secure backward integration into East Asian beneficiation infrastructure before Chinese precipitation processors achieve REACH-equivalent certification status. Defend margin position by accelerating sub-10 micron particle engineering capabilities ahead of Korean specification tightening. Channel control through dedicated raw material qualification teams represents the critical defensive lever against distributor disintermediation. For New Entrants and Emerging Players: Anchor in Yangtze River Delta precipitation synthesis capacity serving underqualified Pearl River Delta electronics assembly demand. White-space targets include waterborne coatings reformulation in secondary German automotive supply chains and construction-grade granule supply to Southeast Asian cement additive distributors. Go-to-market execution should leverage third-party ISO 9001 certification rather than pursuing full quarry-to-mill integration. For Investors and Strategic Acquirers: Secondary-cycle assets sit with European integrated mineral houses holding pre-validated REACH dossiers but lacking East Asian electronics corridor penetration. Long-term viability hinges on 5-10 year dual carbon policy alignment across EU and Chinese regulatory frameworks. Watch for MIIT industrial mineral purity standard convergence with carbon intensity targets as the inflection signal triggering consolidation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captures margin from beneficiation infrastructure serving Korean semiconductor packaging specifications. |
| REACH Dossier Investment | Compresses supplier qualification timelines for German automotive coating formulators. |
| East Asian Joint Venture | Penetrates South Korean and Taiwanese fabrication corridors with localized precipitation synthesis. |
| Carbon Certification Program | Aligns with EU Green Deal border adjustments and Chinese dual carbon policy frameworks. |
| Particle Engineering Scale-Up | Enables sub-10 micron thermal interface material supply to advanced interconnect substrate producers. |
Methodological Framework
The analysis maps Eitelite product grades, application verticals, and procurement channel structures, each validated through direct engagement with mineral processing plant managers, specialty coatings procurement leads, semiconductor packaging raw material qualification teams, and industrial mineral distribution channel partners. Primary interview insights triangulate against customs trade data, ECHA REACH registration databases, SEC 10-K filings from listed mineral processors, and MIIT industrial mineral purity standard disclosures. Bottom-up deposit capacity estimates reconcile with top-down end-use demand aggregation across electronics, coatings, and construction sectors.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models grade tier, end-use industry, packaging format, and regional production hub as core segmentation dimensions. CAGRs derive from regression analysis of historical price-realization trends and forward capacity expansion announcements. Forecast inputs incorporate REACH registration timeline assumptions and carbon border adjustment implementation trajectories.
Material uncertainties — geological assay variance, permitting delays, and substitute mineral pricing volatility — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding specification-grade demand concentration and dual carbon policy convergence timing. Revision becomes warranted when synthetic magnesium carbonate cost curves cross natural Eitelite breakeven thresholds in construction applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Ethyl Ascorbic Acid Market
Specialty Chemicals
4-ADPA Market
Specialty Chemicals
Barium Derivatives Market
Specialty Chemicals
Plastic Stabilizer Market
Specialty Chemicals
Europe Aerosol Cans Market
Specialty Chemicals
Micronized PTFE Market
Specialty Chemicals
Global 28-Homobrassinolide Market
Specialty Chemicals
Special Boiling Point Solvents Market
Specialty Chemicals
Erucic Acid Market
Specialty Chemicals
Contouring Products Market
Specialty Chemicals
Monomethyl Acetoacetamide Market
Specialty Chemicals
Ytterbium Fluoride Market
Specialty Chemicals
Chevron Seals Market
Specialty Chemicals
Ubiquinone Market
Specialty Chemicals
Biodegradable Chelating Agents Market
Specialty Chemicals
Palm Methyl Ester Derivatives Market