
 Eco-Friendly Plasticizers Market | 2026-2036
Eco-Friendly Plasticizers Market Size, Share, and Industry Trends Forecast 2026-2036
Eco-Friendly Plasticizers Market Analysis
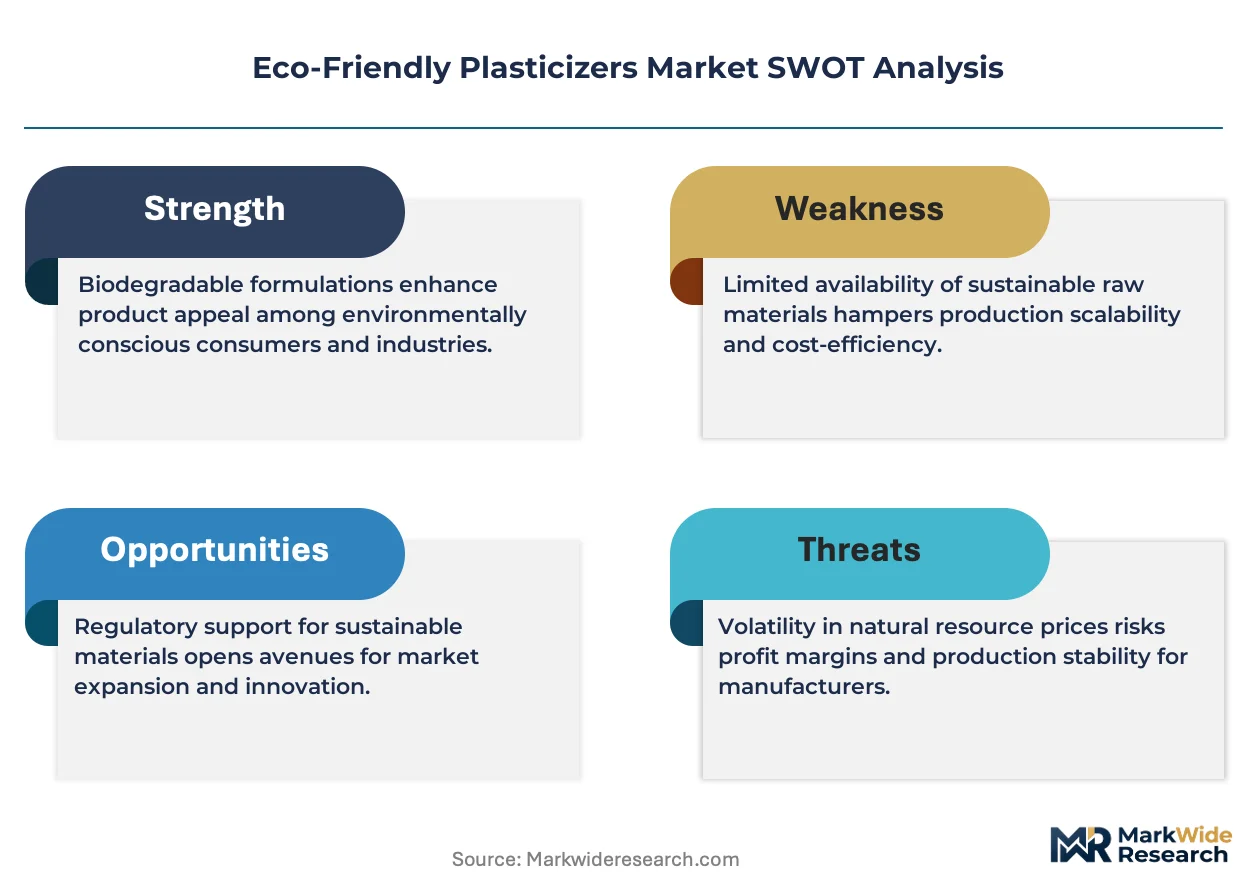
Phthalate-based plasticizers are consolidating around bio-based and vegetable-derived alternatives as compounders absorb reformulation costs. BASF leverages its integrated adipate and sebacate chains to supply European automotive OEMs with certified low-VOC solutions. Eastman Chemical Company anchors North American demand through its non-phthalate ester portfolio, while LG Chem competes on scale from its Korean petrochemical base with expanding bio-content grades.
Eco-friendly plasticizers are additives that impart flexibility and workability to rigid polymers, typically comprising ester compounds derived from renewable feedstocks such as epoxidized soybean oil or citric acid derivatives with molecular weights ranging from 300 to 600 g/mol. They primarily serve polyvinyl chloride compounding for sheeting, cabling, and coated fabrics where migration resistance and low extraction define performance. Vegetable-based formulations now lead volume growth as epoxidized oils displace DINP and DEHP in food-contact films and medical tubing. Packaging applications represent the fastest-expanding segment as brand owners specify bio-derived content for flexible films and shrink wraps. Construction remains the most mature application channel where cost-sensitive flooring and wall-covering producers balance performance against premium pricing for non-toxic grades.
REACH authorization requirements and the EU Green Deal framework restrict phthalate use in consumer-contact applications, compelling compounders to validate alternative plasticizers through ECHA substance evaluation. The EPA and state-level regulations in California and New York parallel these restrictions on children's products and building materials. FDA guidance on food-contact substances further shapes which bio-based chemistries gain commercial traction in packaging films. Stakeholders must monitor evolving substance restrictions across multiple jurisdictions while building formulation libraries that anticipate downstream certification requirements.
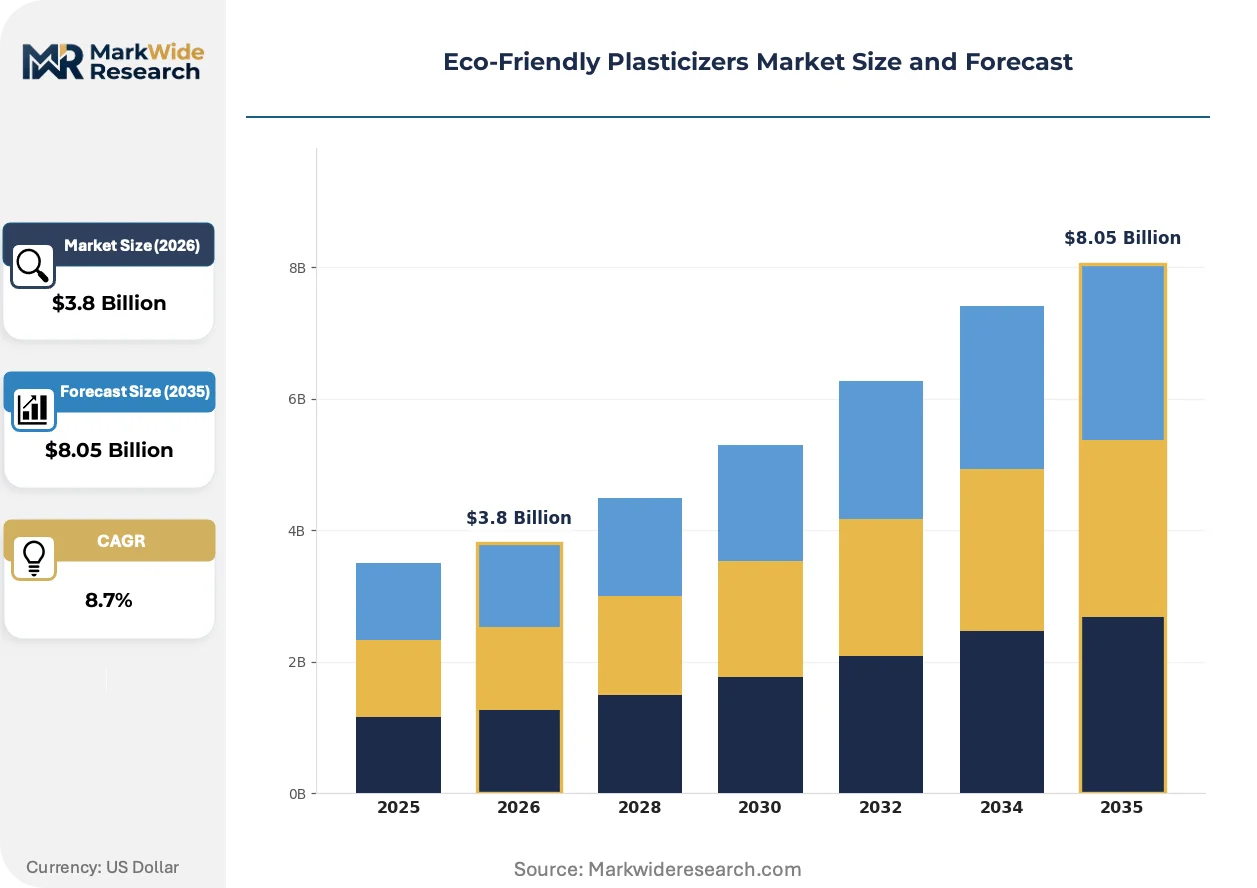
Market Dynamics
REACH authorization requirements and parallel EPA state-level restrictions are forcing compounders to absorb reformulation costs while validating bio-based alternatives through multi-jurisdictional substance evaluation protocols.
Growth Catalysts
- REACH Authorization:ECHA substance evaluation protocols redirect European compounder procurement toward certified bio-based esters for consumer-contact applications.
- Epoxidized Soybean Oil:Vegetable-derived formulations displace DINP and DEHP in food-contact films and medical tubing segments.
- Automotive Interior Mandates:German and US OEM specifications for low-VOC cabin materials accelerate phthalate-free adoption across seating and dashboard compounds.
Market Restraints
- Feedstock Volatility:Soybean and castor oil price swings compress margins for epoxidized oil producers versus petrochemical-based alternatives.
- Performance Gap:Bio-based plasticizers exhibit inferior migration resistance in high-temperature cabling compared to adipate esters.
- Regulatory Fragmentation:Divergent FDA, EFSA, and state-level California requirements extend certification timelines and multiply compliance costs.
Strategic Opportunities
- India Construction:BIS standards evolution and infrastructure investment create entry points for non-phthalate flooring and wall-covering grades.
- Packaging Certification:Brand-owner mandates for bio-derived content in flexible films and shrink wraps outpace supply capacity.
- Sebacate-Citrate Convergence:Hybrid chemistries combining renewable feedstocks with enhanced extraction resistance open medical device applications.
Industry Challenges
- Formulation Expertise Scarcity:Compounders lack technical staff trained in bio-based plasticizer-polymer compatibility and processing window optimization.
- Multi-Jurisdictional Certification:ECHA, FDA, and state-level substance evaluations require parallel testing streams that extend commercialization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eco-Friendly Plasticizers Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phthalate-Free, Vegetable-Based, Bio-Based, Non-Toxic Application: Construction, Automotive, Consumer Goods, Packaging Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers End User: Manufacturers, Exporters, Retailers, Contractors |
| Companies Covered | Lanxess, Dow Chemical Company, BASF, LG Chem, Perstorp Holding AB, Eastman Chemical Company, Arkema Group, Valtris Specialty Chemicals, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eco-Friendly Plasticizers Market Emerging Trajectories
Formulation chemistry is pivoting toward hybrid bio-petrochemical architectures that balance renewable content with performance metrics previously dominated by conventional phthalates.
Epoxidized soybean oil is consolidating its position as the leading vegetable-derived plasticizer by offering cost parity with DINP in flexible PVC compounding. Automotive OEMs in Germany and the United States are specifying ESO grades for interior applications at accelerating volume. The technology is consolidating supply chain control among integrated oilseed processors who capture both feedstock and epoxidation value.
EU Green Deal framework restrictions on phthalate use in consumer-contact applications are tightening substance authorization requirements through 2030. Compounders must now validate alternative plasticizers through ECHA evaluation before securing downstream customer approval. Food-contact film and medical tubing segments face the steepest compliance burden as EFSA safety assessments lag commercial development timelines.
Buyer concentration among automotive OEMs and multinational packaging brand owners is compressing supplier qualification cycles and demanding certified bio-content documentation. Tier-1 compounders are replacing spot purchasing with multi-year supply agreements that lock in renewable feedstock traceability. This pattern is most visible in Germany and the United States where automotive and construction material producers face overlapping chemical safety mandates from regulators and downstream customers.
Eco-Friendly Plasticizers Market Segmentation
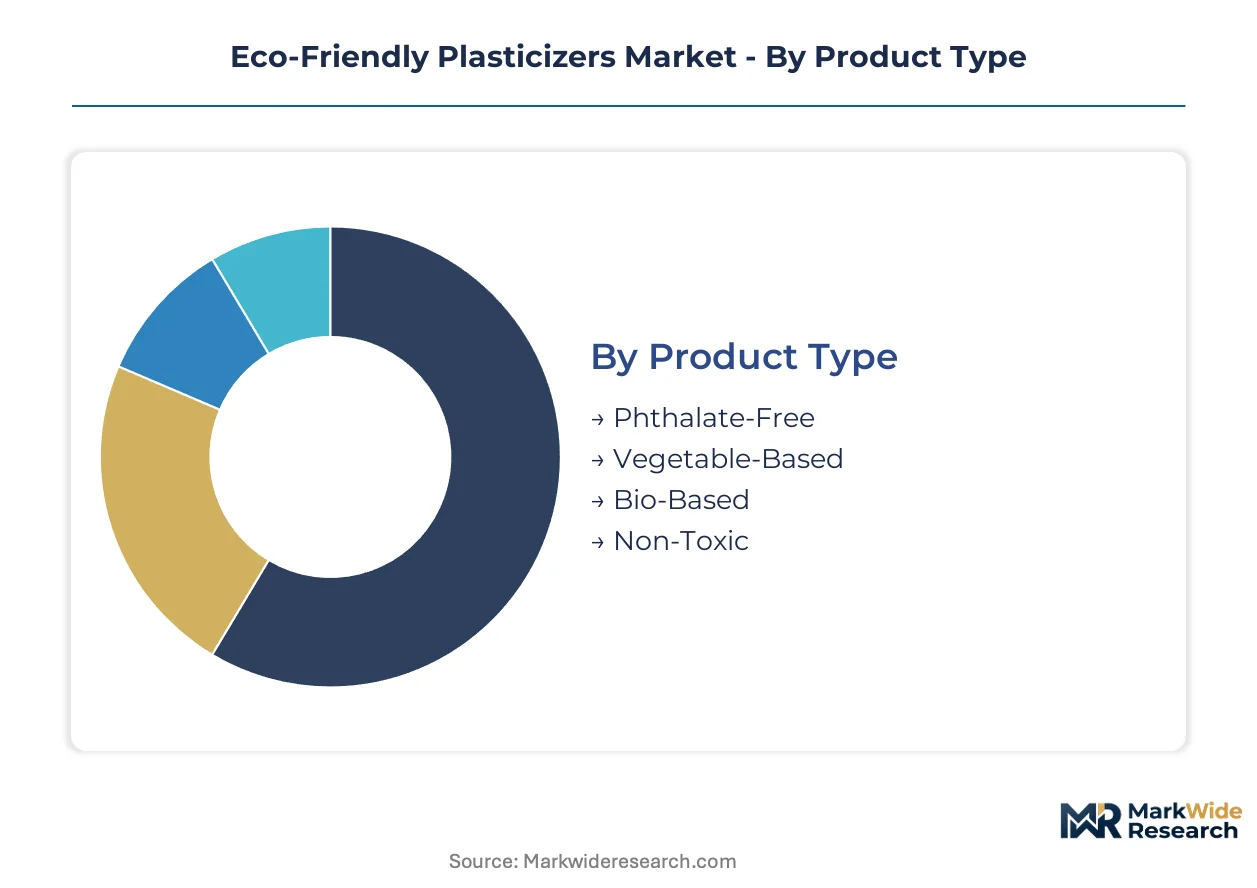
Segmentation in eco-friendly plasticizers reveals how reformulation pressures and certification requirements split demand across technical specifications and buyer procurement patterns. Compounders select plasticizer categories based on end-use regulatory exposure, while channel structure reflects the concentration of automotive OEM and packaging brand-owner purchasing power.
Product Type:
Buyers in this category differentiate by the trade-off between renewable content claims and performance validation in high-extraction applications.
- Vegetable-Based:Epoxidized soybean oil and epoxidized linseed oil formulations deliver cost parity with conventional phthalates in flexible PVC compounding. Demand concentrates in German and US automotive seating applications where OEMs mandate certified low-VOC cabin materials and traceable bio-content documentation.
- Bio-Based:Citrate esters and sebacate derivatives derived from renewable feedstocks offer superior extraction resistance for medical tubing and food-contact films. European compounders facing REACH authorization deadlines are redirecting procurement toward these grades despite premium pricing over petrochemical alternatives.
- Phthalate-Free:Adipate and trimellitate esters formulated without ortho-phthalate structures serve construction flooring and wall-covering producers navigating California Proposition 65 and state-level chemical disclosure mandates.
- Non-Toxic:Grades certified for children's toys and childcare articles under CPSIA and EN 71-3 standards command qualification cycles that lock out unvalidated suppliers.
Volume sits with vegetable-based grades; growth tilts toward bio-based formulations as EFSA food-contact approvals expand.
Application:
End-use selection tracks the severity of regulatory exposure and the premium tolerance of downstream customers.
- Packaging:Flexible films and shrink wraps represent the steepest expansion trajectory as multinational brand owners specify bio-derived content percentages in supplier scorecards. EFSA and FDA parallel evaluations for food-contact substances extend commercialization timelines but lock in multi-year supply agreements.
- Automotive:Interior applications for seating, dashboard skins, and door panels absorb phthalate-free formulations at accelerating volume. German OEM specifications for cabin air quality and US EPA toxicity testing requirements are converging on low-emission plasticizer standards.
- Construction:Flooring, wall coverings, and roofing membranes constitute the most mature demand channel where cost-sensitive producers balance performance against premium pricing for non-toxic grades. BIS standards evolution in India is creating incremental entry points for certified alternatives.
- Consumer Goods:Toys, sporting equipment, and household articles face overlapping CPSIA, EN 71-3, and state-level restrictions that favor pre-validated plasticizer libraries.
Construction holds installed volume; packaging and automotive are climbing the fastest as brand-owner mandates outpace supply capacity.
Distribution Channel:
Channel selection reflects buyer scale, formulation expertise requirements, and the need for technical service support.
- Direct Sales:Tier-1 compounders and automotive OEMs negotiate multi-year supply agreements that lock in renewable feedstock traceability and certified bio-content documentation. BASF and Eastman Chemical anchor this channel with integrated technical service teams.
- Distributors:Regional chemical distributors serve mid-size PVC compounders lacking formulation expertise in bio-based plasticizer-polymer compatibility. Stocking locations in Germany, China, and the United States reduce lead times for qualified grades.
- Online Retail:Specialty chemical platforms and B2B marketplaces capture spot purchasing from small-scale processors and custom compounders seeking sample quantities for reformulation trials.
- Wholesalers:Bulk material handlers supply construction-focused compounders with standardized phthalate-free grades where certification requirements are less stringent than food-contact or medical applications.
Direct sales capture premium-margin volume; distributor relationships are expanding fastest as mid-tier compounders absorb reformulation costs.
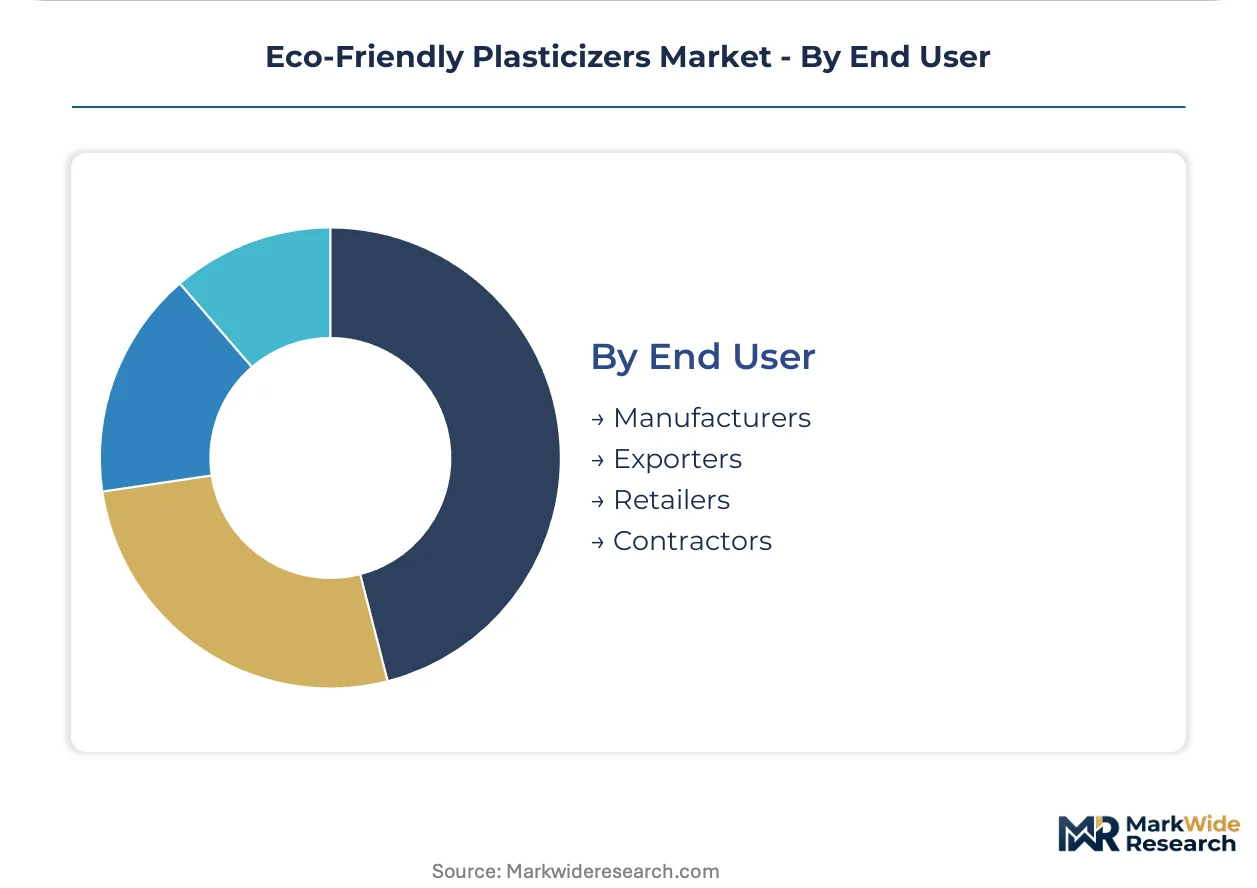
End User:
End-user categories segment by technical capability, regulatory exposure, and supply chain position.
- Manufacturers:PVC compounders and polymer processors constitute the core demand base, selecting plasticizers based on migration resistance specifications and multi-jurisdictional certification status. Technical staff scarcity in bio-based formulation expertise constrains adoption timelines.
- Contractors:Construction installation firms increasingly specify non-phthalate flooring and wall-covering materials in response to green building certification programs and owner procurement guidelines.
- Exporters:Compounders serving cross-border markets must validate plasticizers against destination-country substance restrictions, extending qualification cycles for EU, US, and Japan-bound shipments.
- Retailers:Private-label brand owners in consumer goods and packaging are consolidating supplier bases around pre-certified bio-based plasticizer sources to simplify compliance documentation.
Manufacturers dominate current volume; contractors represent the fastest-expanding category as green building specifications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for eco-friendly plasticizers concentrates in automotive manufacturing corridors and packaging production clusters across Germany, China, and the United States where chemical safety mandates are tightening fastest.
Germany
Automotive OEM specifications for low-VOC cabin materials drive phthalate-free adoption across seating and dashboard compounds. REACH authorization requirements and the EU Green Deal framework restrict conventional plasticizer use in consumer-contact applications. The Rhine-Ruhr industrial corridor anchors European compounding capacity as BASF and Lanxess supply certified bio-based esters to tier-1 suppliers.
China
Domestic automotive production and flexible packaging expansion absorb vegetable-derived plasticizers at accelerating volume. GB standards evolution and dual carbon goals redirect state-owned petrochemical complexes toward bio-content grades. The Yangtze River Delta concentration around Shanghai and Ningbo hosts the largest epoxidized soybean oil processing capacity outside North America.
United States
EPA toxicity testing requirements and California Proposition 65 enforcement compel reformulation across construction flooring and children's products. FDA guidance on food-contact substances shapes which bio-based chemistries gain commercial traction in packaging films. The Gulf Coast petrochemical corridor integrates renewable feedstock streams as Eastman Chemical anchors North American adipate and sebacate supply.
India
Infrastructure investment and urban construction growth create entry points for non-phthalate flooring and wall-covering grades. BIS standards evolution on chemical safety in building materials parallels European REACH restrictions. The Gujarat industrial belt concentrates PVC compounding capacity as domestic producers absorb reformulation costs for export-bound shipments.
South Korea
Automotive export requirements and electronics packaging demand pull bio-based plasticizers through integrated chaebol supply chains. MFDS food-contact substance evaluations and corporate ESG commitments accelerate certified grade procurement. The Ulsan-Busan petrochemical complex hosts expanding epoxidized oil production as LG Chem competes on scale with bio-content grades.
Eco-Friendly Plasticizers Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated petrochemical majors commanding automotive OEM supply agreements while regional compounders serve cost-sensitive construction channels. The vendor base organizes around three archetypes: integrated multinational chemical companies with adipate and sebacate chains, vegetable-oil processors capturing feedstock-to-epoxidation value, and regional distributors providing technical service to mid-tier PVC compounders. Dominant competitive moves include backward integration into renewable feedstock sourcing and multi-year supply agreements that lock in certified bio-content documentation.
Among German-headquartered chemical conglomerates, BASF and Lanxess occupy positions anchored by integrated European supply chains and REACH certification expertise. Eastman Chemical Company exemplifies the North American non-phthalate ester specialist archetype, while LG Chem represents the Asian scale-driven competitor expanding bio-content grades from its Korean petrochemical base. These three anchors illustrate how geographic origin and feedstock integration shape competitive positioning across automotive, packaging, and construction end-uses.
| Leading Market Players |
|---|
| Lanxess |
| Dow Chemical Company |
| BASF |
| LG Chem |
| Perstorp Holding AB |
| Eastman Chemical Company |
| Arkema Group |
| Valtris Specialty Chemicals |
| Evonik Industries AG |
| Others |
Supply Flow & Price Mechanics
REACH authorization requirements in Europe gate both qualified supply and premium-tier pricing access, as compounders lacking ECHA-certified bio-based ester libraries cannot serve automotive OEM or food-contact film customers regardless of price competitiveness. This regulatory filtering concentrates pricing power among integrated suppliers with validated substance portfolios while compressing margins for spot-market participants.
Pricing Analysis
Volume concentrates in vegetable-based grades at cost parity with conventional phthalates, while margins accrue to bio-based citrate and sebacate derivatives commanding certification premiums. Price differentiation hinges on EFSA food-contact approval status and renewable feedstock traceability documentation. Pricing pressure stems from soybean oil feedstock volatility compressing epoxidized oil producer margins. Construction flooring compounders exhibit highest price sensitivity, whereas medical tubing manufacturers absorb premiums for extraction-resistant grades.
Supply Chain Analysis
Reverse-logistics flows for spent epoxidized oil and off-spec bio-based esters remain underdeveloped, with most material directed to fuel blending rather than re-epoxidation or chemical recovery. Supply concentrates in Germany, China, and the United States where integrated adipate and sebacate chains anchor regional compounding hubs. Raw material dependencies include soybean and castor oil feedstocks, plus petrochemical-derived acid precursors for hybrid chemistries. Single-source vulnerability in European epoxidation capacity creates supply chain risk. Distribution runs through direct sales agreements with tier-1 compounders and automotive OEMs, supplemented by regional distributors serving mid-tier processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified bio-based plasticizer supply runs constrained against accelerating OEM and brand-owner procurement mandates, with ECHA substance evaluation bottlenecks propping premium-tier pricing.
For Market Incumbents: Acquire epoxidation capacity and renewable feedstock processing assets to lock in backward integration before soybean oil price volatility erodes margin structures. Defend position by expanding EFSA and FDA parallel certification libraries ahead of competitor submissions. Prioritize multi-year supply agreements with German and US automotive OEMs to secure volume commitments against emerging Asian producers. For New Entrants and Emerging Players: REACH authorization deadlines in Europe open a window for bio-based sebacate and citrate specialists to capture medical tubing and food-contact film segments before incumbent capacity expands. Target India's construction flooring market where BIS standards evolution creates first-mover advantages for non-phthalate grades. Build formulation partnerships with mid-tier PVC compounders lacking in-house bio-based compatibility expertise. For Investors and Strategic Acquirers: Tier-1 automotive OEM multi-year supply agreement announcements are the leading indicator that a bio-based plasticizer supplier has cleared ECHA validation and secured locked-in revenue streams. Long-term viability centers on integrated feedstock-to-epoxidation operations with certified renewable content documentation. Monitor EFSA food-contact substance approval timelines as inflection signals for packaging segment penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Feedstock | Captures soybean and castor oil supply chains to stabilize margins against commodity volatility. |
| ECHA Parallel Certification Investment | Accelerates REACH authorization timelines for bio-based esters serving consumer-contact applications. |
| Long-term Supply Agreement with Automotive OEMs | Locks in volume commitments from German and US manufacturers specifying low-VOC cabin materials. |
| Hybrid Chemistry R&D Partnership | Combines sebacate and citrate architectures to open medical device extraction-resistant applications. |
| Regional Distribution Expansion | Establishes technical service presence in India and South Korea for mid-tier compounder qualification support. |
Methodological Framework
Trade databases, ECHA substance evaluation registries, and automotive OEM procurement disclosures formed the secondary backbone, supplemented by customs records tracking epoxidized soybean oil and sebacate derivative flows. Primary interviews with PVC compounding plant managers, automotive tier-1 supplier procurement leads, and packaging brand-owner sustainability directors validated formulation adoption timelines and certification bottlenecks. Bottom-up and top-down triangulation reconciled volume estimates across application segments.
Bottom-up modeling anchored forecasts in individual end-use adoption curves, while top-down cross-checks applied macro-level regulatory phase-out assumptions across the projection horizon. Segmentation dimensions included product type tier, application regulatory exposure, and regional production hub concentration. CAGRs derived from weighted average of segment-specific growth trajectories incorporating EFSA approval lag assumptions and automotive OEM specification rollout schedules.
Caveats apply where ECHA substance evaluation delays, feedstock price spikes, or automotive production cuts could materially shift the outlook. Practitioners should monitor EFSA food-contact substance approval announcements and German OEM low-VOC specification updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Bio Polyol and Green Polyol Market
Specialty Chemicals
Ethylhexane Diol Market
Specialty Chemicals
5-Hydroxymethylfurfural Market
Specialty Chemicals
PPG-20 Methyl Glucose Ether Market
Specialty Chemicals
Fe EDDHA Market
Specialty Chemicals
Stable Isotopes Market
Specialty Chemicals
Plastic Stabilizer Market
Specialty Chemicals
Global Non-Halogenated Flame Retardants Market
Specialty Chemicals
Insoluble Fibers Market
Specialty Chemicals
Homosalate Market
Specialty Chemicals
Silicone Oil Market
Specialty Chemicals
Organometallics Market
Specialty Chemicals
Global Tetrahexyldecyl Ascorbate Market
Specialty Chemicals
Salicylate Market
Specialty Chemicals
Chromium Polynicotinate Market
Specialty Chemicals
Hydroxyproline Market