
 Insoluble Fibers Market | 2026-2036
Insoluble Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Insoluble Fibers Market Insights
Market Context
Psyllium husk is realigning cost structures across several insoluble fiber categories as formulators seek alternatives to soluble fiber price volatility. Cargill, Incorporated leverages its agricultural supply chain to secure raw material continuity for cellulose derivatives. J. Rettenmaier & Söhne GmbH + Co KG anchors European production of refined fiber concentrates for pharmaceutical-grade applications. DuPont competes on modified cellulose technology leadership, particularly in bioplastics feedstock development.
Technical Profile and Segment Structure
Insoluble fibers are non-digestible carbohydrate polymers—primarily cellulose, lignin, and hemicellulose—that resist hydrolysis by human digestive enzymes and function as bulking agents, moisture regulators, or structural reinforcements in formulated products. These materials typically retain particle integrity at pH ranges from 2 to 8 and withstand extrusion temperatures exceeding 120°C, making them compatible with thermal food processing and melt-compounding operations for bioplastics. Cellulose commands the largest volume position across product types due to its established supply base from wood pulp and agricultural residues, while chitosan derived from crustacean shells represents the fastest-expanding category because of antimicrobial functionality in active packaging and biomedical coatings. Powder form dominates current procurement volumes for dietary supplements and food additives, though pelletized grades are gaining traction in textile spinning and bioplastic compounding where dust control and flow properties determine processing economics.
Regulatory Environment and Outlook
The FDA's 2016 revised definition of dietary fiber under 21 CFR 101.9, combined with EFSA health claim authorization processes in Europe and FSSAI fortification guidelines in India, collectively determine which fiber sources achieve qualified health claims and permissible label declarations. REACH registration requirements for novel cellulose derivatives and EU Green Deal bioplastics targets are redirecting R&D investment toward certified-sustainable feedstocks and compostable end-products. Stakeholders must monitor evolving fiber qualification thresholds across FDA, EFSA, and FSSAI jurisdictions to anticipate which ingredient grades will retain premium positioning versus commodity status.
Market Dynamics
FDA's updated dietary fiber definition under 21 CFR 101.9 is forcing reformulation across bakery and supplement categories, compressing qualification pathways for legacy ingredients while opening premium positioning for novel cellulose derivatives that meet the agency's physiological benefit thresholds.
Growth Catalysts
- Clean-label fortification mandates:Bakery manufacturers in the United States are accelerating insoluble fiber incorporation to replace modified starches and meet consumer transparency expectations.
- EU Green Deal bioplastics targets:Compostable packaging regulations are redirecting cellulose derivative demand toward certified-sustainable feedstocks for active film applications.
- Gut-health positioning:Prebiotic marketing claims in functional foods are concentrating procurement of bulking-grade cellulose from wood pulp suppliers.
Market Restraints
- Psyllium husk price volatility:Soluble fiber cost swings are compressing margins for formulators attempting hybrid soluble-insoluble blends in supplement tablets.
- REACH registration burdens:Novel cellulose derivatives face extended authorization timelines in Europe, delaying commercialization of antimicrobial chitosan grades for biomedical coatings.
- Crustacean supply concentration:Chitosan production depends on seasonal seafood processing waste streams concentrated in coastal East Asian facilities.
Strategic Opportunities
- FSSAI fortification guidelines:India's processed food sector is opening to imported cellulose concentrates as domestic wheat bran supplies prove inconsistent for mass-market bread fortification.
- Pelletized grade adoption:Textile spinners and bioplastic compounders are shifting procurement toward dust-controlled cellulose formats that improve flow properties in melt-compounding operations.
- Antimicrobial packaging convergence:Chitosan-cellulose composite films are capturing interest from active packaging developers seeking shelf-life extension without synthetic preservatives.
Industry Challenges
- Extrusion engineering talent scarcity:Thermal processing of high-fiber formulations requires specialized screw design expertise that remains concentrated among legacy food equipment manufacturers.
- FDA-EFSA alignment delays:Divergent health claim authorization timelines force dual-track clinical substantiation strategies that extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insoluble Fibers Market |
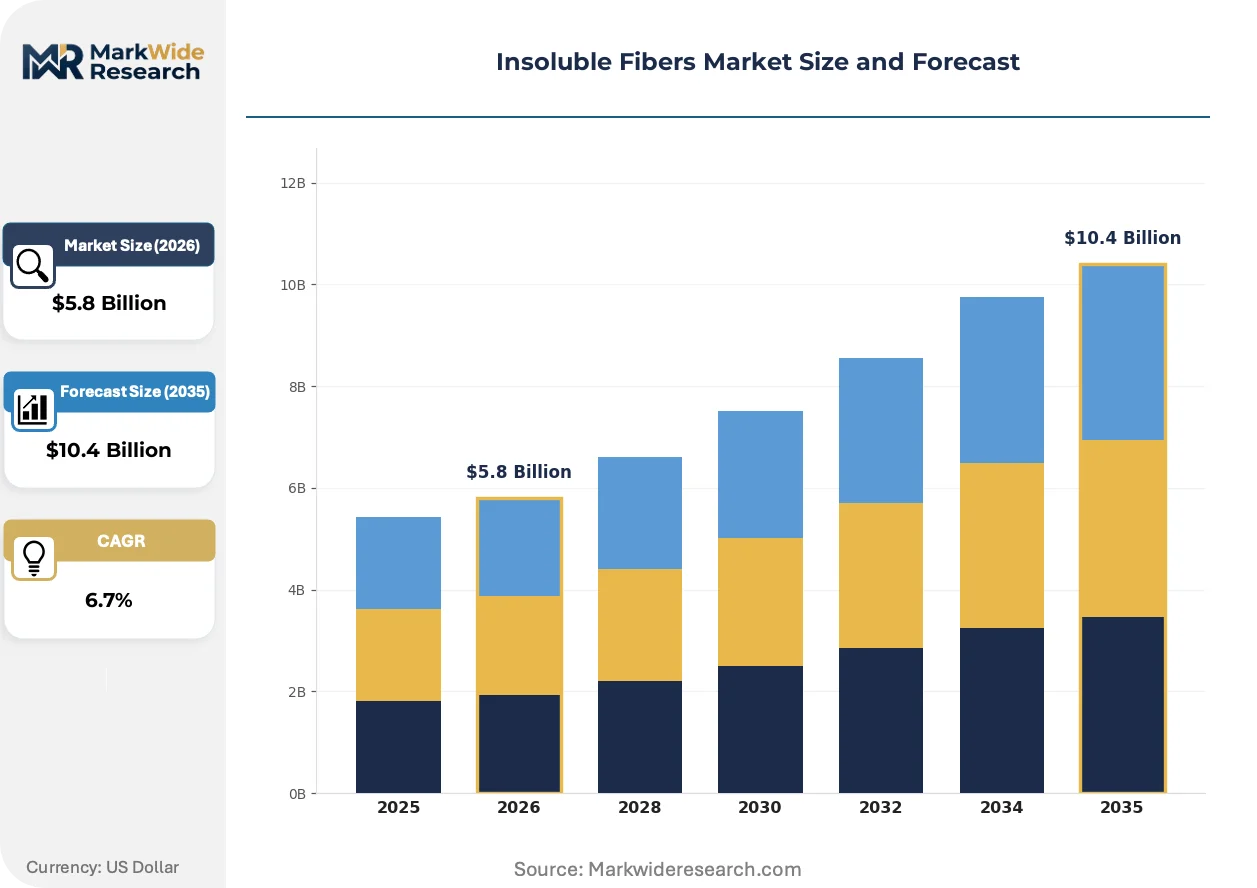
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.4 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cellulose, Lignin, Hemicellulose, Chitosan End Use Industry: Food, Pharmaceuticals, Cosmetics, Agriculture Form: Powder, Granule, Pellet, Flake Application: Dietary Supplements, Food Additives, Textiles, Bioplastics |
| Companies Covered | Cargill, Incorporated, Grain Processing Corporation, Ingredion Incorporated, J. Rettenmaier & Söhne GmbH + Co KG, InterFiber Ltd., DuPont, Roquette Frères, CFF GmbH & Co. KG, Archer Daniels Midland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insoluble Fibers Market Trends and Innovations
Cellulose nanofibril production is absorbing capital from conventional fiber refining, while regulatory qualification pathways and procurement specifications are rewriting competitive positioning across food, pharmaceutical, and materials sectors.
Cellulose nanofibril extraction from agricultural residues is absorbing investment previously directed toward wood pulp derivatives. Food formulators in the United States are adopting these materials at pilot scale for moisture retention in clean-label baked goods. The technology is absorbing market share from microcrystalline cellulose in premium positioning segments where transparency claims command price premiums.
EFSA's evolving health claim authorization process is compressing permissible language for gut-health marketing in Europe. Manufacturers must now substantiate physiological benefits through human intervention studies rather than compositional claims alone. Dietary supplement brands targeting German and French markets are responding by reformulating with specific cellulose types that have pre-existing positive opinions.
Buyer concentration among contract manufacturers is shortening ingredient qualification cycles and demanding standardized certificate-of-analysis formats. Mid-sized bakery and supplement brands are consolidating procurement through co-manufacturing partners rather than direct raw material sourcing. This pattern is most visible in the United States, where private-label growth has concentrated volume among a handful of toll processors.
Insoluble Fibers Market Segmentation
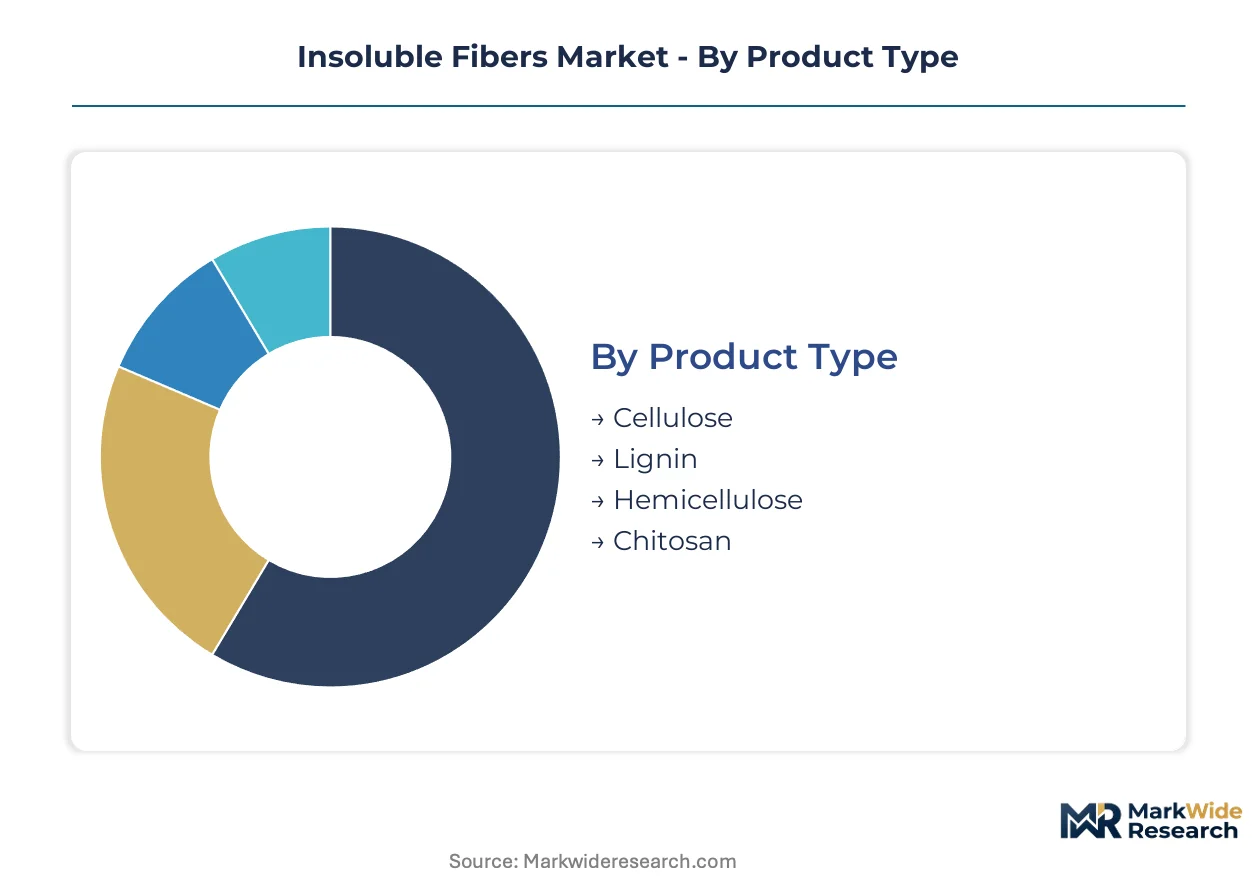
Insoluble fiber procurement decisions hinge on thermal stability thresholds, regulatory qualification status, and end-use processing economics. Formulators across food, pharmaceutical, and materials sectors weight these attributes differently, creating distinct demand profiles that reshape supplier priorities.
Product Type:
Buyers prioritize thermal resistance and supply security when selecting fiber polymers for high-temperature processing applications.
- Cellulose:Derived from wood pulp and agricultural residues, this polymer withstands extrusion temperatures exceeding 120°C. Bakery manufacturers in the United States concentrate procurement here for clean-label bread fortification that meets FDA dietary fiber definition thresholds.
- Chitosan:Extracted from crustacean shells, this biopolymer delivers antimicrobial functionality for active packaging films. Biomedical coating developers in coastal East Asian processing clusters drive fastest expansion as REACH registration delays constrain European supply alternatives.
- Lignin:A phenolic polymer binding plant cell walls, available from paper industry black liquor streams. Bioplastic compounders value its carbon content for thermoset replacement applications.
- Hemicellulose:Branched polysaccharides from cereal husks and hardwoods, offering intermediate solubility between cellulose and soluble fibers. Pharmaceutical tablet formulators explore this grade for controlled-release matrices.
Volume sits with Cellulose; growth tilts toward Chitosan.
End Use Industry:
Application-specific regulatory pathways determine which fiber grades achieve premium positioning versus commodity status.
- Food:Clean-label fortification mandates from bakery and snack manufacturers dominate procurement. FDA's updated dietary fiber definition under 21 CFR 101.9 forces reformulation toward physiologically substantiated cellulose derivatives.
- Pharmaceuticals:Excipient-grade cellulose concentrates require pharmaceutical-grade certification that J. Rettenmaier & Söhne GmbH + Co KG anchors in European production. Tablet disintegration and controlled-release applications drive specification intensity.
- Cosmetics:Microplastic-free exfoliant demand redirects procurement toward cellulose microspheres. Formulators seek particle sizes below 100 microns for rinse-off products.
- Agriculture:Soil amendment and controlled-release fertilizer coating applications absorb lower-purity fiber grades. Seasonal demand patterns track planting cycles in major grain-producing regions.
Procurement intensity clusters in Food; margin expansion favors Pharmaceuticals.
Form:
Processing equipment compatibility and dust control requirements differentiate buyer preferences across manufacturing environments.
- Powder:Dominates dietary supplement and food additive volumes due to dissolution kinetics and uniform dispersion in dry blends. Pneumatic conveying systems at contract manufacturers standardize on this format.
- Pellet:Textile spinners and bioplastic compounders shift procurement here for dust-controlled flow properties in melt-compounding operations. Pellet density above 0.6 g/cm³ optimizes extruder feed consistency.
- Granule:Intermediate particle size for agricultural soil amendment applications where dust suppression matters but dissolution speed does not. Fertilizer coating operations prefer this grade for handling efficiency.
- Flake:Specialized format for cosmetic exfoliant applications requiring visual texture differentiation. Rinse-off product formulators specify flake dimensions between 200-500 microns for sensory performance.
Powder commands current volumes; pelletized grades climb fastest on bioplastics demand.
Application:
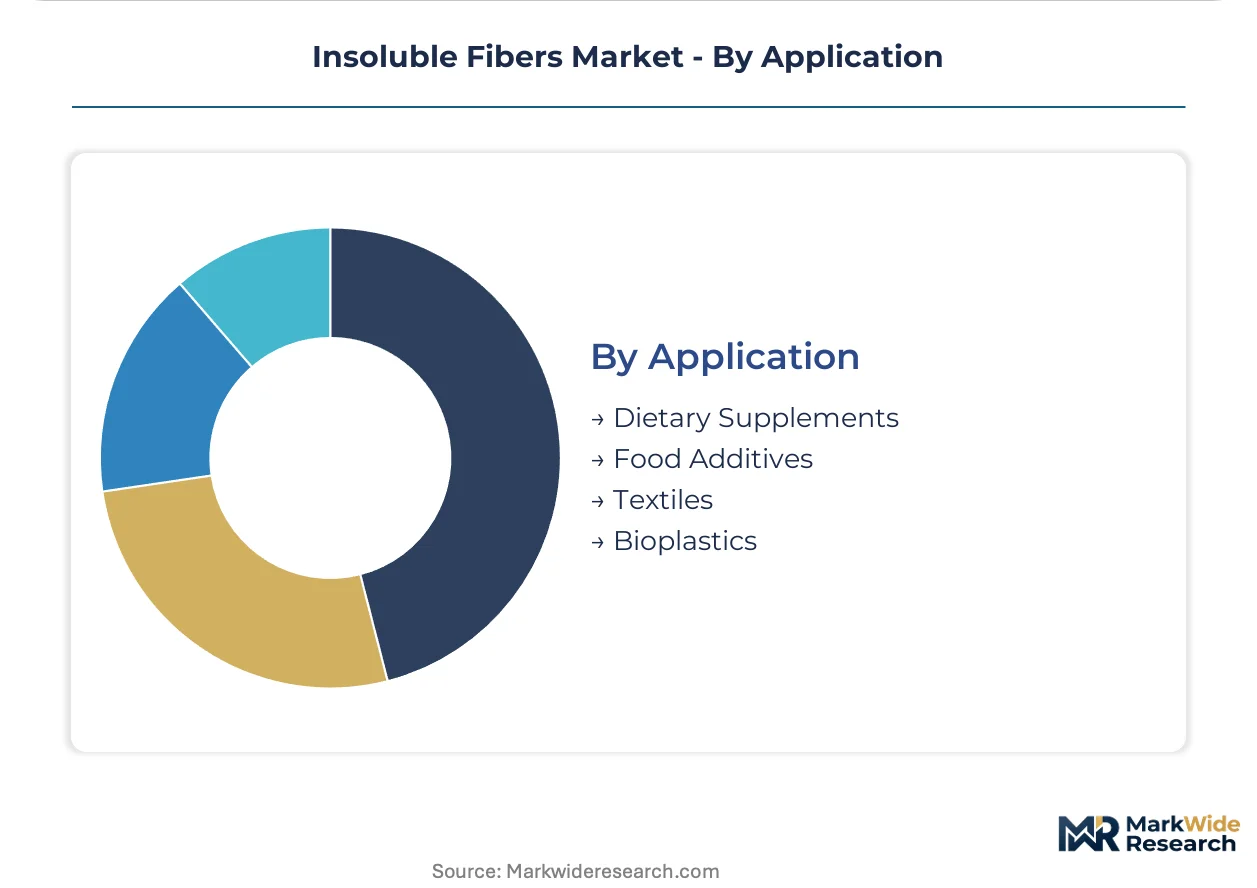
Health claim authorization status and materials performance specifications create divergent value capture opportunities.
- Food Additives:Clean-label reformulation across United States bakery categories absorbs refined cellulose concentrates. EFSA's evolving gut-health claim authorization in Europe compresses permissible marketing language, favoring pre-substantiated fiber types.
- Bioplastics:EU Green Deal compostable packaging targets redirect cellulose derivative demand toward certified-sustainable feedstocks. Active film developers combine chitosan-cellulose composites for shelf-life extension without synthetic preservatives.
- Dietary Supplements:Bulking agent and tablet disintegration functions concentrate procurement among contract manufacturers. Psyllium husk price volatility pressures formulators attempting hybrid soluble-insoluble blends.
- Textiles:Cellulose nanofibril extraction from agricultural residues absorbs investment previously directed toward conventional fiber refining. Pilot-scale adoption for moisture retention functions is visible in premium positioning segments.
Food Additives anchor volume; Bioplastics presents steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement intensity concentrates in the United States, where functional food innovation and gut-health positioning drive volume. Germany, China, India, and Japan follow as distinct demand centers with diverging regulatory pathways and industrial specialization.
United States
FDA's updated dietary fiber definition under 21 CFR 101.9 is compressing qualification pathways for legacy ingredients. Bakery manufacturers in Chicago and Minneapolis-St. Paul metro areas are accelerating cellulose fortification to meet clean-label expectations. The agency's physiological benefit thresholds favor novel cellulose derivatives with pre-substantiated health claims.
Germany
EFSA's evolving health claim authorization process is compressing permissible gut-health marketing language. J. Rettenmaier & Söhne GmbH + Co KG anchors European production of refined fiber concentrates in Rosenberg for pharmaceutical-grade applications. REACH registration requirements for novel cellulose derivatives are redirecting R&D investment toward certified-sustainable feedstocks.
China
Dual carbon goals and bioplastics targets under MIIT planning are stimulating cellulose nanofibril extraction from agricultural residues. Coastal processing clusters in Jiangsu and Zhejiang provinces are absorbing capital previously directed toward conventional fiber refining. GB standards for compostable packaging are converging with EU Green Deal technical specifications.
India
FSSAI fortification guidelines are opening the processed food sector to imported cellulose concentrates. Domestic wheat bran supply inconsistencies in Maharashtra and Gujarat are driving bread manufacturers toward mass-market fortification alternatives. CDSCO pharmaceutical excipient regulations are creating parallel qualification tracks for tablet-grade fiber imports.
Japan
METI bioplastics commercialization programs are accelerating chitosan-cellulose composite film development for active packaging. Seafood processing waste streams in Hokkaido and Kyushu supply crustacean-derived chitosan for antimicrobial coating applications. JIS standards for compostable materials are aligning with OECD technical guidance on marine biodegradability testing.
Insoluble Fibers Market Competitive Landscape
Capacity expansion dominates the current landscape as agricultural processors and chemical specialists build dedicated fiber refining lines. The vendor base stratifies across three tiers: diversified agribusiness conglomerates with captive raw material access, specialized fiber refiners with pharmaceutical-grade certification, and regional toll processors serving contract manufacturing demand. Strategic archetypes include supply-secured integrators, purity-focused specialists, and scale-driven commodity producers. M&A activity and backward integration into agricultural residue sourcing represent the dominant competitive moves.
Among diversified agribusiness conglomerates, Cargill, Incorporated and Archer Daniels Midland exemplify supply-secured positioning through agricultural supply chain control. J. Rettenmaier & Söhne GmbH + Co KG occupies the purity-focused specialist tier with European pharmaceutical-grade production anchoring. DuPont represents technology-led positioning on modified cellulose derivatives, particularly in bioplastics feedstock development where patent-protected processes create differentiation.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Grain Processing Corporation |
| Ingredion Incorporated |
| J. Rettenmaier & Söhne GmbH + Co KG |
| InterFiber Ltd. |
| DuPont |
| Roquette Frères |
| CFF GmbH & Co. KG |
| Archer Daniels Midland |
| Others |
Pricing and Supply Chain Analysis
Extrusion engineering talent scarcity in the United States Midwest widens pricing spreads between premium pharmaceutical-grade cellulose and standard food-additive tiers, as labor-cost differentials compound with certification overhead.
Pricing Analysis
Volume concentrates in commodity cellulose powders for bakery fortification while margin pools in pharmaceutical-grade concentrates and chitosan antimicrobial grades. Three-tier pricing structure across premium, standard, and economy levels separates FDA-substantiated novel derivatives from legacy wood-pulp grades and unqualified agricultural residues. Pricing pressure stems from psyllium husk volatility bleeding into hybrid formulation economics. Contract manufacturers exhibit highest price sensitivity; pharmaceutical excipient buyers absorb premiums for REACH-registered and pharmaceutical-grade certified supply.
Supply Chain Analysis
Ocean freight rate volatility from East Asian chitosan processing clusters to European active-packaging developers compresses margin buffers on antimicrobial-grade shipments. Raw material sourcing draws from wood pulp operations in the United States and Nordic regions, crustacean processing waste streams concentrated in coastal China and Japan, and agricultural residue collection networks across the American Midwest and Chinese Jiangsu province. Single-source vulnerability sits with East Asian chitosan supply given seasonal seafood processing cycles. Distribution runs through agricultural commodity traders for cellulose, specialized biochemical distributors for chitosan, and toll processors for pharmaceutical-grade concentrates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical-grade refining capacity bottlenecks in Europe prop pricing premiums, making this a supply-constrained market where qualified capacity expansion captures sustained margin.
For Market Incumbents: Lock in backward integration into agricultural residue sourcing in the American Midwest and Nordic pulp regions to secure feedstock continuity against wood pulp price cycles. Prioritize REACH registration investment for novel cellulose derivatives to preempt European competitor qualification and defend positioning against emerging chitosan-cellulose composite suppliers. For New Entrants and Emerging Players: Mid-sized Indian bread manufacturers facing FSSAI fortification mandates represent the most penetrable buyer archetype, as domestic wheat bran supply inconsistencies force rapid qualification of imported cellulose alternatives. Target pelletized-grade supply for bioplastic compounders in China and Germany where dust-control specifications and EU Green Deal targets concentrate procurement shifts. Lead with certified-sustainability credentials and standardized certificate-of-analysis formats that shorten toll-processor qualification cycles. For Investors and Strategic Acquirers: Re-rating potential sits with purity-focused specialists holding pharmaceutical-grade certification and captive agricultural residue supply, given FDA and EFSA health claim authorization timelines extending competitive moats. Monitor REACH registration progress for novel cellulose derivatives as the inflection signal indicating which ingredient grades will retain premium positioning versus commodity compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Residue Sourcing | Cargill and ADM leverage captive Midwest supply to insulate cellulose refining from wood pulp price cycles. |
| REACH Registration Investment | Novel cellulose derivative developers secure European market access ahead of competitors facing ECHA authorization delays. |
| Pharmaceutical-Grade Certification Expansion | J. Rettenmaier & Söhne anchors Rosenberg production to capture tablet excipient margin pools. |
| Chitosan-Cellulose Composite Development | Active packaging developers in Japan and Germany combine antimicrobial functionality with compostable film targets. |
| Pelletized Grade Capacity Addition | Bioplastic compounders in China and Germany shift procurement toward dust-controlled formats for melt-compounding operations. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with food formulation directors, pharmaceutical excipient procurement managers, bioplastic compounder technical leads, and agricultural commodity traders. FDA 21 CFR 101.9 guidance documents, EFSA health claim authorization registers, FSSAI fortification circulars, and REACH registration databases provided regulatory validation. Bottom-up fiber grade demand modeling triangulated against top-down end-use industry consumption estimates.
Granularity-level modeling dissected the market by product type, end-use industry, form, and application across national production clusters and regulatory jurisdictions. CAGRs derived from segment-level volume trajectories weighted by pricing tier shifts and qualification timeline assumptions. Forecast inputs incorporated FDA dietary fiber definition enforcement patterns, EU Green Deal bioplastics target adoption curves, and FSSAI processed food sector opening timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH authorization delays, psyllium husk price volatility spillovers, and extrusion engineering talent pipeline constraints. Outputs reflect documented assumptions around regulatory timeline adherence and feedstock supply continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Ethyl Polysilicate Market
Specialty Chemicals
L-Ergothioneine Market
Specialty Chemicals
Rosin Press Market
Specialty Chemicals
Acetyl Isovaleryl Market
Specialty Chemicals
4-ADPA Market
Specialty Chemicals
UV Filters Market
Specialty Chemicals
Dimethylolpropionic Acid (DMPA) Market
Specialty Chemicals
Global Fabric Softener Sheet Market
Specialty Chemicals
PPG-20 Methyl Glucose Ether Market
Specialty Chemicals
VCI Aerosol Market
Specialty Chemicals
Monomethylsilanetriol Market
Specialty Chemicals
Australia and New Zealand Aerosol Market
Specialty Chemicals
US Post Laser Recovery Products Market
Specialty Chemicals
Metal Biocide Market
Specialty Chemicals
Copovidone Market
Specialty Chemicals
Homosalate Market