
 Contouring Products Market | 2026-2036
Contouring Products Market Size, Share, and Industry Trends Forecast 2026-2036
Contouring Products Market Analytics
South Korean contract manufacturers is recalibrating output toward multifunctional cream formats for Western brand partners. Estee Lauder Companies leverages its prestige distribution network to sustain premium positioning across department store channels. Fenty Beauty differentiates through inclusive shade architecture that anchors its professional and consumer crossover appeal. YATSEN Holding competes on digital-native marketing while controlling cost structures in China's domestic supply base.
Contouring products are pigmented cosmetic formulations designed to create optical depth and dimension on facial or body topography through shadowing and highlighting techniques, typically employing matte finishes with specific light-absorption coefficients between 85-95 percent for natural shadow simulation. These products serve both corrective everyday makeup objectives and high-definition media production requirements where camera lighting flattens natural bone structure. Cream formats are capturing accelerated demand growth due to their blendability under 4K and 8K cinematography conditions, while powder segments retain mature volume in consumer retail through established application familiarity. Professional application channels command concentrated margin pools as salons and events require certified product performance under variable temperature and humidity conditions.
The EU Cosmetics Regulation and REACH framework mandate extensive ingredient safety dossiers that shape formulation choices and market access timelines for brands entering European distribution. The US FDA maintains color additive restrictions under 21 CFR 73 and 74 that directly limit pigment selection for facial products sold through interstate commerce. China's NMPA registration requirements for imported cosmetics impose additional testing protocols that filter which formulations achieve commercial presence in that jurisdiction. Stakeholders must monitor evolving clean beauty certification standards across multiple regulatory regimes to anticipate which ingredient classes face future restriction or mandatory substitution.
Market Dynamics
Cream-based formulation dominance is restructuring competitive positioning as professional makeup artists in film and television production demand blendability under high-resolution cinematography. This shift concentrates margin capture among contract manufacturers with flexible emulsion capabilities while compressing powder segment expansion.
Growth Catalysts
- High-definition production standards:4K and 8K cinematography in film and broadcast studios requires cream formulations with superior blendability under intense lighting conditions.
- REACH ingredient disclosure mandates:The EU Cosmetics Regulation tightens safety dossier requirements, filtering out non-compliant suppliers and creating certification premiums for compliant brands.
- Seoul metropolitan cluster concentration:South Korean contract manufacturers are expanding multifunctional cream output for Western brand partnerships, accelerating format innovation cycles.
Market Restraints
- Pigment input volatility:FDA color additive restrictions under 21 CFR 73 and 74 limit approved pigment classes, constraining formulation flexibility for facial products.
- Regulatory friction from NMPA:China's imported cosmetics registration imposes additional testing protocols that extend market access timelines and filter formulation portfolios.
- Substitution from digital editing:Post-production color correction software in media production reduces on-set contouring precision requirements for some applications.
Strategic Opportunities
- Clean beauty certification convergence:Multiple regulatory regimes are evolving ingredient standards, creating first-mover advantage for brands with pre-positioned substitution strategies.
- Professional channel expansion:Salons and certified makeup artists require performance-guaranteed products under variable temperature and humidity, supporting premium positioning.
- Digital-native distribution models:Social commerce platforms enable direct consumer education on application techniques, reducing traditional retail dependency.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in emulsion stability for cream formats under camera lighting conditions commands premium compensation and limits R&D scaling.
- Dual regulatory compliance timelines:Simultaneous EU REACH dossier preparation and FDA color additive petitions create resource bottlenecks for multi-jurisdiction launches.
- Supply chain reconfiguration costs:Shifting from powder to cream production requires retooling filling equipment and temperature-controlled logistics infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contouring Products Market |
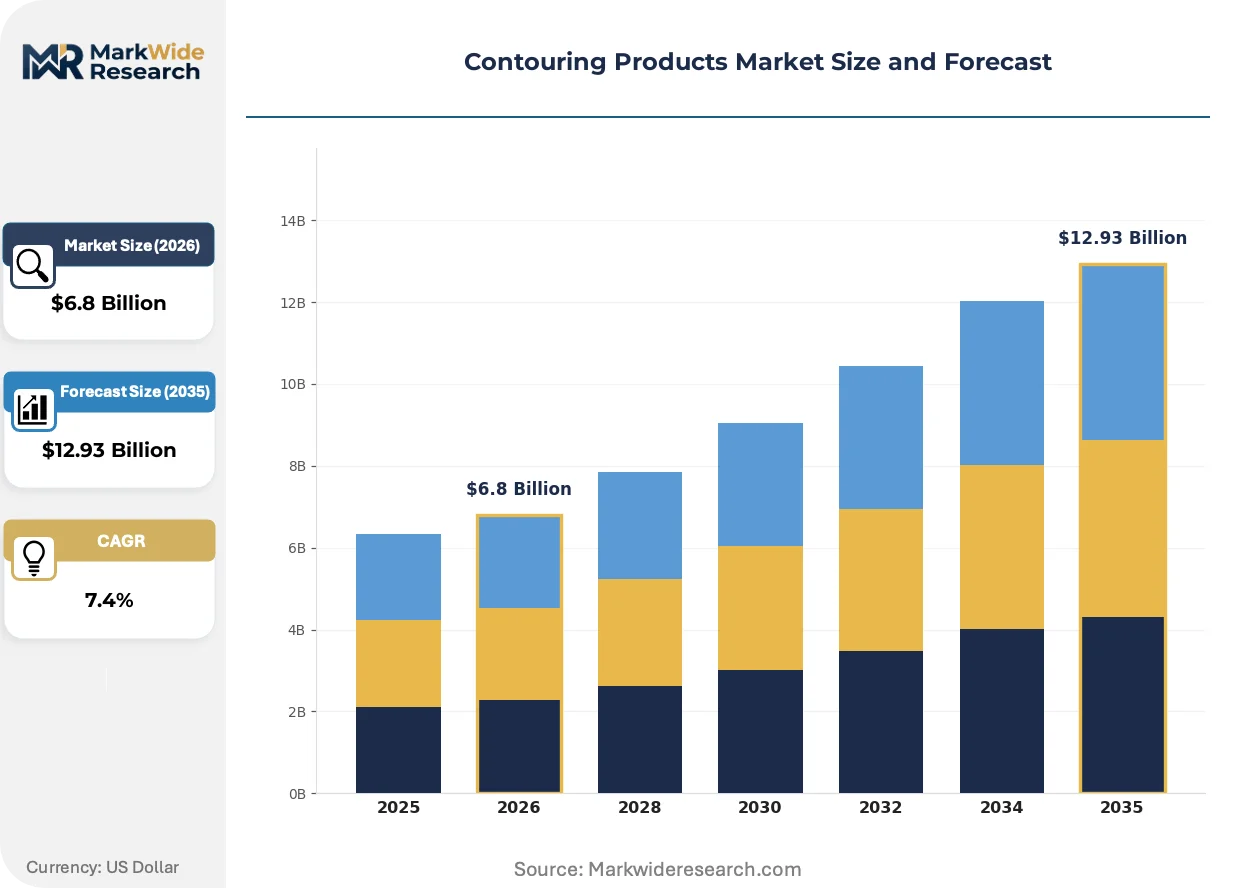
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creams, Powders, Sticks, Palettes Application: Face, Body, Professional, Personal End User: Makeup Artists, Consumers, Salons, Events Distribution Channel: Online Retail, Specialty Stores, Department Stores, Pharmacies |
| Companies Covered | Dior, Carsian, Estee Lauder Companies, Fenty Beauty, YATSEN Holding, Maybelline, Mistine, KVD Vegan Beauty, NYX Professional Makeup, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contouring Products Market Evolving Landscape
Active ingredient transparency and format versatility are compressing traditional category boundaries between professional and consumer segments. Regulatory disclosure requirements and performance demands from high-definition media production are jointly reshaping formulation priorities and competitive differentiation.
Hybrid cream-powder formulations are integrating temperature-responsive polymers that adjust texture based on skin surface conditions. Professional makeup artists in film production are adopting these materials fastest, with studio procurement departments specifying certified performance under 4K lighting. This convergence is integrating corrective and high-definition application categories into unified product architectures.
REACH is tightening safety dossier requirements for cosmetic ingredients entering European distribution, forcing reformulation of legacy shadow and highlight bases. The industrial consequence extends product development cycles by 12-18 months for non-compliant portfolios. Brands with pre-built alternative ingredient libraries are capturing shelf space from slower-adapting competitors.
Consumer education through short-form video platforms is compressing the learning curve for professional application techniques. Retail channel specialists report that tutorial-driven purchase decisions now outpace counter-based consultation in major metropolitan markets. South Korea and China's domestic digital ecosystems exhibit the most pronounced shift toward self-directed product discovery and technique acquisition.
Contouring Products Market Segmentation
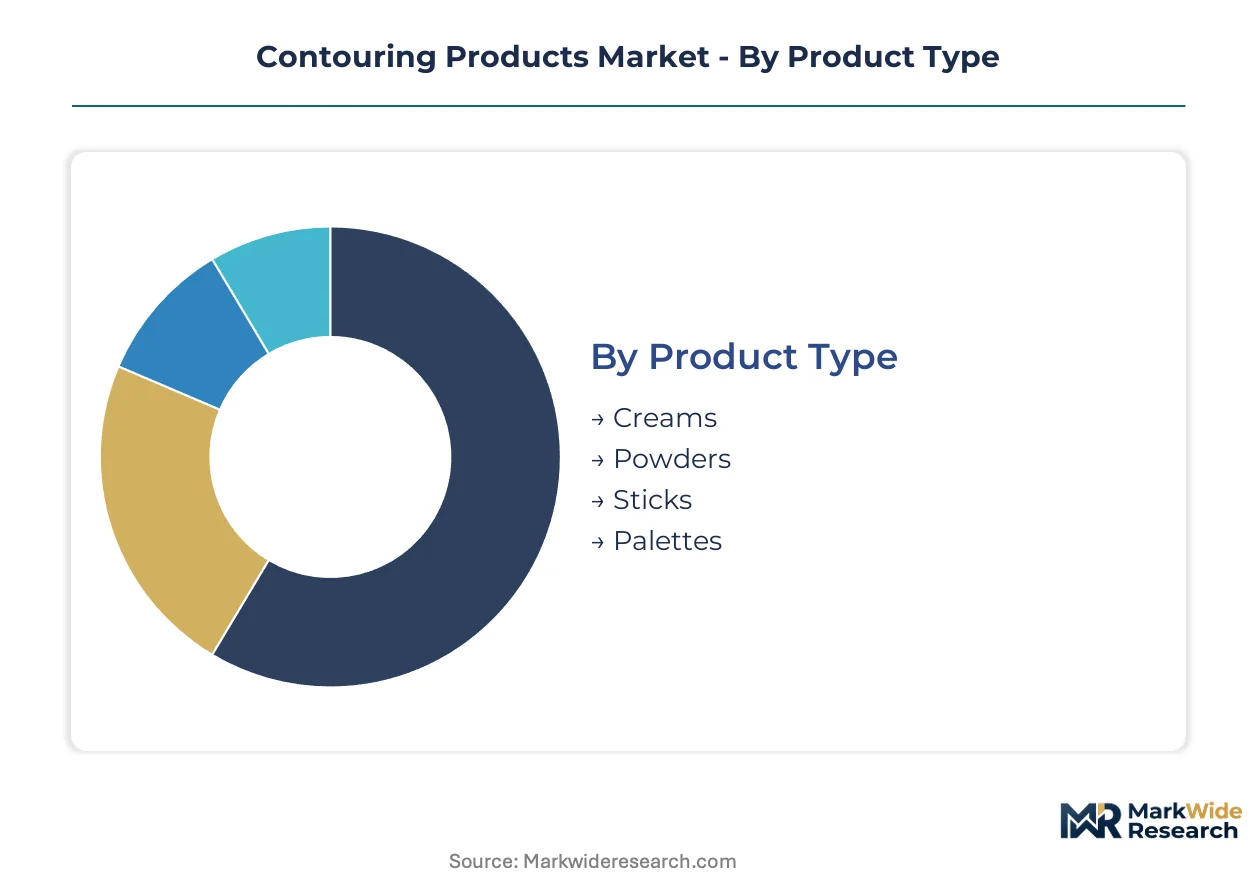
Contouring product segmentation reflects divergent performance requirements between high-definition media production and everyday consumer use. Format selection and channel strategy determine margin capture as professional certification standards separate premium tiers from mass-market alternatives.
Product Type:
Cream formulations command premium positioning due to cinematography-grade blendability demands, while powder segments compete on application familiarity and price accessibility.
- Creams:Emulsion-based formulations with specialized light-absorption coefficients between 85-95 percent simulate natural shadowing under 4K and 8K studio lighting. Demand concentrates among film and television makeup departments in Los Angeles and London production hubs, driven by studio procurement specifications for certified performance under variable humidity.
- Powders:Pressed or loose mineral-based products with established application protocols retain mature retail volume through consumer familiarity. Volume clusters in North American and European drugstore channels where price sensitivity dominates purchase decisions, constrained by slower format innovation cycles relative to cream alternatives.
- Sticks:Solid balm formats offering portable application with controlled dispensing mechanisms.
- Palettes:Multi-shade compacts combining contour, highlight, and transition tones in unified packaging architectures.
Powder formulations lead volumes today; cream segments are gaining share fastest.
Application:
Professional certification requirements create pricing stratification between corrective everyday use and broadcast-performance standards.
- Professional:Products certified for high-definition camera work under studio lighting conditions with documented temperature and humidity tolerances. Demand concentrates in entertainment production centers where makeup artists require formulation stability across 12-hour shooting schedules.
- Face:Precision contouring for cheekbone, jawline, and nasal bridge topography using targeted pigmentation density.
- Body:Larger-surface applications for décolletage, shoulder, and limb contouring with extended blend times.
- Personal:Consumer-grade products designed for self-application with simplified technique requirements and lower pigment concentration.
Personal application leads volumes today; professional segments show steepest expansion trajectory.
End User:
Certification status and volume procurement terms separate institutional buyers from individual purchasers.
- Makeup Artists:Freelance and staff professionals requiring product liability coverage and batch consistency documentation for client work. Demand clusters in metropolitan fashion and entertainment corridors where portfolio-building drives premium product investment.
- Events:Wedding, editorial, and red-carpet specialists with compressed application timelines and photography-dependent outcomes.
- Salons:Service businesses with recurring bulk procurement and retail resale licensing arrangements.
- Consumers:Individual purchasers influenced by tutorial-driven education and social commerce discovery patterns.
Consumer purchases lead volumes today; makeup artist segments are expanding most quickly.
Distribution Channel:
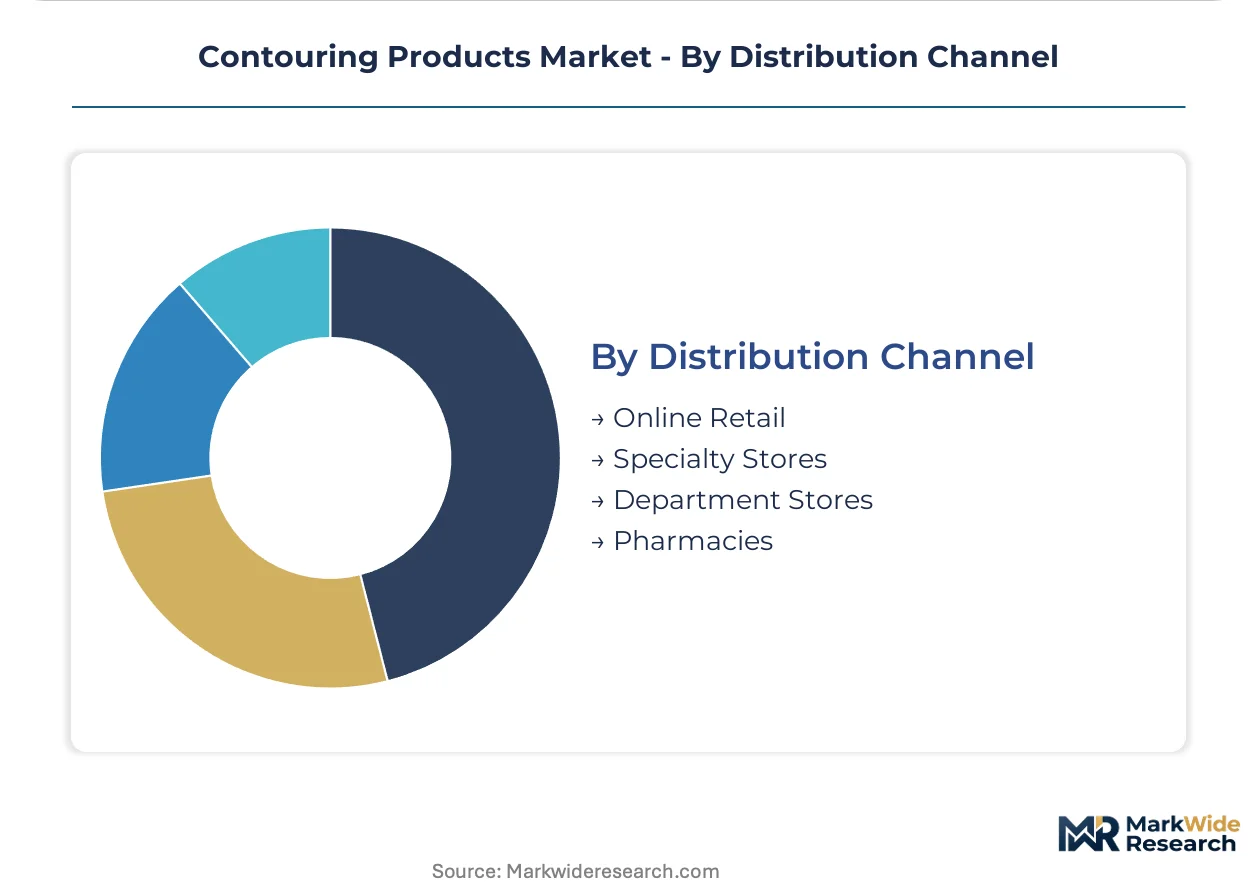
Channel selection determines margin structure through inventory carrying costs and educational service requirements.
- Online Retail:Direct-to-consumer platforms with tutorial-integrated purchase journeys and algorithmic shade-matching tools. Demand concentrates in South Korean and Chinese digital ecosystems where live-commerce demonstrations compress consideration-to-purchase cycles.
- Specialty Stores:Beauty-focused retailers with staffed consultation services and sample-based trial programs.
- Department Stores:Prestige counters with brand-dedicated associates and gift-with-purchase promotional architectures.
- Pharmacies:Mass-market outlets with limited service interaction and price-promotional positioning.
Pharmacy channels lead volumes today; online retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea outpaces Germany in cream-format innovation velocity, while the United States dominates professional channel procurement volumes for high-definition production applications.
United States
Los Angeles and New York production hubs drive professional-grade cream demand from film and television makeup departments. FDA color additive restrictions under 21 CFR 73 and 74 constrain pigment selection for interstate facial product commerce. Studio procurement specifications in Burbank now mandate certified humidity tolerance documentation for 12-hour shooting schedules.
South Korea
Seoul metropolitan contract manufacturers accelerate multifunctional cream output for Western brand partnerships. MFDS cosmetic safety standards enforce rigorous ingredient testing protocols that filter market entrants. The Gangnam beauty cluster concentrates R&D facilities where temperature-responsive polymer development cycles compress to under eight months.
China
Domestic digital ecosystems in Shanghai and Hangzhou compress consideration-to-purchase cycles through live-commerce demonstrations. NMPA registration requirements for imported cosmetics impose extended testing timelines that filter formulation portfolios. Yangtze River Delta manufacturing bases control cost structures for YATSEN Holding's digital-native distribution model.
United Kingdom
London post-production studios reduce on-set contouring precision requirements through advanced color correction software adoption. REACH safety dossier mandates from ECHA reshape formulation priorities for brands entering European distribution. Soho-based makeup artist agencies now require batch consistency documentation for liability coverage in client contracts.
France
Prestige department store channels in Paris sustain premium positioning through gift-with-purchase promotional architectures. EU Cosmetics Regulation disclosure standards tighten ingredient transparency requirements across member state markets. Île-de-France headquarters operations for heritage houses anchor regional distribution network control.
Contouring Products Market Competitive Landscape
South Korean producers anchor the contract manufacturing tier; US and European heritage houses hold premium positioning through prestige distribution networks. The vendor base concentrates among three strategic archetypes: digital-native challengers with cost-controlled supply chains, multinational conglomerates with department store channel dominance, and specialized professional-grade suppliers with certification documentation. Competitive moves center on format innovation cycles in cream emulsions and clean beauty certification pre-positioning to capture regulatory compliance premiums.
Within the heritage conglomerate tier, Estee Lauder Companies and Dior exemplify prestige channel anchoring through controlled distribution networks. Fenty Beauty occupies a position bridging professional certification requirements and inclusive shade architecture for consumer crossover appeal. YATSEN Holding represents the digital-native archetype with domestic China supply base integration and algorithmic shade-matching platform deployment.
| Leading Market Players |
|---|
| Dior |
| Carsian |
| Estee Lauder Companies |
| Fenty Beauty |
| YATSEN Holding |
| Maybelline |
| Mistine |
| KVD Vegan Beauty |
| NYX Professional Makeup |
| Others |
Value Network & Pricing Analysis
Titanium dioxide pigment indices cascade through cream formulation supply chains into three-tier pricing structures across premium, standard, and economy levels. REACH compliance certification premiums and MFDS testing protocols in South Korea amplify cost differentials between certified professional-grade outputs and mass-market alternatives.
Pricing Analysis
Retailer markup layers separate prestige department store counters from pharmacy channels and direct-to-consumer platforms. Price differentiation rests on certification grade—EU Cosmetics Regulation dossier completion versus uncertified mass-market SKUs—and volume scale for salon bulk procurement. Cost compression in economy tiers intensifies as Chinese contract manufacturers absorb NMPA testing overhead for domestic brands. Pharmacy channels exhibit highest price sensitivity; professional makeup artist segments accept premium positioning for batch consistency documentation.
Supply Chain Analysis
Certification gating through REACH safety dossiers and FDA color additive petitions filters supplier eligibility for European and North American distribution. Manufacturing concentrates in South Korea, China, and Italy—Seoul metropolitan contract manufacturers lead cream emulsion innovation while Yangtze River Delta bases control cost structures for digital-native brands. Raw material dependencies include titanium dioxide pigments, temperature-responsive polymers, and emulsion stabilizers. Single-source vulnerability runs through South Korean polymer suppliers for temperature-adaptive formulations. Distribution runs through prestige department store networks, specialty beauty retailers, and algorithmic shade-matching platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The contouring products market functions as a stable compounder anchored by persistent format innovation cycles in professional cinematography applications. High-definition production standards sustain replacement demand regardless of macroeconomic cyclicality.
For Market Incumbents: Acquire specialized emulsion chemistry capabilities to secure formulation chemist talent pools. Consolidate backward integration into temperature-responsive polymer supply to defend margin position against South Korean contract manufacturer expansion. Prioritize REACH pre-certification investment to capture shelf space from slower-adapting competitors facing 12-18 month reformulation delays. For New Entrants and Emerging Players: Begin with algorithmic shade-matching platform deployment targeting China's domestic digital ecosystem where live-commerce demonstrations compress customer acquisition costs. White-space opportunity concentrates in certified professional-grade cream formats for mid-market salon channels underserved by heritage house pricing. Digital-native tutorial integration offers lowest-friction go-to-market positioning. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized professional-grade suppliers possessing documented batch consistency protocols and studio procurement relationships. Five-to-ten year viability hinges on clean beauty certification pre-positioning as regulatory disclosure standards tighten across multiple jurisdictions. Monitor ECHA substance restriction proposals as inflection signal for ingredient substitution cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Clean Beauty Certification Investment | REACH compliance premiums capture shelf space from non-compliant portfolios in European distribution. |
| Professional Channel Expansion | Salon bulk procurement agreements with batch documentation requirements support margin defense. |
| Digital-Native Platform Launch | Algorithmic shade-matching in Chinese live-commerce ecosystems compresses consideration-to-purchase cycles. |
| Backward Integration into Polymers | In-house temperature-responsive polymer production reduces single-source dependency on Seoul suppliers. |
| Multifunctional Format Innovation | Hybrid cream-powder architectures with camera-certified performance unify corrective and professional categories. |
Research Methodology
Direct dialogue with formulation chemists, professional makeup artists, studio procurement managers, and contract manufacturing executives grounded qualitative findings. Secondary validation drew from ECHA substance restriction databases, FDA color additive petition filings, MFDS cosmetic safety standards, and customs trade records for titanium dioxide and polymer inputs. Bottom-up volume estimates triangulated against top-down value projections across the analysis window.
Top-down macroeconomic drivers anchored the analytical framework while bottom-up segment builds captured format-level dynamics across cream, powder, stick, and palette categories. Segmentation modeling incorporated product type, application tier, end-user certification status, and distribution channel complexity. CAGR derivation synthesized historical volume trajectories with professional channel procurement intensity and regulatory compliance timeline impacts. Forecast inputs included studio specification adoption rates for 4K/8K cinematography and REACH dossier completion velocity.
Several conditions sit outside the modeled scope, including abrupt pigment class bans under FDA 21 CFR revisions, digital editing software substitution acceleration in post-production workflows, and geopolitical disruption to South Korean contract manufacturing output. Forecasts reflect documented assumptions about regulatory timeline stability and professional channel growth continuity. A model refresh is warranted upon material change in ECHA substance restriction schedules or studio procurement specification shifts toward unverified formulation categories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Silanes Market
Specialty Chemicals
Perfluoropolyether (PFPE) Market
Specialty Chemicals
Dimethylolpropionic Acid (DMPA) Market
Specialty Chemicals
Phenoxycycloposphazene Market
Specialty Chemicals
Esterquats Market
Specialty Chemicals
Marine Hyaluronic Acid Market
Specialty Chemicals
Global Water Based Acrylates Copolymer Rheology Modifiers Market
Specialty Chemicals
Colloidal Silver Market
Specialty Chemicals
Glucosinolates Market
Specialty Chemicals
Iron Phosphate Market
Specialty Chemicals
Silver Iodide Market
Specialty Chemicals
Global Molecular Weight Marker Market
Specialty Chemicals
Natural Ingredient Insect Repellent Market
Specialty Chemicals
Bio-Based Phenol Market
Specialty Chemicals
Stearates Market
Specialty Chemicals
United States Aerosol Cans Market