
 VCI Aerosol Market | 2026-2036
VCI Aerosol Market Size, Share, and Industry Trends Forecast 2026-2036
VCI Aerosol Market Analytics
Precision electronics manufacturers are unwinding legacy purchasing patterns from general industrial maintenance buyers as semiconductor fabrication facilities demand residue-free VCI aerosol formulations for cleanroom-compatible metal protection. Cortec Corporation leverages proprietary amine-carboxylate chemistry to dominate North American military and aerospace specifications. Daubert Cromwell anchors European supply through REACH-registered solvent-based platforms with established automotive Tier-1 approvals. Armor Protective Packaging specializes in water-based aerosol systems that sustain food-contact and medical device packaging certifications without fluorinated propellants.
VCI aerosol denotes a pressurized delivery system suspending vapor corrosion inhibitor compounds—typically amine salts of organic acids or carboxylate complexes—in a propellant matrix for direct application to metal surfaces, where the active agents volatilize to form a monomolecular protective barrier against moisture and oxygen ingress. The formulation typically contains 5-15% inhibitor concentrate with hydrocarbon or compressed gas propellants, achieving coverage rates of 200-400 square feet per can depending on substrate geometry and ambient humidity. Solvent-based variants retain the largest revenue share due to faster drying and deeper crevice penetration in heavy machinery applications, while water-based formulations are gaining fastest in electronics and food packaging end uses where volatile organic compound restrictions and workplace exposure limits tighten procurement criteria. Electrostatic spray technology leads industrial deployment for uniform coating of complex geometries, whereas cold fogging systems compete in large-volume warehouse and shipping container applications where manual aerosol coverage proves uneconomical.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-based propellant formulations in the United States, while REACH Annex XVII restrictions on volatile organic compounds reshape formulation requirements across European manufacturing supply chains. OSHA permissible exposure limits for amine compounds further constrain production facility operations and worker protection protocols in metalworking plants employing high-volume aerosol applications. Stakeholders must monitor evolving propellant phase-out schedules and cross-reference them against end-user certification requirements to avoid stranded inventory in regulated jurisdictions.
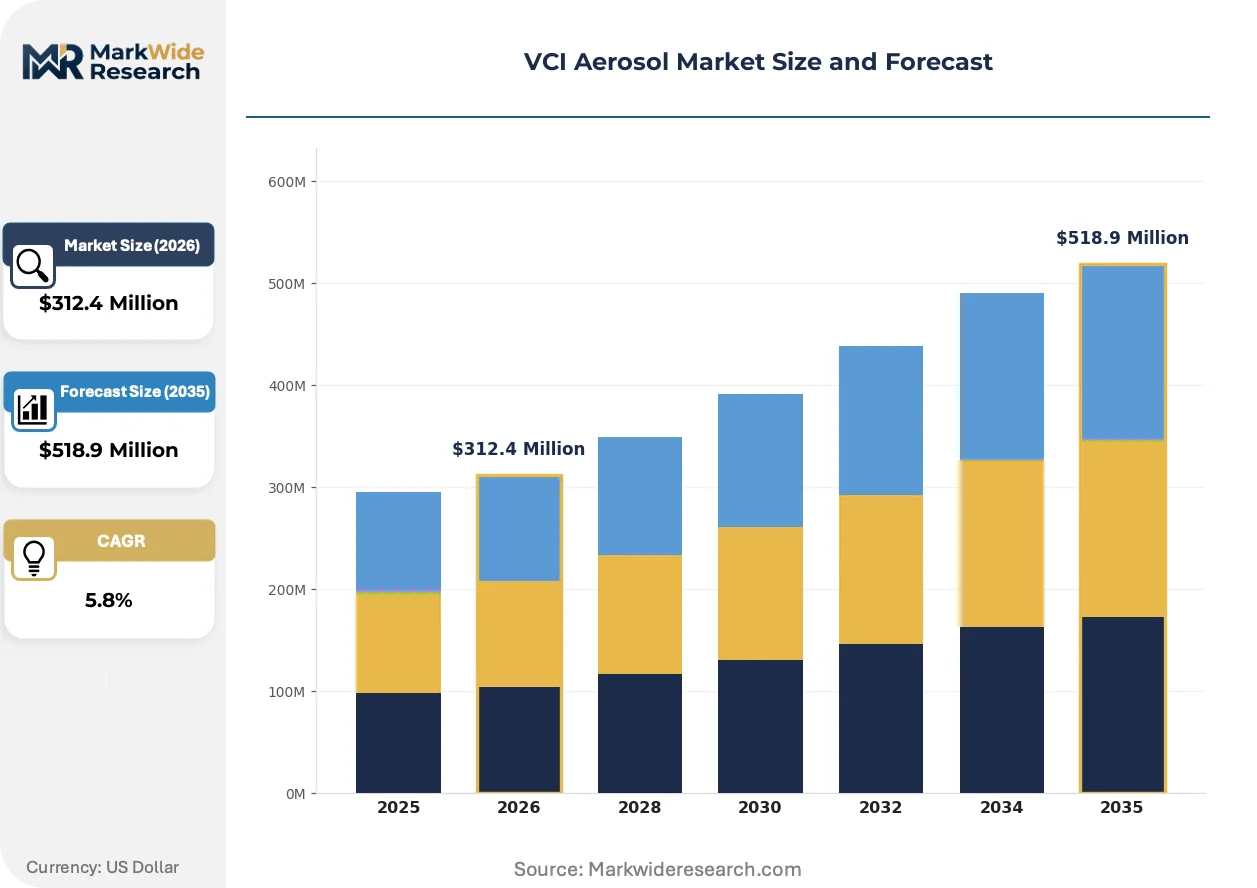
Market Dynamics
REACH Annex XVII volatile organic compound restrictions and EPA National Emission Standards for Hazardous Air Pollutants are forcing simultaneous reformulation of propellant matrices and inhibitor carrier solvents across European and North American supply chains, compressing legacy solvent-based product lifecycles while elevating water-based and compressed gas alternatives.
Growth Catalysts
- Automotive OEM component protection:Extended supply chain transits for precision metal parts from German manufacturing clusters to assembly plants in Mexico and the southeastern United States are accelerating specification of high-performance vapor corrosion inhibitor delivery systems.
- REACH-registered solvent platforms:ECHA registration requirements for amine-carboxylate chemistries have created qualification barriers that favor established European formulators with documented substance dossiers and automotive Tier-1 approvals.
- Electrostatic spray deployment:Industrial metalworking facilities in the United States are adopting charged-particle application technology for uniform coating of complex geometries in heavy machinery maintenance.
Market Restraints
- Propellant input cost volatility:Hydrocarbon propellant pricing tracks petrochemical feedstock indices, exposing formulators to margin compression when crude oil benchmarks fluctuate.
- Amine compound exposure limits:OSHA permissible exposure limits constrain high-volume aerosol application in metalworking plants, requiring capital-intensive ventilation and worker protection protocols.
- Dry film VCI substitutes:Non-aerosol vapor corrosion inhibitor formats including emitters, papers, and films compete for packaging applications where propellant-free delivery satisfies workplace safety requirements.
Strategic Opportunities
- Cleanroom-compatible residue-free formulations:Semiconductor fabrication facilities in Taiwan and South Korea represent underpenetrated demand for VCI aerosols meeting ISO 14644 particulate contamination standards.
- Food-contact packaging certification:Water-based aerosol systems without fluorinated propellants can capture medical device and food packaging segments where FDA indirect food additive regulations apply.
- Cold fogging technology convergence:Integration of ultrasonic atomization with compressed gas propulsion enables large-volume warehouse and shipping container applications previously uneconomical for manual aerosol coverage.
Industry Challenges
- Formulation chemist skill scarcity:Specialized expertise in amine-carboxylate complex stability and propellant-inhibitor compatibility resides with a limited cohort of experienced compounders approaching retirement.
- Cross-jurisdiction certification timelines:Dual registration under EPA FIFRA and REACH requires 18-36 month approval cycles that delay product launches and strand development investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VCI Aerosol Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Foam, Aerosol End User: Manufacturing, Automotive, Electronics, Packaging Application: Corrosion Protection, Surface Treatment, Cleaning, Lubrication Technology: Electrostatic Spray, Compressed Air, Cold Fogging, Thermal Fogging |
| Companies Covered | Cortec Corporation, Daubert Cromwell, Armor Protective Packaging, Northern Technologies International Corporation, The Lubrizol Company, Adsil Corporation, BRANOpac GmbH, Aicello Corporation, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VCI Aerosol Market Evolving Landscape
Formulation chemistry and application hardware are diverging along distinct innovation vectors, with propellant technology racing toward zero-VOC compliance while delivery mechanisms pursue automation and precision coverage capabilities.
Water-based VCI aerosol technology is bifurcating the market between heavy machinery applications demanding solvent-based penetration and electronics packaging requiring residue-free protection. Semiconductor fabrication facilities in Taiwan and South Korea are specifying aqueous formulations at accelerating rates. This technology is compressing the addressable market for legacy solvent platforms in precision metal protection while expanding total category penetration into cleanroom environments.
EPA National Emission Standards for Hazardous Air Pollutants are constraining hydrocarbon propellant formulations in the United States, forcing reformulation toward compressed carbon dioxide and nitrogen matrices. Metalworking facilities in Ohio, Michigan, and Illinois face compliance deadlines that compress product transition timelines. Solvent-based variants retain position in heavy machinery crevice penetration applications where drying speed outweighs regulatory cost.
Specification authority is migrating from general industrial maintenance buyers to precision electronics quality engineers with distinct residue and particulate requirements. Semiconductor and medical device OEMs in Germany and the United States are displacing distributor-centric purchasing with direct technical qualification protocols. This pattern concentrates most visibly in Bavarian automotive electronics clusters and Austin semiconductor fabrication corridors.
VCI Aerosol Market Segmentation
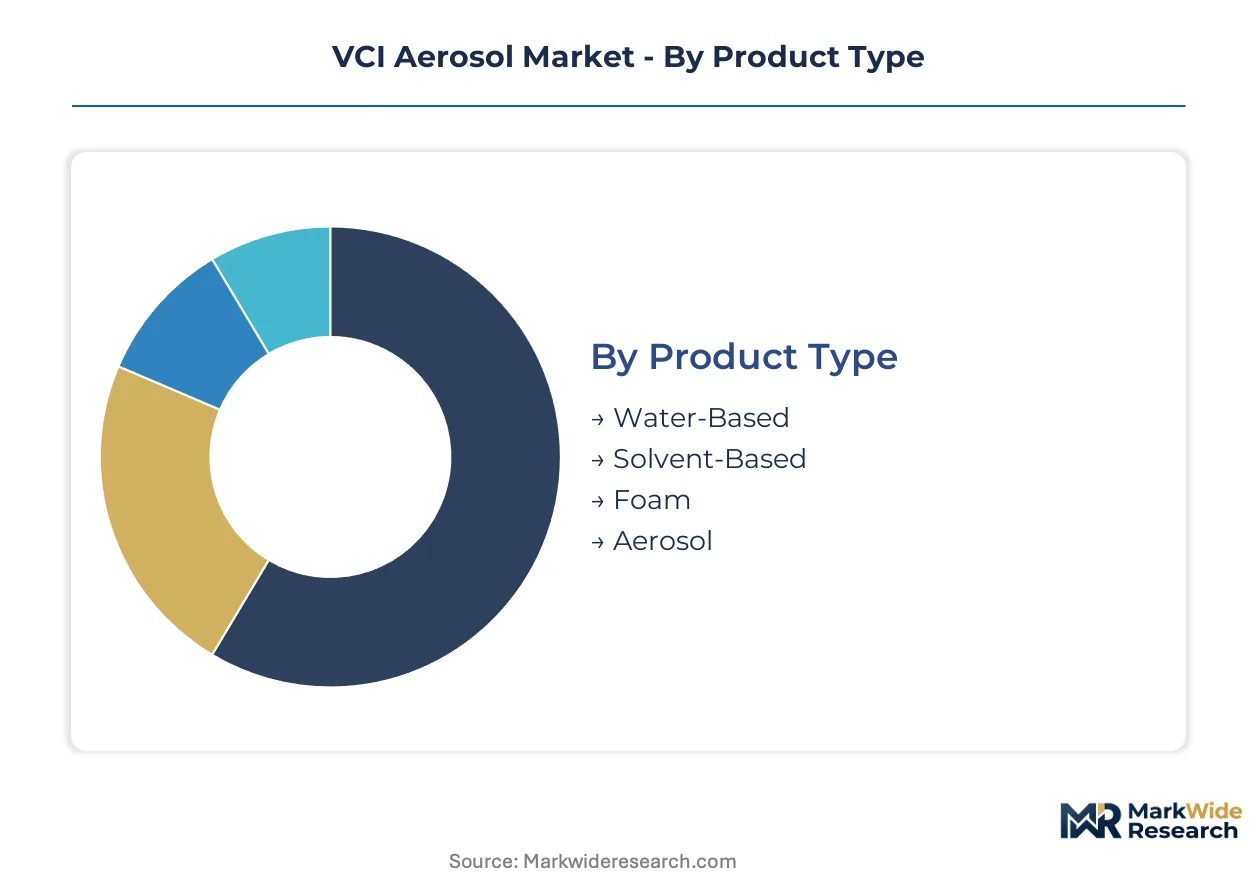
VCI aerosol formulations diverge sharply across end-use requirements, with solvent-based systems dominating heavy machinery maintenance while water-based alternatives penetrate cleanroom-sensitive electronics manufacturing. Understanding these segment boundaries enables suppliers to align R&D investment with regulatory trajectories and procurement authority shifts.
Product Type:
Water-based formulations concentrate demand in domestic electronics clusters where OSHA exposure limits and EPA volatile organic compound rules tighten fastest, while solvent-based platforms retain export-led automotive component protection contracts.
- Water-Based:Aqueous suspensions of amine-carboxylate complexes eliminate hydrocarbon propellants entirely. Semiconductor fabrication facilities in Taiwan and South Korea specify these formulations for ISO 14644-compliant metal protection where particulate residue triggers catastrophic yield loss. FDA indirect food additive pathways further expand deployment into medical device packaging.
- Solvent-Based:Hydrocarbon carrier matrices deliver rapid drying and deep crevice penetration for heavy machinery applications. German automotive Tier-1 suppliers rely on REACH-registered solvent platforms for precision component protection during extended transits to Mexican and southeastern US assembly plants.
- Foam:Thickened emulsion systems cling to vertical surfaces and complex geometries without runoff. Metalworking maintenance crews in Ohio and Michigan deploy foam variants for overhead conveyor protection.
- Aerosol:Pressurized canister delivery remains the default procurement format for field maintenance and small-batch applications. Distributor networks across the United States stock aerosol SKUs for general industrial buyers without electrostatic spray infrastructure.
Solvent-based formulations command the established base. The steepest expansion runs through water-based systems.
End User:
Procurement authority migration from general maintenance buyers to quality engineers reshapes segment economics, with electronics and automotive demanding technical qualification protocols that exclude distributor-centric purchasing.
- Manufacturing:Broad-spectrum metalworking plants apply VCI aerosols for in-process corrosion protection and finished goods preservation. Facilities in Illinois and Indiana balance solvent-based performance against OSHA ventilation upgrade costs.
- Automotive:OEM component suppliers specify high-performance vapor corrosion inhibitor delivery for precision parts traversing multi-modal supply chains. Bavarian manufacturing clusters anchor European demand with documented REACH substance dossiers.
- Electronics:Semiconductor and medical device OEMs impose residue-free requirements that disqualify legacy solvent platforms. Cleanroom-compatible aqueous formulations gain specification authority fastest in this segment.
- Packaging:Food-contact and pharmaceutical logistics drive water-based aerosol adoption where fluorinated propellant bans apply. Medical device sterilization packaging in Germany and the United States requires FDA-compliant barrier formulations.
Automotive procurement maintains volume leadership. Electronics quality engineering is climbing the fastest.
Application:
Functional differentiation separates protective coatings from process chemistry, with corrosion protection commanding premium pricing against commodity cleaning applications.
- Corrosion Protection:Monomolecular barrier formation against moisture and oxygen ingress represents the core value proposition. Extended supply chain transits for German automotive exports to Mexico sustain specification of high-performance inhibitor delivery systems.
- Surface Treatment:Pre-coating preparation and adhesion promotion applications compete with dedicated metal finishing chemistries. Heavy machinery rebuild facilities in Michigan deploy aerosol surface treatment for field repair scenarios.
- Cleaning:Degreasing and contaminant removal functions overlap with general industrial maintenance aerosols. Price pressure from commodity solvent cleaners constrains margin expansion in this application.
- Lubrication:Combined corrosion inhibition and friction reduction targets precision mechanism preservation. Aerospace maintenance depots specify dual-function formulations for avionics hardware storage.
Corrosion protection commands the established base. The steepest expansion runs through surface treatment integration with automated coating lines.
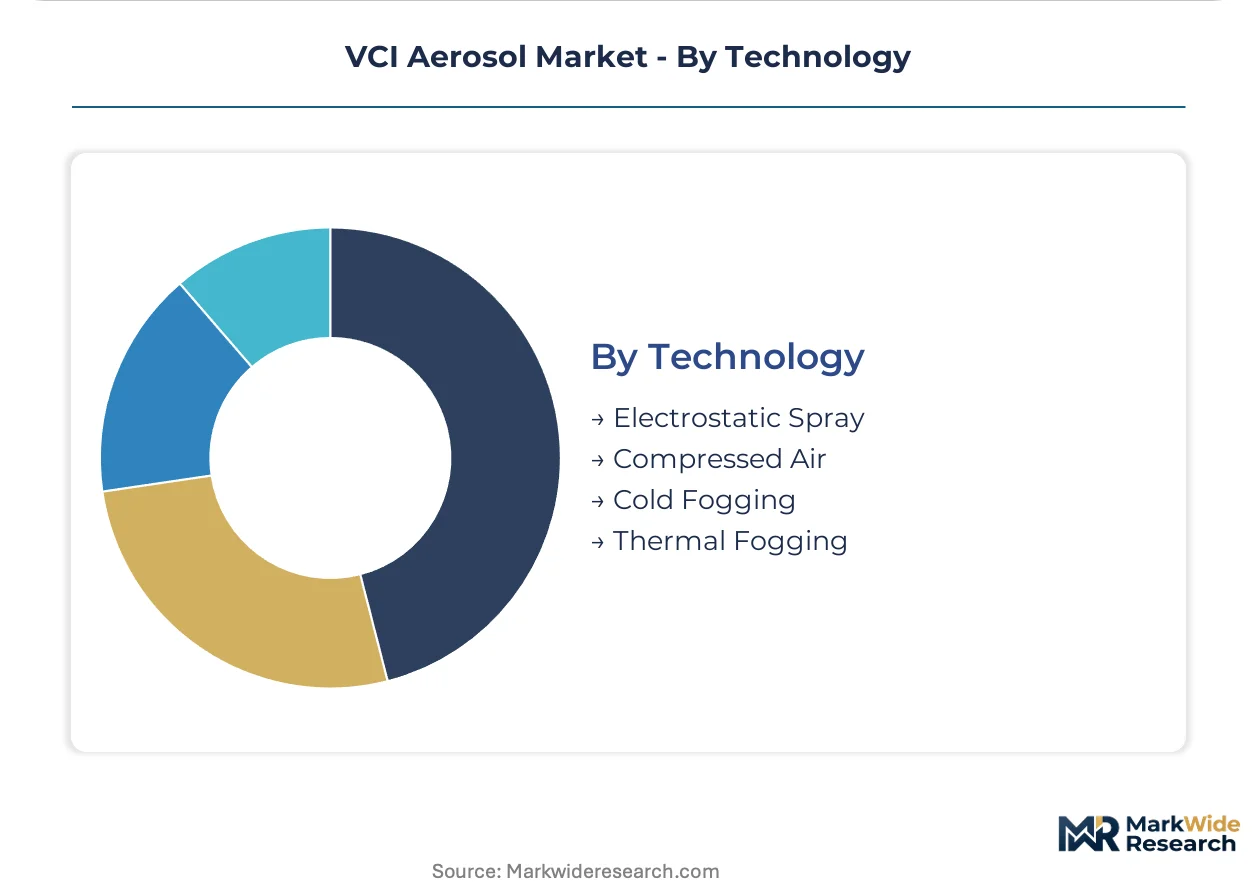
Technology:
Application hardware investment separates high-volume industrial users from manual aerosol purchasers, with electrostatic and fogging systems capturing warehouse-scale deployment.
- Electrostatic Spray:Charged-particle application achieves uniform coating of complex geometries with minimal overspray. US metalworking facilities in Ohio adopt this technology for heavy machinery maintenance efficiency.
- Compressed Air:Conventional pneumatic atomization remains the default for manual and semi-automated lines. Lower capital requirements sustain deployment in small-batch manufacturing environments.
- Cold Fogging:Ultrasonic atomization with compressed gas propulsion enables large-volume warehouse and shipping container applications. Integration with aqueous VCI formulations expands addressable coverage beyond manual aerosol economics.
- Thermal Fogging:Heat-assisted vaporization targets penetrating dense equipment arrays and void spaces. Specialized deployment in military and aerospace preservation protocols where complete enclosure coverage is mandatory.
Compressed air systems command the established base. Cold fogging integration is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulators with REACH-registered substance dossiers and EPA-compliant propellant platforms command disproportionate supply-side influence. Regulatory fragmentation between jurisdictions compresses product lifecycles and elevates qualification barriers for new entrants.
United States
Automotive OEM component protection and heavy machinery maintenance drive procurement volume. EPA National Emission Standards for Hazardous Air Pollutants constrain hydrocarbon propellant formulations, forcing compressed gas alternatives. Metalworking clusters in Ohio, Michigan, and Illinois adopt electrostatic spray infrastructure for uniform coating of complex geometries.
Germany
Bavarian automotive electronics clusters and precision component manufacturing anchor European demand. REACH Annex XVII volatile organic compound restrictions reshape formulation requirements across manufacturing supply chains. Stuttgart and Munich manufacturing corridors specify high-performance vapor corrosion inhibitor delivery for extended export transits to Mexican assembly plants.
China
Domestic automotive production and electronics manufacturing expansion sustain import substitution for solvent-based platforms. National volatile organic compound emission standards tighten formulation requirements in Yangtze River Delta manufacturing zones. Shanghai and Suzhou industrial corridors drive specification of aqueous formulations for workplace exposure compliance.
South Korea
Semiconductor fabrication facilities in Gyeonggi Province specify residue-free aqueous formulations for ISO 14644-compliant metal protection. Ministry of Environment air quality regulations accelerate propellant transition timelines. Seoul Capital Area electronics clusters displace distributor-centric purchasing with direct technical qualification protocols.
Japan
Precision electronics and automotive component manufacturing sustain demand for cleanroom-compatible barrier formulations. METI chemical substance management frameworks align with REACH substance dossier requirements. Nagoya automotive corridors and Osaka electronics clusters drive specification migration toward water-based systems.
VCI Aerosol Market Competitive Landscape
Concentration sits with established formulators possessing cross-jurisdiction regulatory registrations and documented automotive Tier-1 approvals. The competitive terrain separates REACH-registered European specialists from North American military-aerospace specification holders. Three archetypes dominate: regulatory-compliant legacy compounders, water-based cleanroom specialists, and diversified packaging conglomerates with aerosol divisions. Capacity expansion and strategic technology licensing represent the dominant competitive vectors as formulators race to replace hydrocarbon propellants ahead of compliance deadlines.
Within the regulatory-compliant legacy tier, Cortec Corporation and Daubert Cromwell occupy positions anchored by proprietary chemistry platforms and established specification authority. Armor Protective Packaging exemplifies the water-based cleanroom specialist archetype, representing formulation approaches that sustain food-contact and medical device certifications without fluorinated propellants. These three entities collectively illustrate the competitive fault lines between solvent-based performance and aqueous regulatory compliance.
| Leading Market Players |
|---|
| Cortec Corporation |
| Daubert Cromwell |
| Armor Protective Packaging |
| Northern Technologies International Corporation |
| The Lubrizol Company |
| Adsil Corporation |
| BRANOpac GmbH |
| Aicello Corporation |
| Mondi Group |
| Others |
Value Network & Pricing Analysis
REACH Annex XVII volatile organic compound restrictions simultaneously gate supplier qualification and stratify price tiers across European and North American VCI aerosol markets. Formulators bearing ECHA-registered substance dossiers command premium positioning against unregistered competitors facing compliance exclusion.
Pricing Analysis
EPA National Emission Standards for Hazardous Air Pollutants dictates the pricing tier structure across the United States market. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered European imports from domestic compressed-gas formulations and commodity hydrocarbon-propelled alternatives. Price differentiation hinges on certification grade and automotive Tier-1 approval status. Cost compression in solvent-based tiers is intensifying because propellant phase-out deadlines accelerate inventory markdowns. General industrial maintenance buyers exhibit highest price sensitivity, while semiconductor quality engineers prioritize residue-free specifications over unit cost.
Supply Chain Analysis
Propellant feedstock transit from Gulf Coast petrochemical complexes underwrites North American formulation economics. Manufacturing concentration centers on Germany, the United States, and China for finished aerosol production, with active amine-carboxylate inhibitor complexes sourcing from specialty chemical producers in Belgium and Japan. Raw material dependencies span hydrocarbon propellants, compressed gas matrices, and purified amine salts. Single-source vulnerability runs through REACH-registered inhibitor compounders holding documented substance dossiers. Distribution runs through automotive Tier-1 supplier networks and industrial chemical distributors serving metalworking clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in amine-carboxylate complex stability resides with a thinning cohort of experienced compounders, constraining formulation innovation capacity and elevating acquisition premiums for technical talent pipelines.
For Market Incumbents: Secure proprietary propellant-transition formulations ahead of EPA compliance deadlines to outpace hydrocarbon-dependent competitors facing stranded inventory. Deepen backward integration into amine-carboxylate complex manufacturing to control input quality and accelerate REACH dossier updates. Channel control through exclusive automotive Tier-1 supply agreements defends position against water-based specialists encroaching from electronics segments. For New Entrants and Emerging Players: FDA indirect food additive certification fast-tracks penetration into medical device packaging and food-contact logistics where fluorinated propellant bans eliminate incumbent advantages. Taiwan and South Korean semiconductor fabrication facilities represent the most penetrable demand cluster, with residue-free aqueous specifications displacing solvent-based legacy supply. A direct technical qualification protocol bypassing distributor networks accelerates specification authority capture from quality engineers. For Investors and Strategic Acquirers: EPA National Emission Standards for Hazardous Air Pollutants enforcement milestones reshape the acquisition landscape toward water-based formulation platforms with compressed gas propulsion infrastructure. Long-term viability favors targets possessing cross-jurisdiction regulatory registrations and documented automotive Tier-1 approvals. The signal to watch is propellant phase-out schedule acceleration in Ohio, Michigan, and Illinois manufacturing corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amine-Carboxylate Manufacturing | Captive supply of active inhibitor complexes secures REACH dossier continuity and quality consistency. |
| Compressed Gas Propulsion Platform Migration | EPA compliance alignment eliminates hydrocarbon propellant exposure ahead of enforcement deadlines. |
| Cleanroom-Compatible Aqueous Formulation Launch | ISO 14644 certification opens semiconductor fabrication facility procurement in Taiwan and South Korea. |
| Automotive Tier-1 Supply Agreement Extension | Long-term offtake contracts with Bavarian manufacturing clusters anchor European revenue visibility. |
| Joint Venture with Electronics Packaging Specialist | Medical device sterilization packaging expertise accelerates FDA indirect food additive pathway navigation. |
Research Methodology
A spread of perspectives from formulation chemists, automotive Tier-1 procurement leads, semiconductor quality engineers, and industrial chemical distributors converged on the working assumptions underlying this analysis. Primary interviews with plant managers at Ohio and Michigan metalworking facilities, REACH regulatory consultants, and channel sales heads at specialty chemical distributors combined with secondary validation from ECHA substance dossier databases, EPA enforcement calendars, and automotive production data. SEC 10-K filings from listed packaging conglomerates and customs records of amine-carboxylate compound trade flows enabled bottom-up and top-down triangulation.
Segmentation dimensions modeled span formulation chemistry, end-use industry, application function, and propulsion technology across the analysis window. Product type splits between water-based, solvent-based, foam, and aerosol delivery formats intersect with manufacturing, automotive, electronics, and packaging end-user categories. CAGRs were derived from installation base growth in electrostatic spray infrastructure and cold fogging deployment rates. Forecast inputs incorporated semiconductor fabrication facility construction pipelines and automotive export transit duration trends from German manufacturing clusters.
Decision-makers should treat outputs as directional under sustained EPA enforcement timelines and REACH dossier renewal schedules; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as propellant phase-out acceleration and amine compound exposure limit tightening evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Epoxidized Soybean Oil Market
Specialty Chemicals
Abierixin Market
Specialty Chemicals
2-(2,2,2-Trifluoroethoxy)-1,3,2-Dioxaphospholane-2-Oxide Market
Specialty Chemicals
Global Cyclodextrin Market
Specialty Chemicals
Polyquaternium 6 Market
Specialty Chemicals
Contouring Products Market
Specialty Chemicals
Global Mannosylerythritol Lipids Market
Specialty Chemicals
Bio-Based Aromatics Market
Specialty Chemicals
Global Metal Chelates Market
Specialty Chemicals
Disodium Adenosine Triphosphate Market
Specialty Chemicals
Silicone Derivative Market
Specialty Chemicals
South Korea Cleanroom Disposable Gloves Market
Specialty Chemicals
Taurine Market
Specialty Chemicals
Global Hydroxy Ethyl Cellulose (HEC) Market
Specialty Chemicals
Sphingolipids Market
Specialty Chemicals
Methyl Salicylate Market