
 Specialty Plasticizer Market | 2026-2036
Specialty Plasticizer Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Plasticizer Market Outlook
Buyer concentration among automotive OEMs and medical device compounders is expanding as tier-one suppliers consolidate their approved vendor lists. BASF SE leverages its integrated oxo-alcohol chain to sustain cost-advantaged supply of adipate and trimellitate esters. Eastman Chemical Co. anchors North American specialty ester production through its Kingsport manufacturing complex. Valtris Specialty Chemicals differentiates via backward integration into epoxidized soybean oil feedstocks for bio-based grades.
Specialty plasticizers are high-purity ester compounds, typically produced through esterification of acids with C8-C13 alcohols, designed to impart flexibility, low-temperature performance, or migration resistance to PVC and other polymers. Their primary commercial purpose centers on meeting stringent extraction, volatility, and toxicity specifications that commodity phthalates cannot satisfy. Non-phthalate formulations now command the fastest growth trajectory as regulatory pressure and OEM substance restrictions displace legacy chemistries. Bio-based segments remain niche but carry premium positioning where carbon accounting and renewable content thresholds determine supplier qualification. Liquid forms dominate volume flows, though paste and granular variants serve specialized calendering and dry-blend compounding operations.
REACH registration requirements and RoHS substance restrictions in Europe, alongside FDA 21 CFR 175.105 and 177.1210 compliance for food-contact and medical applications in the United States, collectively reshape product development priorities and market access conditions. China's GB standards and evolving MEE environmental enforcement add further compliance layers for suppliers serving Asian manufacturing chains. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation timelines and avoid stranded inventory positions.
Market Dynamics
Regulatory pressure on phthalate chemistries is compressing legacy supply chains while medical device and automotive OEMs consolidate their approved substance lists around high-purity ester alternatives.
Growth Catalysts
- REACH substance restrictions:ECHA's evolving candidate list of substances of very high concern is forcing compounders across Germany, France, and Italy to accelerate reformulation timelines toward adipate and trimellitate esters.
- Medical tubing specification upgrades:Hospital procurement groups in the US and EU are mandating phthalate-free alternatives for IV bags, blood bags, and peristaltic pump tubing to meet FDA 21 CFR 177.1210 and MDR compliance.
- Automotive interior VOC limits:OEM substance restrictions on dashboard and sealant formulations are concentrating demand for low-volatility, non-fogging plasticizer grades in Germany and the US Midwest manufacturing corridors.
Market Restraints
- Oxo-alcohol feedstock volatility:C8-C13 alcohol prices fluctuate with natural gas and propylene contract movements, compressing margin stability for ester producers dependent on merchant supply.
- Specialized reactor asset scarcity:High-purity esterification capacity concentrates among integrated petrochemical complexes in Germany and the US Gulf Coast, limiting new entrant supply expansion.
- Legacy phthalate cost anchoring:DINP and DEHP maintain price advantages in non-regulated applications, creating substitution friction in price-sensitive wire and cable segments.
Strategic Opportunities
- India medical device manufacturing:CDSCO's alignment with ISO 10993 biocompatibility standards and the PLI scheme for medical devices is opening specification windows for imported high-purity grades.
- Epoxidized soybean oil convergence:Bio-based feedstock processing is converging with conventional esterification infrastructure to produce renewable-content grades qualifying for EU Green Deal procurement thresholds.
- Direct OEM qualification channels:Bypassing traditional distributor networks to secure approved vendor list positions with tier-one automotive and medical compounders is capturing margin premiums.
Industry Challenges
- Migration testing protocol complexity:Demonstrating extraction resistance under FDA 21 CFR 175.105 and EU 10/2011 food-contact frameworks requires extended laboratory validation cycles.
- Multi-jurisdiction registration synchronization:Maintaining concurrent REACH, TSCA, and China MEE new substance notifications strains regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Plasticizer Market |
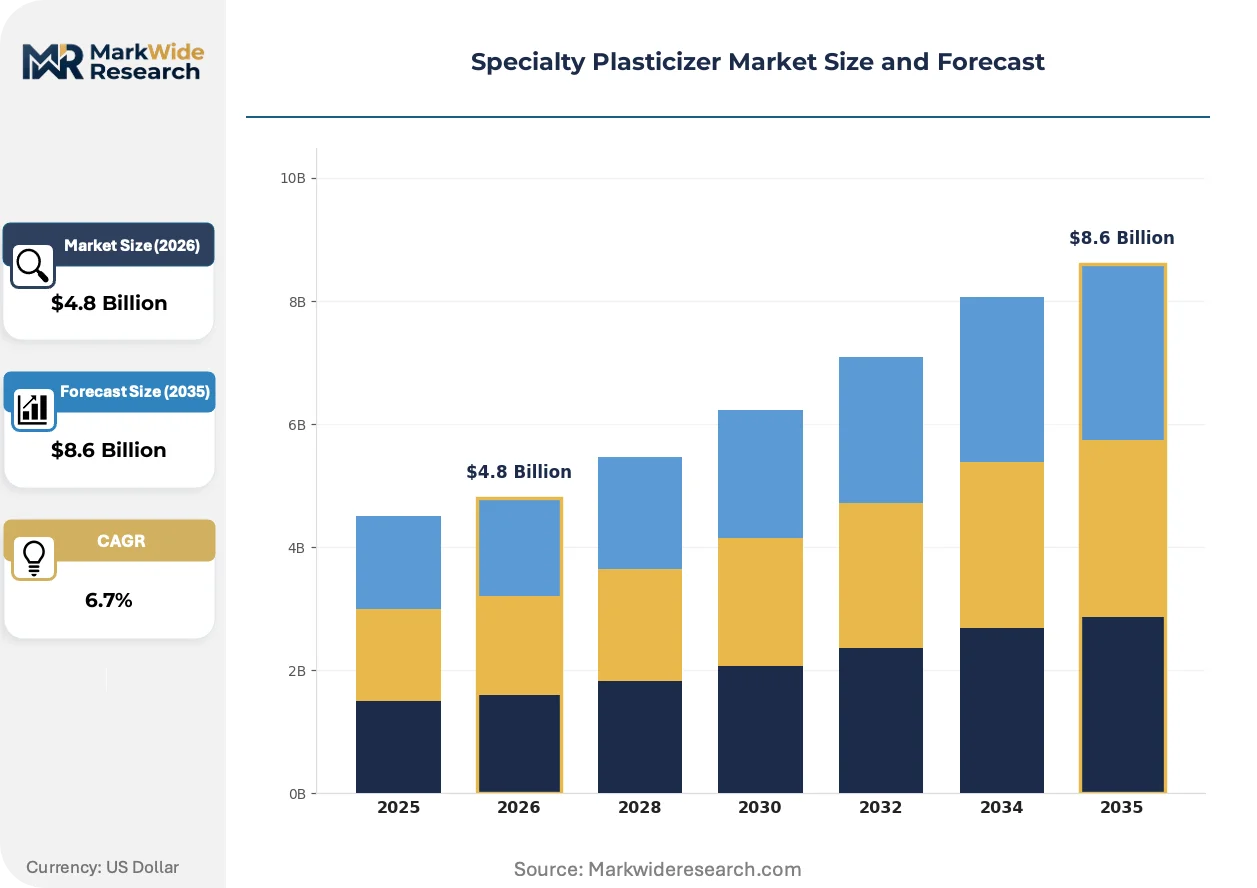
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phthalate-based, Non-Phthalate, Bio-based, Aromatic Application: Automotive, Construction, Medical Devices, Packaging End User: Manufacturers, OEMs, Retailers, Distributors Form: Liquid, Granular, Powder, Paste |
| Companies Covered | Exxon Mobil Corp., Valtris Specialty Chemicals, BASF SE, Aekyung Chemical Co Ltd, LG Chem, Eastman Chemical Co., Ashland Inc., Hallstar Innovations Corp., Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Plasticizer Market Strategic Shifts
Non-phthalate ester chemistries are overtaking legacy formulations as the default specification in regulated applications, while digital formulation tools compress development cycles and bio-based feedstocks gain procurement relevance.
Trimellitate esters are overtaking general-purpose adipates in under-the-hood automotive applications where thermal stability and low volatility determine supplier qualification. German and US automotive OEMs have compressed their substance approval timelines from 18 months to 9 months for these grades. This acceleration is overtaking traditional phthalate incumbents in specification battles where heat-aging performance separates approved from rejected formulations.
ECHA's 2023-2024 updates to REACH authorization and restriction lists are tightening the regulatory noose on medium-chain chlorinated paraffins and certain ortho-phthalate esters used in legacy wire and cable compounds. Compounders serving the EU market face forced reformulation of approximately 15-20% of their product portfolios. Medical device manufacturers are responding fastest, with several German and Irish compounders already completing adipate-to-trimellitate transitions.
Hospital procurement consortiums are consolidating their vendor base around compounders who can demonstrate batch-level extractables documentation and carbon accounting transparency. Traditional distributor relationships are thinning as group purchasing organizations in the US Northeast and Germany's university hospital networks negotiate directly with qualified compounders. This disintermediation is most visible in peristaltic pump tubing and enteral feeding bag supply chains where biocompatibility certification has become the primary selection filter.
Specialty Plasticizer Market Segmentation
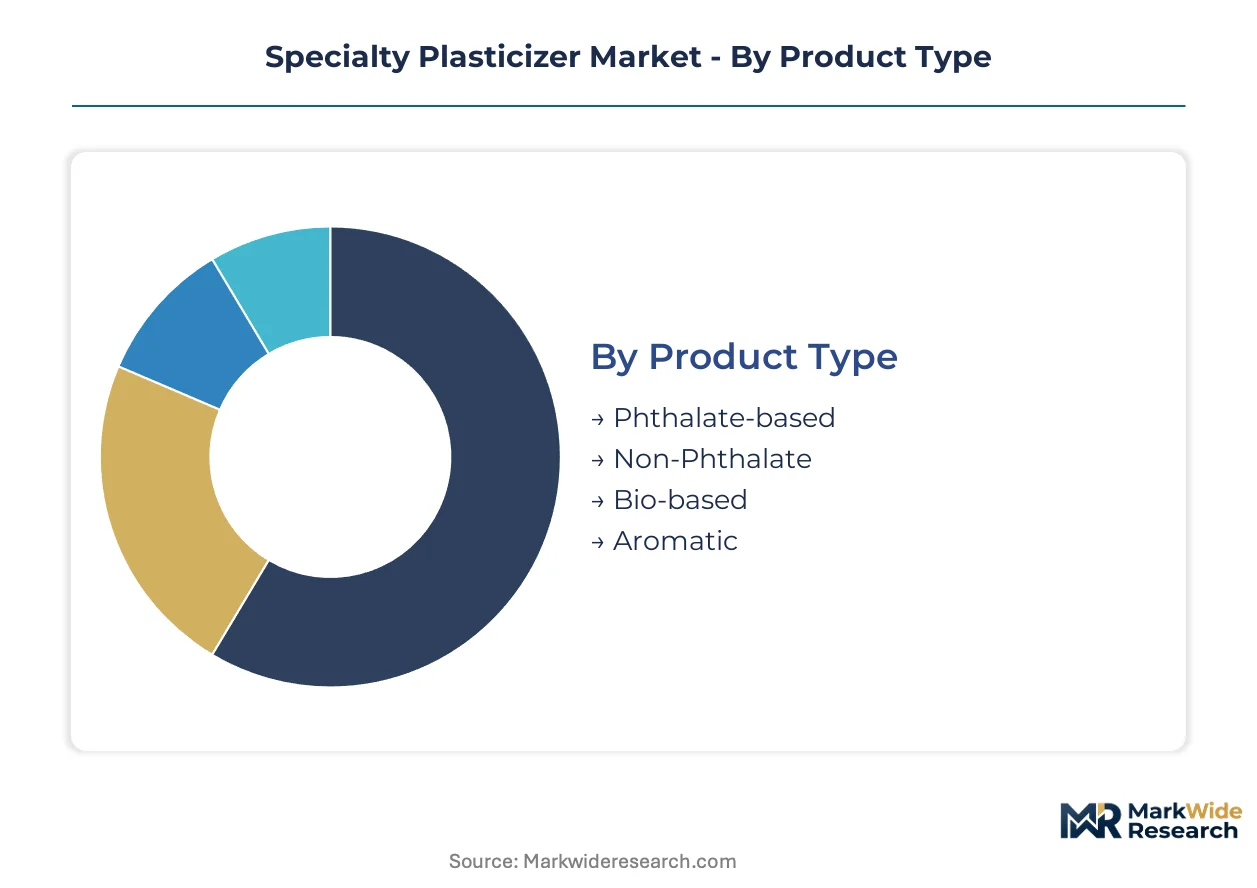
Specialty plasticizer purchasing decisions pivot on regulatory compliance thresholds and performance specifications that vary sharply across end-use verticals. Segmentation reveals how formulation chemistry, physical form, and customer type determine margin capture and supplier qualification pathways in this specification-driven market.
Product Type:
Technology and specification requirements define competitive positioning across chemistry families.
- Non-Phthalate:Adipate and trimellitate esters dominate automotive interior and medical tubing applications where REACH SVHC restrictions and FDA 21 CFR 177.1210 compliance are mandatory. German automotive OEMs and US hospital procurement groups have accelerated their substance list consolidation around these grades, displacing legacy chemistries in specification battles.
- Bio-based:Epoxidized soybean oil and other renewable-content formulations command premium positioning where EU Green Deal procurement thresholds and carbon accounting transparency determine supplier qualification. These grades remain niche in volume but carry strategic importance for compounders serving sustainability-mandated contracts.
- Phthalate-based:DINP and DEHP persist in wire and cable segments where regulatory pressure remains lighter and cost anchoring sustains incumbent positions.
- Aromatic:Specialized grades serve niche applications requiring specific solubility or compatibility profiles in polymer systems.
Non-phthalate formulations lead on scale; bio-based grades lead on momentum.
Application:
End-use performance requirements create divergent specification barriers and qualification timelines.
- Automotive:Under-the-hood applications demand trimellitate esters with thermal stability and low-fogging characteristics for dashboard and sealant formulations. OEM substance restrictions in Germany and the US Midwest manufacturing corridors have compressed approval timelines from 18 months to 9 months for these grades.
- Medical Devices:IV bags, blood bags, and peristaltic pump tubing require batch-level extractables documentation and biocompatibility certification under FDA 21 CFR 177.1210 and EU MDR. Hospital procurement consortiums in the US Northeast and Germany's university hospital networks are consolidating vendor bases around qualified compounders.
- Construction:Flooring and wall covering applications utilize general-purpose adipates where migration resistance and durability specifications are less stringent than automotive or medical tiers.
- Packaging:Food-contact applications face EU 10/2011 and FDA 21 CFR 175.105 compliance requirements that favor high-purity ester alternatives with demonstrated extraction resistance.
Automotive applications lead on scale; medical devices lead on specification intensity.
End User:
Customer type determines channel structure and margin capture potential through the value chain.
- OEMs:Direct qualification channels with tier-one automotive and medical device manufacturers capture margin premiums by bypassing traditional distributor networks. These relationships require extended laboratory validation cycles and concurrent multi-jurisdiction registration maintenance.
- Manufacturers:Compounders serving intermediate processing stages face consolidation pressure as approved vendor lists narrow and procurement centralizes.
- Distributors:Traditional distribution relationships are thinning as group purchasing organizations and hospital networks negotiate directly with qualified suppliers.
- Retailers:Limited role in specialty grades due to specification complexity and technical support requirements.
OEMs lead on margin capture; manufacturers lead on volume throughput.
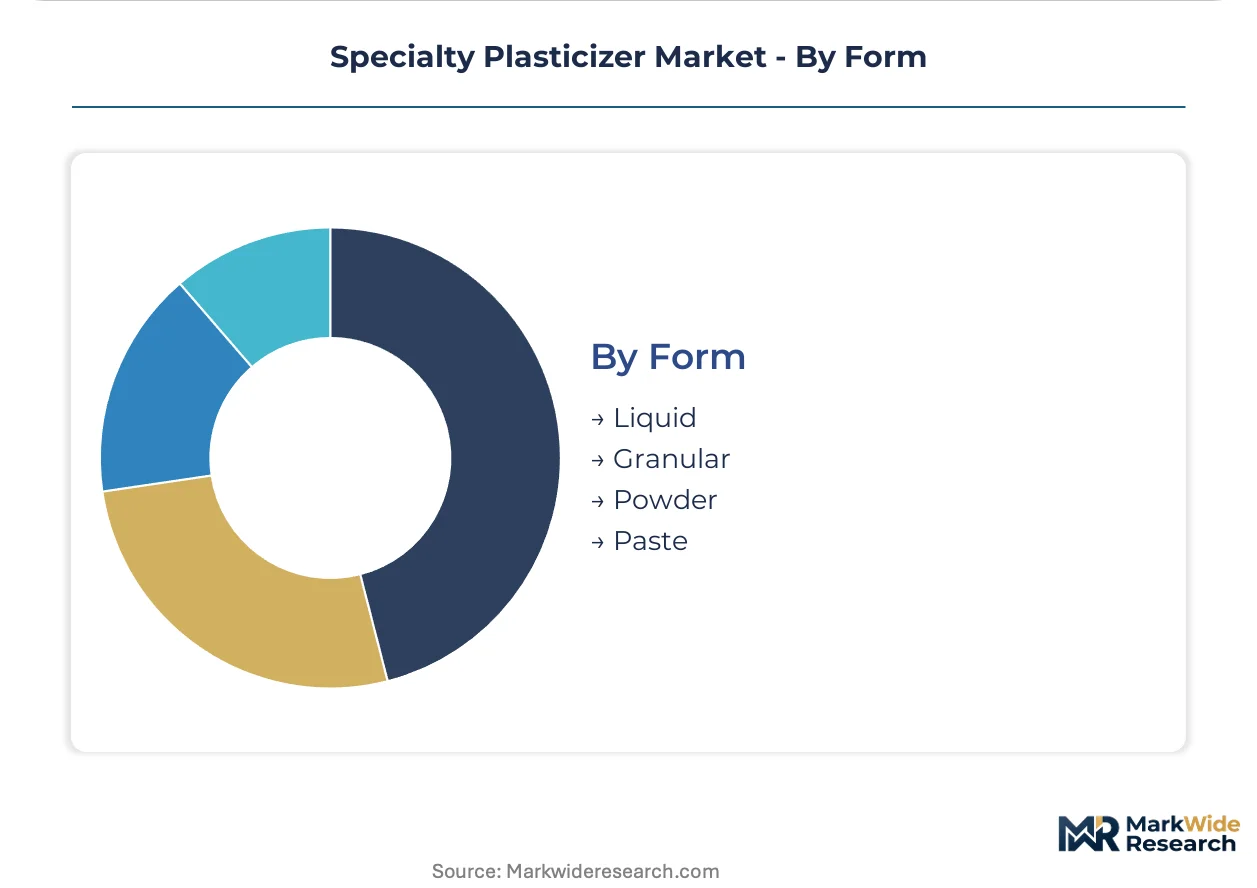
Form:
Physical state determines handling infrastructure compatibility and compounding process integration.
- Liquid:Dominates volume flows through ease of handling in continuous extrusion and injection molding operations. Most adipate and trimellitate esters ship in liquid form for direct integration into PVC compounding lines.
- Paste:Serves specialized calendering operations where controlled viscosity and precise dosing are required for sheet and film production.
- Granular:Supports dry-blend compounding operations where dust control and metering accuracy priorities favor solid-phase handling systems.
- Powder:Niche applications in specific masterbatch and additive concentrate formulations.
Liquid forms lead on scale; paste and granular variants lead on specialized application premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States demonstrate divergent pathways in specialty plasticizer demand, with German automotive OEMs driving rapid specification upgrades while US hospital procurement groups consolidate vendor bases around phthalate-free alternatives.
Germany
Automotive under-the-hood applications and medical device compounding dominate consumption patterns across the country. REACH authorization lists and RoHS substance restrictions from ECHA are compressing reformulation timelines for wire and cable compounders. The Rhine-Ruhr industrial corridor hosts concentrated esterification capacity serving both automotive OEMs in Stuttgart and medical tubing manufacturers in the Frankfurt region.
United States
Medical device tubing for IV bags and peristaltic pump systems commands premium specification requirements from hospital procurement consortiums. FDA 21 CFR 177.1210 compliance mandates are displacing legacy phthalates in blood bag and enteral feeding applications. The US Midwest manufacturing corridor around Ohio and Michigan anchors automotive interior compounding operations serving Detroit-area OEMs.
China
Construction flooring and packaging applications sustain volume demand despite intensifying environmental enforcement. GB standards and MEE regulatory updates are gradually tightening permissible substance lists for food-contact applications. The Yangtze River Delta region around Shanghai concentrates domestic ester production serving both export-oriented manufacturers and domestic construction material processors.
India
Medical device manufacturing expansion under the PLI scheme is creating import windows for high-purity grades meeting CDSCO biocompatibility alignment with ISO 10993. Construction and wire and cable segments retain cost-sensitive demand for general-purpose formulations. Gujarat and Maharashtra industrial zones host emerging compounding operations serving domestic medical device assembly and automotive component manufacturing.
Japan
Automotive electronics and high-durability construction applications sustain demand for low-volatility trimellitate esters. METI chemical substance management frameworks and JIS standards maintain stringent purity thresholds for domestic compounders. The Kansai region around Osaka anchors specialized ester distribution serving precision electronics manufacturers and medical device assemblers.
Specialty Plasticizer Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the specialty plasticizer value chain. The market structure concentrates among integrated petrochemical complexes with captive oxo-alcohol production and merchant esterification specialists serving regional compounding markets. Three archetypes dominate: integrated chemical majors with backward control over feedstock chains, regional esterification specialists with flexible batch capacity, and bio-based feedstock processors leveraging renewable content positioning. Competitive moves center on direct OEM qualification channel development and strategic partnerships with hospital procurement consortiums.
Among integrated chemical majors, BASF SE and Eastman Chemical Co. occupy positions exemplifying scale-driven supply security. BASF SE represents the archetype of integrated oxo-alcohol chain control sustaining cost-advantaged adipate and trimellitate supply. Eastman Chemical Co. anchors North American specialty ester production through its Kingsport manufacturing complex. Valtris Specialty Chemicals sits within the bio-based differentiation tier, with backward integration into epoxidized soybean oil feedstocks supporting renewable-content grade positioning.
| Leading Market Players |
|---|
| Exxon Mobil Corp. |
| Valtris Specialty Chemicals |
| BASF SE |
| Aekyung Chemical Co Ltd |
| LG Chem |
| Eastman Chemical Co. |
| Ashland Inc. |
| Hallstar Innovations Corp. |
| Evonik Industries AG |
| Others |
Value Chain & Pricing Dynamics
Propylene contract price movements on the US Gulf Coast and European petrochemical benchmarks cascade through C8-C13 oxo-alcohol markets into tiered pricing structures for adipate and trimellitate esters. German automotive OEMs and US hospital procurement groups face divergent cost pressures as feedstock volatility intersects with specification premiums for phthalate-free grades.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for general-purpose adipates while specialized trimellitate capacity in Germany and the US Gulf Coast sustains premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates FDA 21 CFR 177.1210-certified medical grades from automotive interior specifications and construction flooring commodities. Cost compression in wire and cable segments intensifies because DINP and DEHP maintain cost anchoring against non-phthalate alternatives. Construction compounders exhibit highest price sensitivity; medical device manufacturers demonstrate lowest sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Reverse-logistics flows for specialty plasticizers remain minimal given the consumable nature of ester compounds and absence of refurbishment economics in polymer additive applications. Geographic supply concentration centers on Germany, the United States, and China where integrated petrochemical complexes and specialized esterification facilities cluster. Raw material dependencies draw from C8-C13 oxo-alcohol feedstocks, epoxidized soybean oil for bio-based grades, and acid precursors including adipic and trimellitic anhydride. Single-source vulnerability concentrates in German oxo-alcohol production serving European automotive and medical compounders. Distribution runs through direct OEM qualification channels for premium grades and regional distributors for standard formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The specialty plasticizer market functions as a stable compounder where regulatory displacement of legacy phthalates generates sustained reformulation demand across automotive and medical verticals.
For Market Incumbents: Anticipate accelerated consolidation among tier-one compounders by securing backward integration into oxo-alcohol feedstocks or captive esterification capacity in the US Gulf Coast and Rhine-Ruhr corridor. ECHA's evolving REACH authorization lists threaten stranded inventory positions for suppliers slow to complete adipate-to-trimellitate transitions. Direct OEM qualification channel development represents the critical defensive lever for margin preservation against distributor disintermediation. For New Entrants and Emerging Players: The premium-to-economy price gap in Indian medical device compounding offers white-space entry under CDSCO's ISO 10993 alignment and PLI scheme incentives. Epoxidized soybean oil convergence with conventional esterification infrastructure enables renewable-content positioning for EU Green Deal procurement thresholds. Target construction flooring segments in Southeast Asia where regulatory pressure remains lighter and cost-sensitive demand sustains import windows for standard adipate grades. For Investors and Strategic Acquirers: Consolidation pressure builds where approved vendor list narrowing concentrates purchasing power among German automotive OEMs and US hospital procurement consortiums. Long-term viability favors integrated producers with captive feedstock positions and multi-jurisdiction registration portfolios. Acquisition target archetype: regional esterification specialists with flexible batch capacity and pending FDA 21 CFR 175.105 compliance certifications. Monitor ECHA SVHC candidate list updates for forced reformulation inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oxo-Alcohol Feedstocks | BASF's integrated chain demonstrates cost-advantaged supply security for adipate and trimellitate esters. |
| Direct OEM Qualification Channel Development | Bypassing distributor networks captures margin premiums with tier-one automotive and medical compounders. |
| Multi-Jurisdiction Registration Synchronization | Concurrent REACH, TSCA, and China MEE compliance prevents stranded inventory from regulatory divergence. |
| Bio-Based Feedstock Processing Convergence | Epoxidized soybean oil integration enables renewable-content grades for EU Green Deal procurement thresholds. |
| Specialized Reactor Asset Expansion | High-purity esterification capacity scarcity in Germany and US Gulf Coast limits competitive supply expansion. |
Study Parameters
Multiple input streams — primary interviews with plant managers and procurement leads at downstream OEMs, technical R&D directors at compounders, and distribution channel partners — were reconciled against secondary validation from customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings. Bottom-up volume modeling across chemistry families, application verticals, and regional production hubs was cross-referenced with top-down macroeconomic indicators to establish market sizing boundaries.
Historical shipment patterns from esterification facilities and import-export flows were cross-referenced against panel input from procurement officers at automotive OEMs and hospital group purchasing organizations. Segmentation dimensions modeled include chemistry family, end-use industry, physical form, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion timelines across the analysis window. Forecast inputs incorporated REACH authorization timelines, FDA 21 CFR compliance transition rates, and OEM substance list consolidation velocities.
Caveats apply where ECHA regulatory acceleration, feedstock price dislocations, or automotive production cycle downturns could materially shift the outlook. Forecasts reflect assumptions about reformulation completion rates and supplier qualification timelines. Practitioners should monitor ECHA SVHC candidate list publications, propylene contract price movements, and hospital procurement consortium vendor consolidation announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global 28-Homobrassinolide Market
Specialty Chemicals
Global Prepacked Chromatography Columns Market
Specialty Chemicals
Marula Oil Market
Specialty Chemicals
Dehazer Market
Specialty Chemicals
Copper Ammonium Carbonate Market
Specialty Chemicals
Automotive Silicone Market
Specialty Chemicals
Diindolylmethane Market
Specialty Chemicals
Organosilicon Electrolyte Market
Specialty Chemicals
Acetum Market
Specialty Chemicals
Petroleum Jelly Market
Specialty Chemicals
Acetyl Isovaleryl Market
Specialty Chemicals
Optical Whitening Agents Market
Specialty Chemicals
Superdisintegrants Market
Specialty Chemicals
Polyether Modified Silicone Market
Specialty Chemicals
Glutathione Market
Specialty Chemicals
Europe Non-Phthalate Plasticizers Market