
 Medical Spa Market | 2026-2036
Medical Spa Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Spa Market Intelligence
The proliferation of franchise operations is reshaping competitive positioning by lowering capital barriers for new entrants. In contrast, destination wellness providers like Canyon Ranch leverage an all-inclusive luxury model. European leaders such as Lanserhof Management GmbH and Clinique La Prairie sustain their market position through a focus on medical-grade diagnostics and long-stay preventative health programs.
A medical spa is a facility providing cosmetic treatments under the supervision of a licensed physician, bridging aesthetic services with clinical oversight. These establishments deliver non-invasive or minimally invasive procedures, such as laser therapy, in a controlled, spa-like environment. Injectables and body contouring services command significant attention due to visible results and high client retention. Dermatology clinics represent a key end-user channel, integrating these aesthetic offerings with traditional medical care.
Regulatory frameworks from bodies like the US FDA, Europe's EMA, and Brazil's ANVISA govern the approval of aesthetic devices and injectable substances. These regulations dictate which procedures can be performed and by whom, directly influencing market access and operational protocols. Stakeholders must navigate the evolving scope-of-practice laws that determine which non-physician practitioners can administer specific treatments.
Market Dynamics
The central force shaping the medical spa market is the convergence of clinical healthcare with consumer-driven wellness. This creates a dynamic tension between the need for medical-grade safety protocols and the demand for accessible, spa-like aesthetic experiences.
Growth Catalysts
- Technology Fusion:The combination of radiofrequency energy with microneedling enhances collagen stimulation and skin tightening, offering superior results that drive adoption in dermatology clinics seeking effective, non-invasive solutions.
- Aesthetic Demand in Brazil:A strong cultural focus on beauty and aesthetic wellness, supported by a clear regulatory pathway from ANVISA, makes Brazil a key driver of demand for procedures like body contouring and injectables.
- Preventative Health Focus:A growing consumer emphasis on preventative and "prejuvenation" treatments, particularly among younger demographics, is expanding the client base for services aimed at maintaining skin health and delaying signs of aging.
Market Restraints
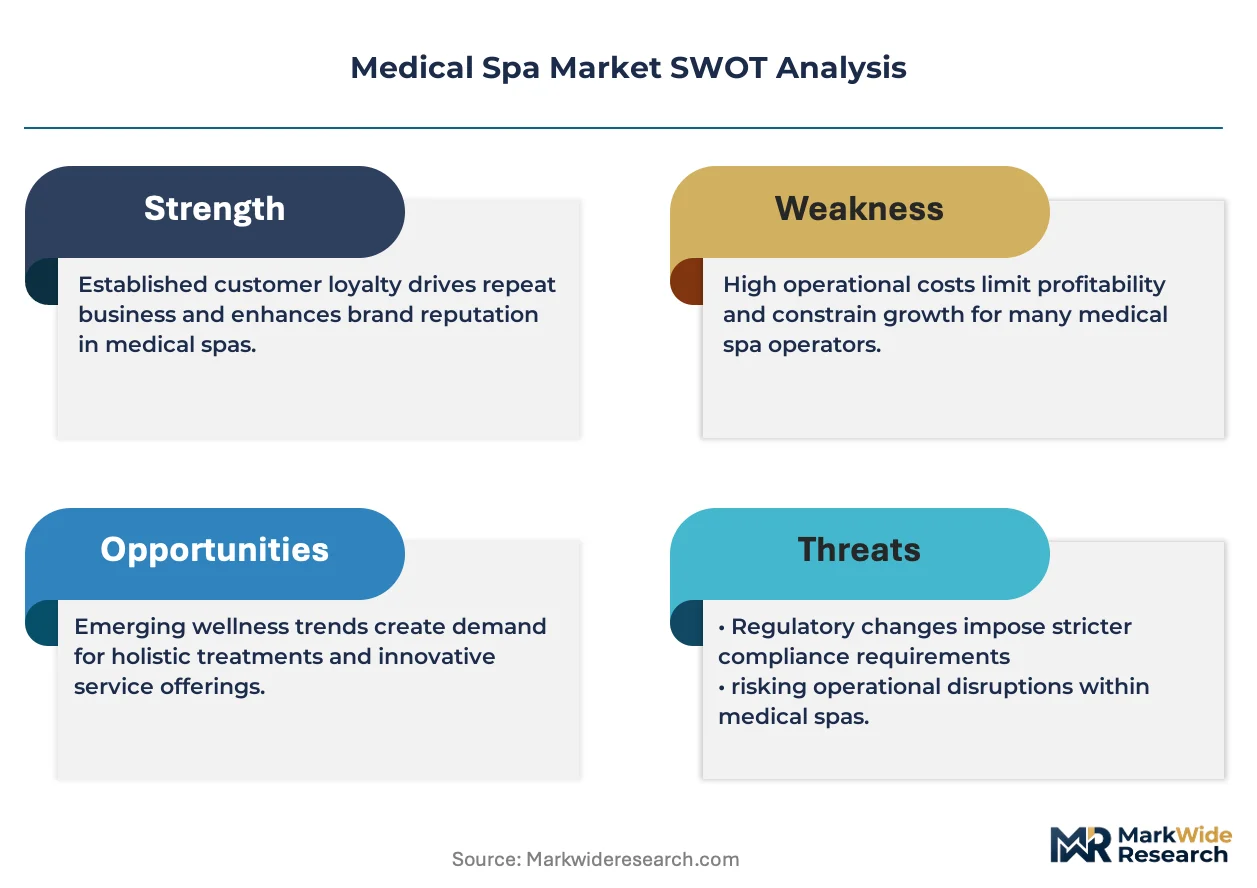
- High Capital Investment:The significant upfront cost of acquiring and maintaining FDA or EMA-approved laser, light, and energy-based devices presents a substantial financial barrier for new entrants and smaller practices.
- Scope-of-Practice Legislation:Strict and inconsistent state-level regulations in the US and national laws elsewhere governing which procedures non-physician practitioners can perform create operational complexity and limit service scalability.
- Consumer Safety Concerns:Reports of adverse events or suboptimal outcomes from improperly administered treatments at less-regulated facilities can generate negative publicity, leading to increased regulatory scrutiny and consumer hesitation.
Strategic Opportunities
- Personalized Treatment AI:Integrating artificial intelligence platforms for skin analysis and treatment planning offers a path to deliver highly customized and effective client regimens, creating a key competitive differentiator.
- Men's Aesthetics Market:The underserved male demographic represents a significant growth vector, with specific opportunities in treatments for hair loss, jawline contouring, and skin texture improvement.
- Wellness Integration:Expanding service menus to include complementary wellness offerings such as IV nutrient therapy, hormone replacement therapy, and medical weight loss programs can attract a wider clientele and increase revenue per client.
Industry Challenges
- Practitioner Skill Gaps:A shortage of nurses, physician assistants, and aestheticians with certified training and hands-on experience with sophisticated aesthetic devices constrains the ability of clinics to expand operations.
- Regulatory Compliance Burden:Navigating the patchwork of regulations for medical device licensing, practitioner oversight, and advertising standards across different jurisdictions requires significant legal and administrative resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Spa Market |
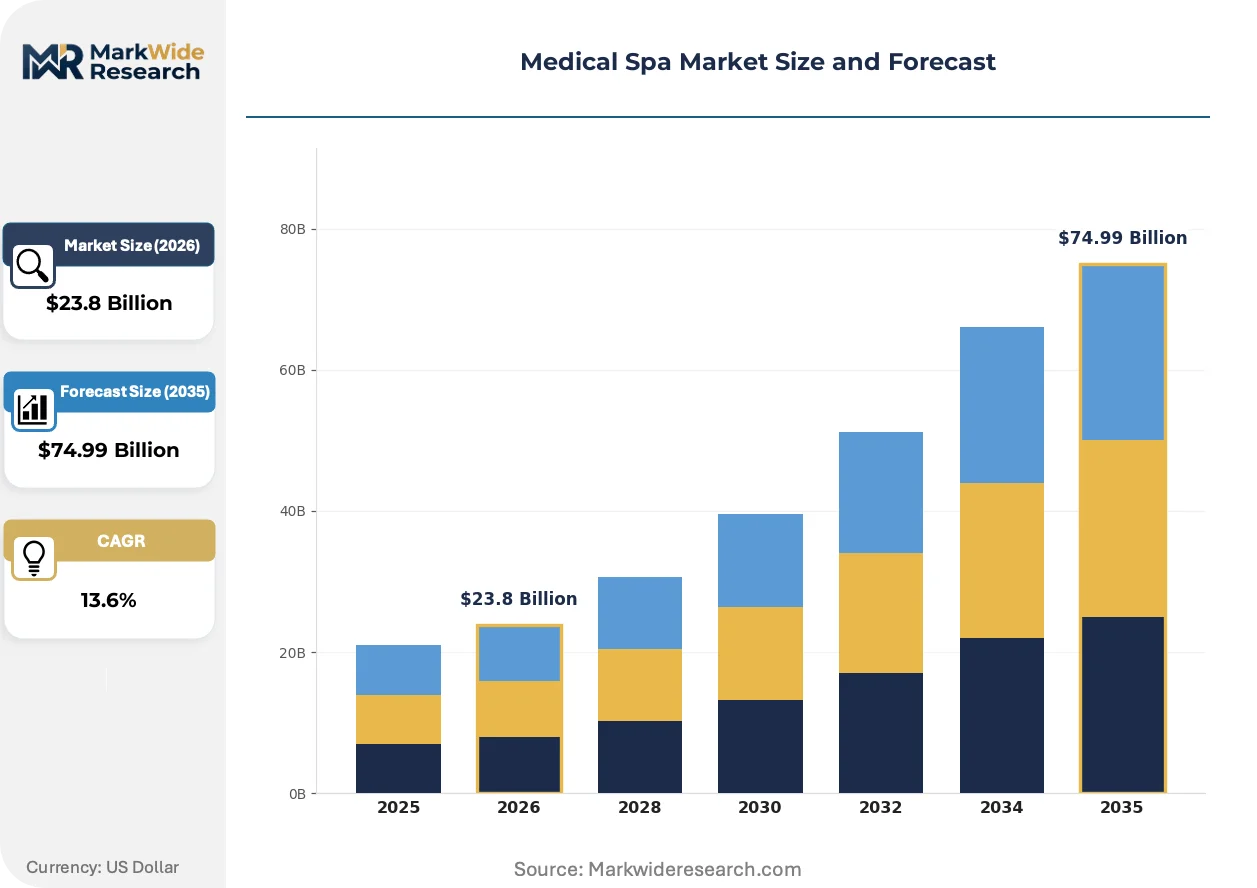
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $74.99 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Laser Therapy, Chemical Peels, Microdermabrasion, Body Contouring, Injectables, Massage Therapy End User: Wellness Centers, Dermatology Clinics, Plastic Surgery Centers, Cosmetic Salons, Rehabilitation Facilities, Fitness Studios Delivery Model: Standalone Clinics, Hospital-Affiliated Services, Mobile Units, Franchise Operations, Boutique Centers, Day Spas Technology: Radiofrequency, Intense Pulsed Light, Ultrasound, Cryotherapy, Microneedling, LED Therapy |
| Companies Covered | Bijoux Medical, Biovital MedSpa LLC, Canyon Ranch, Chic La Vie Med Spa, Cienega Med Spa, Clinique La Prairie, dermani MEDSPA, Innovative MedSpa, Lanserhof Management GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Spa Market Strategic Shifts & Innovations
The market's evolution is defined by a flight to clinical credibility, where data-backed results and personalized care protocols are becoming the primary differentiators. This shift prioritizes medical efficacy over purely experiential luxury, fundamentally altering service delivery and technology adoption.
Non-invasive body contouring technologies, such as cryolipolysis and radiofrequency lipolysis, deliver targeted fat reduction without surgical intervention. Dermatology clinics and high-end medical spas are the primary adopters, integrating these systems to expand their service offerings beyond facial aesthetics. This advanced technology is collapsing the traditional divide between surgical liposuction and topical treatments, creating a new category of body shaping with minimal downtime.
The European Union's Medical Device Regulation (MDR) reclassifies many aesthetic products, including some dermal fillers and energy-based devices, subjecting them to more stringent oversight. This directive mandates enhanced clinical evidence and post-market surveillance for manufacturers to secure or maintain CE marking. Consequently, the injectables and aesthetic device segments face increased compliance costs and longer development timelines to meet these elevated safety and performance standards.
A distinct consumer shift toward preventative aesthetic maintenance is driving the adoption of membership-based business models. This approach is disrupting the conventional pay-per-procedure framework, as clinics increasingly offer monthly subscriptions that bundle a selection of services like facials, laser treatments, or injectables. The model is gaining significant traction in metropolitan areas across the United States, improving client retention and creating more predictable revenue streams for providers.
Medical Spa Market Segmentation
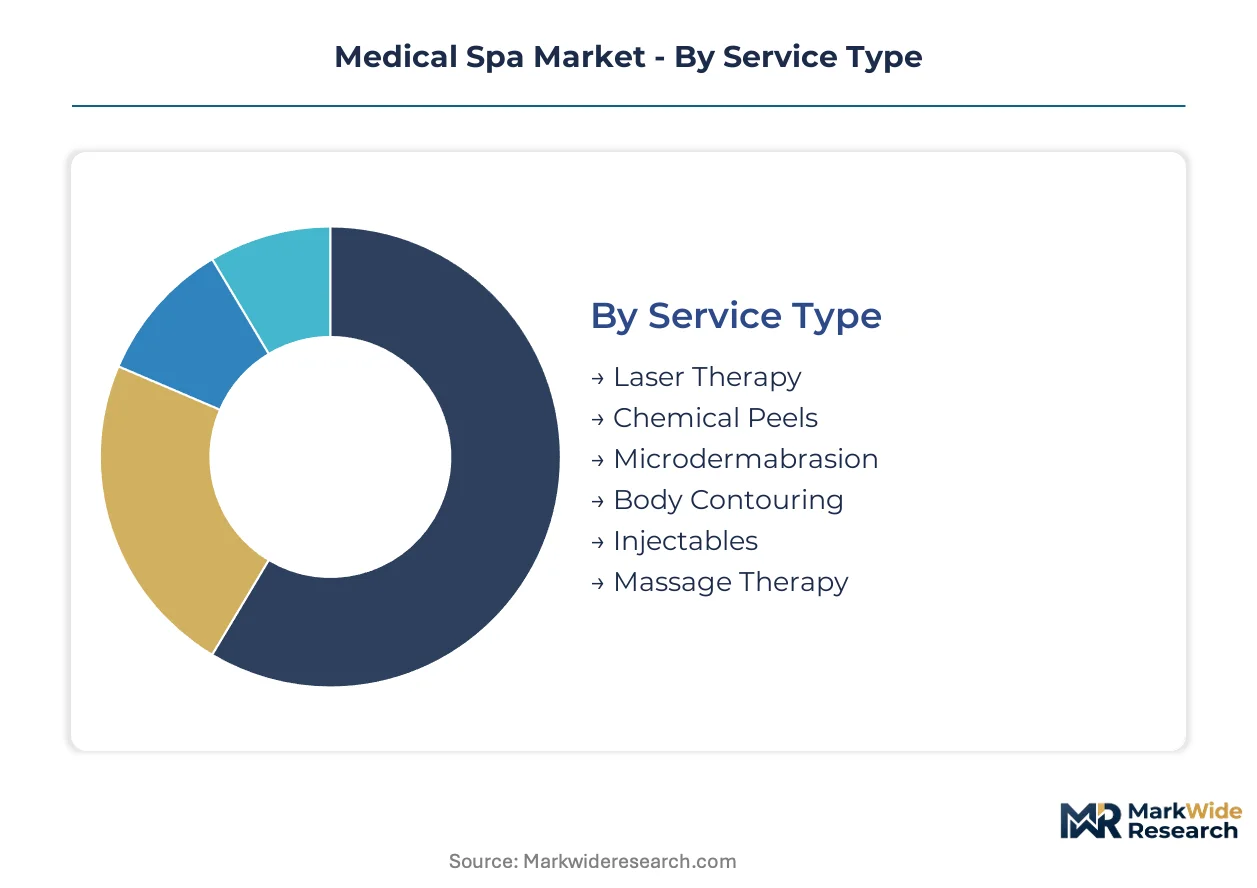
Understanding the segmentation of the medical spa market is crucial for identifying distinct client needs, operational models, and technological applications. This granular analysis helps stakeholders tailor service offerings and investment strategies to specific market niches and growth drivers.
Service Type:
Service types within medical spas exhibit varying client engagement cycles, from frequent, short-term treatments to less frequent, results-driven procedures.
- Laser Therapy:Utilizes focused light energy for diverse treatments including hair removal, skin resurfacing, and pigmentation correction in clinical settings. Demand concentrates in dermatology clinics seeking effective, non-invasive solutions for skin rejuvenation.
- Body Contouring:Employs non-invasive technologies like cryolipolysis and radiofrequency lipolysis for targeted fat reduction without surgical intervention. This service sees significant demand in Brazil, driven by a strong cultural emphasis on aesthetic wellness and visible results.
- Injectables:Involve dermal fillers and neuromodulators administered to reduce wrinkles, restore volume, and enhance facial features.
- Chemical Peels:Apply acidic solutions to exfoliate the skin's outer layers, addressing concerns like acne, fine lines, and uneven tone.
- Microdermabrasion:A mechanical exfoliation method that uses fine crystals or a diamond-tipped wand to gently remove dead skin cells.
- Massage Therapy:Provides relaxation and therapeutic benefits, often integrated as a complementary service within a holistic wellness approach.
Laser Therapy dominates the installed base. Injectables is where expansion concentrates.
End User:
End-user channels define the primary operational environments and client demographics served by medical spa offerings.
- Dermatology Clinics:Integrate aesthetic offerings with traditional medical care, leveraging technologies like radiofrequency with microneedling for enhanced patient outcomes. These clinics are a key channel for non-invasive procedures due to their clinical oversight.
- Plastic Surgery Centers:Leverage medical spa services as non-invasive alternatives or complements to surgical procedures, often offering pre- and post-operative skin care. These centers attract clients seeking both surgical and non-surgical aesthetic enhancements.
- Wellness Centers:Provide a holistic approach, often including medical spa services for preventative health and overall well-being.
- Cosmetic Salons:Expand service menus to include minimally invasive procedures, operating under the supervision of licensed physicians.
- Rehabilitation Facilities:Incorporate aesthetic treatments for scar management, skin texture improvement, or post-operative recovery.
- Fitness Studios:Offer services like body contouring and skin tightening to complement physical training regimens and enhance client results.
Dermatology Clinics represent the largest end-user segment. Plastic Surgery Centers are expanding their service portfolios most rapidly.
Delivery Model:
Delivery models reflect varying capital requirements and operational scales, influencing market accessibility and service specialization.
- Franchise Operations:Lower capital barriers for new entrants, reshaping competitive positioning through standardized offerings and brand recognition. These models attract entrepreneurs seeking established business frameworks.
- Standalone Clinics:Offer a broad range of services under direct physician supervision, representing traditional medical spa operations with independent ownership. These clinics prioritize personalized client experiences.
- Hospital-Affiliated Services:Provide integrated care, often focusing on medical-grade diagnostics and long-stay preventative health programs.
- Mobile Units:Offer flexible, on-demand aesthetic treatments, reaching clients in diverse locations with convenience as a primary driver.
- Boutique Centers:Specialize in personalized, high-end experiences with curated treatment menus and a focus on luxury ambiance.
- Day Spas:Integrate some medical aesthetic services into a traditional spa environment for a broader client base seeking both relaxation and results.
Standalone Clinics maintain a fragmented presence. Franchise Operations are consolidating market reach.
Technology:
Technology types define the treatment modalities and efficacy profiles available, dictating both investment and client outcomes.
- Radiofrequency:Often combined with microneedling, this technology enhances collagen stimulation and skin tightening, offering superior results for various skin concerns. Adoption is expanding in dermatology clinics for effective, non-invasive solutions.
- Microneedling:Creates controlled micro-injuries to stimulate the skin's natural healing process and collagen production, frequently paired with other energy-based devices. This technique is gaining traction for skin texture improvement.
- Intense Pulsed Light:Uses broad-spectrum light for skin rejuvenation, hair removal, and pigmentation correction across various skin types.
- Ultrasound:Employs sound waves for skin tightening and body contouring, targeting deeper tissue layers for non-invasive lifting effects.
- Cryotherapy:Utilizes controlled cooling for localized fat reduction and anti-inflammatory effects in aesthetic applications.
- LED Therapy:Uses specific light wavelengths to promote skin healing, reduce inflammation, and stimulate cellular activity for anti-aging benefits.
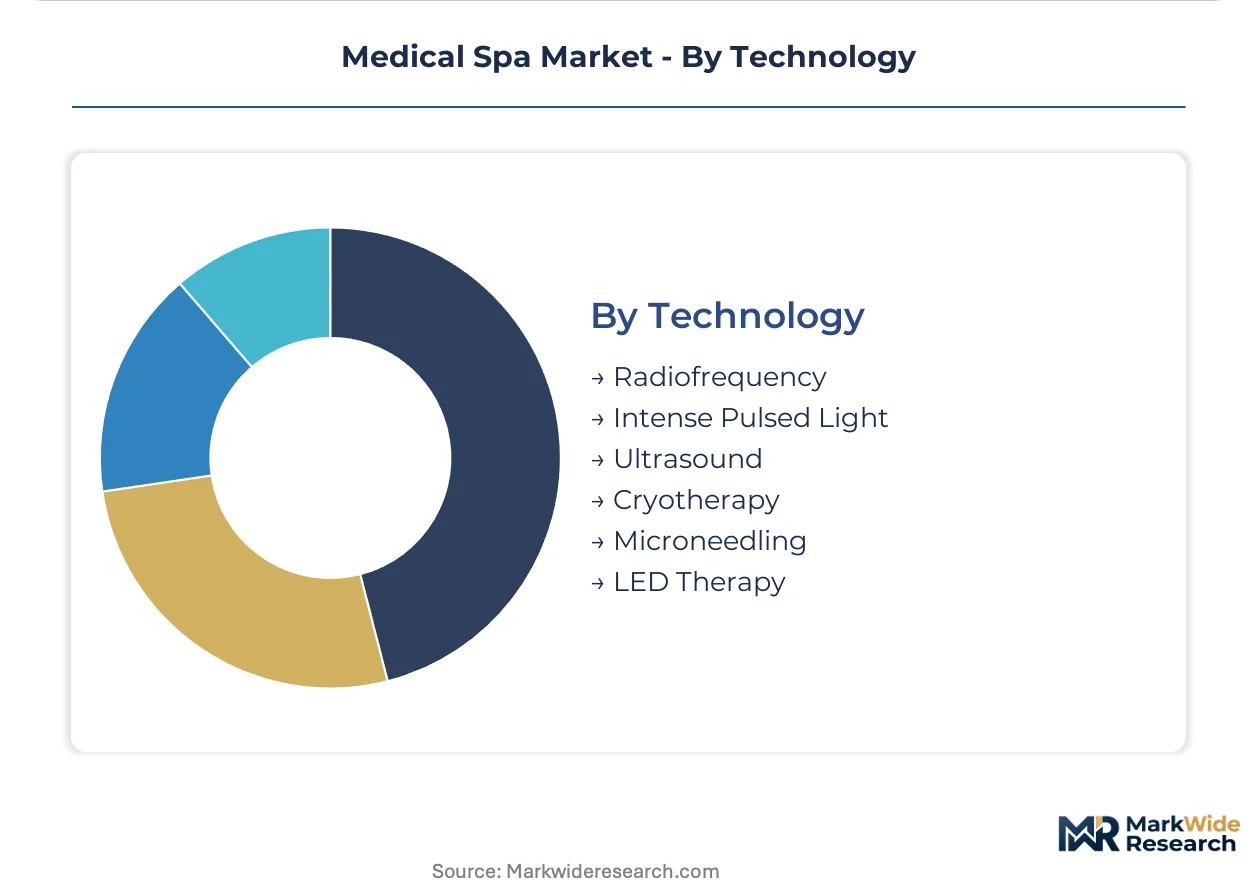
Intense Pulsed Light technologies are widely adopted. Radiofrequency and Microneedling fusion drives current innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the medical spa market exhibits asymmetry, with premium services in the United States commanding higher rates than those observed in Brazil. This disparity reflects differing market maturities and consumer spending capacities. European markets also demonstrate distinct pricing dynamics influenced by local regulatory landscapes.
United States
The United States market sees strong demand for preventative health treatments and personalized aesthetic solutions. FDA regulations strictly oversee laser and energy-based device approvals, ensuring safety. Metropolitan areas like Los Angeles and Miami exhibit significant concentrations of high-end medical spas offering advanced body contouring and injectables.
Brazil
Brazil represents a significant demand concentration, driven by a cultural emphasis on aesthetic wellness and body contouring. ANVISA provides robust regulatory oversight for aesthetic devices and injectable substances, fostering market confidence. Cities like São Paulo and Rio de Janeiro are key centers for advanced body sculpting and laser hair removal treatments.
Germany
German consumers prioritize medical-grade diagnostics and long-stay preventative health programs. The EMA and national health authorities dictate stringent approval processes for aesthetic devices. Clusters around Munich and Berlin are developing specialized clinics focusing on holistic wellness integration and advanced skin rejuvenation.
United Kingdom
The United Kingdom market experiences growth from membership-based business models and demand for 'prejuvenation' treatments. National regulatory bodies refine scope-of-practice laws, affecting practitioner scope. London's urban centers adopt subscription-based aesthetic services, increasing client retention for clinics focusing on injectables.
Japan
Japanese consumers seek advanced anti-aging solutions and sophisticated skin texture improvement procedures. The PMDA ensures strict regulatory compliance for all medical devices and aesthetic injectables. Major urban areas like Tokyo and Osaka host specialized medical spas offering cryolipolysis and radiofrequency microneedling.
Medical Spa Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the medical spa market. This market structure is increasingly tiered, with a blend of fragmented independent operators and consolidating franchise networks. Key strategic archetypes include luxury destination wellness providers, clinically focused medical-grade diagnostic centers, and technology-driven aesthetic clinics. Dominant competitive moves involve portfolio diversification into complementary wellness offerings, geographic expansion through franchise models, and strategic partnerships for technology integration.
Luxury destination wellness providers like Canyon Ranch exemplify the high-end, all-inclusive model, emphasizing holistic experiences and long-term client engagement. European leaders such as Clinique La Prairie sustain their market position through a focus on medical-grade diagnostics and extensive long-stay preventative health programs. In contrast, dermani MEDSPA represents the expanding franchise operations, lowering capital barriers for new entrants and standardizing service delivery across multiple locations while maintaining clinical oversight.
| Leading Market Players |
|---|
| Bijoux Medical |
| Biovital MedSpa LLC |
| Canyon Ranch |
| Chic La Vie Med Spa |
| Cienega Med Spa |
| Clinique La Prairie |
| dermani MEDSPA |
| Innovative MedSpa |
| Lanserhof Management GmbH |
Cost & Logistics Intelligence
Aesthetic device manufacturers, concentrated in North America and Europe, largely dictate pricing power for high-end medical spa services. This upstream concentration significantly influences downstream margin distribution across clinic types.
Pricing Analysis
Configured-to-order pricing for personalized treatment plans commands a premium over standardized, per-procedure rates in the medical spa market, which operates on a hybrid model of per-procedure payments and membership subscriptions. Price differentiation stems from clinical credibility, particularly for advanced laser therapies, and geographic market maturity, with the United States commanding higher rates than Brazil. Pricing pressure arises from stringent regulatory compliance, like the EU MDR, increasing operational costs for device manufacturers. Luxury destination wellness clients exhibit lower price sensitivity, contrasting with consumers of standardized franchise services.
Supply Chain Analysis
Regulatory compliance burden for aesthetic devices and injectables poses a significant supply chain risk, particularly from EU MDR and US FDA regulations. Supply concentration for advanced laser and radiofrequency devices primarily rests with manufacturers in the United States and Europe. The supply chain relies on specialized components for energy-based devices and active pharmaceutical ingredients for injectables. Distribution runs through direct sales channels to dermatology clinics and plastic surgery centers, increasingly utilizing franchise networks for broader market reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Medical Spa Market represents an early-cycle expansion story, poised for substantial growth. This expansion is driven by a strong consumer shift towards preventative and "prejuvenation" treatments, particularly among younger demographics.
For Market Incumbents: Build clinical credibility through certified training programs for practitioners. Acquire smaller, specialized clinics to consolidate market share and mitigate fragmentation. Invest in technology fusion, like radiofrequency with microneedling, to maintain a competitive edge against less regulated facilities. This addresses skill gaps and reinforces safety standards.
For New Entrants and Emerging Players: The underserved male aesthetics market in metropolitan areas presents a significant white-space opportunity. Focus on specific treatments like hair loss and jawline contouring. Leverage personalized treatment AI platforms for customized client regimens, offering a key differentiator. Franchise models provide a penetrable entry point.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across technology-driven aesthetic clinics due to advanced device and compliance costs. This market demonstrates strong long-term viability over the next decade, driven by sustained consumer demand. Target acquisition archetypes include established franchise operations or boutique centers specializing in AI-driven personalized treatments. Monitor evolving scope-of-practice legislation as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Skin Analysis | Integrating artificial intelligence platforms delivers highly customized client regimens, creating a key competitive differentiator. |
| Franchise Network Expansion | Expanding franchise operations lowers capital barriers for new entrants, consolidating market reach and standardizing service delivery. |
| Wellness Service Diversification | Expanding service menus to include IV nutrient therapy attracts wider clientele and increases revenue per client. |
| Certified Practitioner Training | Investing in certified training addresses practitioner skill gaps, ensuring safe and effective administration of sophisticated aesthetic devices. |
| EU MDR Compliance Programs | Proactive compliance with the European Union's Medical Device Regulation ensures market access and sustains product development timelines. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, industry reports, and academic literature. Primary interviews engaged licensed physicians, medical spa clinic owners, aesthetic device manufacturers, and regulatory affairs specialists. This approach integrated insights from both demand-side and supply-side stakeholders. Bottom-up data collection was triangulated with top-down market validation for robust analysis.
Forecast inputs considered historical market performance, evolving regulatory landscapes, and technological advancements across the analysis window. The analytical framework modeled market segmentation by service type, end-user, delivery model, and technology. Compound Annual Growth Rates were derived from a synthesis of historical growth patterns and projected market drivers. Consumer aesthetic demand shifts and non-invasive procedure innovations served as key forecast inputs.
Practitioners should monitor evolving scope-of-practice laws and new regulatory mandates for early signals of market shifts. Forecasts reflect assumptions regarding technological adoption rates and consumer preference stability; significant adverse events or economic downturns could revise these projections. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Surgical Fluid Disposal Market
Healthcare Services
Professional Spa Services Market
Healthcare Services
Assisted Living Market
Healthcare Services
US Acute Hospital Care Market
Healthcare Services
Hair Restoration Services Market
Healthcare Services
US Registered Nurses Market
Healthcare Services
Global Cath Lab Services Market
Healthcare Services
Healthcare Physician Staffing Market
Healthcare Services
Asia-Pacific Healthcare Staffing Market
Healthcare Services
Vaccine Logistics Market
Healthcare Services
Medical Second Opinion Market
Healthcare Services
Contract Manufacturing Organization (CMO) Market
Healthcare Services
Hospital Outsourcing Market
Healthcare Services
Ambulatory Healthcare Service Market
Healthcare Services
Blood Bank Market
Healthcare Services
Patient Throughput and Capacity Management Market