
 Global Perfusion Services Market | 2026-2036
Global Perfusion Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Perfusion Services Market Foresight
Buyer concentration among cardiac surgery centers is shifting as regional hospital networks consolidate perfusion contracts across multiple facilities. Medtronic plc leverages its integrated device-and-service portfolio to anchor long-term agreements with large health systems. LivaNova PLC competes through specialized ECMO perfusion teams that operate across European and North American hospital networks. Terumo Corporation sustains its position by controlling biocompatible tubing supply chains that feed directly into its service operations.
Perfusion services encompass the extracorporeal circulation management of blood flow and oxygenation during cardiac surgery, requiring precise control of pump flow rates typically ranging from 1.5 to 3.0 liters per minute per square meter of body surface area, temperature modulation, and anticoagulation monitoring to maintain patient homeostasis. Intraoperative perfusion commands the largest revenue share due to irreplaceable clinical demand during coronary artery bypass grafting, while extracorporeal life support represents the fastest-expanding segment as hospitals build surge capacity for respiratory failure. Mechanical pumps and oxygenators together form the technology backbone where margin pools concentrate, though monitoring software is gaining share as remote perfusion oversight becomes standard.
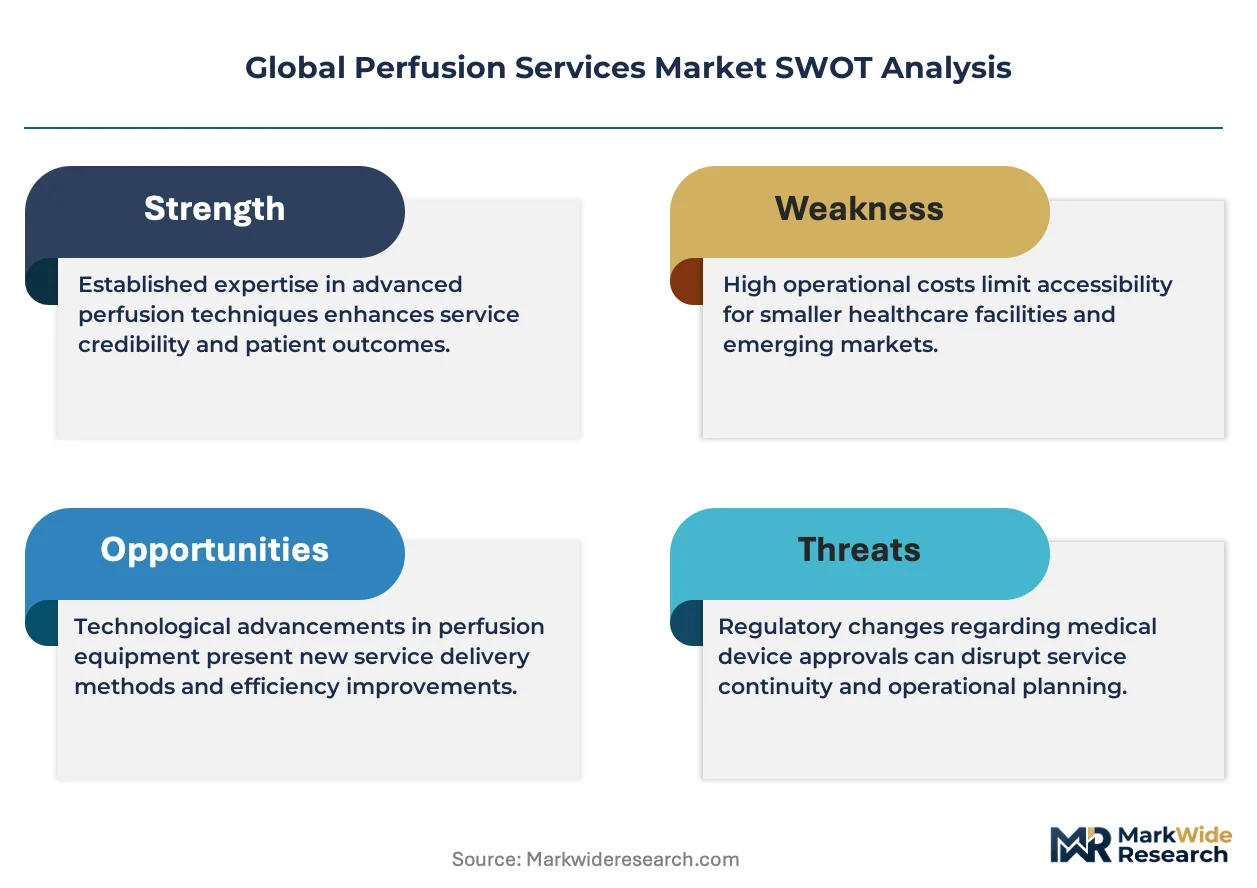
The FDA regulates perfusion devices and associated services under 21 CFR Part 870 cardiovascular device classifications, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence requirements on oxygenators and heat exchangers sold in Europe. Japan's PMDA maintains separate standards for mechanical pump certification that delay market entry for non-domestic service providers. Stakeholders must monitor how divergent regulatory timelines across FDA, EMA, and PMDA jurisdictions reshape the economics of cross-border perfusion service contracts.
Market Dynamics
Hospital consolidation across cardiac networks is compressing vendor relationships, forcing perfusion service providers to restructure contract economics around multi-site coverage rather than single-facility engagements.
Growth Catalysts
- ECMO Surge Capacity Mandates:Post-pandemic respiratory preparedness requirements in the United States are compelling hospitals to maintain outsourced ECMO standby teams they previously deemed non-essential.
- Germany's Cardiac Network Consolidation:University hospital clusters in Bavaria and North Rhine-Westphalia are centralizing perfusion operations, creating economies of scale that favor specialized third-party providers.
- FDA's Evolving Device Guidance:Shifting 21 CFR Part 870 classifications for oxygenators and heat exchangers are increasing compliance burdens that hospitals prefer to transfer to external specialists.
Market Restraints
- Biocompatible Tubing Supply Concentration:Japanese and German polymer suppliers control critical extracorporeal circuit materials, exposing service margins to petrochemical feedstock volatility.
- PMDA Certification Barriers:Japan's distinct mechanical pump approval pathways delay market entry for non-domestic perfusion service providers, fragmenting competitive dynamics.
- Perfusionist Talent Scarcity:Accredited training program output in the United States and Europe fails to match replacement demand from retiring clinical specialists.
Strategic Opportunities
- Remote Perfusion Monitoring Platforms:Cloud-based oversight systems enabling single perfusionists to manage multiple simultaneous procedures across distributed hospital networks.
- India's Private Cardiac Center Expansion:Corporate hospital chains in Mumbai, Delhi, and Chennai are building perfusion capabilities without legacy in-house staffing models.
- EU MDR Clinical Evidence Requirements:Stricter oxygenator documentation mandates are accelerating hospital preference for service providers with embedded regulatory affairs functions.
Industry Challenges
- Anticoagulation Protocol Standardization:Variability in heparin management algorithms across contracting hospitals complicates staff rotation and quality assurance.
- Legacy Pump Interface Integration:Proprietary data protocols from incumbent device manufacturers obstruct seamless connectivity with emerging monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Perfusion Services Market |
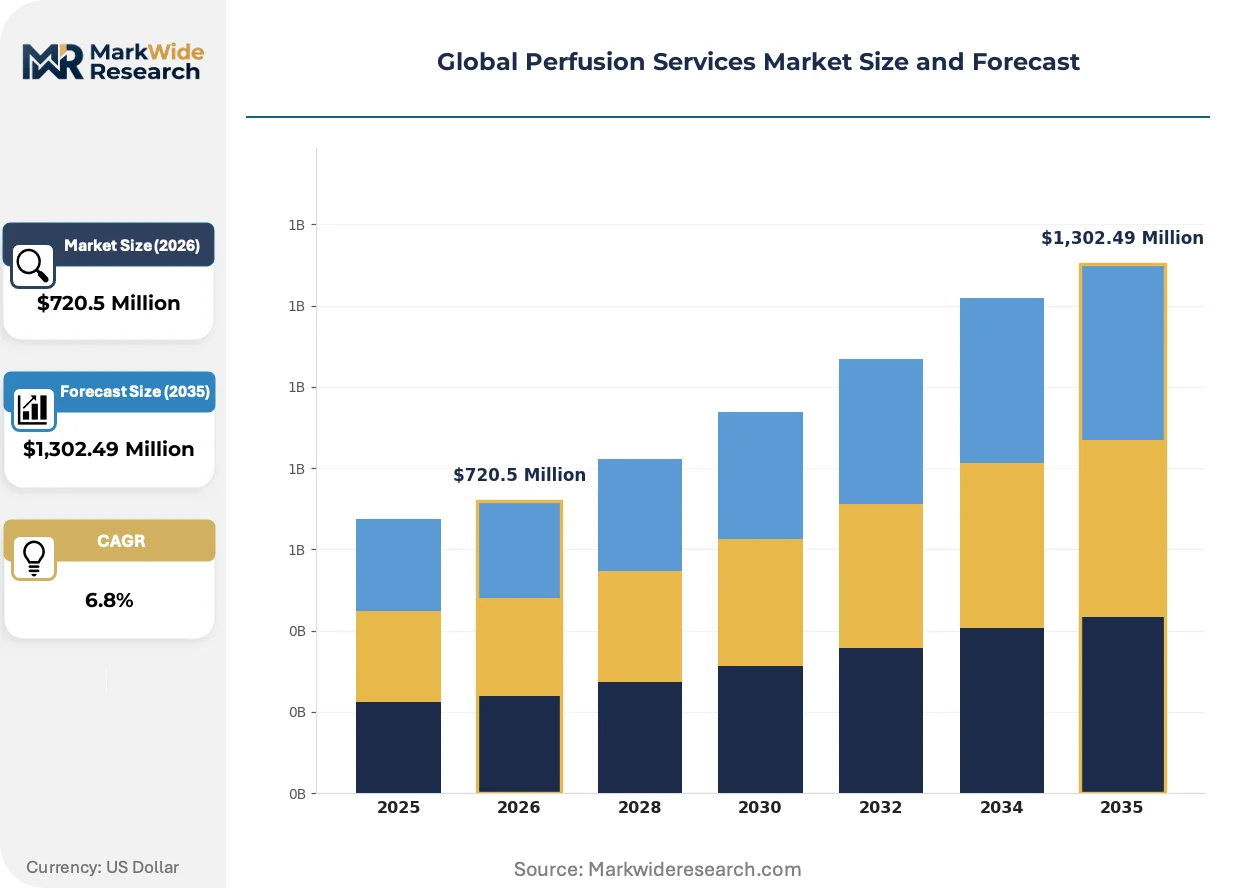
| Market Size in 2026 | $720.5 Million |
| Market Size in 2035 | $1,302.49 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Intraoperative Perfusion, Extracorporeal Life Support, Perfusion Equipment Maintenance, Patient Monitoring, Consulting Application: Cardiopulmonary Bypass, Organ Preservation, Extracorporeal Membrane Oxygenation, Therapeutic Hypothermia, Blood Oxygenation End User: Cardiac Surgery Centers, Organ Transplant Units, Critical Care Facilities, Research Laboratories Technology: Mechanical Pumps, Oxygenators, Heat Exchangers, Monitoring Software, Biocompatible Tubing |
| Companies Covered | Medtronic plc, LivaNova PLC, Terumo Corporation, Nipro Corporation, Getinge AB, Fresenius SE & Co. KGaA, Repligen Corporation, Spectrum Medical, XVIVO Perfusion AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Perfusion Services Market Shifts & Advancements
Telemedicine infrastructure originally deployed for post-operative cardiac care is being repurposed to enable real-time perfusion oversight across geographically dispersed surgical suites.
Teleperfusion platforms utilizing encrypted telemetry streams are decentralizing clinical decision-making during cardiopulmonary bypass. Rural and community hospitals without resident perfusionists are adopting these systems fastest. The technology is decentralizing service delivery economics by collapsing the historical requirement for on-site specialist presence.
EU MDR's tightened clinical evidence thresholds for Class III cardiovascular devices are extending oxygenator recertification timelines. Manufacturers must now submit prospective safety data that previously relied on predicate approvals. Heat exchanger categories face the steepest documentation burdens, prompting some European hospitals to accelerate outsourcing partnerships.
Cardiac surgery centers are unbundling perfusion services from traditional device procurement bundles. Large health systems now negotiate standalone clinical service agreements separate from capital equipment purchases. This separation is most advanced in the United States, where GPOs have created distinct contract categories for extracorporeal life support staffing.
Global Perfusion Services Market Segmentation
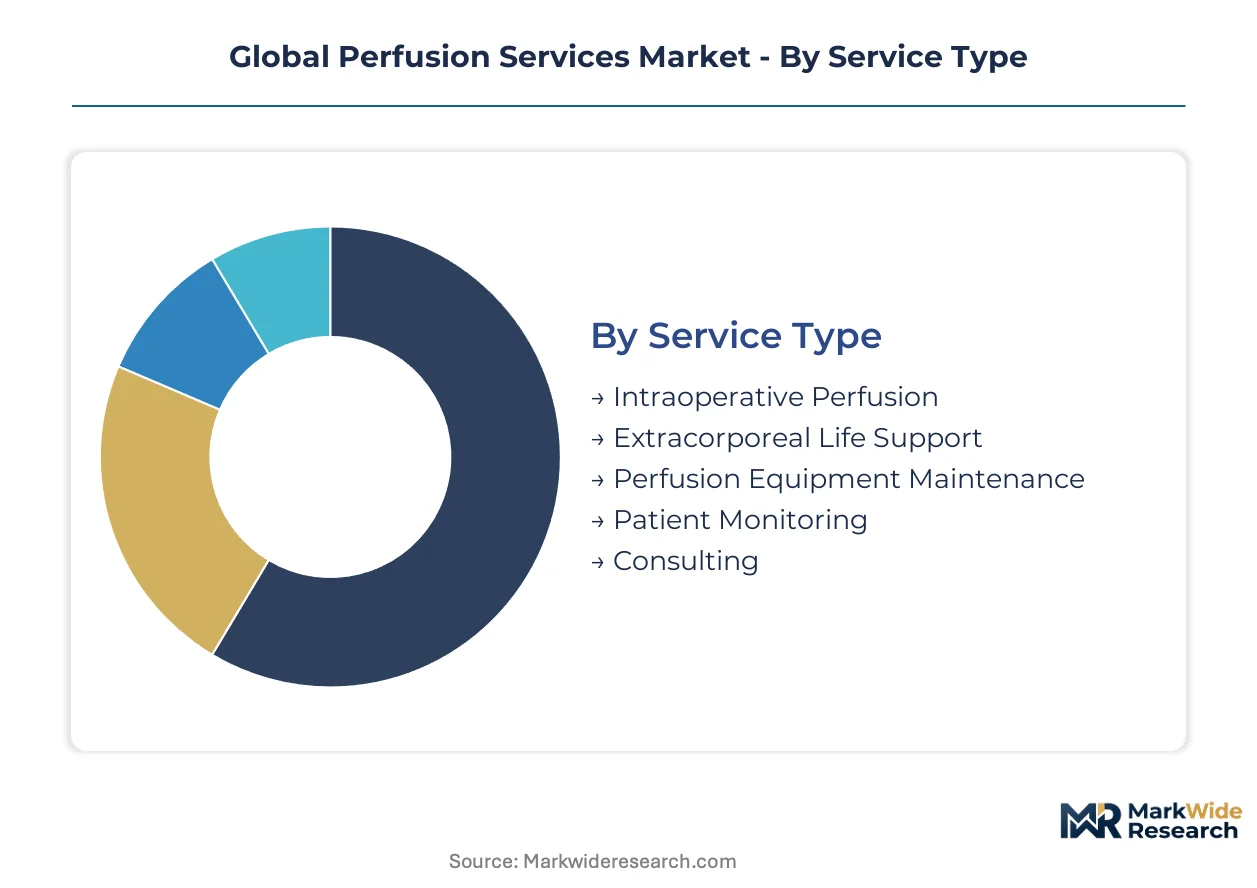
Perfusion services fragment across four distinct taxonomies that govern procurement patterns and vendor specialization. Each dimension carries unique margin structures and regulatory exposure that reshape competitive positioning across cardiac surgery networks.
Service Type:
Supply concentration in specialized clinical labor determines which service lines command premium pricing and long-term contract stability.
- Intraoperative Perfusion:Direct management of cardiopulmonary bypass circuits during open-heart procedures, requiring certified perfusionists to maintain pump flow rates and anticoagulation protocols. Demand clusters at high-volume cardiac surgery centers in the United States and Germany where procedure throughput justifies dedicated on-site teams.
- Extracorporeal Life Support:ECMO deployment for acute respiratory or cardiac failure, involving prolonged extracorporeal circulation management. Hospital networks in Bavaria and North Rhine-Westphalia are consolidating standby ECMO teams across multi-site contracts to satisfy post-pandemic surge mandates.
- Perfusion Equipment Maintenance:Preventive servicing and calibration of mechanical pumps, oxygenators, and heat exchangers.
- Patient Monitoring:Continuous oversight of anticoagulation, temperature modulation, and perfusion parameters.
- Consulting:Regulatory affairs support and workflow optimization for perfusion program establishment.
Intraoperative Perfusion absorbs the bulk of installed capacity; Extracorporeal Life Support is expanding most quickly.
Application:
Clinical application dictates the intensity of regulatory scrutiny and the specialization depth required from service providers.
- Cardiopulmonary Bypass:Temporary replacement of heart and lung function during coronary artery bypass grafting and valve replacement. Centers in the United States leverage this application as the anchor service in bundled perfusion contracts with device manufacturers.
- Extracorporeal Membrane Oxygenation:Prolonged blood oxygenation and carbon dioxide removal for refractory respiratory failure. German university hospitals are centralizing ECMO capabilities across cardiac networks to achieve economies of scale in staffing and equipment utilization.
- Organ Preservation:Hypothermic or normothermic perfusion of donor organs prior to transplantation.
- Therapeutic Hypothermia:Controlled temperature reduction during or after cardiac arrest.
- Blood Oxygenation:Augmentation of oxygen delivery in high-risk surgical patients.
Cardiopulmonary Bypass dominates current service volumes; Extracorporeal Membrane Oxygenation climbs the fastest as respiratory preparedness mandates proliferate.
End User:
Facility type determines whether perfusion services are delivered through embedded teams, outsourced contracts, or hybrid staffing models.
- Cardiac Surgery Centers:Dedicated facilities performing coronary artery bypass grafting, valve repair, and aortic procedures. These centers in the United States are unbundling perfusion services from device procurement bundles to negotiate standalone clinical agreements.
- Organ Transplant Units:Specialized departments managing donor organ perfusion and recipient support during transplantation.
- Critical Care Facilities:Intensive care units deploying ECMO for acute respiratory or circulatory failure.
- Research Laboratories:Preclinical and clinical trial settings investigating novel perfusion protocols and devices.
Cardiac Surgery Centers anchor the installed base; Critical Care Facilities are gaining share fastest as ECMO indications broaden.
Technology:
Technology segmentation reveals where supply chain control and regulatory compliance burdens concentrate competitive advantage.
- Mechanical Pumps:Centrifugal and roller pumps generating controlled blood flow through extracorporeal circuits. Japanese polymer suppliers dominate biocompatible tubing feedstocks that integrate with these systems, exposing service margins to petrochemical volatility.
- Oxygenators:Membrane and bubble oxygenators enabling gas exchange outside the body. EU MDR's tightened clinical evidence requirements for Class III devices are extending recertification timelines and accelerating hospital preference for outsourced regulatory management.
- Heat Exchangers:Temperature modulation devices for hypothermic perfusion protocols.
- Monitoring Software:Cloud-based platforms enabling remote perfusion oversight across distributed surgical suites.
- Biocompatible Tubing:Polymer conduits for blood transport, controlled by Japanese and German material suppliers.
Mechanical Pumps and Oxygenators together command the largest technology spend; Monitoring Software is expanding most quickly as teleperfusion platforms decentralize service delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese and German polymer suppliers anchor the biocompatible tubing feedstock chain that feeds perfusion circuit manufacturing, while cardiac surgery demand concentrates in North American and European hospital networks.
United States
Cardiac surgery centers in the United States are expanding perfusion service contracts as open-heart procedure volumes rebound from pandemic-era lows. The FDA's evolving guidance on extracorporeal membrane oxygenation devices under 21 CFR Part 870 is prompting hospitals to outsource specialized perfusion expertise rather than maintain full in-house teams. Regional hospital networks in the Southeast and Midwest are consolidating perfusion contracts across multi-site cardiac networks.
Germany
University hospital clusters in Bavaria and North Rhine-Westphalia are centralizing perfusion operations across cardiac networks to achieve economies of scale in staffing and equipment utilization. The EU Medical Device Regulation imposes stricter clinical evidence requirements on oxygenators and heat exchangers sold in Europe, extending recertification timelines. Berlin and Hamburg are emerging as coordination hubs for outsourced perfusion management across multi-site contracts.
Japan
Domestic polymer suppliers control critical biocompatible tubing materials that integrate with mechanical pump systems, exposing service margins to petrochemical feedstock volatility. The Pharmaceuticals and Medical Devices Agency maintains separate standards for mechanical pump certification that delay market entry for non-domestic service providers. Tokyo and Osaka anchor the domestic perfusion device manufacturing base while constraining foreign service provider penetration.
India
Corporate hospital chains in Mumbai, Delhi, and Chennai are building perfusion capabilities without legacy in-house staffing models, creating greenfield opportunities for specialized service providers. The Central Drugs Standard Control Organization regulates cardiovascular devices under the Medical Device Rules, with recent amendments streamlining import pathways for critical care equipment. Karnataka and Telangana are attracting perfusion service contracts as private cardiac center expansion accelerates in Bangalore and Hyderabad.
United Kingdom
NHS cardiac networks are evaluating outsourced perfusion models to address perfusionist talent scarcity and reduce fixed staffing costs across regional surgery centers. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR transition timelines for oxygenator recertification, though post-Brexit divergence creates compliance complexity. London and the Southeast concentrate private cardiac surgery volume where standalone perfusion service agreements are gaining traction.
Global Perfusion Services Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue remote monitoring platforms and regulatory affairs specialization. The market structures around three distinct tiers: integrated device-and-service conglomerates, specialized ECMO staffing firms, and regional equipment maintenance providers. Consolidation pressure from hospital network procurement is compressing vendor relationships toward multi-site coverage models. Dominant competitive moves include backward integration into biocompatible material supply chains and technology licensing for teleperfusion platforms.
Within the integrated tier, Medtronic plc and LivaNova PLC exemplify device-and-service bundling strategies that anchor long-term agreements with large health systems. Terumo Corporation occupies a position tied to polymer supply chain control, while Nipro Corporation and Getinge AB sit within the specialized equipment and maintenance archetype. Fresenius SE & Co. KGaA represents the diversified healthcare conglomerate model with perfusion services embedded within broader critical care portfolios.
| Leading Market Players |
|---|
| Medtronic plc |
| LivaNova PLC |
| Terumo Corporation |
| Nipro Corporation |
| Getinge AB |
| Fresenius SE & Co. KGaA |
| Repligen Corporation |
| Spectrum Medical |
| XVIVO Perfusion AB |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up perfusion specialists have consolidated regional service contracts across United States cardiac networks, tightening pricing discipline through captive labor pools while simultaneously locking in multi-year polymer supply agreements with Japanese tubing manufacturers. This ownership concentration creates asymmetric bargaining power against hospital GPOs, embedding cost-plus escalation clauses that insulate margins from raw material volatility.
Pricing Analysis
High-volume intraoperative contracts sacrifice margin for fleet utilization, while ECMO standby agreements capture premium pricing through scarcity of certified specialists. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and geographic coverage radius. Pricing pressure stems from hospital consolidation forcing volume discounts across multi-site networks. Community cardiac centers exhibit highest price sensitivity due to constrained capital budgets; academic medical centers prioritize outcome guarantees over unit cost.
Supply Chain Analysis
Direct-to-hospital contracting dominates hyperscale health system demand, bypassing traditional device distributor markups. Manufacturing concentrates in Japan, Germany, and United States for mechanical pumps, oxygenators, and biocompatible tubing respectively. Supply chains draw from specialized polymer feedstocks, precision-machined pump housings, and membrane oxygenator components. Single-source vulnerability in Japanese polymer suppliers exposes service margins to petrochemical price swings. Distribution runs through integrated device-and-service providers with captive installation and maintenance teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Perfusionist talent scarcity functions as the binding capacity constraint, propping pricing power for service providers with accredited training pipelines and retention infrastructure.
For Market Incumbents: Deepen backward integration into biocompatible tubing supply chains to neutralize Japanese polymer supplier leverage and secure margin stability. Lock in exclusive perfusionist training partnerships with university programs to defend against emerging remote-monitoring entrants poaching clinical labor. Prioritize multi-site contract consolidation before hospital GPOs complete vendor reduction programs. For New Entrants and Emerging Players: Rural community hospitals without resident perfusionists represent the most penetrable buyer archetype for teleperfusion platform deployment. India's corporate cardiac center expansion offers greenfield contracting opportunities unencumbered by legacy in-house staffing models. Lead with regulatory affairs outsourcing as the wedge value proposition to capture EU MDR compliance burden relief. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized ECMO staffing firms in Germany facing temporary margin compression from network consolidation delays. Long-term viability hinges on teleperfusion technology adoption curves displacing on-site specialist requirements. Monitor FDA oxygenator reclassification timelines as the inflection signal for outsourced service demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Teleperfusion Platform Deployment | Cloud-based oversight collapses on-site specialist requirements across distributed rural cardiac networks. |
| Perfusionist Training Pipeline Investment | Accredited program partnerships create captive labor supply insulating against industry-wide talent scarcity. |
| EU MDR Regulatory Affairs Outsourcing | Embedded compliance functions capture oxygenator recertification burden from resource-constrained hospitals. |
| Biocompatible Tubing Supply Integration | Upstream polymer control neutralizes Japanese supplier concentration risk and stabilizes service margins. |
| Multi-Site Contract Consolidation | Regional health system bundling achieves economies of scale in staffing and equipment utilization. |
Research Methodology
FDA 510(k) filings, EU MDR technical documentation databases, and hospital GPO contract registries formed the secondary backbone for device approval timelines and procurement pattern analysis. Primary interviews with perfusionist clinical directors, hospital purchasing committee members, biomedical engineering managers, and cardiovascular service line executives validated demand assumptions and pricing dynamics. Bottom-up service volume estimates triangulated against top-down health system expenditure data.
Bottom-up modeling of procedure volumes by cardiac surgery center and application type anchored the analytical framework across the analysis window. Segmentation dimensions included service type, clinical application, end-user facility category, and technology platform. CAGRs derived from regression analysis of historical contract value growth and forward-looking hospital capacity expansion plans. Forecast inputs incorporated perfusionist training program output projections and ECMO surge mandate compliance requirements.
Revisions become necessary when FDA device reclassification timelines accelerate, EU MDR enforcement intensity shifts, or teleperfusion reimbursement codes achieve widespread adoption. Forecasts reflect assumptions about hospital outsourcing preference evolution and polymer supply chain stability. Periodic stress-testing of base assumptions against perfusionist retirement rates and training program enrollment trends is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Healthcare Physician Staffing Market
Healthcare Services
Medical Transcription Services Market
Healthcare Services
Vaccine Logistics Market
Healthcare Services
United States Senior Living Market
Healthcare Services
In-Home Senior Care Franchises Market
Healthcare Services
Blood Bank Market
Healthcare Services
Hospital Workforce Management Market
Healthcare Services
Outpatient Clinics Market
Healthcare Services
US Retail Clinics Market
Healthcare Services
Global Healthcare Services Market
Healthcare Services
Australia Senior Living Market
Healthcare Services
Global Sperm Bank Market
Healthcare Services
Healthcare Patent Filing Outsourcing Market
Healthcare Services
United States Pharmaceutical Logistic Services Market
Healthcare Services
UK Ambulatory Services Market
Healthcare Services
Medical Waste Disposal Services Market