
 India Senior Living Market | 2026-2036
India Senior Living Market Size, Share, and Industry Trends Forecast 2026-2036
India Senior Living Market Foresight
The National Policy for Senior Citizens is hardening compliance requirements for eldercare infrastructure across Indian states. Antara Senior Care leverages its Max Group hospital network to sustain clinical credibility in assisted living operations. Ashiana Housing Ltd anchors the mid-market segment through standardized designs optimized for Tier-2 city replication. Columbia Pacific Communities differentiates via American operational protocols adapted to Indian family visitation norms.
India senior living encompasses purpose-built residential environments engineered for accessibility, emergency response systems, and continuum-of-care transitions from independent to skilled nursing support. Facilities integrate anti-slip flooring, 24/7 paramedic staffing, and centralized health monitoring to reduce fall-related hospitalization risk for residents aged sixty and above. Independent Living dominates current inventory supply while Memory Care captures the fastest expansion trajectory as dementia prevalence rises among India's aging upper-middle class. Rehabilitation Services within the service model dimension concentrate margin pools through recurring physiotherapy and post-surgical recovery contracts.
BIS building codes for elderly-friendly design, CDSCO medical device clearance for in-facility diagnostic equipment, and state-level RERA registration mandates collectively shape developer entry barriers and operational licensing timelines. The CEA electrical safety standards enforce backup power specifications that inflate capital costs but reduce operational liability exposure. Stakeholders must monitor evolving state-level eldercare subsidies and municipal zoning relaxions that could redraw location economics for greenfield projects.
Market Dynamics
India's PLI scheme for healthcare infrastructure is accelerating capital deployment into eldercare assets, concentrating development in Maharashtra's Pune-Mumbai corridor where premium integrated retirement communities now command waitlists exceeding twelve months.
Growth Catalysts
- Affluent urban retirees:India's aging upper-middle class is driving demand for purpose-built residential environments with continuum-of-care transitions from independent to skilled nursing support.
- BIS building codes:Mandatory elderly-friendly design standards are professionalizing developer capabilities and raising entry barriers for substandard operators.
- Memory Care services:Dementia prevalence among India's wealthy elderly is accelerating specialized facility construction beyond traditional independent living inventory.
Market Restraints
- CEA electrical safety standards:Backup power specifications inflate capital costs for greenfield projects while reducing operational liability exposure.
- CDSCO medical device clearance:Diagnostic equipment licensing timelines delay in-facility health monitoring deployment.
- State-level RERA registration:Municipal zoning restrictions and multi-layered approvals extend project commissioning cycles in Tier-1 cities.
Strategic Opportunities
- Tier-2 city replication:Standardized mid-market designs optimized for cities like Jaipur, Coimbatore, and Chandigarh remain underpenetrated relative to metropolitan saturation.
- Rehabilitation Services:Post-surgical recovery and physiotherapy contracts offer recurring revenue pools within integrated care models.
- State-level eldercare subsidies:Evolving municipal zoning relaxations could redraw location economics for greenfield developments in Gujarat and Karnataka.
Industry Challenges
- Paramedic staffing scarcity:24/7 clinical staffing requirements exceed trained healthcare worker availability in secondary cities.
- Family visitation norm integration:American operational protocols require adaptation to Indian multi-generational household expectations, complicating service design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Senior Living Market |
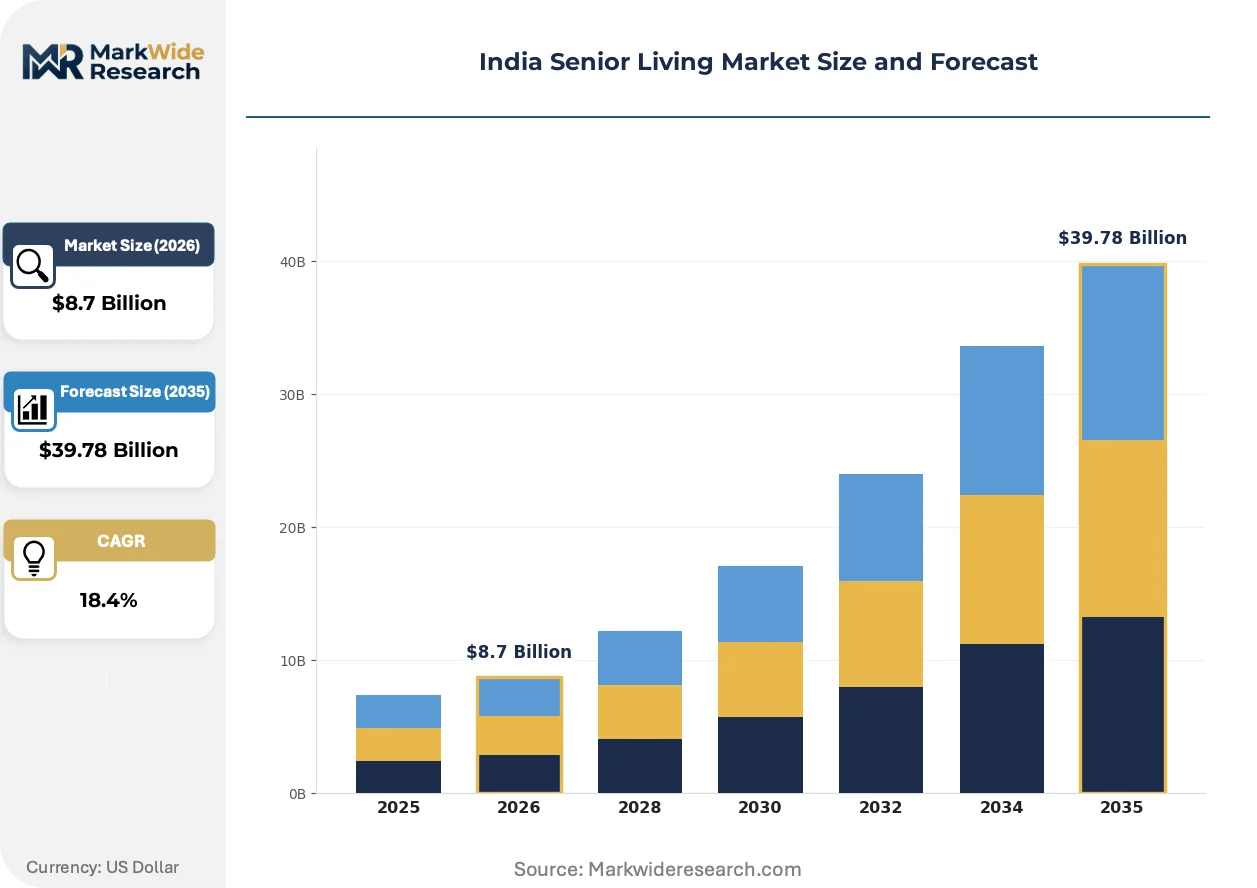
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Independent Living, Assisted Living, Memory Care, Nursing Homes Service Model: Residential Care, Day Care, Home Care, Rehabilitation Services Facility Type: Senior Apartments, Continuing Care Retirement Communities, Group Homes, Co-housing Customer Type: Active Seniors, Individuals with Disabilities, Families of Seniors, Caregivers |
| Companies Covered | Athulya Senior Care, Covai Property Centre (I) Pvt Ltd, Antara Senior Care, Godrej Properties Godrej Seasons Senior Living, Vedaanta Retirement Communities, Columbia Pacific Communities, Primus Lifespaces Pvt Ltd, Gracias Living, Ashiana Housing Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Senior Living Market Shifts & Advancements
Technology convergence with clinical care protocols is reshaping facility operations, while regulatory compliance hardens and buyer preferences fragment across service tiers.
Centralized health monitoring systems integrating fall-detection sensors and emergency response protocols are expanding into premium and mid-market facilities simultaneously. Antara Senior Care and Columbia Pacific Communities are deploying these platforms to reduce hospitalization risk for residents aged sixty and above. Real-time biometric tracking is expanding into family communication applications, compressing information asymmetry between distant children and facility operators.
BIS elderly-friendly design mandates now enforce anti-slip flooring specifications, grab-bar placement standards, and wheelchair-accessible corridor widths across all new construction. CDSCO clearance requirements for in-facility diagnostic equipment are extending licensing timelines but improving clinical credibility. Developers in Maharashtra and Karnataka are responding by pre-approving equipment suites during project planning phases.
Children of NRI parents are consolidating purchase decisions through virtual facility tours and digital contract execution rather than traditional site visits. This channel shift is compressing sales cycles for premium operators while raising digital marketing expenditure requirements. The Pune-Mumbai corridor exhibits the highest concentration of remote buyers, followed by Bengaluru's Whitefield and Electronic City clusters.
India Senior Living Market Segmentation
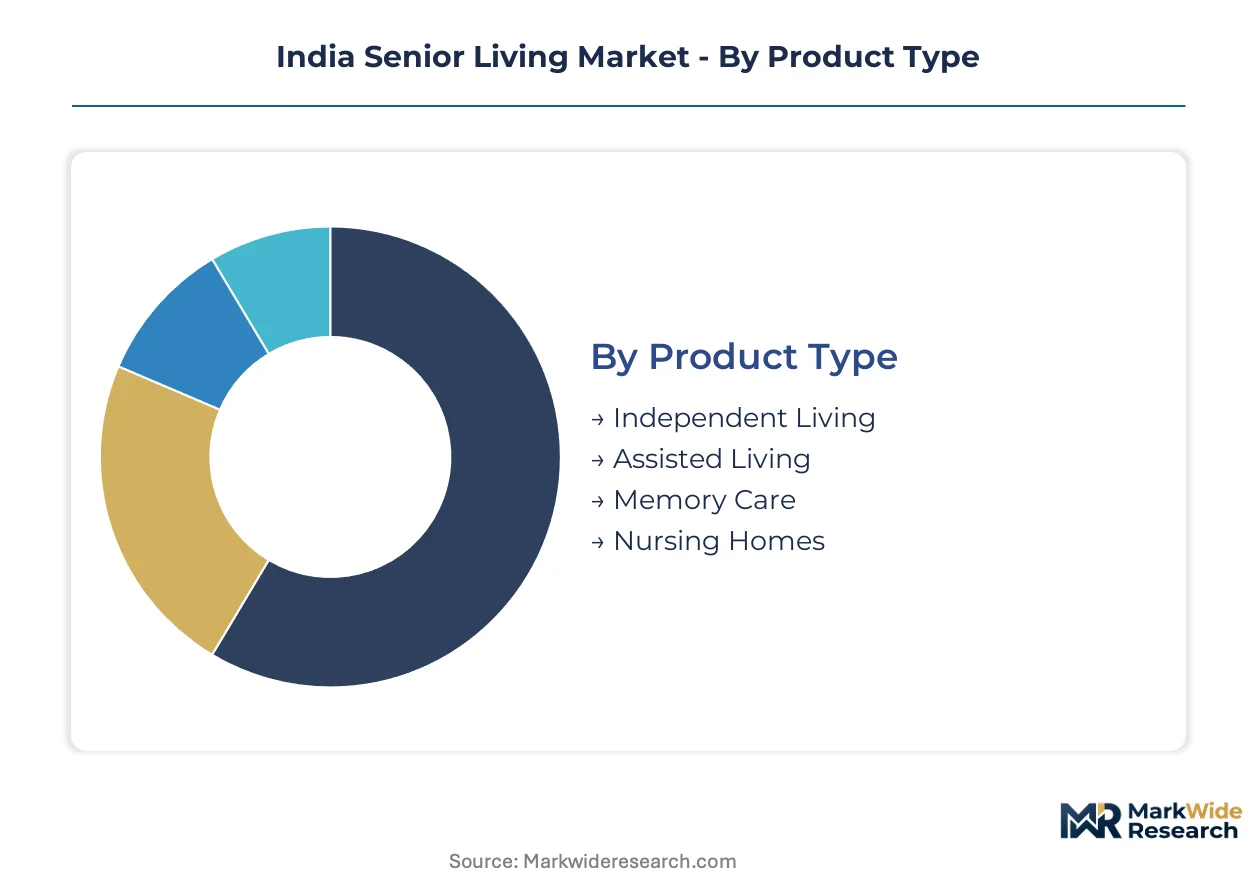
Segmentation in India's senior living market reveals distinct capital intensity and operational complexity profiles across service tiers. Product type and facility configuration determine land acquisition strategies, while customer archetypes drive location selection and amenity programming decisions.
Product Type:
Customization intensity varies sharply across this category, from standardized apartment configurations to clinically intensive skilled nursing environments.
- Independent Living:Self-contained residential units with accessibility modifications but no medical staffing. Demand concentrates in Maharashtra's Pune-Mumbai corridor where affluent urban retirees seek maintenance-free lifestyles with emergency response infrastructure.
- Assisted Living:Supervised residential settings with medication management and daily activity support. Families of seniors in Bengaluru's Whitefield cluster drive demand for facilities bridging independence and nursing care.
- Memory Care:Secured environments with specialized dementia programming and behavioral management protocols. CDSCO-regulated diagnostic equipment supports early cognitive screening protocols.
- Nursing Homes:Skilled nursing facilities with 24/7 medical oversight and post-acute rehabilitation capacity. BIS building codes enforce stricter fire safety and infection control specifications than other product tiers.
Most installed capacity flows through Independent Living. Expansion is steepest in Memory Care.
Service Model:
Revenue recurrence and margin stability differentiate this category, from one-time placement fees to ongoing care subscriptions.
- Residential Care:Full-time facility-based living with bundled accommodation and care services. Tier-2 cities like Jaipur and Coimbatore exhibit rising demand as mid-market developers replicate standardized designs.
- Rehabilitation Services:Post-surgical recovery and physiotherapy programs generating recurring revenue through insurance contracts. CEA electrical safety standards mandate backup power for continuous therapeutic equipment operation.
- Day Care:Non-residential daytime supervision with meals, activities, and health monitoring for seniors living with family. Municipal zoning in Tier-1 cities restricts standalone day care licensing.
- Home Care:Domestic nursing and personal assistance delivered to private residences. Paramedic staffing scarcity limits service scalability outside metropolitan clusters.
Residential Care captures the dominant revenue share. Rehabilitation Services are climbing the fastest as post-surgical recovery contracts expand.
Facility Type:
Land use efficiency and care continuum integration define developer choices across this architectural spectrum.
- Continuing Care Retirement Communities:Campus-style developments enabling transitions from independent living through skilled nursing without relocation. State-level RERA registration requirements extend commissioning timelines for these capital-intensive projects.
- Senior Apartments:Age-restricted rental or ownership housing with limited services. Ashiana Housing Ltd anchors this segment through replicable Tier-2 city templates.
- Group Homes:Small-scale residential settings serving 6-12 residents with shared caregiving. Families of seniors with moderate care needs favor these for personalized attention ratios.
- Co-housing:Collaborative living arrangements with shared common spaces and mutual assistance structures. Active Seniors in Chandigarh and Pune experimental clusters drive nascent demand.
Senior Apartments hold the largest existing inventory. Continuing Care Retirement Communities are gaining share fastest as wealth concentration enables premium positioning.
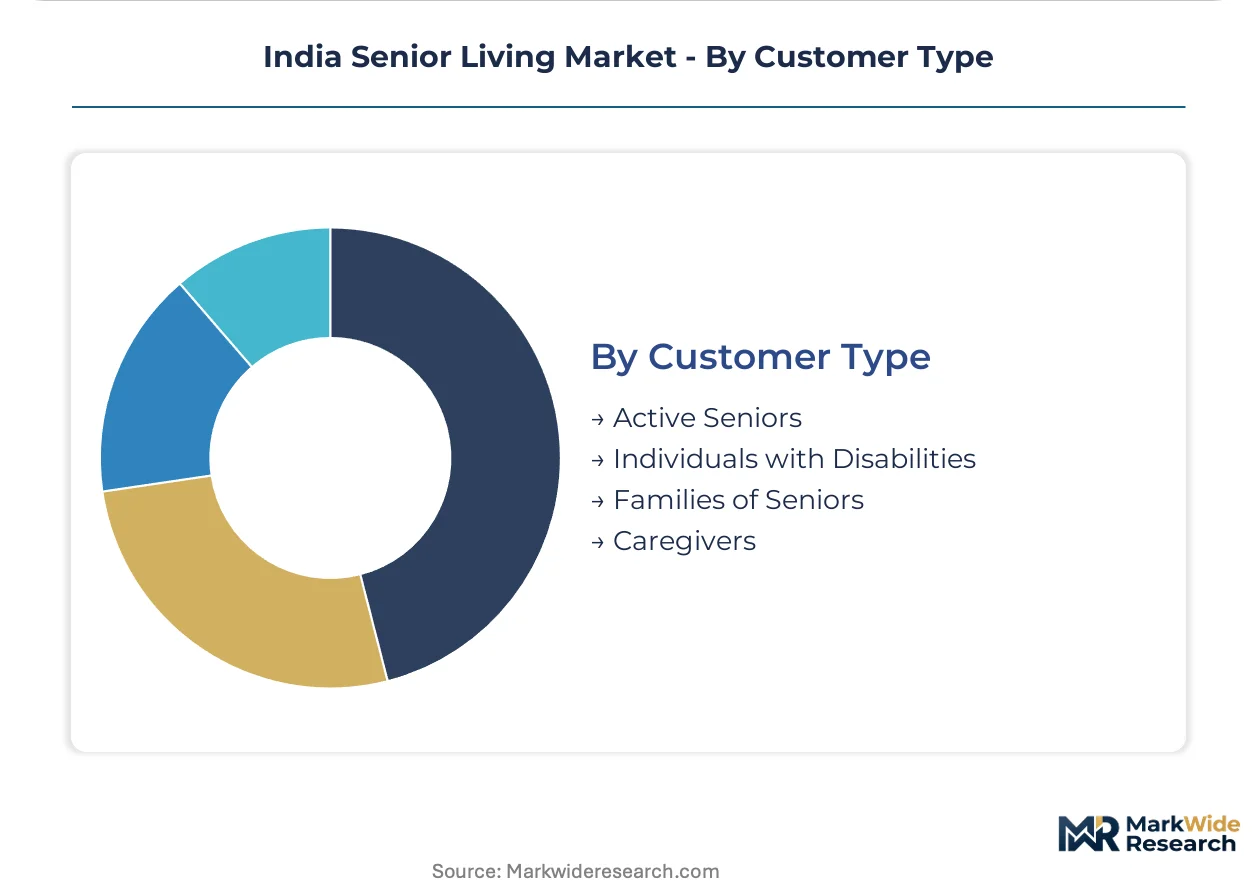
Customer Type:
Purchase decision authority and payment source fragmentation create distinct acquisition strategies across this category.
- Families of Seniors:Adult children, often NRIs, controlling facility selection and financial commitment. Virtual tours and digital contract execution now dominate this segment's sales channel in the Pune-Mumbai corridor.
- Active Seniors:Independent decision-makers aged 60-75 seeking lifestyle amenities and social infrastructure. Maharashtra and Karnataka municipal zoning relaxions could redraw location economics for greenfield projects targeting this cohort.
- Individuals with Disabilities:Younger adults with physical or cognitive impairments requiring adapted living environments. BIS elderly-friendly design mandates partially address accessibility needs for this overlapping population.
- Caregivers:Professional and family care providers seeking respite services or residential placement support. PLI scheme healthcare infrastructure investments indirectly expand training capacity for this stakeholder group.
Families of Seniors control the dominant purchase volume. Active Seniors are expanding most quickly as first-generation wealthy retirees age into target demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trained healthcare workers and specialized facility managers concentrate in India's western and southern corridors, anchoring the nation's eldercare infrastructure deployment.
Maharashtra
Affluent urban retirees from Mumbai's financial services sector drive premium community demand. BIS building codes for elderly-friendly design harden compliance timelines for Pune-Mumbai corridor developers. Integrated retirement communities in Pune command waitlists exceeding twelve months as NRI children consolidate remote purchase decisions.
Karnataka
Bengaluru's technology executive class generates demand for continuum-of-care facilities bridging independent and assisted living. State-level RERA registration extends commissioning cycles for capital-intensive projects. Whitefield and Electronic City clusters exhibit the highest concentration of memory care construction outside Maharashtra.
Tamil Nadu
Coimbatore's manufacturing wealth creates mid-market buyer pools seeking standardized apartment configurations. CDSCO medical device clearance requirements delay diagnostic equipment deployment in new facilities. Chennai's peripheral districts attract day care operators facing municipal zoning restrictions in the core city.
Gujarat
Pharmaceutical and diamond trading families in Ahmedabad and Surat represent emerging active senior demographics. PLI scheme healthcare infrastructure investments indirectly expand paramedic training capacity for facility staffing. Gandhinagar's planned city framework offers zoning flexibility for greenfield continuing care campuses.
Telangana
Hyderabad's pharmaceutical and IT wealth concentration supports premium positioning for new market entrants. CEA electrical safety standards enforce backup power specifications that inflate project capital costs. The city's western corridor exhibits rising land acquisition activity among developers replicating Maharashtra's integrated community model.
India Senior Living Market Competitive Landscape
Capital-heavy real estate developers compete with asset-light healthcare operators for resident acquisition and clinical credibility. The market structure tiers across hospital-network affiliates, pure-play housing developers, and international protocol adapters. Three archetypes dominate: integrated healthcare-housing hybrids, standardized mid-market replicators, and foreign-operational-standard importers. Capacity expansion through land banking in Tier-2 cities and clinical staffing partnerships constitute the primary competitive vectors.
Among hospital-network affiliates, Antara Senior Care leverages its Max Group clinical infrastructure to anchor assisted living credibility. Ashiana Housing Ltd occupies the standardized mid-market replicator position with Tier-2 city templates optimized for Jaipur and Coimbatore deployment. Columbia Pacific Communities represents the foreign-protocol adapter archetype, adapting American operational frameworks to Indian family visitation expectations.
| Leading Market Players |
|---|
| Athulya Senior Care |
| Covai Property Centre (I) Pvt Ltd |
| Antara Senior Care |
| Godrej Properties Godrej Seasons Senior Living |
| Vedaanta Retirement Communities |
| Columbia Pacific Communities |
| Primus Lifespaces Pvt Ltd |
| Gracias Living |
| Ashiana Housing Ltd |
| Others |
Supply & Pricing Matrix
NRI children consolidating remote purchase decisions in the Pune-Mumbai corridor anchor pricing power for premium integrated retirement communities, where waitlist dynamics sustain entry fee premiums and monthly subscription escalations that mid-market operators in Tier-2 cities cannot replicate.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by clinical staffing intensity and amenity depth. Premium operators command entry fees and monthly subscriptions that reflect 24/7 paramedic coverage and BIS-certified elderly-friendly design, while mid-market replicators compete on standardized apartment configurations. Pricing pressure stems from CEA-mandated backup power specifications inflating capital costs for greenfield projects. Families of seniors exhibit highest price sensitivity in Tier-2 markets, whereas affluent urban retirees in Maharashtra demonstrate lowest elasticity due to limited inventory availability.
Supply Chain Analysis
Trained paramedic and facility manager scarcity in Jaipur, Coimbatore, and Chandigarh constrains rapid capacity scaling beyond western and southern corridors. Construction inputs draw from Gujarat's cement clusters and Karnataka's building materials networks, while clinical equipment sourcing hinges on CDSCO clearance timelines for diagnostic devices. Single-source vulnerability pervades specialized dementia care programming expertise concentrated in Bengaluru and Hyderabad. Distribution runs through hospital-network affiliates for clinical credibility, pure-play developers for standardized replication, and foreign-protocol adapters for operational differentiation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India senior living functions as a stable compounder where demographic aging of the upper-middle class generates predictable demand expansion with limited cyclicality.
For Market Incumbents: Acquire land parcels in Gandhinagar and Chandigarh before municipal zoning relaxions intensify competition. Deepen clinical staffing partnerships with Max Group-affiliated training programs to defend against paramedic scarcity threatening service quality. Pursue backward integration into rehabilitation equipment supply to capture margin pools from post-surgical recovery contracts. For New Entrants and Emerging Players: Virtual facility tours and digital contract execution channels offer lowest-friction entry into NRI-family purchase decisions concentrated in the Pune-Mumbai corridor. Target memory care construction in Whitefield and Electronic City clusters where dementia prevalence among technology executives outpaces specialized inventory. Anchor go-to-market positioning on CDSCO pre-approved diagnostic suites that compress licensing timelines versus competitors. For Investors and Strategic Acquirers: Hospital-network affiliates are the most active acquirer in this space as Max Group and comparable clinical platforms seek eldercare vertical extension. Five-to-ten year viability rests on land banking execution in Tier-2 cities and regulatory navigation capability. Monitor state-level eldercare subsidy announcements as inflection signals for location economics redistribution toward Gujarat and Karnataka.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Staffing Partnership | Max Group hospital networks anchor assisted living credibility through trained paramedic pipelines. |
| Land Banking in Tier-2 Cities | Jaipur and Coimbatore parcels enable standardized mid-market replication before zoning intensifies. |
| CDSCO Pre-Approval Investment | Diagnostic equipment suite pre-clearance compresses commissioning cycles for new facilities. |
| Digital Sales Channel Buildout | Virtual tours capture NRI children consolidating remote purchase decisions in Maharashtra. |
| Rehabilitation Service Integration | Post-surgical recovery contracts generate recurring revenue through insurance reimbursement pathways. |
Research Methodology
Coverage spans Maharashtra, Karnataka, Tamil Nadu, Gujarat, and Telangana, with primary inputs from each. The approach combines structured interviews with facility operations directors, clinical staffing managers, state regulatory affairs leads, and NRI family decision-makers with secondary validation from BIS building code filings, CDSCO medical device clearance records, state RERA registration databases, and PLI scheme healthcare infrastructure disclosures. Bottom-up unit economics triangulate against top-down demographic demand projections.
Granularity-level modeling disaggregates revenue across independent living, assisted living, memory care, and nursing home product types; residential care, rehabilitation services, day care, and home care service models; and continuing care retirement communities, senior apartments, group homes, and co-housing facility configurations. CAGRs derive from cohort-specific penetration rate trajectories applied to aging demographic forecasts. Industry-specific inputs include dementia prevalence curves among India's wealthy elderly and municipal zoning relaxation probability assessments.
The model assumes a particular technology adoption path for centralized health monitoring and fall-detection sensor deployment; alternative pathways for biometric tracking integration would alter the outlook. Forecasts reflect assumptions regarding PLI scheme continuity, paramedic training capacity expansion, and NRI remittance stability. Material deviation in state-level eldercare subsidy announcements or BIS code enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
US Hospice Care Market
Healthcare Services
Tissue Banking Market
Healthcare Services
Global Healthcare Contract Manufacturing Market
Healthcare Services
Healthcare Transportation Services Market
Healthcare Services
Contract Manufacturing Organization (CMO) Market
Healthcare Services
Prescription Delivery Services Market
Healthcare Services
Aged Care Market
Healthcare Services
Global Funeral Homes and Funeral Services Market
Healthcare Services
Global Concierge Medicine Market
Healthcare Services
US Value-Based Healthcare Service Market
Healthcare Services
Contract Manufacturing Services Market
Healthcare Services
Packaging and Labeling (Healthcare) Services Market
Healthcare Services
Hospice Market
Healthcare Services
South Korea Healthcare Cold Chain Logistics Market
Healthcare Services
Primary Care Physicians Market
Healthcare Services
Medical Recruitment Market