
 Light Reflective Film Market | 2026-2036
Light Reflective Film Market Size, Share, and Industry Trends Forecast 2026-2036
Light Reflective Film Market Analysis
Electronics OEMs is bifurcating demand away from traditional automotive and signage buyers as display mini-LED and quantum-dot diffusion applications multiply. 3M Company leverages its optical film patent portfolio to sustain premium positioning in high-reflective substrates. Yongtek anchors supply for East Asian panel makers through dedicated roll-to-roll manufacturing lines. DUNMORE competes on thin-gauge metallized films for aerospace and transportation laminates.
Light reflective film denotes a polymer substrate—typically polyethylene terephthalate or polycarbonate—coated with vapor-deposited aluminum or silver layers, engineered to achieve reflectance values exceeding 95% across visible wavelengths for optical management and thermal control. High-reflective films dominate margin pools in electronics backlighting where micron-level thickness tolerances command technical premiums, while window films represent the mature volume base in commercial architecture retrofits. Electronics applications generate the fastest-growing demand segment as display manufacturers specify multi-layer stacks for brightness enhancement.
REACH compliance in Europe restricts certain halogenated flame retardants in polymer films, while China's GB standards mandate solar reflectance thresholds for cool-roof building materials. The US EPA Energy Star program shapes product specifications for architectural window films through labeled performance criteria. South Korea's MFDS and KOSHA frameworks govern occupational exposure limits in film manufacturing facilities. Stakeholders must monitor evolving perfluorinated substance restrictions across multiple jurisdictions that threaten conventional release coatings.
Market Dynamics
Display panel manufacturers are compressing backlight unit thickness specifications while simultaneously demanding higher reflectance efficiency, forcing substrate suppliers to reconcile micron-level tolerances with multi-layer vapor-deposition processes that strain existing roll-to-roll infrastructure.
Growth Catalysts
- Mini-LED diffusion stacks:Display makers specify reflective films as brightness-enhancement layers in quantum-dot backlighting assemblies. Jiangsu province fabrication lines now dedicate capacity to these multi-layer configurations.
- China's GB 50189 building codes:Mandatory solar reflectance thresholds for commercial roofing materials accelerate cool-roof film specification in retrofits. The MEE enforces compliance through provincial environmental inspections.
- South Korea's display corridor:Panel producers in Gyeonggi-do concentrate procurement for optical-grade substrates. Local MFDS workplace safety mandates simultaneously drive equipment upgrades that expand reflective film throughput.
Market Restraints
- Aluminum vapor-deposition cost volatility:Raw metal price swings compress margin predictability for metallized film producers. Smaller roll-to-roll operators lack hedging mechanisms available to integrated chemical conglomerates.
- East Asian supply concentration:Over-reliance on South Korean and Chinese substrate manufacturers exposes buyers to single-source risk. Geopolitical friction threatens just-in-time delivery schedules for European and North American electronics assemblers.
- Perfluorinated release-coating restrictions:REACH and evolving state-level US prohibitions threaten conventional silicone-fluoropolymer formulations. Reformulation timelines lag regulatory phase-out schedules by 18-24 months.
Strategic Opportunities
- India's BIS certification pathway:Domestic electronics manufacturing incentives under PLI schemes create demand for locally sourced optical films. Early entrants capture specification-setting roles with contract manufacturers.
- Aerospace thermal-control laminates:Thin-gauge metallized films penetrate satellite and UAV insulation stacks. DUNMORE and specialty converters already supply qualification batches to prime contractors.
- EU Green Deal procurement mandates:Public building retrofits must meet embodied-carbon thresholds favoring high-durability reflective window films. The CSRD disclosure requirements amplify specification transparency for architectural buyers.
Industry Challenges
- Vacuum-coating technician scarcity:Roll-to-roll vapor-deposition expertise concentrates in East Asian facilities. Western and emerging-market producers struggle to replicate process control knowledge.
- Multi-stack integration complexity:Display manufacturers demand pre-laminated reflective-diffuser combinations that complicate quality-assurance protocols. Defect detection across bonded layers requires capital-intensive optical inspection systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Light Reflective Film Market |
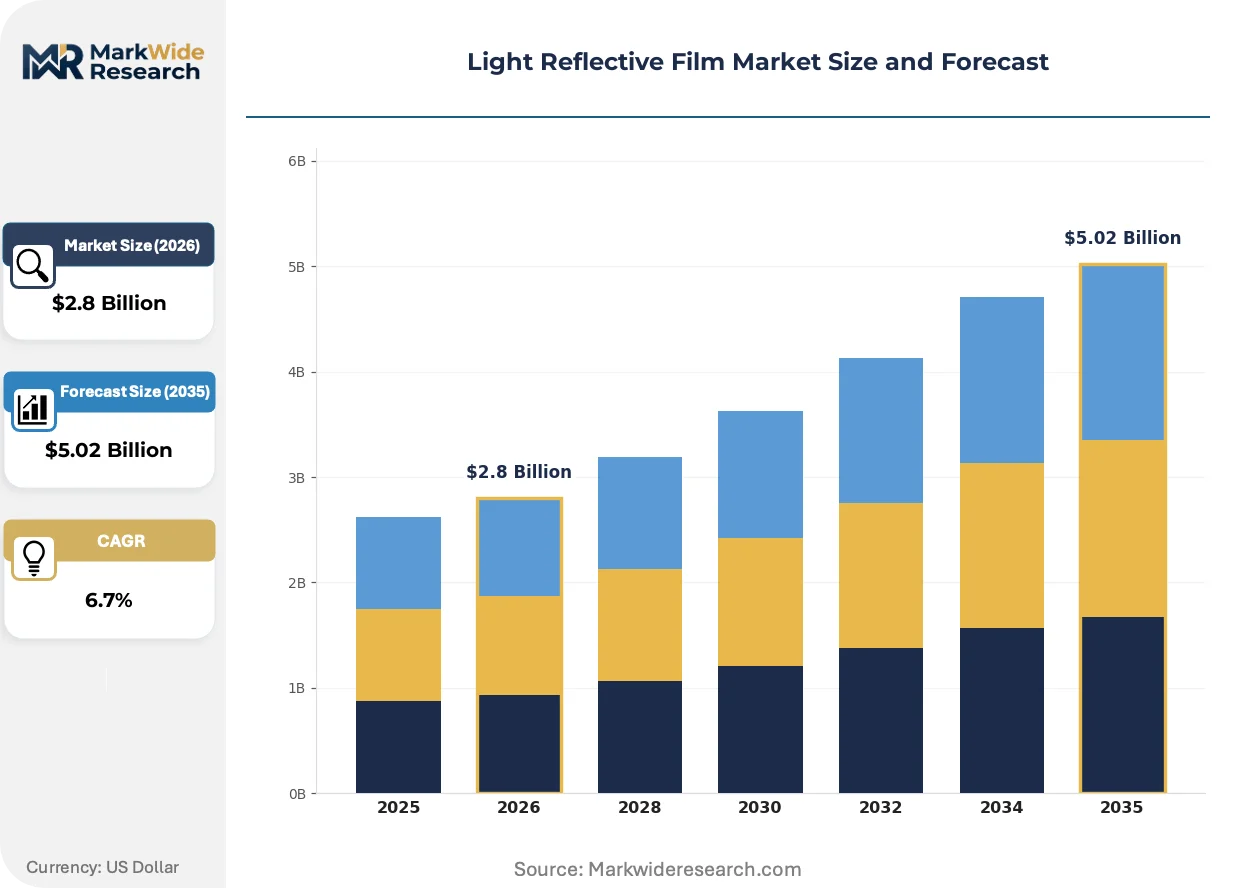
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Reflective Films, Window Films, Decorative Films, Safety Films Application: Automotive, Architecture, Advertising, Electronics End User: OEMs, Retailers, Contractors, Distributors Distribution Channel: Online Retailers, Wholesalers, Direct Sales, Specialized Stores |
| Companies Covered | DUNMORE, 3M Company, WhiteOptics LLC, ORAFOL Europe GmbH, Avery Dennison Corporation, FLEx Lighting LLC, Yongtek, Hefei Bright Reflective Material, Fusion Optix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Light Reflective Film Market Emerging Trajectories
Reflective film architecture is bifurcating toward ultra-thin electronics-grade stacks and durable building-envelope membranes, with manufacturing equipment repurposing between these divergent thickness regimes.
Nano-porous PET substrates with embedded ceramic scatterers are miniaturizing total stack thickness below 50 microns while maintaining 96% visible reflectance. Samsung Display and BOE Technology Group accelerate adoption for tablet and notebook backlighting units. This compression is miniaturizing optical engine volumes, enabling slimmer device form factors that displace conventional prism-sheet configurations.
REACH Annex XVII restrictions on halogenated flame retardants are forcing polymer film reformulation across European supply chains. ECHA substance-of-very-high-concern listings now cover legacy brominated additives common in architectural-grade reflective membranes. German and French building-material distributors are pivoting procurement toward phosphorus-based alternatives, though these compounds degrade vapor-deposition adhesion properties.
Electronics OEMs now consolidate reflective film procurement through designated component integrators rather than direct substrate sourcing. Foxconn and Luxshare-ICT aggregate specifications across multiple display customers, compressing supplier negotiation leverage. This intermediation concentrates most visibly in South Korea's panel corridor, where tier-one assemblers have displaced independent film distributors from specification-setting conversations.
Light Reflective Film Market Segmentation
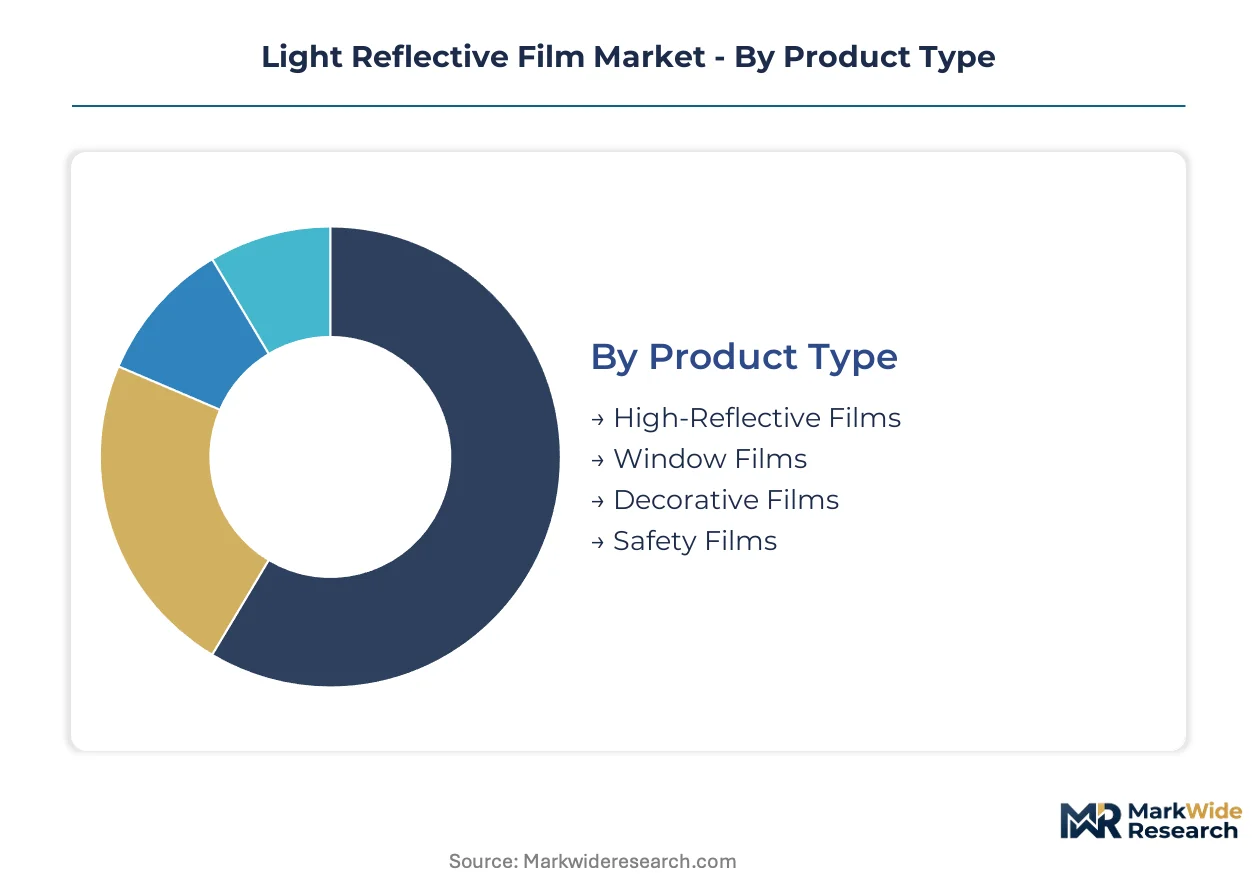
Segmentation in the light reflective film market reveals divergent margin structures and procurement pathways. Electronics applications command technical premiums through designated component integrators, while architectural volumes flow through wholesale distribution networks with compressed pricing.
Product Type:
Channel mix varies sharply by film performance tier, with high-reflective grades flowing through direct OEM contracts and commodity window films saturating wholesale building-material channels.
- High-Reflective Films:Multi-layer vapor-deposited substrates achieving 95%+ visible reflectance through aluminum or silver metallization. Electronics OEMs in South Korea's Gyeonggi-do corridor specify these for mini-LED backlighting stacks, with Foxconn and Luxshare-ICT consolidating procurement through designated integrators.
- Window Films:Solar-control laminates for commercial architecture retrofits, typically metallized PET at 50-100 micron thickness. China's GB 50189 cool-roof mandates accelerate specification through provincial environmental inspections, with Jiangsu province fabrication lines dedicating capacity to building-envelope grades.
- Decorative Films:Aesthetic metallized substrates for interior and exterior architectural applications. German and French building-material distributors pivot procurement toward phosphorus-based flame-retardant formulations under REACH Annex XVII pressures.
- Safety Films:Impact-resistant laminates combining reflective properties with shatter retention. Automotive glazing and transportation infrastructure represent primary specification pathways.
By volume, Window Films leads. By growth pace, High-Reflective Films is ahead.
Application:
Cost tier stratification separates premium electronics-grade specifications from standardized automotive and signage procurement.
- Electronics:Display backlighting units for tablets, notebooks, and televisions. BOE Technology Group and Samsung Display compress stack thickness below 50 microns while maintaining 96% reflectance through nano-porous PET with embedded ceramic scatterers.
- Architecture:Commercial roofing and fenestration retrofits driven by energy-efficiency codes. The EU Green Deal procurement mandates for public buildings favor high-durability reflective membranes with embodied-carbon disclosure under CSRD requirements.
- Automotive:Interior trim and exterior accent applications with moderate reflectance requirements. Supply concentrates through tier-one interior system suppliers rather than direct film sourcing.
- Advertising:Signage and display applications with cost-sensitive specifications. Roll-to-roll converters serve this segment through distributor networks with minimal technical support.
Electronics generates the steepest expansion trajectory. Architecture retains the largest installed base.
End User:
Customer type determines specification authority, with OEMs controlling technical requirements and retailers managing commoditized volumes.
- OEMs:Electronics and automotive manufacturers with direct substrate qualification protocols. Panel producers in South Korea concentrate procurement for optical-grade films, displacing independent distributors from specification-setting conversations.
- Contractors:Building envelope installers sourcing through regional wholesale channels. China's MEE enforces GB standard compliance through provincial environmental inspections that shape contractor material selection.
- Distributors:Independent film converters serving fragmented signage and architectural markets. Margin pressure intensifies as direct OEM contracts bypass traditional distribution layers.
- Retailers:Consumer-facing channels for DIY window film applications. Online platforms capture share from specialized storefronts in mature markets.
OEMs command specification authority. Contractors manage the broadest geographic footprint.
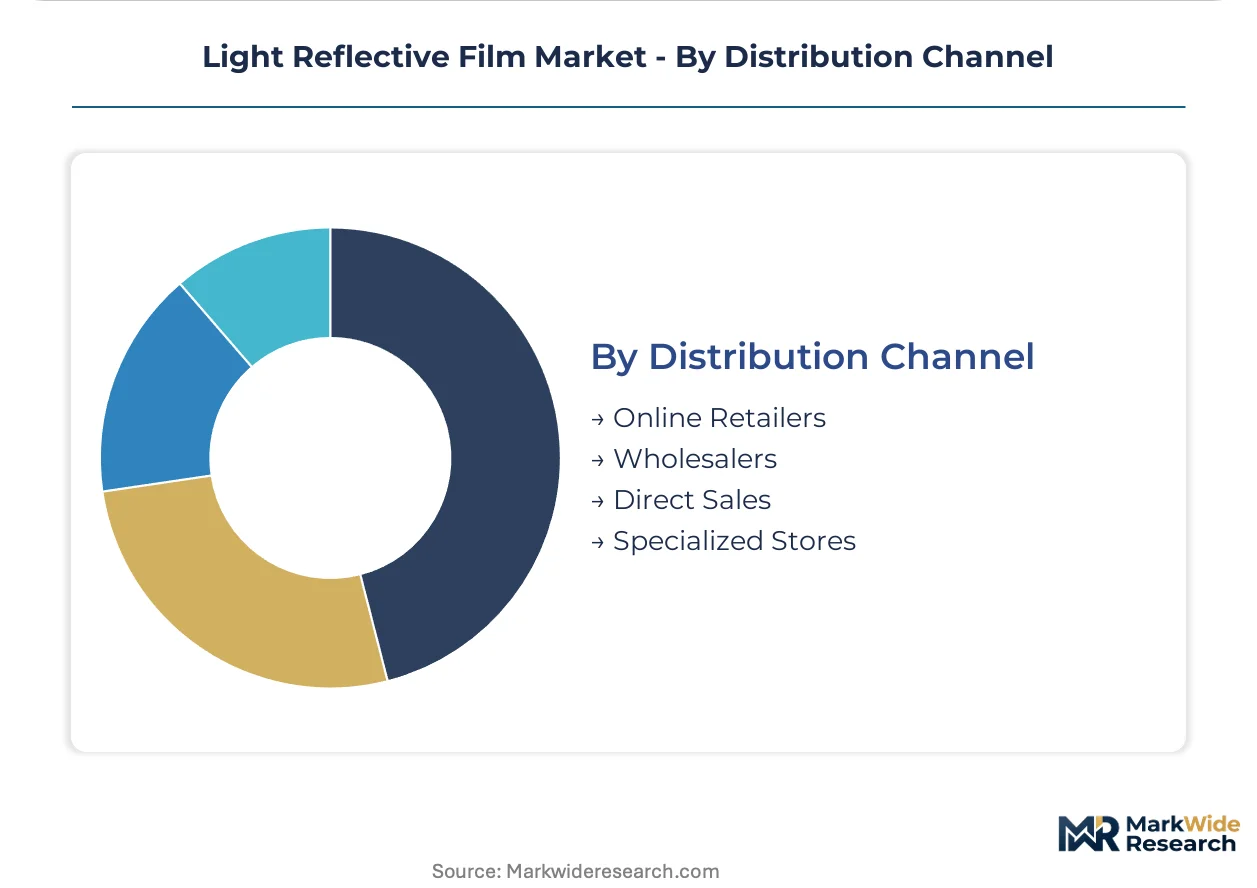
Distribution Channel:
Supply concentration in East Asian manufacturing clusters shapes channel viability for European and North American buyers.
- Direct Sales:Long-term supply agreements between substrate manufacturers and electronics assemblers. Yongtek anchors supply for East Asian panel makers through dedicated roll-to-roll manufacturing lines.
- Wholesalers:Regional building-material distributors serving architecture and advertising segments. REACH compliance documentation requirements now accompany standard shipments to European wholesale customers.
- Online Retailers:E-commerce platforms capturing consumer and small-contractor demand. India's PLI scheme for domestic electronics manufacturing creates openings for locally sourced optical films through digital procurement channels.
- Specialized Stores:Technical distributors offering application support and custom cutting. Vacuum-coating technician scarcity in Western markets limits the service depth these channels can provide.
Wholesalers move the highest tonnage. Direct Sales captures the most value per square meter.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Busan anchors East Asian substrate logistics, channeling metallized PET feedstock from Jiangsu province fabrication lines to Gyeonggi-do panel corridors. This maritime throughput underwrites South Korea's dominance in optical-grade film qualification.
China
Jiangsu province hosts dedicated roll-to-roll manufacturing lines for multi-layer reflective stacks. The MEE enforces GB 50189 solar reflectance thresholds through provincial environmental inspections that reshape contractor material selection. Nanjing and Suzhou fabrication clusters now bifurcate capacity between electronics-grade thin films and building-envelope membranes.
South Korea
Gyeonggi-do panel producers concentrate procurement for optical-grade substrates, displacing independent distributors from specification-setting conversations. MFDS workplace safety mandates drive equipment upgrades that expand reflective film throughput. The Busan-Ulsan industrial corridor channels vapor-deposited aluminum supply to display backlighter manufacturers.
United States
The EPA Energy Star program shapes product specifications for architectural window films through labeled performance criteria. California's Title 24 building codes mandate cool-roof solar reflectance for commercial retrofits. Midwestern roll-to-roll converters serve aerospace thermal-control laminate demand from satellite prime contractors.
Germany
ECHA Annex XVII restrictions on halogenated flame retardants force polymer film reformulation across European supply chains. The EU Green Deal procurement mandates for public buildings favor high-durability reflective membranes with embodied-carbon disclosure. Bavarian chemical conglomerates leverage hedging mechanisms unavailable to smaller metallized film operators.
India
PLI scheme incentives for domestic electronics manufacturing create demand for locally sourced optical films. BIS certification pathways enable early entrants to capture specification-setting roles with contract manufacturers. Tamil Nadu and Karnataka fabrication corridors attract substrate suppliers targeting display assembly operations.
Light Reflective Film Market Vendor Landscape
Listed leaders compete with private specialists across capital access and strategic flexibility dimensions, producing a tiered structure where scale advantages clash with customization agility. The vendor base separates into three archetypes: diversified chemical conglomerates with captive metallization capacity, dedicated optical film specialists with roll-to-roll expertise, and regional converters serving commoditized architectural segments. Dominant competitive moves include backward integration into polymer resin production and strategic partnerships with display panel assemblers that lock in multi-year supply commitments.
Within the diversified conglomerate tier, 3M Company and Avery Dennison Corporation exemplify players leveraging patent portfolios and global distribution infrastructure to sustain premium positioning. Among East Asian specialists, Yongtek anchors supply relationships with dedicated manufacturing lines, while DUNMORE occupies a position serving aerospace and transportation laminate demand through thin-gauge metallization expertise. These named entities represent strategic archetypes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| DUNMORE |
| 3M Company |
| WhiteOptics LLC |
| ORAFOL Europe GmbH |
| Avery Dennison Corporation |
| FLEx Lighting LLC |
| Yongtek |
| Hefei Bright Reflective Material |
| Fusion Optix |
| Others |
Supply Flow & Price Mechanics
Roll-to-roll vapor-deposition capacity utilization above 85% in Jiangsu province and Gyeonggi-do clusters compresses margin floors for smaller metallized film converters while amplifying pricing leverage for integrated chemical conglomerates with captive aluminum sourcing. This scale asymmetry concentrates procurement power among East Asian panel assemblers who negotiate multi-year supply commitments that lock in volume-discount tiers unavailable to fragmented architectural buyers.
Pricing Analysis
Volume-discount tiering separates electronics OEM direct contracts from wholesale architectural channels, with premium-mid-economy pricing differentiation driven by reflectance certification grades and micron-level thickness tolerances. Electronics-grade specifications command technical premiums through designated component integrators like Foxconn and Luxshare-ICT, while window film distributors face margin compression from commodity spot pricing. Cost compression in building-envelope segments intensifies because Jiangsu fabrication lines prioritize display backlighting capacity, forcing architectural buyers toward higher-cost import alternatives. Contractors sourcing through regional wholesale channels exhibit highest price sensitivity, whereas South Korean panel producers locked into qualification protocols demonstrate lowest sensitivity to unit cost fluctuations.
Supply Chain Analysis
The Port of Busan transit underwrites East Asian substrate logistics, channeling vapor-deposited aluminum feedstock from Jiangsu province to Gyeonggi-do panel corridors with single-source vulnerability concentrated in South Korean and Chinese metallization facilities. Raw material dependencies draw from aluminum ingot smelters, PET resin producers, and ceramic scatterer suppliers for nano-porous substrates. Tariff exposure threatens just-in-time delivery schedules for European and North American electronics assemblers sourcing from concentrated East Asian manufacturing nodes. Distribution runs through direct OEM contracts for high-reflective grades and regional building-material wholesalers for architectural volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mini-LED diffusion stack adoption represents a high-growth disruption reshaping procurement patterns, with China's GB 50189 enforcement and South Korea's MFDS workplace mandates creating dual regulatory inflections that favor qualified suppliers with compliant manufacturing infrastructure.
For Market Incumbents: Shield proprietary roll-to-roll process knowledge through technician retention programs and equipment upgrade cycles that expand Gyeonggi-do throughput under MFDS mandates. Backward integration into PET resin production secures margin control against aluminum price volatility, while patent portfolio enforcement around optical film architectures defends premium positioning from emerging Chinese competitors with reverse-engineered metallization techniques. For New Entrants and Emerging Players: Lead with BIS certification pathways in India's Tamil Nadu and Karnataka fabrication corridors, where PLI scheme incentives for domestic electronics manufacturing create specification-setting opportunities with contract manufacturers lacking established optical film suppliers. Aerospace thermal-control laminates for satellite and UAV insulation stacks offer the most penetrable application segment, with qualification batch supply to prime contractors serving as the optimal go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among roll-to-roll specialists with multi-year supply commitments to South Korean panel producers, suggesting long-term viability over a 5-10 year window rests on locked-in OEM relationships rather than spot-market exposure. Acquisition targets should prioritize East Asian specialists with MFDS-compliant facilities and captive metallization capacity. The signal to watch is REACH Annex XVII expansion to additional flame-retardant chemistries, which would force reformulation timelines that lag regulatory phase-outs by 18-24 months and strand non-compliant inventory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PET Resin | Captive polymer supply insulates margin from petrochemical feedstock volatility affecting Jiangsu converters. |
| Multi-Year Supply Commitment Lock-in | Foxconn and Luxshare-ICT consolidation creates specification authority that displaces independent distributors. |
| REACH-Compliant Reformulation | Phosphorus-based flame-retardant pivot preserves European market access as ECHA restrictions expand. |
| India BIS Certification Pathway | Early PLI scheme qualification captures domestic electronics manufacturing incentives in Tamil Nadu corridors. |
| Aerospace Qualification Batch Supply | DUNMORE's thermal-control laminate precedent opens satellite and UAV insulation stack penetration. |
Methodological Framework
Operator-level perspectives from roll-to-roll plant managers, display panel procurement leads, architectural wholesale distributors, vacuum-coating technicians, and ECHA regulatory affairs specialists anchored the qualitative base. Primary interview insights combined with secondary validation from SEC 10-K filings of diversified chemical conglomerates, Chinese customs metallized film trade data, MFDS workplace safety inspection records, and EU Green Deal procurement mandate documentation. Bottom-up capacity modeling across Jiangsu and Gyeonggi-do fabrication lines triangulated against top-down demand estimates from BOE Technology Group and Samsung Display supply chain disclosures.
Sensitivity analysis tested forecast robustness across aluminum price volatility scenarios, REACH regulatory expansion timelines, and mini-LED adoption penetration curves throughout the projection horizon. Segmentation dimensions modeled include product performance tier, application end-use, customer type procurement authority, and regional manufacturing hub concentration. CAGRs derived from historical capacity expansion rates and qualified supplier qualification protocols, with nano-porous PET substrate miniaturization below 50 microns and embedded ceramic scatterer adoption serving as primary technology trajectory inputs.
The analysis sits within stated boundaries; outcomes outside sustained mini-LED backlighting specification growth or accelerated perfluorinated release-coating restrictions would require recalibration. Forecasts reflect assumptions around East Asian supply concentration persistence and display manufacturer consolidation through designated component integrators. Practitioners should keep alternative scenarios live as China's dual carbon goals enforcement intensity and South Korea's MFDS equipment upgrade mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Mexico Plastic Packaging Films Market
Poly film
Polypropylene Packaging Films Market
Poly film
Polylaminate Capsules Market
Poly film
Multi-Layer Blown Films Market
Poly film
Metallized Film Market
Poly film
PVC Film for Medical Market
Poly film
Anti Fog Polycarbonate Films and Sheets Market
Poly film
Printed Plastic Films Market
Poly film
Polyolefin Films Market
Poly film
Polyester Film Market
Poly film
Polyethylene Terephthalate (PET) Shrink Films Market
Poly film
Spain Plastic Packaging Films Market
Poly film
Polymer Dispersed Liquid Crystal (PDLC) Film Market
Poly film
Polystyrene Films Market
Poly film
Global Reclosable Films Market
Poly film
Craft Plastic Films Market