
 Recyclable Lidding Films Market | 2026-2036
Recyclable Lidding Films Market Size, Share, and Industry Trends Forecast 2026-2036
Recyclable Lidding Films Market Insights
Subscription-based packaging design services is hardening as a distinct revenue layer, with converters bundling material selection, seal-performance testing, and end-of-life certification into recurring contracts. Amcor leverages its global laboratory network to anchor this service model across European dairy and ready-meal accounts. Mondi competes through captive pulp and paper integration that sustains cost advantages in cellulose-based lidding formats. Sealed Air differentiates by controlling proprietary vacuum-skin equipment placements that lock in film specification decisions at meat packagers.
Recyclable lidding films are thin-gauge flexible structures, typically 25-80 micron thickness, engineered for single-substrate or compatible multi-layer construction that passes mechanical recycling sortation without adhesive contamination. Their primary commercial purpose is hermetic sealing of trays, cups, and bowls with controlled peel force and oxygen barrier, while enabling post-consumer collection streams to produce food-grade recycled resin. Mono-material polyethylene and polypropylene film technology leads volume due to established mechanical recycling infrastructure and lower reprocessing cost, whereas polylactic acid and cellulose acetate material types represent the fastest-growing structural category as brand owners pursue bio-based claims and home composting certifications. Multi-layer foil-based configurations occupy a narrowing but high-margin niche in pharmaceutical sealing where barrier performance requirements currently exceed mono-material capabilities.
The EU Green Deal and REACH regulations under ECHA enforce design-for-recycling criteria that reshape product standards across European flexible packaging. FDA food contact notification requirements in the United States and Health Canada guidance on recycled content in food packaging create parallel compliance pathways that influence multinational film specifications. Stakeholders must monitor whether chemical recycling scale-up resolves the performance gap for high-barrier applications or perpetuates reliance on non-recyclable multi-layer structures.
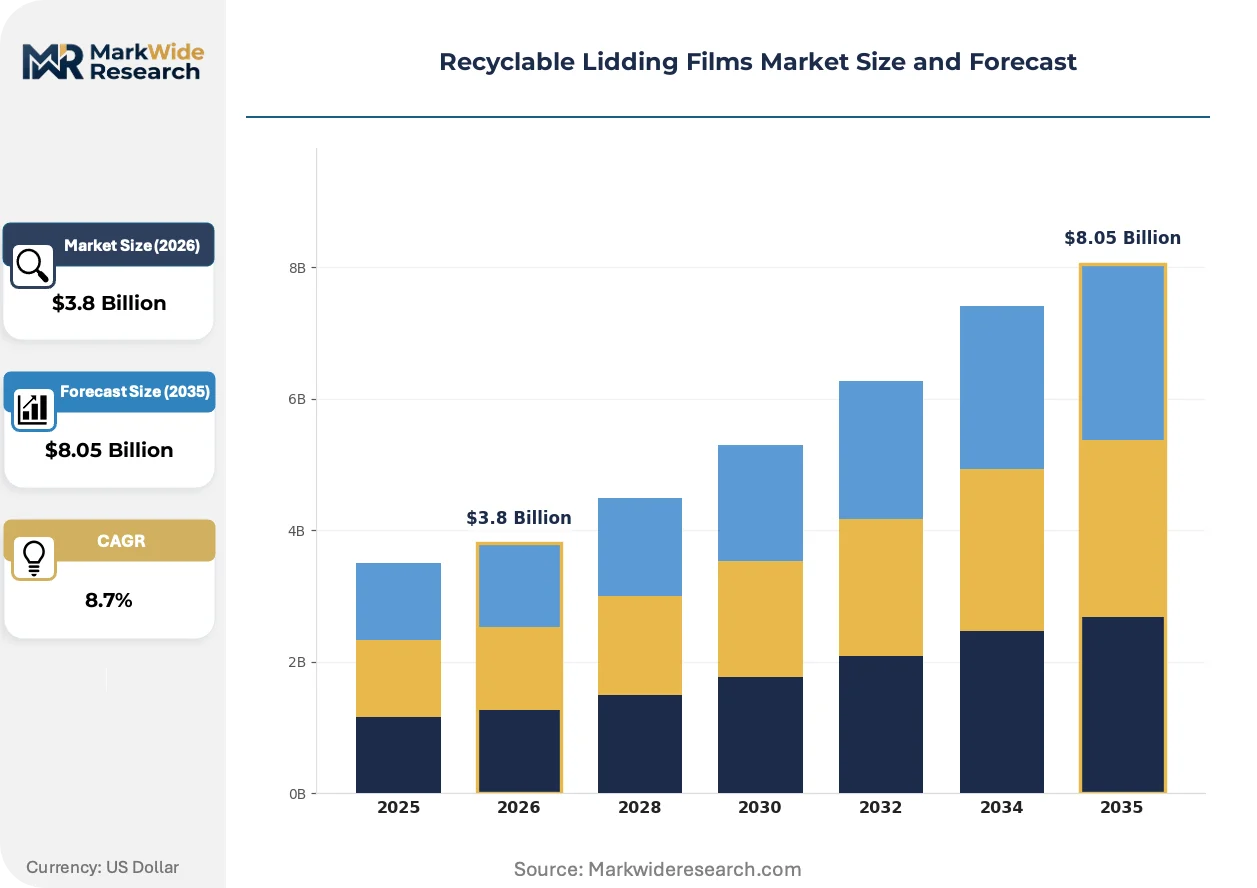
Market Dynamics
Mono-material film specifications are hardening as the dominant design constraint across European flexible packaging, with ECHA REACH substance restrictions and EU Green Deal circularity targets forcing converters to abandon incompatible multi-layer structures regardless of barrier performance trade-offs.
Growth Catalysts
- Extended Producer Responsibility schemes:France's Citeo eco-modulation penalties reward mono-material lidding with fee reductions, pushing dairy brands to specify polyethylene sealant layers.
- Mechanical recycling infrastructure:Germany's DKR and Italy's COREPLA sorting upgrades now accept 80-micron polypropylene lidding films, expanding viable feedstock pools for food-grade recyclate.
- Cellulose acetate film development:Composting certification under EN 13432 opens home-disposal pathways for ready-meal packaging in markets with limited industrial composting access.
Market Restraints
- Ethylene feedstock volatility:Naphtha-cracker margins in Northwest Europe swing polyethylene resin costs, compressing converter margins on fixed-price annual contracts.
- Barrier performance ceiling:Mono-material oxygen transmission rates above 10 cc/m²/day fail pharmaceutical blister specifications, preserving foil-laminate dominance in drug packaging.
- Adhesive contamination risk:Solvent-based lamination chemistries persist in legacy equipment, risking mechanical recycling rejection at European sortation plants.
Strategic Opportunities
- Chemical recycling scale-up:Pyrolysis partnerships with petrochemical majors in the Netherlands and Belgium could unlock food-grade polypropylene from mixed flexible waste streams.
- Vacuum-skin packaging conversion:Meat processors in Spain and Poland are retrofitting lines for recyclable top-web films, displacing non-recyclable barrier webs.
- Digital watermark integration:AIM-Digimarc and Polytag tracer technologies enable AI-driven sortation, creating premium pricing tiers for digitally-marked lidding rolls.
Industry Challenges
- Seal-performance engineering talent:Formulating compatible heat-seal layers for mono-material structures requires polymer scientists with 10+ years of coextrusion experience, a scarce profile in Central European labor markets.
- Migration testing timelines:EFSA food contact material approvals for recycled content lidding extend 18-24 months, delaying product launches ahead of sustainability commitments.
- Legacy thermoformer retrofit costs:Converting form-fill-seal lines from PET/PE multi-web to mono-material sealing jaws demands capital outlays that mid-size meat packagers defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recyclable Lidding Films Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene Terephthalate, Polypropylene, Polylactic Acid, Cellulose Acetate, Polyethylene, Polyvinyl Alcohol Application: Food Packaging, Pharmaceutical Sealing, Cosmetic Containers, Consumer Electronics, Industrial Goods, Industrial Packaging End User: Packagers, Contract Manufacturers, Retail Brands, E-commerce Sellers, Bulk Distributors, Specialty Converters Film Technology: Mono-material Films, Multi-layer Films, Biodegradable Films, Foil-based Films, Coated Films, Heat-sealable Films |
| Companies Covered | Amcor, Berry Global, Mondi, Huhtamaki, Winpak, Sealed Air, Uflex, Toray Plastics, Plastopil Hazorea, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recyclable Lidding Films Market Trends and Innovations
Material science advances and regulatory enforcement timelines are compressing the viable technology set for lidding films, with performance validation protocols now determining which innovations achieve commercial scale before mandate deadlines.
Polyethylene-based mono-material lidding is expanding into high-oxygen-barrier applications through advanced coextrusion of ethylene vinyl alcohol tie layers. Dutch dairy processors are trialing these structures for cheese packaging with 120-day shelf life requirements. The technology is expanding into segments previously reserved for foil laminates, forcing incumbent suppliers to defend specification positions at major retail private-label accounts.
EU Green Deal packaging and packaging waste regulations are mandating recyclability-by-design criteria with 2030 enforcement horizons. Film converters must demonstrate compatibility with established mechanical recycling streams or face market exclusion. Ready-meal and fresh produce segments in Germany and France are responding fastest, with specification committees rewriting tender documents to exclude non-recyclable multi-web alternatives.
Subscription-based technical service contracts are displacing transactional material supply relationships at major food manufacturers. Converters bundle seal-performance testing, regulatory documentation, and end-of-life certification into recurring fee structures. This pattern concentrates most visibly in the United Kingdom and Ireland, where retailer sustainability audits demand continuous compliance evidence rather than one-time material declarations.
Recyclable Lidding Films Market Segmentation
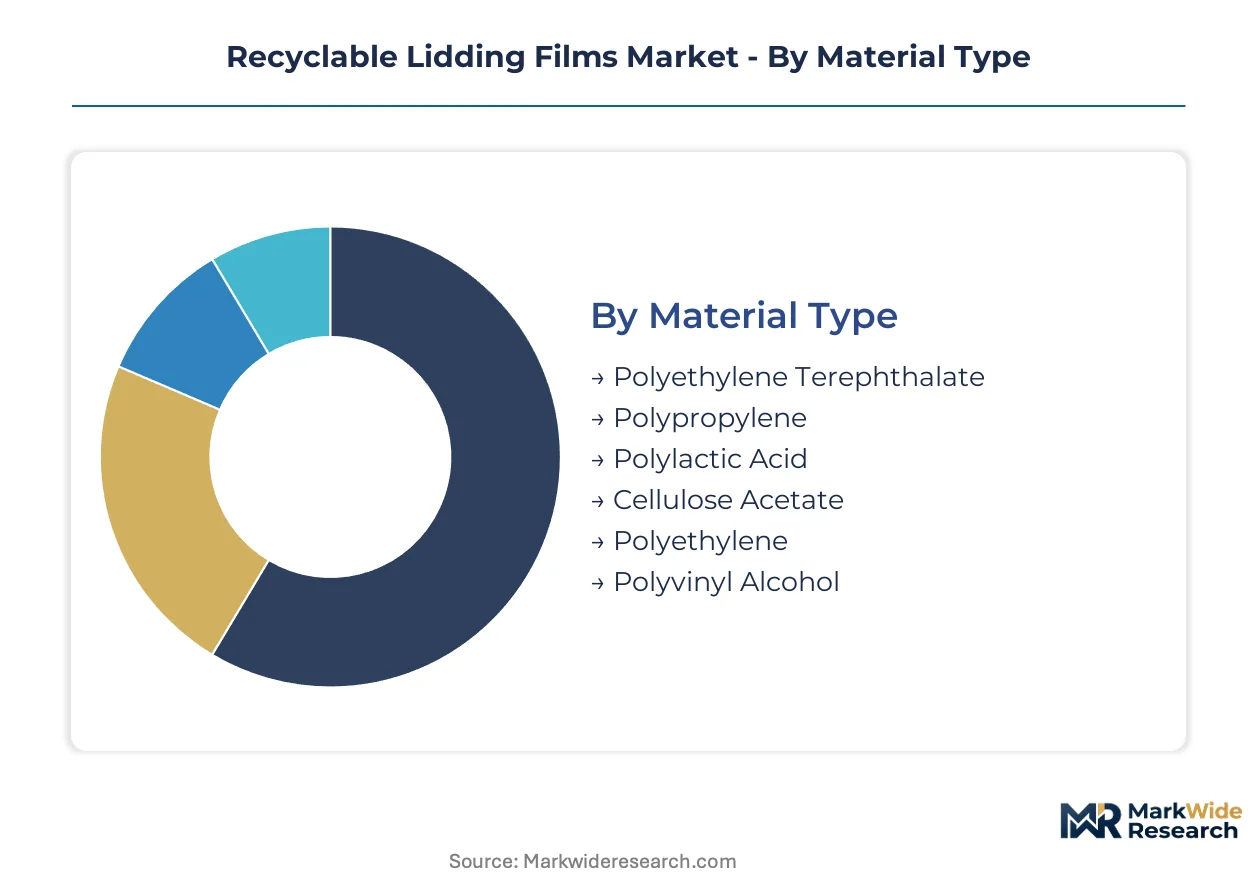
Segmentation in recyclable lidding films reveals how material specifications, application requirements, and converter capabilities interlock. Each dimension carries distinct margin profiles and technical barriers that determine competitive positioning across European flexible packaging value chains.
Material Type:
Supply concentration among petrochemical majors in Northwest Europe shapes resin availability and pricing power across material categories.
- Polyethylene:Low-density and linear-low-density grades dominate mono-material lidding formulations due to established mechanical recycling infrastructure. Dairy processors in France and Germany specify polyethylene sealant layers to qualify for Citeo eco-modulation fee reductions under extended producer responsibility schemes.
- Polypropylene:Cast and oriented polypropylene films offer superior clarity and heat resistance for ready-meal applications. Italy's COREPLA sorting upgrades now accept 80-micron polypropylene lidding, expanding viable feedstock pools for food-grade recyclate production.
- Polyethylene Terephthalate:Amorphous PET grades serve tray-lidding applications requiring dimensional stability and printability.
- Polylactic Acid:Bio-based polyester derived from corn starch or sugarcane supports home composting certifications under EN 13432.
- Cellulose Acetate:Wood-pulp-derived films from Mondi's captive fiber integration provide transparency and grease resistance for fresh produce.
- Polyvinyl Alcohol:Water-soluble barrier layers enable dishwasher-safe pod packaging with controlled dissolution rates.
Today's leader: Polyethylene. Tomorrow's challenger: Cellulose acetate.
Application:
Application-driven specifications create divergent margin tiers, with pharmaceutical sealing commanding premium pricing against commoditized food packaging volumes.
- Food Packaging:Dairy, meat, and ready-meal segments drive volume adoption as retail chains mandate circular packaging commitments. Vacuum-skin packaging conversion in Spain and Poland is retrofitting lines for recyclable top-web films, displacing legacy barrier webs.
- Pharmaceutical Sealing:Blister packs and medical device lidding demand oxygen transmission rates below 10 cc/m²/day. Mono-material barriers currently fail these specifications, preserving foil-laminate dominance in drug packaging.
- Cosmetic Containers:Premium skincare brands specify cellulose-based lidding for shelf differentiation and sustainability claims.
- Consumer Electronics:Anti-static films protect sensitive components during final assembly and distribution.
- Industrial Goods:Heavy-gauge lidding seals lubricant and chemical containers for bulk transport.
- Industrial Packaging:Palletized unit loads utilize stretch-lidding hybrids for weather protection.
Food packaging generates the volume base. Pharmaceutical sealing captures the margin premium.
End User:
Procurement sophistication varies sharply across end-user categories, with retail brands driving standardization while specialty converters preserve customization margins.
- Retail Brands:Supermarket private-label accounts in the United Kingdom and Ireland rewrite tender documents to exclude non-recyclable multi-web alternatives, forcing specification compliance across supplier bases.
- Contract Manufacturers:Co-manufacturers serving multiple brand owners prioritize mono-material compatibility to simplify inventory and avoid line-change penalties.
- Packagers:Independent packaging operations focus on seal-performance reliability and equipment compatibility.
- Specialty Converters:Niche players serving organic and premium segments experiment with polylactic acid and cellulose acetate formats.
- E-commerce Sellers:Direct-to-consumer brands prioritize lightweight films to minimize dimensional weight shipping charges.
- Bulk Distributors:Industrial supply houses emphasize cost-per-unit and availability over sustainability certifications.
Retail brands set the sustainability agenda. Contract manufacturers scale the operational execution.
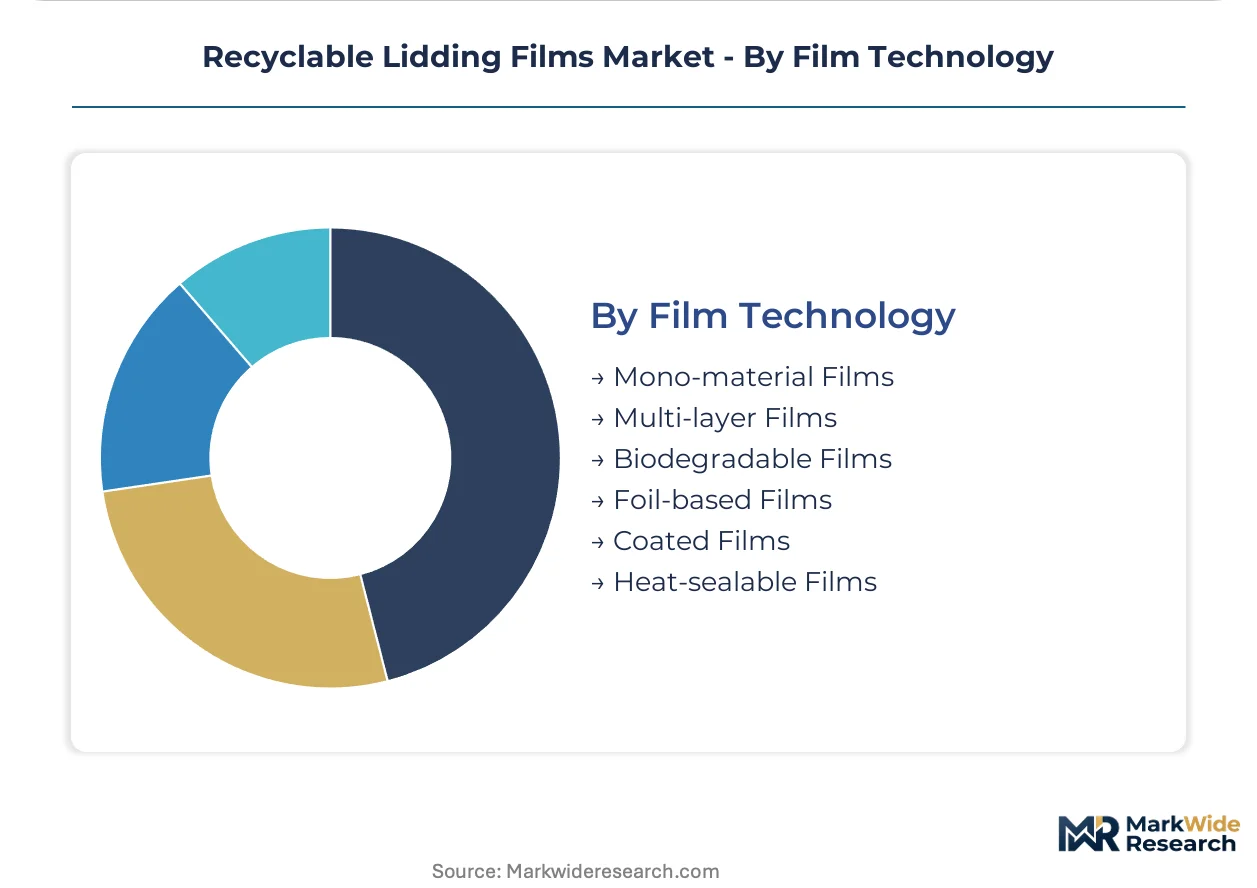
Film Technology:
Technology selection determines recyclability pathway eligibility, with mono-material constructions unlocking mechanical recycling streams that multi-layer alternatives cannot access.
- Mono-material Films:Single-substrate polyethylene or polypropylene constructions pass European sortation without adhesive contamination. ECHA REACH substance restrictions and EU Green Deal circularity targets are forcing converters to abandon incompatible multi-layer structures.
- Biodegradable Films:Composting certification under EN 13432 opens home-disposal pathways in markets with limited industrial composting infrastructure.
- Multi-layer Films:Coextruded barrier structures persist where oxygen or moisture protection exceeds mono-material capabilities.
- Foil-based Films:Aluminum laminates occupy narrowing pharmaceutical and premium food niches where barrier performance requirements currently exceed polymer alternatives.
- Coated Films:Solvent- and water-based coatings modify seal initiation temperatures and peel force characteristics.
- Heat-sealable Films:Engineered seal layers compatible with mono-material tray substrates enable hermetic closure without compromising recyclability.
Mono-material films own the regulatory tailwind. Biodegradable films claim the bio-based positioning advantage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where converters locate mono-material film production, as ECHA REACH compliance costs in Northwest Europe push mid-cap players toward Central European manufacturing zones with lower environmental overhead burdens.
Germany
Dairy processors in Bavaria and North Rhine-Westphalia specify polyethylene sealant layers to qualify for DSD fee reductions under the Packaging Act. ECHA substance restrictions on perfluorinated chemicals force converters in the Eindhoven-Düsseldorf corridor to reformulate heat-seal coatings. The DKR sorting consortium in Cologne now accepts 80-micron polypropylene lidding, expanding viable feedstock pools for food-grade recyclate.
France
Ready-meal brands in the Paris Basin rewrite tender documents to exclude non-recyclable multi-web alternatives under Citeo eco-modulation penalties. ANSM pharmaceutical packaging guidelines preserve foil-laminate dominance for blister packs where oxygen barriers below 10 cc/m²/day remain mandatory. The Lyon-Grenoble polymer cluster hosts pilot lines for ethylene vinyl alcohol coextrusion targeting 120-day cheese shelf life specifications.
Italy
Meat processors in Emilia-Romagna retrofit vacuum-skin packaging lines for recyclable top-web films, displacing legacy barrier webs. COREPLA sorting infrastructure upgrades in Milan and Bologna now process polypropylene lidding films into food-grade recyclate streams. The Bologna-Turin industrial corridor concentrates cellulose acetate development for fresh produce applications requiring grease resistance.
Netherlands
Pyrolysis partnerships between converters and petrochemical majors in Rotterdam and Antwerp aim to unlock food-grade polypropylene from mixed flexible waste streams. The Port of Rotterdam chemical recycling hub attracts film producers seeking alternative feedstock pathways beyond mechanical recycling limitations. Wageningen University research clusters support EN 13432 composting certification trials for polylactic acid formulations.
Spain
Meat packagers in Catalonia and the Basque Country accelerate vacuum-skin packaging conversion to meet retailer circular packaging commitments. Spanish dairy cooperatives in Galicia trial polyethylene-based mono-material structures for export cheese shipments to German retail accounts. The Barcelona polymer technology cluster develops digital watermark integration for AI-driven sortation compatibility.
Recyclable Lidding Films Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational converters anchoring premium-tier accounts through subscription-based technical service contracts while regional players compete on spot pricing for standard-grade volumes. The vendor base organizes around three strategic archetypes: integrated petrochemical-to-film producers with captive resin supply, independent converters relying on merchant resin markets, and equipment-anchored specialists bundling film specifications with machinery placements. Dominant competitive moves include backward integration into resin compounding to secure mono-material formulation control, and geographic expansion into Central European manufacturing zones to arbitrage ECHA compliance cost differentials.
Among integrated packaging conglomerates, Amcor and Mondi exemplify divergent strategic positioning within the premium tier. Amcor leverages its global laboratory network to anchor subscription-based service models across European dairy and ready-meal accounts. Mondi competes through captive pulp and paper integration that sustains cost advantages in cellulose-based lidding formats. Sealed Air occupies a distinct equipment-anchored position, controlling proprietary vacuum-skin machinery placements that lock in film specification decisions at meat packagers.
| Leading Market Players |
|---|
| Amcor |
| Berry Global |
| Mondi |
| Huhtamaki |
| Winpak |
| Sealed Air |
| Uflex |
| Toray Plastics |
| Plastopil Hazorea |
| Others |
Pricing and Supply Chain Analysis
Captive resin compounding through backward integration into polyethylene and polypropylene feedstocks anchors both supply security and pricing power for Northwest European film converters facing ECHA REACH compliance cost escalation. This integration choice insulates integrated producers from naphtha-cracker margin volatility while forcing merchant-resin-dependent competitors into fixed-price annual contracts that compress margins during feedstock price spikes.
Pricing Analysis
Retailer markup layers in private-label dairy and ready-meal accounts dominate pricing architecture, with subscription-based technical service contracts displacing per-unit transactional models at major food manufacturers. Price differentiation separates EN 13432 composting-certified cellulose acetate tiers from standard polyethylene grades, with vacuum-skin packaging specifications commanding premiums for seal-performance guarantees. Cost compression in commodity mono-material polyethylene is intensifying because Citeo eco-modulation fee reductions reward recyclability compliance that mid-size converters struggle to achieve. Contract manufacturers serving multiple brand owners exhibit highest price sensitivity due to inventory simplification mandates, while pharmaceutical blister packagers remain least sensitive given barrier performance floors that preserve foil-laminate dominance.
Supply Chain Analysis
Freight cost differentials between Rotterdam-Antwerp chemical recycling hubs and Central European manufacturing zones are reshaping production location decisions for mid-cap converters seeking ECHA compliance arbitrage. Supply concentrates in Germany, France, and the Netherlands, with resin feedstock drawing from Northwest European petrochemical complexes and cellulose pulp anchored in Nordic fiber markets. Single-source vulnerability persists in ethylene vinyl alcohol coextrusion equipment where German and Italian machinery suppliers control specification lock-in. Distribution runs through converter-direct relationships with dairy processors and meat packagers, bypassing traditional distributor layers for technical service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between ECHA REACH compliance costs in Northwest Europe and lower environmental overhead in Central European manufacturing zones creates relocation incentives for mid-cap converters seeking margin preservation.
For Market Incumbents: Anchor specification positions at major retail private-label accounts through captive laboratory networks that bundle seal-performance testing with regulatory documentation subscriptions. Backward integration into resin compounding secures mono-material formulation control against merchant-resin price volatility. Capacity addition in Poland and Czech Republic manufacturing corridors captures ECHA compliance cost differentials while maintaining EU market access. For New Entrants and Emerging Players: Equipment-anchored partnerships with vacuum-skin packaging machinery suppliers offer the most penetrable entry path into Spanish and Polish meat processing accounts seeking retrofit compatibility guarantees. Specialty converters serving organic and premium segments present white-space opportunity in cellulose acetate formats where Mondi's captive fiber integration has not fully saturated niche demand. Go-to-market execution should prioritize EN 13432 composting certification pre-investment to differentiate against commodity polyethylene incumbents. For Investors and Strategic Acquirers: Roll-up economics work for regional mono-material specialists because EFSA food contact approval timelines create 18-24 month barriers that deter new facility investment and consolidate viable target pools. Long-term viability over the coming decade hinges on chemical recycling partnership access that unlocks food-grade polypropylene from mixed flexible waste streams. Watch pyrolysis scale-up announcements from Rotterdam and Antwerp petrochemical majors as the inflection signal for mechanical recycling limitation resolution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polyethylene formulation control insulates converters from naphtha-cracker margin volatility in Northwest Europe. |
| Geographic Expansion into Central Europe | Poland and Czech Republic manufacturing corridors offer ECHA REACH compliance cost arbitrage for mid-cap players. |
| Digital Watermark Integration | AIM-Digimarc tracer technologies enable AI-driven sortation premium pricing at German and French retail accounts. |
| Chemical Recycling Partnership Formation | Pyrolysis alliances with Rotterdam petrochemical majors unlock food-grade polypropylene from mixed flexible waste. |
| Subscription Service Model Conversion | Recurring technical service contracts displace transactional supply relationships at UK and Irish retail chains. |
Research Methodology
Bottom-up food packaging application modeling reconciled against top-down converter capacity tracking forms the analytical core of this study. Primary interviews with polymer scientists at film converters, procurement leads at dairy and meat processors, sustainability directors at retail chains, and equipment specialists at vacuum-skin packaging machinery suppliers combined with secondary validation from ECHA REACH substance restriction databases, EFSA food contact material approval filings, and Citeo eco-modulation fee schedules. Top-down triangulation against customs data on polyethylene and polypropylene resin trade flows and COREPLA sorting infrastructure investment disclosures verified volume assumptions.
Input-output matrices mapping resin feedstock availability to converter extrusion capacity and downstream food manufacturer specification requirements generated volume and value outputs across the projection horizon. Segmentation dimensions modeled include material type, application shelf-life requirement, end-user procurement sophistication tier, and film technology recyclability pathway eligibility. CAGRs derived from elasticity-adjusted demand curves incorporating EPR scheme penalty structures and mechanical recycling infrastructure upgrade timelines. Forecast inputs included ethylene feedstock price volatility scenarios and EFSA migration testing approval queue projections.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to chemical recycling scale-up velocity and EU Green Deal packaging waste regulation enforcement timing. Forecasts reflect documented assumptions about resin substitution elasticity and retail chain sustainability commitment durability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Global Polyethylene Packaging Market
Poly film
PVC Film for Medical Market
Poly film
Polycarbonate Films Market
Poly film
China BOPP Film Market
Poly film
Bundling Film Market
Poly film
Asia Pacific Plastic Packaging Film Market
Poly film
Twist Wrap Film Market
Poly film
Surface Printed Film Market
Poly film
Polytetrafluoroethylene (PTFE) Films Market
Poly film
Shrink Bundling Films Market
Poly film
Cast Stretch Packaging Films Market
Poly film
PVC Films Market
Poly film
North America BOPP Films Market
Poly film
Global Fluoropolymer Films Market
Poly film
Global Sound Insulation PVB Film Market
Poly film
EVOH Encapsulation Film Market