
 Global Stretch Films Market | 2026-2036
Global Stretch Films Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stretch Films Market Intelligence
Capital-intensity divergence between blown film extrusion specialists and cast film volume producers is unwinding competitive stability across the Global Stretch Films Market. Sealed Air Corporation leverages its integrated equipment-film systems to sustain premium positioning in automated pallet wrapping. Berry Global Group anchors North American supply through multi-site blown film capacity. Polifilm GmbH specializes in high-clarity agricultural films for European produce distribution.
Stretch films are elastic polymer membranes, typically 12–35 microns thick, manufactured through cast or blown extrusion of linear low-density polyethylene with metallocene additives to achieve controlled cling and puncture resistance. Their primary purpose is unitizing palletized loads to prevent shifting during transit and reduce product damage across supply chains. Cast stretch films dominate high-speed automated lines due to superior optical clarity and consistent gauge, while pre-stretched films capture growing share among manual wrapping operations seeking reduced material consumption. Blown films retain structural preference for irregular loads in industrial packaging where puncture resistance commands premium positioning.
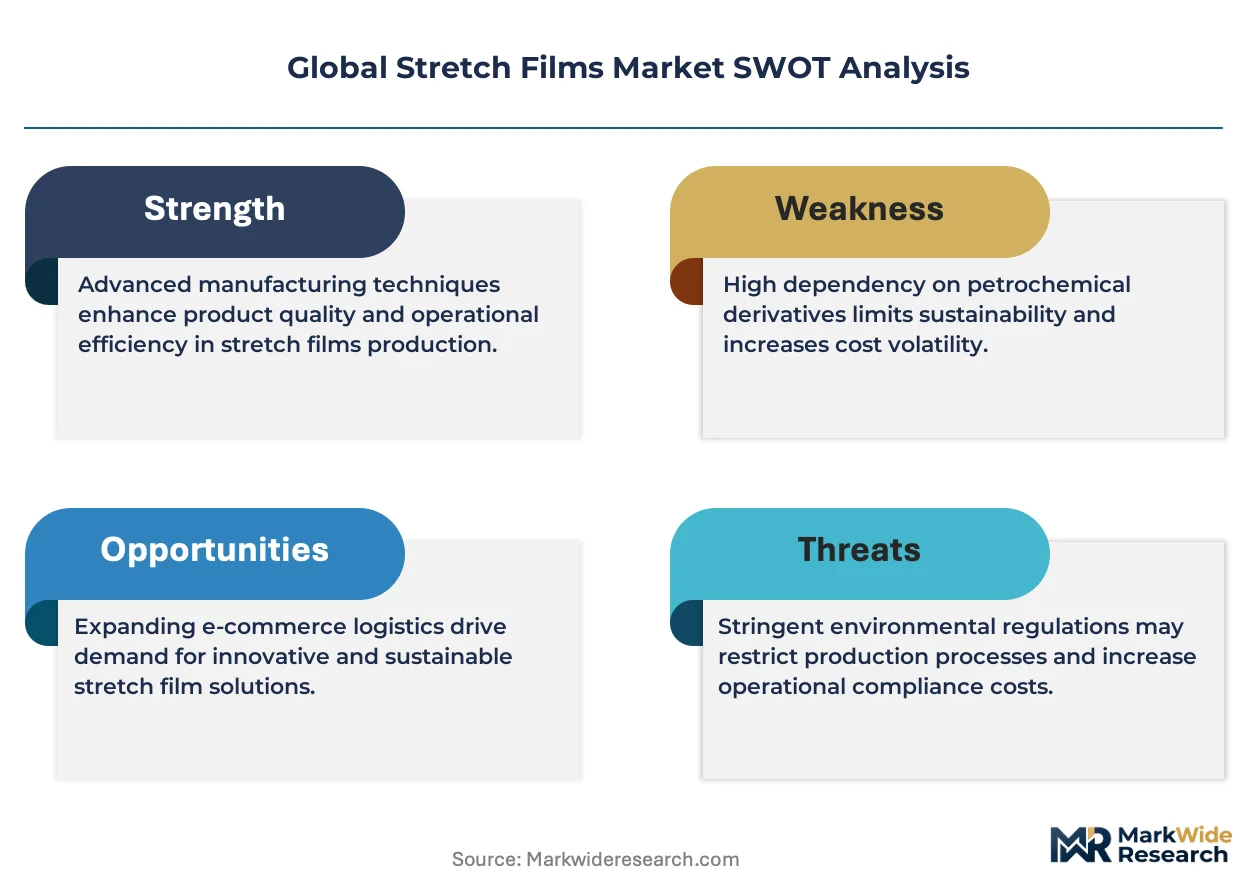
FDA food-contact regulations, EPA resin identification standards, and REACH substance restrictions collectively shape formulation choices and regional market access for stretch film producers. The EU Green Deal's packaging waste directives are accelerating migration toward mono-material, recyclable structures that complicate legacy multi-layer product lines. Stakeholders must monitor evolving extended producer responsibility schemes and resin recycling infrastructure investments to align capacity planning with compliance timelines.
Market Dynamics
The Global Stretch Films Market faces a structural squeeze between resin cost volatility and the EU Green Deal's mono-material mandates, forcing converters to reformulate legacy multi-layer products while defending margin positions against thinner-gauge competition.
Growth Catalysts
- REACH compliance migration:European converters are accelerating adoption of metallocene-catalyzed polyethylene formulations to meet ECHA substance restrictions while maintaining cling performance.
- E-commerce fulfillment expansion:Automated pallet wrapping demand from third-party logistics operators in Germany's Rhine-Ruhr corridor is pulling high-clarity cast film volumes.
- Pre-stretched film technology:Manual wrapping operations in China's Pearl River Delta manufacturing clusters are switching to pre-stretched films to reduce material consumption per pallet.
Market Restraints
- LLDPE resin price volatility:Ethylene feedstock costs tied to naphtha cracking economics in Middle Eastern supply hubs create margin compression for non-integrated extruders.
- Blown film capacity concentration:North American blown film supply concentrates among multi-site producers with backward integration into resin production, limiting new entrant access.
- Mechanical recycling contamination:Legacy multi-layer structures with EVA cling layers complicate mechanical reprocessing under EPA resin identification standards.
Strategic Opportunities
- India's cold chain infrastructure:Food processing corridors around Pune and Bengaluru are underpenetrated for agricultural stretch film applications in produce distribution.
- Chemical recycling partnerships:Pyrolysis-based feedstock recovery is enabling circular polyethylene claims for premium brand owners seeking ESG-aligned packaging.
- Direct-to-film digital printing:Convergence of inkjet deposition and cast film extrusion is opening branded unitization for consumer goods exporters.
Industry Challenges
- Metallocene catalyst procurement:Specialized co-monomer expertise sits with a narrow supplier base, creating formulation bottlenecks for mid-cap converters.
- ISO 9001 certification timelines:Extended audit cycles for food-contact manufacturing facilities are delaying market access for new production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stretch Films Market |
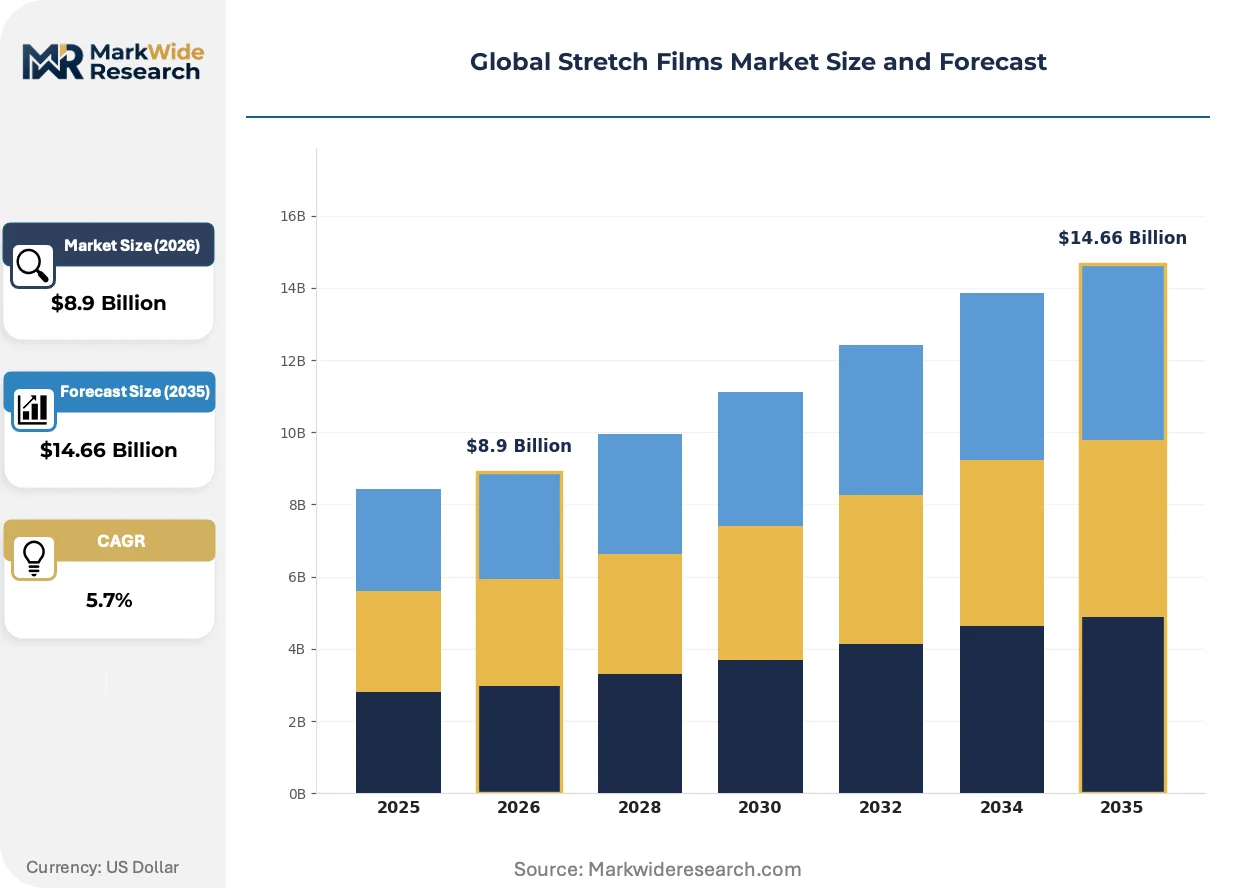
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $14.66 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cast Stretch Films, Blown Stretch Films, Colored Stretch Films, Pre-Stretched Films Application: Pallet Wrapping, Bundle Wrapping, Product Wrapping, Agricultural Use, Industrial Packaging End User: Logistics Companies, Packaging Manufacturers, Food & Beverage Producers, Textile Suppliers, Chemical Plants Distribution Channel: Direct Sales, Distributors, E-commerce Platforms, Wholesale, Retailers |
| Companies Covered | Sealed Air Corporation, Sigma Plastics Group, Berry Global Group, Inc., AEP Industries Inc., Intertape Polymer Group Inc., Amcor plc, Dow Inc., Polifilm GmbH, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stretch Films Market Strategic Shifts & Innovations
Active reformulation of stretch film architectures is compressing legacy product lifecycles, with regulatory chemistry restrictions and equipment-film system integration demanding simultaneous technical pivots across formulation and application engineering.
Machine-direction oriented (MDO) cast films with controlled pre-stretch ratios are fragmenting the conventional cast-blown segmentation. High-speed automated lines in German automotive parts distribution centers are adopting MDO films for consistent load containment at reduced gauge. This technology is fragmenting supplier portfolios as equipment OEMs bundle film specifications with wrapping machinery contracts.
The EU Green Deal's packaging waste directive is mandating mono-material recyclability for pallet wrap entering European distribution networks. Formulators are stripping EVA and polyisobutylene cling additives from legacy recipes to achieve HDPE stream compatibility. Blown film specialists serving French retail logistics are most affected, accelerating trials of ionomer-based cling surfaces.
Consolidated buying by multinational third-party logistics operators is compressing supplier switching cycles and unbundling film procurement from equipment leases. Amazon's European fulfillment network now sources stretch films through centralized tenders separate from wrapping machinery contracts. This pattern is most visible in the Netherlands and Belgium, where Antwerp-Rotterdam port logistics clusters have standardized on annual film procurement auctions.
Global Stretch Films Market Segmentation
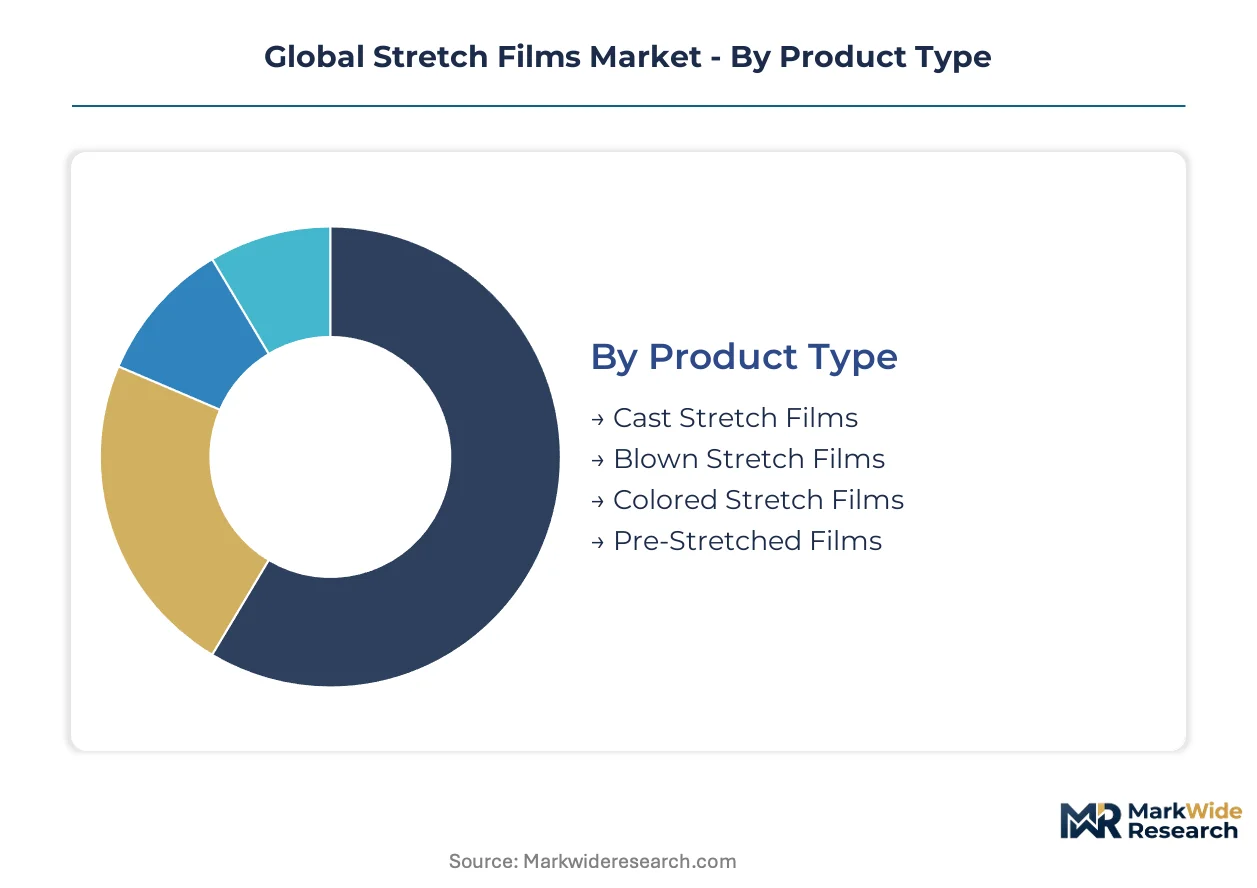
Stretch film procurement patterns diverge sharply between high-volume automated operations and fragmented manual wrapping environments. Equipment integration requirements and regulatory compliance timelines reshape how converters align product portfolios with end-use specifications across export manufacturing corridors.
Product Type:
Cast stretch films dominate export-led demand from China's Pearl River Delta manufacturing clusters, while blown films anchor domestic industrial applications in Germany's automotive parts distribution network.
- Cast Stretch Films:Manufactured through flat-die extrusion with rapid quenching on chilled rolls, delivering superior optical clarity and gauge consistency for automated pallet wrapping lines. Demand concentrates in Germany's Rhine-Ruhr logistics corridor where third-party logistics operators require high-speed compatibility with orbital wrapping equipment.
- Blown Stretch Films:Produced via tubular bubble extrusion with biaxial orientation, yielding puncture-resistant membranes with superior load containment for irregular industrial shipments. Domestic consumption dominates North American heavy manufacturing where backward-integrated resin producers supply multi-site blown film capacity.
- Colored Stretch Films:Pigmented LLDPE formulations enable load identification and tamper-evidence for pharmaceutical distribution in India's Pune pharmaceutical cluster.
- Pre-Stretched Films:Machine-direction oriented films with controlled elongation ratios reduce material consumption per pallet in manual wrapping operations across China's Dongguan export manufacturing belt.
Cast stretch films command the established base. The steepest expansion runs through pre-stretched films.
Application:
Cost-tier segmentation separates high-frequency automated pallet operations from intermittent manual wrapping workflows with divergent equipment investment thresholds.
- Pallet Wrapping:Unitization of palletized loads through spiral or orbital application methods, representing the core volume driver for cast film consumption. E-commerce fulfillment expansion in Belgium's Antwerp-Rotterdam port logistics cluster pulls high-clarity formulations for automated lines.
- Bundle Wrapping:Aggregation of individual items into stable handling units for retail distribution, requiring lower gauge films with controlled cling. Agricultural produce distribution across France's retail logistics networks drives specification for ionomer-based cling surfaces compliant with EU Green Deal mono-material mandates.
- Product Wrapping:Individual item protection for consumer goods exports from Shenzhen manufacturing corridors, leveraging direct-to-film digital printing for branded unitization.
- Agricultural Use:Silage and haylage wrapping for European dairy operations, with Polifilm GmbH specializing in high-clarity formulations for produce distribution.
- Industrial Packaging:Heavy-load containment for chemical and construction materials where puncture resistance commands premium positioning in North American supply chains.
Pallet wrapping captures the volume anchor. Agricultural use climbs the fastest as India's cold chain infrastructure expands around Bengaluru food processing corridors.
End User:
Customer-type concentration varies between consolidated multinational procurement and fragmented regional converter relationships.
- Logistics Companies:Third-party operators in Germany's Rhine-Ruhr corridor and Netherlands-Belgium port clusters driving automated wrapping equipment-film system integration. Amazon's European fulfillment network sources through centralized tenders separate from machinery contracts.
- Packaging Manufacturers:Regional converters serving downstream brand owners with customized formulations for food-contact compliance under FDA and REACH substance restrictions.
- Food & Beverage Producers:Cold chain participants requiring FDA-compliant films for direct food contact in India's emerging Pune processing infrastructure.
- Textile Suppliers:Export-oriented manufacturers in China's Dongguan cluster utilizing colored films for shipment identification.
- Chemical Plants:Industrial bulk shippers specifying blown film puncture resistance for hazardous material containment under EPA resin identification standards.
Logistics companies concentrate procurement leverage. Food and beverage producers gain share fastest as India's cold chain infrastructure matures.
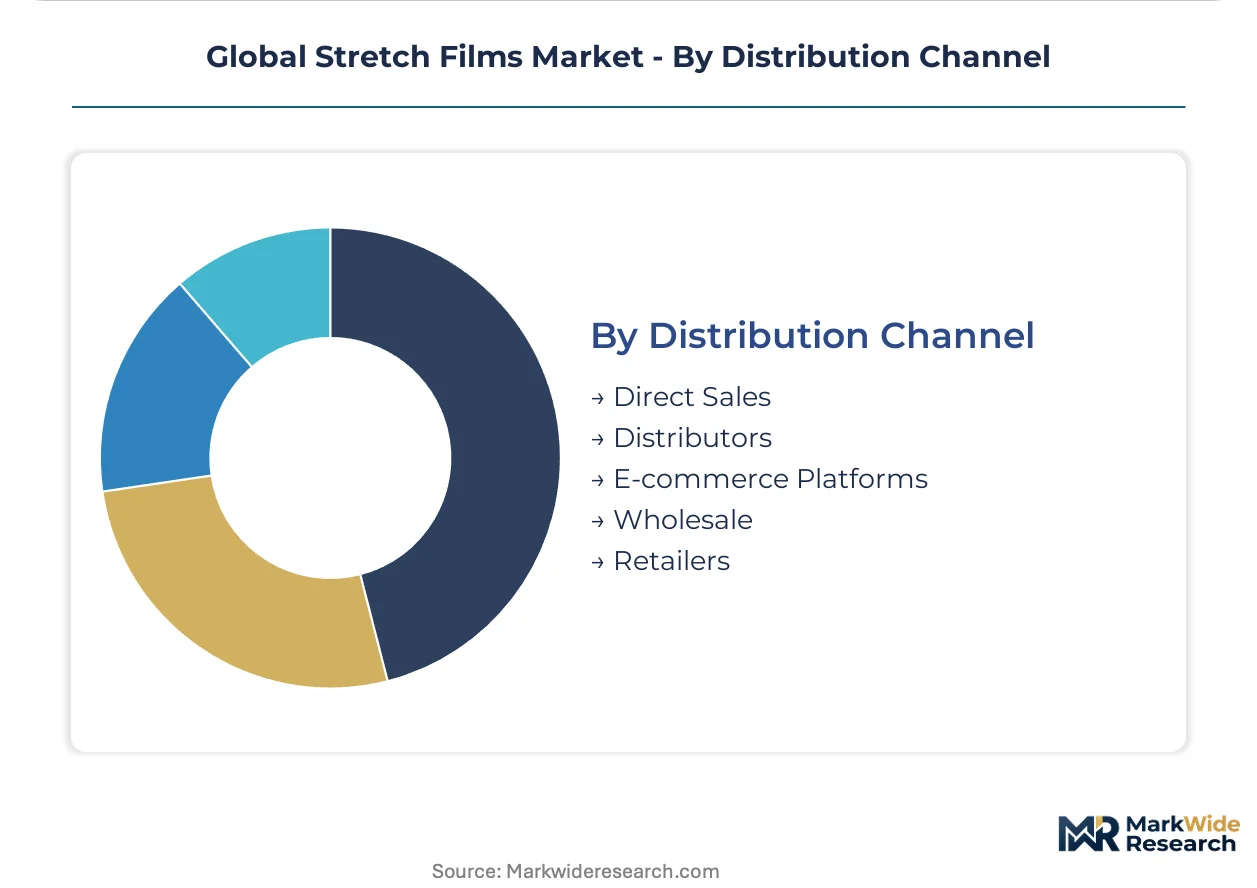
Distribution Channel:
Supply concentration patterns favor direct relationships with high-volume automated operators while distributors serve fragmented manual wrapping demand.
- Direct Sales:Equipment OEMs bundle film specifications with wrapping machinery contracts for German automotive parts distribution centers adopting MDO cast films.
- Distributors:Regional inventory positioning serves mid-cap converters lacking metallocene catalyst procurement relationships with narrow supplier bases.
- E-commerce Platforms:Emerging procurement channel for small-volume manual wrapping operations in China's Pearl River Delta manufacturing clusters.
- Wholesale:Volume aggregation for retail logistics standardization across Netherlands-Belgium port clusters with annual film procurement auctions.
- Retailers:Point-of-sale access for agricultural producers in European dairy regions with seasonal demand spikes.
Direct sales anchor high-value relationships. E-commerce platforms expand most quickly among small-scale manual wrapping operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's export manufacturing clusters demonstrate acute price sensitivity to resin fluctuations, while German logistics operators absorb premium pricing for equipment-integrated film systems. India's emerging cold chain infrastructure sits at the elasticity midpoint, balancing cost pressures against compliance investments.
United States
Heavy manufacturing and automotive parts distribution drive blown film consumption across the Midwest industrial corridor. EPA resin identification standards complicate mechanical recycling of legacy multi-layer structures. Chicago and Detroit logistics hubs specify puncture-resistant formulations for irregular industrial shipments.
Germany
Rhine-Ruhr third-party logistics operators pull high-clarity cast films for automated pallet wrapping lines. EU Green Deal packaging waste directives mandate mono-material recyclability for pallet wrap entering European distribution networks. Dortmund and Düsseldorf distribution centers are standardizing on annual film procurement auctions separate from equipment contracts.
China
Pearl River Delta export manufacturing corridors around Shenzhen and Dongguan concentrate demand for pre-stretched films in manual wrapping operations. The country's dual carbon goals pressure converters toward thinner-gauge formulations. Dongguan textile suppliers utilize colored films for shipment identification to European and North American markets.
India
Food processing corridors around Pune and Bengaluru are underpenetrated for agricultural stretch film applications in produce distribution. FSSAI food-contact regulations shape formulation choices for cold chain participants. Bengaluru's emerging cold chain infrastructure is expanding film specification for dairy and pharmaceutical distribution.
Netherlands
Antwerp-Rotterdam port logistics clusters have standardized on centralized film procurement through annual tenders. REACH substance restrictions accelerate adoption of metallocene-catalyzed polyethylene formulations. Rotterdam's automated container handling facilities specify high-speed compatible cast films for transhipment operations.
Global Stretch Films Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with backward-integrated resin producers commanding supply security while mid-cap converters face formulation bottlenecks. The upper tier leverages captive ethylene supply and multi-site extrusion networks to defend margin positions against resin volatility. Three archetypes dominate: equipment-film system integrators, blown film capacity aggregators, and regional agricultural specialists. Competitive moves concentrate on strategic partnerships for chemical recycling feedstock and geographic expansion into India's cold chain infrastructure.
Within the integrated systems tier, Sealed Air Corporation and Berry Global Group occupy positions that exemplify equipment-film convergence and multi-site capacity aggregation respectively. Polifilm GmbH represents the specialist archetype, with its German corporate structure signaling European agricultural film expertise. These three anchors illustrate how competitive positioning fragments across system integration, scale-driven supply security, and application-specific formulation depth.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Sigma Plastics Group |
| Berry Global Group, Inc. |
| AEP Industries Inc. |
| Intertape Polymer Group Inc. |
| Amcor plc |
| Dow Inc. |
| Polifilm GmbH |
| Mondi Group |
| Others |
Cost & Logistics Intelligence
Sixty-day resin inventory buffers at German logistics hubs concentrate pricing power with backward-integrated extruders while forcing non-integrated converters into thinner-gauge competition. This inventory-lead structure ties cost pass-through capability directly to captive ethylene supply positions across European distribution networks.
Pricing Analysis
After-sales service contracts for wrapping equipment maintenance drive lifetime value beyond film unit sales. Three-tier pricing structure across premium, standard, and economy levels separates equipment-integrated system providers from commodity resin converters and regional distributors. Price differentiation hinges on metallocene formulation certification and volume scale commitments from multinational logistics operators. Cost compression in standard-grade cast films is intensifying because Chinese export manufacturers demand thinner gauges with equivalent load containment.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for Middle Eastern ethylene derivatives. Manufacturing gravity draws from Germany, China, and the United States as the dominant extrusion hubs. Raw material feeds rest on LLDPE resin, metallocene catalysts, and ionomer cling additives. Single-source vulnerability concentrates in metallocene co-monomer expertise held by narrow supplier bases. Distribution runs through direct equipment OEM bundling for automated operations and regional distributors for fragmented manual wrapping demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment service contracts and chemical recycling feedstock partnerships expand recurring revenue faster than virgin resin sales. This service-attach dynamic repositions film converters toward circular economy participation beyond commodity supply.
For Market Incumbents: Fortify backward integration into resin production to defend margin positions against naphtha-cracking cost volatility. Deepen equipment-film system bundling for German automotive parts distribution centers to lock out specialist competitors. Prioritize ISO 9001 certification investments for food-contact manufacturing lines to accelerate market access timelines. For New Entrants and Emerging Players: Differentiate on chemical recycling partnerships enabling circular polyethylene claims for ESG-aligned brand owners. Target India's Pune and Bengaluru food processing corridors where cold chain infrastructure remains underpenetrated for agricultural film applications. Pursue direct-to-film digital printing capabilities to capture branded unitization demand from Shenzhen consumer goods exporters. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with non-core stretch film assets lacking metallocene formulation depth. Long-term viability centers on circular economy positioning and geographic exposure to India's cold chain buildout. Monitor chemical recycling infrastructure investment announcements as inflection indicators for premium pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Supply | Captive resin production insulates margins from naphtha-cracking volatility in Middle Eastern supply hubs. |
| Chemical Recycling Partnership | Pyrolysis-based feedstock recovery enables circular polyethylene claims under EU Green Deal compliance timelines. |
| Equipment-Film System Bundling | Integrated wrapping machinery contracts lock in premium positioning with German Rhine-Ruhr logistics operators. |
| Pre-Stretched Film Capacity Addition | Machine-direction orientation technology captures material-reduction demand from China's Dongguan manufacturing belt. |
| Direct-to-Film Digital Printing | Inkjet deposition convergence opens branded unitization for consumer goods exporters in Shenzhen corridors. |
Research Approach
The analysis maps cast film extrusion, blown film production, pre-stretched technology, and agricultural formulations, each validated through plant managers, procurement leads at downstream logistics operators, distribution channel partners, and technical R&D directors. Primary fieldwork combined with customs trade data, SEC filings from integrated resin producers, European Chemicals Agency substance restriction updates, and industry association capacity surveys. Bottom-up volume triangulation against top-down resin consumption estimates anchored regional demand splits.
Consistency checks validated outputs against external benchmarks across the analysis window. Segmentation dimensions modeled include product architecture, application intensity, end-user procurement scale, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating equipment penetration rates and compliance-driven reformulation timelines. Forecast inputs included ethylene feedstock cost trajectories and extended producer responsibility scheme implementation schedules.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or abrupt resin supply disruptions would require recalibration. Forecasts reflect documented assumptions regarding metallocene catalyst availability and mechanical recycling infrastructure scaling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Plastic Tubes Market
Plastic Packaging
India Plastic Bottles Market
Plastic Packaging
Rewritable PVC Cards Market
Plastic Packaging
MENA Thermoform Plastic Packaging Market
Plastic Packaging
PCR Bottles Market
Plastic Packaging
Australia and New Zealand Plastic Bottles Market
Plastic Packaging
Canada Plastic Packaging Market
Plastic Packaging
UVI Stretch Films Market
Plastic Packaging
United Kingdom Plastic Packaging Market
Plastic Packaging
Nigeria Plastic Bottles Market
Plastic Packaging
South Africa Rigid Plastic Packaging Market
Plastic Packaging
Vietnam Plastic Bottles Market
Plastic Packaging
Plastic-Free Packs Market
Plastic Packaging
Plastic Medicine Bottles Market
Plastic Packaging
North America Single-Use Plastic Packaging Market
Plastic Packaging
Recycled Plastic Envelope Market