
 Printable Solar Cells Market | 2026-2036
Printable Solar Cells Market Size, Share, and Industry Trends Forecast 2026-2036
Printable Solar Cells Market Intelligence
Asset-light business models using contract printing facilities is tilting the competitive field toward materials specialists over capital-heavy incumbents. DuPont de Nemours, Inc. leverages its polymer science expertise to supply specialized inks and substrates. This approach contrasts with JinkoSolar Holding Co., Ltd., which maintains control over its photovoltaic component supply. Meanwhile, InfinityPV ApS specializes in roll-to-roll production, targeting flexible solar applications.
Printable solar cells are photovoltaic devices fabricated by depositing layers of semiconductor inks onto various substrates using scalable printing methods. The technology commonly utilizes materials like organic polymers or perovskite crystals to convert light into electricity, often on flexible or transparent surfaces. Among technologies, perovskite cells exhibit the highest growth potential due to rapid advances in power conversion efficiency. Demand from building-integrated photovoltaics and wearable electronics applications steers innovation toward flexible sheet and transparent film form factors.
European Union RoHS directives place strict limitations on hazardous materials, influencing perovskite cell chemistry. Incentive programs in China and the US, supported by agencies like the MEE and EPA, encourage domestic renewable technology development. Global market access hinges on adherence to IEC standards for performance, safety, and reliability testing. Scaling production while navigating evolving material regulations remains the central strategic challenge for manufacturers.
Market Dynamics
The central force shaping the market is the decoupling of material science from capital-intensive manufacturing. This shift allows specialized chemical and polymer firms to innovate on inks and substrates, while contract printing facilities handle scalable production, lowering market entry barriers.
Growth Catalysts
- National Industrial Policies:China's strategic prioritization of advanced solar manufacturing, supported by national policies from bodies like the MEE, provides significant investment and demand-side pull for domestic producers, creating a large-scale proving ground for the technology.
- Building-Integrated Photovoltaics (BIPV):Demand from the architecture and construction sectors for aesthetically integrated, flexible, and lightweight solar solutions on building facades, windows, and roofing materials is a primary application driver.
- Material Efficiency Gains:Continuous improvements in the power conversion efficiency and stability of perovskite and organic polymer materials are making printable cells a viable alternative to conventional silicon in a growing number of applications.
Market Restraints
- Material Stability and Longevity:Perovskite and organic solar cells exhibit shorter operational lifespans and higher degradation rates when exposed to moisture and oxygen compared to silicon, limiting their use in long-term, harsh-environment applications.
- Hazardous Material Content:The use of lead in many high-efficiency perovskite formulations creates regulatory friction, particularly with directives like the European Union's RoHS, which restricts hazardous substances in electronic equipment.
- High-Cost Specialized Inputs:The cost of high-purity semiconductor inks, specialized conductive pastes, and high-performance flexible substrates remains a significant barrier to achieving cost parity with mass-produced conventional solar panels.
Strategic Opportunities
- Wearable and IoT Device Integration:The market for low-power electronics, including wearable sensors, smart labels, and remote IoT devices, presents a significant opportunity for lightweight, flexible power sources that can be integrated directly into product designs.
- Incentive-Driven Domestic Production:Government programs like the US Inflation Reduction Act (IRA) offer tax credits and incentives for domestic manufacturing of renewable energy components, creating an opportunity to establish localized supply chains.
- Transparent Solar Films:Developing highly transparent printable cells opens opportunities for energy-harvesting windows and displays in buildings and vehicles, a segment where conventional opaque solar panels cannot compete.
Industry Challenges
- Scaling Roll-to-Roll Production:Transitioning complex, multi-layer cell architectures from laboratory-scale coating methods to high-speed, high-yield commercial roll-to-roll printing remains a significant engineering and quality control challenge.
- Standardization and Bankability:Establishing industry-wide performance, reliability, and safety standards, such as those governed by the IEC, is essential for securing project financing and achieving broad market acceptance, especially in utility-scale applications.
- Specialized Talent Scarcity:The field requires a multidisciplinary workforce with expertise in materials science, chemistry, printing technology, and photovoltaic engineering, and a shortage of such cross-functional talent can slow innovation and production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Printable Solar Cells Market |
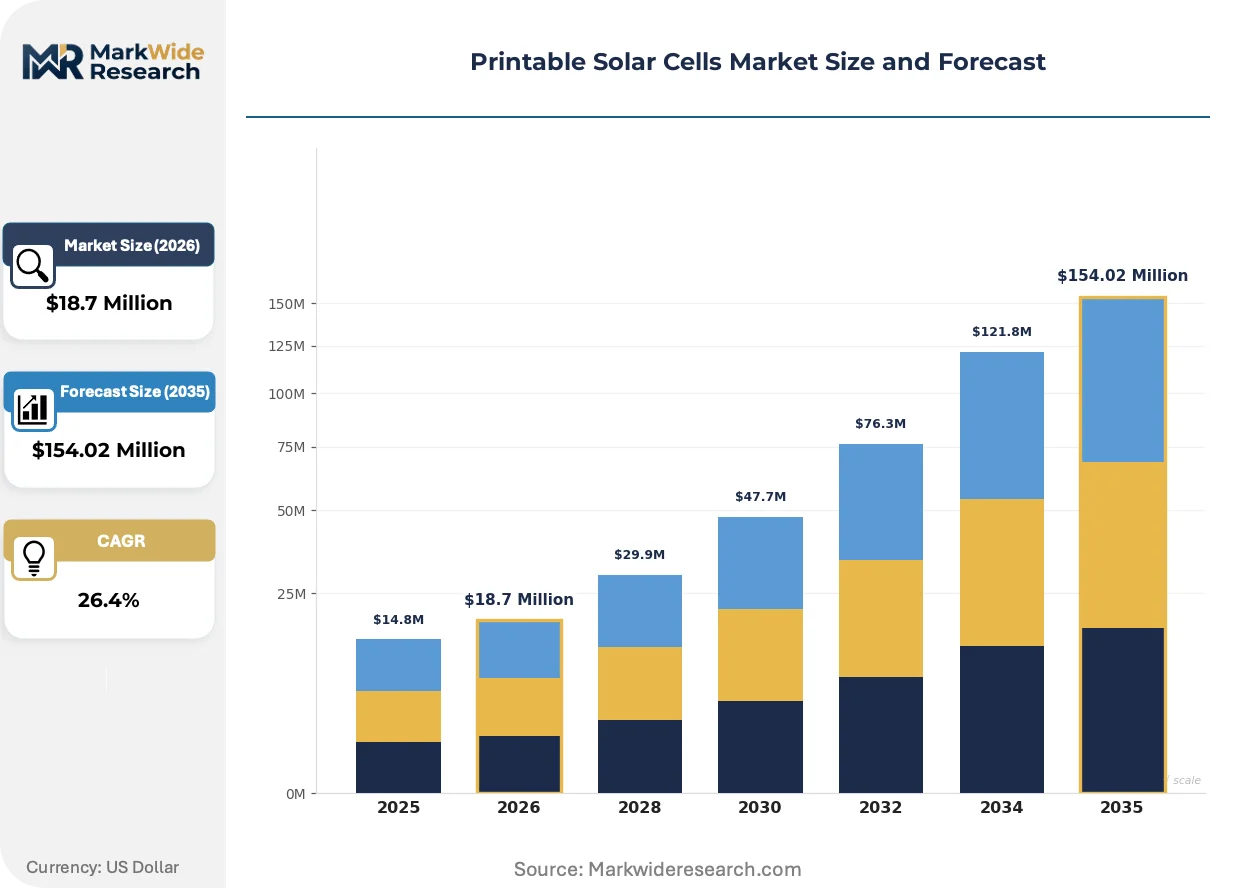
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $154.02 Million |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Organic Photovoltaics, Perovskite Cells, Dye-Sensitized Cells, Quantum Dot Cells, Thin-Film Cells Application: Wearable Electronics, Building-Integrated Photovoltaics, Portable Chargers, Agrivoltaics, Remote Sensors Form Factor: Flexible Sheets, Rigid Panels, Transparent Films, Roll-to-Roll Modules, Laminated Layers End User: Electronics Manufacturers, Construction Firms, Agricultural Operators, Defense Agencies, Research Institutions |
| Companies Covered | Nanosolar Corporation, InfinityPV ApS, DuPont de Nemours, Inc., Triton Solar LLC, JinkoSolar Holding Co., Ltd., JA Solar Technology Co., Ltd., Trina Solar Co., Ltd., LONGi Green Energy Technology Co., Ltd., Canadian Solar Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Printable Solar Cells Market Strategic Shifts & Innovations
Innovation is centered on material formulation and process optimization, aiming to balance power conversion efficiency with operational stability and manufacturing cost. This effort is moving the technology from niche applications toward broader integration in consumer electronics and the built environment.
Roll-to-roll printing technology allows for the continuous, high-speed fabrication of solar cells on flexible substrates. Flexible electronics and smart packaging manufacturers are the primary adopters of this production method. This process is digitizing photovoltaic manufacturing, replacing the discrete, batch-based wafer handling of conventional silicon cell production with a continuous, data-driven workflow that enables mass customization.
The European Union's RoHS directive directly influences material science research within the printable solar sector. It forces manufacturers to invest in R&D for lead-free perovskite alternatives or develop encapsulation methods robust enough to prevent any potential lead leakage over the product's lifetime. Perovskite cell developers are most affected, accelerating work on tin-based and other alternative chemistries to ensure market access in Europe.
A notable shift in purchasing behavior involves architects and product designers specifying integrated power sources early in the design phase. This disrupts the traditional model of retrofitting standard solar panels, favoring instead direct collaboration with building material suppliers or electronics designers. This trend is most visible in the building-integrated photovoltaics (BIPV) and high-end consumer electronics sectors, where aesthetics and form factor are paramount.
Printable Solar Cells Market Segmentation
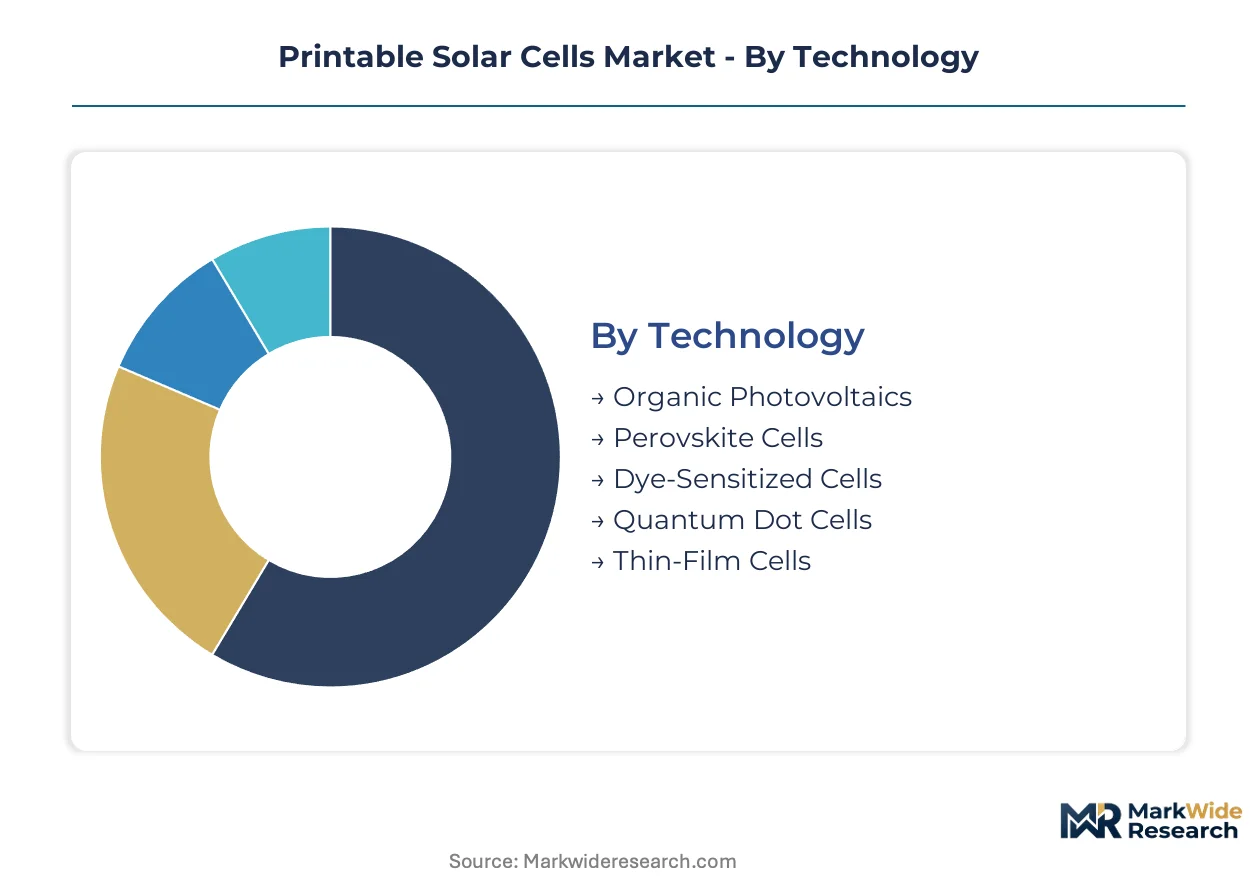
The printable solar cells market categorizes diverse technologies and applications, reflecting distinct material science advancements and end-user needs. Understanding these segments clarifies where innovation concentrates and how market demand manifests across various industries.
Technology:
The technological landscape for printable solar cells differentiates based on the core semiconductor materials and fabrication methods.
- Organic Photovoltaics:Comprising active layers of organic polymers and small molecules, these cells offer flexibility and transparency. Electronics manufacturers integrate these materials into flexible displays and wearable devices.
- Perovskite Cells:These devices utilize organic-inorganic hybrid perovskite materials for light absorption, offering high power conversion efficiencies. Demand from building-integrated photovoltaics drives ongoing research into their stability and longevity.
- Dye-Sensitized Cells:These cells mimic photosynthesis, using a layer of dye molecules to absorb light and generate electrons.
- Quantum Dot Cells:Utilizing semiconductor nanocrystals, these cells convert light across a broad spectrum into electrical energy.
- Thin-Film Cells:These broadly encompass technologies where active photovoltaic material layers are deposited onto a substrate.
Organic Photovoltaics commands the established base. The steepest expansion runs through Perovskite Cells.
Application:
Market demand for printable solar cells spans multiple industries, with specific applications driving material and form factor innovation.
- Building-Integrated Photovoltaics:This application integrates solar cells directly into architectural elements like facades, windows, and roofing. Construction firms prioritize aesthetically integrated and lightweight solar solutions.
- Wearable Electronics:Low-power devices such as smartwatches, health monitors, and smart labels require lightweight, flexible power sources. Electronics manufacturers integrate these cells directly into product designs.
- Portable Chargers:These compact power solutions utilize printable solar cells for on-the-go charging of small electronic devices.
- Agrivoltaics:Integrating solar technology into agricultural settings provides power for farm operations and enhances crop growth.
- Remote Sensors:These devices, often deployed in inaccessible locations, rely on printable solar cells for continuous, off-grid power.
Building-Integrated Photovoltaics forms the current revenue base. Wearable Electronics shows significant opportunity for future growth.
Form Factor:
The physical configuration of printable solar cells dictates their integration potential and suitability for various end-use environments.
- Flexible Sheets:These thin, pliable solar cells can conform to irregular surfaces, enabling integration into non-flat designs. Innovation in roll-to-roll production processes targets this form factor for mass manufacturing.
- Transparent Films:These cells allow light to pass through while generating electricity, ideal for windows and display screens. Architects and product designers specify these for energy-harvesting building materials.
- Rigid Panels:While less common, printable cells can also be manufactured as traditional, stiff panels for certain applications.
- Roll-to-Roll Modules:These continuously produced modules represent a scalable manufacturing method for flexible solar cells.
- Laminated Layers:Multiple layers of printable solar materials are encapsulated together to enhance durability and performance.
Flexible Sheets constitute the primary volume. Transparent Films exhibit the most rapidly expanding adoption.
End User:
Different industry sectors drive demand for printable solar cells, each with unique performance and integration requirements.
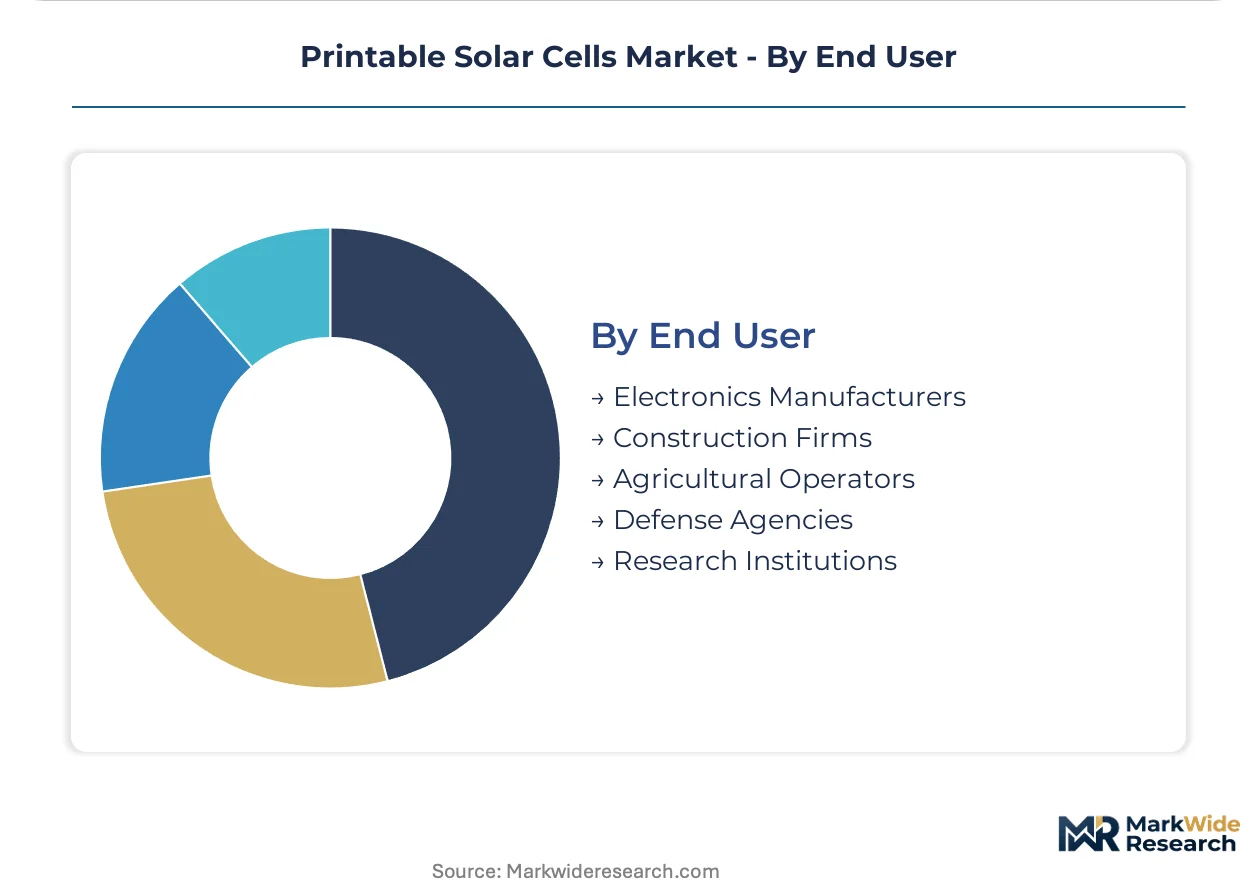
- Electronics Manufacturers:Companies producing consumer wearables, IoT devices, and smart packaging integrate printable solar cells for embedded power solutions. This sector prioritizes miniaturization and aesthetic integration.
- Construction Firms:These firms adopt printable solar cells for building-integrated photovoltaics, seeking lightweight, conformable, and visually appealing energy solutions. Their demand influences material and form factor development.
- Agricultural Operators:Farmers employ printable solar cells for powering smart farming equipment and remote sensing devices.
- Defense Agencies:Military and security applications utilize lightweight, portable power sources for field equipment and remote surveillance.
- Research Institutions:Universities and private labs actively develop new materials and manufacturing processes for next-generation printable solar cells.
Electronics Manufacturers represent the largest consumer base. Agricultural Operators are an emerging end-user segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global printable solar cells market demonstrates a varied landscape, with certain regions driving both export capability and import demand. Demand for adaptable energy solutions is reshaping industrial priorities across diverse economies, influencing both material innovation and manufacturing scale.
China
China's demand for building-integrated photovoltaics and advanced manufacturing solutions remains robust. The MEE's national policies, coupled with dual carbon goals, prioritize domestic renewable technology development. The Yangtze River Delta region, particularly in Jiangsu and Zhejiang, drives significant investment in advanced solar manufacturing facilities and research.
United States
Demand in the United States centers on flexible power sources for IoT devices and BIPV applications. The US Inflation Reduction Act (IRA) offers substantial incentives for domestic manufacturing of renewable energy components. California's robust innovation ecosystem, especially around Silicon Valley, fosters research into advanced materials and flexible electronics integration.
Germany
Germany exhibits strong demand for high-efficiency flexible solar cells for sustainable architecture and consumer electronics. The European Union's RoHS directives heavily influence material science research, pushing for lead-free perovskite formulations. Bavaria's research institutions and industrial clusters lead innovation in organic photovoltaics and advanced printing techniques.
Japan
Japan's market for printable solar cells focuses on transparent films for smart windows and low-power applications in consumer electronics. The Ministry of Economy, Trade and Industry (METI) supports advanced materials research and energy efficiency initiatives. The Kanto region, including Tokyo, serves as a hub for electronics manufacturers integrating these novel power solutions.
Printable Solar Cells Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, with materials specialists operating alongside vertically integrated solar manufacturers and niche roll-to-roll producers. This mix creates a competitive field where material innovation holds significant sway. Strategic partnerships between chemical companies and printing facilities, alongside targeted capacity expansion, are dominant competitive moves.
Specialists in material science and advanced inks, such as DuPont de Nemours, Inc., exemplify the asset-light model, leveraging polymer expertise to supply critical components. Firms like JinkoSolar Holding Co., Ltd., represent established solar incumbents with extensive control over their photovoltaic component supply. Meanwhile, InfinityPV ApS occupies a position as a leader in roll-to-roll production, targeting flexible solar applications with specialized manufacturing processes.
| Leading Market Players |
|---|
| Nanosolar Corporation |
| InfinityPV ApS |
| DuPont de Nemours, Inc. |
| Triton Solar LLC |
| JinkoSolar Holding Co., Ltd. |
| JA Solar Technology Co., Ltd. |
| Trina Solar Co., Ltd. |
| LONGi Green Energy Technology Co., Ltd. |
| Canadian Solar Inc. |
| Others |
Cost & Logistics Intelligence
The Shanghai-Rotterdam freight corridor's fluctuating costs influence supply concentration in advanced material inputs, which in turn shapes downstream price differentiation for flexible solar films.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake agreements for printable solar cells. Price differentiation stems from power conversion efficiency grades and IEC certification levels. Pricing softness reflects increasing competition from conventional solar in certain applications. Wearable electronics manufacturers exhibit higher price sensitivity compared to BIPV project developers.
Supply Chain Analysis
Extended payment terms from materials suppliers support the capital-intensive nature of advanced ink production. Geographic supply concentration for key inputs like perovskite precursors and conductive pastes is primarily in China and Germany. Raw material dependencies include high-purity organic polymers and specialized transparent conductive oxides. Regulatory restrictions, such as EU RoHS directives on lead content, pose a structural supply chain risk. Distribution runs through direct sales channels to large-scale integrators and specialized distributors for niche applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The printable solar cells market presents a defensive moat due to regulatory entrenchment around performance and safety standards, making market access challenging for uncertified products.
For Market Incumbents: Insulate core market share by deepening R&D into lead-free perovskite formulations, addressing EU RoHS directives. Expand manufacturing capacity in US facilities, leveraging IRA incentives to counter cost advantages from China. This counters the threat from emerging material specialists and ensures long-term market access.
For New Entrants and Emerging Players: Establish a beachhead in the wearable electronics segment, focusing on flexible sheet form factors. Target niche applications requiring custom transparent films, such as smart labels, where volume is lower but margins are higher. A direct-to-designer go-to-market angle can bypass traditional distribution channels.
For Investors and Strategic Acquirers: Specialized materials science firms with proprietary ink formulations represent attractive acquisition targets for their intellectual property. The long-term viability of this market hinges on overcoming material stability challenges. Watch for significant breakthroughs in perovskite longevity testing as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Lead-Free Perovskite R&D | This secures market access in Europe by adhering to strict EU RoHS directives. |
| Expand Roll-to-Roll Production Capacity | Scaling high-speed fabrication methods lowers unit costs and meets demand for flexible sheets. |
| Partner with BIPV Integrators | Collaborating with construction firms drives adoption of aesthetically integrated solar solutions. |
| Secure High-Purity Material Supply | Long-term contracts with chemical suppliers mitigate commodity price volatility for semiconductor inks. |
| Pursue IEC Performance Certifications | Achieving global standards builds bankability and broadens acceptance for printable solar cells. |
Research Approach
Desk research of academic journals, patent databases, and national energy agency reports preceded structured interviews with materials scientists, BIPV architects, and electronics manufacturing procurement leads. This combined primary and secondary data, triangulating findings through both bottom-up and top-down approaches for market sizing and validation.
Key assumptions regarding perovskite stability improvements and regulatory support for renewable energy were held constant across the analysis window. The market was segmented by technology, application, and form factor, alongside regional adoption patterns. Compound annual growth rates were derived from historical data trends and projected technological advancements, with material cost reductions serving as a key input.
Stress conditions across raw material costs and manufacturing scale-up timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Vegetable Dryer Market
Solar Power Systems
Global Airport Solar Power Market
Solar Power Systems
Malaysia Solar Energy Market
Solar Power Systems
Solar Cells Market
Solar Power Systems
Asia-Pacific Rooftop Solar Market
Solar Power Systems
Solar Backsheet Market
Solar Power Systems
Residential Solar Inverter Market
Solar Power Systems
Solar Powered Elevator Market
Solar Power Systems
Asia-Pacific Solar Blanket Market
Solar Power Systems
Greece Renewable Energy Market
Solar Power Systems
Italy Solar Energy Market
Solar Power Systems
Netherlands Solar Energy Market
Solar Power Systems
Bulgaria Solar Energy Market
Solar Power Systems
Philippines Solar Energy Market
Solar Power Systems
Trinidad and Tobago Solar Energy Market
Solar Power Systems
Solar PV Mounting Systems Market