
 Power Lithium Battery Market | 2026-2036
Power Lithium Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Power Lithium Battery Market Insights
Buyer concentration in automotive procurement is rebalancing as legacy OEMs diversify supplier rosters while Chinese EV makers consolidate around captive cell sources. Contemporary Amperex Technology Co. Limited anchors the global supply base through vertical integration into lithium refining and cathode production. LG Energy Solution competes on high-nickel chemistry leadership for premium EV platforms. BYD Company Limited leverages its in-house blade cell architecture to dominate integrated vehicle-battery systems.
Power lithium batteries are rechargeable electrochemical cells employing lithium-ion intercalation chemistry, typically operating at nominal voltages of 3.2–3.7 V with energy densities reaching 250–300 Wh/kg in NMC formulations, designed to store and discharge electrical energy for motive, stationary, and portable applications. Li-NMC formulations command the largest revenue share due to their energy density advantage in long-range electric vehicles. LiFePO4 chemistry sustains faster growth in energy storage systems where cycle life and thermal stability outweigh gravimetric performance. Rack-mounted installations occupy the dominant share of utility-scale deployments, while modular formats are gaining traction in commercial and industrial retrofit applications.
China's MIIT enforces GB standards for battery safety and traceability, while the EU's Battery Regulation mandates carbon footprint declarations and recycled content quotas that reshape import competitiveness. The US EPA and NHTSA coordinate tailpipe and battery supply chain rules under the Inflation Reduction Act's domestic content thresholds. Stakeholders must monitor how divergent compliance timelines across Beijing, Brussels, and Washington alter cell factory location decisions and chemistry roadmaps.
Market Dynamics
Fleet electrification mandates across Germany, China, and the United States are compressing procurement timelines for high-nickel cathode cells. Cell manufacturers face simultaneous pressure to scale capacity, secure lithium supply, and meet divergent carbon footprint standards.
Growth Catalysts
- EU Battery Regulation:Mandatory recycled content quotas and carbon footprint declarations are accelerating investment in European cell gigafactories and local recycling infrastructure.
- Energy storage systems:Grid-scale battery deployments for renewable integration are absorbing surplus cell capacity and extending factory utilization rates.
- Lithium refining:New extraction and processing capacity in Chile and Australia is loosening feedstock constraints that previously capped cell output.
Market Restraints
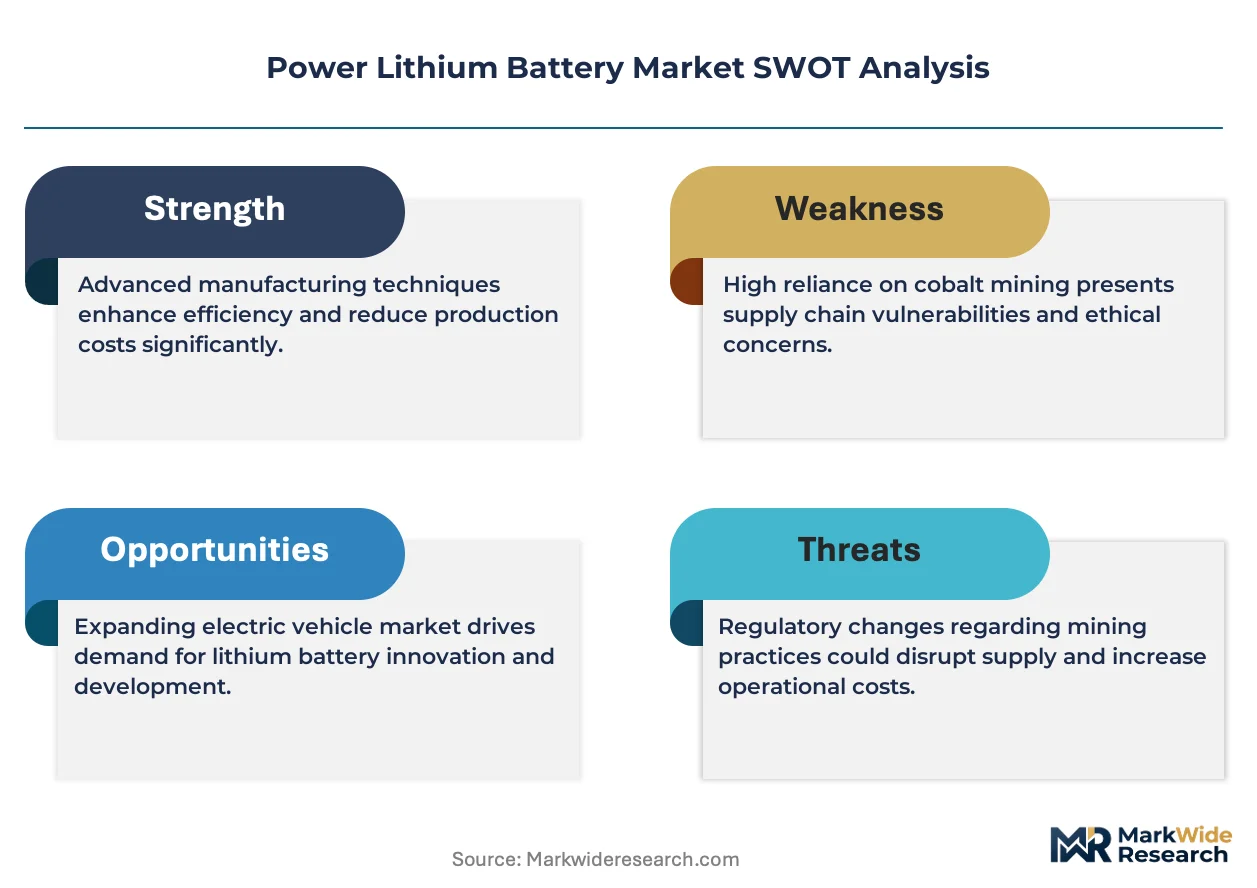
- Cobalt price volatility:Concentrated supply from the Democratic Republic of Congo creates input cost instability for high-nickel NMC formulations.
- Chinese cathode dominance:Over 70 percent of global cathode active material production concentrates in Chinese chemical parks, creating single-source vulnerability.
- Solid-state timeline uncertainty:Prolonged commercialization delays for sulfide and oxide electrolyte cells extend incumbent lithium-ion technology lock-in.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for advanced chemistry cell manufacturing are attracting greenfield investments in Gujarat and Tamil Nadu.
- Second-life automotive batteries:Retired EV packs are repurposing for stationary storage, creating circular revenue streams independent of virgin cell production.
- Sodium-ion convergence:Hybrid manufacturing lines capable of producing both lithium-ion and sodium-ion cells are opening cost-competitive entry into mass-market two-wheelers.
Industry Challenges
- Electrolyte formulation expertise:Shortages of experienced scientists in solid-electrolyte interphase engineering are slowing next-generation cell development.
- GB standard compliance:China's MIIT safety and traceability certifications require 12-18 month validation cycles that delay product launches for export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Lithium Battery Market |
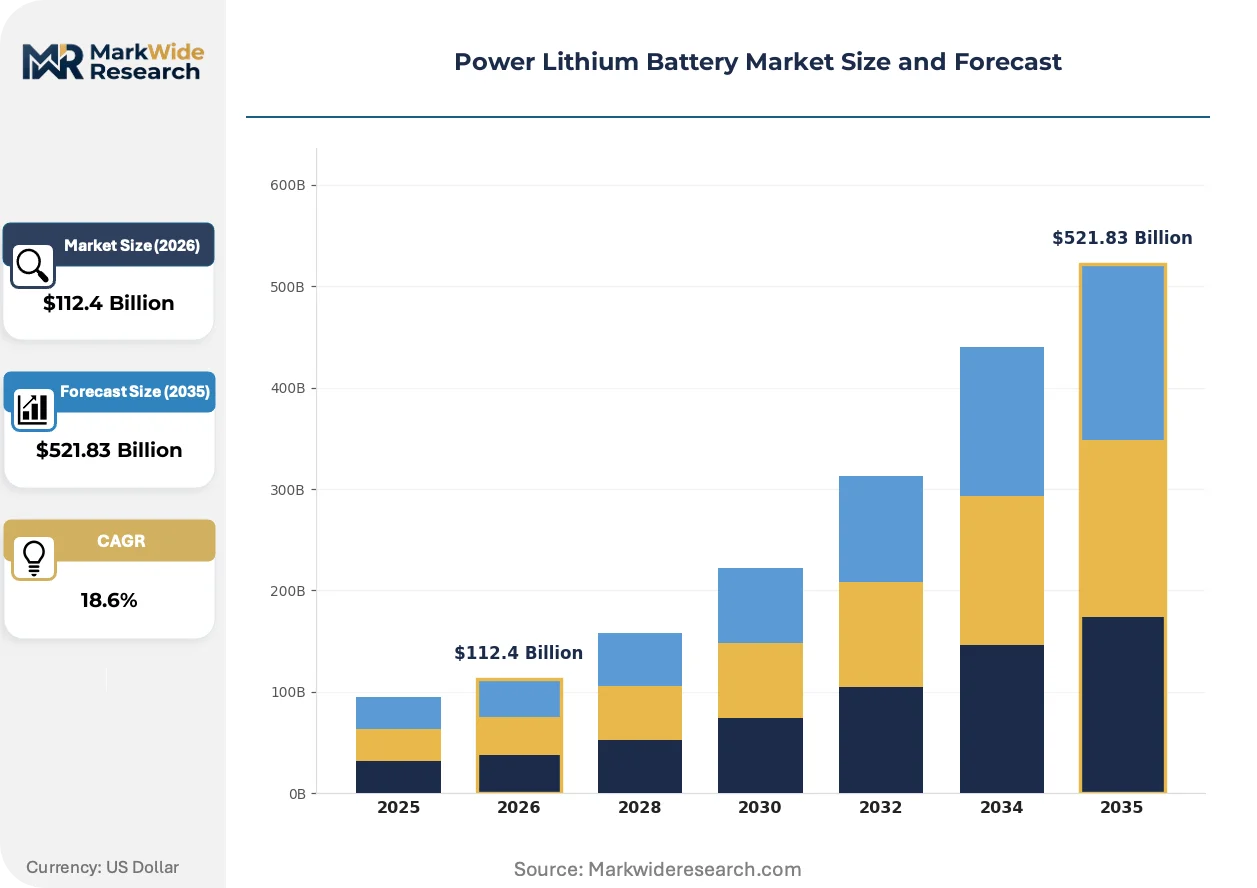
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $521.83 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Li-ion, LiFePO4, Li-polymer, Li-NMC Application: Electric Vehicles, Energy Storage Systems, Consumer Electronics, Industrial Equipment End User: Automotive Manufacturers, Renewable Energy Providers, Electronics Firms, Machinery Suppliers Installation: Modular, Rack-mounted, Integrated, Portable |
| Companies Covered | Contemporary Amperex Technology Co. Limited, LG Energy Solution, Panasonic Holdings Corporation, BYD Company Limited, Samsung SDI, SK On, CALB, Gotion High-Tech, Sunwoda, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Lithium Battery Market Trends and Innovations
Cell architecture and manufacturing processes are fragmenting as regional regulatory requirements diverge and end-use applications multiply. Three developments are restructuring competitive positioning.
Dry electrode coating is eliminating solvent-based processing steps and reducing energy consumption in electrode manufacturing. Automotive OEMs in Germany and South Korea are qualifying dry-coated cells for 2026 platform launches. This process shift is decentralizing cathode production away from traditional chemical park concentrations toward integrated cell-vehicle manufacturing corridors.
China's MIIT battery passport standards are mandating full supply chain traceability from mine to pack. The regulation forces foreign cell suppliers to adopt Chinese data infrastructure or face exclusion from the world's largest EV market. European and Korean manufacturers are responding by establishing parallel certification systems that satisfy both Beijing and Brussels requirements.
Long-term service agreements are replacing spot-market cell purchases for utility-scale storage developers. Asset owners in Texas and California are contracting 15-year performance guarantees that bundle cell supply with degradation insurance and remote monitoring. This contractual innovation concentrates procurement authority with integrated system providers and marginalizes standalone cell merchants.
Power Lithium Battery Market Segmentation
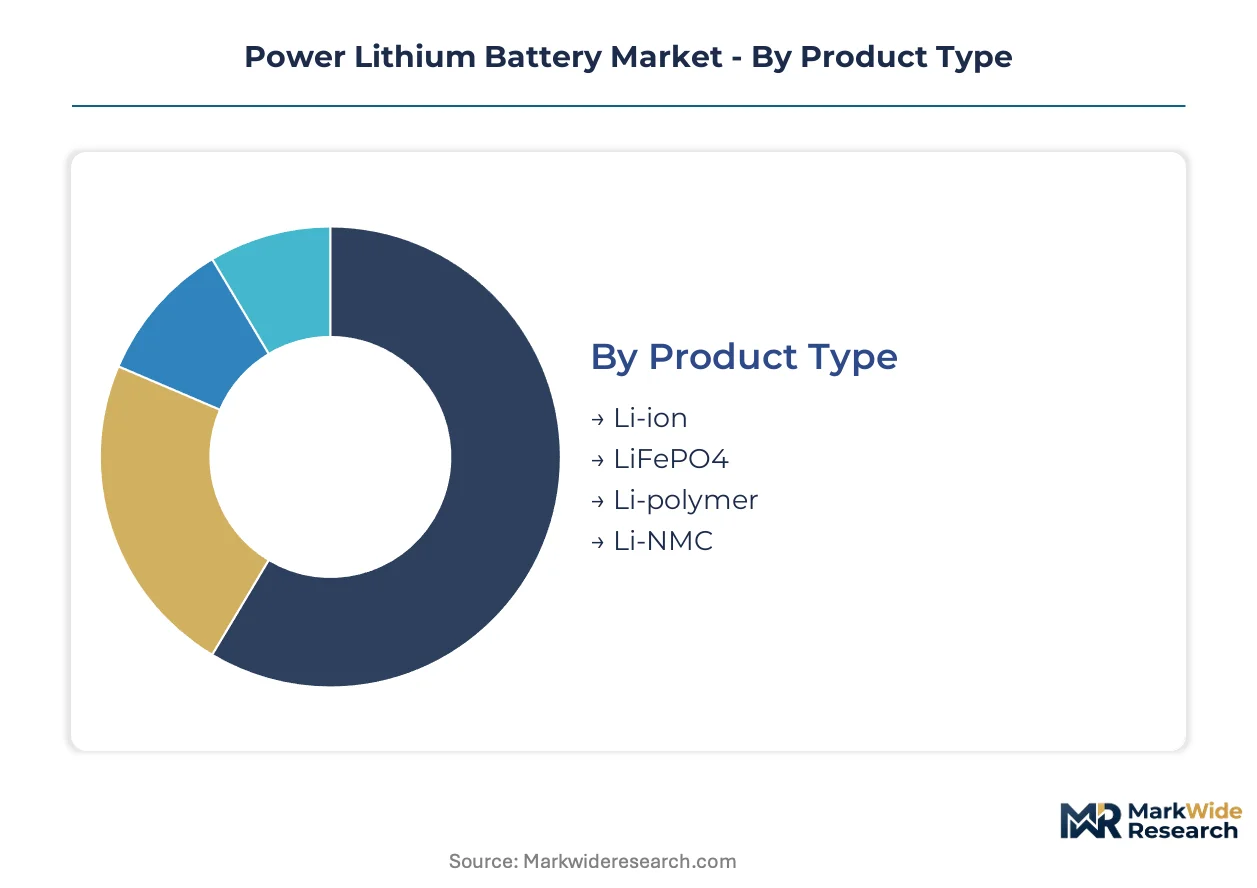
Segmentation in the power lithium battery market reveals how chemistry choices, installation formats, and customer procurement patterns diverge across motive, stationary, and portable applications. Understanding these splits clarifies where margin pools concentrate and which technical specifications command pricing power.
Product Type:
Standardization dominates commodity lithium-ion cells while specialized cathode formulations require custom engineering and qualification cycles.
- Li-NMC:Nickel-manganese-cobalt layered oxide cathodes deliver energy densities of 250–300 Wh/kg through optimized nickel ratios above 80 percent. Automotive OEMs in Germany's manufacturing corridor specify these cells for premium electric vehicle platforms where range certification determines fleet compliance.
- LiFePO4:Lithium iron phosphate chemistry trades gravimetric density for thermal stability and cycle life exceeding 6,000 cycles. Grid-scale developers in Texas and California deploy these cells in rack-mounted configurations where degradation insurance contracts favor longevity over energy density.
- Li-ion:Conventional cobalt-based formulations serve legacy consumer electronics and industrial lift equipment with established supply chains.
- Li-polymer:Pouch-format cells with gel electrolytes occupy thin-profile wearables and medical devices requiring form-factor flexibility.
Leading the category by volume: Li-NMC. Expanding most quickly: LiFePO4.
Application:
Volume concentration shifts from consumer electronics toward fleet electrification mandates and renewable integration requirements.
- Electric Vehicles:Passenger and commercial vehicle platforms absorb the majority of high-nickel cell output. Procurement timelines compress as China's MIIT and the EU's Battery Regulation impose parallel traceability and carbon footprint standards on cell suppliers.
- Energy Storage Systems:Utility-scale and commercial installations buffer intermittent renewable generation. Developers in California's CAISO market contract 15-year performance guarantees that bundle cell supply with remote monitoring and degradation insurance.
- Consumer Electronics:Smartphones, laptops, and power tools sustain demand for compact cylindrical and prismatic formats with mature cost curves.
- Industrial Equipment:Forklifts, mining vehicles, and port machinery convert from lead-acid to lithium-ion for operational uptime gains.
Dominant by procurement value: Electric Vehicles. Steepest expansion trajectory: Energy Storage Systems.
End User:
Customer concentration varies from consolidated automotive OEMs to fragmented machinery suppliers with divergent technical qualification capabilities.
- Automotive Manufacturers:Volkswagen, BMW, and BYD qualify cell suppliers through 24–36 month platform integration programs. These buyers demand backward integration into lithium refining and cathode production to secure IRA domestic content credits.
- Renewable Energy Providers:NextEra, Orsted, and domestic Chinese developers procure cells through engineering-procurement-construction contractors. Long-term service agreements are displacing spot-market purchases as asset owners seek performance certainty.
- Electronics Firms:Apple, Samsung, and Dell specify cells through tier-one battery pack assemblers with established IEC certification pathways.
- Machinery Suppliers:Crown, Hyster-Yale, and Komatsu convert product lines to lithium-ion with regional distributor support networks.
Highest concentration of procurement authority: Automotive Manufacturers. Fastest-growing customer investment: Renewable Energy Providers.
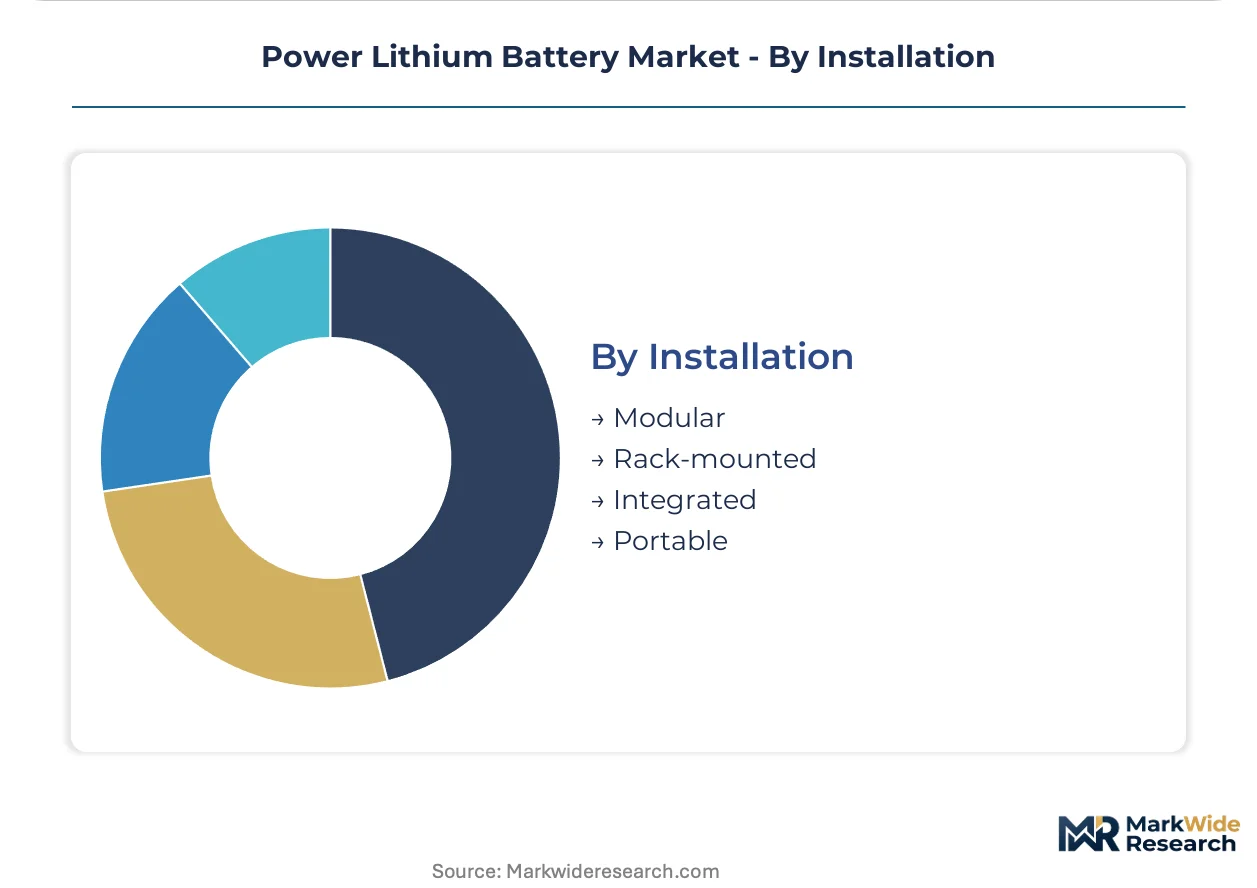
Installation:
Physical integration depth separates standardized modular formats from site-engineered permanent installations.
- Rack-mounted:Standardized 19-inch or custom-dimension battery racks dominate utility-scale deployments. Installations in Germany's grid stabilization markets require CE marking and EU Battery Regulation carbon footprint declarations.
- Modular:Containerized or skid-mounted systems enable rapid deployment and future capacity expansion. Commercial and industrial retrofit applications in India's Gujarat and Tamil Nadu favor this format for production-linked incentive compliance.
- Integrated:Cell-to-pack and cell-to-chassis architectures eliminate module housings. BYD's blade cell and Tesla's structural battery pack exemplify this approach for OEM captive supply.
- Portable:Power stations and tool battery packs serve outdoor recreation and professional trades with plug-and-play interchangeability.
Leading format by deployed capacity: Rack-mounted. Gaining share fastest: Modular.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chilean lithium brine operations and Australian spodumene mines anchor the upstream feedstock geography for power lithium battery manufacturing. Cell production clusters concentrate in jurisdictions with integrated cathode supply chains and fleet electrification mandates.
China
CATL and BYD anchor domestic cell production serving BYD's vehicle platforms and external OEM contracts. MIIT battery passport standards and GB safety certifications enforce traceability from mine to pack. The Yangtze River Delta and Pearl River Delta host cathode chemical parks and gigafactory corridors co-located with vehicle assembly.
Germany
Volkswagen and BMW procurement programs compress supplier qualification timelines for high-nickel cell platforms. EU Battery Regulation carbon footprint declarations and recycled content quotas reshape import competitiveness. The automotive corridor spanning Bavaria and Baden-Württemberg co-locates cell gigafactories with OEM assembly plants.
United States
Tesla's structural battery pack and GM's Ultium platform absorb domestic cell output under IRA domestic content thresholds. EPA and NHTSA coordinate tailpipe and supply chain rules favoring North American lithium refining. Texas and California utility markets contract 15-year performance guarantees for grid-scale storage deployments.
South Korea
LG Energy Solution and SK On supply premium EV platforms with high-nickel NMC chemistry leadership. MFDS and METI alignment on safety standards accelerates qualification for export markets. The Seoul Capital Area and Busan-Ulsan industrial belt concentrate electrode coating and cell assembly capacity.
India
Reliance Industries and Ola Electric advance domestic cell manufacturing under PLI scheme incentives for advanced chemistry production. CEA grid codes and BIS safety standards create parallel certification pathways. Gujarat and Tamil Nadu host greenfield investments targeting two-wheeler and commercial vehicle electrification.
Power Lithium Battery Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue sodium-ion and solid-state chemistry positions. The vendor base concentrates around three strategic archetypes: integrated vehicle-battery systems specialists, independent cell merchants with cathode backward integration, and captive suppliers serving single OEM platforms. Capacity expansion and strategic partnerships dominate competitive moves as manufacturers secure lithium offtake and co-locate with automotive assembly.
Within the integrated systems tier, BYD Company Limited and Contemporary Amperex Technology Co. Limited exemplify divergent approaches to captive versus merchant supply. LG Energy Solution occupies a position between these models with independent cell production serving multiple premium OEM platforms. Panasonic Holdings Corporation represents the Japan-based archetype with historical ties to Tesla's Nevada operations and ongoing platform diversification.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co. Limited |
| LG Energy Solution |
| Panasonic Holdings Corporation |
| BYD Company Limited |
| Samsung SDI |
| SK On |
| CALB |
| Gotion High-Tech |
| Sunwoda |
| Others |
Pricing and Supply Chain Analysis
Captive cathode production within Chinese chemical parks anchors both supply security and pricing leverage for integrated cell manufacturers serving automotive OEMs. This backward integration into lithium refining and precursor synthesis insulates dominant producers from spot-market volatility while compressing margins for merchant cathode suppliers competing on unbundled material sales.
Pricing Analysis
Warranty bundling now separates premium cell suppliers from commodity merchants in contract negotiations. Automotive OEMs in Germany's manufacturing corridor demand 8-year performance guarantees with degradation insurance, while grid-scale developers in Texas accept shorter warranty terms for price-sensitive rack-mounted deployments. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with UL-listed cells commanding substantial premiums over unverified alternatives. Cost compression in standard-grade cylindrical formats is intensifying because Chinese producers are absorbing margin erosion to maintain factory utilization. Renewable energy providers exhibit highest price sensitivity due to project finance constraints, whereas luxury EV platforms show lowest sensitivity as range certification outweighs cell cost in total vehicle economics.
Supply Chain Analysis
Single-source vulnerability sits with Chinese cathode active material production, where over seventy percent of global capacity concentrates in Yangtze River Delta chemical parks. Lithium carbonate from Chilean brine operations, spodumene concentrate from Australian hard-rock mines, and cobalt hydroxide from the Democratic Republic of Congo feed this processing concentration. Tariff exposure on finished cells entering the European Union and United States is accelerating geographic diversification into Hungary, Canada, and Mexico. Distribution runs through long-term offtake contracts with automotive OEMs and engineering-procurement-construction contractors for utility-scale storage, displacing spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated producers with captive lithium supply and in-house cathode production, as capital intensity and regulatory compliance costs force smaller cell merchants toward acquisition or exit.
For Market Incumbents: Extend platform integration programs with automotive OEMs to 36-month qualification cycles that lock out challenger suppliers. Secure lithium offtake from Chilean and Australian producers before project finance closes on new extraction capacity, and invest in dry electrode coating qualification to meet 2026 platform requirements from German and South Korean OEMs. For New Entrants and Emerging Players: Capture India's PLI scheme incentives for advanced chemistry cell manufacturing in Gujarat and Tamil Nadu, where domestic content requirements and two-wheeler electrification mandates create protected demand. Sodium-ion chemistry for mass-market applications offers the most penetrable segment, with hybrid manufacturing lines enabling cost-competitive entry without competing directly on lithium-ion energy density. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by automotive OEMs seeking captive cell supply for IRA domestic content compliance. Five-to-ten year viability hinges on securing lithium refining partnerships and cathode precursor supply agreements. The signal to watch is qualification timeline compression by China's MIIT, which accelerates capital requirements for market access and favors scaled incumbents with dedicated regulatory affairs infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Lithium Offtake Agreement | Locks in feedstock supply for IRA domestic content thresholds ahead of competitor procurement. |
| Dry Electrode Coating Qualification | Meets 2026 platform requirements from Volkswagen and BMW while reducing manufacturing energy intensity. |
| Battery Passport Compliance Investment | Satisfies China's MIIT traceability mandates and EU Battery Regulation carbon footprint declarations simultaneously. |
| Second-life Battery Partnership | Creates circular revenue streams with renewable energy providers seeking 15-year performance guarantees. |
| Sodium-ion Hybrid Line Deployment | Opens cost-competitive entry into India's two-wheeler and mass-market commercial vehicle segments. |
Research Methodology
SEC filings from cell manufacturers, customs and trade data from Chilean and Australian export authorities, and EU Battery Regulation implementation guidance formed the secondary backbone of this analysis. Primary interviews with automotive platform engineers, utility-scale storage procurement leads at engineering-procurement-construction firms, lithium refinery operations managers, and cathode chemical park technical directors validated demand assumptions and supply constraints. Bottom-up cell shipment estimates by chemistry and installation format were cross-checked against top-down electric vehicle production forecasts and grid-scale storage deployment databases.
Historical trendline analysis of cell pricing, factory utilization rates, and raw material input costs established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated chemistry type, installation format, end-use application, and regional regulatory cluster dimensions. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion schedules, with lithium carbonate price scenarios and fleet electrification mandate compliance timelines serving as primary forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to solid-state commercialization delays, cobalt supply disruptions from the Democratic Republic of Congo, and divergence between Beijing, Brussels, and Washington regulatory timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
North America Lithium-Ion Battery Separator Market
Lithium-ion Battery
Lithium Iron Phosphate (LiFePO4) Battery Market
Lithium-ion Battery
Global Nanowire Battery Market
Lithium-ion Battery
Lithium Ion Secondary Battery Sales Market
Lithium-ion Battery
China SLI Battery Market
Lithium-ion Battery
Asia-Pacific Solid State Battery Market
Lithium-ion Battery
Lithium-Ion Battery Pack for Consumer Market
Lithium-ion Battery
Lithium-Ion Stationary Battery Market
Lithium-ion Battery
Next Generation Advanced Battery Market
Lithium-ion Battery
Automotive Lithium-Sulfur Battery Market
Lithium-ion Battery
Outdoor Lithium Battery Power Supplies Market
Lithium-ion Battery
South America Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Italy Electric Vehicles Battery Anode Market
Lithium-ion Battery
Lithium Battery for Passenger Car Market
Lithium-ion Battery
Lithium-Ion Battery Metal Market
Lithium-ion Battery
Lithium-Ion Forklift Battery Market