
 Germany Electric Vehicle Battery Anode Market | 2026-2036
Germany Electric Vehicle Battery Anode Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Electric Vehicle Battery Anode Market Insights
Buyer concentration among German OEMs is consolidating as Volkswagen, BMW, and Mercedes-Benz tighten supplier qualification requirements for their dedicated battery cell factories. BASF SE leverages its Ludwigshafen chemical complex to anchor domestic precursor production for anode active materials. SGL Carbon SE specializes in synthetic graphite manufacturing, sustaining supply relationships with European cell producers. Robert Bosch GmbH competes through its systems integration expertise, positioning battery management technologies alongside material partnerships.
Germany electric vehicle battery anodes are negative electrodes composed primarily of carbonaceous materials such as synthetic or natural graphite, with silicon and tin emerging as higher-capacity alternatives; these structures intercalate lithium ions during charging and release them during discharge, with typical gravimetric capacities ranging from 372 mAh/g for pure graphite to over 1,000 mAh/g for silicon-doped formulations. Graphite anodes currently dominate installed capacity due to proven cycle stability and established supply chains, while silicon-blended chemistries represent the fastest-growing product category as manufacturers pursue energy density targets above 300 Wh/kg at the cell level. Fast charging technology commands premium positioning among technology segments, though long cycle life remains the decisive specification for commercial vehicle applications where warranty obligations extend to eight years or more.
KBA enforces type-approval standards that incorporate UN ECE R100 battery safety requirements, while the EU Battery Regulation through ECHA establishes due diligence obligations for raw material sourcing and mandatory disclosure of carbon intensity per kWh. These frameworks compel anode producers to document supply chain provenance and invest in European-based graphite purification capacity rather than relying exclusively on imported active materials. Stakeholders must monitor whether domestic precursor manufacturing scales sufficiently to satisfy local content expectations as cell gigafactories in Salzgitter, Heilbronn, and Kaiserslautern reach operational maturity.
Market Dynamics
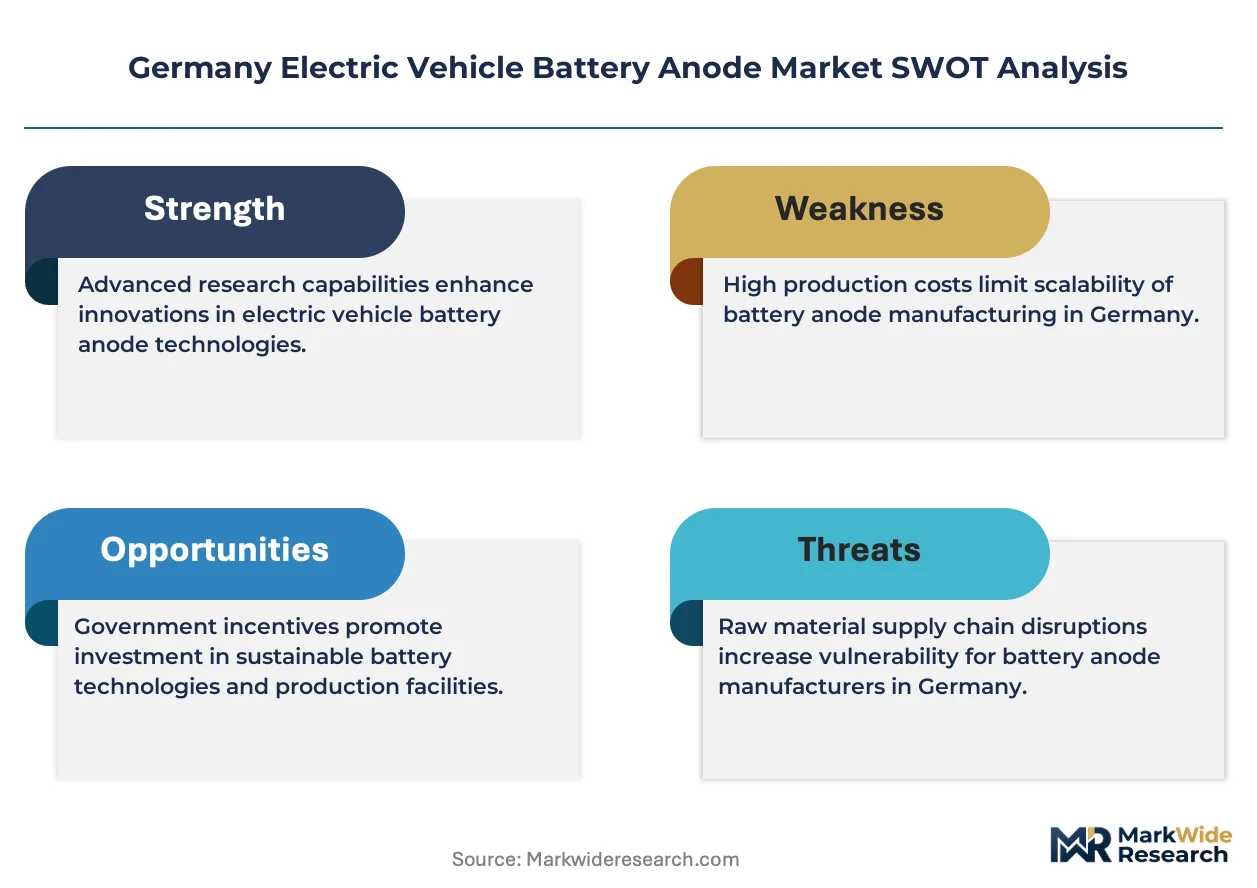
OEM qualification requirements for high-capacity silicon-blended anodes are compressing supplier margins while consolidating procurement around vertically integrated chemical conglomerates with domestic precursor capabilities.
Growth Catalysts
- EU Battery Regulation recycled content mandates:ECHA due diligence obligations are compelling anode producers to invest in European graphite purification capacity rather than relying on imported active materials.
- Silicon-doped formulation adoption:Cell manufacturers pursuing energy density targets above 300 Wh/kg are accelerating qualification programs for silicon-blended anodes in premium passenger EV segments.
- Baden-Württemberg and Bavaria cluster concentration:Volkswagen, BMW, and Porsche battery development facilities are creating localized demand pull for just-in-time anode material supply.
Market Restraints
- Spherical graphite purification cost structure:Energy-intensive thermal and chemical processing steps constrain margin expansion for domestic producers competing against Asian supply.
- Natural graphite supply concentration risk:Dependence on single-source jurisdictions for flake graphite feedstock exposes anode manufacturers to export restriction vulnerabilities.
- SiOx blending technical limitation:First-cycle irreversible capacity loss in silicon oxide composites exceeds 15%, degrading pack-level energy density calculations.
Strategic Opportunities
- Commercial vehicle fast-charging specification:Eight-year warranty obligations for heavy-duty electric trucks are creating demand for anode formulations optimized for cycle stability over energy density.
- Salzgitter cell gigafactory localization:Volkswagen's dedicated battery facility creates captive supply opportunities for qualified domestic anode material producers.
- Pre-lithiation technology convergence:Integration of stabilized lithium metal powders with graphite substrates offers pathway to offset silicon-induced capacity fade.
Industry Challenges
- Electrode slurry formulation expertise gap:Shortage of process engineers with silicon-anode water-based binder system experience is constraining production ramp timelines.
- KBA UN ECE R100 certification timeline:Extended type-approval procedures for novel anode chemistries delay commercial deployment by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Electric Vehicle Battery Anode Market |
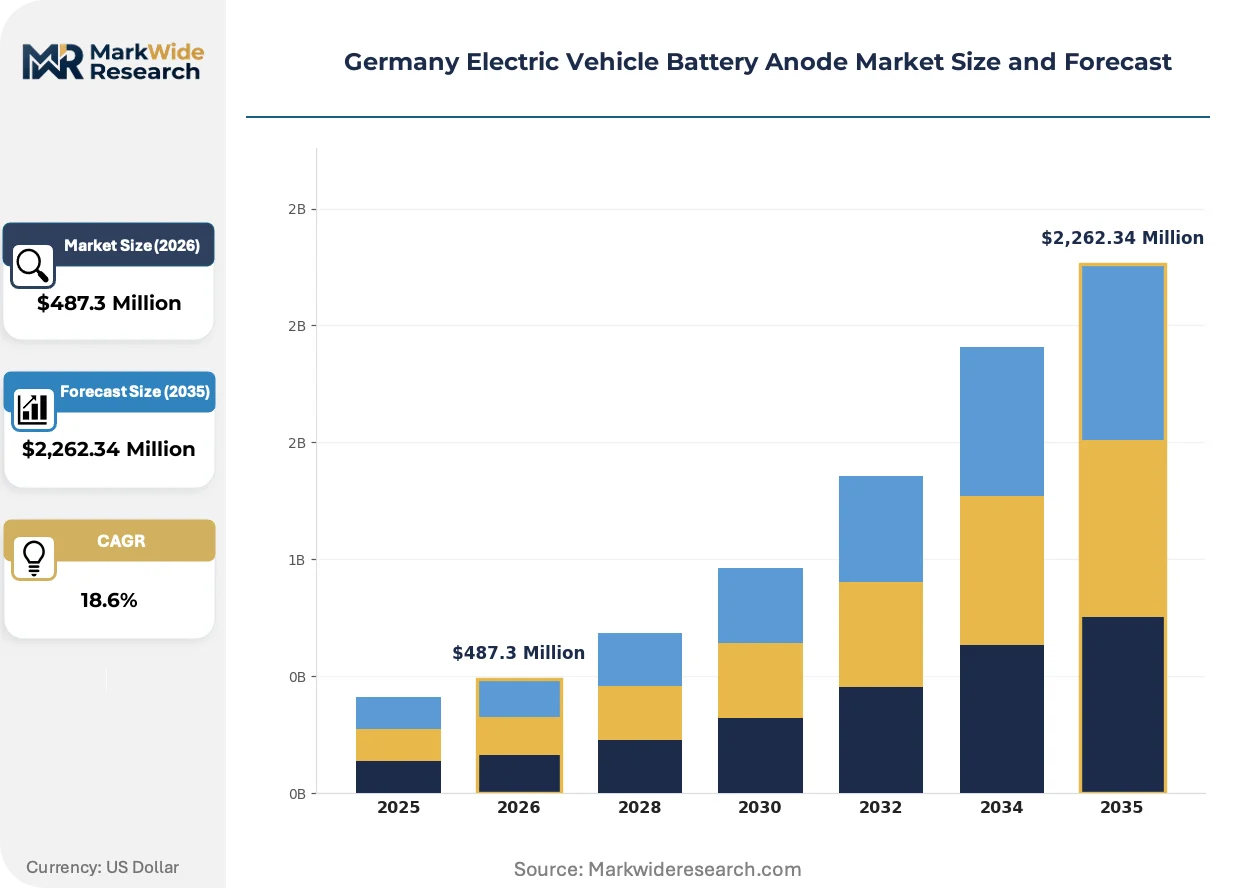
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $2,262.34 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Graphite, Silicon, Tin Application: Passenger Vehicles, Commercial Vehicles, E-Bikes, E-Scooters End User: OEMs, Aftermarket Providers, Fleet Operators, Battery Manufacturers Technology: Fast Charging, Long Cycle Life, Enhanced Energy Density, Safety Features |
| Companies Covered | BASF SE, Varta AG, SGL Carbon SE, Evonik Industries AG, Robert Bosch GmbH, Innolith AG, Leclanché GmbH, Heraeus Holding GmbH, Wacker Chemie AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Electric Vehicle Battery Anode Market Trends and Innovations
Silicon-blended anode formulations are displacing pure graphite architectures as German OEMs prioritize energy density in next-generation cell designs, while regulatory pressure on carbon intensity accelerates domestic supply chain investments.
Synthetic graphite manufacturing is consolidating around chemical vapor deposition processes that achieve 99.95% carbon purity. BMW and Mercedes-Benz cell engineering teams are qualifying these materials for 2027 platform launches. The technology is consolidating procurement relationships around producers with integrated needle coke-to-anode supply chains.
ECHA enforcement of EU Battery Regulation carbon footprint declarations is compelling anode producers to document Scope 3 emissions from mining through purification. Industrial consequence includes accelerated investment in renewable-powered thermal processing. Premium passenger EV segments are responding first, with OEMs demanding batch-level traceability certificates.
Buyer concentration among dedicated battery cell factories is compressing supplier negotiation leverage. Long-term offtake agreements with volume commitments are displacing spot market transactions for active materials. Bavaria and Baden-Württemberg assembly corridors exhibit the most pronounced contract structuring.
Germany Electric Vehicle Battery Anode Market Segmentation
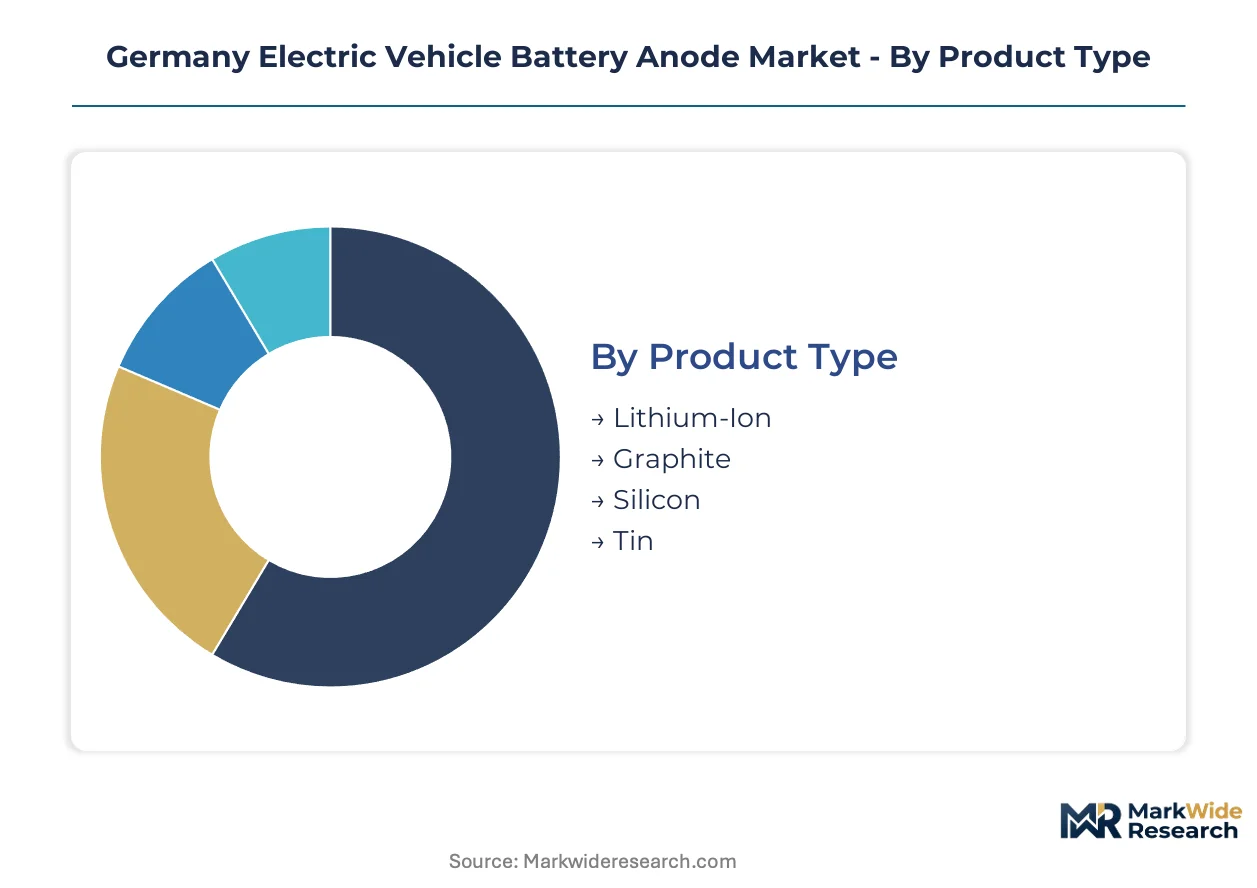
German OEM procurement patterns fragment anode demand across multiple technical and commercial dimensions. Understanding how specifications diverge between passenger and commercial applications enables suppliers to align purification investments with qualified revenue streams.
Product Type:
Supply concentration around synthetic graphite purification in Ludwigshafen and Bavaria is reshaping domestic active material availability.
- Graphite:Synthetic and natural graphite formulations dominate current procurement volumes, with spherical purification processes achieving 99.95% carbon purity for BMW and Mercedes-Benz cell qualification programs. Baden-Württemberg assembly corridors absorb the majority of domestic graphite anode output.
- Silicon:Silicon-doped and silicon oxide composites are expanding most quickly as Volkswagen pursues energy density targets above 300 Wh/kg for premium platform launches. First-cycle irreversible capacity loss remains the critical technical barrier for Salzgitter gigafactory acceptance.
- Lithium-Ion:Intercalation chemistry improvements in lithium-ion anode architectures support incremental capacity gains without silicon blending complexity.
- Tin:Tin-based alloy anodes occupy niche research positions, constrained by volume expansion degradation mechanisms that exceed commercial warranty thresholds.
Graphite absorbs the bulk of installed capacity; silicon is expanding most quickly.
Application:
Cost tier differentiation between passenger and commercial specifications is forcing anode producers to maintain parallel formulation portfolios.
- Passenger Vehicles:Premium German OEMs prioritize energy density above 300 Wh/kg, accelerating silicon-blended qualification timelines for next-generation cell platforms. Fast-charging compatibility commands specification premiums in this segment.
- Commercial Vehicles:Heavy-duty electric trucks require anode formulations optimized for cycle stability over eight-year warranty periods, with KBA type-approval standards extending validation timelines. Long cycle life specifications dominate procurement criteria.
- E-Bikes:Cost-sensitive micromobility applications favor established graphite chemistries with proven supply chain scale.
- E-Scooters:Shared fleet operators demand safety-certified anode materials with thermal runaway prevention characteristics.
Passenger vehicles command the highest specification premiums; commercial vehicles impose the most demanding cycle life requirements.
End User:
Customer type concentration around dedicated battery cell factories is compressing supplier negotiation leverage across all procurement tiers.
- OEMs:Volkswagen, BMW, and Mercedes-Benz are consolidating supplier qualification requirements for captive cell production in Salzgitter, Heilbronn, and Kaiserslautern. Long-term offtake agreements with volume commitments are displacing spot market transactions.
- Battery Manufacturers:Independent cell producers serving multiple OEMs require flexible anode material specifications that span customer platforms.
- Fleet Operators:Commercial vehicle fleet procurement emphasizes total cost of ownership calculations incorporating cycle life warranty terms.
- Aftermarket Providers:Replacement battery demand concentrates in lower-specification graphite formulations with established supply availability.
OEMs absorb the bulk of qualified supply; battery manufacturers are expanding most quickly as independent cell capacity scales.
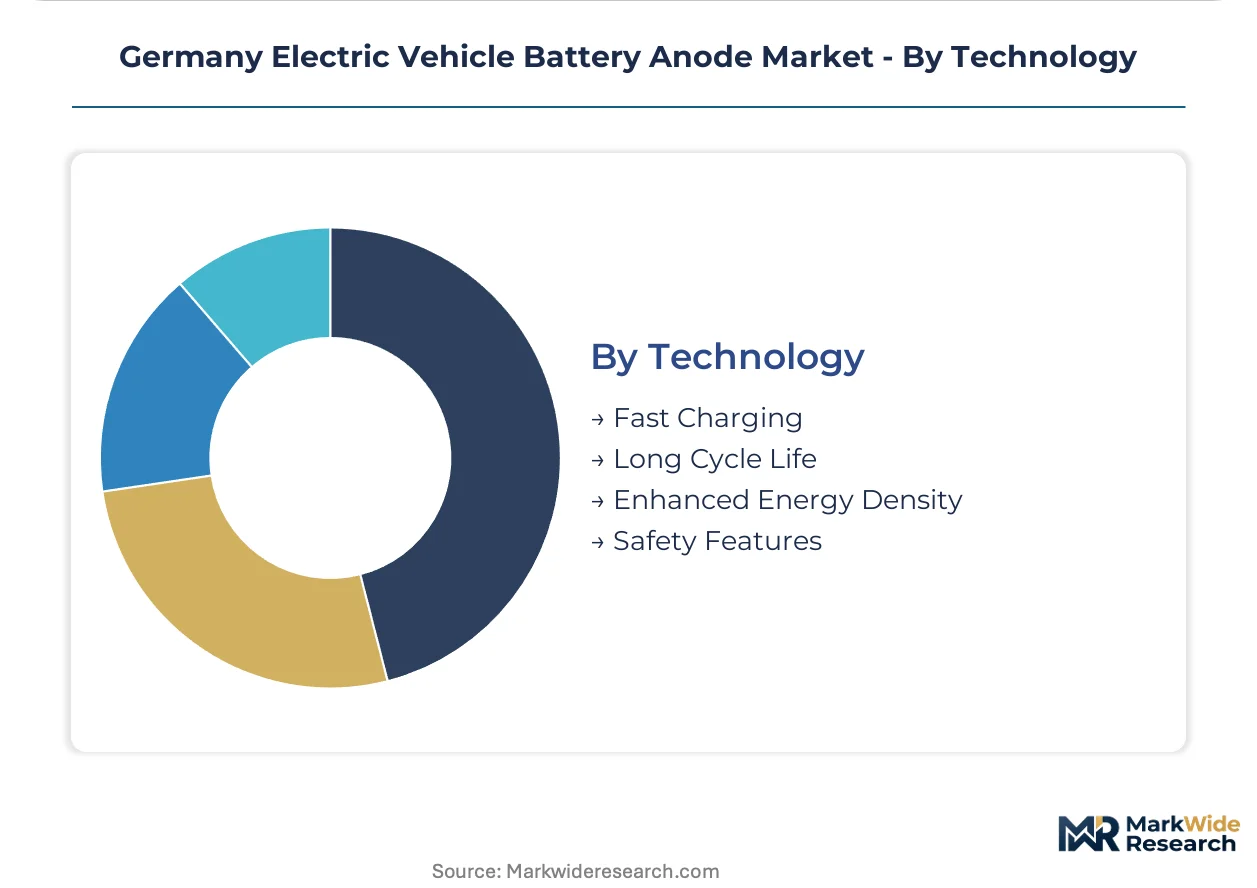
Technology:
Margin structure across technology tiers reflects the technical complexity of silicon integration and pre-lithiation processing.
- Enhanced Energy Density:Silicon-blended architectures and advanced carbon substrates enable gravimetric capacities exceeding 1,000 mAh/g, positioning these materials for premium passenger EV segments. ECHA carbon footprint declarations are accelerating renewable-powered processing investments.
- Fast Charging:Anode formulations optimized for lithium ion transport kinetics command specification premiums, though thermal management requirements constrain pack integration.
- Long Cycle Life:Graphite purity and electrolyte compatibility engineering dominate commercial vehicle applications where warranty obligations extend beyond eight years.
- Safety Features:Thermal runaway prevention and solid-electrolyte interphase stabilization are mandatory for KBA UN ECE R100 type-approval.
Enhanced energy density absorbs the bulk of R&D investment; fast charging is climbing the fastest as infrastructure deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German OEM procurement concentrates anode demand in southern industrial corridors. Bavaria and Baden-Württemberg host the majority of qualified cell production capacity.
Baden-Württemberg
Volkswagen and Porsche battery engineering centers drive qualification timelines for silicon-blended formulations. KBA enforces UN ECE R100 type-approval standards that extend validation cycles for novel chemistries. Stuttgart's automotive cluster anchors precursor material testing facilities serving southwestern assembly plants.
Bavaria
BMW cell development programs in Munich prioritize energy density specifications above 300 Wh/kg for premium platforms. ECHA carbon footprint declarations under the EU Battery Regulation mandate supply chain documentation from mining through purification. Dingolfing and Regensburg assembly corridors absorb qualified anode output from domestic chemical producers.
Lower Saxony
Volkswagen's Salzgitter cell gigafactory creates captive demand for high-volume anode material supply. The EU Battery Regulation's recycled content thresholds compel investment in European graphite purification rather than imported active materials. Wolfsburg engineering headquarters coordinates qualification protocols with southwestern chemical suppliers.
North Rhine-Westphalia
Mercedes-Benz battery development in Sindelfingen extends procurement specifications to independent cell producers. ECHA due diligence obligations for raw material sourcing expose anode manufacturers to supply concentration risks in natural graphite feedstock. Leverkusen and Düsseldorf chemical corridors sustain precursor production infrastructure.
Hesse
Robert Bosch GmbH's systems integration expertise positions battery management technologies alongside material partnerships. The EU Battery Regulation's mandatory carbon intensity disclosures per kWh accelerate renewable-powered thermal processing investments. Frankfurt-Rhine-Main logistics hubs facilitate just-in-time material flows to Bavarian assembly plants.
Germany Electric Vehicle Battery Anode Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue silicon-doped formulation specialization. Procurement consolidation around Volkswagen, BMW, and Mercedes-Benz cell factories compresses supplier negotiation leverage across all tiers. Three archetypes dominate: chemical conglomerates with integrated precursor capabilities, carbon specialists with purification expertise, and systems integrators with battery management technologies. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure long-term offtake agreements.
Among German-based chemical producers, BASF SE and Evonik Industries AG exemplify the conglomerate archetype with Ludwigshafen and Essen headquarters anchoring domestic precursor production. SGL Carbon SE represents the carbon specialist tier with synthetic graphite manufacturing capabilities. These three entities occupy positions within a supplier base consolidating around OEM captive cell production requirements.
| Leading Market Players |
|---|
| BASF SE |
| Varta AG |
| SGL Carbon SE |
| Evonik Industries AG |
| Robert Bosch GmbH |
| Innolith AG |
| Leclanché GmbH |
| Heraeus Holding GmbH |
| Wacker Chemie AG |
| Others |
Pricing and Supply Chain Analysis
ECHA carbon footprint declarations under the EU Battery Regulation gate both qualified supply access and premium-tier pricing eligibility for anode material producers serving German OEMs. Manufacturers lacking renewable-powered purification capacity or documented Scope 3 traceability face exclusion from long-term offtake negotiations with Volkswagen, BMW, and Mercedes-Benz cell factories.
Pricing Analysis
High-volume synthetic graphite contracts trade at compressed margins while silicon-blended formulations capture premium positioning. Contract-based long-term offtake agreements with volume commitments displace spot market transactions across all tiers. Price differentiation hinges on carbon purity certification and KBA UN ECE R100 qualification status, with unqualified imports facing structural cost disadvantages. Cost compression in standard graphite runs through energy-intensive spherical purification processes, while independent battery manufacturers exhibit greatest price sensitivity compared to captive OEM supply chains.
Supply Chain Analysis
Regional distribution centers in Ludwigshafen, Stuttgart, and Munich operate hub-and-spoke patterns feeding just-in-time material flows to Bavarian and Baden-Württemberg assembly corridors. Feedstock concentration in China for spherical graphite and Mozambique for natural flake creates single-source vulnerability exposure for European purification facilities. Raw material dependencies center on needle coke precursors, lithium metal powders for pre-lithiation, and silicon oxide composites. Distribution runs through dedicated chemical logistics corridors with batch-level traceability certification mandatory for EU Battery Regulation compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vertically integrated chemical conglomerates with domestic precursor capabilities, as ECHA due diligence obligations force specialized anode producers without purification assets toward acquisition or exit.
For Market Incumbents: Cement backward integration into needle coke production or renewable-powered thermal processing to defend margin position against Asian import competition. Secure captive supply relationships with Salzgitter, Heilbronn, and Kaiserslautern cell gigafactories through multi-year offtake commitments before independent battery manufacturers scale alternative supplier bases. For New Entrants and Emerging Players: Commercial vehicle fleet operators represent an underserved buyer archetype with distinct cycle-life specifications decoupled from passenger EV energy density races. Target fast-charging anode formulations for heavy-duty electric trucks where eight-year warranty obligations and KBA validation timelines deter established players from rapid reallocation of R&D resources. For Investors and Strategic Acquirers: Volkswagen's Salzgitter gigafactory achieving operational qualification for silicon-blended anodes is the leading indicator that domestic purification capacity will command scarcity premiums. Position acquisition screening around synthetic graphite specialists with existing ECHA carbon footprint documentation and renewable energy offtake agreements, treating KBA certification pipeline depth as the primary inflection signal for valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Needle Coke Production | BASF SE and Evonik Industries AG anchor domestic precursor supply chains against Asian import dependency. |
| Renewable-Powered Thermal Processing Investment | SGL Carbon SE's Ludwigshafen facilities achieve ECHA carbon footprint thresholds for BMW qualification programs. |
| Long-Term Offtake Agreement with OEM Cell Factories | Procurement consolidation around Volkswagen, BMW, and Mercedes-Benz compresses supplier negotiation leverage. |
| Silicon-Blended Formulation R&D Partnership | Robert Bosch GmbH leverages systems integration expertise alongside material partnerships for pre-lithiation technology. |
| KBA UN ECE R100 Certification Acceleration | Novel anode chemistries face 18-24 month validation delays that extend commercial deployment timelines. |
Research Methodology
Trade databases, ECHA regulatory filings, and KBA type-approval records formed the secondary backbone for supply chain mapping and carbon intensity benchmarking. Primary interviews with anode material procurement leads at German OEMs, purification plant managers in Ludwigshafen and Bavaria, and ECHA compliance officers validated secondary estimates. Bottom-up and top-down triangulation cross-referenced cell production capacity announcements against qualified anode supplier base expansion.
Bottom-up modeling aggregated individual gigafactory demand profiles across Salzgitter, Heilbronn, and Kaiserslautern facilities, while top-down analysis tracked EU Battery Regulation implementation timelines. Segmentation dimensions included anode chemistry type, vehicle application class, and end-user procurement structure. CAGRs derived from volume-weighted capacity utilization trajectories and silicon-blended formulation adoption curves across the projection horizon.
Revisions become necessary when ECHA enforcement intensity shifts, natural graphite export restrictions materialize, or silicon oxide composite technical barriers resolve faster than qualification timelines assume. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Asia-Pacific Lithium-Ion Battery Market
Lithium-ion Battery
Lithium Battery Components Market
Lithium-ion Battery
Germany SLI Battery Market
Lithium-ion Battery
Automotive 48-Volt Lithium Ion Battery Market
Lithium-ion Battery
Global Lithium-Ion Battery Energy Storage System Market
Lithium-ion Battery
Europe Solid State Battery Market
Lithium-ion Battery
Portable Lithium Battery Energy Storage Products Market
Lithium-ion Battery
South America Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
United Kingdom Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Next-Generation Lithium Batteries Market
Lithium-ion Battery
Middle East and Africa Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Lithium Manganate Battery Market
Lithium-ion Battery
Prismatic Lithium Cobalt Oxide (LiCoO2) Battery Market
Lithium-ion Battery
France Electric Vehicle Battery Anode Market
Lithium-ion Battery
Lithium-Ion Stationary Battery Storage Market
Lithium-ion Battery
Automotive 48V Lithium Battery Market