
 India Electric Vehicle Battery Anode Market | 2026-2036
India Electric Vehicle Battery Anode Market Size, Share, and Industry Trends Forecast 2026-2036
India Electric Vehicle Battery Anode Market Insights
Software-defined battery management is decoupling anode performance from hardware ownership, allowing fleet operators to pay for cycle life rather than purchase cells outright. Epsilon Advanced Materials leverages its synthetic graphite expertise to anchor domestic supply chains for NMC cell producers. Himadri Speciality Chemical Ltd. specializes in coal-tar pitch derivatives, occupying a critical position in precursor material availability. Exide Industries extends its legacy lead-acid distribution network to navigate the transition toward lithium-ion anode sourcing.
India electric vehicle battery anodes are carbon-based negative electrodes, typically composed of synthetic or natural graphite with particle sizes between 10-25 microns, engineered to intercalate lithium ions during charge cycles and deliver reversible capacities above 350 mAh/g in commercial formats. Graphite anodes currently dominate installed capacity due to mature supply chains and established compatibility with Indian cell assembly lines, while silicon-composite formulations represent the fastest-growing product type as manufacturers pursue energy density targets above 300 Wh/kg. Among end users, two-wheelers sustain the largest volume pull given India's position as the world's largest scooter and motorcycle market, though commercial vehicles are concentrating margin pools through higher per-pack anode content and stricter cycle-life requirements.
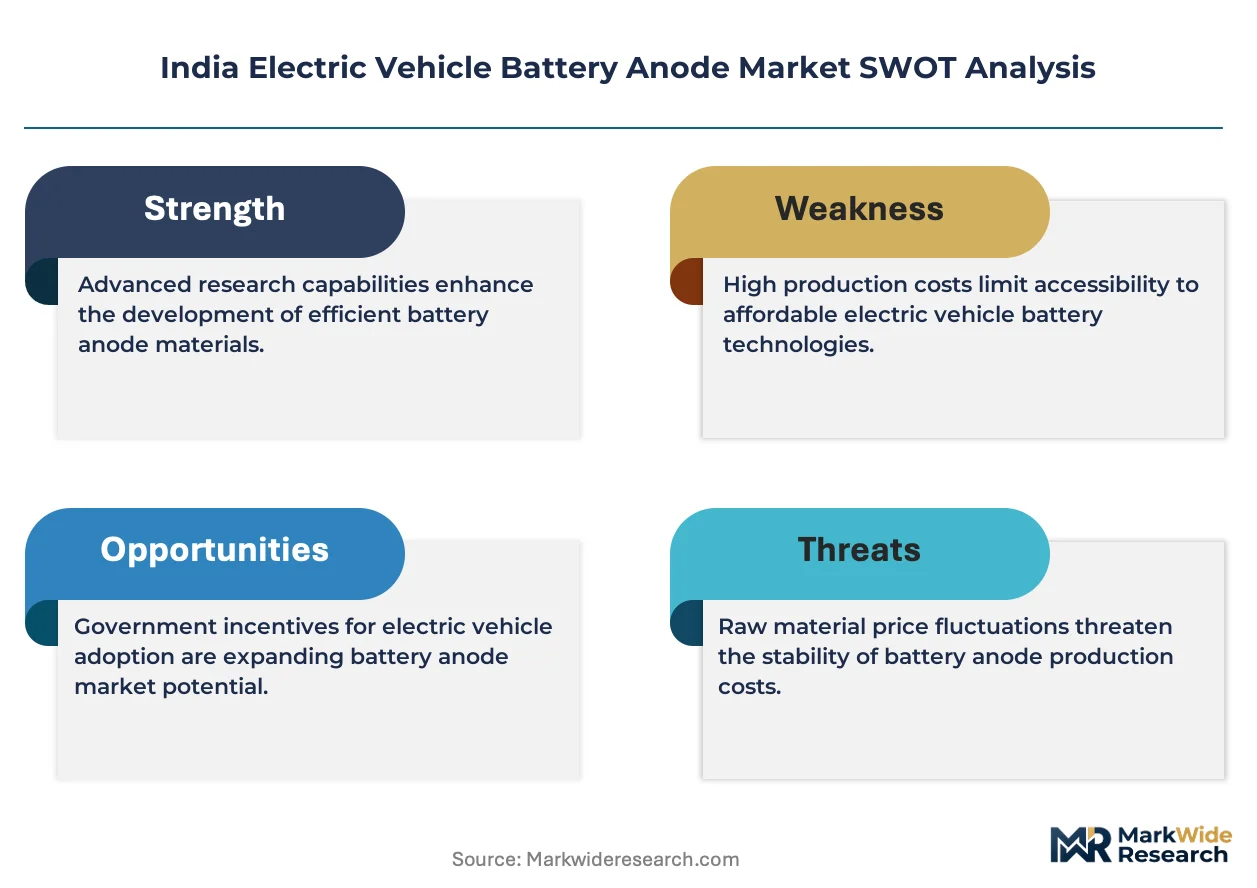
BIS certification mandates for cell and battery safety, coupled with the Ministry of Heavy Industries' PLI scheme disbursement criteria, are conditioning market access on domestic value addition thresholds and localized testing protocols. The Automotive Research Association of India and CEA technical standards for energy storage systems are further shaping anode specifications around thermal runaway prevention and fast-charging compatibility. Stakeholders must weigh backward integration into precursor synthesis against offtake partnerships with emerging Tamil Nadu and Gujarat gigafactory clusters.
Market Dynamics
India's PLI scheme for advanced chemistry cell manufacturing is redirecting capital toward domestic anode production, compressing procurement timelines for gigafactory operators while conditioning market access on localized value addition thresholds.
Growth Catalysts
- Production-Linked Incentive disbursement criteria:The Ministry of Heavy Industries mandates domestic value addition thresholds that accelerate backward integration into precursor synthesis for anode manufacturers.
- Tamil Nadu gigafactory clustering:Concentrated cell assembly investments in Sriperumbudur and Hosur are generating captive demand for synthetic graphite anodes within a 200-kilometer supply radius.
- Silicon-composite formulations:Energy density targets above 300 Wh/kg for commercial vehicle packs are pulling R&D investment toward silicon-doped anode architectures.
Market Restraints
- Petroleum needle coke import dependence:Precursor availability for synthetic graphite production concentrates in Chinese and Japanese refinery complexes, exposing margins to freight volatility and currency fluctuation.
- BIS certification timelines:Cell and battery safety mandates require localized testing protocols that extend qualification cycles for new anode suppliers by 8-12 months.
- Natural graphite substitution ceiling:Purity requirements for fast-charging compatibility limit natural graphite blending ratios below 15% in commercial formats, constraining cost-down pathways.
Strategic Opportunities
- Karnataka anode precursor corridor:Underdeveloped coal-tar pitch distillation capacity in Mangalore presents greenfield investment space for integrated pitch-to-anode operations.
- Battery-as-a-Service penetration:Two-wheeler fleet operators are separating cell ownership from vehicle ownership, creating recurring anode volume contracts indexed to cycle-life performance.
- CEA technical standards for energy storage:Grid-scale battery mandates are opening a parallel demand channel with less stringent energy density requirements than automotive applications.
Industry Challenges
- Graphitization furnace operator scarcity:High-temperature processing expertise for synthetic graphite conversion concentrates among a limited pool of technicians trained in electrode manufacturing.
- Automotive Research Association of India homologation:Thermal runaway test protocols require destructive sampling that consumes 15-20% of pilot production volumes during qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Electric Vehicle Battery Anode Market |
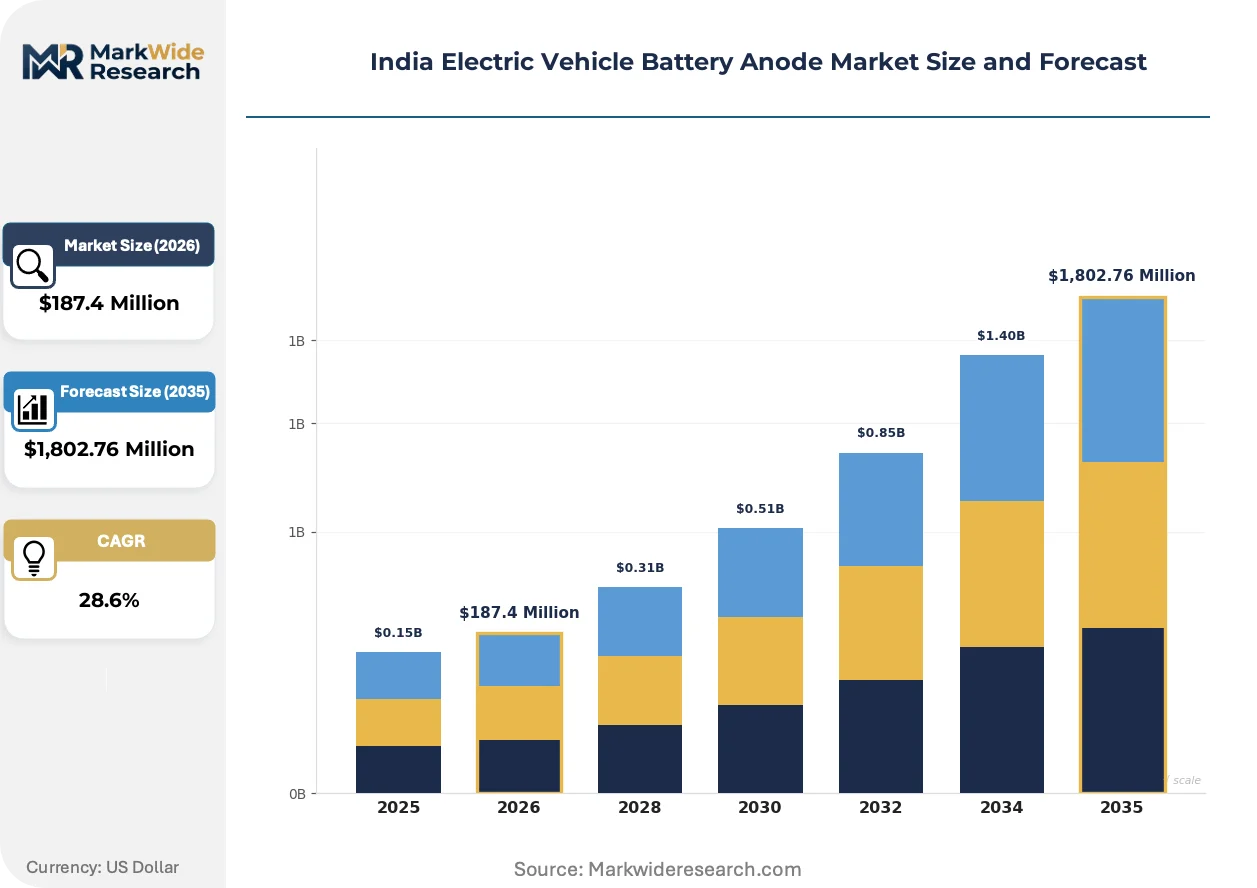
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,802.76 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Graphite, Silicon, Composite Feature: High Energy Density, Fast Charging, Long Cycle Life, Safety End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Buses Technology: Lithium Polymer, LiFePO4, NMC, Others |
| Companies Covered | PSL Limited, Epsilon Advanced Materials, Himadri Speciality Chemical Ltd., HEG Limited, BASF Shanshan Battery Materials Co., Targray Technology International Inc, Exide Industries, Amara Raja Batteries, Grinntech Motors & Services Pvt. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Electric Vehicle Battery Anode Market Trends and Innovations
Silicon-composite anode architectures are rewriting performance benchmarks for Indian cell manufacturers, compressing the gap between laboratory energy density targets and commercial pack deployment.
Silicon-doped graphite formulations intercalate lithium ions at capacities approaching 500 mAh/g while managing volumetric expansion through engineered void structures. Commercial vehicle pack assemblers in Gujarat are piloting these materials at 5-10% silicon loadings ahead of two-wheeler adoption. This chemistry is rewriting the cost-performance tradeoff for NMC cell producers by reducing anode mass fraction without sacrificing cycle stability.
BIS certification mandates for cell and battery safety are tightening material traceability requirements from precursor mining through final assembly. The standards now require batch-level documentation of particle size distribution and surface area metrics for graphite anodes. Tamil Nadu-based gigafactory operators are responding by qualifying dual-source anode suppliers to maintain production continuity during audit cycles.
Fleet operators are unbundling cell ownership from vehicle procurement through performance-based leasing structures that charge per kilometer based on guaranteed cycle life. Commercial vehicle aggregators in Maharashtra and Karnataka are driving this model, displacing upfront cell purchases with service contracts that transfer degradation risk to battery asset managers. This restructuring concentrates anode specification power among a smaller pool of fleet-scale buyers with technical due diligence capabilities.
India Electric Vehicle Battery Anode Market Segmentation
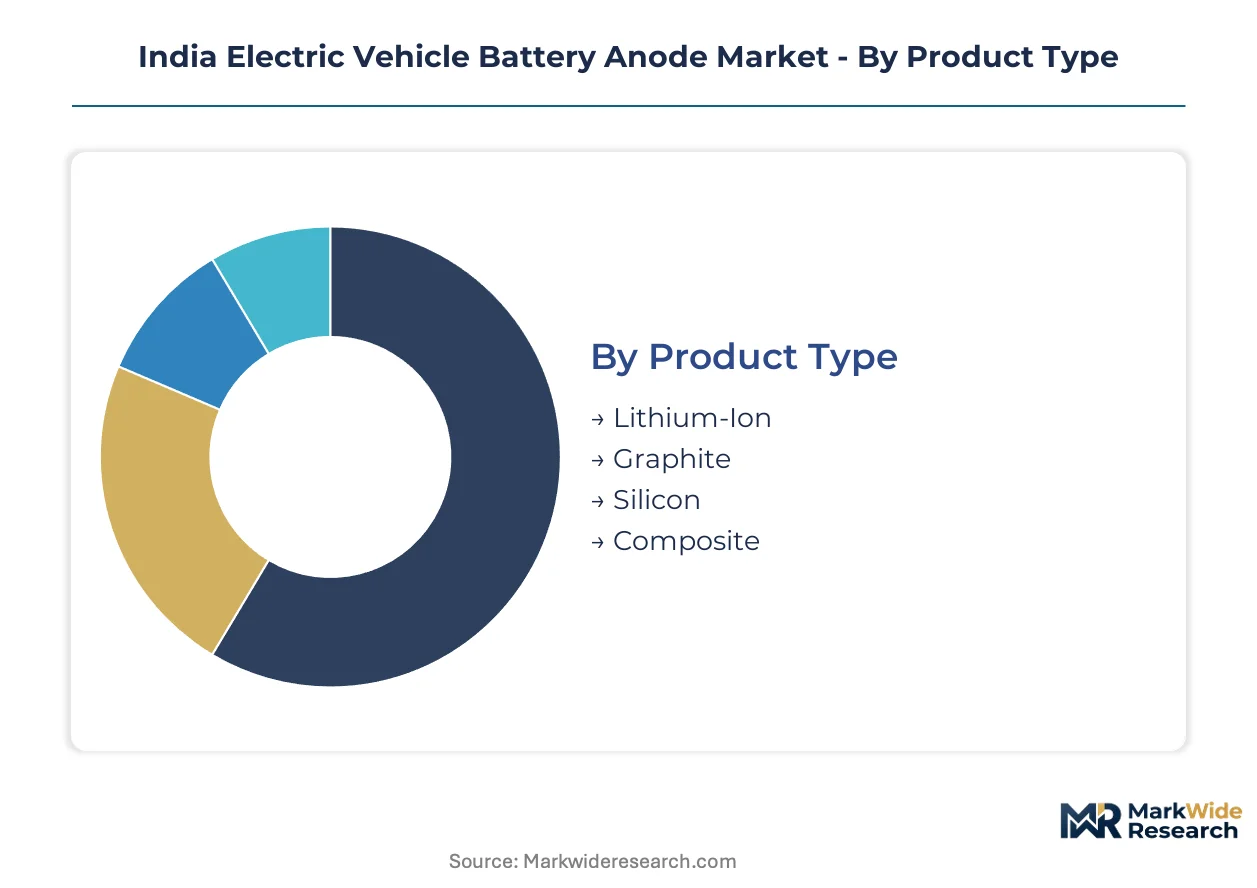
Anode procurement patterns in India diverge sharply across vehicle platforms and cell chemistries, with upgrade cycles compressing as gigafactory operators push for higher energy density formats. Fleet operators and OEMs now segment supplier qualifications by thermal runaway protocols and fast-charging compatibility rather than commodity graphite grades alone.
Product Type:
Replacement-cycle dynamics vary dramatically by anode chemistry, with silicon-composite formulations demanding earlier refresh schedules than graphite-dominant packs due to volumetric expansion stress.
- Graphite:Synthetic and natural graphite particles sized 10-25 microns deliver reversible capacities above 350 mAh/g. Tamil Nadu gigafactory clusters source predominantly synthetic grades from domestic graphitization operations to meet BIS certification batch-traceability mandates.
- Silicon:Silicon-doped architectures intercalate lithium at capacities approaching 500 mAh/g through engineered void structures. Gujarat-based commercial vehicle pack assemblers pilot 5-10% silicon loadings ahead of broader adoption, chasing energy density targets above 300 Wh/kg.
- Composite:Blended silicon-graphite formulations balance capacity gains against cycle stability degradation.
- Lithium-Ion:Catch-all category spanning intercalation compounds beyond carbon-based systems.
Volume placements concentrate in Graphite; the faster expansion belongs to Silicon.
Feature:
Performance specifications now stratify procurement tiers, with fast-charging capability commanding premium positioning in commercial fleet contracts.
- Fast Charging:Anode surface area and particle distribution optimization enables 15-minute charge windows. Purity requirements constrain natural graphite blending below 15% in these formats, locking in synthetic graphite cost structures.
- High Energy Density:Gravimetric targets above 250 Wh/kg at pack level drive silicon-composite adoption in premium two-wheeler segments.
- Long Cycle Life:Performance-based leasing contracts index payments to guaranteed cycle counts, elevating specification scrutiny.
- Safety:Thermal runaway prevention protocols under ARAI homologation consume 15-20% of pilot production volumes during destructive qualification testing.
Fast Charging commands the steepest premium tier; Long Cycle Life anchors fleet procurement decisions.
End User:
Vehicle platform segmentation determines anode mass per pack and cycle-life requirements, with commercial applications generating higher per-unit material consumption.
- Two-Wheelers:India's scooter and motorcycle market sustains the largest volume pull for anode materials. Battery-as-a-Service penetration in Maharashtra and Karnataka is unbundling cell ownership from vehicle procurement, creating recurring volume contracts.
- Commercial Vehicles:Higher per-pack anode content and stricter cycle-life requirements concentrate margin pools. Fleet aggregators transfer degradation risk to battery asset managers through performance-based leasing structures.
- Passenger Vehicles:OEM-directed procurement favors established synthetic graphite supply chains with qualified BIS documentation.
- Buses:State transport undertakings drive demand with standardized pack formats and extended warranty requirements.
Two-Wheelers dominate unit volumes; Commercial Vehicles capture the expanding margin pool.
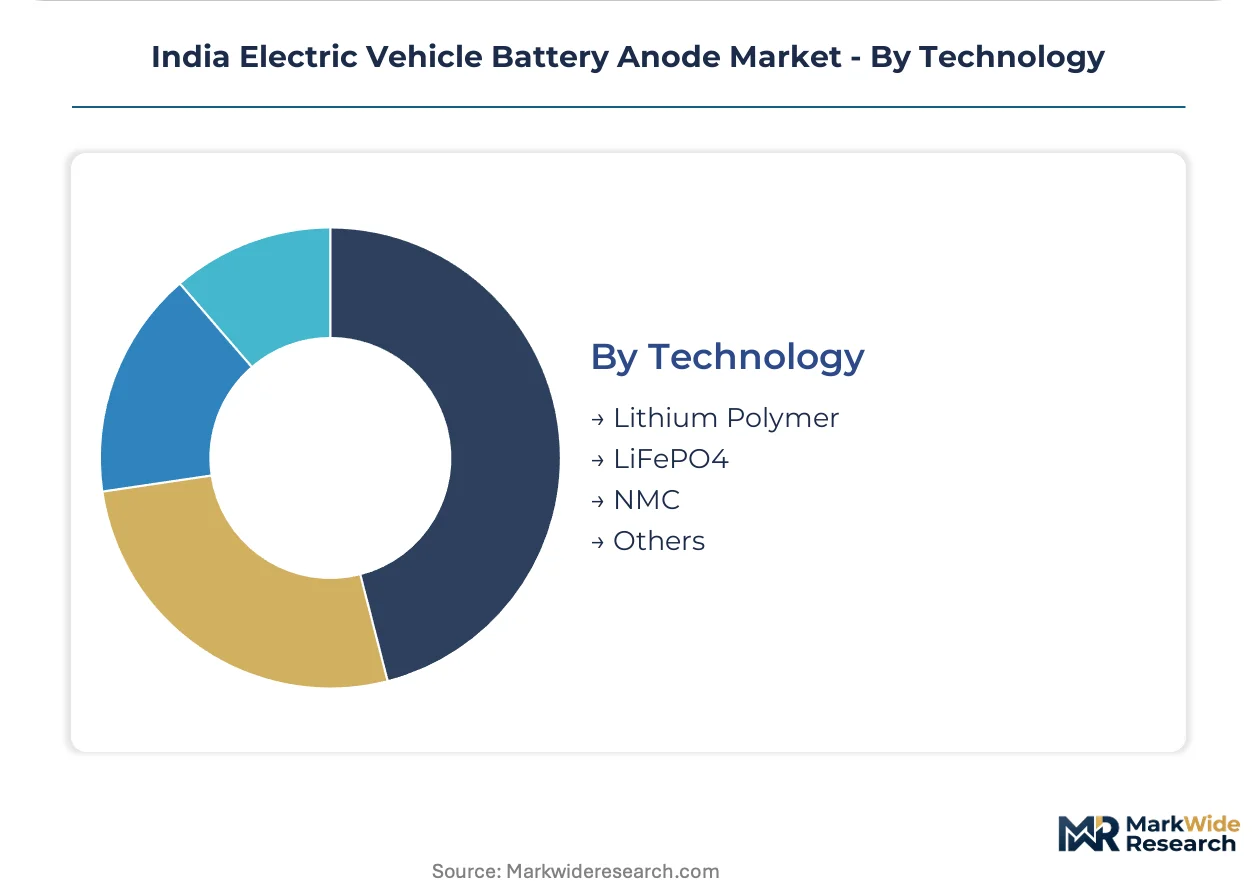
Technology:
Cell chemistry selection gates anode compatibility, with NMC and LFP formats diverging on carbon grade specifications and silicon doping tolerance.
- NMC:Nickel-manganese-cobalt cathode pairings with graphite or silicon-composite anodes target energy density above 300 Wh/kg. Epsilon Advanced Materials anchors domestic supply chains for these cell producers.
- LiFePO4:Lithium iron phosphate chemistry tolerates lower-cost natural graphite blends but sacrifices energy density. Grid-scale CEA-mandated storage applications favor this chemistry for thermal stability.
- Lithium Polymer:Pouch cell formats with gel electrolyte configurations.
- Others:Emerging sodium-ion and solid-state architectures with unproven anode specifications.
NMC claims the premium automotive tier; LiFePO4 scales fastest in grid-storage parallel demand channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's anode production capacity lags behind domestic cell assembly investments, creating import dependence for synthetic graphite precursors while Tamil Nadu and Gujarat concentrate gigafactory demand.
Tamil Nadu
Sriperumbudur and Hosur host concentrated cell assembly investments generating captive demand within a 200-kilometer supply radius. The state's industrial policy offers capital subsidies for advanced chemistry cell manufacturing. Epsilon Advanced Materials anchors synthetic graphite supply chains for NMC cell producers in this corridor.
Gujarat
Commercial vehicle pack assemblers pilot silicon-doped anode architectures at 5-10% loadings to chase energy density targets above 300 Wh/kg. The state's electronics manufacturing clusters benefit from streamlined environmental clearances for battery material projects. Hazira and Sanand industrial zones attract precursor distillation investments.
Karnataka
Two-wheeler fleet operators in Bengaluru and Pune markets drive Battery-as-a-Service penetration, unbundling cell ownership from vehicle procurement. The state government's EV policy mandates 100% electric public transport procurement by 2030. Mangalore presents greenfield investment space for integrated pitch-to-anode operations.
Maharashtra
Commercial vehicle aggregators transfer degradation risk to battery asset managers through performance-based leasing structures indexed to cycle life. The state's industrial infrastructure supports automotive R&D centers testing fast-charging compatibility protocols. Mumbai-Pune corridor logistics operators concentrate margin pools through higher per-pack anode content.
India Electric Vehicle Battery Anode Market Competitive Landscape
Top-tier vendors anchor synthetic graphite supply chains, while mid-scale specialists occupy precursor synthesis niches and emerging players target silicon-composite formulations. The vendor base stratifies across three archetypes: integrated material processors with graphitization furnace assets, coal-tar pitch derivative specialists controlling precursor availability, and legacy battery manufacturers extending distribution networks into lithium-ion sourcing. Capacity expansion and backward integration into needle coke procurement represent the dominant competitive moves.
Within the integrated processing tier, Epsilon Advanced Materials and HEG Limited occupy positions as synthetic graphite anchors for domestic NMC cell producers. Himadri Speciality Chemical Ltd. exemplifies the precursor-specialist archetype through coal-tar pitch derivative operations. Exide Industries represents legacy battery manufacturers navigating the transition from lead-acid distribution toward lithium-ion anode sourcing. These three company types collectively map the competitive structure: furnace operators, pitch distillers, and channel extenders.
| Leading Market Players |
|---|
| PSL Limited |
| Epsilon Advanced Materials |
| Himadri Speciality Chemical Ltd. |
| HEG Limited |
| BASF Shanshan Battery Materials Co. |
| Targray Technology International Inc |
| Exide Industries |
| Amara Raja Batteries |
| Grinntech Motors & Services Pvt. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Captive graphitization furnace operations anchor synthetic graphite producers to fixed-cost structures that insulate pricing power against petroleum needle coke volatility. Tamil Nadu gigafactory operators leverage this backward integration to negotiate long-term offtake contracts indexed to BIS certification batch-traceability premiums rather than spot commodity movements.
Pricing Analysis
Cost-down pressure on synthetic graphite anodes accelerates because petroleum needle coke import dependence exposes margins to freight volatility and currency fluctuation. Three-tier pricing structure across premium, standard, and economy levels stratifies by BIS certification grade and fast-charging compatibility protocols. Fleet operators with Battery-as-a-Service contracts exhibit lowest price sensitivity due to cycle-life performance guarantees, while unaffiliated two-wheeler OEMs drive hardest bargain on per-kilogram contract terms.
Supply Chain Analysis
BIS certification timelines and ARAI homologation protocols gate supplier qualification, extending procurement cycles by 8-12 months for new market entrants. Raw material flows draw from Chinese and Japanese petroleum needle coke refineries, Indian coal-tar pitch distillation corridors, and Australian natural graphite mining operations. Single-source vulnerability concentrates in graphitization furnace operator scarcity among electrode manufacturing technicians. Distribution runs through Tamil Nadu and Gujarat gigafactory clusters with 200-kilometer supply radius requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's electric vehicle battery anode market operates as a supply-constrained environment where graphitization furnace capacity scarcity props pricing premiums for qualified domestic suppliers.
For Market Incumbents: Acquire graphitization furnace assets and trained technician pools to consolidate synthetic graphite production capacity ahead of PLI scheme disbursement waves. Lock in multi-year petroleum needle coke supply contracts with Japanese refineries before currency volatility escalates. Silicon-composite formulation R&D from Gujarat commercial vehicle pilots threatens to displace graphite-dominant architectures within the analysis window. For New Entrants and Emerging Players: The 15-20% pilot production volume consumed by ARAI destructive qualification testing creates a price-point gap between established BIS-certified suppliers and unqualified imports. Target Karnataka's underdeveloped Mangalore pitch-to-anode corridor for greenfield integrated operations. Grid-scale CEA-mandated energy storage applications offer fastest certification pathway with less stringent energy density requirements than automotive segments. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of precursor-specialist firms with coal-tar pitch derivative operations and established BIS documentation workflows. Long-term viability over the next decade hinges on silicon-composite formulation capabilities and captive needle coke procurement positions. Watch for PLI scheme disbursement acceleration as inflection signal for domestic capacity utilization rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Needle Coke Procurement | Captive petroleum needle coke supply from Japanese refineries insulates Epsilon Advanced Materials from freight volatility. |
| Silicon-Composite Formulation Scale-Up | Gujarat commercial vehicle pack assemblers pilot 5-10% silicon loadings to chase 300 Wh/kg energy density targets. |
| BIS Certification Dual-Source Qualification | Tamil Nadu gigafactory operators maintain production continuity during audit cycles through qualified secondary suppliers. |
| Battery-as-a-Service Platform Launch | Maharashtra and Karnataka fleet operators unbundle cell ownership from vehicle procurement through cycle-life indexed contracts. |
| Graphitization Furnace Capacity Expansion | HEG Limited and domestic electrode manufacturers leverage high-temperature processing expertise for synthetic graphite conversion. |
Research Methodology
Ministry of Heavy Industries PLI scheme disbursement records, BIS certification databases, and CEA technical standards documentation formed the secondary backbone for supply-side capacity mapping. Primary interviews with graphitization furnace operators, coal-tar pitch procurement leads at Himadri Speciality Chemical, Tamil Nadu gigafactory supply chain directors, and ARAI homologation officers validated production volume assumptions. Bottom-up cell assembly capacity estimates from Sriperumbudur and Hosur industrial zones were triangulated against top-down anode material consumption models.
Bottom-up segmentation by vehicle platform, cell chemistry, and anode material grade was cross-referenced against top-down PLI incentive allocation trajectories across the projection horizon. Modeled dimensions include synthetic versus natural graphite sourcing, silicon-composite adoption curves, fast-charging compatibility tiers, and Battery-as-a-Service penetration rates by state. CAGRs were derived from installed cell assembly capacity timelines and anode mass-per-pack technical specifications. Petroleum needle coke import volumes and currency fluctuation bands fed sensitivity analysis.
Inputs from ARAI thermal runaway test protocols and BIS batch-traceability audit cycles were available through the study window; gaps in silicon-composite long-term degradation data introduce uncertainty bands around cycle-life performance guarantees. Forecasts reflect documented assumptions regarding PLI scheme continuation and gigafactory construction schedules. A model refresh is warranted upon material change in Ministry of Heavy Industries disbursement criteria or CEA grid-scale storage mandate acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium-Ion Battery Pack for Consumer Market
Lithium-ion Battery
North America Lithium-Ion Battery Market
Lithium-ion Battery
Lithium-Ion Polymer Batteries Market
Lithium-ion Battery
Global Nanowire Battery Market
Lithium-ion Battery
Automotive 48-Volt Lithium Ion Battery Market
Lithium-ion Battery
Automotive Cylindrical Lithium Batteries Market
Lithium-ion Battery
Next Generation Advanced Battery Market
Lithium-ion Battery
Asia-Pacific Solid State Battery Market
Lithium-ion Battery
Lithium-Ion Battery Anode Market
Lithium-ion Battery
Automotive Lithium Based Battery Market
Lithium-ion Battery
Li-Ion Portable Battery Market
Lithium-ion Battery
Global Pin Type Lithium-Based Battery Market
Lithium-ion Battery
Lithium Nickel Manganese Cobalt Oxide Battery Market
Lithium-ion Battery
South America Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Lithium Ion Energy Accumulator Market
Lithium-ion Battery
Lithium-Air Battery Market