
 Lithium Recycling Market | 2026-2036
Lithium Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Recycling Market Insights
Automotive battery procurement is pivoting toward recycled feedstock as OEMs lock in long-term cathode supply. Brunp Recycling leverages integrated pyrometallurgical capacity across southern China. Redwood Materials anchors North American collection infrastructure for end-of-life EV packs. Umicore competes on hydrometallurgical purity that meets battery-grade lithium carbonate specifications.
Lithium recycling recovers lithium, cobalt, nickel, and manganese from spent lithium-ion cells through hydrometallurgical leaching, pyrometallurgical smelting, or mechanical shredding followed by chemical purification, yielding materials that re-enter cathode active material production. Hydrometallurgical routes dominate capacity additions due to lower energy intensity and higher lithium recovery rates compared to pyrometallurgical alternatives. Battery-grade output commands premium positioning within the grade taxonomy, while automotive end-use absorbs the majority of recovered cathode material volumes.
The EU Battery Regulation and REACH frameworks mandate minimum recycled content thresholds and restrict hazardous substance leakage, compelling recyclers to certify closed-loop material flows. China's MIIT issues dual carbon-aligned standards that favor hydrometallurgical investments with sub-50 kWh per ton energy footprints. Stakeholders must monitor feedstock security as EV retirement curves diverge from installed recycling nameplate across major economies.
Market Dynamics
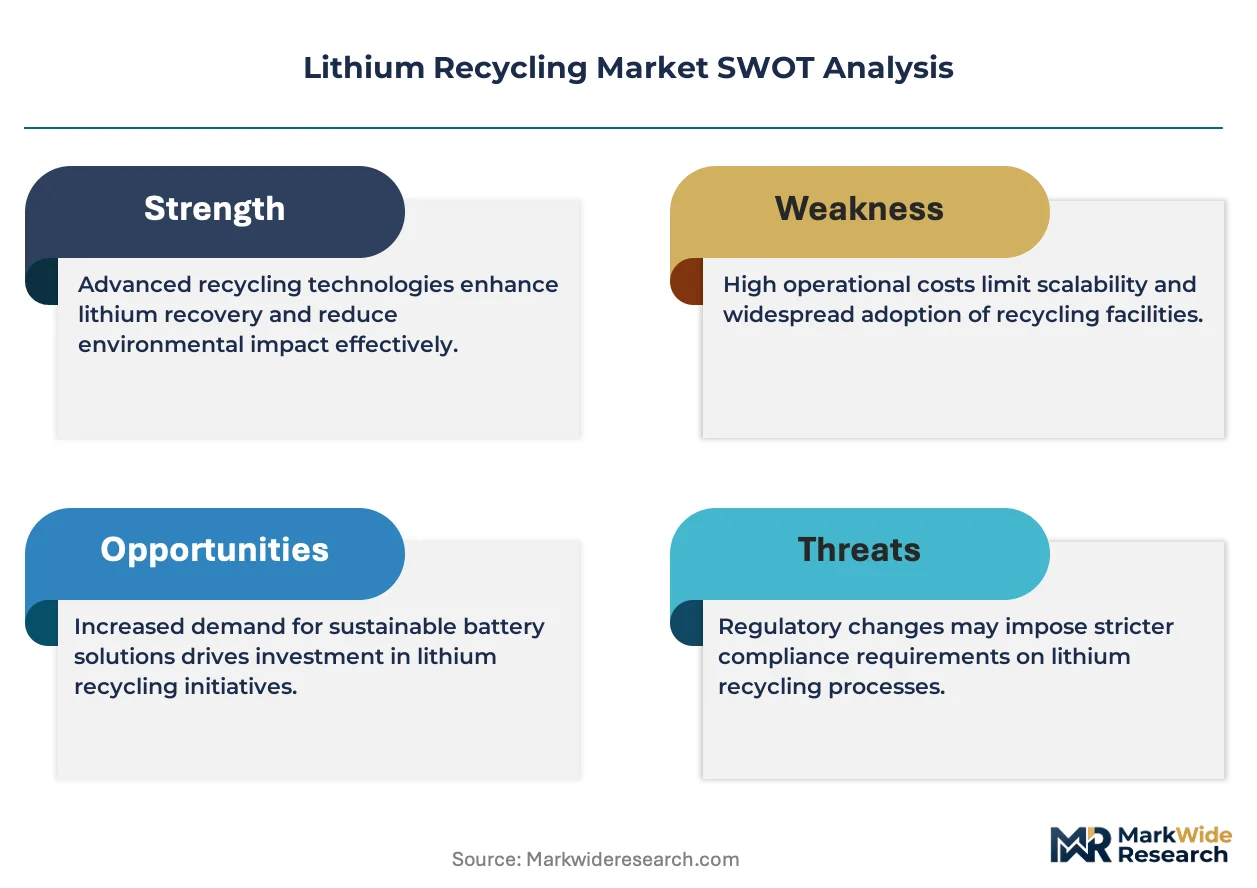
EU Battery Regulation mandates are compressing timelines for recycled content certification, forcing recyclers to secure feedstock contracts before nameplate capacity comes online. This regulatory pull is restructuring competitive positioning around hydrometallurgical purity and closed-loop traceability systems.
Growth Catalysts
- EU Battery Regulation thresholds:Minimum recycled content mandates for lithium, cobalt, and nickel in new EV batteries create guaranteed offtake for certified recyclers. The regulation phases in stricter requirements through 2031.
- Automotive OEM cathode procurement:Electric vehicle manufacturers are locking decade-long supply agreements with recyclers to hedge against primary lithium price volatility and ESG compliance risks.
- Pyrometallurgical-hydrometallurgical hybrid flowsheets:Integrated processing routes achieve higher lithium recovery rates than standalone methods, attracting capital toward multi-stage facilities.
Market Restraints
- Feedstock supply concentration:End-of-life EV battery availability clusters in China, creating geographic mismatch with planned recycling capacity in Europe and North America.
- Spent battery collection infrastructure gaps:Reverse logistics networks for hazardous lithium-ion transport remain underdeveloped outside established automotive dismantling corridors.
- Primary lithium price volatility:Hard rock and brine extraction cost curves directly compress margins for recycled material when spot prices collapse below $12,000 per ton carbonate equivalent.
Strategic Opportunities
- Stationary energy storage second-life applications:Retired EV packs with 70-80% remaining capacity can defer recycling costs by 5-7 years while serving grid-scale storage before final material recovery.
- US Inflation Reduction Act domestic content credits:Clean vehicle tax incentives for North American-sourced critical minerals create preferential pricing for US-based recycled lithium.
- Direct recycling cathode regeneration:Emerging electrochemical processes promise to rebuild cathode active materials without full elemental separation, cutting energy intensity by half.
Industry Challenges
- Battery-grade lithium carbonate certification timelines:Achieving automotive OEM qualification for recycled material requires 18-24 months of continuous pilot production and third-party assay verification.
- Skilled pyrometallurgical engineer scarcity:The specialized workforce for high-temperature lithium recovery operations is concentrated at legacy nickel and copper smelters, not battery supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Recycling Market |
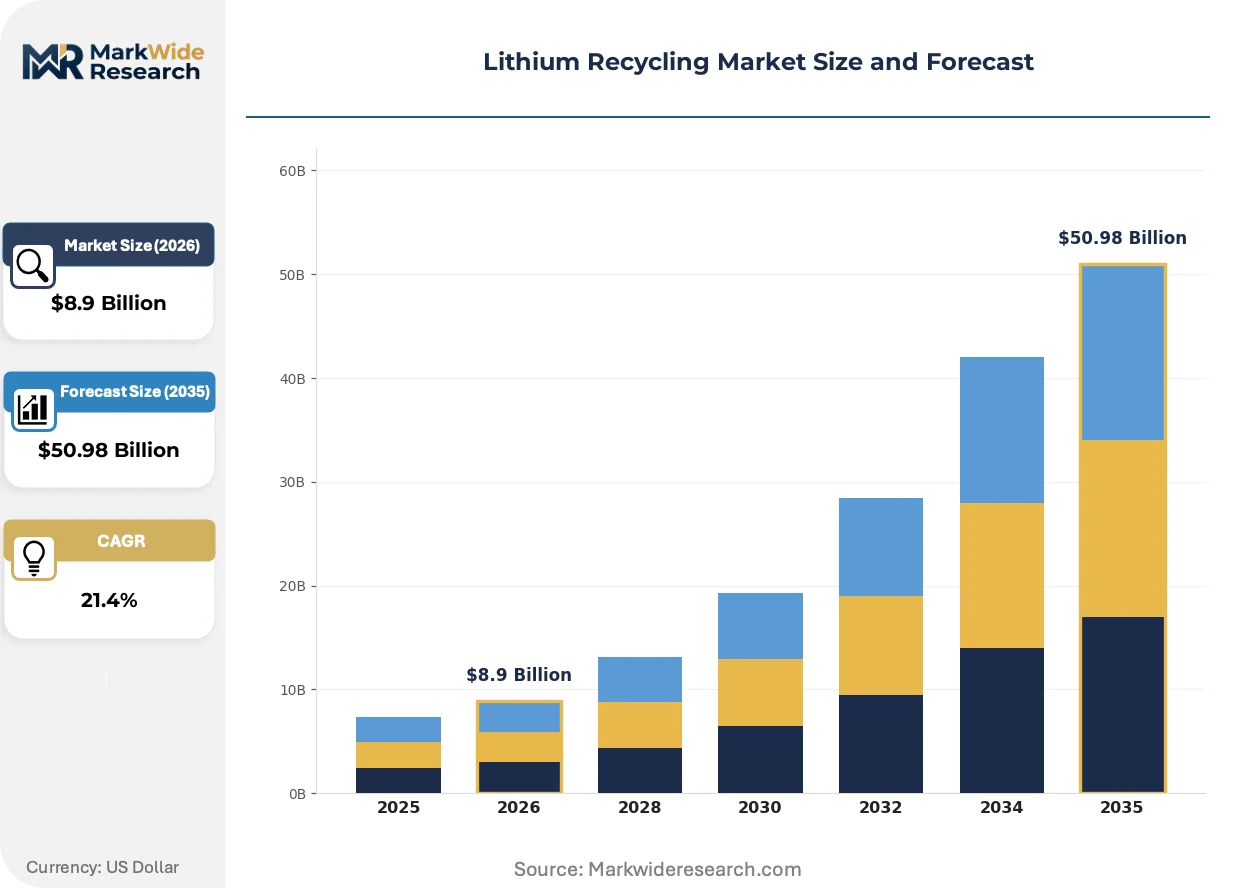
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $50.98 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Hydrometallurgical, Pyrometallurgical, Biotechnological, Mechanical Product Type: Cathode, Anode, Lithium Salts, Battery Packs End User: Automotive, Electronics, Energy Storage, Industrial Grade: Battery Grade, Technical Grade, Reagent Grade, Others |
| Companies Covered | Brunp Recycling, GEM Co., Ltd., Umicore, Glencore, Li-Cycle Holdings Corp., Redwood Materials, Inc., American Battery Technology Company, Fortum, Ecobat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Recycling Market Trends and Innovations
Recycling technology is converging toward closed-loop material flows that bypass primary extraction entirely. Three forces are compressing the pathway from spent cell to cathode powder.
Direct cathode regeneration is unifying mechanical separation with electrochemical relithiation in single-process lines. Battery manufacturers in South Korea and Japan are piloting this approach to slash re-manufacturing costs. The technology is unifying previously separate shredding, leaching, and re-synthesis stages into continuous flow production.
REACH substance restrictions are tightening impurity thresholds for recovered cobalt and nickel entering EU battery supply chains. ECHA hazard classifications now cover additional solvent residues from hydrometallurgical processing. European recyclers are responding by investing in multi-stage purification and blockchain traceability to document compliance.
Automotive OEMs are consolidating cathode procurement through dedicated recycling joint ventures rather than spot market purchasing. This long-term contracting model displaces merchant market volumes and locks in price floors. The shift is most visible in Germany and Sweden, where Volvo and Northvolt have established captive recycling pipelines.
Lithium Recycling Market Segmentation
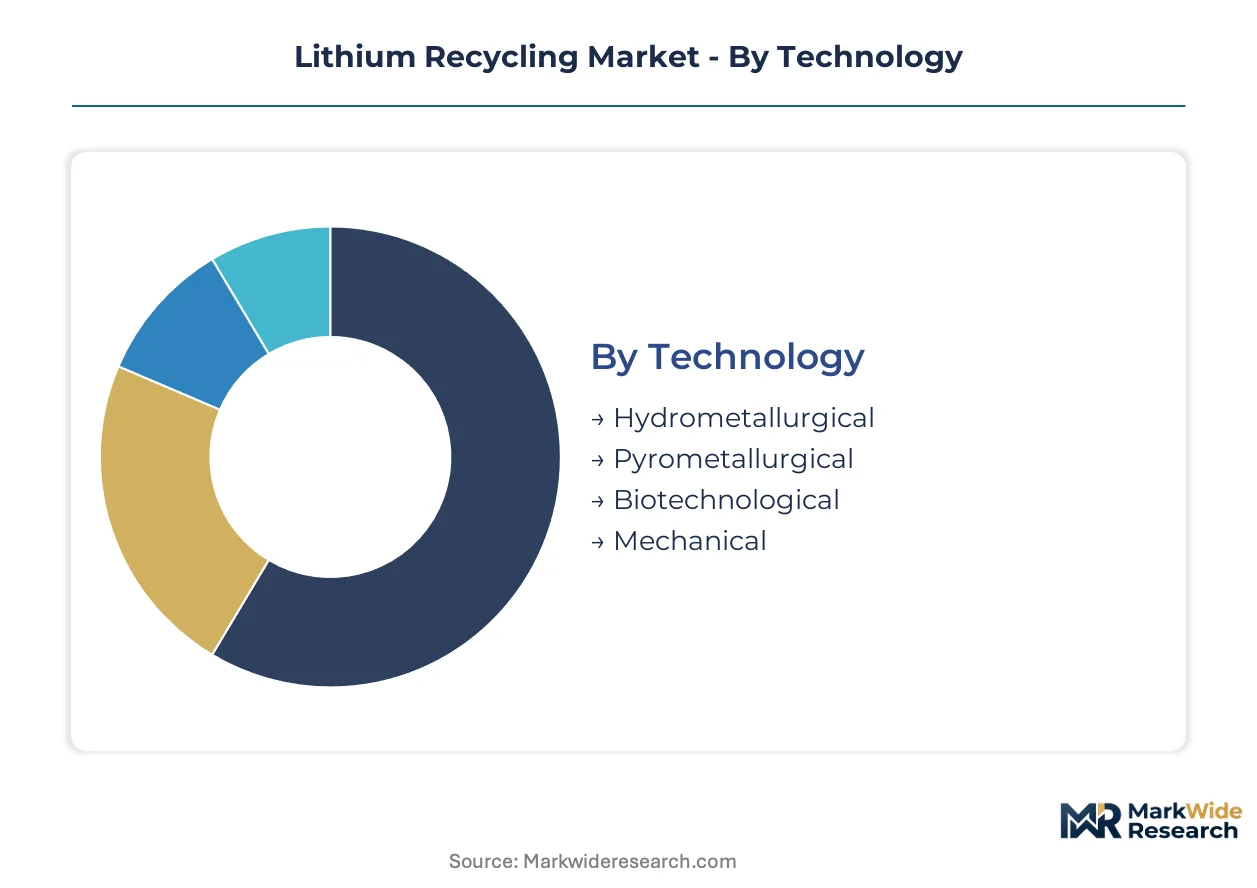
Recyclers configure process flows around feedstock chemistry and end-use specifications. Technology selection determines recovery rates and energy intensity. Product purity tiers align with cathode manufacturer qualification requirements.
Technology:
Upgrade cycles in processing technology track tightening recovery efficiency mandates and energy footprint regulations.
- Hydrometallurgical:Leaching-based extraction employs acid dissolution and solvent precipitation to isolate lithium, cobalt, and nickel with recovery rates exceeding 95%. European recyclers favor this route for its alignment with EU Green Deal energy intensity targets and REACH solvent management frameworks.
- Pyrometallurgical:High-temperature smelting reduces metal oxides to alloy phases requiring subsequent hydrometallurgical refinement. China dominates installed capacity here, leveraging legacy non-ferrous smelter infrastructure and MIIT dual carbon standards that accommodate energy-intensive operations with emissions capture.
- Biotechnological:Bioleaching employs acidophilic bacteria to mobilize metals from crushed cell material at ambient temperatures.
- Mechanical:Physical shredding and separation stages precede chemical processing, concentrating black mass for downstream refinement.
Hydrometallurgical sits at the top of the volume ranking, with biotechnological climbing the fastest.
Product Type:
Cost tier differentiation separates commodity outputs from qualified battery-grade materials commanding substantial premiums.
- Cathode:Recovered nickel-cobalt-manganese and lithium iron phosphate powders undergo relithiation and particle engineering to meet OEM specifications. Automotive cathode procurement contracts specify traceable recycled content percentages under EU Battery Regulation thresholds.
- Lithium Salts:Battery-grade lithium carbonate and hydroxide emerge from purification cascades with impurity profiles matching brine and spodumene equivalents. Korean cathode manufacturers qualify these salts for high-nickel NCM production lines.
- Anode:Graphite recovery from spent cells remains technically challenging, with most material currently downcycled to lower-value applications.
- Battery Packs:Module-level refurbishment targets second-life stationary storage before eventual material recovery.
Cathode materials sit at the top of the volume ranking, with lithium salts climbing the fastest.
End User:
Application-specific purity requirements and contract structures fragment demand across customer categories.
- Automotive:OEMs impose the most stringent qualification protocols, requiring 18-24 months of continuous production data and third-party assay verification. Long-term offtake agreements now span 7-10 years as manufacturers secure ESG-compliant supply.
- Energy Storage:Grid-scale battery developers accept broader specification ranges, prioritizing cost over traceability for stationary applications.
- Electronics:Consumer device manufacturers source recovered cobalt for supply chain transparency reporting.
- Industrial:Non-battery applications including lubricants and ceramics absorb lower-purity lithium streams.
Automotive sits at the top of the volume ranking, with energy storage climbing the fastest.
Grade:
Margin structures widen dramatically between certified battery-grade output and technical-grade alternatives.
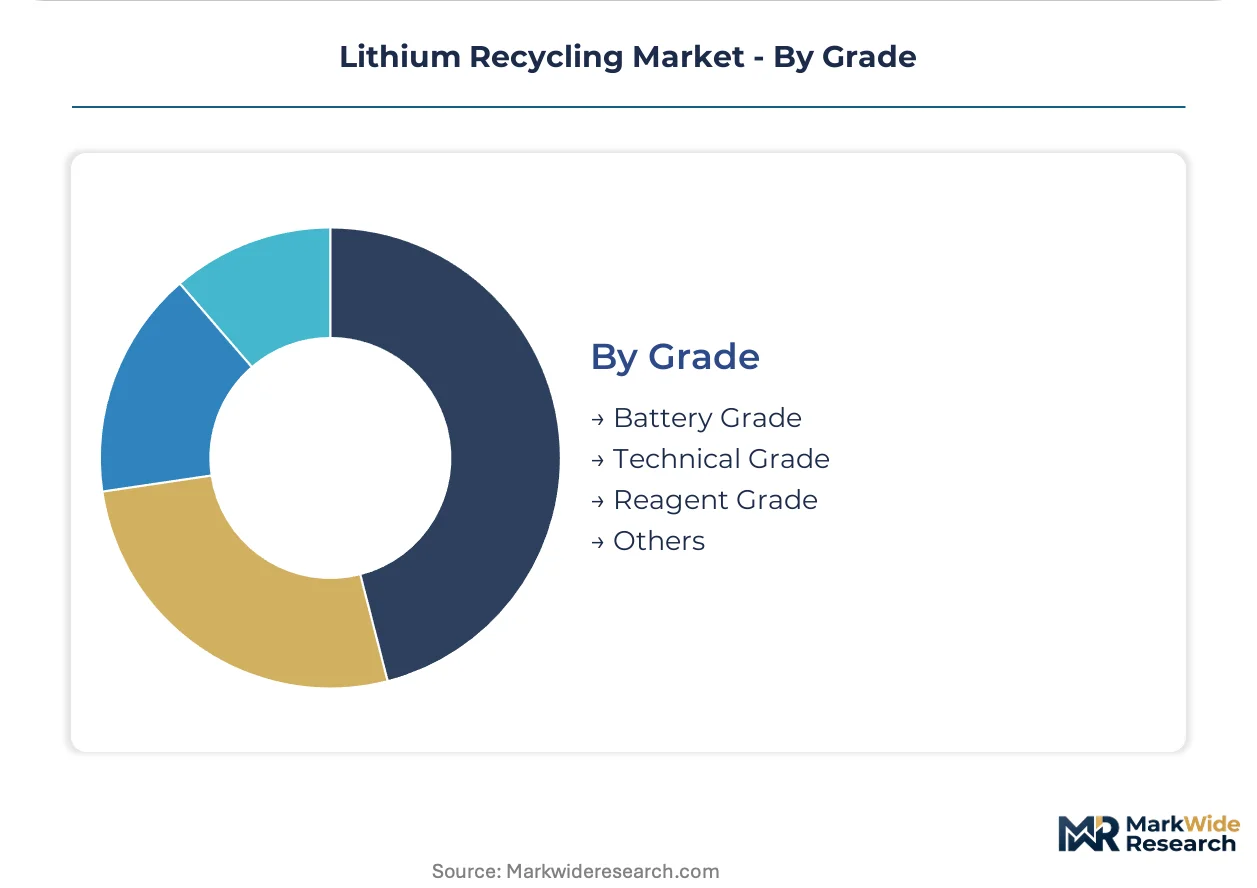
- Battery Grade:Sub-20 ppm impurity thresholds for sodium, calcium, and magnesium enable direct incorporation into cathode active material synthesis. Qualification with Samsung SDI, LG Chem, and CATL separates premium recyclers from merchant market suppliers.
- Technical Grade:Moderate purity lithium carbonate serves glass, ceramics, and metallurgical flux applications with less demanding specifications.
- Reagent Grade:Laboratory and pharmaceutical applications require additional purification stages.
- Others:Unclassified or blended outputs sell into industrial chemical markets.
Battery grade sits at the top of the volume ranking, with technical grade climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting lithium recycling investment toward jurisdictions with the widest gap between compliance costs and subsidy intensity. Capital flows concentrate where feedstock access, energy pricing, and carbon-accounting rules create favorable unit economics.
China
MIIT dual-carbon standards favor hydrometallurgical investments with sub-50 kWh per ton energy footprints. Brunp Recycling and GEM Co., Ltd. anchor integrated pyrometallurgical capacity across Guangdong and Hunan provinces. The Yangtze River Delta cluster hosts the densest concentration of cathode material recovery demand.
Germany
Automotive OEM cathode procurement is consolidating through dedicated recycling joint ventures under EU Battery Regulation thresholds. ECHA REACH frameworks mandate multi-stage purification for recovered cobalt and nickel entering battery supply chains. Northvolt's Skellefteå-adjacent pipeline exemplifies captive recycling integration.
United States
US Inflation Reduction Act domestic content credits create preferential pricing for North American-sourced recycled lithium. EPA hazardous waste transport rules shape reverse logistics network development. Redwood Materials anchors collection infrastructure across Nevada and the broader Southwest.
South Korea
Korean cathode manufacturers qualify recycled lithium salts for high-nickel NCM production lines under MFDS-aligned purity protocols. Samsung SDI and LG Chem impose 18-24 month qualification timelines on recycled material suppliers. The Seoul Capital Area concentrates battery-grade certification demand.
Belgium
Umicore competes on hydrometallurgical purity that meets battery-grade lithium carbonate specifications. ECHA substance restrictions tighten impurity thresholds for recovered materials entering EU supply chains. The Antwerp-Rotterdam port cluster facilitates black mass import logistics from end-of-life EV retirement corridors.
Lithium Recycling Market Competitive Landscape
Capacity expansion dominates the current landscape as recyclers race to lock in feedstock contracts before nameplate facilities come online. The vendor base stratifies across integrated smelter operators, pure-play hydrometallurgical specialists, and automotive-captive joint ventures. Three archetypes anchor competitive positioning: Chinese state-linked industrial conglomerates with legacy non-ferrous infrastructure; European chemical multinationals with hydrometallurgical purity capabilities; and North American venture-backed platforms building collection-first networks. M&A activity and long-term offtake contracting represent the dominant competitive moves, with OEMs acquiring equity stakes to secure ESG-compliant supply.
Within the integrated industrial conglomerate tier, Brunp Recycling and GEM Co., Ltd. exemplify state-linked players leveraging legacy pyrometallurgical infrastructure across southern China. Umicore occupies a position representing European chemical-multinational archetypes competing on hydrometallurgical purity and REACH-aligned traceability systems. Redwood Materials anchors the North American venture-backed platform model, building collection infrastructure before downstream refining capacity.
| Leading Market Players |
|---|
| Brunp Recycling |
| GEM Co., Ltd. |
| Umicore |
| Glencore |
| Li-Cycle Holdings Corp. |
| Redwood Materials, Inc. |
| American Battery Technology Company |
| Fortum |
| Ecobat |
| Others |
Pricing and Supply Chain Analysis
Captive recycling joint ventures between automotive OEMs and hydrometallurgical specialists anchor both supply security and pricing power in the lithium recovery sector. This integration pattern locks in decade-long offtake agreements that bypass volatile spot markets for battery-grade lithium carbonate.
Pricing Analysis
Direct-to-OEM contracting eliminates distributor margins and compresses price discovery into bilateral negotiations between cathode manufacturers and certified recyclers. Contract-based long-term offtake dominates, with price differentiation driven by battery-grade certification status and volume scale commitments. Cost compression in technical-grade streams is intensifying because primary lithium spot prices periodically collapse below recycling breakeven thresholds. Energy storage developers exhibit the highest price sensitivity, while automotive OEMs prioritize traceability over unit cost.
Supply Chain Analysis
US Inflation Reduction Act domestic content credits and EU Battery Regulation recycled-content mandates are reshaping sourcing patterns toward regionalized feedstock security. Geographic supply concentrates in China, Germany, and the United States, with raw material dependencies on end-of-life EV battery flows, black mass concentrate, and reagent chemicals for hydrometallurgical processing. Single-source vulnerability around Chinese feedstock concentration threatens European and North American capacity utilization. Distribution runs through dedicated reverse logistics networks and port-centric black mass import corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in lithium recycling rests on hydrometallurgical energy intensity reductions and the shift toward battery-grade certification premiums that separate qualified suppliers from merchant market players.
For Market Incumbents: Deploy multi-stage purification capacity additions in Antwerp-Rotterdam and Nevada corridors to preempt feedstock competition from emerging hydrometallurgical entrants. Secure binding offtake with Korean cathode manufacturers before qualification timelines extend. The threat of direct cathode regeneration technologies displacing elemental separation routes demands pilot partnerships with South Korean battery makers. For New Entrants and Emerging Players: Biotechnological bioleaching platforms offer a capital-light wedge against incumbent pyrometallurgical infrastructure. Target stationary energy storage second-life refurbishment as the most penetrable segment, where qualification protocols remain less stringent than automotive tiers. A feedstock-first go-to-market angle—anchoring collection infrastructure before refining capacity—mirrors the Redwood Materials model. For Investors and Strategic Acquirers: Roll-up economics work for regional collection-platform specialists because fragmented reverse logistics networks resist organic scaling. Five-to-ten year viability hinges on feedstock contract duration rather than technology differentiation. Watch for EU Battery Regulation threshold acceleration as the inflection signal that compresses merchant market viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Collection | Redwood Materials anchors Nevada infrastructure to secure end-of-life EV battery flows before competitors. |
| Long-term Supply Agreement | Northvolt's captive recycling pipeline locks in decade-long cathode procurement under EU Battery Regulation thresholds. |
| Joint Venture | Brunp Recycling leverages state-linked Guangdong smelter capacity to dominate Yangtze River Delta cathode demand. |
| Green Certification Program | Umicore's REACH-aligned traceability systems qualify recovered lithium for Samsung SDI and LG Chem supply chains. |
| Technology Licensing | Direct cathode regeneration pilots in South Korea promise to halve energy intensity versus conventional hydrometallurgical routes. |
Research Methodology
Bottom-up automotive cathode procurement modeling reconciled against top-down hydrometallurgical capacity tracking forms the analytical core of this study. Primary interviews with recycling plant managers, cathode manufacturer procurement leads, OEM sustainability officers, and reverse logistics operators combined with secondary validation from EPA hazardous waste manifests, MIIT dual-carbon standard disclosures, EU Battery Regulation implementation documents, and customs trade data. Triangulation across these sources grounds volume estimates in observed feedstock flows and qualification timelines.
Historical trendline analysis of lithium recovery rates and energy intensity metrics established baseline parameters for projection. The forecast framework segments by technology route, product purity tier, end-use qualification protocol, and regional regulatory cluster across the analysis window. CAGRs derive from fitted growth curves applied to nameplate capacity announcements and EV retirement curves. Key inputs include hydrometallurgical energy consumption per ton and battery-grade certification success rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to primary lithium price volatility and direct recycling technology maturation. The analytical envelope assumes continued EU Battery Regulation threshold enforcement and stable Chinese feedstock export licensing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Recycling
Lithium-Ion Battery Recycling Service Market
Battery Recycling
Lithium-Ion Battery Recycling Process Market
Battery Recycling
Automotive Oil Recycling Market
Battery Recycling
Global Primary Battery Recycling Market
Battery Recycling
North America Lithium-Ion Battery Recycling Market
Battery Recycling
India Battery Recycling Market
Battery Recycling
Middle East and Africa Lithium-Ion Battery Recycling Market
Battery Recycling
Second-Life EV Battery Market
Battery Recycling
Battery Recycling Market
Battery Recycling
Prepaid Battery Recycling Market
Battery Recycling
Global Lead Recycling Battery Market
Battery Recycling
EV Battery Reuse Market
Battery Recycling
Electric Vehicle (EV) Battery Recycling Market
Battery Recycling
Power Battery Recycling Market
Battery Recycling
Battery Recycling Process Quality and Purity Test Instruments Market
Battery Recycling
Lithium Ion Battery Recycling Market