
 Lithium-Ion Battery Packs Market | 2026-2036
Lithium-Ion Battery Packs Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium-Ion Battery Packs Market Analysis
Buyer concentration among automotive OEMs is hardening as volume commitments consolidate around fewer platforms with longer contract horizons. Contemporary Amperex Technology Co. Limited leverages integrated cathode production to secure cost positions on prismatic cell contracts. LG Energy Solution anchors its competitive stance through dedicated joint-venture plants with three North American and European automakers. BYD Company Limited controls a vertically closed loop from lithium extraction through pack assembly, insulating margin from external cathode price swings.
Lithium-ion battery packs are modular electrochemical energy storage systems comprising cells, battery management circuitry, thermal management hardware, and structural enclosures rated typically between 3.6 V and 800 V depending on series-parallel configuration; they convert stored chemical energy into direct-current electrical output for motive, stationary, or portable power applications. Prismatic formats now dominate automotive traction applications where space efficiency and pack-level energy density above 250 Wh/kg matter most, while cylindrical cells sustain cost advantages in power tools and certain entry-level electric vehicle platforms. NMC chemistries retain premium positioning in long-range electric vehicles, though LFP is displacing nickel-cobalt configurations in commercial fleet and grid storage segments where cycle life exceeds range requirements.
China's SAMR enforces GB standards on cell safety and transport classification, while the EU's Battery Regulation mandates carbon footprint declarations and recycled content thresholds that reshape supplier qualification timelines for European-bound exports. The US IRA domestic content rules are redirecting cathode and cell investment toward North American assembly corridors, complicating supply strategies for pack makers without regional chemical precursor partnerships. Stakeholders must monitor how divergent recycling mandates across Beijing, Brussels, and Washington redefine end-of-life cost liabilities and closed-loop material access.
Market Dynamics
Automotive OEM procurement consolidation around unified electric vehicle platforms is compressing supplier margins while demanding decade-long volume guarantees. This buyer concentration is forcing pack manufacturers to absorb cathode price volatility through fixed-price contracts.
Growth Catalysts
- NMPA cell-grade certification:China's tightening safety standards are disqualifying second-tier producers and concentrating orders among certified suppliers with integrated testing capabilities.
- LFP chemistry expansion:Commercial fleet operators and grid storage developers are pivoting toward iron-phosphate configurations that prioritize cycle life over energy density.
- Jiangsu-Fujian manufacturing corridor:Proximity between precursor chemical plants and cell-to-pack assembly facilities is reducing logistics costs and lead times for domestic Chinese demand.
Market Restraints
- Lithium carbonate volatility:Spot market swings in raw material costs are eroding margin predictability for pack assemblers without captive mining or long-term offtake agreements.
- Single-source cathode dependence:Concentration of high-nickel precursor production within Chinese state-affiliated refiners creates geopolitical supply risk for non-domestic pack makers.
- Thermal runaway containment:Current cell-to-pack architectures face hard engineering limits on passive propagation resistance without adding prohibitive weight to enclosure systems.
Strategic Opportunities
- US IRA domestic content credits:North American pack assembly paired with regional cathode precursor partnerships qualifies for production tax incentives that offset labor cost disadvantages.
- Second-life stationary storage:Retired automotive packs with degraded capacity retain commercial viability for grid buffering applications with lower cycle depth requirements.
- Solid-state electrolyte convergence:Sulfide-based ceramic separators paired with silicon-anode architectures promise step-change energy density for aviation and heavy-duty segments.
Industry Challenges
- Electrochemical engineering talent scarcity:Pack manufacturers compete with semiconductor and pharmaceutical sectors for specialists in interfacial chemistry and computational materials science.
- EU Battery Regulation compliance timelines:Carbon footprint declarations and recycled content thresholds require supply chain documentation systems that most Asian producers have not yet built.
- Legacy thermal management integration:Existing vehicle platforms constrain pack form factors, forcing compromises between cooling channel geometry and volumetric energy density targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium-Ion Battery Packs Market |
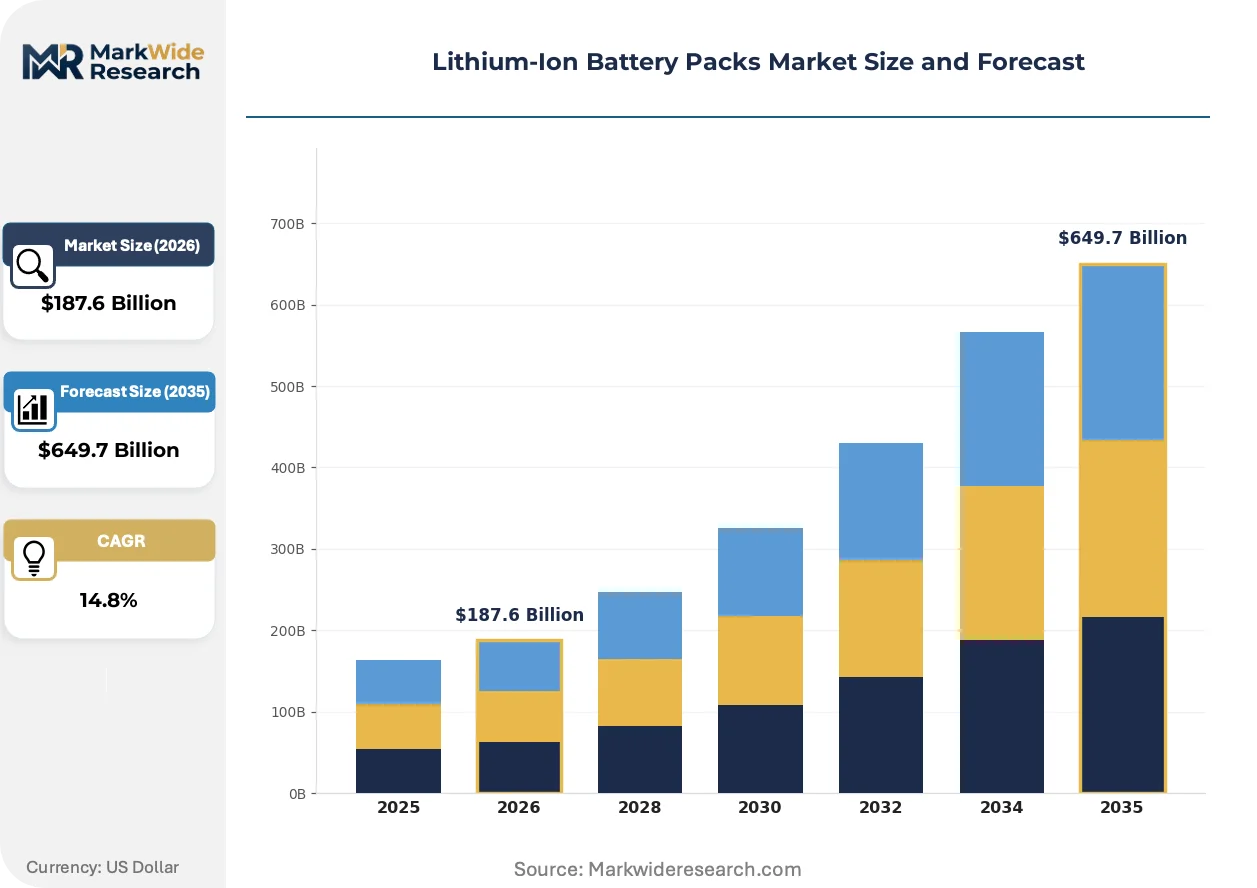
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $649.7 Billion |
| CAGR (2026 – 2036) | 14.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prismatic, Cylindrical, Polymer, Glass, Others End User: Consumer Electronics, Automotive OEMs, Renewable Energy, Industrial Equipment Technology: LFP, NMC, LTO, NCA Application: Electric Vehicles, Grid Storage, Portable Devices, Medical Equipment |
| Companies Covered | Contemporary Amperex Technology Co. Limited, LG Energy Solution, Panasonic Holdings Corporation, BYD Company Limited, Samsung SDI, SK On, AESC, CALB Co., Gotion High-Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium-Ion Battery Packs Market Emerging Trajectories
Cell-to-pack architectures are eliminating module housings and interconnection hardware. This structural simplification is compressing bill-of-materials costs while demanding precision in cell sorting and state-of-health matching.
Silicon-anode blending is modularizing traditional graphite-only electrode designs. Premium electric vehicle platforms from German and Korean OEMs are adopting 5-10% silicon oxide loadings to push gravimetric energy density toward 300 Wh/kg at cell level. The technology is modularizing pack design flexibility, enabling thinner profiles for sports car and aviation applications without sacrificing range targets.
EU Battery Regulation mandates are forcing carbon footprint declarations at the cell level. Pack exporters to European markets must now document upstream mining, refining, and assembly emissions through third-party verification. Long-range passenger vehicle segments face the steepest compliance burdens, with suppliers accelerating partnerships with European recycling operators to secure post-consumer material streams.
Fleet operators are consolidating procurement through direct manufacturer relationships rather than distributor networks. Commercial van and bus buyers in Nordic countries and California are negotiating multi-year service agreements that bundle pack replacement, thermal management maintenance, and residual value guarantees. This channel compression is squeezing independent pack distributors and forcing them toward aftermarket refurbishment specialization.
Lithium-Ion Battery Packs Market Segmentation
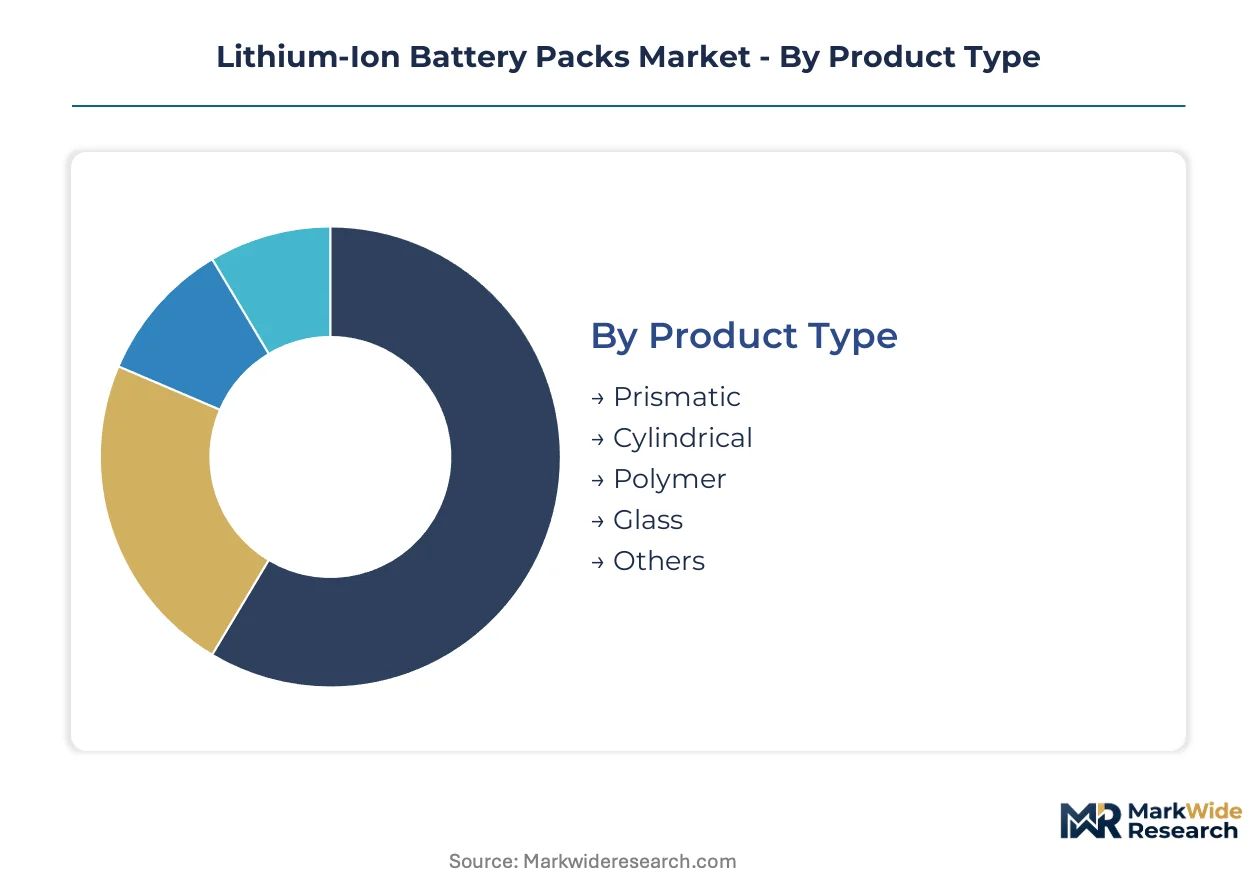
Pack geometry, cathode chemistry, and end-use duty cycles create fundamentally different margin structures and qualification barriers. Procurement teams segment suppliers by thermal management complexity and cycle life requirements rather than nominal capacity alone.
Product Type:
Automotive OEMs select formats based on volumetric packaging constraints and cooling channel integration costs.
- Prismatic:Rectangular aluminum-cased cells with stacked electrode layers enable direct cell-to-pack assembly without module housings. Demand concentrates in German and Korean premium electric vehicle platforms where pack-level energy density above 250 Wh/kg justifies higher cell-sorting precision costs.
- Cylindrical:Rolled jellyroll construction in standardized 18650 and 21700 formats leverages mature winding equipment and automated inspection. Tesla's Nevada and Shanghai facilities anchor procurement volume for this format, though cylindrical share is compressing as prismatic cell-to-pack architectures mature.
- Polymer:Pouch cells with laminated aluminum foil enclosures maximize packaging flexibility for wearable electronics and thin-profile consumer devices.
- Glass:Solid-state prototypes using glass-ceramic electrolyte separators target aviation and medical implant applications requiring extreme thermal stability.
- Others:Emerging formats including blade cells and coin cells serve niche industrial and Internet-of-Things sensor applications.
Volume sits with Prismatic; growth tilts toward Polymer as foldable electronics and drone applications expand.
End User:
Contract structures diverge sharply between spot-market consumer purchases and decade-long automotive platform commitments.
- Automotive OEMs:Long-range passenger vehicle programs in Germany, China, and the United States specify NMC cells with 800-volt architectures and active liquid cooling. These buyers demand 10-year performance warranties and cell-level traceability documentation for EU Battery Regulation compliance.
- Renewable Energy:Utility-scale grid storage developers in California and Texas prioritize LFP chemistries with 6,000+ cycle life and passive air cooling to minimize operational expenditure.
- Consumer Electronics:Smartphone and laptop manufacturers source high-voltage polymer cells through competitive bidding with 12-month price locks.
- Industrial Equipment:Forklift and warehouse robot fleets in Japan and South Korea require rapid-charge LTO configurations for three-shift operations.
Revenue concentrates with Automotive OEMs; margin expansion favors Renewable Energy as utility procurement scales.
Technology:
Cathode chemistry selection trades energy density against thermal stability and raw material cost exposure.
- NMC:Nickel-manganese-cobalt layered oxides deliver 200-250 Wh/kg cell-level density for long-range electric vehicles. Korean and Japanese cathode producers dominate high-nickel NMC 811 supply, creating single-source risk for European pack assemblers.
- LFP:Lithium iron phosphate eliminates cobalt and nickel exposure while offering 3,000-6,000 cycle life. Chinese producers in Hubei and Guizhou provinces have scaled LFP precursor capacity to serve domestic grid storage and commercial fleet demand.
- NCA:Nickel-cobalt-aluminum oxides maximize gravimetric density for luxury electric vehicles and aviation prototypes.
- LTO:Lithium titanate anodes enable 10-minute fast charging for electric buses and port equipment with extreme cycle durability.
Deployment volume favors NMC; chemistry share is shifting fastest toward LFP as iron-phosphate production costs compress.
Application:
Duty cycle depth and ambient temperature range dictate pack architecture and management system complexity.
- Electric Vehicles:Passenger cars require 60-100 kWh packs with active thermal management for -30°C to 60°C operation. Pack producers must integrate with vehicle crash structures and meet UN 38.3 transport certification.
- Grid Storage:Containerized megawatt-hour systems favor LFP cells with passive cooling and modular inverter integration. Projects in Arizona and Australia are climbing the fastest as renewable curtailment economics improve.
- Portable Devices:Smartphones and tablets demand 10-20 Wh packs with polymer flexibility and wireless charging coil integration.
- Medical Equipment:Implantable and portable diagnostic devices require ISO 13485 quality systems and hermetic sealing for sterilization compatibility.
Capital deployment concentrates in Electric Vehicles; expansion trajectory is steepest for Grid Storage as utility procurement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium brine deposits in Chile's Atacama Desert and hard-rock spodumene mines in Western Australia anchor upstream material flows for pack manufacturing across three continents. Cell assembly capacity clusters near precursor chemical plants in East Asia, while final pack integration follows automotive OEM footprints into Germany, the United States, and China.
China
CATL and BYD anchor demand for high-nickel cathode precursors in Ningde and Shenzhen. SAMR enforces GB 38031 standards on cell safety and thermal propagation resistance. The Jiangsu-Fujian manufacturing corridor concentrates integrated cell-to-pack facilities within 200 kilometers of lithium hydroxide refiners in Yibin.
Germany
BMW and Volkswagen procurement teams specify 800-volt architectures for next-generation electric vehicle platforms. The EU Battery Regulation mandates carbon footprint declarations and recycled content thresholds for cells entering European markets. Bavaria's Ingolstadt and Stuttgart production zones host pack assembly joint ventures between domestic OEMs and Korean cell suppliers.
United States
Tesla's Nevada facility and emerging plants in Kentucky and Tennessee drive cylindrical and prismatic cell demand. IRA domestic content rules redirect cathode precursor investment toward North American chemical partnerships. Michigan's Detroit-Toledo corridor attracts pack assembly operations seeking proximity to legacy automotive engineering talent.
South Korea
LG Energy Solution and Samsung SDI supply NMC 811 cells to German and US luxury electric vehicle programs. MFDS maintains pharmaceutical-grade quality system expectations that transfer to automotive cell documentation. Gyeonggi Province's Suwon and Ochang industrial zones concentrate electrode coating and formation capacity.
Japan
Panasonic Holdings Corporation sustains cylindrical cell production for premium electric vehicle platforms. METI's Green Transformation initiative funds solid-state electrolyte research through 2030. Osaka and Nagoya manufacturing hubs specialize in high-precision winding equipment and electrode slurry formulation.
Lithium-Ion Battery Packs Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue solid-state and silicon-anode architectures to differentiate beyond commodity cell supply. The market structure concentrates volume among six Asian manufacturers with integrated cathode production, while European and North American pack assemblers depend on joint ventures for cell access. Three archetypes dominate: vertically integrated miners-to-packers, pure-play cell specialists with captive OEM relationships, and automotive spin-offs controlling pack design but outsourcing electrode manufacturing. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with players securing decade-long offtake agreements to lock in lithium supply.
Among China-based producers, Contemporary Amperex Technology Co. Limited and BYD Company Limited exemplify the vertically integrated archetype, controlling lithium extraction through pack assembly. LG Energy Solution represents the Korean pure-play model, anchoring competitive position through dedicated joint-venture plants with North American and European automakers. Panasonic Holdings Corporation occupies a distinctive tier, maintaining cylindrical cell specialization for premium electric vehicle platforms.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co. Limited |
| LG Energy Solution |
| Panasonic Holdings Corporation |
| BYD Company Limited |
| Samsung SDI |
| SK On |
| AESC |
| CALB Co. |
| Gotion High-Tech |
| Others |
Supply Flow & Price Mechanics
Cell-grade certification tiering separates NMPA-qualified suppliers from uncertified assemblers, concentrating pricing power among integrated producers while forcing second-tier competitors toward unbundled cell-only transactions without warranty backing. This bifurcation manifests in divergent supply chain footprints: certified vendors anchor cathode production within 200 kilometers of Jiangsu-Fujian pack assembly corridors, while uncertified players absorb spot-market lithium carbonate volatility without captive refining buffers.
Pricing Analysis
Warranty bundling distinguishes automotive OEM contracts from spot-market transactions, with decade-long performance guarantees commanding 15-20% premiums over unbundled cell supply. Pricing stratifies across premium NMC 811 configurations for long-range platforms, standard LFP packs for commercial fleets, and economy cylindrical formats for power tools. Cost compression in standard-tier LFP is intensifying because Chinese state-affiliated refiners have scaled iron-phosphate precursor capacity ahead of global demand. Renewable energy developers exhibit highest price sensitivity, while German luxury OEMs prioritize energy density over unit economics.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Los Angeles, and Singapore buffer finished pack inventory against ocean freight volatility, though hub-and-spoke patterns remain secondary to direct plant-to-OEM logistics for automotive contracts. Upstream concentration centers on Chilean brine operations, Australian spodumene mines, and Chinese hydroxide refiners. Cathode precursor production draws from nickel laterite deposits in Indonesia and cobalt hydroxide from the DRC, creating single-source vulnerability for high-nickel NMC formulations. Distribution runs through long-term offtake agreements rather than merchant spot markets, with pack assemblers locking lithium supply five to seven years forward.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Battery Regulation's carbon footprint declaration mandate erects a compliance moat that favors incumbents with documented supply chain emissions systems, while disqualifying Asian producers lacking third-party verification infrastructure.
For Market Incumbents: To counter margin erosion from fixed-price automotive contracts, secure captive lithium offtake through direct mining partnerships in Chile and Australia, and accelerate in-house production of high-nickel cathode precursors to insulate against Chinese state-affiliated refiner pricing power. For New Entrants and Emerging Players: Enter via second-life stationary storage refurbishment, where degraded automotive packs with 70-80% residual capacity serve grid buffering applications with lower certification barriers. Target Nordic utility procurement offices and California C&I developers through performance-based leasing models rather than upfront capital sales. For Investors and Strategic Acquirers: Re-rating potential sits with solid-state electrolyte specialists given sulfide-based ceramic separator breakthroughs promising aviation-grade energy density. Long-term viability frames around five-to-ten year technology convergence windows. Monitor cathode precursor joint venture announcements between Korean cell producers and North American chemical partners as inflection signals for IRA-compliant supply chain formation.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Architecture Adoption | Eliminates module housings and reduces bill-of-materials costs for CATL and BYD assembly lines. |
| Silicon-Anode Blending Scale-Up | Enables 300 Wh/kg cell-level density for German OEM premium electric vehicle platforms. |
| IRA Domestic Content Partnership | Qualifies North American pack assembly for production tax credits through regional cathode precursor supply. |
| Second-Life Storage Refurbishment | Captures residual value from retired automotive packs for California grid storage developers. |
| Solid-State Electrolyte R&D | Positions sulfide-ceramic separators for aviation and heavy-duty segments requiring extreme thermal stability. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews spanning cell engineering directors, automotive platform procurement leads, cathode precursor plant managers, and utility-scale storage developers. Bottom-up cell shipment tallies from SAMR certification databases and top-down automotive production forecasts from vehicle registration data were reconciled to triangulate market sizing across the analysis window.
Data-stream reconciliation applied a segmented analytical framework modeling pack geometry, cathode chemistry, end-use duty cycle, and regional regulatory cluster throughout the forecast period. CAGRs derived from installed base growth curves and replacement cycle assumptions, with specific inputs including NMPA certification timelines, IRA domestic content phase-in schedules, and EU Battery Regulation compliance cost estimates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium carbonate spot price spikes or sudden NMPA safety standard revisions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Liquid Lithium Ion Battery Market
Lithium-ion Battery
Global Lithium-Ion Battery Energy Storage System Market
Lithium-ion Battery
Global Pin Type Lithium-Based Battery Market
Lithium-ion Battery
Sodium-Ion Battery Market
Lithium-ion Battery
Lithium Ion Secondary Battery Sales Market
Lithium-ion Battery
Lithium Ion Battery Wet Coated Diaphragm Market
Lithium-ion Battery
Lithium Battery for Passenger Car Market
Lithium-ion Battery
Asia Pacific Electric Vehicle Battery Anode Market
Lithium-ion Battery
Italy Electric Vehicles Battery Anode Market
Lithium-ion Battery
Consumer Lithium-Ion Battery Market
Lithium-ion Battery
Graphite Anode for LIB Market
Lithium-ion Battery
Lifepo4 Battery Market
Lithium-ion Battery
China Electric Vehicle Lithium-Ion Battery Separator Market
Lithium-ion Battery
Lithium-Ion Batteries for Electric Vehicles Market
Lithium-ion Battery
Lithium-Ion Batteries Electric Bike Market
Lithium-ion Battery
Canada Electric Vehicle Battery Anode Market