
 High Temperature Lithium Battery Market | 2026-2036
High Temperature Lithium Battery Market Size, Share, and Industry Trends Forecast 2026-2036
High Temperature Lithium Battery Market Insights
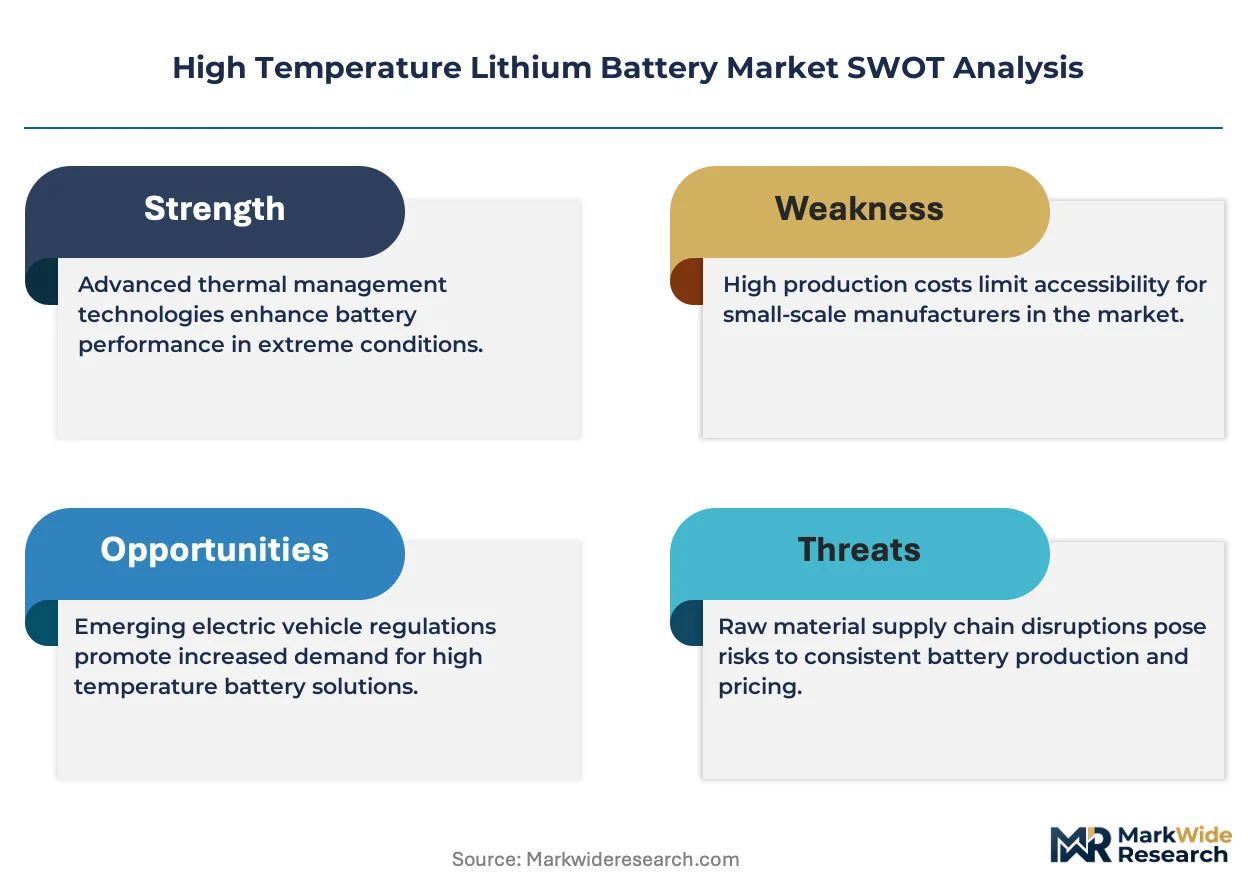
UN 38.3 lithium battery transport certification is bifurcating the competitive landscape into qualified incumbents and excluded challengers. CATL leverages its integrated cathode production to control cost positions in high-temperature LiFePO4 cells. SAFT anchors European defense and aerospace procurement through decades of MIL-STD qualification heritage. Samsung SDI competes on cylindrical form factors optimized for industrial telemetry in geothermal and oilfield applications.
High temperature lithium batteries are electrochemical energy storage devices engineered with thermally stable electrolyte formulations and ceramic-coated separators to sustain operation above 60°C without thermal runaway, primarily serving industrial, defense, and energy extraction sectors where standard lithium-ion chemistry fails. The LiFePO4 chemistry segment dominates commercial and energy storage deployments due to intrinsic thermal stability and extended cycle life under thermal stress. Solid-state technology leads R&D investment as ceramic electrolytes promise elimination of volatile organic solvents, though graphene-hybrid architectures occupy the near-term pipeline for aerospace weight reduction targets.
UN 38.3 testing protocols, China's GB/T standards, and the EU Battery Regulation collectively tighten cell qualification requirements and mandate carbon footprint disclosure, reshaping supplier eligibility and procurement criteria across export-dependent manufacturers. The US FAA and NHTSA maintain parallel certification tracks for aviation and automotive thermal propagation resistance, creating dual compliance burdens for multi-sector suppliers. Stakeholders must monitor solid-state manufacturing yield breakthroughs and evolving thermal test protocols to determine capacity allocation between incumbent liquid electrolyte platforms and next-generation ceramic architectures.
Market Dynamics
UN 38.3 transport certification and China's tightening GB/T standards are bifurcating supplier eligibility, locking out uncertified challengers while incumbents capture procurement contracts in Saudi Arabia's upstream energy sector and European defense channels.
Growth Catalysts
- LiFePO4 thermal stability:Intrinsic cathode chemistry eliminates cobalt dependency while sustaining 60°C+ operation without thermal runaway, qualifying cells for downhole drilling telemetry.
- Saudi upstream energy expansion:Aramco's drilling intensity in the Empty Quarter creates sustained procurement pull for batteries rated above standard lithium-ion thermal thresholds.
- EU Battery Regulation carbon disclosure:Mandatory supply chain footprint tracking favors manufacturers with integrated cathode production and auditable mineral sourcing.
Market Restraints
- Electrolyte solvent volatility:Ethylene carbonate and dimethyl carbonate formulations degrade above 85°C, requiring ceramic-coated separators that inflate cell costs 15-25% versus standard lithium-ion.
- Cathode precursor concentration:Lithium iron phosphate powder production clusters in Hubei and Hunan provinces, exposing supply chains to China's power rationing and export licensing.
- Solid-state manufacturing yield:Ceramic electrolyte sintering defects exceed 40% at pilot scale, compressing effective capacity versus liquid electrolyte lines.
Strategic Opportunities
- Geothermal telemetry retrofit:Indonesia's 2.3 GW geothermal expansion requires battery upgrades for wellhead monitoring in 150°C subsurface conditions.
- MIL-STD-810G qualification pathway:Defense procurement in NATO countries mandates thermal shock and altitude testing that certified suppliers can leverage for dual-use industrial sales.
- Graphene-hybrid anode convergence:Silicon-graphene composite architectures promise 30% weight reduction for aerospace power systems without solid-state yield penalties.
Industry Challenges
- UN 38.3 certification timeline:Eight mandatory test sequences require 4-6 months and $50,000+ per cell variant, freezing product iteration cycles for mid-tier manufacturers.
- Thermal propagation test facility scarcity:Only three independent labs in North America and Europe can execute nail penetration and overcharge abuse testing to FAA and NHTSA protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Temperature Lithium Battery Market |
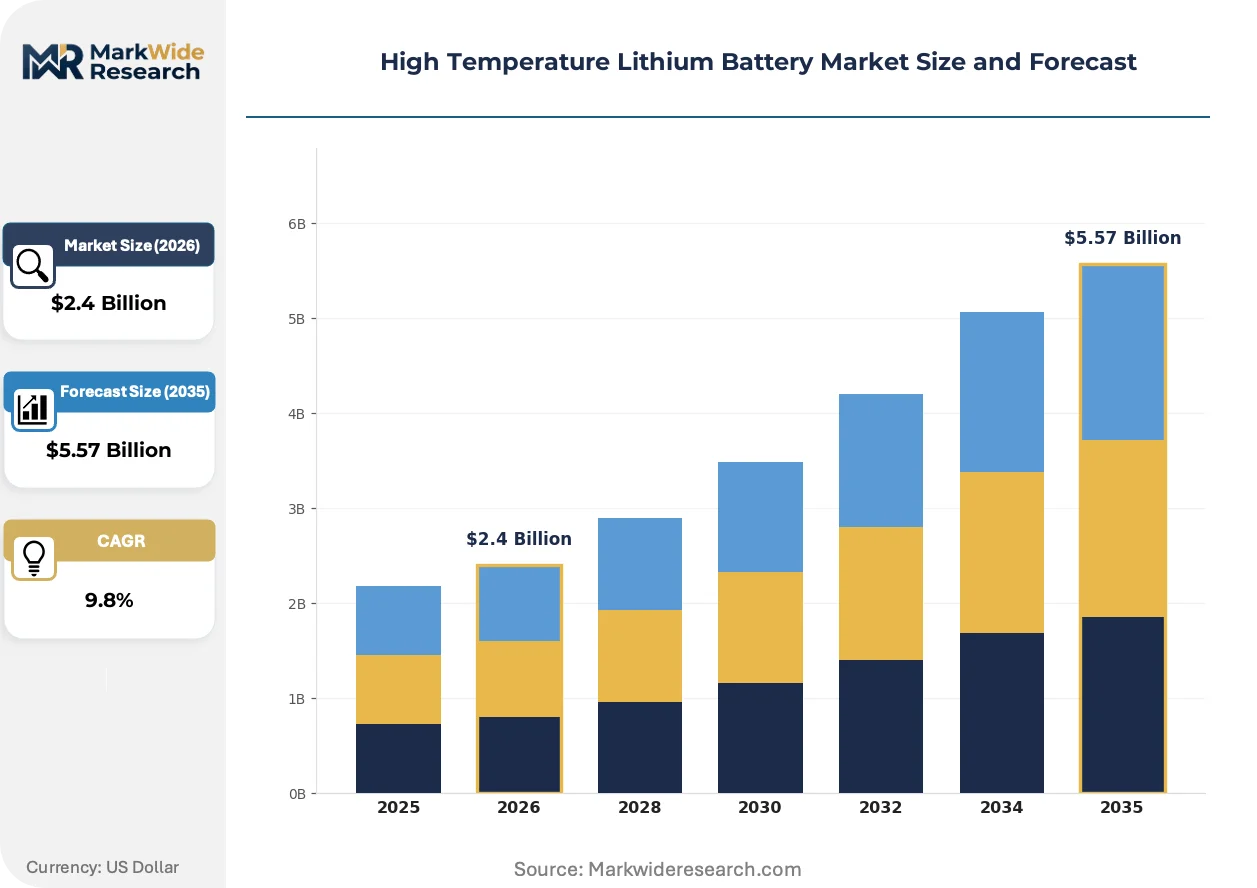
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.57 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LiCoO2, LiFePO4, LiMn2O4, NCA Application: Aerospace, Automotive, Industrial, Telecommunications End User: Defense, Commercial, Energy Storage, Transportation Technology: Solid State, Lithium Sulfur, Graphene, Hybrid |
| Companies Covered | Contemporary Amperex Technology Co. (CATL), LG Energy Solution, Samsung SDI, Panasonic Corporation, BYD Co., SAFT, Tadiran, NGK Insulators, EVE Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Temperature Lithium Battery Market Trends and Innovations
Ceramic electrolyte architectures and graphene-hybrid electrodes are decomposing the incumbent liquid electrolyte supply base, while certification requirements harden competitive moats around qualified incumbents.
Solid-state lithium-metal cells with sulfide and oxide ceramic electrolytes are decomposing the liquid electrolyte value chain. Oilfield service companies in Saudi Arabia and geothermal operators in Indonesia are piloting these cells for 150°C downhole environments. The technology is decomposing procurement patterns that previously accepted 18-month replacement cycles for conventional lithium-thionyl chloride batteries.
China's GB 38031-2020 electric vehicle battery safety standard is tightening thermal runaway propagation requirements, forcing export-oriented cell manufacturers to redesign separator architectures and venting mechanisms. The regulation compresses eligibility for Middle East and European industrial battery tenders. Suppliers with existing GB/T 31485 certification are capturing procurement share in Saudi Aramco's drilling tool supply chain.
Service-unbundling is fragmenting traditional battery-plus-systems contracts. Oilfield operators now procure cells separately from battery management systems, compressing margins for integrated pack assemblers. This pattern is most visible in North Sea and Gulf of Mexico offshore platforms, where operators source UN 38.3-certified cells directly from CATL and SAFT while contracting local integrators for thermal management packaging.
High Temperature Lithium Battery Market Segmentation
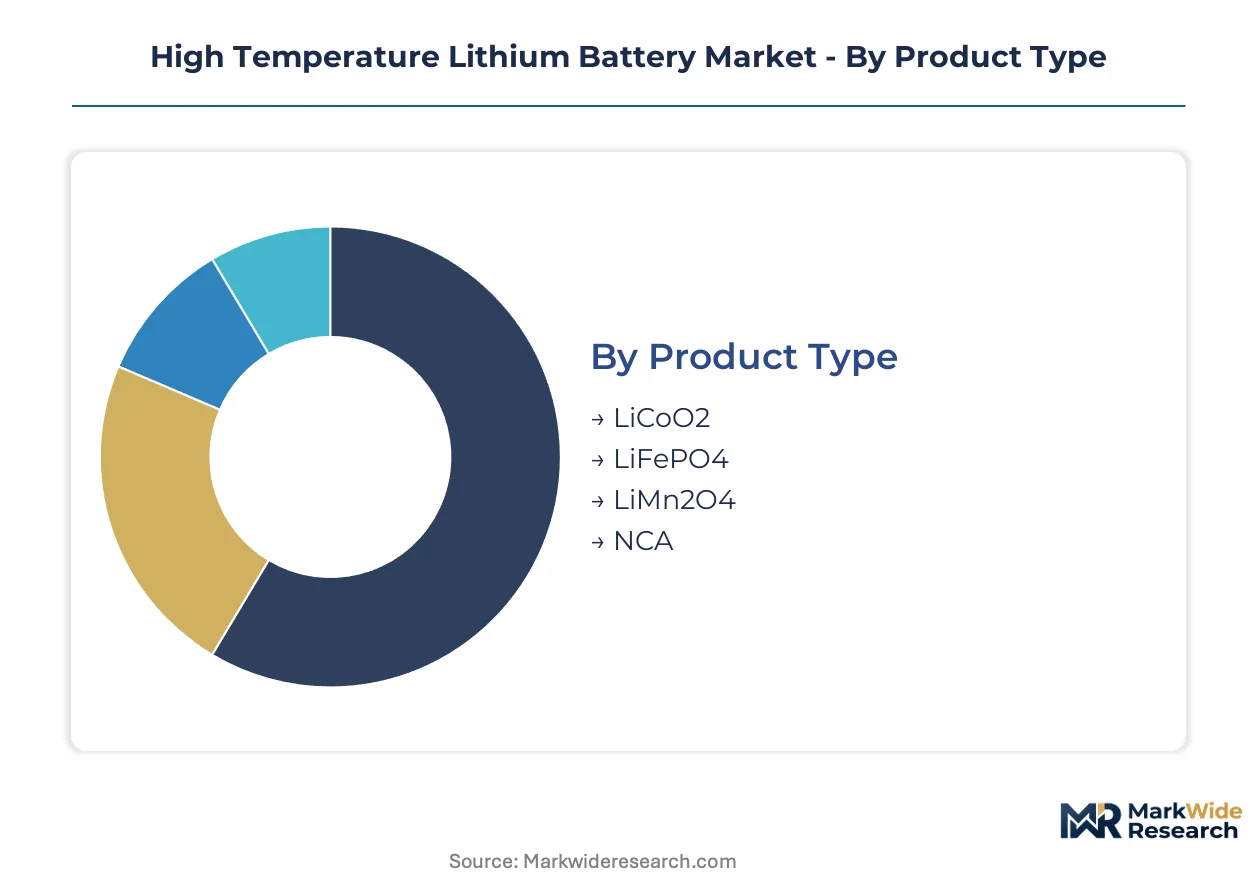
High temperature lithium battery procurement hinges on chemistry-specific certifications and application-driven thermal thresholds. Segment boundaries align with UN 38.3 transport classes and end-use temperature specifications rather than conventional consumer electronics categories.
Product Type:
Regulatory differentiation separates qualified chemistries from excluded alternatives under China's GB/T 31485 and EU Battery Regulation carbon disclosure mandates.
- LiFePO4:Lithium iron phosphate cathodes deliver intrinsic thermal stability above 60°C without cobalt dependency. Saudi Aramco's drilling telemetry procurement concentrates here due to UN 38.3 qualification pathways and extended cycle life under thermal stress.
- NCA:Nickel-cobalt-aluminum oxide formulations achieve higher energy density for aerospace weight constraints but require ceramic-coated separators to suppress thermal runaway. FAA certification timelines favor incumbent suppliers with existing abuse-test documentation.
- LiCoO2:Cobalt-based layered oxide chemistry dominates standard consumer applications but fails high-temperature thresholds without prohibitively expensive thermal management.
- LiMn2O4:Spinel manganese oxide occupies mid-tier industrial applications where cost sensitivity outweighs energy density requirements.
Established volume favors LiFePO4; emerging adoption favors NCA.
Application:
Cost tier stratification mirrors certification burden and replacement cycle economics across deployment environments.
- Industrial:Oilfield downhole tools and geothermal wellhead monitoring demand 150°C-rated cells with 5-10 year service intervals. Indonesia's 2.3 GW geothermal expansion and Saudi Arabia's Empty Quarter drilling intensity concentrate procurement pull here.
- Aerospace:Satellite power systems and avionics backup require MIL-STD-810G thermal shock qualification plus FAA propagation resistance certification. Weight reduction targets favor graphene-hybrid architectures over conventional liquid electrolyte cells.
- Automotive:Underhood electronics and battery thermal management systems operate at elevated ambient temperatures but below industrial thresholds.
- Telecommunications:Remote base stations in desert climates require moderate high-temperature tolerance with emphasis on capital cost minimization.
Industrial applications command premium pricing; aerospace delivers steepest expansion trajectory.
End User:
Customer type determines procurement modality and contract structure across defense, commercial, and infrastructure deployments.
- Defense:NATO country procurement mandates MIL-STD-810G altitude and thermal shock testing that certified suppliers leverage for dual-use industrial sales. Multi-year sole-source contracts dominate.
- Energy Storage:Grid-scale thermal buffering and renewable integration projects require GB/T 36276-compliant cells with auditable carbon footprint documentation under EU Battery Regulation.
- Commercial:Oilfield service companies and industrial OEMs increasingly unbundle cell procurement from battery management systems, compressing pack assembler margins.
- Transportation:Electric vehicle thermal management and heavy-duty underhood applications face GB 38031-2020 propagation requirements that redesign separator architectures.
Defense contracts anchor supplier qualification investment; energy storage drives volume scaling.
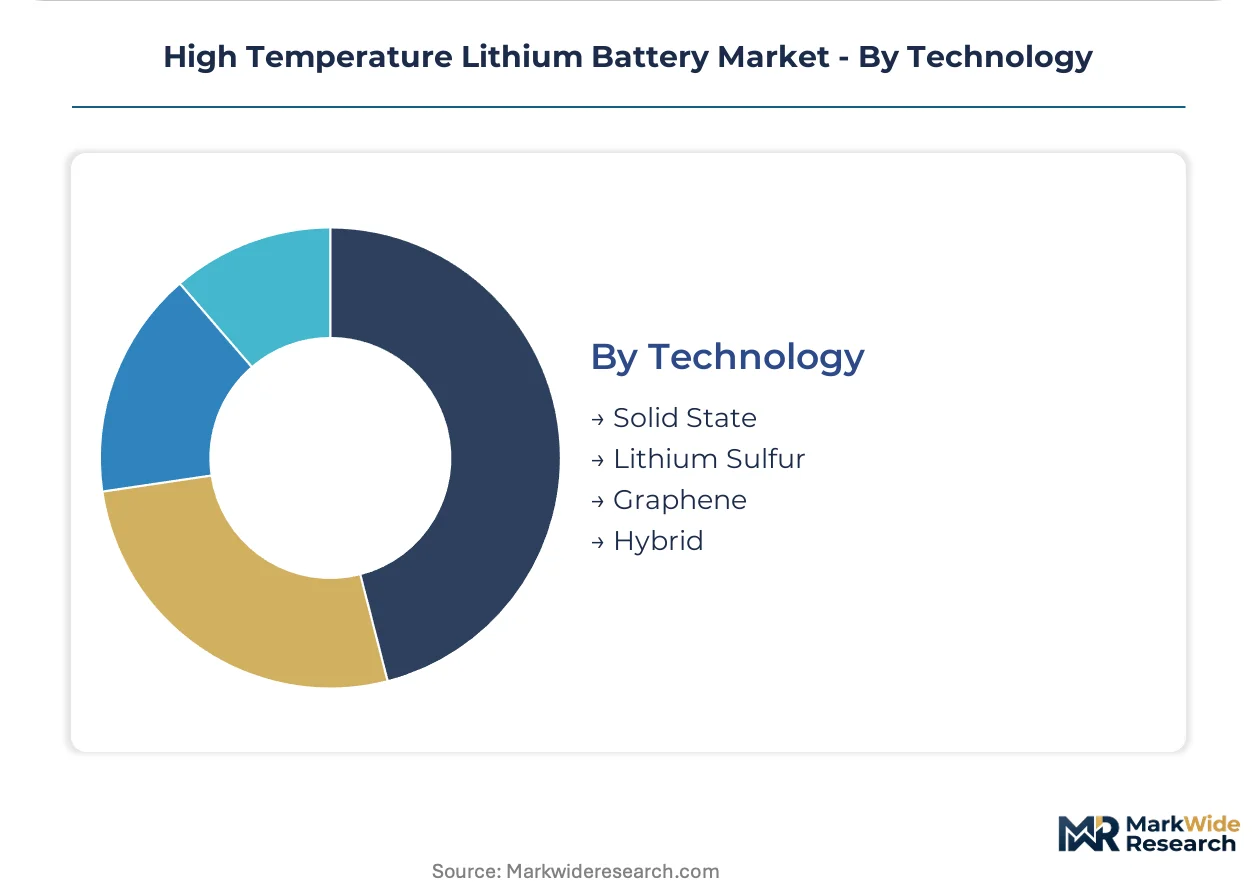
Technology:
Manufacturing maturity separates near-term deployable platforms from R&D-stage architectures with unresolved yield constraints.
- Solid State:Ceramic electrolyte lithium-metal cells eliminate volatile organic solvents for 150°C downhole environments. Sulfide and oxide electrolyte sintering defects exceed 40% at pilot scale, compressing effective capacity versus liquid electrolyte lines.
- Graphene:Silicon-graphene composite anodes promise 30% weight reduction for aerospace power systems without solid-state yield penalties. Near-term commercialization timelines favor this pathway.
- Lithium Sulfur:Theoretical energy density advantages confront polysulfide shuttle degradation and electrolyte compatibility challenges at elevated temperatures.
- Hybrid:Mixed electrolyte and electrode architectures attempt to bridge performance gaps but lack standardized qualification protocols.
Graphene-hybrid architectures gain share fastest; solid-state awaits manufacturing yield breakthroughs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government procurement programs and mineral processing incentives are redistributing high temperature lithium battery manufacturing capacity across industrial clusters with established cathode precursor supply chains.
China
MIIT's battery industry development guidelines prioritize high-temperature cell qualification for export markets. GB 38031-2020 thermal runaway standards tighten separator architecture requirements. Hubei and Hunan provinces concentrate lithium iron phosphate powder production, exposing supply chains to periodic power rationing and export licensing reviews.
United States
FAA thermal propagation resistance certification and NHTSA abuse-test protocols create dual compliance burdens for multi-sector suppliers. The Inflation Reduction Act's domestic content credits incentivize cathode active material production. Texas and Arizona host emerging cell manufacturing investments targeting oilfield and defense procurement channels.
Germany
EU Battery Regulation carbon footprint disclosure mandates favor manufacturers with integrated cathode production and auditable mineral sourcing. KBA automotive standards overlap with industrial battery qualification pathways. Baden-Württemberg and Bavaria anchor European defense and aerospace procurement through established MIL-STD test infrastructure.
Saudi Arabia
Aramco's drilling intensity in the Empty Quarter generates sustained procurement pull for batteries rated above standard lithium-ion thermal thresholds. SFDA industrial safety requirements align with UN 38.3 transport certification. Eastern Province clusters oilfield service companies now unbundling cell procurement from battery management systems.
Japan
METI's battery supply chain resilience program subsidizes solid-state electrolyte R&D and ceramic manufacturing equipment. JIS standards for industrial lithium batteries inform geothermal and downhole tool specifications. Kyushu and Kansai regions concentrate specialty ceramic producers supplying sulfide and oxide electrolyte materials.
High Temperature Lithium Battery Market Competitive Landscape
Player mix skews toward integrated cathode producers and defense-qualified incumbents with decades of MIL-STD heritage. Market structure concentrates procurement share among suppliers with existing UN 38.3 certification and GB/T 31485 qualification, locking out mid-tier challengers. Two strategic archetypes dominate: integrated material-to-cell manufacturers controlling precursor costs, and specialty defense contractors leveraging sole-source contract relationships. Competitive moves center on backward integration into lithium iron phosphate powder production and strategic partnerships with oilfield service companies for downhole tool qualification.
Among Asia-Pacific-based integrated manufacturers, Contemporary Amperex Technology Co. and BYD Co. occupy positions anchored by captive cathode supply chains and export certification portfolios. Samsung SDI represents the cylindrical form factor specialization archetype, while SAFT exemplifies European defense and aerospace qualification heritage. These three companies illustrate the bifurcation between volume-driven industrial procurement and premium-tier defense contracting.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co. (CATL) |
| LG Energy Solution |
| Samsung SDI |
| Panasonic Corporation |
| BYD Co. |
| SAFT |
| Tadiran |
| NGK Insulators |
| EVE Energy |
| Others |
Pricing and Supply Chain Analysis
Ceramic-coated separator substitution for conventional polyolefin architectures simultaneously concentrates procurement leverage in China and Japan while inflating cell costs relative to standard lithium-ion baselines. This input transition reshapes supplier economics as oilfield operators in Saudi Arabia and geothermal developers in Indonesia absorb premium pricing for 150°C-rated configurations.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate industrial procurement for downhole drilling applications. Price differentiation rests on UN 38.3 certification tier and cathode chemistry grade, with certified LiFePO4 cells commanding substantial premiums over uncertified alternatives. Cost compression in mid-tier industrial segments is intensifying because oilfield service companies now unbundle cell procurement from battery management systems. Commercial oilfield operators exhibit highest price sensitivity; defense contractors demonstrate lowest sensitivity due to sole-source contract structures.
Supply Chain Analysis
China and South Korea anchor cathode active material production for high-temperature lithium batteries. Manufacturing draws from lithium iron phosphate powder, ceramic-coated separators, and thermally stable electrolyte formulations. Single-source vulnerability concentrates in Hubei and Hunan provinces where power rationing disrupts precursor output. Distribution runs through direct OEM supply agreements and oilfield service company procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high temperature lithium battery market sits at a solid-state disruption inflection where ceramic electrolyte yield breakthroughs would restructure competitive economics. China's GB 38031-2020 thermal runaway standards and the EU Battery Regulation carbon disclosure mandates accelerate qualification barriers that favor prepared incumbents.
For Market Incumbents: Secure captive lithium iron phosphate powder production in Hubei or Hunan provinces to insulate against China's export licensing volatility. Deepen MIL-STD-810G qualification documentation to defend against emerging solid-state challengers in European defense channels. For New Entrants and Emerging Players: Lead with graphene-hybrid anode architectures targeting aerospace weight reduction specifications where solid-state yield constraints exclude ceramic electrolyte competitors. Indonesia's geothermal telemetry retrofit segment offers the most penetrable white-space opportunity through direct EPC contractor partnerships. For Investors and Strategic Acquirers: The market sits at a pre-yield-breakthrough phase that favors integrated material-to-cell manufacturers with existing GB/T 31485 certification. Long-term viability over the next decade hinges on backward integration into cathode precursor production. Watch solid-state sintering defect rates as the critical inflection signal for capacity reallocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursor Production | CATL and BYD leverage Hubei-based lithium iron phosphate powder capacity to control input costs for Saudi Aramco contracts. |
| MIL-STD-810G Qualification Investment | SAFT anchors NATO defense procurement through thermal shock and altitude testing infrastructure in Baden-Württemberg. |
| Solid-State Ceramic Electrolyte R&D Partnership | Japanese sulfide electrolyte developers in Kyushu target 150°C downhole applications for Indonesian geothermal expansion. |
| UN 38.3 Certification Acceleration | Mid-tier manufacturers compress 4-6 month test timelines to capture Saudi oilfield service company procurement. |
| Graphene-Hybrid Anode Commercialization | Samsung SDI cylindrical form factors integrate silicon-graphene composites for aerospace weight reduction targets. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with battery system engineers, oilfield procurement managers, defense contract officers, and ceramic electrolyte R&D directors; and secondary validation through MIIT industry guidelines, FAA thermal propagation protocols, GB/T standard filings, and Aramco supplier qualification documents. Bottom-up cell shipment estimates triangulated against top-down energy sector capex allocations across the analysis window.
Across the projection horizon, the analytical framework modeled chemistry type, application temperature tier, end-user procurement modality, and technology maturity stage. CAGRs derived from segment-level volume build-ups incorporating replacement cycle economics for downhole drilling tools and geothermal wellhead monitoring systems. Inputs included Saudi drilling intensity projections, Indonesian geothermal capacity additions, and EU Battery Regulation compliance timelines.
Forecasts assume regulatory continuity in China's GB standard regime and EU carbon disclosure mandates; material policy shifts would require re-modeling. Specific risks include solid-state manufacturing yield breakthroughs that accelerate ceramic electrolyte adoption, and export licensing restrictions on Chinese lithium iron phosphate powder. Recalibration cycles align with material shifts in thermal test protocol updates and cathode precursor supply disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Italy Electric Vehicles Battery Anode Market
Lithium-ion Battery
LAMEA Solid State Battery Market
Lithium-ion Battery
France Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Lithium-Ion Batteries for Electric Vehicles Market
Lithium-ion Battery
Lithium-Ion Polymer Batteries Market
Lithium-ion Battery
Portable Lithium Battery Energy Storage Products Market
Lithium-ion Battery
Global Pin Type Lithium-Based Battery Market
Lithium-ion Battery
HEV Li-Ion Battery Market
Lithium-ion Battery
Automotive Lithium Ion Battery Market
Lithium-ion Battery
Cathode Material of Power Lithium Battery Market
Lithium-ion Battery
Automotive Lithium Based Battery Market
Lithium-ion Battery
Thin Film Lithium-Ion Battery Market
Lithium-ion Battery
South America Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lithium-Ion Battery Wet-Process Separator Market
Lithium-ion Battery
Nanotechnology Enabled Battery Market
Lithium-ion Battery
France SLI Battery Market