
 Smart Inhalers Market | 2026-2036
Smart Inhalers Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Inhalers Market Analysis
Capital-intensity divergence between sensor-integrated platform developers and legacy pharmaceutical manufacturers is bifurcating competitive positioning in the smart inhalers space. Propeller Health leverages cloud-connected analytics to anchor its presence in remote patient monitoring, while GlaxoSmithKline sustains scale advantages through backward integration into drug-device combination portfolios. AstraZeneca differentiates via biologics-linked digital adherence programs, and Teva Pharmaceuticals Industries competes on manufacturing breadth across both generic and branded respiratory categories.
Smart inhalers comprise electronically augmented respiratory delivery systems that embed sensors, wireless transmitters, and software algorithms to track actuation timing, inspiratory flow rates, and geographic usage patterns. Bluetooth-enabled metered-dose inhalers dominate current volume, while mobile app integration represents the fastest-expanding technology layer as healthcare providers seek real-time adherence dashboards. Dry powder inhalers occupy a mature but stable position in COPD care, whereas smart sensors attached to legacy devices are capturing emerging margin pools among cost-conscious health systems.
The FDA's digital health pre-certification program and the EU Medical Device Regulation impose distinct compliance burdens on wireless connectivity and cybersecurity validation, respectively. HIPAA constraints in the United States and GDPR requirements in Europe further shape how patient inhalation data flows between devices, apps, and electronic health records. Stakeholders must monitor evolving reimbursement codes for remote therapeutic monitoring, as payer acceptance will determine whether connected inhaler investments convert from pilot programs to standard-of-care infrastructure.
Market Dynamics
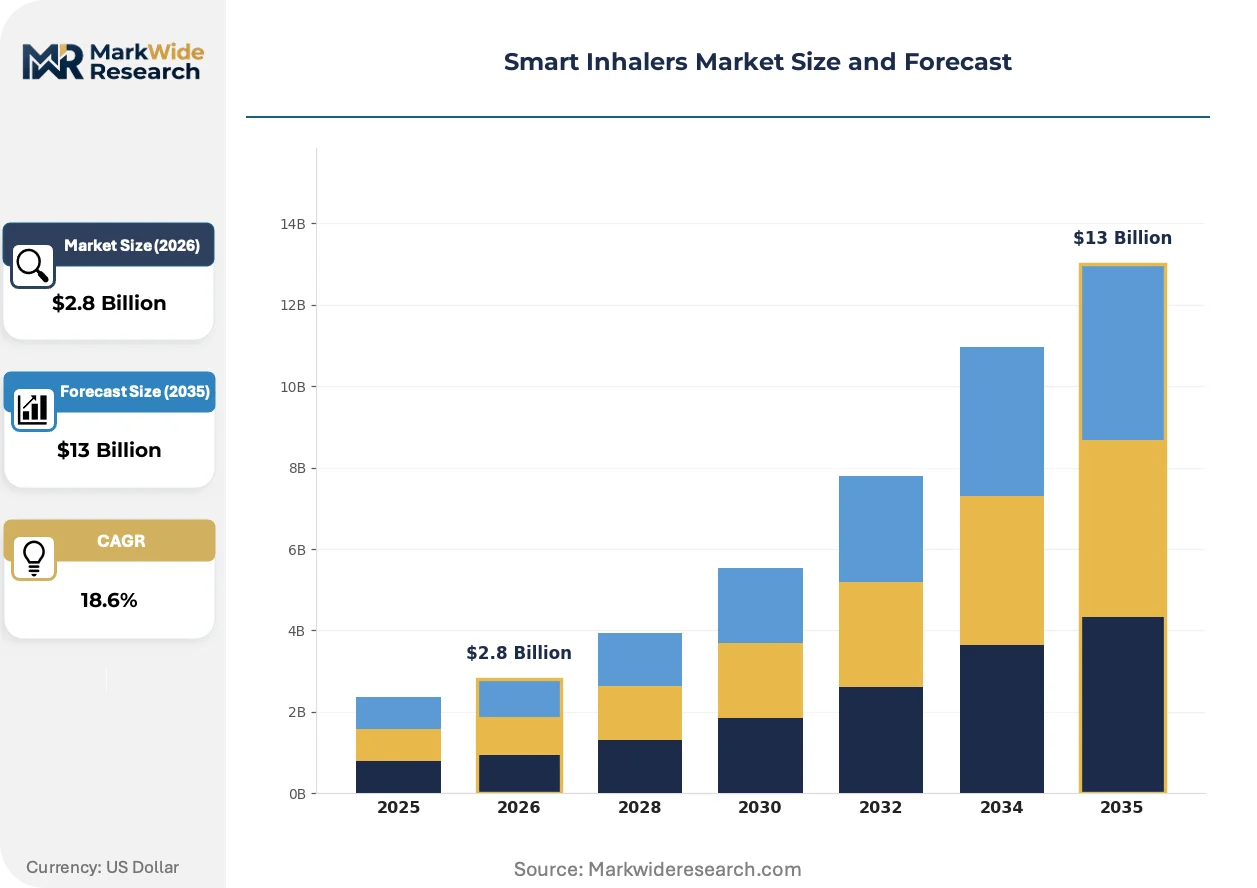
Reimbursement code evolution for remote therapeutic monitoring is restructuring how health systems evaluate connected inhaler investments, converting pilot deployments into infrastructure commitments as Medicare and private payers establish coverage pathways for sensor-integrated respiratory care.
Growth Catalysts
- EU Medical Device Regulation:MDR certification requirements for wireless respiratory devices are accelerating compliance investments among European manufacturers, creating first-mover advantages for validated sensor platforms.
- Value-based care contracts:Hospital systems in the United States are embedding smart inhaler adherence metrics into accountable care organization performance frameworks, directly linking device data to shared savings calculations.
- Bluetooth Low Energy:Power-efficient wireless protocols are enabling multi-day battery life in compact inhaler sensors, removing a critical barrier to patient daily use compliance.
Market Restraints
- MEMS sensor supply concentration:Taiwan and South Korean foundries control the majority of microelectromechanical systems production for flow-rate detection, exposing device manufacturers to single-source vulnerability.
- GDPR data residency mandates:European patient inhalation data must remain within jurisdictional boundaries, forcing cloud infrastructure duplication that elevates platform operating costs.
- Dry powder inhaler substitution:Non-connected DPIs retain cost advantages in COPD maintenance therapy, limiting smart inhaler penetration in price-sensitive generic drug markets.
Strategic Opportunities
- India's PLI scheme for medical devices:Production-linked incentives for electronics manufacturing are attracting sensor-assembly investments that could establish South Asian export hubs for cost-optimized inhaler platforms.
- Pediatric asthma management:Gamified adherence applications for children remain underdeveloped relative to adult COPD solutions, representing a whitespace for age-appropriate user experience design.
- HIPAA-compliant API ecosystems:Standardized data exchange protocols between inhaler apps and Epic, Cerner, and Meditech EHR systems are reducing integration friction for health system procurement committees.
Industry Challenges
- Firmware validation timelines:FDA software-as-a-medical-device pre-submissions for over-the-air update capabilities are extending time-to-market by eight to fourteen months for connected inhaler developers.
- Biometric sensor fusion:Integrating spirometry-grade flow measurement with acoustic cough detection and GPS environmental triggers demands rare cross-functional expertise in respiratory physiology, signal processing, and cloud architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Inhalers Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metered-Dose Inhalers, Dry Powder Inhalers, Nebulizers, Smart Sensors Technology: Bluetooth, RFID, GPS, Mobile App Integration End User: Patients, Healthcare Providers, Caregivers, Researchers Application: Asthma Management, COPD Care, Allergy Treatment, Clinical Trials |
| Companies Covered | Adherium, Propeller Health, GlaxoSmithKline, AstraZeneca, Novartis AG, Teva Pharmaceuticals Industries, COHERO Health Inc., 3M, Cipla Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Inhalers Market Emerging Trajectories
Sensor miniaturization and edge computing migration are redistributing analytical workloads between inhaler hardware and mobile applications, altering how adherence algorithms process patient data in real time.
Capacitive sensing technology is fragmenting the incumbent pressure-based flow measurement paradigm in smart inhaler design. Pulmonology clinics in Germany and the Netherlands are piloting capacitive platforms for sub-optimal inhalation technique detection. The technology is fragmenting vendor competitive sets by enabling new entrants to bypass established MEMS supply relationships.
FDA digital health pre-certification pilot expansion is compressing review timelines for software-integrated respiratory devices. Manufacturers with established quality management systems now qualify for streamlined 510(k) pathways when modifying cloud analytics algorithms. Small-cap platform developers with limited regulatory affairs staffing are disproportionately benefiting from this procedural efficiency.
Hospital pharmacy committees are unbundling device procurement from pharmaceutical supply contracts, enabling standalone evaluation of sensor platform value. Academic medical centers in Massachusetts and California are leading this separation, creating direct purchasing relationships with connected inhaler vendors independent of drug manufacturer bundling. The shift is most visible in Medicaid-managed care populations where adherence data supports quality bonus calculations.
Smart Inhalers Market Segmentation
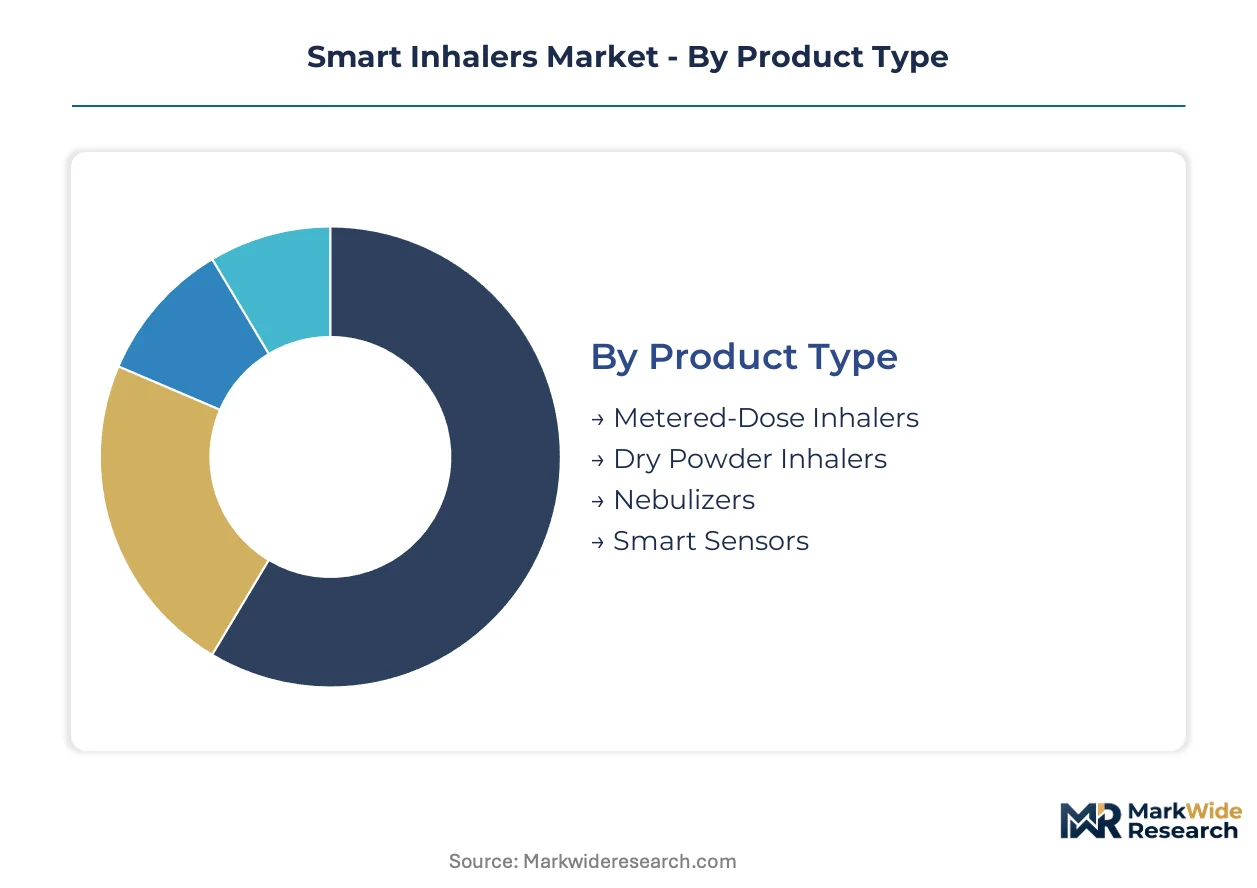
Smart inhaler segmentation reveals how regulatory pathways, reimbursement structures, and patient adherence requirements reshape procurement priorities across device categories. Technology layers and end-user workflows fragment competitive positioning, with FDA software-as-a-medical-device pathways and EU MDR certification creating divergent compliance costs for connected respiratory platforms.
Product Type:
FDA 510(k) clearance timelines and EU MDR technical documentation requirements impose distinct compliance burdens on sensor-integrated versus legacy mechanical designs, favoring manufacturers with established quality management systems.
- Metered-Dose Inhalers:Electronically augmented pMDIs embed Bluetooth Low Energy transmitters and MEMS flow sensors to capture actuation timing and inspiratory velocity. Hospital systems in the United States prioritize these devices for asthma populations where Medicare remote therapeutic monitoring codes now reimburse adherence data transmission. Established volume favors metered-dose inhalers; emerging adoption favors smart sensors.
- Dry Powder Inhalers:Non-connected DPIs retain cost advantages in COPD maintenance therapy, though sensor-attachment retrofit kits are penetrating European markets where GDPR data residency mandates complicate cloud infrastructure. Pulmonology clinics in Germany pilot capacitive sensing overlays for inhalation technique feedback.
- Nebulizers:Compressor and mesh nebulizer platforms with connectivity modules serve severe asthma and pediatric populations requiring dose verification.
- Smart Sensors:Clip-on and cap-integrated adapters transform legacy inhalers into connected devices, capturing margin pools among cost-conscious health systems in India and Southeast Asia.
Cost tiering separates premium integrated platforms from economy retrofit attachments.
Technology:
Power consumption and cybersecurity validation requirements fragment technology adoption curves across patient-facing and clinical-facing deployment scenarios.
- Bluetooth:Bluetooth Low Energy protocols dominate patient daily use compliance, enabling multi-day battery life in compact form factors. FDA pre-certification pilot participants leverage established wireless stacks for streamlined 510(k) submissions. Established volume favors Bluetooth; emerging adoption favors mobile app integration.
- Mobile App Integration:Real-time adherence dashboards and gamified interfaces represent the technology layer expanding most quickly as Epic and Cerner EHR integration reduces health system procurement friction.
- RFID:Near-field authentication supports pharmacy dispensing verification and counterfeit detection in European supply chains.
- GPS:Environmental trigger correlation via geolocation tagging remains concentrated in research applications and academic medical center pilots.
Procurement committees weight interoperability against standalone functionality.
End User:
Workflow integration requirements and data literacy levels reshape user experience design priorities across patient-direct and clinical-intermediated channels.
- Patients:Direct-to-consumer channels emphasize simplified onboarding and medication reminder interfaces. Pediatric asthma management demands age-appropriate gamification absent from adult COPD solutions.
- Healthcare Providers:Pulmonology clinics and hospital systems drive volume through value-based care contracts linking adherence metrics to shared savings calculations. Established volume favors healthcare providers; emerging adoption favors caregivers.
- Caregivers:Family member dashboard access and alert escalation pathways serve pediatric and elderly populations with medication supervision needs.
- Researchers:Clinical trial sponsors utilize connected inhaler data for real-world evidence generation and protocol adherence monitoring.
Customer type determines data export format and regulatory documentation requirements.
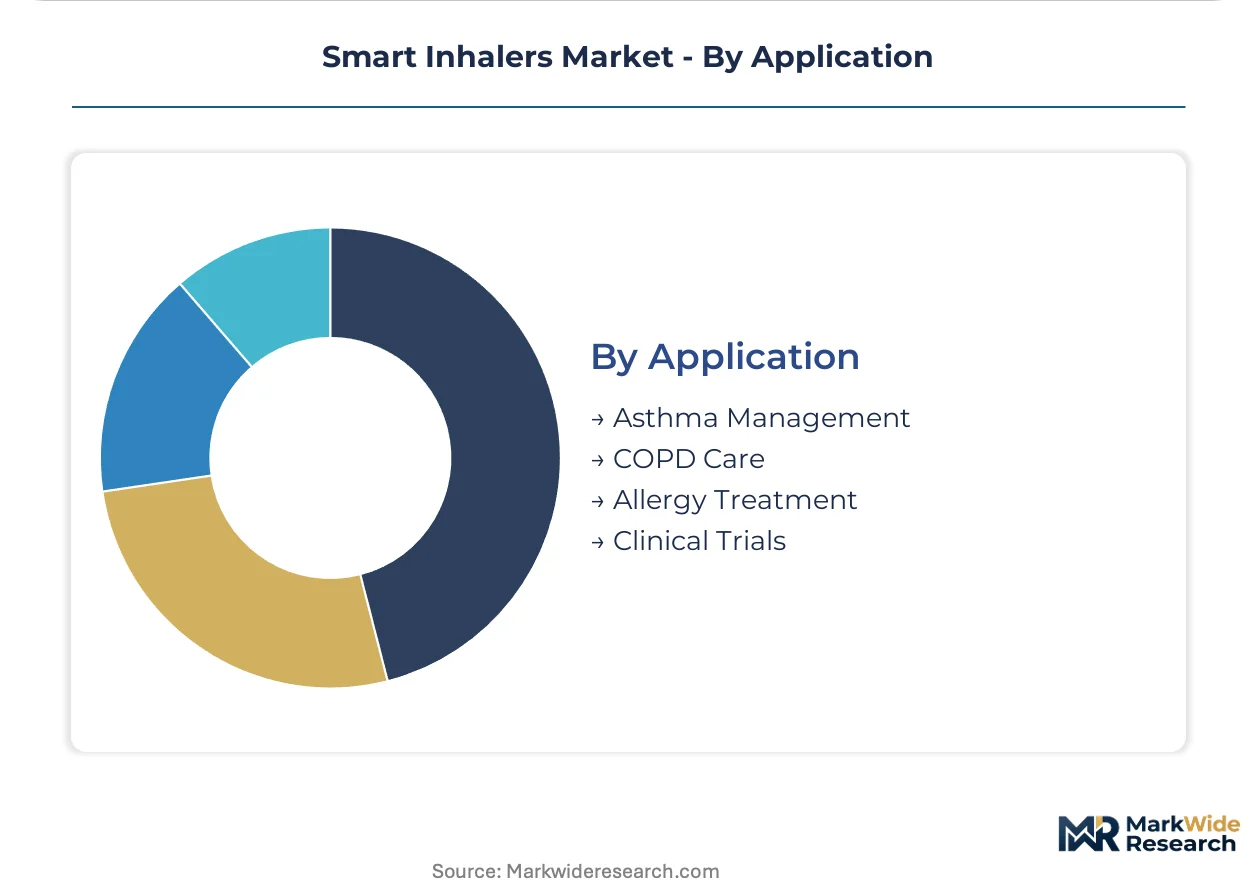
Application:
Disease severity profiles and reimbursement code availability concentrate deployment economics across chronic maintenance and acute intervention scenarios.
- Asthma Management:Pediatric and adolescent populations drive demand for technique coaching and trigger identification, with school-based deployment programs expanding in Massachusetts and California. Established volume favors asthma management; emerging adoption favors clinical trials.
- COPD Care:Medicare Advantage plans incorporate connected inhaler adherence into STAR rating calculations, accelerating deployment among dual-eligible populations.
- Allergy Treatment:Seasonal immunotherapy adherence tracking remains underpenetrated relative to chronic respiratory conditions.
- Clinical Trials:Pharmaceutical sponsors deploy connected platforms for decentralized trial designs, with FDA guidance on digital health endpoints shaping validation requirements.
Application maturity correlates with chronic disease prevalence and payer incentive alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of sensor-integrated inhaler platforms concentrate from German and Swiss precision manufacturers toward North American hospital systems, while South Korean MEMS foundries supply critical flow-detection components to device assemblers across multiple continents. Import dependency for microelectromechanical systems creates supply vulnerability that regional production incentives in India and Southeast Asia aim to address.
United States
Medicare remote therapeutic monitoring reimbursement codes and value-based care contracts drive hospital system procurement of connected inhaler platforms. FDA digital health pre-certification programs streamline 510(k) pathways for sensor-integrated devices. Massachusetts and California academic medical centers lead unbundled device procurement from pharmaceutical supply contracts.
Germany
Pulmonology clinics in Bavaria and Baden-Württemberg pilot capacitive sensing overlays for inhalation technique detection in COPD populations. EU Medical Device Regulation technical documentation requirements favor established quality management systems among domestic manufacturers. Berlin-Brandenburg hosts regulatory consulting clusters supporting MDR certification for wireless respiratory devices.
India
Production-linked incentive schemes for electronics manufacturing attract sensor-assembly investments targeting cost-optimized inhaler platform exports. Central Drugs Standard Control Organization medical device rules govern connected respiratory product registrations. Maharashtra and Karnataka industrial corridors develop component sourcing ecosystems for clip-on smart sensor attachments.
United Kingdom
National Health Service long-term plan commitments to respiratory disease management support pilot deployments of adherence-monitoring technologies. Medicines and Healthcare products Regulatory Agency guidance on software as a medical device shapes validation requirements for connected inhaler apps. London and Greater Manchester health systems integrate inhaler data into electronic health record workflows.
Japan
Pharmaceutical and Medical Devices Agency digital health endpoint validation frameworks guide connected inhaler integration into clinical trial designs. Ministry of Economy, Trade and Industry industrial standards support Bluetooth Low Energy protocol adoption in compact medical devices. Kanto region medical device clusters develop multi-day battery life innovations for patient compliance.
Smart Inhalers Market Vendor Landscape
Concentration sits with pharmaceutical-device combination portfolios and standalone sensor platform developers, creating a bifurcated structure where backward integration into drug supply chains competes against cloud-native adherence analytics. Tier-one positions cluster around large-cap respiratory pharmaceutical manufacturers with captive device divisions. Tier-two positions aggregate specialized digital health platform developers. Competitive moves center on portfolio diversification into biologics-linked adherence programs and strategic partnerships for EHR interoperability.
Within the pharmaceutical-device combination tier, GlaxoSmithKline and AstraZeneca exemplify archetypes leveraging drug portfolio scale to anchor connected inhaler distribution. Among standalone platform developers, Propeller Health occupies a position representing cloud-connected analytics specialization. Teva Pharmaceuticals Industries sits within a hybrid archetype spanning both generic manufacturing breadth and branded respiratory device integration. These three anchors illustrate how competitive positioning fragments across drug-device integration depth versus software-native architecture purity.
| Leading Market Players |
|---|
| Adherium |
| Propeller Health |
| GlaxoSmithKline |
| AstraZeneca |
| Novartis AG |
| Teva Pharmaceuticals Industries |
| COHERO Health Inc. |
| 3M |
| Cipla Ltd. |
| Others |
Supply Flow & Price Mechanics
Capacitive sensing overlays displacing MEMS-based flow sensors in German and Dutch pulmonology clinics are simultaneously redrawing component sourcing maps from Taiwan and South Korea toward European precision manufacturers and compressing price premiums for inhalation technique detection modules.
Pricing Analysis
Hospital pharmacy committees anchor pricing negotiations through unbundled device procurement from pharmaceutical supply contracts. Three-tier pricing structure across premium integrated platforms, mid-range Bluetooth-enabled pMDIs, and economy clip-on sensor attachments stratifies according to FDA 510(k) clearance tier and Epic EHR integration depth. Cost compression in economy retrofit tiers intensifies as Indian PLI scheme beneficiaries enter export markets. Medicaid-managed care populations exhibit highest price sensitivity; academic medical centers with quality bonus calculations demonstrate lowest.
Supply Chain Analysis
Taiwan Strait shipping lanes underwrite critical microelectromechanical systems flow sensor delivery to device assemblers across North America and Europe. MEMS production concentrates in Taiwan and South Korean foundries; capacitive sensing component manufacturing clusters in Bavaria and Baden-Württemberg. Supply chain vulnerability rests on single-source dependency for spirometry-grade flow measurement chips. Distribution runs through hospital GPO contracts and direct purchasing relationships with academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around FDA digital health pre-certification and EU MDR technical documentation creates defensive moats for established quality management systems, raising compliance barriers for unvalidated sensor platforms.
For Market Incumbents: Consolidate backward integration into MEMS sensor supply through captive relationships with South Korean foundries or strategic capacitive sensing technology acquisitions. Deepen hospital system partnerships in Massachusetts and California where unbundled procurement creates direct vendor relationships independent of pharmaceutical bundling.
For New Entrants and Emerging Players: Anchor in pediatric asthma management whitespace where gamified adherence applications remain underdeveloped relative to adult COPD solutions. Target school-based deployment programs in California and Massachusetts with age-appropriate user experience design and caregiver dashboard access.
For Investors and Strategic Acquirers: FDA digital health pre-certification pilot expansion reshapes the acquisition landscape toward small-cap platform developers with streamlined 510(k) pathways. Long-term viability hinges on reimbursement code evolution for remote therapeutic monitoring. Watch Medicare Advantage STAR rating calculation methodologies as inflection signal for COPD care monetization.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Digital Health Pre-Certification | Streamlined 510(k) pathways compress regulatory timelines for sensor-integrated pMDI developers. |
| EU MDR Technical Documentation | Wireless respiratory device certification favors established German and Swiss quality management systems. |
| Hospital System Partnership | Epic and Cerner EHR integration reduces procurement friction for pulmonology clinic adherence dashboards. |
| Capacitive Sensing Development | Bypasses incumbent MEMS supply relationships while enabling sub-optimal inhalation technique detection. |
| Reimbursement Strategy | Medicare remote therapeutic monitoring codes convert pilot deployments into infrastructure commitments. |
Methodological Framework
Initial hypotheses were tested against primary input from pulmonology clinic directors, hospital pharmacy committee chairs, biomedical engineers, and GPO contracts managers and refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement code updates, and hospital procurement records. Bottom-up unit economics triangulated against top-down market sizing.
Variance decomposition across product type, technology layer, end-user workflow, and application severity drove analytical framework construction throughout the projection horizon. CAGRs derived from patient population growth, reimbursement code adoption curves, and health system capital expenditure patterns. Modeled inputs included Bluetooth Low Energy protocol penetration rates and cloud infrastructure deployment costs.
Material uncertainties — MEMS foundry supply disruptions, FDA software-as-a-medical-device pre-submission timeline extensions, GDPR data residency mandate enforcement — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as Medicare remote therapeutic monitoring reimbursement evolution and EU MDR certification backlog resolution unfold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Upper GI Series Market
Diagnostic and Therapeutic Devices
One-Step ELISA Market
Diagnostic and Therapeutic Devices
Localized Temperature Therapy Products Market
Diagnostic and Therapeutic Devices
Electroceuticals Bioelectric Medicine Market
Diagnostic and Therapeutic Devices
Positive Patient Identification Market
Diagnostic and Therapeutic Devices
Therapeutic Medical Guidewire Market
Diagnostic and Therapeutic Devices
Dental Surgical and Diagnostic Devices Market
Diagnostic and Therapeutic Devices
Therapeutic Support Surface Market
Diagnostic and Therapeutic Devices
Smart Drug Delivery Systems Market
Diagnostic and Therapeutic Devices
US Cancer Contrast Media Market
Diagnostic and Therapeutic Devices
Dermatology Diagnostic Equipment Market
Diagnostic and Therapeutic Devices
Automated Immunoassay Analyzers Market
Diagnostic and Therapeutic Devices
Global Acute Ischemic Stroke Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Therapeutic Catheters Market
Diagnostic and Therapeutic Devices
Global Acoustic Medicine and Ultrasound Therapy Market
Diagnostic and Therapeutic Devices
Global Needle Free Injection Systems Market