
 Smart Drug Delivery Systems Market | 2026-2036
Smart Drug Delivery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Drug Delivery Systems Market Analytics
Project finance for connected infusion pump fleets is tilting competitive dynamics toward asset-light service models. Medtronic plc leverages its vertical integration in pump manufacturing and sensor technology to sustain pricing power across hospital contracts. Insulet Corporation anchors its position through direct-to-consumer channel control in insulin delivery, while Gerresheimer AG specializes in glass and polymer primary packaging that competes on material compatibility with biologics.
Smart drug delivery systems integrate sensors, feedback algorithms, and actuators into pharmaceutical administration devices to achieve dose precision, timing control, and patient adherence monitoring through programmable release kinetics and real-time biometric inputs. Infusion pumps incorporating microfluidics technology dominate current hospital procurement, while nanotechnology-enabled injectables represent the fastest-expanding segment as biologic drug pipelines thicken. Transdermal patches with biodegradable polymer matrices occupy mature volume positions, though margin pools concentrate in smart biologics delivery where formulation-device integration creates higher barriers.
The FDA's breakthrough device designation and the EU MDR's clinical evidence requirements for active implantable devices shape product development timelines and market access costs on both sides of the Atlantic. REACH compliance for polymer constituents and ECHA substance restrictions further constrain material selection for transdermal and microneedle platforms entering European distribution. Stakeholders must monitor how reimbursement authorities in Germany and the United States calibrate coding for connected delivery outcomes versus conventional administration.
Market Dynamics
The programmable infusion pump sector is experiencing a structural compression between hospital capital budgets and biologic therapy complexity, forcing manufacturers to absorb sensor integration costs while maintaining service uptime guarantees across multi-year fleet contracts.
Growth Catalysts
- FDA Breakthrough Device Designation:The accelerated review pathway for connected delivery platforms shortens commercialization timelines by 12-18 months, enabling faster hospital procurement cycles for programmable pumps.
- German Digital Therapeutics Reimbursement:Expanding coverage codes for device-integrated drug administration in hospital networks creates predictable revenue streams for connected delivery system vendors.
- Microfluidics Integration:Precision dosing capabilities in oncology and endocrinology applications are pulling replacement demand from legacy volumetric pumps across United States cancer centers.
Market Restraints
- Polymer Input Volatility:Medical-grade polycarbonate and cyclic olefin polymer prices fluctuate with petrochemical feedstock costs, squeezing margins for transdermal patch and microneedle manufacturers.
- EU MDR Clinical Evidence Burden:The expanded requirements for active implantable devices force manufacturers to maintain parallel technical documentation systems, doubling regulatory compliance overhead.
- Biologic Formulation Compatibility:Protein aggregation and shear sensitivity in monoclonal antibodies limit material choices for pump reservoirs and tubing, constraining design flexibility.
Strategic Opportunities
- Home-Based Infusion Expansion:Untapped demand for ambulatory pumps in United States post-acute care settings offers volume growth outside saturated hospital procurement channels.
- Biodegradable Microneedle Arrays:Convergence of polymer science and miniaturized electronics enables single-use smart patches for vaccine delivery, opening pediatric and travel medicine applications.
- India PLI Scheme for Medical Devices:Production-linked incentives for domestic manufacturing of drug delivery hardware reduce import dependence and create localized supply hubs for South Asian markets.
Industry Challenges
- Cybersecurity Certification Complexity:FDA premarket guidance for interconnected devices requires specialized firmware validation expertise that outstrips current talent pools in most engineering organizations.
- Legacy Hospital IT Integration:Electronic health record interoperability with pump data streams demands custom API development, extending deployment timelines and inflating implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Drug Delivery Systems Market |
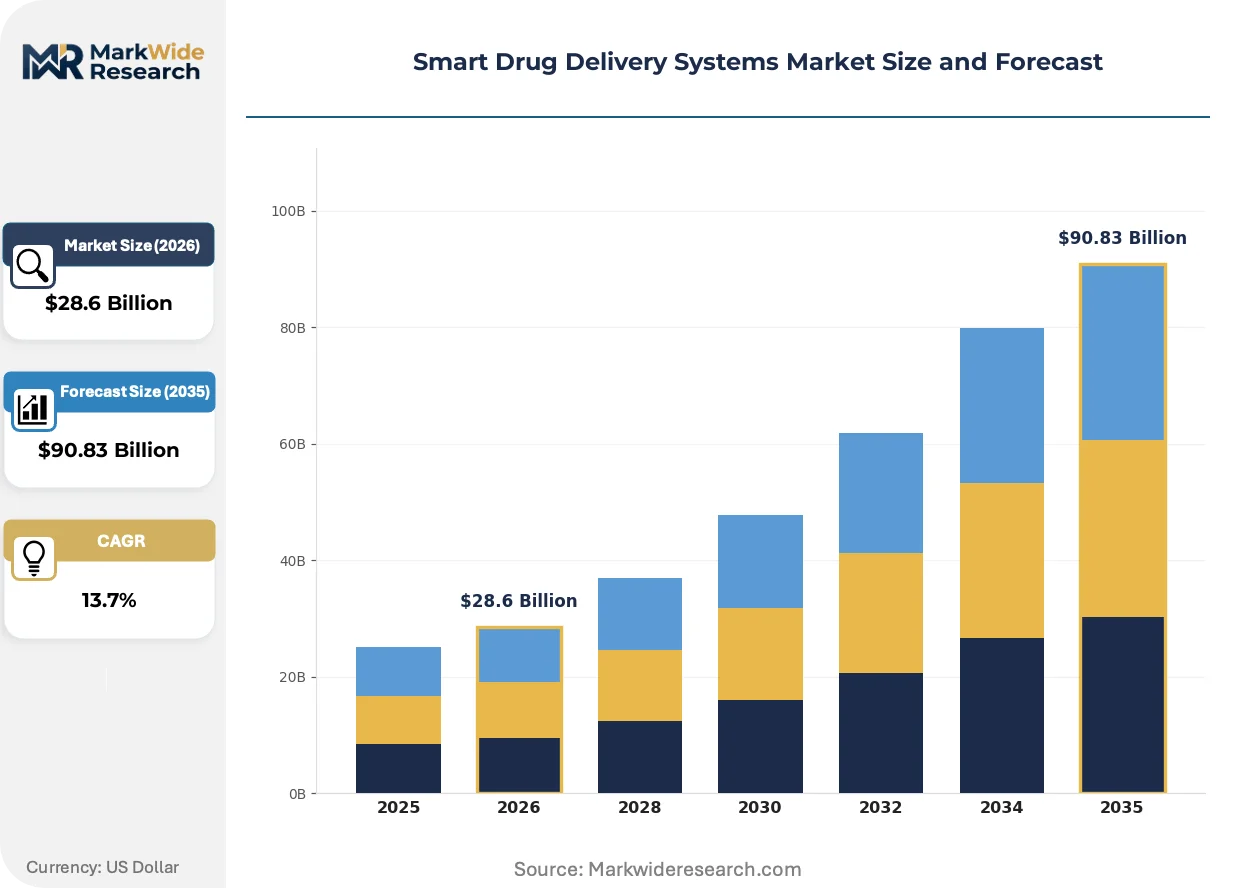
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $90.83 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microneedles, Inhalers, Transdermal Patches, Infusion Pumps Technology: Nanotechnology, Biodegradable Polymers, Smart Biologics, Microfluidics End User: Hospitals, Home Care, Clinics, Research Laboratories Delivery Mode: Oral, Injectable, Intranasal, Topical |
| Companies Covered | Medtronic plc, Becton, Dickinson and Company, Insulet Corporation, Novo Nordisk A/S, Baxter International Inc., Johnson & Johnson Services, Inc., Gerresheimer AG, Smiths Group plc, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Drug Delivery Systems Market Evolving Landscape
Sensor-enabled drug delivery is fragmenting into parallel technology tracks, with hospital procurement favoring closed-loop infusion systems while consumer markets pull toward discreet wearable injectors.
Closed-loop insulin delivery systems are hybridizing continuous glucose monitoring with algorithm-driven basal rate adjustments. Pediatric endocrinology clinics in the United States are adopting these platforms faster than adult diabetes centers, compressing the competitive window for conventional pump manufacturers to demonstrate glycemic outcome superiority.
REACH substance restrictions on phthalates and bisphenol-A are forcing reformulation of polymer matrices in transdermal and implantable devices. European manufacturers face 18-24 month material requalification timelines, while Asian suppliers without equivalent regulatory exposure capture transitional market share in non-EU distribution channels.
Hospital pharmacy directors are unbundling device acquisition from drug supply contracts, treating pumps as capital equipment rather than bundled consumables. This purchasing autonomy is most visible in Germany's university hospital networks, where centralized procurement offices negotiate multi-vendor fleet agreements separate from pharmaceutical formularies.
Smart Drug Delivery Systems Market Segmentation
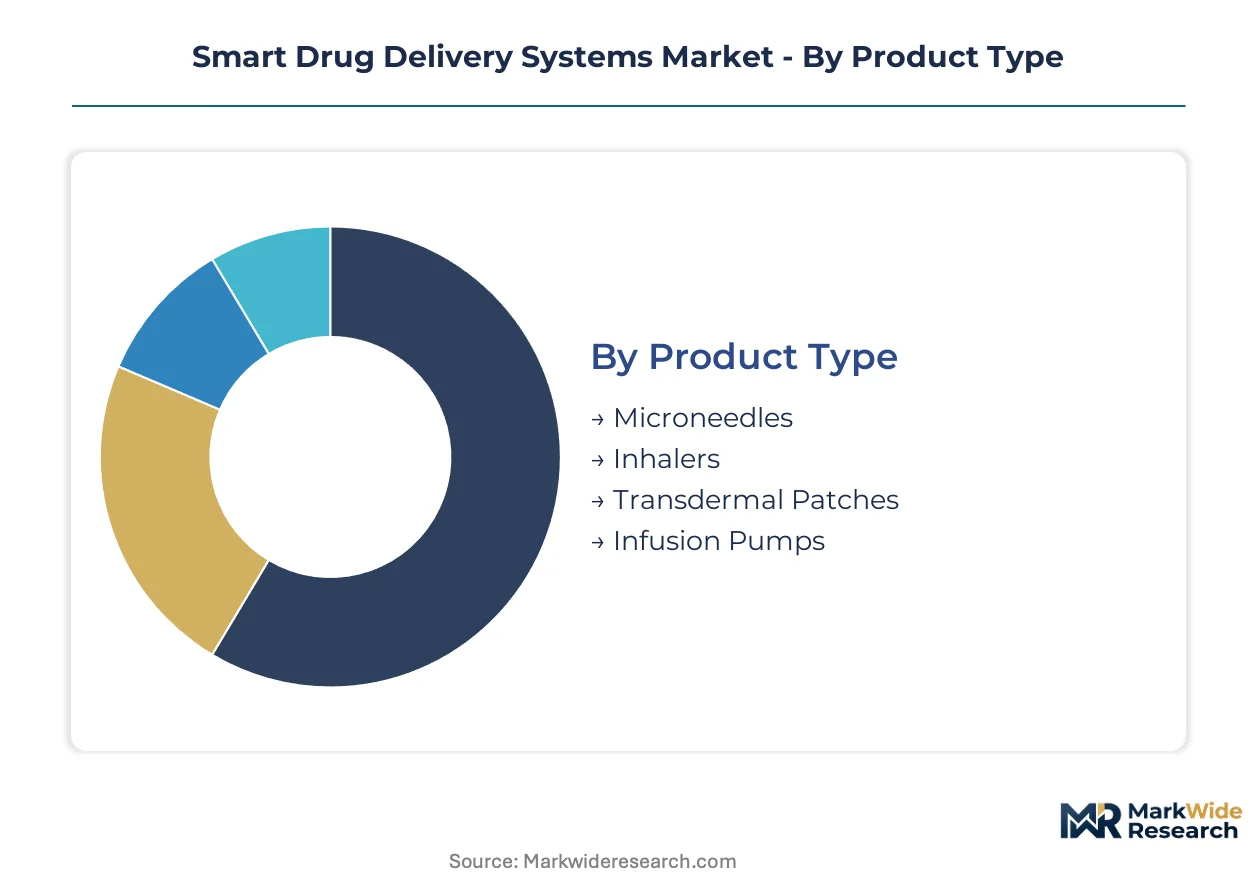
Segmentation in smart drug delivery systems reveals divergent investment cycles across hardware platforms and molecular technologies. Replacement rates vary from 3-year pump fleet rotations to decade-long transdermal formulation patents, reshaping how vendors allocate R&D and manufacturing capacity.
Product Type:
Cycle times range from single-use microneedle disposables to capital-intensive infusion pumps with 7-year depreciation schedules.
- Infusion Pumps:Programmable volumetric and syringe pumps incorporate sensor feedback loops for closed-loop insulin and chemotherapy administration. United States oncology centers are expanding fleet procurement under 5-year service contracts that bundle hardware, maintenance, and cybersecurity updates.
- Microneedles:Dissolving and hydrogel-forming arrays enable painless transdermal delivery of vaccines and biologics without cold-chain requirements. Pediatric vaccination programs in Germany are piloting single-use microneedle patches to reduce needle phobia and improve coverage rates in school-based immunization campaigns.
- Transdermal Patches:Matrix and reservoir-type patches with rate-controlling membranes deliver hormones, pain medications, and smoking cessation therapies through intact skin.
- Inhalers:Dry powder and metered-dose inhalers with dose counters and Bluetooth connectivity monitor adherence in asthma and COPD management.
Infusion pumps dominate installed base. Microneedles are where expansion concentrates.
Technology:
Cost tiers separate commodity polymer platforms from premium nanotechnology-enabled systems requiring specialized manufacturing infrastructure.
- Microfluidics:Precision-machined channels and valves enable picoliter-scale dosing control for personalized medicine applications. Hospital pharmacies in the United States are adopting microfluidic infusion systems for pediatric chemotherapy to minimize dosing errors in weight-based calculations.
- Nanotechnology:Lipid nanoparticles, polymeric micelles, and dendrimers enhance solubility and targeted delivery of poorly bioavailable compounds. Oncology drug developers are prioritizing nanotechnology formulations for tumor-targeted payload release, though EMA stability requirements extend development timelines.
- Biodegradable Polymers:Polylactic acid, polyglycolic acid, and their copolymers enable controlled release from implantable depots and microneedles without surgical retrieval.
- Smart Biologics:Formulation-device integration for monoclonal antibodies and cell therapies demands material compatibility testing to prevent protein aggregation and immunogenicity.
Microfluidics commands premium pricing in acute care. Nanotechnology is climbing the fastest in development pipelines.
End User:
Volume concentrates in institutional procurement, while margin pools shift toward home-based delivery models with recurring consumable revenue.
- Hospitals:Inpatient and outpatient departments require FDA-cleared pumps with interoperability to electronic health record systems. German university hospital networks are consolidating procurement through centralized fleet management offices that negotiate multi-vendor agreements.
- Home Care:Ambulatory infusion pumps and wearable injectors enable chemotherapy, immunoglobulin, and parenteral nutrition outside acute settings. United States home infusion providers are expanding remote monitoring capabilities to reduce nursing visit frequency and hospital readmission penalties.
- Clinics:Physician offices and dialysis centers utilize simpler pump configurations for shorter-duration therapies without intensive monitoring.
- Research Laboratories:Preclinical and clinical trial units demand flexible pump platforms with programmable protocols for pharmacokinetic studies.
Hospitals anchor volume demand. Home care is where vendor margins are expanding.
Delivery Mode:
Maturity curves separate established oral and injectable routes from emerging intranasal and topical platforms seeking regulatory validation.
- Injectable:Subcutaneous, intramuscular, and intravenous administration via prefilled syringes, autoinjectors, and infusion systems remains the standard for biologics. Monoclonal antibody compatibility constraints limit material choices for pump reservoirs and tubing, forcing polymer requalification cycles.
- Oral:Modified-release tablets and capsules with osmotic pump technology dominate chronic disease management for small molecules. Patient adherence monitoring through sensor-enabled pill bottles is gaining traction in United States value-based care contracts.
- Intranasal:Mucosal delivery of vaccines and emergency medications exploits high vascularization and bypasses first-pass metabolism.
- Topical:Transdermal and dermal formulations for local and systemic effects compete on patient convenience versus absorption variability.
Injectable modes command the largest revenue base. Intranasal delivery is gaining share fastest in vaccine applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement offices in Germany and oncology centers across the United States concentrate purchasing authority for connected infusion platforms, while India's production-linked incentives are drawing manufacturing investment away from traditional European supply bases.
United States
Oncology centers in Boston and Houston are expanding fleet procurement of programmable infusion pumps under bundled service contracts. The FDA's breakthrough device designation pathway accelerates commercialization timelines for connected delivery platforms seeking hospital formulary inclusion. Greater Boston's biotech corridor anchors development activity for closed-loop insulin systems.
Germany
University hospital networks in Berlin and Munich are consolidating procurement through centralized fleet management offices that negotiate multi-vendor agreements. The EMA's clinical evidence requirements for active implantable devices shape product development timelines for manufacturers seeking European market access. Baden-Württemberg's medical technology cluster concentrates sensor manufacturing for pump integration.
India
Domestic hospital chains in Mumbai and Delhi are expanding adoption of ambulatory infusion systems for post-acute care transitions. The PLI scheme for medical devices reduces import dependence and creates localized supply hubs for South Asian markets. Gujarat's pharmaceutical manufacturing belt is attracting contract production of polymer-based drug delivery components.
Japan
Aging demographics in Tokyo and Osaka are driving demand for home-based infusion therapies with remote monitoring capabilities. The PMDA's regulatory framework for combination products governs approval pathways for device-drug integrated systems. The Kansai region's precision engineering base supplies microfluidic components for next-generation pump platforms.
Switzerland
Specialty pharmaceutical manufacturers in Basel are prioritizing formulation-device integration for monoclonal antibody delivery. Swissmedic's regulatory requirements for biologic compatibility testing constrain material selection for pump reservoirs and tubing. The Zurich-Lugano corridor hosts development partnerships between device engineers and biologics formulators.
Smart Drug Delivery Systems Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers: vertically integrated conglomerates with captive hospital sales forces, mid-scale technology licensors focused on sensor integration, and regional fabricators serving localized procurement channels. Market structure tilts toward consolidation in programmable infusion pumps while fragmenting across microneedle disposables and transdermal platforms. Dominant competitive moves include backward integration into polymer manufacturing and strategic partnerships with biologics developers for formulation-device co-development.
Among diversified healthcare conglomerates, Medtronic plc and Johnson & Johnson Services, Inc. occupy positions spanning pump manufacturing and hospital contracting infrastructure. Insulet Corporation exemplifies the direct-to-consumer channel control archetype in insulin delivery, while Gerresheimer AG represents European specialization in primary packaging materials. Becton, Dickinson and Company and Baxter International Inc. anchor the hospital procurement tier through established service relationships with United States oncology centers.
| Leading Market Players |
|---|
| Medtronic plc |
| Becton, Dickinson and Company |
| Insulet Corporation |
| Novo Nordisk A/S |
| Baxter International Inc. |
| Johnson & Johnson Services, Inc. |
| Gerresheimer AG |
| Smiths Group plc |
| Abbott Laboratories |
| Others |
Value Network & Pricing Analysis
Polymer feedstock volatility tethered to petrochemical indexation determines both the spread between premium sensor-integrated pumps and economy volumetric units and the geographic clustering of component sourcing. REACH substance restrictions on phthalates and bisphenol-A force European manufacturers into 18-24 month material requalification cycles, while Asian suppliers without equivalent regulatory exposure capture transitional share in non-EU channels.
Pricing Analysis
Cost-plus contracts with medical-grade polycarbonate and cyclic olefin polymer indexation dominate procurement for transdermal patch and microneedle manufacturers. Three-tier pricing structure across premium closed-loop systems, standard programmable pumps, and economy volumetric units separates FDA breakthrough-designated platforms from CE-marked alternatives and unconnected legacy hardware. Pricing pressure stems from hospital pharmacy directors unbundling device acquisition from drug supply contracts and treating pumps as capital equipment rather than bundled consumables. Home care providers exhibit highest price sensitivity due to reimbursement compression, while German university hospital networks demonstrate lowest sensitivity under centralized fleet management with multi-year service guarantees.
Supply Chain Analysis
Upstream medical-grade polymer production concentrates in Germany, the United States, and Japan, with specialized cyclic olefin polymer and polycarbonate formulations feeding transdermal and microneedle fabrication. Sensor module assembly draws from South Korean and Taiwanese semiconductor foundries, while precision microfluidic machining anchors in Switzerland and the Kansai region of Japan. Single-source vulnerability in FDA-cleared pump firmware validation expertise extends procurement timelines and inflates implementation costs for hospital IT integration. Distribution runs through GPO-contracted medical device distributors in the United States, direct hospital procurement offices in Germany, and domestic hospital chains in India leveraging PLI scheme localization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through FDA breakthrough designation and EU MDR technical documentation creates switching costs that hospital procurement offices cannot easily circumvent.
For Market Incumbents: Build switching-cost moats through backward integration into polymer manufacturing and captive sensor technology production. Consolidate position by acquiring specialized firmware validation capabilities to address cybersecurity certification complexity that outstrips current talent pools. Defend against emerging Asian suppliers capturing transitional share by accelerating material requalification cycles ahead of REACH substance restriction enforcement. For New Entrants and Emerging Players: Pursue white-space expansion in United States home-based infusion settings where post-acute care transitions create demand for ambulatory pumps outside saturated hospital procurement channels. Target biodegradable microneedle arrays for pediatric vaccination programs in Germany, where school-based immunization campaigns seek needle-phobia reduction. Establish go-to-market positioning through direct partnerships with home infusion providers rather than competing for GPO-contracted hospital access. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors technology licensors with sensor integration specialization over diversified conglomerates with captive sales forces. Long-term viability through the analysis window hinges on formulation-device co-development partnerships with biologics developers as monoclonal antibody pipelines thicken. Watch for inflection signals in German digital therapeutics reimbursement coding expansion, which would validate connected delivery outcome premiums over conventional administration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerates commercialization timelines for connected infusion platforms seeking hospital formulary inclusion. |
| Hospital System Partnership | Enables multi-year fleet service contracts bundling hardware, maintenance, and cybersecurity updates. |
| Software Companion Development | Addresses EHR interoperability demands through custom API development for pump data streams. |
| Reimbursement Strategy | Captures expanding German coverage codes for device-integrated drug administration in hospital networks. |
| CE Marking Pathway | Navigates EU MDR clinical evidence requirements for active implantable devices entering European distribution. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital procurement managers, biomedical engineers, GPO contracts managers, and regulatory affairs leads at connected delivery platform developers. Secondary validation drew from FDA 510(k) and breakthrough device filings, EMA submission databases, German hospital procurement office fleet agreements, and CMS Medicare reimbursement coding records. Bottom-up installed base modeling for infusion pump fleets triangulated against top-down pharmaceutical administration volume projections.
Calibration across the analysis window employed segmented growth models by product type, technology tier, end-user setting, and delivery mode, with regional regulatory clusters as an overlay dimension. CAGRs were derived from replacement cycle analysis for capital equipment and consumable attach rates for disposables. Forecast inputs incorporated biologics pipeline density by therapeutic area, REACH substance restriction implementation timelines, and PLI scheme capacity buildout trajectories in India.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles, petrochemical feedstock costs, or biologics development funding would shift the trajectory. Forecasts reflect documented assumptions about regulatory pathway durations and reimbursement coding expansion. Cross-checking against hospital procurement database benchmarks and GPO contract award records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Middle-East and Africa Stroke Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Microneedle Drug Delivery Systems Market
Diagnostic and Therapeutic Devices
Global Smart Healthcare Products Market
Diagnostic and Therapeutic Devices
Dissolving Microneedles Market
Diagnostic and Therapeutic Devices
Nanobiosensors in Healthcare Market
Diagnostic and Therapeutic Devices
Therapeutic Hypothermia Systems Market
Diagnostic and Therapeutic Devices
Smart Inhalers Market
Diagnostic and Therapeutic Devices
Global Aspiration and Biopsy Needles Market
Diagnostic and Therapeutic Devices
Breast Lesion Localization Market
Diagnostic and Therapeutic Devices
US Cancer Contrast Media Market
Diagnostic and Therapeutic Devices
Global Exosome Diagnostic and Therapeutic Market
Diagnostic and Therapeutic Devices
Crohn's Disease Diagnostic and Therapeutic Market
Diagnostic and Therapeutic Devices
Disposable Negative Pressure Wound Therapy Devices Market
Diagnostic and Therapeutic Devices
Leukocytapheresis Device Market
Diagnostic and Therapeutic Devices
RF Microneedling Market
Diagnostic and Therapeutic Devices
Fully Automated Coagulometer Market