
 Global Smart Healthcare Products Market | 2026-2036
Global Smart Healthcare Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Healthcare Products Market Foresight
ISO 13485 certification is rotating as the primary gating mechanism for supplier qualification in connected medical device ecosystems. Abbott Laboratories leverages vertical integration across sensor fabrication and cloud analytics to sustain platform stickiness. Koninklijke Philips N.V. anchors European hospital procurement through entrenched diagnostic imaging relationships. Medtronic plc dominates implantable smart device segments with deep regulatory dossiers across multiple jurisdictions.
Smart healthcare products encompass sensor-enabled medical devices, connected drug delivery systems, and AI-assisted diagnostic platforms that transmit physiological data to clinical decision systems via encrypted networks. These systems typically operate on low-power wireless protocols with FDA-mandated cybersecurity controls and serve to shift acute interventions toward predictive, continuous care models. Wearable Devices and Remote Monitoring Equipment occupy the largest revenue pools where hospital-at-home programs are expanding device deployment. Digital Therapeutics represents the fastest-expanding category as payers in Germany and the United States establish reimbursement codes for software-based interventions. Artificial Intelligence and Internet of Medical Things technologies concentrate margin capture among vendors with proprietary training datasets and cleared algorithms.
FDA premarket authorization pathways and EMA Medical Device Regulation compliance requirements are elevating documentation burdens for AI-enabled diagnostics while accelerating consolidation among undercapitalized developers. The EU AI Act introduces additional conformity obligations for high-risk healthcare algorithms that will reshape vendor R&D prioritization. Stakeholders must monitor evolving reimbursement decisions from CMS and Germany's Federal Joint Committee as these determine commercial viability for home-based smart care platforms.
Market Dynamics
Hospital-at-home reimbursement expansions by CMS and Germany's Federal Joint Committee are compressing acute care delivery timelines and forcing device manufacturers to reconfigure service models around remote monitoring infrastructure.
Growth Catalysts
- Remote Patient Monitoring Reimbursement:CMS coverage decisions in the United States and parallel rulings by Germany's Federal Joint Committee have established sustainable payment pathways for connected chronic disease management devices.
- EU AI Act Conformity Pathways:The European Union's risk-based algorithm classification system is creating predictable regulatory roadmaps for high-risk diagnostic software developers seeking CE marking under MDR.
- Low-Power Wide-Area Networks:NB-IoT and LoRa protocol deployments across hospital systems are enabling continuous physiological streaming without Wi-Fi infrastructure dependency.
Market Restraints
- Semiconductor Supply Concentration:Advanced biosensor fabrication depends on Taiwanese and South Korean foundry capacity, exposing device makers to single-source vulnerability.
- Cybersecurity Validation Burden:FDA premarket submission requirements for encrypted data transmission are extending clearance timelines for connected diagnostic platforms.
- Legacy System Interoperability:Proprietary electronic health record architectures at major US hospital chains block seamless device-to-clinic data flow without expensive middleware.
Strategic Opportunities
- Japan's Super-Aging Demographics:METI incentives for home-based care technologies are opening procurement channels for fall-detection and medication adherence systems in rural prefectures.
- Digital Therapeutics Reimbursement:Germany's DiGA fast-track approval process is creating first-mover advantages for prescription software interventions targeting diabetes and mental health.
- AI-Edge Convergence:On-device inference chips are enabling real-time arrhythmia detection without cloud dependency, reducing latency for cardiac implantable devices.
Industry Challenges
- ISO 13485 Auditor Scarcity:Qualified certification bodies for connected device quality management are backlogged 8-14 months across North America and Europe.
- Multi-Jurisdiction Dossier Fragmentation:Divergent cybersecurity documentation requirements between FDA, EMA, and PMDA are forcing redundant testing expenditures.
- Clinical Evidence Generation Costs:Randomized controlled trials for AI diagnostic algorithms require patient cohorts exceeding 10,000 subjects to satisfy regulatory statistical power thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Healthcare Products Market |
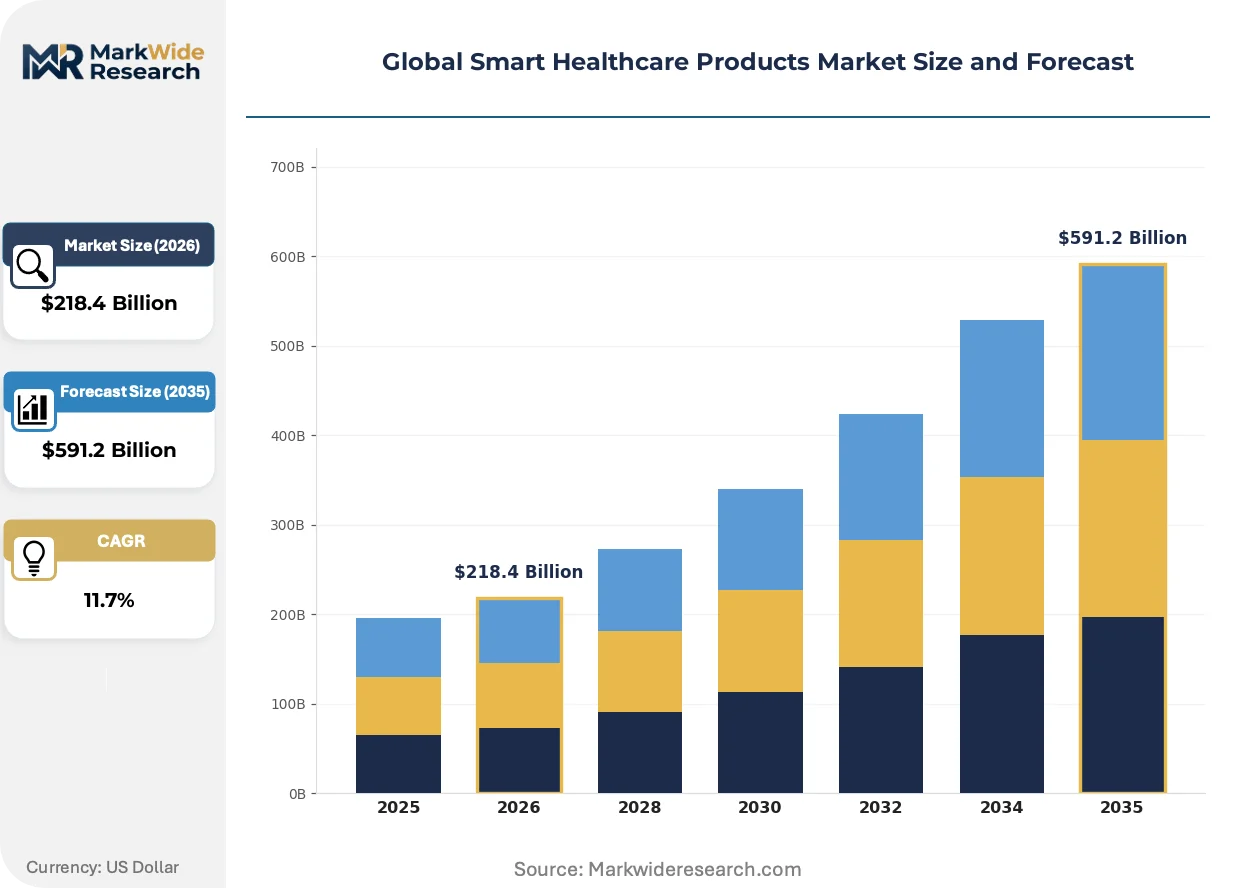
| Market Size in 2026 | $218.4 Billion |
| Market Size in 2035 | $591.2 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Remote Monitoring Equipment, Smart Pills, Connected Inhalers, Digital Therapeutics Application: Chronic Disease Management, Preventive Care, Elderly Care, Fitness Monitoring, Medication Adherence End User: Hospitals, Ambulatory Care Centers, Home Care Settings, Diagnostic Laboratories, Rehabilitation Centers Technology: Artificial Intelligence, Internet of Medical Things, Cloud Computing, Data Analytics, Blockchain |
| Companies Covered | Abbott Laboratories, GE Healthcare, Koninklijke Philips N.V., Medtronic plc, Siemens Healthineers AG, Apple Inc., Samsung, Dexcom Inc., Allscripts Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Healthcare Products Market Shifts & Advancements
Continuous glucose monitoring platforms are migrating from diabetes management toward broader metabolic health applications, reshaping sensor economics and expanding addressable patient populations beyond traditional chronic disease boundaries.
Photoplethysmography-based blood pressure estimation is supplanting cuff-based oscillometric devices in ambulatory settings. Cardiology departments at US academic medical centers are piloting wrist-worn systems for 24-hour hypertension surveillance. This transition is compressing reimbursement timelines for wearable cardiovascular diagnostics as payers recognize cost avoidance from reduced emergency department utilization.
The EU AI Act's high-risk healthcare algorithm classification is mandating conformity assessments for diagnostic software previously self-certified under MDR. Developers must now submit technical documentation demonstrating bias mitigation and post-market monitoring protocols. French and Dutch notified bodies are experiencing application surges that are delaying CE marking decisions by 4-6 months for machine learning-enabled imaging tools.
Hospital procurement committees are unbundling device hardware from data analytics subscriptions, forcing vendors to price components separately. Health systems in the United Kingdom and Australia are negotiating direct cloud infrastructure contracts independent of device OEMs. This disaggregation is most advanced in radiology departments where PACS-agnostic AI viewers are gaining preference over integrated platform offerings.
Global Smart Healthcare Products Market Segmentation
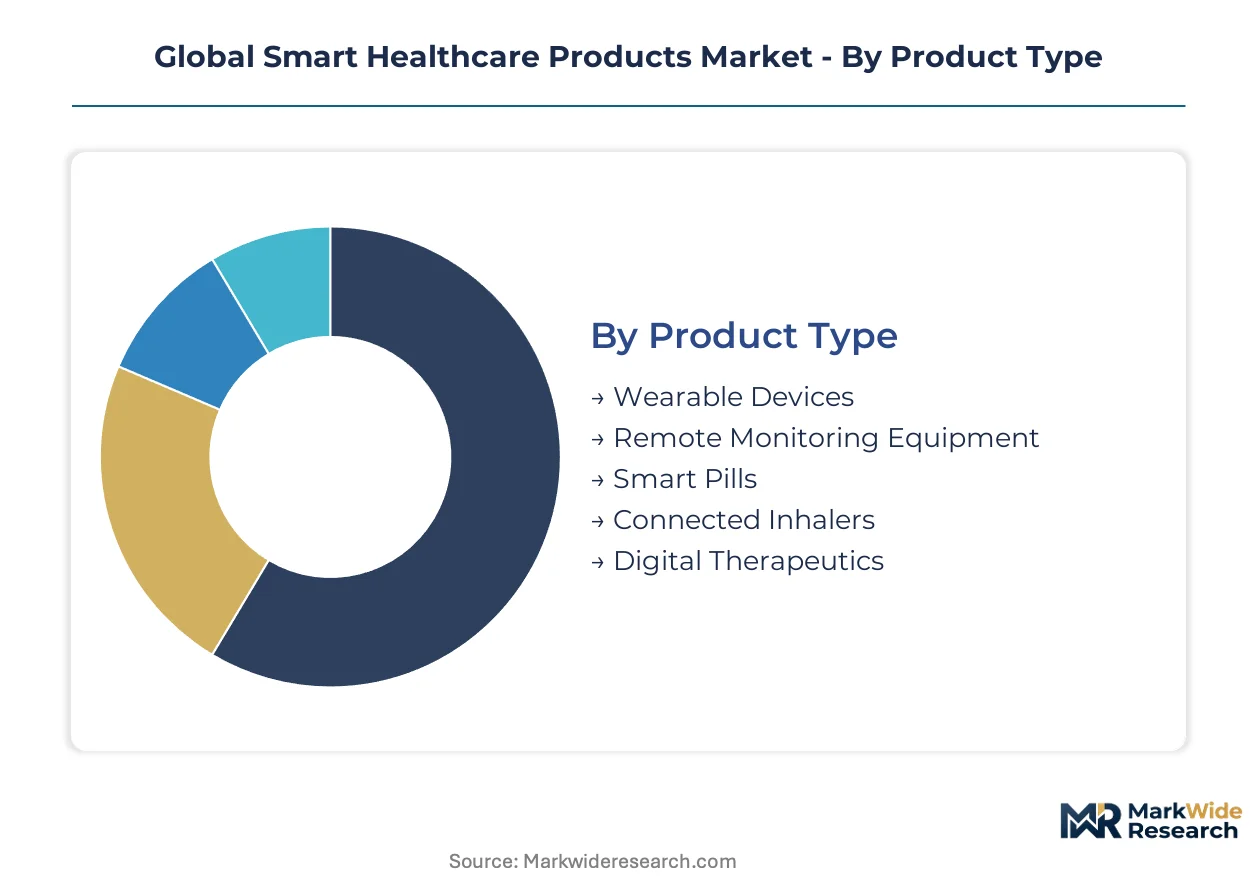
Smart healthcare products fragment across four critical dimensions that determine pricing power, regulatory pathway, and customer acquisition cost. Product type and application segmentation reveal where reimbursement codes align with technology capabilities, while end-user and technology splits expose integration friction points.
Product Type:
Margin pools concentrate in devices that secure recurring revenue through consumable sensors or subscription analytics rather than one-time hardware sales.
- Wearable Devices:Continuous glucose monitors and cardiac patches integrate biosensors with low-power wireless transmission. Hospital-at-home programs in the United States and Germany are expanding procurement of wrist-worn systems for hypertension surveillance, compressing reimbursement timelines as payers recognize emergency department cost avoidance.
- Remote Monitoring Equipment:Hub-and-spoke architectures connect bedside telemetry to cloud analytics platforms for post-acute surveillance. Japan's METI incentives for rural home-based care are opening procurement channels for fall-detection and medication adherence systems in prefectures with aging demographics.
- Smart Pills:Ingestible sensors with biocompatible coatings transmit adherence data to smartphone apps. FDA clearance pathways for digital biomarkers are accelerating clinical validation requirements.
- Connected Inhalers:Bluetooth-enabled respiratory devices track usage patterns and environmental triggers. Payer coverage for asthma and COPD management is expanding in Germany's DiGA framework.
- Digital Therapeutics:Prescription software interventions deliver cognitive behavioral therapy and diabetes management protocols. Germany's fast-track approval process creates first-mover advantages for mental health and metabolic disease platforms.
The dominant share belongs to Wearable Devices, while Digital Therapeutics is closing the gap fastest.
Application:
Volume concentration tracks reimbursement expansion, with CMS and Germany's Federal Joint Committee decisions reshaping addressable patient populations.
- Chronic Disease Management:Diabetes, heart failure, and COPD platforms dominate hospital procurement budgets. Continuous physiological streaming enables predictive intervention before acute decompensation.
- Preventive Care:Risk stratification algorithms identify pre-symptomatic populations for early intervention. United States health systems are piloting employer-sponsored metabolic health programs.
- Elderly Care:Fall detection, wandering alerts, and polypharmacy management address Japan's super-aging demographics. METI procurement incentives target rural prefectures with physician shortages.
- Fitness Monitoring:Consumer-grade wearables with clinical-grade sensors blur wellness and medical device boundaries. FDA enforcement discretion letters are clarifying regulatory jurisdiction.
- Medication Adherence:Smart packaging and digital reminders address non-compliance costs exceeding $300 billion annually in the United States alone. Payer ROI calculations favor high-cost specialty pharmaceuticals.
Chronic Disease Management commands the largest installed base, though Preventive Care applications are expanding most quickly as risk-bearing contracts proliferate.
End User:
Customer acquisition cost varies threefold across settings, with home care requiring direct-to-consumer marketing spend absent in hospital procurement.
- Hospitals:Integrated delivery networks negotiate enterprise contracts spanning multiple facilities. Procurement committees are unbundling hardware from analytics subscriptions, forcing vendors toward component pricing.
- Ambulatory Care Centers:Specialty clinics for cardiology and endocrinology represent high-volume deployment points for condition-specific monitoring. Reimbursement codes for remote physiological monitoring are stabilizing revenue models.
- Home Care Settings:Patients and family caregivers operate devices with minimal clinical supervision. User interface design and technical support infrastructure determine retention rates.
- Diagnostic Laboratories:Reference labs integrate connected devices with automated result reporting to ordering physicians. ISO 13485 certification requirements are gating supplier qualification.
- Rehabilitation Centers:Post-surgical and stroke recovery protocols incorporate wearable motion tracking for functional outcome measurement. Payer bundled payment contracts create shared savings incentives.
Hospitals retain the deepest purchasing power, yet Home Care Settings are gaining share fastest as hospital-at-home reimbursement frameworks mature.
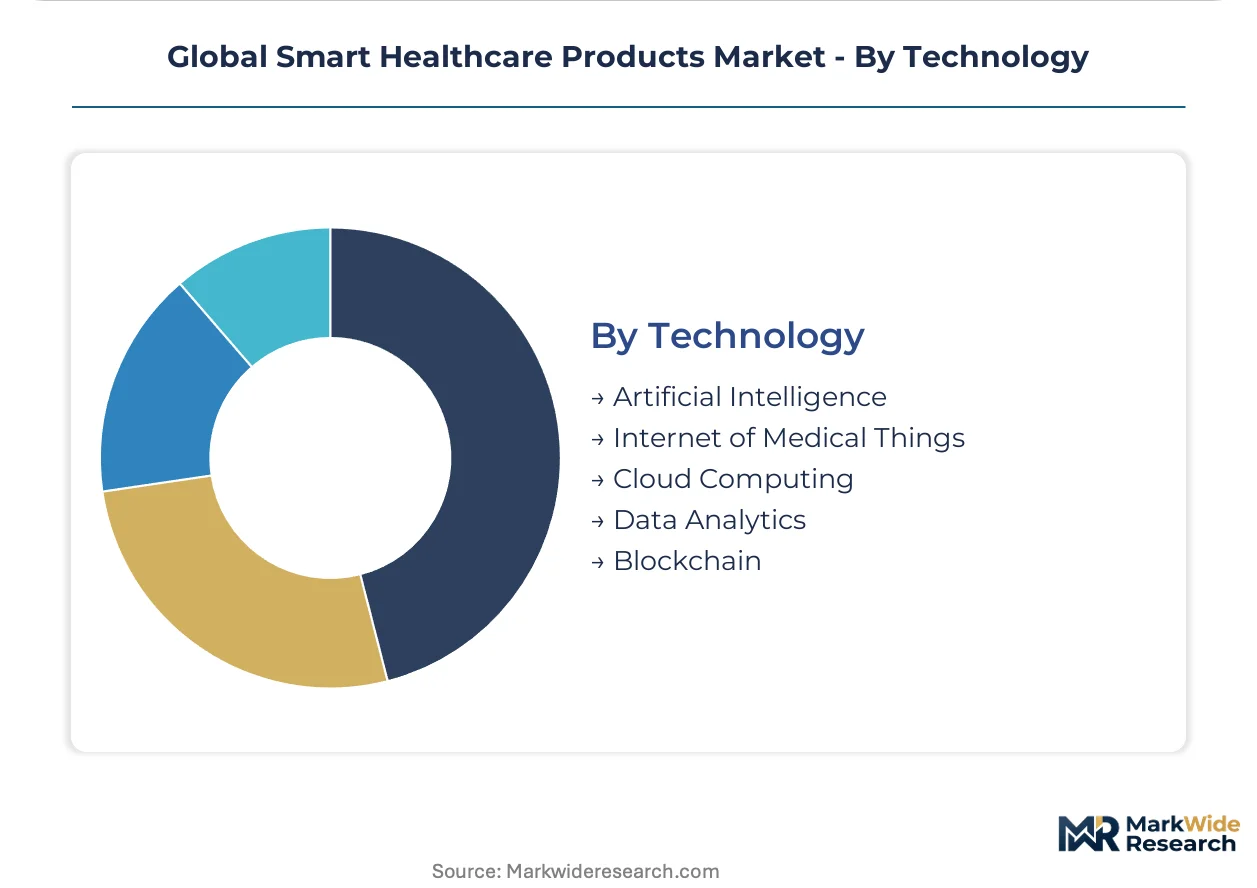
Technology:
Proprietary training datasets and cleared algorithms determine margin capture, with first-movers in FDA-authorized AI diagnostics sustaining pricing premiums.
- Artificial Intelligence:Machine learning models for arrhythmia detection, diabetic retinopathy screening, and sepsis prediction require patient cohorts exceeding 10,000 subjects for regulatory statistical power. The EU AI Act's high-risk classification mandates bias mitigation documentation and post-market monitoring protocols.
- Internet of Medical Things:NB-IoT and LoRa protocol deployments enable continuous streaming without Wi-Fi infrastructure dependency. Taiwanese and South Korean foundry concentration exposes device makers to single-source vulnerability.
- Cloud Computing:Health systems in the United Kingdom and Australia are negotiating direct infrastructure contracts independent of device OEMs. Data residency requirements are fragmenting vendor architectures across jurisdictions.
- Data Analytics:Predictive risk scores integrate multiple physiological streams for clinical decision support. Proprietary electronic health record architectures at major United States hospital chains block seamless data flow without expensive middleware.
- Blockchain:Distributed ledger applications for pharmaceutical supply chain integrity and clinical trial data provenance remain pilot-stage. Regulatory acceptance of immutable audit trails is clarifying across FDA and EMA guidance documents.
Artificial Intelligence anchors current R&D investment, while Internet of Medical Things infrastructure deployment is climbing the fastest as low-power wide-area networks achieve hospital system scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees and national reimbursement authorities concentrate demand in five countries where regulatory frameworks for connected medical devices have achieved operational maturity. Each jurisdiction presents distinct compliance pathways and infrastructure readiness levels that shape vendor market entry sequencing.
United States
CMS coverage decisions for remote patient monitoring have established sustainable payment pathways for connected chronic disease management devices. FDA premarket authorization pathways for AI-enabled diagnostics compress time-to-market for algorithm developers. The Greater Boston and San Francisco Bay Area clusters host the highest density of digital health venture funding and regulatory consulting expertise.
Germany
The Federal Joint Committee's reimbursement rulings for hospital-at-home programs are expanding procurement of remote monitoring infrastructure. The DiGA fast-track approval process creates first-mover advantages for prescription software interventions targeting diabetes and mental health. Berlin and Munich anchor European regulatory dossier preparation and notified body relationships.
Japan
METI incentives for home-based care technologies open procurement channels for fall-detection and medication adherence systems in rural prefectures. PMDA regulatory dossiers for implantable smart devices require extensive clinical evidence generation. The Kanto region around Tokyo concentrates hospital system headquarters and medical device distribution networks.
China
NMPA clearance pathways for AI-assisted diagnostic platforms are accelerating as the regulator publishes standardized review guidelines. The Yangtze River Delta and Pearl River Delta regions concentrate connected device manufacturing and cloud infrastructure deployment. Domestic champions are securing market share in low-power wireless monitoring segments.
United Kingdom
NHS procurement frameworks for digital therapeutics are expanding reimbursement codes for software-based interventions. Health systems negotiate direct cloud infrastructure contracts independent of device OEMs. London and the Southeast concentrate health technology assessment expertise and venture capital allocation for clinical validation studies.
Global Smart Healthcare Products Market Competitive Landscape
Player mix skews toward diversified health technology conglomerates with entrenched hospital procurement relationships and specialized pure-plays with cleared AI algorithms. The structure exhibits tiered concentration where three to five integrated device-data platforms capture disproportionate margin in high-acuity segments. Strategic archetypes include verticalized sensor-to-cloud operators, modular hardware vendors seeking analytics partnerships, and algorithm developers pursuing OEM licensing. Dominant competitive moves encompass M&A for regulatory dossier accumulation and strategic partnerships to bypass legacy EHR interoperability barriers.
Among diversified health technology conglomerates, Abbott Laboratories, Koninklijke Philips N.V., and Medtronic plc exemplify archetypes with deep regulatory dossiers across multiple jurisdictions. Abbott represents verticalized sensor-to-cloud integration through captive fabrication and analytics platforms. Philips occupies a position anchored in European hospital procurement through diagnostic imaging relationships. Medtronic sits within the implantable smart device segment where regulatory barriers protect incumbent positions. These three entities collectively illustrate how scale and regulatory sophistication create defensive moats against specialized challengers.
| Leading Market Players |
|---|
| Abbott Laboratories |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Medtronic plc |
| Siemens Healthineers AG |
| Apple Inc. |
| Samsung |
| Dexcom Inc. |
| Allscripts Healthcare |
| Others |
Supply & Pricing Matrix
Foundry-scale economies in Taiwanese and South Korean semiconductor fabrication create dual concentration effects: supply bottlenecks at advanced biosensor nodes simultaneously elevate input costs and compress margin floors for device OEMs unable to secure preferred allocation.
Pricing Analysis
Cost-plus contracts with Taiwanese foundry indexation dominate component procurement, locking device manufacturers into pass-through volatility for sensor chips. Pricing stratifies across FDA-cleared premium tiers, CE-marked standard offerings, and economy grades lacking clinical certification. Cost compression in the economy tier intensifies because Chinese domestic champions flood low-power wireless segments with subsidized alternatives. Hospital procurement committees exhibit lowest price sensitivity given bundled payment incentives, while direct-to-consumer home care channels face acute margin pressure.
Supply Chain Analysis
Just-in-time inventory strategies prevail among US and German hospital systems, though strategic stockpiling of semiconductor components accelerated following foundry allocation crises. Supply draws from Taiwan, South Korea, and China for advanced biosensors, with German and Swiss precision optics feeding diagnostic imaging integration. Single-source vulnerability concentrates in 28nm and below fabrication nodes. Distribution runs through regional medical device distributors with ISO 13485 certification, bypassing general electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 13485 auditor scarcity and FDA premarket submission backlogs create structural bottlenecks where regulatory navigation capabilities determine competitive survival more than raw R&D spend.
For Market Incumbents: Shield platform stickiness by deepening captive sensor fabrication partnerships with Taiwanese foundries and accelerating cloud analytics subscription attach rates. The threat of modular hardware vendors unbundling device-data contracts demands preemptive bundling of cybersecurity validation services. ISO 13485 certification investment represents the priority defensive lever against auditor backlog delays. For New Entrants and Emerging Players: Post-acute monitoring service gaps in Japan's rural prefectures offer white-space penetration where METI incentives offset thin hardware margins. Germany's DiGA fast-track pathway for prescription software presents the most penetrable regulatory entry point. A direct-to-clinic go-to-market angle bypassing hospital procurement committee complexity accelerates initial traction. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among verticalized sensor-to-cloud operators with cleared AI algorithms and established GPO contracts. Long-term viability across the analysis window favors targets with proprietary training datasets and multi-jurisdiction regulatory dossiers. Watch FDA premarket authorization timeline compression as the inflection signal for algorithm developer valuation resets.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Acceleration | Compressed 510(k) pathways for AI-enabled diagnostics reduce time-to-revenue for algorithm developers. |
| CE Marking Pathway Investment | EU AI Act conformity assessments create regulatory moats against undercapitalized software competitors. |
| Hospital System Partnership | Enterprise contracts with integrated delivery networks lock in multi-year remote monitoring deployment. |
| Software Companion Development | Digital therapeutics bundling with hardware devices captures DiGA reimbursement codes in Germany. |
| Reimbursement Strategy Execution | CMS coverage decisions for remote patient monitoring determine commercial viability for home-based platforms. |
Research Methodology
Desk research of FDA 510(k) filings, EMA MDR submissions, and hospital procurement databases preceded structured interviews with biomedical engineers, GPO contracts managers, and regulatory affairs leads at connected device manufacturers. Primary fieldwork with hospital purchasing committees and payer policy specialists cross-validated secondary data on reimbursement expansion timelines. Bottom-up device shipment modeling and top-down healthcare IT spend analysis were triangulated against CMS claims data.
Variance decomposition across product type, application, end-user setting, and technology stack shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro healthcare expenditure trends. Forecast inputs incorporated ISO 13485 certification pipeline delays and EU AI Act implementation timelines.
Underlying assumptions cover sustained CMS reimbursement for remote patient monitoring and stable Taiwanese foundry allocation, with deviation risk concentrated in semiconductor supply disruptions and FDA premarket review timeline volatility. Revision becomes warranted when hospital-at-home reimbursement thresholds cross statutory adjustment triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
One-Step ELISA Market
Diagnostic and Therapeutic Devices
Localized Temperature Therapy Products Market
Diagnostic and Therapeutic Devices
Smart Infusion System Market
Diagnostic and Therapeutic Devices
Breast Lesion Localization Market
Diagnostic and Therapeutic Devices
Nanobiosensors in Healthcare Market
Diagnostic and Therapeutic Devices
Global Smart Inhaler Technology Market
Diagnostic and Therapeutic Devices
Smart Drug Delivery Systems Market
Diagnostic and Therapeutic Devices
Disposable Negative Pressure Wound Therapy Devices Market
Diagnostic and Therapeutic Devices
Heat Therapy Lamp Market
Diagnostic and Therapeutic Devices
US Cancer Contrast Media Market
Diagnostic and Therapeutic Devices
Microneedle Drug Delivery Systems Market
Diagnostic and Therapeutic Devices
Dermatology Diagnostic Equipment Market
Diagnostic and Therapeutic Devices
Anti Neurofilament L Antibody Market
Diagnostic and Therapeutic Devices
Venous Diseases Treatment Market
Diagnostic and Therapeutic Devices
Sustained Acoustic Medicine Market
Diagnostic and Therapeutic Devices
Therapeutic Robots Market