
 Anti Neurofilament L Antibody Market | 2026-2036
Anti Neurofilament L Antibody Market Size, Share, and Industry Trends Forecast 2026-2036
Anti Neurofilament L Antibody Market Outlook
Contract research service revenue is reshaping margin distribution across the Anti Neurofilament L Antibody value chain. Merck KGaA leverages its hybridoma production infrastructure to dominate European supply channels for research-grade antibodies. BioLegend anchors its position through recombinant antibody engineering capabilities that reduce lot-to-lot variability. Cell Signaling Technology specializes in phospho-specific and modified neurofilament antibody variants for biomarker research.
Anti neurofilament L antibodies are immunoglobulin reagents that bind the light subunit of neurofilament triplet proteins, typically produced through hybridoma fusion or recombinant expression in mammalian cell systems, with specificity verified by Western blotting and immunohistochemistry against denatured and native antigen conformations. These reagents serve as critical tools for quantifying axonal injury in cerebrospinal fluid and tissue specimens across neurology research and clinical laboratory settings. Monoclonal antibodies capture the largest share of product-type revenue due to their defined epitope specificity and regulatory acceptance in diagnostic workflows, while recombinant antibodies represent the fastest-expanding category as manufacturers seek to eliminate animal-derived components and secure batch consistency. Among applications, neurodegenerative disorders command the dominant position because of intensifying pharmaceutical investment in multiple sclerosis and amyotrophic lateral sclerosis biomarker programs, whereas biomarker discovery attracts accelerating R&D expenditure as liquid biopsy platforms expand into neurological indications.
FDA biomarker qualification programs and EMA's ICH Q5D guidelines on cell substrate sourcing shape antibody development timelines and documentation burdens for manufacturers seeking diagnostic market access. ISO 13485 quality management requirements and CLSI analytical performance standards further constrain suppliers serving clinical laboratories, filtering out uncertified reagent providers. Stakeholders must monitor evolving regulatory distinctions between research-use-only and in-vitro diagnostic classifications, as reclassification events could abruptly reshape addressable market boundaries and compliance investment requirements.
Market Dynamics
FDA biomarker qualification pathways and EMA ICH Q5D guidelines are compressing development timelines while forcing documentation investments that filter uncertified suppliers from clinical-grade antibody markets. This regulatory tightening concentrates procurement among vertically integrated manufacturers with ISO 13485-certified production infrastructure.
Growth Catalysts
- Biomarker qualification programs:FDA's formal pathway for neurofilament L assay validation accelerates diagnostic adoption in multiple sclerosis monitoring protocols.
- Liquid biopsy platform expansion:Cerebrospinal fluid testing infrastructure in academic medical centers drives bulk reagent procurement for neurodegenerative panels.
- Germany:Contract research organizations in Munich and Heidelberg anchor European demand for certified research-grade antibodies.
Market Restraints
- Hybridoma cell line sourcing:ICH Q5D documentation requirements for animal-derived substrates extend development timelines by 12-18 months.
- Lot-to-lot variability:Traditional polyclonal production methods create analytical performance drift unacceptable to CLSI-compliant clinical laboratories.
- Recombinant expression costs:Mammalian cell culture systems for antibody production carry 3-4x cost premiums versus bacterial platforms.
Strategic Opportunities
- India:CDSCO's expanding in-vitro diagnostic registration framework opens clinical laboratory markets previously restricted to research-use-only classifications.
- Phospho-specific variants:Modified neurofilament antibodies for biomarker discovery address unmet needs in traumatic brain injury stratification.
- Direct-to-laboratory distribution:E-commerce platforms bypass traditional distributor markups for mid-volume academic purchasers.
Industry Challenges
- ISO 13485 certification timelines:Quality management system implementation requires 18-24 months before clinical reagent market entry.
- Western blot validation protocols:Dual confirmation against denatured and native antigen conformations consumes specialized technical labor pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti Neurofilament L Antibody Market |
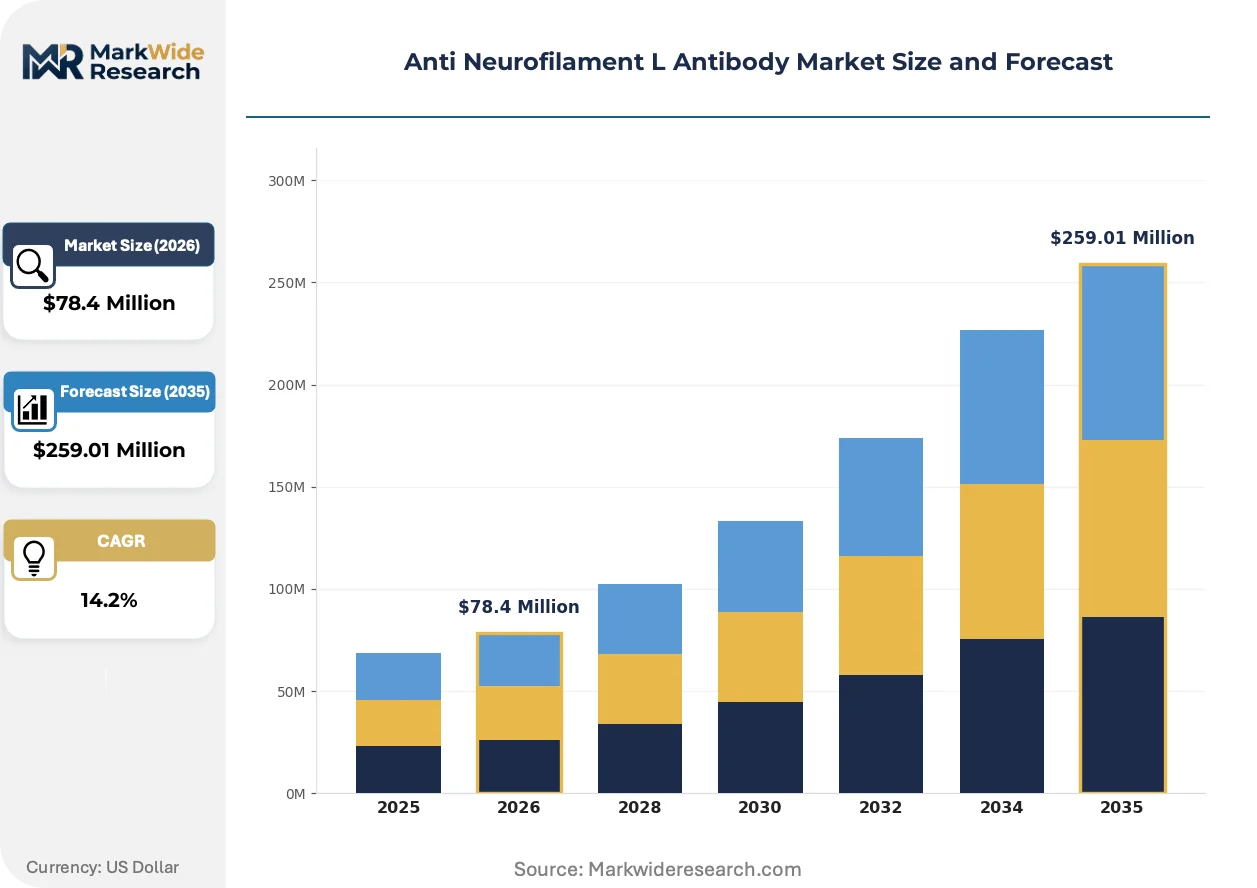
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $259.01 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Polyclonal Antibodies, Recombinant Antibodies, Hybridoma Antibodies End User: Hospitals, Research Laboratories, Diagnostic Centers, Academic Institutions Technology: ELISA, Western Blotting, Immunohistochemistry, Flow Cytometry Application: Neurodegenerative Disorders, Biomarker Discovery, Cancer Research, Clinical Diagnostics |
| Companies Covered | Merck KGaA, BioLegend, Cell Signaling Technology, Rockland Immunochemicals, Bio-Rad Laboratories, EnCor Biotechnology, Boster Biological Technology, Proteintech Group, Santa Cruz Biotechnology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti Neurofilament L Antibody Market Strategic Shifts
Recombinant antibody engineering is displacing hybridoma production as the dominant manufacturing paradigm, with manufacturers investing in animal-free expression systems to secure regulatory acceptance and batch reproducibility. This technological pivot reshapes competitive capabilities across the value chain.
Single B-cell cloning technology is digitizing epitope mapping workflows by enabling direct isolation of antibody sequences from immunized donors without hybridoma fusion bottlenecks. Clinical diagnostic manufacturers in the United States adopt these platforms to compress development cycles for neurodegenerative disease panels. The technology is digitizing quality control documentation by generating sequence-level traceability required for FDA biomarker qualification submissions.
EMA's MDR implementation tightens performance evaluation requirements for antibody-based in-vitro diagnostic devices marketed in Europe. Manufacturers must now generate clinical evidence packages demonstrating analytical validity for neurofilament L quantification assays. German notified bodies interpret these provisions most stringently, forcing suppliers to redesign labeling and instructions-for-use documentation before CE marking renewal.
Research-use-only reagent buyers increasingly demand certificate of analysis packages matching clinical-grade specifications despite lower price points. Academic core facilities in Boston and San Francisco now require lot-specific Western blot validation data before purchase authorization. This specification inflation compresses margins for suppliers serving the preclinical research segment while creating qualification backlogs at certified manufacturing sites.
Anti Neurofilament L Antibody Market Segmentation
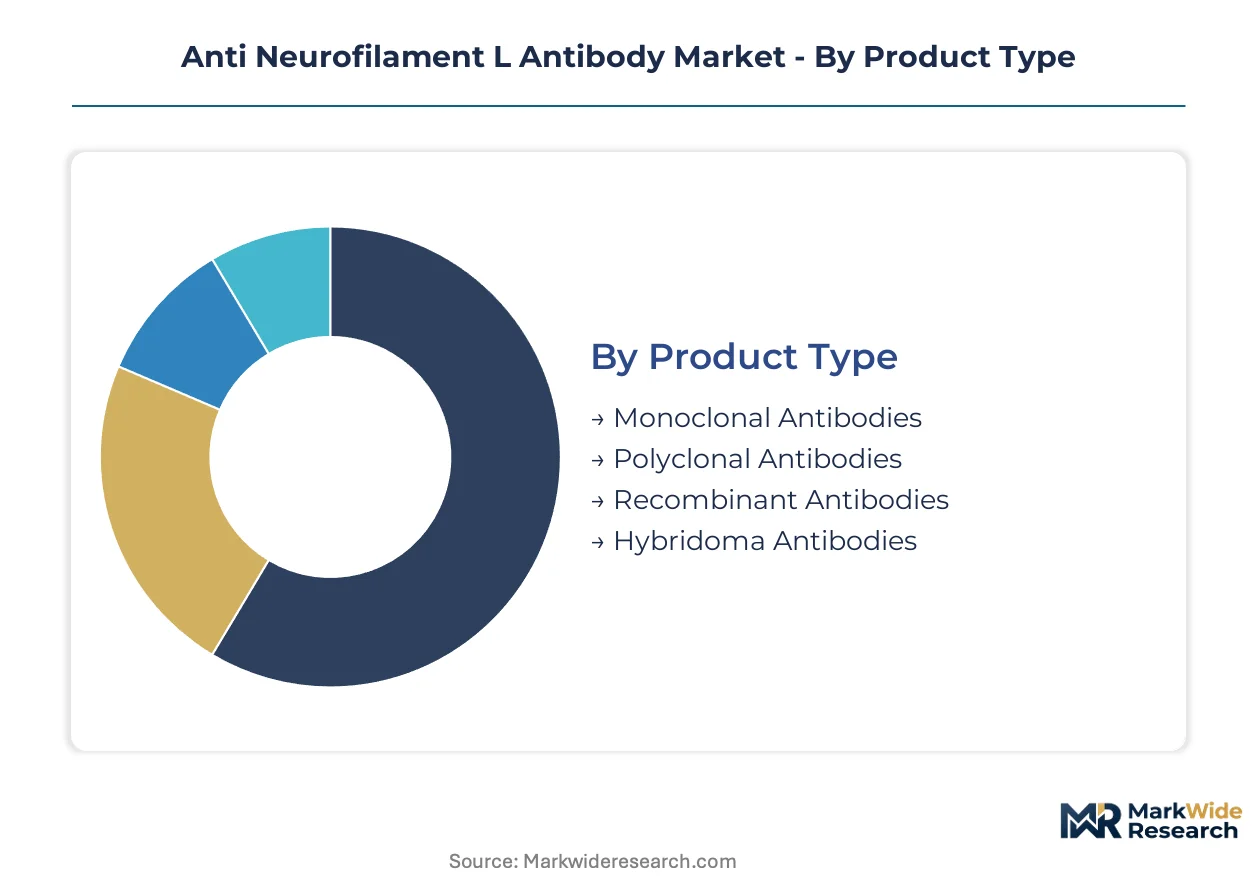
Segmentation in the Anti Neurofilament L Antibody Market reveals how regulatory pathways, manufacturing technologies, and end-user requirements fragment procurement patterns. Each dimension carries distinct compliance burdens and margin structures that reshape supplier positioning across clinical and research channels.
Product Type:
Mature hybridoma-derived formats dominate current revenue, while recombinant platforms are accelerating fastest as manufacturers eliminate animal-derived substrates.
- Monoclonal Antibodies:Defined epitope specificity from single B-cell clones enables reproducible diagnostic workflows. Demand concentrates in United States academic medical centers running FDA-aligned biomarker qualification studies for multiple sclerosis monitoring protocols.
- Recombinant Antibodies:Sequence-defined immunoglobulins produced in mammalian cell culture eliminate lot-to-lot variability. German contract research organizations in Munich and Heidelberg drive procurement for certified research-grade reagents requiring ISO 13485 documentation.
- Polyclonal Antibodies:Multi-epitope sera from immunized hosts retain utility in exploratory research settings where absolute specificity is secondary.
- Hybridoma Antibodies:Traditional fusion-based production faces ICH Q5D documentation delays that extend development timelines.
Monoclonal antibodies retain volume leadership; recombinant antibodies hold the steepest expansion curve.
End User:
Customer type determines pricing tolerance and certification requirements, with clinical-grade buyers commanding premium specifications.
- Research Laboratories:Preclinical investigators require certificate of analysis packages matching clinical-grade specifications despite lower price points. Boston and San Francisco academic core facilities now mandate lot-specific Western blot validation data.
- Hospitals:Clinical laboratories in tertiary care centers drive bulk procurement for neurodegenerative disease panels integrated into electronic medical record systems.
- Diagnostic Centers:Specialized testing facilities prioritize CLSI-compliant analytical performance standards for cerebrospinal fluid neurofilament quantification.
- Academic Institutions:University core facilities balance budget constraints against evolving data quality requirements for publication-grade results.
Research laboratories dominate transaction volume; hospitals command the highest per-unit pricing tier.
Technology:
Detection platform selection hinges on sample throughput, multiplexing requirements, and regulatory submission pathways.
- ELISA:Enzyme-linked immunosorbent assays deliver quantitative neurofilament L quantification in cerebrospinal fluid with established FDA biomarker qualification precedents.
- Western Blotting:Denatured protein separation remains mandatory for antibody specificity verification against both native and denatured antigen conformations.
- Immunohistochemistry:Tissue-based neurofilament visualization supports amyotrophic lateral sclerosis pathology studies in academic medical centers.
- Flow Cytometry:Single-cell resolution platforms enable rare neural cell population analysis in biomarker discovery workflows.
ELISA captures the largest installed base; Western blotting maintains irreplaceable validation utility.
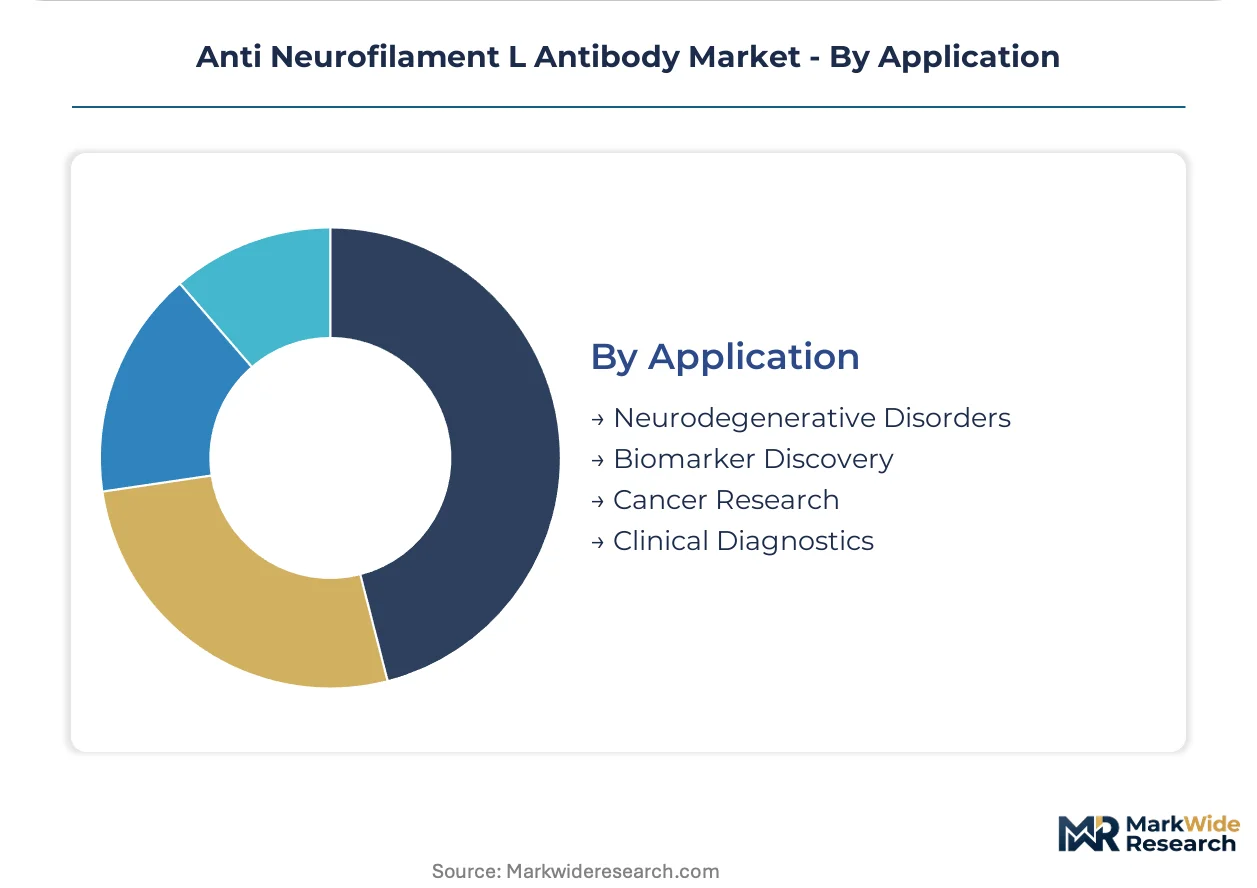
Application:
Clinical indication and research objective dictate antibody performance specifications and regulatory classification.
- Neurodegenerative Disorders:Multiple sclerosis and amyotrophic lateral sclerosis monitoring protocols drive pharmaceutical investment in validated assay development. United States and German academic centers anchor demand for diagnostic-grade reagents.
- Biomarker Discovery:Liquid biopsy platform expansion into neurological indications accelerates R&D expenditure for phospho-specific and modified neurofilament antibody variants.
- Cancer Research:Paraneoplastic neurological syndrome investigation creates niche demand for neurofilament detection in oncology settings.
- Clinical Diagnostics:In-vitro diagnostic classification requirements filter uncertified suppliers from addressable market boundaries.
Neurodegenerative disorders retain volume leadership; biomarker discovery holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States demonstrate the lowest price elasticity, absorbing premium pricing for ISO 13485-certified reagents, while academic purchasers in India and Brazil remain highly sensitive to unit costs despite demanding equivalent validation documentation.
United States
FDA biomarker qualification programs for multiple sclerosis monitoring protocols drive procurement from academic medical centers in Boston and San Francisco. Clinical laboratories at Massachusetts General Hospital and UCSF Medical Center mandate lot-specific Western blot validation data for all antibody purchases. The NIH's Accelerating Medicines Partnership for neurodegenerative diseases channels federal funding toward standardized assay development.
Germany
Contract research organizations in Munich and Heidelberg anchor European demand for certified research-grade antibodies requiring EMA ICH Q5D documentation. German notified bodies interpret MDR provisions most stringently, forcing suppliers to redesign labeling before CE marking renewal. Bavaria's biotechnology cluster concentrates hybridoma production infrastructure serving diagnostic manufacturers across the Rhine-Main region.
India
CDSCO's expanding in-vitro diagnostic registration framework opens clinical laboratory markets previously restricted to research-use-only classifications. Research institutes in Bangalore and Hyderabad drive procurement volume for preclinical neurodegenerative studies. The Department of Biotechnology's National Biopharma Mission subsidizes domestic antibody production capabilities to reduce import dependence.
China
NMPA's medical device classification reforms accelerate clinical-grade antibody registration for cerebrospinal fluid diagnostic panels. Shanghai and Suzhou biotech parks concentrate recombinant expression infrastructure serving domestic pharmaceutical companies. The 14th Five-Year Plan for Bioeconomy Development prioritizes biomarker assay localization to replace Western reagent imports.
United Kingdom
Academic core facilities at Oxford and Cambridge require certificate of analysis packages matching clinical-grade specifications despite research budgets. The MHRA's post-Brexit regulatory autonomy enables streamlined biomarker validation pathways for neurodegenerative disease consortia. London's Francis Crick Institute coordinates multi-site antibody procurement for standardized neuroscience research protocols.
Anti Neurofilament L Antibody Market Competitive Environment
Capability concentration sits with vertically integrated manufacturers possessing ISO 13485-certified hybridoma infrastructure; scale advantage sits with recombinant antibody engineering specialists serving high-volume research channels. The market structures around three tiers: multinational life science conglomerates with diagnostic-grade production, mid-cap recombinant specialists, and regional polyclonal suppliers. Dominant competitive moves include backward integration into mammalian cell culture capacity and technology licensing for single B-cell cloning platforms.
Within the multinational tier, Merck KGaA represents European supply channel dominance through captive hybridoma production, while BioLegend exemplifies recombinant engineering capabilities that reduce lot-to-lot variability for biomarker research. Cell Signaling Technology anchors the phospho-specific specialization vector, occupying a position in modified neurofilament antibody variants for traumatic brain injury stratification.
| Leading Market Players |
|---|
| Merck KGaA |
| BioLegend |
| Cell Signaling Technology |
| Rockland Immunochemicals |
| Bio-Rad Laboratories |
| EnCor Biotechnology |
| Boster Biological Technology |
| Proteintech Group |
| Santa Cruz Biotechnology |
| Others |
Value Chain & Pricing Dynamics
ICH Q5D documentation requirements for animal-derived hybridoma substrates create a regulatory chokepoint that determines both pricing tier spreads and supply chain shape. This compliance burden bifurcates procurement between ISO 13485-certified clinical-grade suppliers commanding premium positioning and uncertified research-grade providers competing on unit cost.
Pricing Analysis
Certificate of analysis packages and extended validation contracts drive lifetime value for clinical-grade antibody suppliers. Three-tier pricing structure across premium diagnostic-grade, standard research-certified, and economy exploratory tiers separates procurement budgets at academic medical centers, contract research organizations, and exploratory laboratories respectively. Cost compression in the economy tier intensifies because research-use-only buyers now demand clinical-matching documentation without price premiums. Contract research organizations in Germany demonstrate the lowest price sensitivity, while academic core facilities in India and Brazil absorb cost pressure most acutely.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for mammalian cell culture media and recombinant expression vectors. Manufacturing concentration rests on Germany, the United States, and China, with Bavaria's biotechnology cluster and Shanghai's biotech parks anchoring hybridoma and recombinant production respectively. Raw material dependencies draw from fetal bovine serum suppliers, protein-free chemically defined media formulators, and single-use bioreactor component manufacturers. Distribution runs through direct-to-laboratory e-commerce platforms for mid-volume academic purchasers and specialized distributor networks for clinical diagnostic manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regulatory classification boundaries creates niche opportunities as FDA biomarker qualification programs and EMA MDR implementation force tiered compliance investments that smaller suppliers cannot absorb.
For Market Incumbents: Insulate diagnostic-grade revenue streams by deepening captive hybridoma production capacity in ISO 13485-certified facilities and securing exclusive distributor arrangements with Massachusetts General Hospital and UCSF Medical Center procurement committees. The recombinant antibody engineering threat from BioLegend and emerging sequence-defined specialists demands accelerated single B-cell cloning platform licensing to compress development cycles. For New Entrants and Emerging Players: India's CDSCO-expanding in-vitro diagnostic registration framework offers the most penetrable geographic entry point, with Bangalore and Hyderabad research institutes driving volume for preclinical neurodegenerative studies. Phospho-specific neurofilament variants for traumatic brain injury stratification represent the least contested application white-space. A direct-to-laboratory digital distribution model bypasses traditional distributor markups and captures mid-volume academic purchasers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors recombinant engineering specialists with mammalian cell culture capacity and existing ISO 13485 documentation. Long-term viability over the next decade hinges on biomarker qualification program alignment rather than research-grade volume leadership. The signal to watch is FDA neurofilament L assay validation decisions for multiple sclerosis monitoring protocols, which would abruptly reclassify addressable market boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Pathway | Quality management system implementation opens clinical diagnostic reagent markets previously restricted to research-use-only classifications. |
| Single B-Cell Cloning Platform Licensing | Direct antibody sequence isolation from immunized donors compresses development cycles for FDA biomarker qualification submissions. |
| Direct-to-Laboratory E-Commerce Launch | Digital distribution bypasses traditional distributor markups and captures mid-volume academic purchasers in Boston and San Francisco. |
| Phospho-Specific Antibody Pipeline Expansion | Modified neurofilament variants address unmet needs in traumatic brain injury stratification and biomarker discovery workflows. |
| India CDSCO Registration Investment | Regulatory pathway expansion opens clinical laboratory markets previously restricted to research-use-only antibody classifications. |
Study Parameters
Initial hypotheses were tested against primary input from antibody manufacturing executives, clinical laboratory directors at academic medical centers, contract research organization procurement leads, and regulatory affairs specialists at diagnostic manufacturers, and refined through secondary validation against FDA biomarker qualification program documentation, EMA ICH Q5D guideline publications, CDSCO in-vitro diagnostic registration frameworks, and ISO 13485 certification body records. Bottom-up triangulation across product-type demand curves and top-down validation against end-user expenditure patterns anchored volume and value estimates.
Demand-supply-balance framing structured the analytical approach across the analysis window, with segmentation dimensions spanning monoclonal versus recombinant versus polyclonal product types, research laboratory versus hospital versus diagnostic center end users, and neurodegenerative disorder versus biomarker discovery applications. CAGRs were derived from fitted growth curves incorporating pharmaceutical R&D expenditure trends, liquid biopsy platform expansion rates, and regulatory reclassification probability assessments.
Practitioners should monitor FDA neurofilament L biomarker qualification decisions, EMA MDR enforcement stringency variations across German notified bodies, and CDSCO registration framework expansion velocity for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Leukocytapheresis Device Market
Diagnostic and Therapeutic Devices
Pressure Ulcer Relief Products Market
Diagnostic and Therapeutic Devices
Smart Drug Delivery Systems Market
Diagnostic and Therapeutic Devices
Global Therapeutic Plasma Exchange Market
Diagnostic and Therapeutic Devices
Breast Lesion Localization Market
Diagnostic and Therapeutic Devices
Magnetic Therapy Devices Market
Diagnostic and Therapeutic Devices
Disposable Negative Pressure Wound Therapy Devices Market
Diagnostic and Therapeutic Devices
Global Exosome Diagnostic and Therapeutic Market
Diagnostic and Therapeutic Devices
Cruciate Ligament Diagnosis Treatment Market
Diagnostic and Therapeutic Devices
Smart Inhalers Market
Diagnostic and Therapeutic Devices
Global Smart Healthcare Products Market
Diagnostic and Therapeutic Devices
Dental Surgical and Diagnostic Devices Market
Diagnostic and Therapeutic Devices
Localized Temperature Therapy Products Market
Diagnostic and Therapeutic Devices
Venous Diseases Treatment Market
Diagnostic and Therapeutic Devices
Heat Therapy Lamp Market
Diagnostic and Therapeutic Devices
Robotic Surgery System Haptic Feedback Test Platforms Market