
 Global Cold Plasma in Healthcare Market | 2026-2036
Global Cold Plasma in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cold Plasma in Healthcare Market Foresight
Germany is rewriting European cold plasma adoption through terraplasma medical GmbH and CINOGY System GmbH. Terraplasma medical GmbH leverages Munich-based manufacturing to dominate chronic wound protocols across German university hospitals. CINOGY System GmbH anchors its position through CE-marked plasma jet systems distributed to oncology centers in Düsseldorf and Hamburg. Relyon Plasma GmbH competes via specialized compact generators designed for ambulatory dermatology clinics.
Cold plasma in healthcare denotes partially ionized gas generated at near-ambient temperatures, typically operating at 20-40°C with electron densities of 10^15-10^18 m^-3, deployed for tissue disinfection, selective cell ablation, and accelerated wound closure without thermal necrosis. Dielectric Barrier Discharge systems occupy the largest installed base due to electrode reliability and uniform plasma distribution across irregular wound surfaces. Plasma Jet configurations represent the fastest-expanding segment, driven by precision targeting in dental and dermatology procedures where tissue selectivity commands premium pricing. Cancer Therapy applications remain concentrated in research laboratories awaiting Phase III validation, while Sterilization deployments in hospitals generate the most predictable recurring revenue streams.
FDA breakthrough device designations shape United States market access timelines, compressing premarket review for wound healing and oncology applications. EU MDR compliance requirements and EMA clinical evidence standards determine which plasma systems achieve commercial distribution across German, French, and Italian healthcare networks. Stakeholders must monitor reimbursement decisions by CMS in the United States and Germany's G-BA, as these determinations will separate commercially viable plasma therapies from research-stage technologies.
Market Dynamics
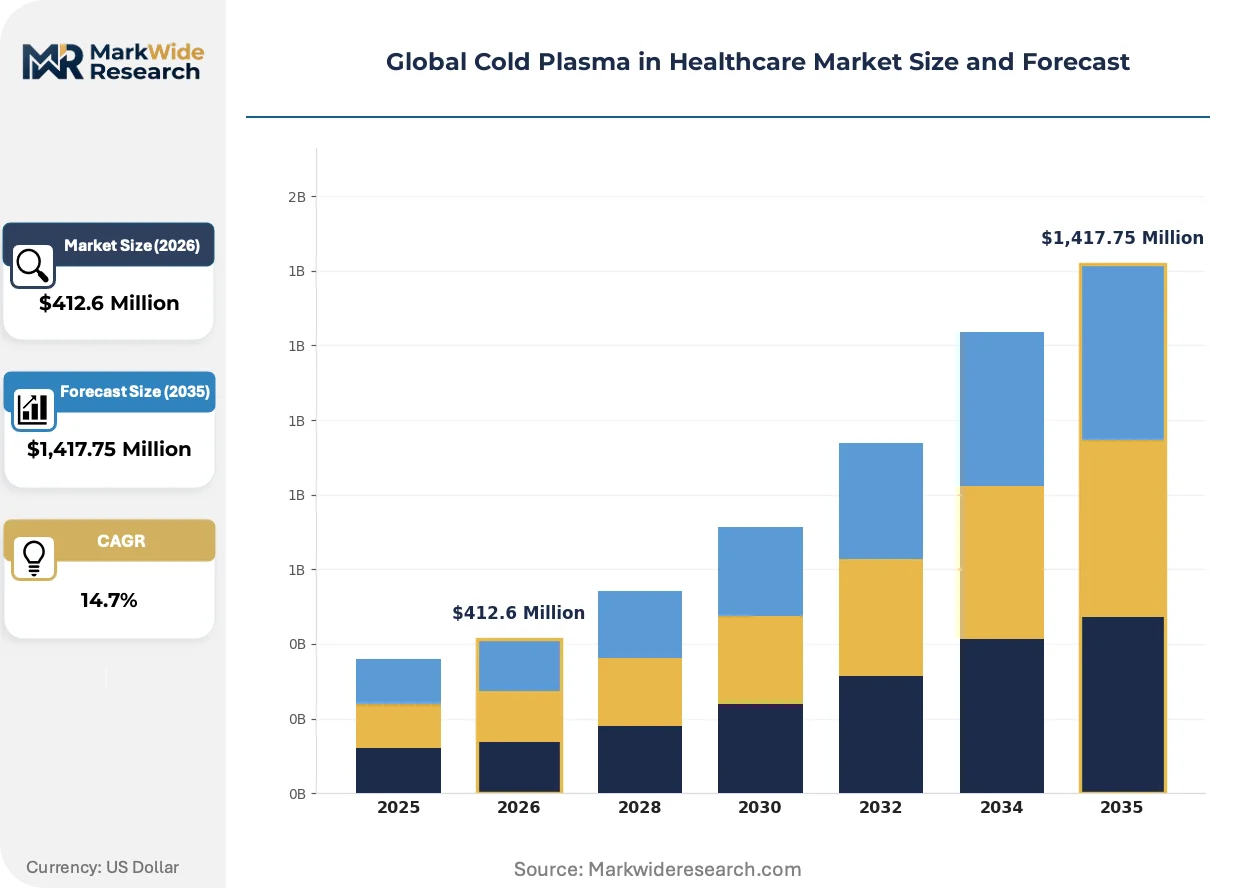
Dielectric Barrier Discharge systems dominate installed capacity, yet Plasma Jet configurations are compressing clinical validation timelines through precision-targeted oncology and dental protocols that command premium reimbursement rates.
Growth Catalysts
- FDA Breakthrough Device Designation:The FDA pathway accelerates premarket review for wound healing applications, compressing timelines from 18 months to under 12 months for qualifying plasma systems.
- Chronic Wound Burden:German university hospitals are expanding cold plasma protocols for diabetic foot ulcers, driving repeat purchase cycles for consumable electrode assemblies.
- EU MDR Compliance:The Medical Device Regulation framework creates competitive moats for CE-marked systems, filtering out non-compliant competitors from European distribution networks.
Market Restraints
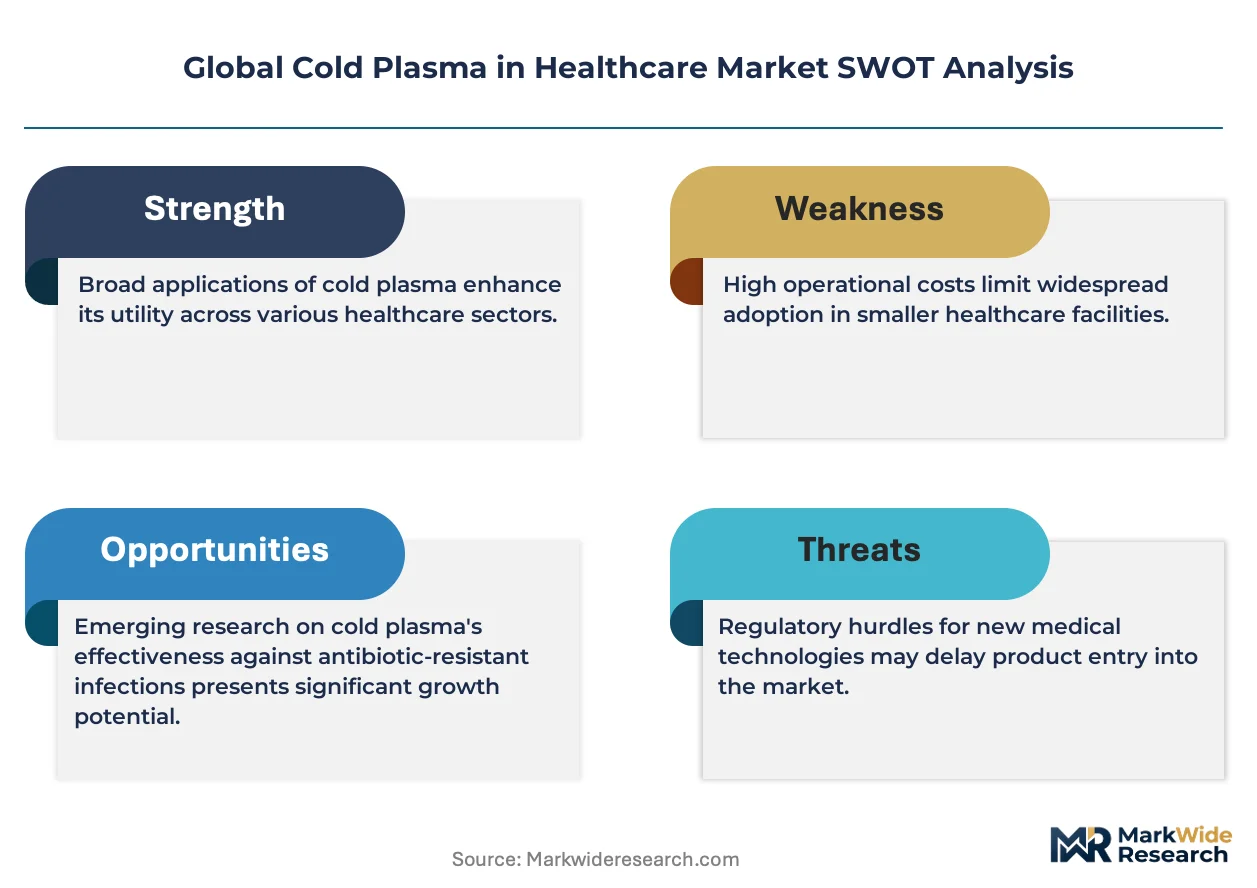
- Helium Supply Concentration:Plasma Jet systems depend on helium feedstock where Qatar and the United States control over 60% of global liquefaction capacity, exposing manufacturers to input cost volatility.
- Phase III Validation Gaps:Cancer therapy applications remain locked in research laboratories awaiting randomized controlled trials, blocking commercialization pathways for oncology-focused device developers.
- Reimbursement Uncertainty:CMS coverage determinations for plasma-based wound treatments remain pending in multiple Medicare Administrative Contractor jurisdictions, freezing hospital capital expenditure decisions.
Strategic Opportunities
- Ambulatory Surgery Centers:Compact cold plasma generators designed for outpatient dermatology clinics in Japan represent underpenetrated demand, with METI subsidies supporting capital equipment purchases.
- Dental Oncology Integration:Convergence of cold plasma with photodynamic therapy protocols opens precision ablation applications for oral squamous cell carcinoma, a segment with limited thermal alternatives.
- India PLI Scheme:The Production Linked Incentive scheme for medical devices offers 5% cashback on eligible sales, creating manufacturing cost advantages for domestic assembly of plasma generators.
Industry Challenges
- Biocompatibility Certification:ISO 10993 testing timelines for plasma-treated implant surfaces extend 14-18 months, delaying product launches for cardiovascular and orthopedic applications.
- Clinical Evidence Generation:Multi-center trial coordination across German, Japanese, and United States sites requires specialized contract research organizations with plasma-specific regulatory expertise, a scarce resource pool.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cold Plasma in Healthcare Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,417.75 Million |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dielectric Barrier Discharge, Plasma Jet, Corona Discharge, Gliding Arc, Radio Frequency Plasma Application: Wound Healing, Sterilization, Cancer Therapy, Dentistry Procedures, Dermatology Treatments End User: Hospitals, Dental Clinics, Oncology Centers, Skin Care Clinics, Research Laboratories Deployment Model: In-hospital Setup, Mobile Units, Ambulatory Care, Home Healthcare Devices, Outpatient Clinics |
| Companies Covered | Apyx Medical, Neoplas med GmbH, terraplasma medical GmbH, US Medical Innovations, Adtec Healthcare Limited, CINOGY System GmbH, Relyon Plasma GmbH, Plasmacure, Nordson Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cold Plasma in Healthcare Market Shifts & Advancements
Plasma generation architectures are fragmenting across clinical specialties, with wound care prioritizing uniform field distribution while oncology demands sub-millimeter targeting precision that existing electrode configurations cannot deliver.
Atmospheric-pressure plasma systems are migrating from Dielectric Barrier Discharge configurations toward Plasma Jet architectures in dental and dermatology suites. Japanese oral surgery clinics in Osaka and Tokyo are adopting jet-based systems for selective caries removal at three times the installation rate of field-based alternatives. This migration is compressing pricing premiums for legacy DBD platforms while elevating service contract margins for precision-calibrated jet systems.
The EU MDR clinical evidence requirements are forcing device manufacturers to submit post-market surveillance data for CE-mark renewals. German notified bodies in Munich and Stuttgart are rejecting technical files lacking real-world performance registries, pushing terraplasma medical GmbH and CINOGY System GmbH to invest in hospital-based outcome tracking infrastructure. Oncology applications face the steepest evidence thresholds, with EMA-equivalent standards now expected for Class III device classifications.
Hospital procurement committees in the United States are unbundling device acquisition from consumable supply agreements, reversing prior bundled pricing models. IDN purchasing coalitions in Texas and California are negotiating electrode supply contracts separately from capital equipment leases, compressing vendor margins on disposable components. This unbundling is most visible in wound care segments where electrode replacement cycles generate predictable recurring revenue streams.
Global Cold Plasma in Healthcare Market Segmentation
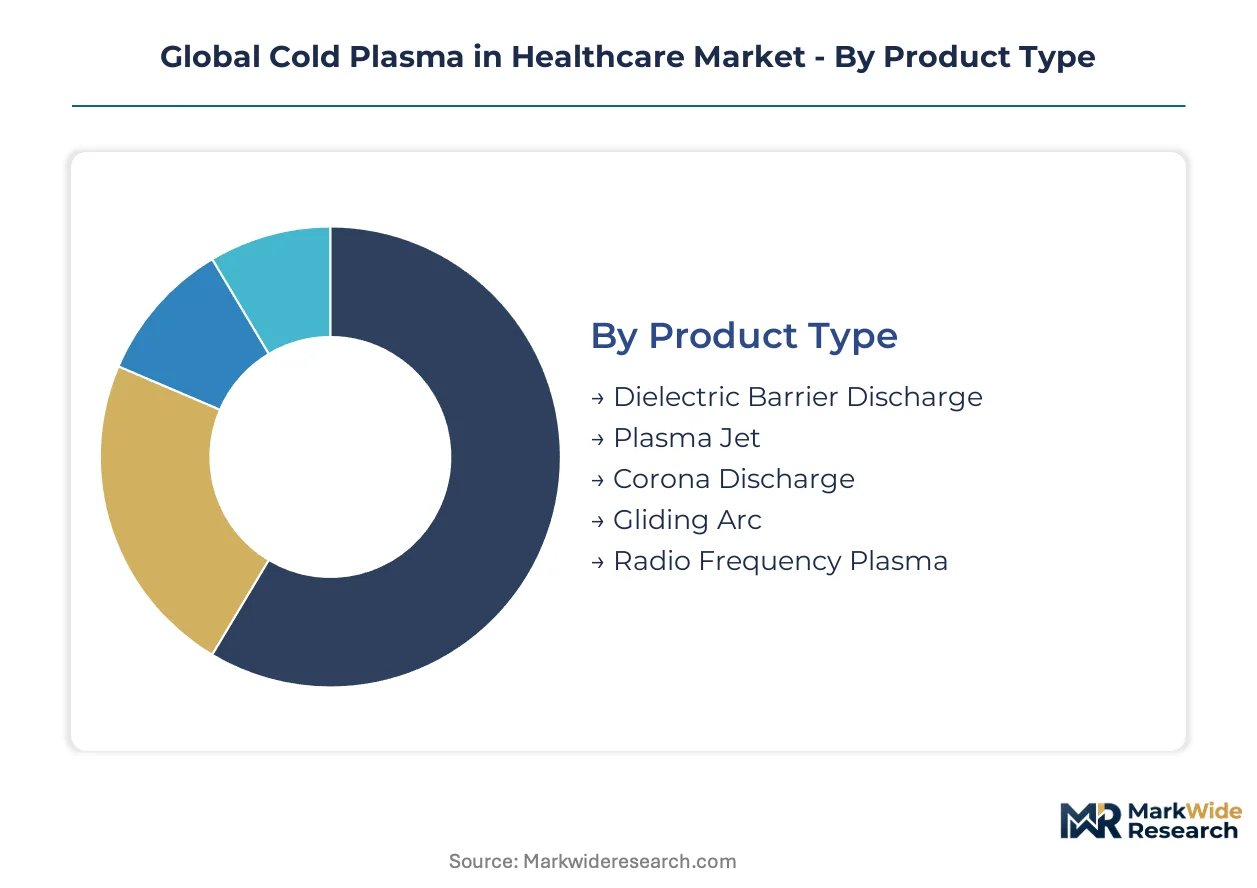
Cold plasma systems fragment across multiple technical and commercial dimensions, with electrode architecture and clinical setting determining reimbursement pathways and capital deployment cycles. Segmentation reveals where installed capacity concentrates versus where validation timelines are compressing fastest.
Product Type:
Technical architecture determines plasma uniformity, temperature control, and tissue selectivity, with each configuration commanding distinct price points and service contract structures.
- Dielectric Barrier Discharge:Electrode arrays generate uniform plasma fields across irregular wound surfaces through dielectric barrier separation. German university hospitals in Munich and Berlin anchor installed capacity for chronic diabetic foot protocols, driving recurring electrode replacement cycles.
- Plasma Jet:Nozzle-directed ionized gas streams achieve sub-millimeter precision for dental caries removal and dermatological ablation. Japanese oral surgery clinics in Osaka and Tokyo adopt jet systems at triple the rate of field-based alternatives, compressing pricing premiums for legacy platforms.
- Corona Discharge:Point-source ionization suits surface sterilization of medical instruments in centralized processing departments.
- Gliding Arc:Rotating arc configurations generate high-velocity plasma for industrial-scale sterilization throughput.
- Radio Frequency Plasma:RF-excited systems enable tunable ion density for research-stage oncology protocols awaiting Phase III validation.
Dielectric Barrier Discharge holds installed capacity. Plasma Jet is rotating up the share rankings.
Application:
Clinical use case governs regulatory pathway complexity, with wound healing accessing commercial markets while oncology remains locked in evidence-generation phases.
- Wound Healing:Chronic ulcer management protocols leverage plasma's bactericidal and proliferation-stimulating effects without thermal necrosis. FDA breakthrough device designations accelerate premarket review for qualifying systems, compressing timelines from 18 months to under 12 months.
- Sterilization:Hospital central processing departments deploy plasma for heat-sensitive instrument decontamination, generating the most predictable recurring revenue streams through consumable electrode contracts.
- Cancer Therapy:Selective ablation of malignant tissue remains concentrated in research laboratories awaiting randomized controlled trials, blocking commercialization for device developers.
- Dentistry Procedures:Caries removal and periodontal disinfection protocols in Japanese and German clinics drive precision-targeted system demand.
- Dermatology Treatments:Aesthetic and pathological skin applications command premium pricing in ambulatory settings.
Sterilization commands revenue predictability. Cancer Therapy is climbing the fastest through research investment intensity.
End User:
Customer type shapes procurement authority, with hospital IDNs negotiating unbundled contracts while specialized clinics accept bundled device-consumable packages.
- Hospitals:Integrated delivery networks in Texas and California unbundle device acquisition from electrode supply agreements, compressing vendor margins on disposable components through separate contract negotiations.
- Dental Clinics:Japanese oral surgery practices in metropolitan Osaka and Tokyo represent concentrated demand for precision jet systems.
- Oncology Centers:Düsseldorf and Hamburg facilities in Germany anchor CE-marked plasma jet distribution for research-stage ablation protocols.
- Skin Care Clinics:Ambulatory dermatology settings in Germany adopt compact generators from Relyon Plasma GmbH.
- Research Laboratories:Multi-center trial coordination across German, Japanese, and United States sites requires specialized contract research organizations with plasma-specific regulatory expertise.
Hospitals dominate procurement volume. Dental Clinics are gaining share fastest through Japanese installation rates.
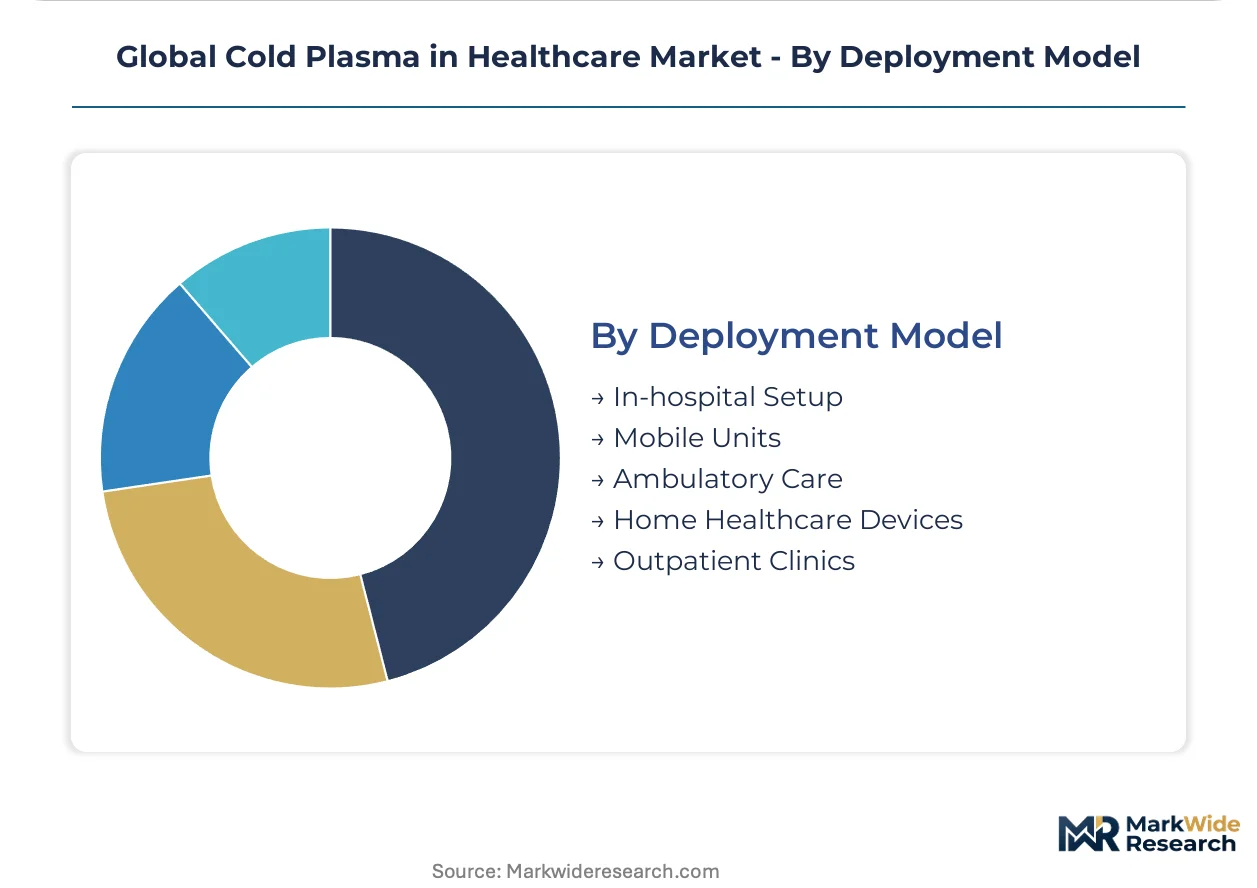
Deployment Model:
Physical configuration determines capital intensity and regulatory classification, with fixed installations accessing different reimbursement codes than mobile or home-based alternatives.
- In-hospital Setup:Fixed installations in German university hospitals anchor chronic wound management protocols with dedicated infrastructure and trained clinical staff.
- Mobile Units:Transportable systems enable plasma deployment across multiple procedure rooms, with METI subsidies in Japan supporting capital equipment purchases for qualifying facilities.
- Ambulatory Care:Outpatient surgical centers represent underpenetrated demand for compact generators designed for same-day procedures.
- Home Healthcare Devices:Patient-operated systems face steepest biocompatibility certification barriers under ISO 10993 timelines extending 14-18 months.
- Outpatient Clinics:Standalone dermatology and dental practices command premium pricing for precision-calibrated systems with service contract attachments.
In-hospital Setup holds installed base concentration. Mobile Units are expanding most quickly through Japanese subsidy programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German university hospitals anchor European installed capacity for chronic wound protocols, while Japanese METI subsidies accelerate ambulatory adoption and FDA breakthrough pathways compress United States market access timelines. Device manufacturers concentrate CE-mark validation resources across Munich, Stuttgart, and Düsseldorf clusters to satisfy EU MDR post-market surveillance requirements.
United States
FDA breakthrough device designations compress premarket review timelines from 18 months to under 12 months for qualifying wound healing systems. CMS coverage determinations remain pending across multiple Medicare Administrative Contractor jurisdictions, freezing hospital capital expenditure decisions in Texas and California IDN purchasing coalitions. Dallas and Houston medical centers anchor plasma sterilization deployments in centralized processing departments.
Germany
EU MDR compliance requirements and EMA clinical evidence standards filter non-compliant competitors from European distribution networks. G-BA reimbursement decisions separate commercially viable plasma therapies from research-stage technologies in chronic wound management. Munich and Berlin university hospitals drive recurring electrode replacement cycles for diabetic foot ulcer protocols.
Japan
METI subsidies support capital equipment purchases for compact plasma generators in ambulatory surgery centers and dental clinics. Osaka and Tokyo oral surgery practices adopt jet-based systems for selective caries removal at triple the rate of field-based alternatives. PMDA regulatory pathways align with international standards for device classification.
India
The Production Linked Incentive scheme for medical devices offers 5% cashback on eligible sales, creating manufacturing cost advantages for domestic assembly of plasma generators. CDSCO regulatory frameworks govern clinical trial approvals for wound healing applications. Maharashtra and Karnataka medical device clusters attract contract manufacturing investments from international device developers.
United Kingdom
MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards while streamlining UK-specific market access pathways. London and Southeast England research hospitals coordinate multi-center trial infrastructure for plasma-based oncology protocols. NICE technology appraisals determine reimbursement eligibility for novel wound care interventions.
Global Cold Plasma in Healthcare Market Competitive Landscape
Specialized plasma technology developers and diversified medical device conglomerates split the market along precision-versus-scale vectors. The vendor base concentrates among German engineering-intensive specialists and United States wound care platform builders. Three archetypes dominate: university-spinout technology specialists, diversified surgical device conglomerates, and contract manufacturing service providers. Strategic partnerships and CE-mark validation investments constitute the dominant competitive moves across European markets.
Within the German specialist tier, terraplasma medical GmbH and CINOGY System GmbH occupy anchor positions representing Munich-based engineering capabilities and CE-marked distribution infrastructure respectively. Relyon Plasma GmbH exemplifies the compact-generator archetype serving ambulatory dermatology settings. These GmbH-structured entities concentrate regulatory expertise across Bavarian and North Rhine-Westphalian industrial clusters.
| Leading Market Players |
|---|
| Apyx Medical |
| Neoplas med GmbH |
| terraplasma medical GmbH |
| US Medical Innovations |
| Adtec Healthcare Limited |
| CINOGY System GmbH |
| Relyon Plasma GmbH |
| Plasmacure |
| Nordson Corporation |
| Others |
Supply & Pricing Matrix
Munich-based electrode manufacturing clusters anchor European plasma generator supply, with their capacity utilization rates directly transmitting into downstream pricing power for German device manufacturers serving chronic wound protocols.
Pricing Analysis
EU MDR compliance dictates the pricing tier structure across European distribution networks. Three-tier pricing structure across premium CE-marked, standard ISO-certified, and economy non-certified levels separates hospital IDN procurement from ambulatory clinic purchases. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in economy tiers is intensifying because helium feedstock volatility squeezes consumable margins. Hospital IDNs in Texas and California demonstrate highest price sensitivity through unbundled contract negotiations, while Japanese dental clinics accept premium pricing for precision-calibrated jet systems.
Supply Chain Analysis
Tariff exposure between Qatar and Germany dominates helium feedstock security for plasma jet manufacturers. Component assembly concentrates in Germany, Japan, and the United States, with electrode fabrication tethered to Bavarian precision engineering clusters. Raw material dependencies include high-purity helium, alumina ceramic substrates, and RF power modules. Single-source vulnerability in Qatari helium liquefaction exposes manufacturers to input cost spikes. Distribution runs through hospital IDN purchasing coalitions in North America and specialized medical device distributors in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across clinical specialties creates niche opportunities as wound care, dentistry, and oncology applications diverge in technical requirements and regulatory pathways.
For Market Incumbents: Pre-empt margin erosion in Dielectric Barrier Discharge platforms by deepening backward integration into electrode manufacturing in Bavarian industrial clusters. Lock in hospital IDN purchasing coalitions through multi-year consumable supply agreements before CMS coverage determinations clarify reimbursement codes. Certification investment in ISO 10993 biocompatibility testing creates defensive moats against mid-tier competitors lacking capital for extended validation timelines. For New Entrants and Emerging Players: Build out ambulatory surgery center presence in Japanese metropolitan markets where METI subsidies offset capital equipment costs. Target precision oncology applications in Düsseldorf and Hamburg research hospitals awaiting Phase III validation completion. Dental-dermatology convergence protocols offer the most penetrable entry point through compact jet system designs with service contract attachments. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because reimbursement pathway maturation will separate commercially viable device developers from research-stage technologies. Acquisition targets should display CE-mark validation infrastructure and hospital-based outcome tracking capabilities. The signal to watch is CMS national coverage determination for plasma-based wound treatments, which would unlock hospital capital expenditure cycles and validate recurring revenue models.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated premarket review compresses timelines for wound healing systems seeking CMS reimbursement eligibility. |
| CE Marking Pathway Investment | EU MDR compliance filters non-compliant competitors from German, French, and Italian healthcare network distribution. |
| Hospital System Partnership | Integrated delivery network contracts in Texas and California anchor recurring electrode replacement revenue streams. |
| Software Companion Development | Digital dosing protocols for plasma jet systems enable precision targeting in dental and dermatology procedures. |
| Reimbursement Strategy | G-BA and CMS coverage determinations separate commercially viable plasma therapies from research-stage technologies. |
Research Methodology
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and plasma device R&D directors and refined through secondary validation against FDA 510(k) filings, EMA device registration databases, hospital procurement records, and CMS Medicare coverage determinations. Bottom-up installed base estimates triangulated with top-down addressable market calculations.
Demand-supply balance across plasma generator manufacturing capacity and hospital capital expenditure cycles anchored the analytical framework over the projection horizon. Segmentation dimensions modeled include product architecture, clinical application, end-user setting, and regional regulatory cluster. CAGRs were derived from penetration rate trajectories and replacement cycle analysis. Forecast inputs incorporated helium supply elasticity and reimbursement pathway probability assessments.
Stress conditions across helium price volatility, CMS coverage determination delays, and EU MDR technical file rejection rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding clinical trial progression and regulatory approval timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Intracranial Hemorrhage Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Phototherapy Device Market
Diagnostic and Therapeutic Devices
Nanobiosensors in Healthcare Market
Diagnostic and Therapeutic Devices
Smart Infusion System Market
Diagnostic and Therapeutic Devices
Pelvic Congestion Syndrome Treatment Market
Diagnostic and Therapeutic Devices
Smart Inhalers Market
Diagnostic and Therapeutic Devices
Crohn's Disease Diagnostic and Therapeutic Market
Diagnostic and Therapeutic Devices
Therapeutic Support Surface Market
Diagnostic and Therapeutic Devices
Sustained Acoustic Medicine Market
Diagnostic and Therapeutic Devices
Vacuum Therapy Devices Market
Diagnostic and Therapeutic Devices
Therapeutic Bed Market
Diagnostic and Therapeutic Devices
Automated Immunoassay Analyzers Market
Diagnostic and Therapeutic Devices
Germany Smart Healthcare Market
Diagnostic and Therapeutic Devices
Electroceuticals Bioelectric Medicine Market
Diagnostic and Therapeutic Devices
Therapeutic Medical Guidewire Market
Diagnostic and Therapeutic Devices
Dermatology Diagnostic Equipment Market