
 Skin Biopsy Market | 2026-2036
Skin Biopsy Market Size, Share, and Industry Trends Forecast 2026-2036
Skin Biopsy Market Analysis
Aftermarket service revenue for biopsy device maintenance and calibration is reconfiguring how manufacturers capture lifetime value from installed bases. BD leverages its extensive hospital distribution network to sustain recurring service contracts across North American accounts. Danaher anchors its position through diagnostic workflow integration that extends from tissue acquisition to digital pathology. Hologic, Inc. differentiates with specialized breast biopsy systems that occupy a defensible niche in oncology screening protocols.
A skin biopsy is a minimally invasive surgical procedure that extracts tissue samples from cutaneous lesions using instruments ranging from circular punch blades to electrosurgical loops, with specimen depths typically spanning 1 to 8 millimeters depending on diagnostic intent. The primary purpose is histopathological examination to distinguish benign from malignant cellular changes, guide staging decisions, and monitor therapeutic response in dermatological and oncological care. Punch biopsy instruments dominate routine dermatology practice due to standardized cylindrical cores that preserve dermal architecture for reliable diagnosis. Vacuum-assisted techniques are gaining traction in research laboratories where larger tissue volumes improve molecular analysis yield without multiple incision sites. Automated devices command premium positioning in high-throughput diagnostic centers where throughput consistency reduces operator-dependent variability.
FDA oversight of premarket notification pathways shapes device classification and clinical evidence requirements for new biopsy technologies entering the United States market. The Clinical Laboratory Improvement Amendments framework governs quality standards for histopathological processing, directly influencing how hospitals and diagnostic centers validate internal workflows. ISO 13485 certification requirements from notified bodies affect supplier qualification for manufacturers targeting European distribution channels. Stakeholders must monitor how reimbursement coding revisions for office-based versus facility-based biopsy procedures redistribute site-of-care economics across dermatology clinics and hospital outpatient departments.
Market Dynamics
Minimally invasive diagnostic protocols are compressing procedure times and site-of-care requirements, while FDA's evolving laboratory-developed test guidance forces manufacturers to recalibrate quality management systems across distributed laboratory networks.
Growth Catalysts
- CLIA Quality Standards:The Clinical Laboratory Improvement Amendments framework mandates rigorous histopathological processing protocols, compelling diagnostic centers to upgrade automated specimen handling systems and expand trained technician staffing.
- Dermatology Clinic Expansion:Integrated health networks in the United States are standardizing office-based biopsy workflows, driving demand for portable punch instruments and rapid on-site specimen assessment capabilities.
- Vacuum-Assisted Techniques:Research laboratories increasingly adopt vacuum-assisted biopsy devices to extract larger tissue volumes through single incision sites, improving molecular analysis yield for genomic profiling applications.
Market Restraints
- ISO 13485 Certification Barriers:European notified bodies impose stringent supplier qualification requirements, extending market entry timelines for smaller manufacturers lacking established quality management infrastructure.
- Reimbursement Coding Compression:CMS revisions to facility-based versus office-based procedure codes redistribute economics unpredictably, constraining capital allocation for clinic equipment upgrades.
- Histopathologist Supply Constraints:Specialized dermatopathology training programs produce insufficient board-certified specialists to match biopsy volume growth, creating diagnostic backlogs in high-throughput centers.
Strategic Opportunities
- Digital Pathology Integration:Convergence of whole-slide imaging with artificial intelligence algorithms enables remote diagnosis and second-opinion networks, opening underserved rural markets to specialist-level interpretation.
- IRIA Incentive Structures:The Inflation Reduction Act's diagnostic innovation provisions create reimbursement pathways for advanced biopsy technologies that demonstrate measurable reduction in repeat procedures.
- Automated Device White Space:High-throughput diagnostic centers seek operator-independent consistency, presenting openings for robotics-enabled specimen acquisition systems with embedded quality verification sensors.
Industry Challenges
- Legacy System Interoperability:Digital pathology platforms must integrate with existing laboratory information systems and electronic health records, requiring costly middleware development and validation cycles.
- Technician Training Compression:Rapid device innovation outpaces institutional training programs, creating competency gaps in specimen handling, artifact prevention, and quality control documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skin Biopsy Market |
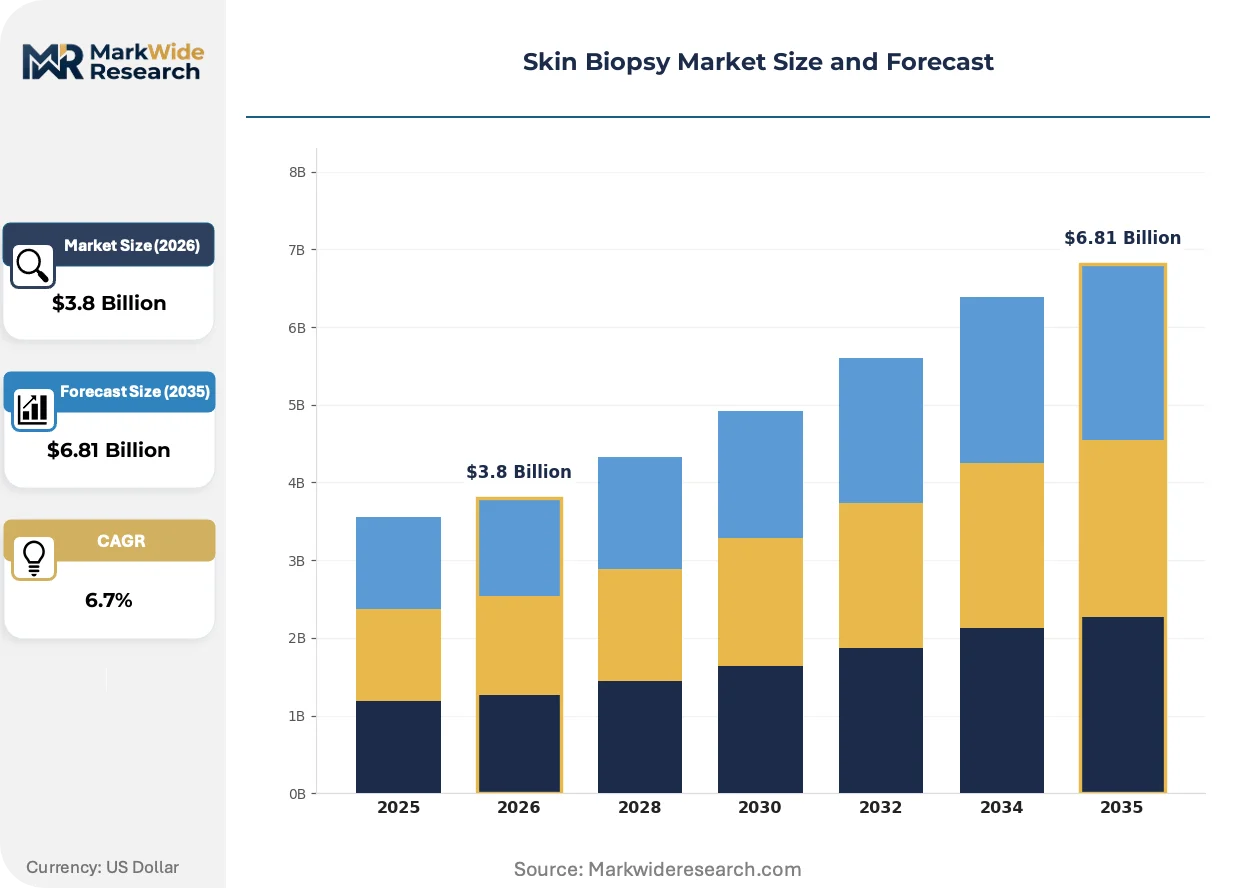
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Punch Biopsy, Excisional Biopsy, Shave Biopsy, Incisional Biopsy Application: Dermatology, Oncology, Inflammatory Disorders, Infectious Diseases Technology: Manual Techniques, Electrosurgical Techniques, Vacuum-Assisted Techniques, Automated Devices End User: Hospitals, Dermatology Clinics, Research Laboratories, Diagnostic Centers |
| Companies Covered | BD, Boston Scientific Corporation, Cardinal Health, Danaher, Hologic, Inc., Leica Biosystems Nussloch GmbH, Cook, DTR Medical Ltd, Devicor Medical Products, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skin Biopsy Market Emerging Trajectories
Diagnostic workflows are fragmenting across decentralized acquisition points and centralized interpretation hubs, compressing traditional hospital-based pathology service models while elevating real-time specimen assessment technologies.
Confocal laser endomicroscopy is collapsing the diagnostic pathway for certain lesion types by enabling non-invasive cellular-level imaging that substitutes for excisional biopsy in select monitoring protocols. Academic medical centers in Germany and the Netherlands are piloting this technology for longitudinal tracking of high-risk patients. The structural consequence is reduced specimen volume flowing to traditional histopathology laboratories, forcing service providers to diversify revenue streams toward molecular and genomic testing.
REACH chemical substance restrictions are compelling European manufacturers to reformulate sterilization processes and device coatings, eliminating certain phthalates and heavy metal stabilizers from punch biopsy instrument production. Notified bodies now require updated biocompatibility documentation under MDR Article 10, extending technical file review periods. German and French distributors report accelerated supplier audits to verify compliance with substance of very high concern thresholds.
Point-of-care specimen assessment is altering procurement patterns as dermatology clinics acquire rapid staining and microscopic evaluation capabilities previously confined to hospital laboratories. United States outpatient facilities are unbundling after-sales service contracts, selecting third-party calibration providers over manufacturer-authorized technicians. This behavioral shift concentrates in the southeastern states where independent practice associations negotiate collective purchasing arrangements for diagnostic equipment.
Skin Biopsy Market Segmentation
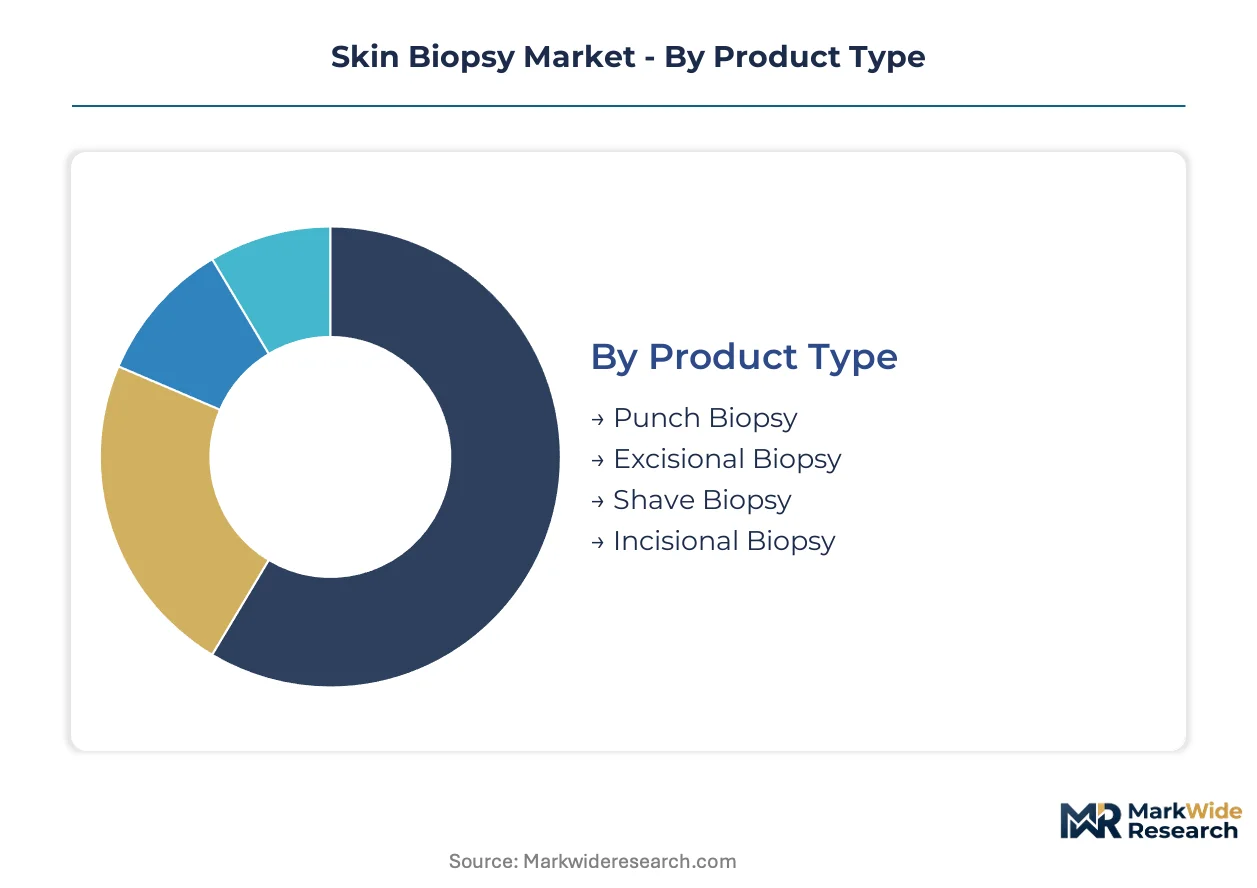
Segmentation in the skin biopsy market reveals how diagnostic intent, procedural setting, and technological sophistication reshape procurement patterns across healthcare networks. Understanding these divides enables manufacturers to calibrate device specifications, service models, and distribution strategies to match distinct customer requirements.
Product Type:
The use-case spectrum spans routine screening to definitive cancer staging, with instrument selection driven by lesion depth, suspected pathology, and cosmetic outcome priorities.
- Punch Biopsy:Cylindrical blades extract standardized 1-8mm tissue cores preserving dermal architecture for reliable histopathological interpretation. United States dermatology clinics favor disposable punch instruments for office-based workflows, constrained by CLIA-mandated quality documentation requirements.
- Excisional Biopsy:Complete lesion removal with adequate margins serves definitive diagnosis and therapeutic intervention simultaneously. Hospital outpatient departments in Germany and France concentrate demand for excisional protocols where suspected melanoma requires full histological assessment.
- Shave Biopsy:Superficial tangential excision suits raised benign lesions and cosmetically sensitive locations. Dermatology clinics deploy shave techniques for rapid benign nevus evaluation without suture closure.
- Incisional Biopsy:Wedge-shaped tissue sampling from larger lesions preserves representative architecture when complete excision is impractical. Academic medical centers apply incisional methods for inflammatory dermatoses requiring deep dermal and subcutaneous tissue analysis.
Established volume favors punch biopsy for routine dermatology; emerging adoption favors excisional protocols in integrated oncology networks.
Application:
Cost tier stratification separates high-reimbursement cancer diagnostics from commodity screening procedures with compressed margins.
- Dermatology:Basal cell carcinoma, squamous cell carcinoma, and melanoma screening dominate procedural volumes in outpatient settings. United States integrated health networks standardize dermatology biopsy protocols across multi-site clinic systems, driving demand for portable instruments with rapid on-site assessment capabilities.
- Oncology:Staging biopsies and treatment response monitoring command premium pricing in hospital-based care pathways. German university hospitals anchor European oncology biopsy volume through centralized referral networks for complex cutaneous malignancies.
- Inflammatory Disorders:Lupus erythematosus and vasculitis diagnosis requires specialized handling to preserve immunofluorescence patterns. Academic pathology laboratories in the Netherlands develop standardized protocols for autoimmune dermatosis specimen processing.
- Infectious Diseases:Deep fungal infections and atypical mycobacterial disease necessitate tissue culture submission alongside histopathology. Tropical medicine centers in southern United States states manage infectious disease biopsy workflows for imported pathogen identification.
Reimbursement concentration favors oncology applications; diagnostic complexity favors inflammatory disorder protocols in specialized centers.
Technology:
Volume differentiation separates high-throughput automated systems from operator-dependent manual techniques in resource-constrained settings.
- Manual Techniques:Hand-held punch blades and scalpels remain standard in smaller dermatology practices with limited capital budgets. Rural United States clinics sustain manual technique dominance where procedure volumes do not justify automated system investment.
- Electrosurgical Techniques:Radiofrequency and hyfrecator devices enable hemostatic specimen removal with reduced bleeding complications. French outpatient surgery centers adopt electrosurgical biopsy methods for anticoagulated patient populations.
- Vacuum-Assisted Techniques:Negative pressure extraction harvests larger tissue volumes through single incision sites for molecular analysis. Research laboratories at Dutch academic medical centers deploy vacuum-assisted devices to improve genomic profiling yield from precious lesion samples.
- Automated Devices:Robotics-enabled specimen acquisition with embedded quality verification sensors commands premium positioning in high-throughput diagnostic centers. United States commercial pathology laboratories pilot automated systems to reduce operator-dependent variability across multi-site networks.
Installed base concentration favors manual techniques; capability investment favors automated devices in centralized laboratory networks.
End User:
Customer type fragmentation redistributes purchasing authority from hospital procurement departments to independent clinic associations and research consortia.
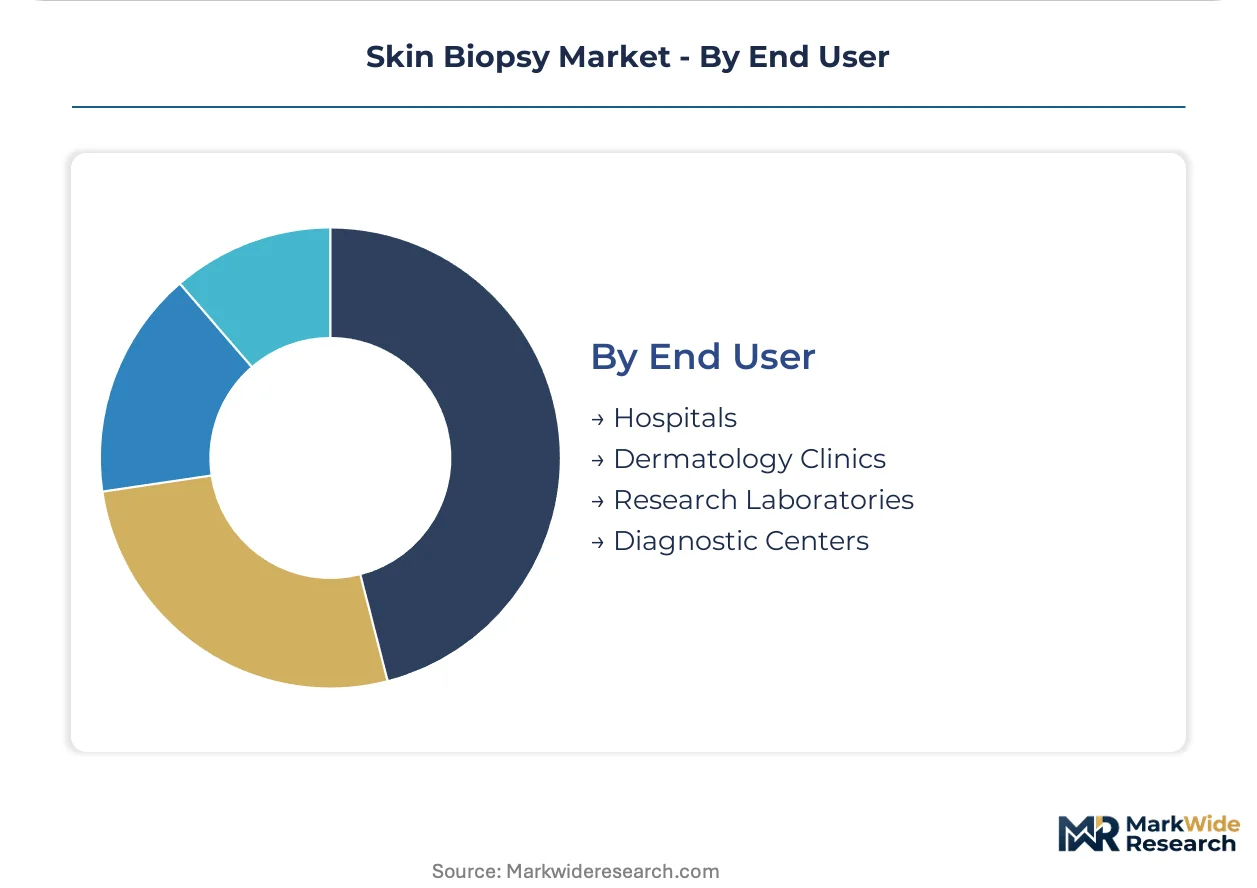
- Hospitals:Inpatient and emergency department biopsy services require integration with surgical scheduling and pathology information systems. German hospital networks consolidate device purchasing through regional procurement cooperatives.
- Dermatology Clinics:Independent and group practices drive demand for portable, disposable instruments with minimal maintenance requirements. Southeastern United States independent practice associations negotiate collective purchasing arrangements for diagnostic equipment.
- Research Laboratories:Academic and commercial research settings prioritize specimen quality for genomic, proteomic, and transcriptomic analysis. Netherlands cancer research institutes specify vacuum-assisted devices to maximize nucleic acid yield from limited tissue samples.
- Diagnostic Centers:Centralized commercial pathology laboratories seek throughput consistency and automated quality documentation. United States reference laboratories invest in digital pathology integration to support remote interpretation networks.
Procurement scale favors hospital systems; decision velocity favors dermatology clinics with unbundled service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement environments. United States hospital networks negotiate aggressively on service contracts while German university hospitals prioritize precision engineering regardless of premium positioning. Emerging diagnostic centers in India and Brazil face capital constraints that compress margins for mid-tier device suppliers.
United States
Integrated health networks in Texas and Florida drive standardization across multi-site dermatology clinic systems. FDA's evolving guidance on laboratory-developed tests forces manufacturers to recalibrate quality management systems. Greater Boston anchors commercial pathology laboratory concentration where automated biopsy systems reduce operator-dependent variability.
Germany
University hospitals in Bavaria and North Rhine-Westphalia anchor European oncology biopsy volume through centralized referral networks. REACH chemical substance restrictions compel manufacturers to reformulate sterilization processes and eliminate phthalates from punch instrument production. The Eindhoven-to-Düsseldorf corridor hosts diagnostic workflow integration specialists serving cross-border hospital procurement cooperatives.
Netherlands
Academic medical centers in Amsterdam and Rotterdam pilot vacuum-assisted devices to maximize nucleic acid yield for genomic profiling applications. MDR Article 10 biocompatibility documentation requirements extend technical file review periods for notified body submissions. Leiden cancer research institutes specify advanced biopsy technologies for molecular analysis workflows.
France
Outpatient surgery centers in Île-de-France adopt electrosurgical biopsy methods for anticoagulated patient populations. ANSM intensifies supplier audits to verify compliance with substance of very high concern thresholds under REACH annexes. Lyon-based distributors report accelerated qualification timelines for MDR-compliant device portfolios.
India
Metropolitan diagnostic chains in Maharashtra and Karnataka expand point-of-care specimen assessment capabilities previously confined to hospital laboratories. CDSCO premarket notification pathways shape device classification for new biopsy technologies entering domestic distribution. Hyderabad medical device clusters develop cost-optimized punch instruments for price-sensitive clinic procurement.
Skin Biopsy Market Vendor Landscape
Capability concentration sits with specialized diagnostic workflow integrators; scale advantage sits with diversified medical technology conglomerates. The vendor base stratifies across three tiers: premium-tier automation specialists, mid-market disposable instrument suppliers, and regional fabrication houses serving price-sensitive procurement. Strategic archetypes include hospital distribution network operators, diagnostic platform integrators, and niche oncology screening specialists. M&A activity targets digital pathology workflow assets while geographic expansion concentrates on Southeast Asian diagnostic center formation.
Within the diagnostic platform integrator tier, Danaher and BD exemplify contrasting scale-capture mechanisms. Danaher anchors position through workflow integration extending from tissue acquisition to digital pathology interpretation. BD leverages extensive hospital distribution infrastructure to sustain recurring service contract penetration. Hologic, Inc. occupies a defensible specialization position in breast biopsy systems serving oncology screening protocols. These three entities represent distinct competitive vectors: platform breadth, channel dominance, and clinical niche depth respectively.
| Leading Market Players |
|---|
| BD |
| Boston Scientific Corporation |
| Cardinal Health |
| Danaher |
| Hologic, Inc. |
| Leica Biosystems Nussloch GmbH |
| Cook |
| DTR Medical Ltd |
| Devicor Medical Products, Inc. |
| Others |
Supply Flow & Price Mechanics
The Rotterdam-Antwerp-Düsseldorf freight corridor carries sterilized biopsy instruments and precision-engineered punch blades from German manufacturing clusters to Benelux distribution hubs, with per-kilogram logistics costs compressing margin structures for mid-tier disposable suppliers while enabling premium-tier automated device manufacturers to sustain price differentiation through bundled calibration services.
Pricing Analysis
After-sales service revenue streams anchor lifetime value capture for biopsy device manufacturers, with multi-year calibration contracts and preventive maintenance agreements generating recurring income that offsets compressed margins on initial hardware placement. Three-tier pricing structure across premium, standard, and economy levels separates robotics-enabled automated systems from electrosurgical devices and manual punch instruments. Cost compression in the economy tier intensifies because Hyderabad-based fabricators export cost-optimized disposable blades to price-sensitive clinic procurement in India and Brazil. Dermatology clinics in the southeastern United States exhibit highest price sensitivity through collective purchasing arrangements, while German university hospitals show lowest sensitivity, prioritizing precision engineering and MDR-compliant documentation regardless of premium positioning.
Supply Chain Analysis
Export-control restrictions on advanced robotics components and precision sensor technologies limit flows of automated biopsy system subassemblies from United States and German suppliers to certain research laboratory networks. Manufacturing concentration centers on Germany for precision-engineered punch instruments, the United States for automated diagnostic platforms, and India for cost-optimized disposable blades. Raw material dependencies include surgical-grade stainless steel from Swedish mills, medical-grade polymers from Belgian chemical clusters, and precision electric motors from Japanese suppliers. Single-source vulnerability concentrates in high-tolerance actuator components for robotics-enabled systems. Distribution runs through regional procurement cooperatives in German hospital networks, GPO contracts in United States health systems, and independent practice associations in southeastern states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The skin biopsy market sits at an inflection where FDA's evolving laboratory-developed test guidance forces quality management system recalibration across distributed laboratory networks, creating structural openings for workflow-integrated platform providers.
For Market Incumbents: Insulate installed base positions by deepening backward integration into precision component manufacturing for automated device lines, reducing exposure to robotics actuator supply constraints. Secure channel control through exclusive service contracts with United States integrated health networks before third-party calibration providers capture aftermarket revenue. Invest in CLIA-mandated quality documentation capabilities to defend against emerging diagnostic platform integrators.
For New Entrants and Emerging Players: Rural United States dermatology clinics represent underpenetrated demand for portable, disposable punch instruments with minimal maintenance requirements, where procedure volumes do not justify automated system investment. Target research laboratories in the Netherlands with vacuum-assisted devices optimized for nucleic acid yield in genomic profiling workflows. Pursue go-to-market partnerships with third-party calibration providers to unbundle service contracts from manufacturer-authorized technician networks.
For Investors and Strategic Acquirers: Digital pathology workflow specialists with embedded AI algorithms for remote diagnosis represent priority acquisition targets, enabling convergence of tissue acquisition with centralized interpretation capabilities. Long-term viability hinges on platforms demonstrating measurable reduction in repeat procedures under IRIA incentive structures. Monitor CMS reimbursement coding revisions for office-based versus facility-based procedures as early signal of site-of-care economics redistribution.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | 510(k) pathway alignment with evolving laboratory-developed test guidance accelerates market entry timelines. |
| CE Marking Pathway | MDR Article 10 biocompatibility documentation compliance extends European market access durability. |
| Hospital System Partnership | Integrated health network contracts in Texas and Florida anchor recurring service revenue streams. |
| Software Companion Development | AI-enabled whole-slide imaging integration opens underserved rural markets to specialist interpretation. |
| Reimbursement Strategy | IRIA diagnostic innovation provisions create pathways for advanced technologies reducing repeat procedures. |
Methodological Framework
Desk research of FDA 510(k) filings, MDR technical documentation, and CMS reimbursement coding databases preceded structured interviews with dermatology clinic operations directors, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and pathology laboratory directors. Primary fieldwork combined with secondary validation against hospital procurement databases, GPO contract repositories, and CLIA laboratory certification records. Bottom-up procedure volume estimates triangulated with top-down market sizing across product type, application, technology, and end user segmentation dimensions.
Assumptions regarding regulatory pathway stability, reimbursement code durability, and supply chain corridor cost structures were held fixed across baseline scenarios while stress-testing sensitivity to REACH chemical substance restriction expansion and histopathologist supply constraint intensification. Segmentation modeling spanned product type, application, technology tier, and end user category across the projection horizon. CAGRs derived from procedure volume trajectories, price evolution by tier, and technology substitution rates. Forecast inputs incorporated CLIA-mandated quality upgrade cycles and digital pathology adoption curves in commercial laboratory networks.
Practitioners should monitor FDA guidance finalization on laboratory-developed tests, CMS site-of-care reimbursement recalibration, and REACH substance of very high concern threshold adjustments for early signals of forecast revision necessity. Material shifts in regulatory pathway requirements, reimbursement code valuations, or supply chain corridor cost structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Heat Therapy Lamp Market
Diagnostic and Therapeutic Devices
Smart Infusion System Market
Diagnostic and Therapeutic Devices
Dermatology Diagnostic Equipment Market
Diagnostic and Therapeutic Devices
Dissolving Microneedles Market
Diagnostic and Therapeutic Devices
Therapeutic Catheters Market
Diagnostic and Therapeutic Devices
Magnetic Therapy Devices Market
Diagnostic and Therapeutic Devices
Global Therapeutic Plasma Exchange Market
Diagnostic and Therapeutic Devices
Intracranial Hemorrhage Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Acupuncture Needles Market
Diagnostic and Therapeutic Devices
Germany Smart Healthcare Market
Diagnostic and Therapeutic Devices
Global Far Infrared Therapy Device Market
Diagnostic and Therapeutic Devices
Breast Lesion Localization Market
Diagnostic and Therapeutic Devices
Global Smart Inhaler Technology Market
Diagnostic and Therapeutic Devices
Electroceuticals Bioelectric Medicine Market
Diagnostic and Therapeutic Devices
Vacuum Therapy Devices Market
Diagnostic and Therapeutic Devices
Therapeutic Medical Guidewire Market