
 Support Surfaces Market | 2026-2036
Support Surfaces Market Size, Share, and Industry Trends Forecast 2026-2036
Support Surfaces Market Insights
Certified wound-care nursing shortages across North American health systems is unwinding capacity for pressure injury prevention programs. Stryker Corporation leverages its integrated bed-surface platform to dominate acute care contracting in the United States. Hill-Rom Holdings, Inc. sustains R&D intensity in microclimate management technology, while ArjoHuntleigh specializes in bariatric surface configurations for long-term care operators.
Support surfaces are engineered pressure redistribution platforms—typically constructed from viscoelastic polyurethane foams, gel-filled bladders, or alternating air cells—designed to reduce tissue interface pressure below capillary closing thresholds for immobilized patients. Foam-based static surfaces occupy the largest installed base due to lower capital requirements and minimal maintenance, though dynamic air systems capture disproportionate margin pools in critical care settings. Long-term care facilities represent the fastest-growing end user segment as aging demographics expand skilled nursing bed counts and regulatory scrutiny intensifies.
The FDA's medical device quality system regulation and the EU MDR's reclassification of powered support surfaces are elevating documentation burdens and testing costs for manufacturers seeking dual-market access. ISO 10993 biocompatibility standards and EN 60601 electrical safety requirements further constrain material selection and design freedom for gel and latex compositions. Stakeholders must monitor how evolving reimbursement codes for pressure ulcer prevention in home care settings reshape channel economics between rental and purchase models.
Market Dynamics
The FDA's reclassification of powered air surfaces as Class II medical devices is forcing manufacturers to restructure quality management systems and clinical validation protocols, compressing margins for mid-tier suppliers while creating compliance moats for established platforms.
Growth Catalysts
- Acute care pressure injury protocols:CMS reimbursement penalties for hospital-acquired conditions are mandating surface upgrades in United States intensive care units, accelerating replacement cycles for legacy foam mattresses.
- Germany's long-term care reforms:Bundled reimbursement for pressure ulcer prevention in skilled nursing facilities is shifting capital allocation toward dynamic air systems with microclimate control.
- Viscoelastic polyurethane formulations:Next-generation open-cell foams with zoned density gradients are reducing peak interface pressures below 32 mmHg thresholds in bariatric patient populations.
Market Restraints
- MDR documentation burdens:EU MDR's enhanced clinical evidence requirements for powered support surfaces are extending registration timelines by 18-24 months and consuming 15-20% of R&D budgets for dual-market manufacturers.
- Specialized polymer supply concentration:Medical-grade viscoelastic foam production concentrates among three German chemical suppliers, creating input cost volatility and allocation risk during demand surges.
- Alternating pressure mattress longevity:Dynamic air cell systems require 3-5 year replacement cycles versus 7-10 years for static foam, elevating total cost of ownership calculations in procurement committees.
Strategic Opportunities
- Home care reimbursement expansion:Medicare's emerging pressure ulcer prevention codes for durable medical equipment in home settings are opening rental-to-purchase conversion channels previously dominated by acute care leasing.
- Sensor-embedded surfaces:Integration of capacitive pressure mapping with IoT telemetry is enabling real-time tissue perfusion monitoring and predictive repositioning alerts for immobilized patients.
- India's skilled nursing buildout:National Health Mission investments in tier-2 and tier-3 city long-term care infrastructure are creating first-mover advantages for ISO 13485-certified manufacturers with localized assembly.
Industry Challenges
- Wound-care certification scarcity:North American health systems face critical shortages of CWOCN-certified nurses capable of conducting surface selection protocols and staff training programs, constraining program rollout velocity.
- Legacy bed frame incompatibility:Dynamic surface integration with existing hospital bed platforms requires proprietary rail systems and power supply modifications, complicating fleet upgrade decisions in capital-constrained facilities.
- Biocompatibility testing bottlenecks:ISO 10993-5 cytotoxicity and ISO 10993-10 sensitization studies for novel gel formulations face 6-9 month queue times at accredited laboratories, compressing product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Support Surfaces Market |
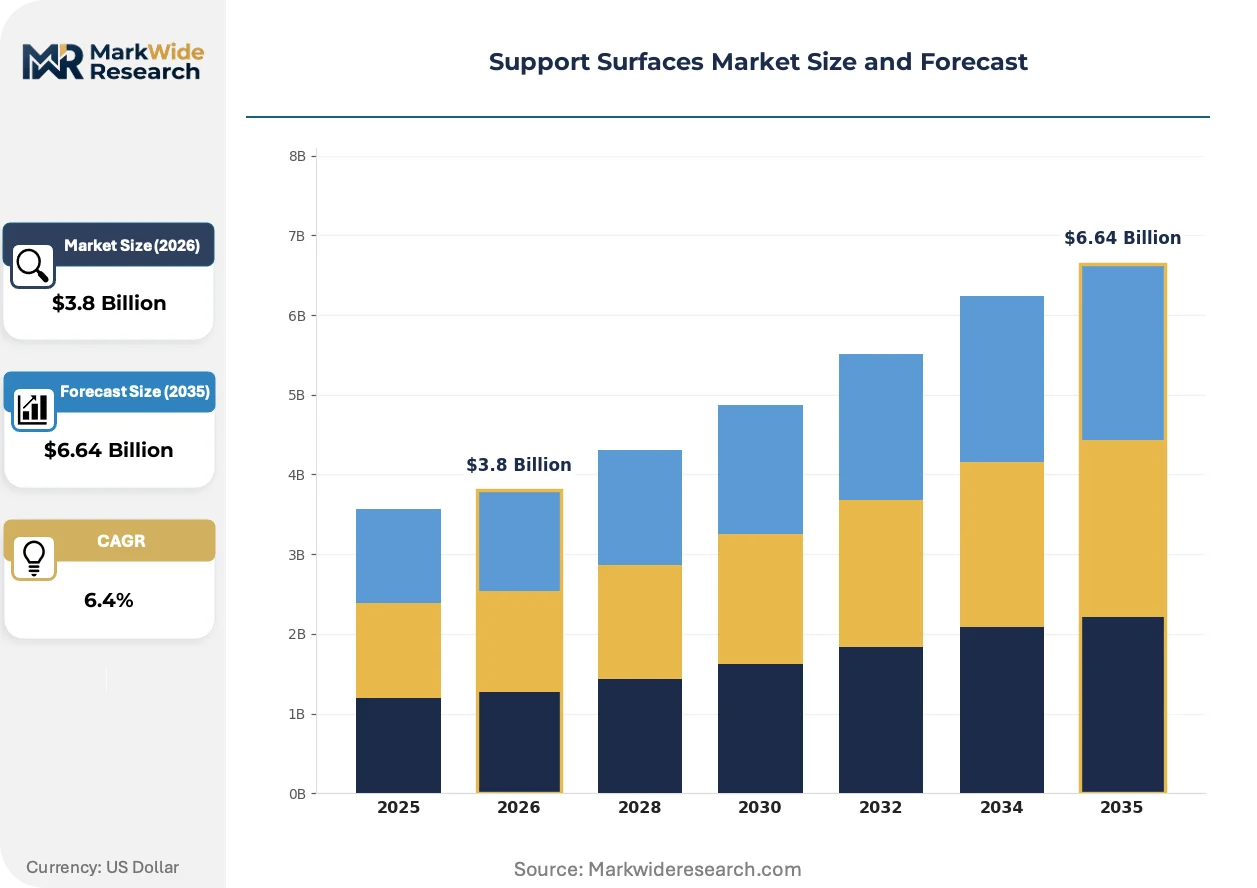
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static, Dynamic, Air, Foam End User: Hospitals, Long-Term Care Facilities, Home Care, Rehabilitation Centers Material: Polyurethane, Gel, Memory Foam, Latex Application: Pressure Ulcer Prevention, Post-Operative Care, Patient Comfort, Wound Healing |
| Companies Covered | Span-America Medical Systems, Inc., Agiliti Health, Inc., Hill-Rom Holdings, Inc., Invacare Corporation, Sizewise, Stryker Corporation, Butterfly Healthcare Pvt Ltd, Drive DeVilbiss Healthcare, ArjoHuntleigh, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Support Surfaces Market Trends and Innovations
Sensor fusion and materials science convergence is redefining how support surfaces interface with patient monitoring ecosystems, shifting value capture from hardware margins toward data-enabled service layers.
Capacitive pressure sensing arrays woven into mattress covers are miniaturizing from discrete pad attachments to fully integrated textile matrices. Critical care units in United States academic medical centers are piloting these systems for continuous tissue perfusion mapping. This miniaturization is compressing the boundary between surface manufacturers and remote patient monitoring platforms, forcing traditional suppliers to develop software competencies or cede data revenue streams.
EU MDR's 2021 reclassification of powered support surfaces as active therapeutic devices is mandating clinical performance studies for CE marking renewal. German and French notified bodies are rejecting substantial equivalence arguments for legacy products, compelling manufacturers to generate new clinical evidence. Long-term care operators in the Netherlands and Belgium are delaying procurement decisions pending clearer guidance on acceptable predicate devices.
Hospital procurement committees are unbundling mattress acquisition from full bed system contracts, creating direct purchasing relationships with specialized surface manufacturers. Group purchasing organizations in the United States are establishing dedicated pressure injury prevention categories with distinct clinical evaluation criteria. This disintermediation is most visible in the Southeast and Midwest regions where independent health systems retain greater contracting autonomy than integrated delivery networks.
Support Surfaces Market Segmentation
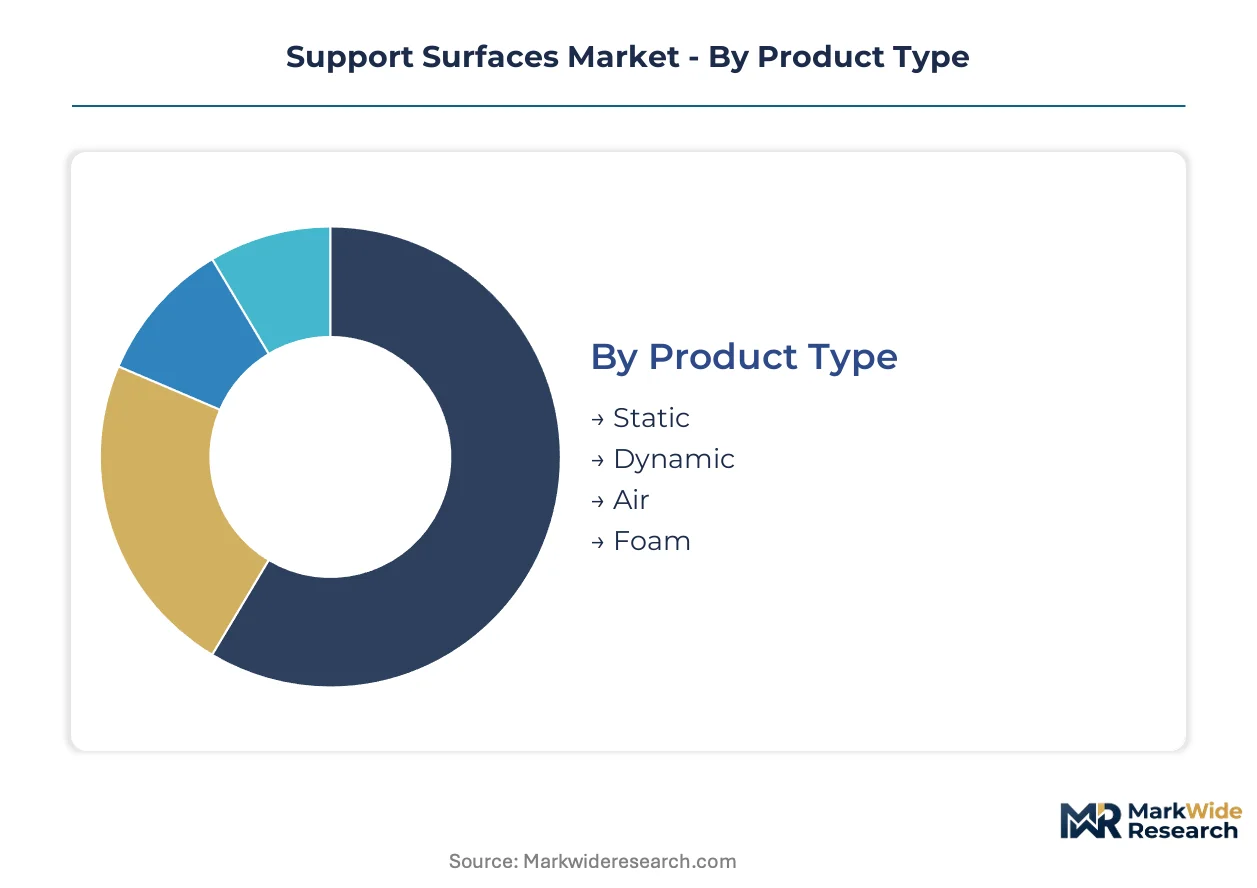
Support surfaces serve heterogeneous care environments with divergent performance requirements and capital constraints. Segmentation reveals how material science, reimbursement pathways, and clinical acuity reshape competitive positioning across product categories.
Product Type:
Domestic manufacturing concentrates static and foam variants in regional polymer hubs, while dynamic and air systems rely on German and Japanese component imports for precision pumps and sensor arrays.
- Static:Non-powered surfaces redistribute pressure through viscoelastic foam or gel bladders without mechanical intervention. German long-term care operators are accelerating replacement cycles under bundled reimbursement reforms for pressure ulcer prevention. Static commands the established base.
- Dynamic:Alternating pressure systems cycle air cell inflation to maintain tissue perfusion below 32 mmHg thresholds. United States intensive care units are mandating upgrades under CMS hospital-acquired condition penalties, compressing procurement timelines. The steepest expansion runs through Dynamic.
- Air:Low-air-loss platforms combine pressure redistribution with microclimate management through controlled air permeability. FDA Class II reclassification is elevating quality system documentation burdens for manufacturers seeking United States market entry.
- Foam:Zoned-density polyurethane constructions dominate bariatric applications through open-cell formulations that reduce peak interface pressures. Three German chemical suppliers control medical-grade viscoelastic foam production, creating allocation risk during demand surges.
Cost stratification separates premium dynamic systems from commoditized foam replacements, with rental economics favoring air platforms in acute care.
End User:
Procurement authority fragments across facility types, with hospitals consolidating through group purchasing organizations while long-term care operators negotiate directly with specialized surface manufacturers.
- Hospitals:Acute care settings prioritize dynamic surfaces with integrated pressure mapping for intensive care and surgical recovery units. Southeast and Midwest United States health systems are disintermediating full-bed vendors to establish direct mattress procurement relationships.
- Long-Term Care Facilities:Skilled nursing operators represent the volume anchor for static foam and basic alternating pressure systems. Netherlands and Belgian facilities are delaying procurement pending EU MDR clarity on acceptable predicate devices for CE marking renewal.
- Home Care:Medicare's emerging durable medical equipment codes for pressure ulcer prevention are opening rental-to-purchase conversion channels. Sensor-embedded surfaces with IoT telemetry are penetrating this segment for remote patient monitoring integration.
- Rehabilitation Centers:Post-acute settings demand bariatric-capable surfaces with rapid repositioning features for mobility restoration protocols. India's National Health Mission investments in tier-2 and tier-3 city infrastructure are creating first-mover opportunities for ISO 13485-certified suppliers with localized assembly.
Long-term care facilities anchor installed base volume. Home care is gaining share fastest as reimbursement shifts enable residential pressure injury prevention programs.
Material:
Supply concentration in German polymer production elevates input cost volatility, while biocompatibility testing bottlenecks constrain novel gel formulation launches.
- Polyurethane:Open-cell viscoelastic formulations with zoned density gradients dominate mid-tier acute care and long-term care specifications. ISO 10993-5 cytotoxicity studies face 6-9 month queue times at accredited laboratories, compressing product launch windows for modified chemistries.
- Gel:Bladder-based systems provide consistent pressure redistribution without power requirements, favoring home care and backup applications. EN 60601 electrical safety exemptions reduce regulatory burden compared with powered alternatives.
- Memory Foam:Temperature-responsive viscoelastic formulations adapt to patient contour for pressure redistribution in static applications. United States academic medical centers are piloting sensor-fusion covers with capacitive pressure mapping woven into textile matrices.
- Latex:Natural rubber compositions persist in niche allergy-tested segments despite synthetic substitution trends. Latex sensitization concerns restrict deployment in pediatric and immunocompromised patient populations.
Polyurethane holds the dominant share position. Gel is climbing the fastest as home care reimbursement expansion favors non-powered alternatives.
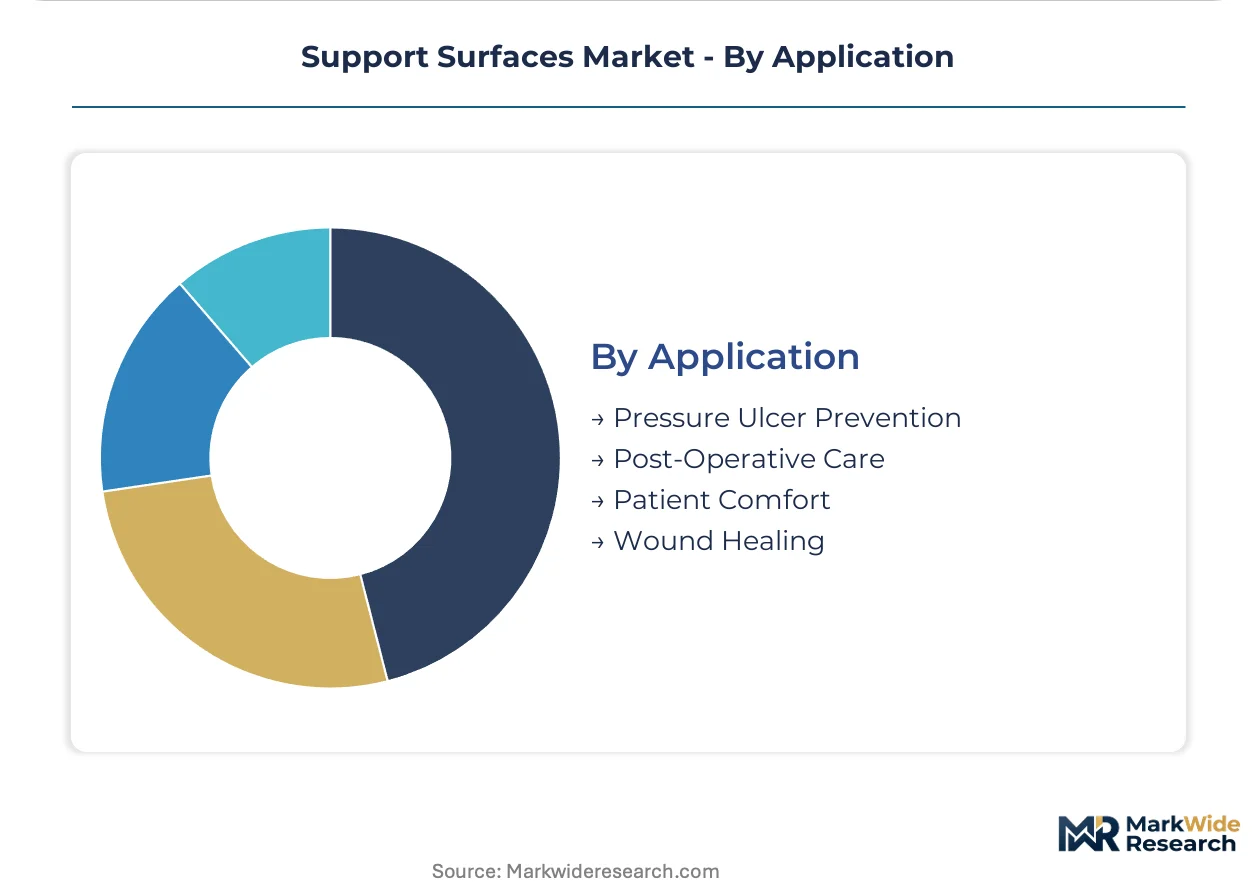
Application:
Clinical outcome requirements determine material selection and sensor integration intensity, with wound healing applications commanding premium pricing.
- Pressure Ulcer Prevention:Primary indication driving regulatory scrutiny and reimbursement code development across United States and German markets. CMS penalties for hospital-acquired conditions mandate surface upgrades in intensive care units.
- Post-Operative Care:Surgical recovery protocols prioritize microclimate management to reduce shear forces during immobilization. Hill-Rom Holdings sustains R&D intensity in this application through integrated bed-surface platforms.
- Patient Comfort:Non-clinical positioning applications in general medical-surgical wards favor lower-cost foam configurations. Procurement committees are unbundling comfort specifications from critical care surface contracts.
- Wound Healing:Advanced applications require negative pressure integration and continuous perfusion monitoring for Stage III and IV pressure injuries. Sensor-embedded surfaces with predictive repositioning alerts are penetrating this high-acuity segment.
Pressure ulcer prevention dominates procurement volume. Wound healing carries the steepest technology premium as sensor fusion redefines clinical value capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States acute care settings favor dynamic air systems with integrated pressure mapping, while German long-term care operators prioritize static foam replacements under bundled reimbursement. India's emerging skilled nursing infrastructure purchases basic alternating pressure surfaces from localized assembly operations.
United States
CMS hospital-acquired condition penalties mandate surface upgrades across intensive care units and surgical recovery wards. The FDA's Class II reclassification of powered air surfaces elevates quality system documentation burdens for market entrants. Southeast and Midwest health systems are disintermediating full-bed vendors to establish direct mattress procurement relationships with specialized manufacturers.
Germany
Bundled reimbursement reforms for pressure ulcer prevention in skilled nursing facilities accelerate replacement cycles for legacy foam mattresses. The EU MDR's enhanced clinical evidence requirements extend registration timelines for powered support surfaces seeking CE marking renewal. Medical-grade viscoelastic foam production concentrates among chemical suppliers in the North Rhine-Westphalia polymer corridor, creating allocation risk during demand surges.
India
National Health Mission investments in tier-2 and tier-3 city long-term care infrastructure expand skilled nursing bed counts. The Central Drugs Standard Control Organization regulates powered therapeutic surfaces as medical devices, requiring ISO 13485 certification for import and distribution. Maharashtra and Karnataka host emerging assembly operations for ISO-certified manufacturers targeting price-sensitive procurement committees.
Netherlands
Long-term care operators delay capital allocation pending clarity on acceptable predicate devices for EU MDR CE marking renewal of legacy powered surfaces. The Health and Youth Care Inspectorate enforces pressure injury prevention protocols in nursing homes, driving specification upgrades. Eindhoven-region technical universities collaborate with surface manufacturers on sensor-embedded textile development for remote patient monitoring integration.
Japan
Aging demographics expand demand for home care pressure injury prevention equipment as residential care shifts away from institutional settings. The Pharmaceuticals and Medical Devices Agency maintains stringent electrical safety standards under EN 60601 harmonization for powered therapeutic devices. Osaka-based medical device distributors concentrate import relationships with European and North American surface manufacturers.
Support Surfaces Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding acute care contracting through full-bed platform integration while specialists capture long-term care volume via direct mattress procurement. The competitive terrain splits between capital-intensive dynamic system fabricators and foam conversion specialists serving replacement markets. Dominant competitive moves include sensor-embedded surface development for remote monitoring integration and backward integration into medical-grade polymer supply chains.
Among United States-based diversified health technology corporations, Stryker Corporation and Hill-Rom Holdings, Inc. occupy positions exemplifying the integrated platform archetype, while ArjoHuntleigh represents the European specialist tier focused on bariatric and long-term care configurations. These three entities anchor the competitive structure through divergent channel strategies rather than overlapping segment contention.
| Leading Market Players |
|---|
| Span-America Medical Systems, Inc. |
| Agiliti Health, Inc. |
| Hill-Rom Holdings, Inc. |
| Invacare Corporation |
| Sizewise |
| Stryker Corporation |
| Butterfly Healthcare Pvt Ltd |
| Drive DeVilbiss Healthcare |
| ArjoHuntleigh |
| Others |
Pricing and Supply Chain Analysis
Six-to-nine-month queue times for ISO 10993 biocompatibility studies at accredited laboratories concentrate pricing power among manufacturers with pre-cleared material libraries and captive testing relationships, while compressing launch windows for competitors dependent on third-party validation.
Pricing Analysis
Long-term rental contracts dominate acute care procurement, with United States hospitals locking in multi-year fleet agreements through group purchasing organizations. Price differentiation rests on FDA Class II certification tier and integrated pressure-mapping capability, with sensor-embedded platforms commanding premium positioning. Cost compression in static foam tiers is intensifying as German chemical suppliers ration medical-grade viscoelastic allocations during demand surges. Long-term care facilities exhibit highest price sensitivity, while academic medical centers prioritize clinical performance over unit economics.
Supply Chain Analysis
North Rhine-Westphalia polymer corridor chokepoints in medical-grade viscoelastic foam production tether global supply to three German chemical suppliers. Component sourcing draws from Japanese precision pump manufacturers for dynamic air systems and Taiwanese sensor array fabricators for pressure-mapping textiles. Single-source vulnerability concentrates in medical-grade polyurethane feedstock, where demand spikes trigger allocation protocols. Distribution runs through specialized durable medical equipment distributors in developed markets and hospital procurement committees in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's Class II reclassification of powered air surfaces is compressing margins for mid-tier suppliers while erecting compliance moats around established platforms with pre-cleared quality management systems.
For Market Incumbents: Consolidate backward integration into medical-grade polymer supply chains to secure allocation priority during German supplier rationing. Deepen hospital system partnerships through integrated bed-surface platforms that lock out modular competitors. Sensor-embedded surface development represents the critical R&D lever for capturing data-enabled service revenue streams before remote patient monitoring platforms disintermediate hardware margins. For New Entrants and Emerging Players: Anchor in India's tier-2 and tier-3 city skilled nursing buildout, where National Health Mission investments outpace ISO 13485-certified local supply. Home care reimbursement expansion under Medicare's emerging durable medical equipment codes offers the most penetrable white-space for rental-to-purchase conversion plays. A direct-to-facility sales model bypassing legacy distributor networks accelerates initial traction. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sensor-embedded surface development, favoring platforms with existing software competencies over pure hardware fabricators. The viable acquisition window spans five to ten years as EU MDR documentation burdens force consolidation among dual-market manufacturers. Target mid-tier specialists with CE marking renewal pipelines and established German polymer supplier relationships. The signal to watch is CMS reimbursement code finalization for home care pressure ulcer prevention, which would rechannel capital allocation toward residential monitoring platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Embedded Surface Development | Integration with IoT telemetry platforms captures data revenue streams from United States academic medical center pilots. |
| Backward Integration into Polymer Supply | In-house medical-grade viscoelastic production insulates against German chemical supplier allocation rationing during demand surges. |
| CE Marking Renewal Investment | EU MDR clinical evidence requirements extend registration timelines, creating compliance moats for manufacturers with predicate device libraries. |
| Home Care Reimbursement Strategy | Medicare durable medical equipment code positioning enables rental-to-purchase conversion in residential pressure injury prevention. |
| Hospital System Partnership | Direct procurement relationships with Southeast and Midwest United States health systems disintermediate full-bed vendor bundling. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across wound-care clinicians, hospital purchasing committee members, biomedical engineers, group purchasing organization contract managers, and long-term care facility operators. Secondary validation drew from FDA 510(k) filings, EU MDR notified body guidance documents, CMS Medicare reimbursement code databases, and hospital procurement records. Bottom-up unit economics and top-down market sizing were triangulated to anchor volume and value estimates.
Across the analysis window, the analytical framework modeled product type, end user facility category, material composition, and clinical application intensity. CAGRs were derived from replacement cycle dynamics, reimbursement pathway evolution, and installed base expansion in aging demographics. Forecast inputs incorporated EU MDR registration timeline extensions and German bundled reimbursement reform implementation pace.
Material uncertainties — regulatory reclassification delays, polymer supply allocation disruptions, and wound-care nursing certification bottlenecks — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as FDA guidance on powered air surface clinical validation protocols evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Lancing Devices and Lancets Market
Medical Devices
Unilateral Biportal Endoscopy Market
Medical Devices
Battery-Operated Lactate Meter Market
Medical Devices
Elastomeric Infusion Pump Market
Medical Devices
Hydrogen Inhalers Market
Medical Devices
Smart Lenses Market
Medical Devices
Laparoscopic Electrodes Market
Medical Devices
Asia-Pacific Radiotherapy Market
Medical Devices
Middle East and Africa Single-Use Medical Device Reprocessing Market
Medical Devices
Japan Minimally Invasive Surgery Devices Market
Medical Devices
Global Female Stress Urinary Incontinence Treatment Devices Market
Medical Devices
Wireless ECG Devices Market
Medical Devices
Lacrimal Duct Stent Tube Market
Medical Devices
Autotransfusion Devices Market
Medical Devices
Vortex Mixer Market
Medical Devices
Global Capnography Market