
 Venous Diseases Treatment Market | 2026-2036
Venous Diseases Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Venous Diseases Treatment Market Outlook
Image-guided minimally invasive ablation is reconfiguring how venous interventions are planned, executed, and reimbursed across outpatient settings. Medtronic leverages its endovenous catheter portfolio to sustain leadership in thermal ablation systems. Boston Scientific Corporation anchors its position through radiofrequency platform specialization that competes directly with laser-based alternatives. Alma Lasers differentiates by occupying the non-invasive aesthetic segment with dual-wavelength systems for spider vein management.
Venous diseases treatment encompasses medical and interventional modalities designed to restore venous valve competence, eliminate reflux, and resolve thrombotic obstruction through mechanical, thermal, chemical, or photonic mechanisms. Endovenous laser ablation typically delivers energy at 810–1470 nm wavelengths to achieve vein wall contraction and fibrotic occlusion, while sclerotherapy employs detergent or osmotic sclerosants to induce endothelial damage and vessel sclerosis. Compression stockings represent the mature conservative foundation with stable reimbursement but compressed margins, whereas laser therapy and minimally invasive delivery modes capture faster expansion as ambulatory surgical centers and specialty clinics shift procedures away from hospital inpatient settings.
FDA 510(k) clearances govern endovenous laser and radiofrequency device entry in the United States, while the EU Medical Device Regulation imposes enhanced clinical evidence requirements for Class IIa and IIb thermal ablation systems in Europe. Japan's PMDA evaluates venous intervention devices under pharmaceutical and medical device agency pathways that extend approval timelines relative to US benchmarks. Stakeholders must monitor how reimbursement parity between hospital outpatient departments and freestanding ambulatory surgical centers reshapes site-of-service economics and capital deployment priorities.
Market Dynamics
Hospital systems are aggressively expanding outpatient venous procedure capacity, redirecting capital from inpatient surgical suites to ambulatory surgical centers where thermal ablation and sclerotherapy generate superior reimbursement economics per square foot.
Growth Catalysts
- Ambulatory Surgical Center Reimbursement Parity:Medicare's site-neutral payment policies now align HOPD and ASC rates for endovenous ablation, accelerating procedural migration to freestanding facilities in the United States.
- Radiofrequency Catheter Miniaturization:Next-generation 7-French delivery systems enable office-based treatment without tumescent anesthesia, collapsing the clinical infrastructure required for thermal ablation.
- Germany's Statutory Health Insurance Reform:The G-BA's expanded coverage for minimally invasive varicose vein treatment removed prior conservative therapy mandates, unlocking procedural volume growth.
Market Restraints
- FDA 510(k) Clinical Evidence Requirements:Thermal ablation device sponsors must demonstrate non-inferiority to predicate devices through prospective trials, extending commercialization timelines by 18-24 months.
- Single-Source Laser Fiber Supply:High-purity silica fiber production concentrates in Japanese and German specialty manufacturers, exposing device OEMs to input cost volatility and allocation risk.
- Non-Thermal Ablation Substitution:Cyanoacrylate adhesive closure and mechanochemical ablation eliminate tumescent anesthesia requirements, threatening laser and radiofrequency system utilization in select patient segments.
Strategic Opportunities
- Japan's Aging Demographic Tailwind:PMDA's streamlined Class II device review pathway for thermal ablation systems targets the 65+ population where chronic venous insufficiency prevalence exceeds 40 percent.
- Home-Based Compression Monitoring:Integration of pressure-sensing textiles with remote patient monitoring platforms enables adherence tracking and reimbursement capture outside clinical settings.
- EU MDR Clinical Data Leverage:Post-market clinical follow-up requirements for Class IIb thermal devices create barriers for new entrants, rewarding incumbent sponsors with established PMCF databases.
Industry Challenges
- Phlebology Training Pipeline Constraints:The Society for Vascular Surgery's fellowship match data shows declining vascular surgery applicants, constraining operator supply for catheter-based interventions.
- Capital Equipment Refresh Cycles:Laser generator and radiofrequency console replacement timelines extend to 7-10 years as ASCs prioritize disposable catheter revenue over hardware upgrades.
- EU MDR Technical Documentation Burden:Legacy device dossiers require substantial clinical evidence supplementation to maintain CE marking, diverting regulatory resources from new product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Venous Diseases Treatment Market |
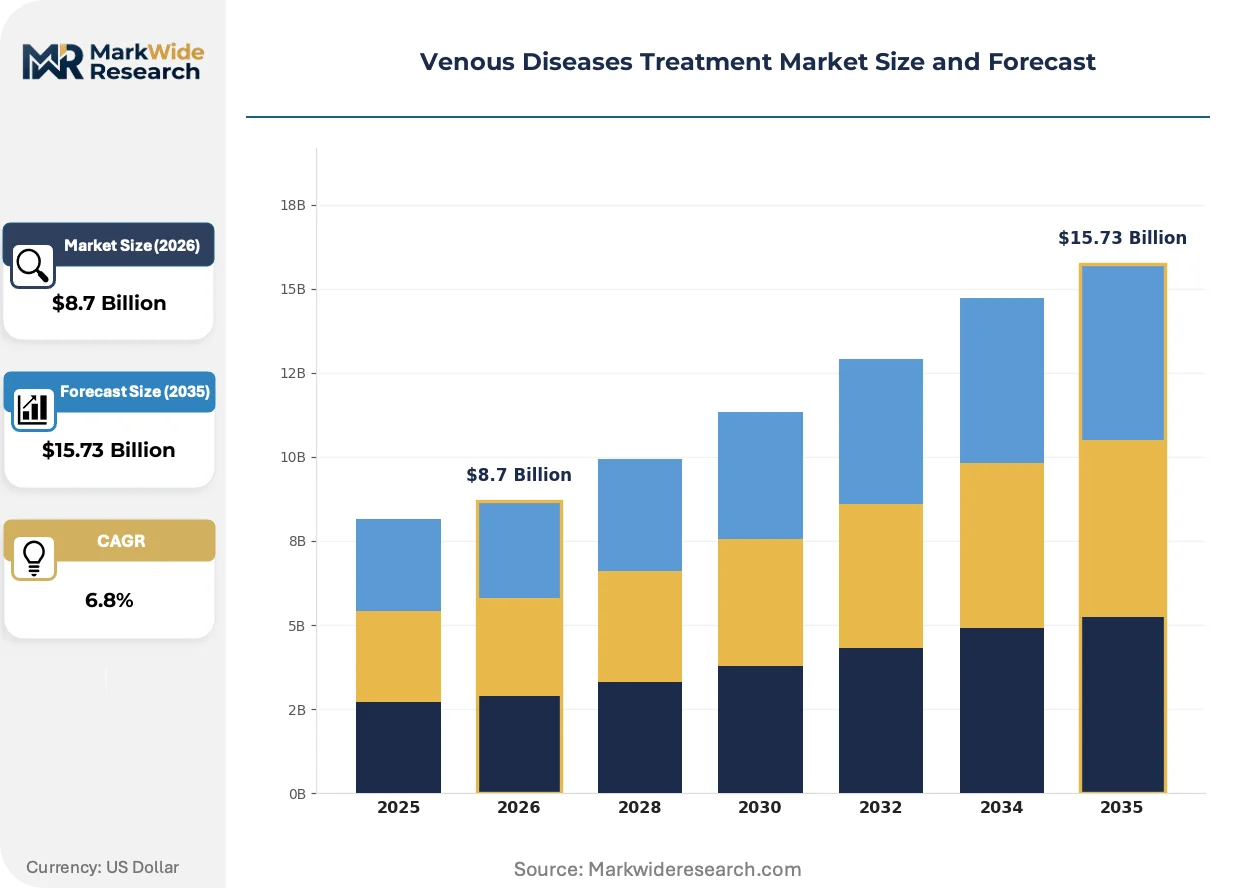
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compression Stockings, Varicose Vein Treatments, Sclerotherapy, Laser Therapy Application: Peripheral Venous Disease, Deep Vein Thrombosis, Chronic Venous Insufficiency, Spider Veins End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Homecare Delivery Mode: Invasive, Non-Invasive, Minimally Invasive, Outpatient |
| Companies Covered | Medtronic, Boston Scientific Corporation, AngioDynamics, Biolitec AG, Alma Lasers, Lumenis Be Ltd., Quanta System, Candela Medical, Merit Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Venous Diseases Treatment Market Strategic Shifts
Image-guided intervention is compressing the gap between diagnosis and therapy, enabling same-visit treatment planning that collapses traditional multi-appointment care pathways for venous disease.
Endovenous laser technology is migrating from hospital-based surgical suites to office-based laboratories. Ambulatory phlebology practices in the United States and Germany now deploy compact 1470 nm diode systems requiring minimal facility infrastructure. This technology is migrating from capital-intensive settings to leased equipment models that convert fixed costs to per-procedure expenses, compressing the minimum viable scale for independent vein clinics.
The EU Medical Device Regulation's enhanced clinical evidence requirements for Class IIa and IIb thermal ablation systems are reshaping competitive entry. Sponsors must now conduct prospective PMCF studies rather than relying on literature-based equivalence, extending time-to-market for new laser wavelengths and catheter designs. German and French notified bodies are applying the most stringent interpretation of MDR Annex XIV, favoring established manufacturers with existing clinical databases over emerging competitors.
Patient selection criteria are tightening as payers demand documented saphenous reflux before authorizing thermal ablation. United States commercial insurers now require duplex ultrasound reports with specific reflux duration thresholds, shifting diagnostic burden to accredited vascular laboratories. This behavioral shift is most visible in Medicare Advantage plans, where prior authorization denial rates for cosmetic vein procedures have risen substantially, forcing practices to restructure intake workflows around documentation completeness.
Venous Diseases Treatment Market Segmentation
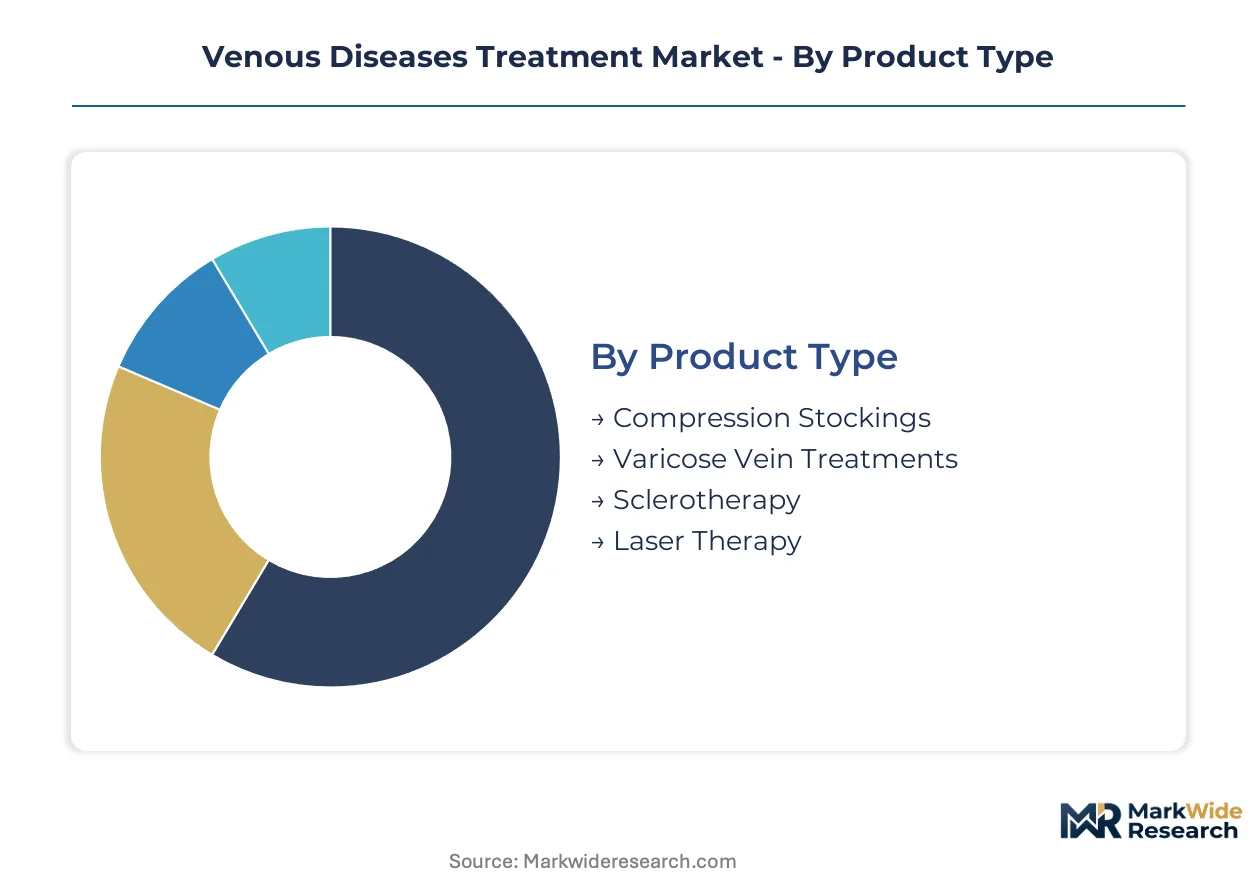
Venous disease treatment segments exhibit divergent capital intensity and reimbursement velocity. Product categories span disposable consumables with rapid turnover to durable laser platforms with decade-long replacement cycles. Understanding these temporal patterns illuminates where manufacturers should deploy R&D resources versus where service revenue models dominate.
Product Type:
Cycle times vary dramatically across this category, from compression garments requiring quarterly replacement to laser generators lasting seven to ten years. This temporal spread creates fundamentally different cash flow profiles and customer lock-in mechanisms.
- Compression Stockings:Gradient compression textiles deliver 20-30 mmHg pressure through elastic fiber blends. Demand concentrates in Germany's statutory health insurance system where conservative therapy mandates preceded interventional authorization. The segment's quarterly replacement cycle generates predictable recurring revenue but compressed per-unit margins.
- Laser Therapy:Diode-based endovenous systems operate at 810-1470 nm wavelengths to achieve thermal vein occlusion. Demand concentrates in United States ambulatory surgical centers where site-neutral Medicare reimbursement accelerated capital deployment. The seven-year equipment refresh cycle forces manufacturers toward disposable fiber revenue models.
- Varicose Vein Treatments:Mechanical and thermal interventions targeting saphenous reflux.
- Sclerotherapy:Detergent and osmotic sclerosants inducing endothelial damage for spider vein management.
Compression Stockings anchors the volume base while Laser Therapy gains share at the steepest rate.
Application:
Clinical acuity tiers separate emergency thrombotic interventions from elective cosmetic procedures, with reimbursement intensity scaling to disease severity and complication risk.
- Chronic Venous Insufficiency:Progressive valve incompetence causing edema, skin changes, and ulceration. Demand concentrates in Japan's aging prefectures where PMDA streamlined Class II device reviews target the 65+ demographic. Ulcer care costs drive payer preference for early interventional treatment.
- Deep Vein Thrombosis:Acute thrombotic obstruction requiring anticoagulation and possible mechanical thrombectomy. Demand concentrates in United States hospital emergency departments where CMS severity-adjusted diagnosis-related groups reward rapid intervention. The acute presentation compresses device procurement cycles to days.
- Peripheral Venous Disease:Superficial venous reflux and varicosity without deep system involvement.
- Spider Veins:Telangiectatic cosmetic concerns treated through sclerotherapy or surface laser.
Chronic Venous Insufficiency commands the reimbursement premium while Spider Veins expands most quickly through aesthetic channel growth.
End User:
Site-of-service economics separate capital-intensive hospital infrastructure from lean ambulatory models, with reimbursement parity reshaping where procedures physically occur.
- Ambulatory Surgical Centers:Freestanding facilities optimized for same-day thermal ablation and sclerotherapy. United States Medicare's site-neutral payment alignment with hospital outpatient departments accelerated procedural migration. Per-square-foot revenue economics favor these settings for high-volume venous work.
- Specialty Clinics:Dedicated phlebology practices with leased laser equipment converting fixed costs to per-procedure expenses. Germany's G-BA reform removing conservative therapy mandates unlocked independent clinic expansion. Minimal facility infrastructure requirements collapse barriers to entry.
- Hospitals:Inpatient and hospital-based outpatient surgical suites with full emergency backup capacity.
- Homecare:Compression therapy adherence monitoring and wound care management outside clinical settings.
Hospitals retain the highest-acuity caseload while Ambulatory Surgical Centers captures volume at the steepest expansion trajectory.
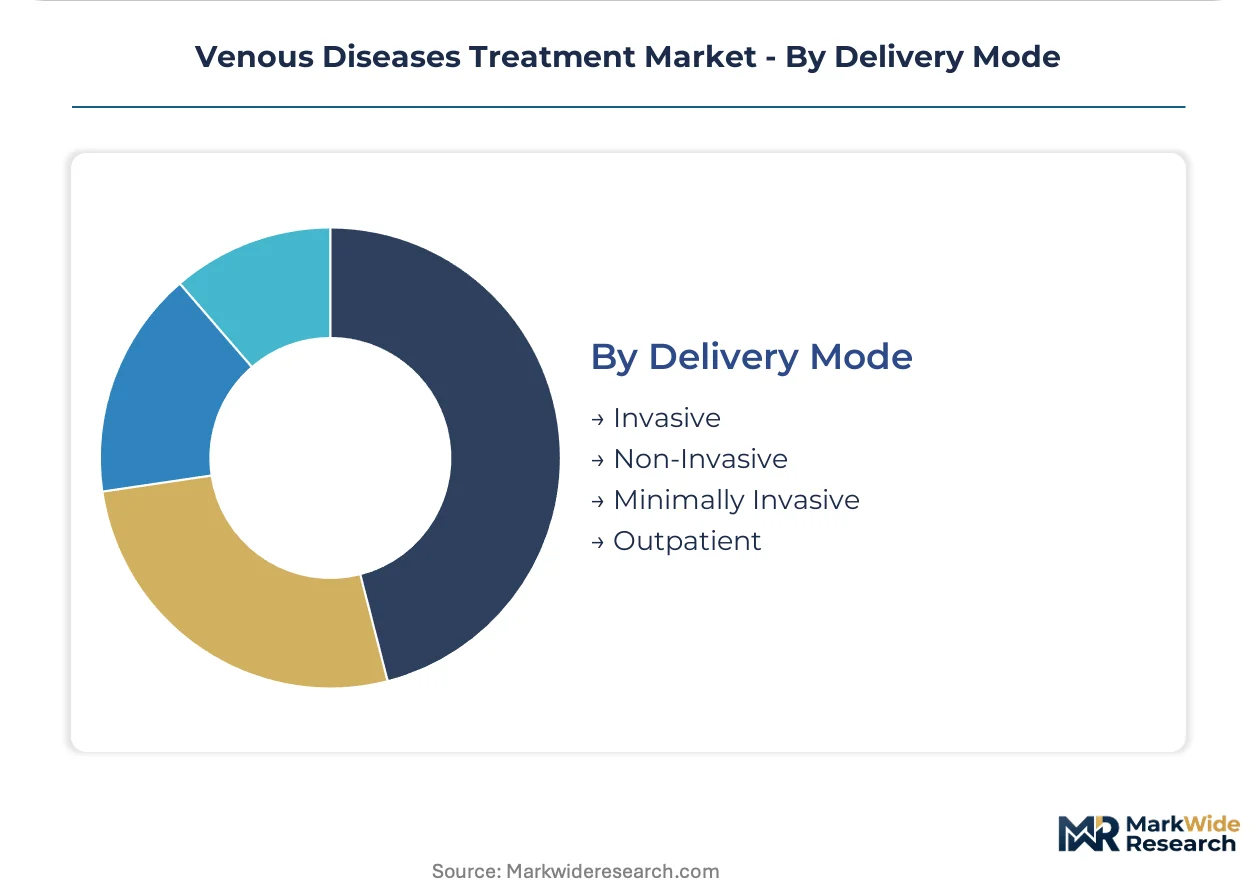
Delivery Mode:
Anesthesia requirements and facility standards stratify this category, with tumescent-free modalities collapsing the clinical infrastructure needed for treatment.
- Minimally Invasive:Catheter-based thermal ablation with tumescent anesthesia and duplex guidance. United States commercial insurers now mandate documented saphenous reflux with specific duration thresholds prior to authorization. Prior authorization denial rates in Medicare Advantage plans have forced workflow restructuring around documentation completeness.
- Non-Invasive:External laser and compression-based therapies without skin penetration. Surface treatments for spider veins occupy the aesthetic segment where dual-wavelength systems differentiate through pain reduction. Patient self-pay dynamics insulate this mode from payer authorization friction.
- Invasive:Surgical ligation, stripping, and open thrombectomy procedures.
- Outpatient:Same-day discharge protocols across intervention types regardless of technical approach.
Invasive procedures anchor the residual surgical volume while Non-Invasive modalities climb the fastest through cosmetic channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The venous diseases treatment market exhibits pronounced trade asymmetry, with Germany and the United States serving as net exporters of thermal ablation systems while Japan and China remain import-dependent for high-purity laser fiber components.
United States
Medicare's site-neutral payment alignment between hospital outpatient departments and ambulatory surgical centers has accelerated procedural migration to freestanding facilities. FDA 510(k) clearances govern endovenous laser and radiofrequency device entry, extending commercialization timelines through prospective non-inferiority trials. The Dallas-Fort Worth metroplex anchors independent vein clinic expansion where leased 1470 nm diode systems convert fixed costs to per-procedure expenses.
Germany
The G-BA's statutory health insurance reform removed prior conservative therapy mandates for minimally invasive varicose vein treatment, unlocking procedural volume growth. EU MDR enhanced clinical evidence requirements for Class IIa and Class IIb thermal ablation systems impose prospective post-market clinical follow-up studies. The Rhine-Ruhr metropolitan region concentrates outpatient phlebology practices capitalizing on reimbursement clarity.
Japan
PMDA's streamlined Class II device review pathway targets the 65-plus population where chronic venous insufficiency prevalence exceeds 40 percent. Japan's Pharmaceutical and Medical Device Agency evaluates venous intervention devices under pathways extending approval timelines relative to US benchmarks. Tokyo and Osaka prefectures concentrate aging demographics driving demand for catheter-based thermal ablation.
China
NMPA medical device registration requirements for imported thermal ablation systems create regulatory friction for foreign OEMs seeking market entry. The country's national pharmaceutical regulator imposes clinical trial obligations for Class III venous intervention devices. The Yangtze River Delta region, particularly Shanghai and Suzhou, hosts domestic manufacturing initiatives for compression textile production.
United Kingdom
NHS England's commissioning frameworks for varicose vein treatment restrict interventional procedures to patients with documented venous reflux and skin changes. The Medicines and Healthcare products Regulatory Agency applies EU MDR-equivalent standards through retained law post-Brexit. London and the Southeast concentrate private ambulatory phlebology capacity serving self-pay cosmetic segments.
Venous Diseases Treatment Market Competitive Environment
On the supply side, the industry is consolidating around diversified medtech conglomerates with endovenous catheter portfolios, while specialized laser manufacturers occupy distinct aesthetic and thermal ablation niches. Three strategic archetypes dominate: integrated surgical device conglomerates with multi-modality vascular platforms, pure-play energy-based device specialists with wavelength-specific expertise, and aesthetic medicine providers with surface laser systems. Competitive positioning depends on disposable catheter revenue models versus capital equipment leasing, alongside regulatory dossier depth for EU MDR compliance.
Within the integrated surgical device tier, Medtronic and Boston Scientific Corporation exemplify conglomerate-scale positioning across thermal ablation modalities. Alma Lasers occupies a distinct position within the aesthetic energy device segment. These three entities anchor the competitive spectrum from hospital-based interventional systems to office-based cosmetic applications, with each representing divergent capital intensity and reimbursement exposure profiles.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| AngioDynamics |
| Biolitec AG |
| Alma Lasers |
| Lumenis Be Ltd. |
| Quanta System |
| Candela Medical |
| Merit Medical Systems |
| Others |
Value Chain & Pricing Dynamics
The Yokohama-Hamburg maritime corridor channels high-purity silica fiber from Japanese specialty manufacturers to German thermal ablation device assemblers, with freight cost volatility amplifying price differentiation between premium laser systems and standard radiofrequency consoles. This logistics artery concentrates supply-side leverage among fiber producers while forcing OEMs to absorb margin compression or pass through costs to ambulatory surgical centers.
Pricing Analysis
Industrial OEM buyers anchor a tiered pricing structure across premium, standard, and economy laser generator tiers. Price differentiation hinges on wavelength precision certification and disposable catheter bundling intensity. Cost compression in the standard tier is intensifying because Japanese fiber allocation constraints squeeze mid-range system margins. Hospital purchasing committees exhibit highest price sensitivity, whereas independent vein clinics prioritize per-procedure cost predictability over capital outlay.
Supply Chain Analysis
Extended payment terms from Japanese fiber suppliers now stretch to 120 days, straining working capital for German and United States device manufacturers. Geographic supply concentrates in Japan for silica fiber, Germany for precision optics assembly, and the United States for RF generator components. Raw material dependencies center on high-purity quartz, rare-earth dopants, and medical-grade catheter polymers. Single-source vulnerability in Japanese fiber production exposes OEMs to allocation risk. Distribution runs through specialized medical device distributors serving hospital systems and ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The venous diseases treatment market functions as a service-attach opportunity where disposable catheter revenue and maintenance contracts expand faster than laser generator hardware sales. Recurring revenue from fiber replacements and generator calibration services now determines customer lifetime value calculations.
For Market Incumbents: Pre-empt cyanoacrylate adhesive substitution by accelerating next-generation 7-French radiofrequency catheter launches that eliminate tumescent anesthesia requirements. Secure backward integration into high-purity silica fiber sourcing through long-term offtake agreements with Japanese specialty manufacturers. Defend installed base lock-in through software companion development that integrates duplex ultrasound guidance with thermal ablation consoles.
For New Entrants and Emerging Players: Japan's prefectural aging clusters outside Tokyo and Osaka represent underpenetrated demand where PMDA's streamlined Class II pathway lowers regulatory barriers. Target independent phlebology practices in Germany's Rhine-Ruhr region with leased equipment models converting fixed costs to per-procedure expenses. Pursue white-label manufacturing partnerships with established fiber suppliers to bypass capital-intensive generator development.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medtech conglomerates seeking to divest non-core venous intervention portfolios amid EU MDR compliance cost escalation. Long-term viability hinges on disposable revenue attachment rates rather than hardware shipment volume. Monitor PMDA approval velocity for thermal ablation systems as inflection indicator for Japanese market access timing.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates commercialization timelines for next-generation radiofrequency catheters in United States ambulatory settings. |
| CE Marking Pathway | EU MDR compliance unlocks German statutory health insurance reimbursement for minimally invasive varicose vein procedures. |
| Hospital System Partnership | GPO contracts with United States hospital networks secure thermal ablation volume commitments and catheter pull-through. |
| Software Companion Development | Duplex ultrasound integration platforms differentiate thermal ablation consoles from non-thermal adhesive alternatives. |
| Reimbursement Strategy | Medicare site-neutral parity alignment maximizes ambulatory surgical center procedural economics per square foot. |
Study Parameters
The analysis maps thermal ablation systems, sclerotherapy agents, compression textiles, and diagnostic imaging modalities, each validated through vascular surgeons, ambulatory surgical center administrators, biomedical engineers, and GPO contracts managers. Primary interviews with these stakeholders combined secondary validation through FDA 510(k) filings, PMDA approval databases, CMS Medicare reimbursement schedules, and EU MDR notified body guidance documents. Bottom-up procedure volume estimates triangulated against top-down manufacturer shipment data.
Assumptions held reimbursement parity between hospital outpatient departments and ambulatory surgical centers fixed across the projection horizon, while varying regulatory approval timelines by geography. Segmentation dimensions modeled include product type, application severity tier, end-user site of service, and delivery mode anesthesia requirements. CAGRs derived from procedure volume growth trajectories weighted by disposable versus capital equipment revenue mix. Forecast inputs incorporated aging demographic projections and statutory health insurance reform implementation schedules.
Practitioners should monitor FDA 510(k) clinical evidence requirement intensification and EU MDR post-market clinical follow-up study obligations for early signals of competitive entry barrier elevation. Forecasts reflect these documented assumptions; macroeconomic contraction, regulatory timeline extension, or non-thermal ablation technology breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Robotic Surgery System Haptic Feedback Test Platforms Market
Diagnostic and Therapeutic Devices
Vacuum Therapy Devices Market
Diagnostic and Therapeutic Devices
Therapeutic Robots Market
Diagnostic and Therapeutic Devices
Magnetic Therapy Devices Market
Diagnostic and Therapeutic Devices
One-Step ELISA Market
Diagnostic and Therapeutic Devices
Dental Surgical and Diagnostic Devices Market
Diagnostic and Therapeutic Devices
Phototherapy Device Market
Diagnostic and Therapeutic Devices
Electroceuticals Bioelectric Medicine Market
Diagnostic and Therapeutic Devices
Therapeutic Support Surface Market
Diagnostic and Therapeutic Devices
Global Therapeutic Plasma Exchange Market
Diagnostic and Therapeutic Devices
Global Acute Ischemic Stroke Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Automated Immunoassay Analyzers Market
Diagnostic and Therapeutic Devices
Germany Smart Healthcare Market
Diagnostic and Therapeutic Devices
Disposable Negative Pressure Wound Therapy Devices Market
Diagnostic and Therapeutic Devices
Global Smart Healthcare Products Market
Diagnostic and Therapeutic Devices
Acupuncture Needles Market