
 Global Smart Inhaler Technology Market | 2026-2036
Global Smart Inhaler Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Inhaler Technology Market Foresight
Sensor-to-cloud integration is fragmenting traditional inhaler architectures into modular hardware-software ecosystems. Propeller Health leverages Bluetooth-enabled dose tracking to anchor its position in asthma management platforms. Adherium competes through medication adherence analytics that extend provider oversight into home care settings.
Smart inhaler technology encompasses drug delivery devices embedded with electronic sensors, wireless connectivity modules, and data processing algorithms that capture, transmit, and analyze patient inhalation patterns and compliance metrics. These systems typically incorporate pressure transducers, accelerometers, and flow sensors with detection thresholds of 10-30 liters per minute to verify proper actuation technique and timing. Metered dose inhalers with integrated dose counters currently lead product type deployment due to their compatibility with existing corticosteroid and bronchodilator formulations. Bluetooth connectivity dominates the technology layer as the lowest-power wireless protocol for continuous pairing with patient smartphones. Home care represents the fastest-expanding end user segment as reimbursement shifts favor decentralized respiratory disease management.
The FDA regulates smart inhalers as combination products requiring both device and software validation, while the EU Medical Device Regulation mandates clinical evidence for connectivity-enabled claims. Japan's PMDA has accelerated review timelines for digital therapeutics paired with inhalable biologics. Stakeholders must monitor how divergent cybersecurity standards across these agencies reshape development roadmaps and market access timelines.
Market Dynamics
Sensor-to-cloud modularization is fragmenting traditional inhaler architectures into hardware-software ecosystems, forcing manufacturers to validate device and software components separately under divergent regulatory frameworks across the US, EU, and Japan.
Growth Catalysts
- Remote patient monitoring reimbursement:CMS and Germany's G-BA have established billing codes for connected respiratory devices, accelerating pulmonology clinic procurement cycles in both markets.
- MDR connectivity-enabled claims pathway:The EU Medical Device Regulation's streamlined evidence requirements for digital health features is reducing time-to-market for sensor-integrated inhalers seeking CE marking.
- Home care decentralization:Post-acute care networks in Japan and the United States are deploying Bluetooth-enabled inhalers to reduce hospital readmission penalties and shift chronic disease management into residential settings.
Market Restraints
- Silicon supply concentration:MEMS pressure sensor fabrication relies on Taiwanese and South Korean foundry capacity, creating input bottlenecks for flow detection modules.
- FDA combination product validation:The requirement for simultaneous device and software validation under 21 CFR 3.2(e) extends development timelines and raises regulatory capital requirements.
- Smartphone dependency:Bluetooth Low Energy pairing requirements exclude elderly patient populations with limited iOS or Android device penetration, compressing addressable market scope in aging demographics.
Strategic Opportunities
- Pediatric asthma management:Unmet need in school-based care settings across Germany and Japan creates white space for tamper-resistant dose-tracking devices with parental notification features.
- Biologics-inhaler convergence:PMDA's accelerated review pathway for digital therapeutics paired with inhalable monoclonal antibodies enables first-mover positioning in severe asthma and COPD segments.
- Pharmacy channel integration:US specialty pharmacies are building remote monitoring capabilities, creating direct-to-patient distribution bypassing traditional device sales through hospital procurement.
Industry Challenges
- Embedded systems talent scarcity:Firmware engineering for ultra-low-power medical sensors requires specialized expertise concentrated in Boston, Tel Aviv, and Tokyo metro clusters.
- Legacy EHR integration:HL7 FHIR connectivity with Epic and Cerner systems demands custom API development, extending deployment timelines for health system contracts.
- Cybersecurity certification divergence:FDA premarket guidance, EU MDR Annex I, and Japan's PMDA cybersecurity notices impose non-overlapping testing requirements, fragmenting quality assurance protocols.
Report Scope
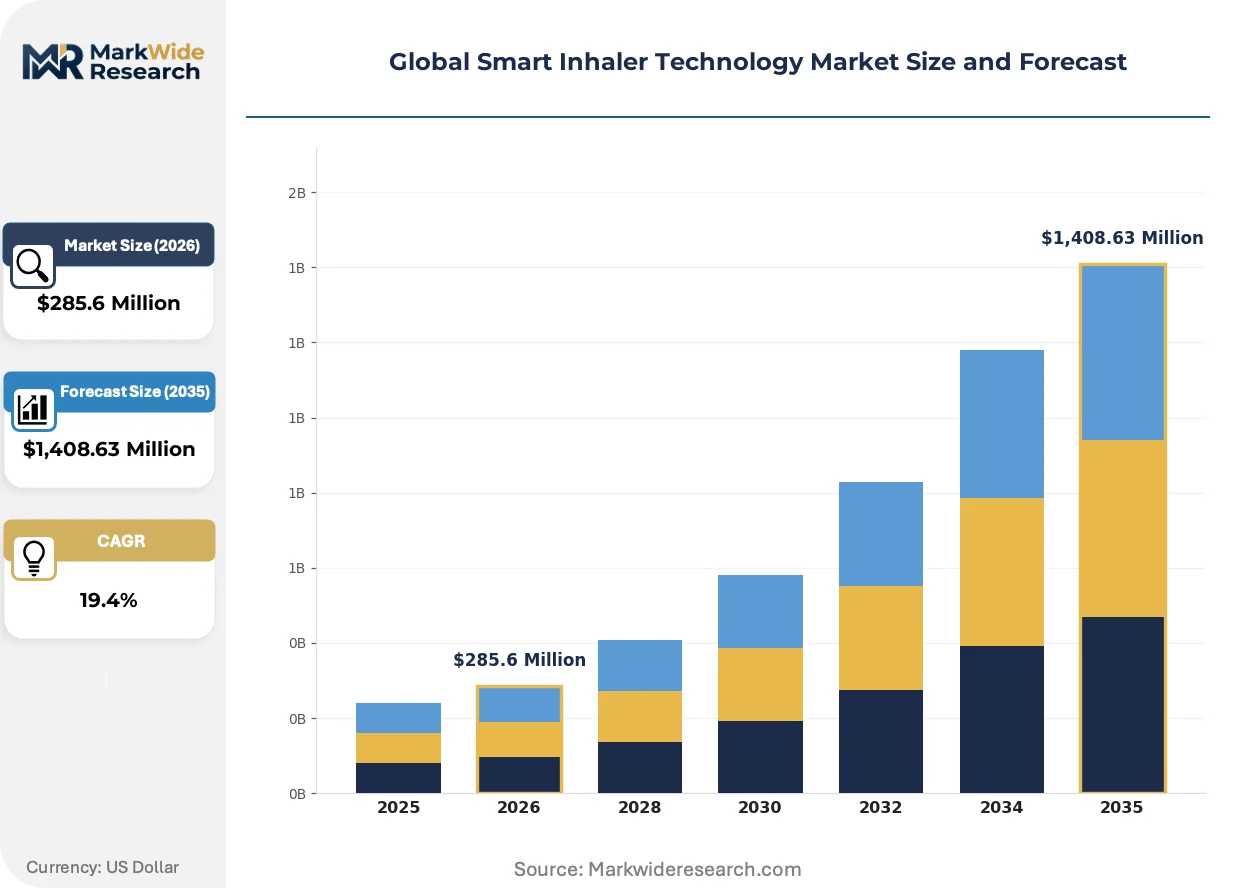
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Inhaler Technology Market |
| Market Size in 2026 | $285.6 Million |
| Market Size in 2035 | $1,408.63 Million |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metered Dose Inhalers, Dry Powder Inhalers, Nebulizers, Soft Mist Inhalers, Breath Activated Inhalers Technology: Bluetooth, NFC, Sensors, Mobile Apps, Cloud Connectivity, Artificial Intelligence Application: Asthma Management, COPD Treatment, Respiratory Monitoring, Allergy Control, Pulmonary Rehabilitation End User: Pulmonology Clinics, Home Care, Pharmacies, Respiratory Care Centers, Telemedicine Providers |
| Companies Covered | AstraZeneca, GlaxoSmithKline, Novartis AG, Teva Pharmaceutical, Adherium, Propeller Health, AptarGroup, 3M Health Care, Boehringer Ingelheim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Inhaler Technology Market Shifts & Advancements
Edge computing migration and algorithmic dose verification are compressing the latency between patient actuation and clinical intervention, redefining respiratory care workflows across ambulatory and residential settings.
Machine learning inference is hybridizing on-device accelerometer pattern recognition with cloud-based adherence analytics. Pulmonology clinics in the United States and Germany are deploying these hybrid architectures to reduce false-positive technique alerts while preserving battery life for 30-day continuous monitoring cycles. This convergence is compressing the traditional separation between consumer wellness devices and clinical-grade respiratory monitors.
The EU AI Act's risk classification for medical device software is mandating conformity assessments for algorithmic dose prediction features. Manufacturers seeking CE marking must now document training data provenance and performance drift monitoring protocols. Inhaler platforms with embedded neural networks for flow pattern classification face the steepest compliance burden, driving consolidation in European AI development partnerships.
Subscription-based device provisioning is displacing capital purchase models in US integrated delivery networks. Hospitals in Texas and California are leasing sensor-enabled inhalers with per-patient monthly fees that bundle hardware, connectivity, and analytics dashboards. This shift transfers obsolescence risk to manufacturers while locking in multi-year data licensing agreements for real-world evidence generation.
Global Smart Inhaler Technology Market Segmentation
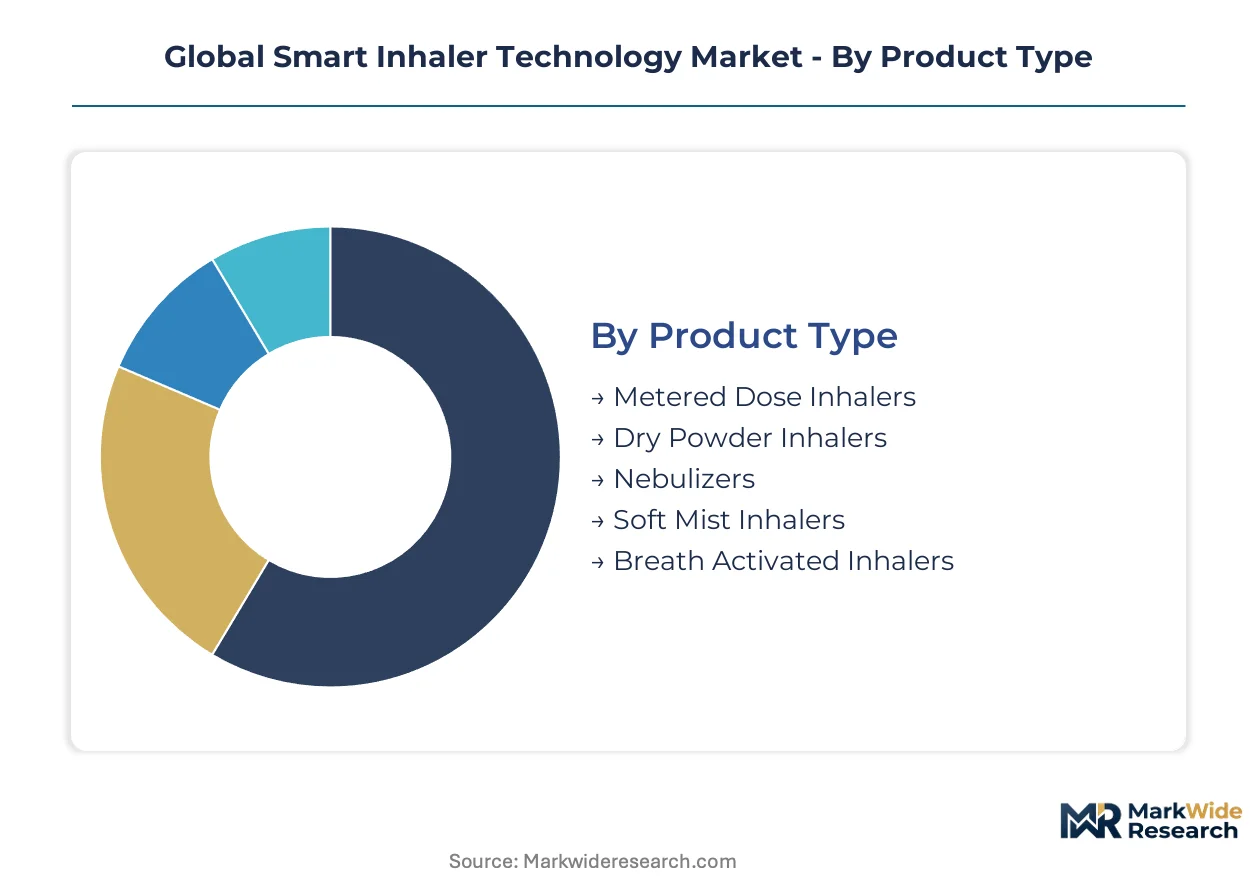
Smart inhaler segmentation reveals how hardware-software coupling intensity varies across device architectures and care settings. Service obligations diverge sharply between clinic-deployed systems requiring continuous calibration and consumer-oriented home units with limited technical support.
Product Type:
After-sales service intensity escalates with mechanical complexity and sensor integration density, creating tiered support obligations that reshape manufacturer margin structures.
- Metered Dose Inhalers:Pressure-actuated canister systems with integrated dose counters dominate current deployment due to corticosteroid compatibility. Demand concentrates in United States pulmonology clinics where CMS reimbursement codes incentivize connected respiratory monitoring for chronic asthma populations.
- Dry Powder Inhalers:Breath-activated powder dispersion mechanisms eliminate propellant dependencies while requiring flow sensor calibration for patient-specific inspiratory force detection. Germany's G-BA reimbursement framework accelerates procurement in outpatient respiratory networks seeking to reduce hospitalization frequency.
- Nebulizers:Compressor-driven aerosol generation systems with ultrasonic mesh variants.
- Soft Mist Inhalers:Spring-mechanized slow-moving aerosol generators.
- Breath Activated Inhalers:Flow-triggered valve systems eliminating hand-breath coordination requirements.
By volume, Metered Dose Inhalers leads. By growth pace, Dry Powder Inhalers is ahead.
Technology:
Component sourcing geography fragments development roadmaps, with wireless module procurement concentrated in East Asian semiconductor clusters and algorithm development anchored in Boston and Tel Aviv metro areas.
- Bluetooth:Low-energy wireless protocol enabling continuous smartphone pairing with sub-10mW power consumption for 30-day battery cycles. United States home care networks deploy Bluetooth-enabled inhalers most aggressively as post-acute care decentralization shifts chronic disease management into residential settings.
- NFC:Near-field communication for tap-to-pair medication authentication and pharmacy verification workflows.
- Sensors:MEMS pressure transducers and accelerometers with 10-30 L/min flow detection thresholds.
- Mobile Apps:Patient-facing adherence dashboards with HL7 FHIR EHR integration requirements.
- Cloud Connectivity:AWS and Azure-hosted analytics platforms for real-world evidence generation.
- Artificial Intelligence:On-device neural networks for inhalation pattern classification facing EU AI Act conformity assessments.
Bluetooth captures the largest installed base. Artificial Intelligence is climbing the fastest as regulatory pathways mature.
Application:
Clinical outcome measurement rigor varies by disease severity, with severe asthma and COPD segments demanding FDA-validated digital biomarkers while allergy management tolerates consumer-grade accuracy thresholds.
- Asthma Management:Pediatric and adult populations requiring technique verification and trigger pattern identification. Japan's PMDA accelerated review pathway for digital therapeutics paired with inhalable biologics concentrates demand in severe asthma segments.
- COPD Treatment:Progressive airflow limitation monitoring with exacerbation prediction algorithms. United States pulmonology clinics deploy connected inhalers to reduce Medicare readmission penalties.
- Respiratory Monitoring:General-purpose lung function tracking across undifferentiated patient populations.
- Allergy Control:Seasonal allergen-triggered prophylactic medication timing.
- Pulmonary Rehabilitation:Post-acute recovery support with exercise tolerance correlation.
Asthma Management holds the broadest addressable population. COPD Treatment is gaining share fastest as aging demographics expand.
End User:
Procurement authority fragmentation creates divergent sales cycles, with hospital procurement departments negotiating enterprise contracts while home care and pharmacy channels require direct-to-patient marketing investments.
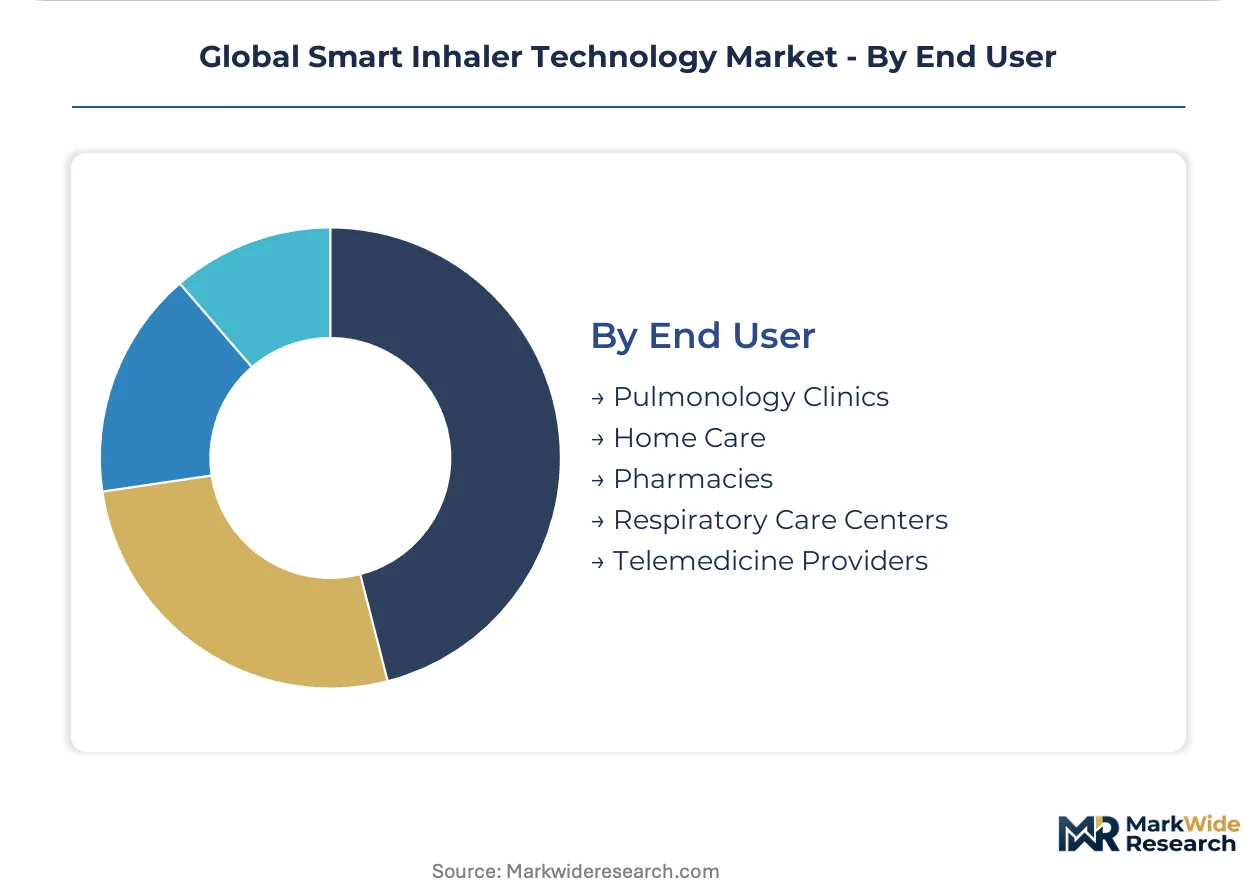
- Home Care:Residential deployment for chronic disease management with remote provider oversight. United States and Japan lead this segment as reimbursement shifts favor decentralized respiratory monitoring and telemedicine integration reduces clinic visit dependencies.
- Pulmonology Clinics:Specialist-directed asthma and COPD management with integrated EHR workflows. Germany's outpatient respiratory networks procure connected inhalers through regional purchasing cooperatives.
- Pharmacies:United States specialty pharmacy channels building remote monitoring capabilities.
- Respiratory Care Centers:Post-acute skilled nursing facilities with therapist-supervised inhalation training.
- Telemedicine Providers:Virtual-first care models requiring asynchronous patient data streams.
Home Care leads by patient volume. Pulmonology Clinics is expanding most quickly as specialist adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global smart inhaler technology market exhibits a pronounced import dependency for MEMS sensor modules, with device assembly concentrated in the United States, Germany, and Japan while semiconductor inputs flow from Taiwanese and South Korean foundries.
United States
CMS reimbursement codes for connected respiratory devices accelerate pulmonology clinic procurement cycles across Texas and California health systems. The FDA's combination product framework under 21 CFR 3.2(e) mandates simultaneous device and software validation, extending regulatory timelines for sensor-integrated inhalers seeking market authorization. Boston anchors firmware engineering talent clusters serving ultra-low-power medical sensor development.
Germany
G-BA reimbursement frameworks incentivize outpatient respiratory networks in Bavaria and North Rhine-Westphalia to deploy connected inhalers for chronic disease management. The EU Medical Device Regulation's streamlined evidence requirements for digital health features reduce time-to-market for CE-marked sensor devices. Regional purchasing cooperatives aggregate demand from pulmonology clinics across Baden-Württemberg.
Japan
PMDA's accelerated review pathway for digital therapeutics paired with inhalable biologics concentrates severe asthma segment demand in the Kanto region. METI funding for telemedicine infrastructure shifts chronic respiratory management into residential settings across Osaka and Nagoya metro areas. Tokyo firmware engineering clusters compete with Boston and Tel Aviv for embedded systems talent.
United Kingdom
NHS Long Term Plan targets for respiratory disease reduction drive procurement of Bluetooth-enabled adherence monitoring devices across London and Southeast integrated care systems. The MHRA's post-Brexit regulatory autonomy enables divergence from EU MDR timelines, creating parallel approval pathways for sensor-integrated inhalers. Cambridge medtech clusters specialize in machine learning inference for inhalation pattern classification.
South Korea
MFDS digital health guidance aligns with PMDA accelerated pathways, positioning Seoul-based manufacturers as contract suppliers for multinational pharmaceutical device partnerships. Samsung and LG display divisions provide OLED components for next-generation inhaler interface modules. Busan-Ulsan industrial corridors host MEMS packaging facilities serving pressure transducer assembly for flow detection modules.
Global Smart Inhaler Technology Market Competitive Landscape
On the supply side, the industry is consolidating around pharmaceutical-device convergence partnerships that combine corticosteroid formulation expertise with sensor hardware capabilities. Tiered competitive positioning separates multinational respiratory drug manufacturers from digital health platform specialists and component suppliers. Three archetypes dominate: integrated pharma-device conglomerates, connectivity-focused health technology platforms, and precision sensor component vendors. M&A activity concentrates on digital therapeutic capabilities, while strategic partnerships address EHR integration requirements.
Within the pharmaceutical-device integrated tier, AstraZeneca and GlaxoSmithKline occupy positions that exemplify formulation-led market entry strategies. Propeller Health represents the connectivity-platform archetype, anchoring Bluetooth-enabled dose tracking deployments across United States pulmonology networks. Adherium sits within the medication adherence analytics specialization, extending provider oversight architectures into home care settings through sensor-to-cloud modular systems.
| Leading Market Players |
|---|
| AstraZeneca |
| GlaxoSmithKline |
| Novartis AG |
| Teva Pharmaceutical |
| Adherium |
| Propeller Health |
| AptarGroup |
| 3M Health Care |
| Boehringer Ingelheim |
| Others |
Supply & Pricing Matrix
Undercapacity in Taiwanese MEMS foundries is compressing sensor module availability while simultaneously elevating pricing leverage for flow detection component suppliers serving inhaler manufacturers in the United States, Germany, and Japan. This utilization squeeze forces device assemblers to accept extended lead times or premium slotting fees, reshaping procurement postures across Bluetooth-enabled inhaler programs.
Pricing Analysis
Pulmonology clinic procurement committees anchor pricing negotiations through multi-year subscription contracts that bundle hardware, connectivity, and analytics dashboards. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated clinical systems from consumer-grade adherence trackers and basic dose counters without cloud integration. Cost compression in the economy tier is intensifying because South Korean foundries are prioritizing automotive MEMS contracts over medical sensor allocations. Home care networks exhibit the highest price sensitivity due to reimbursement rate caps, while integrated delivery networks in Texas and California demonstrate the lowest sensitivity through captive data licensing agreements.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard as inhaler manufacturers seek supply-chain finance facilities to bridge working capital gaps during FDA combination product validation cycles. MEMS pressure sensor fabrication draws from Taiwanese and South Korean foundry capacity, while Bluetooth Low Energy modules source from Shenzhen and Seoul packaging facilities. Single-source vulnerability concentrates in TSMC's 8-inch MEMS lines, where medical sensor wafers compete with automotive and consumer electronics for allocation. Distribution runs through specialty pharmacy channels in the United States, regional purchasing cooperatives in Germany, and hospital procurement consortia in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recurring revenue from adherence analytics subscriptions is expanding faster than hardware unit sales, transforming smart inhaler economics into a service-attach model where data licensing agreements generate multi-year income streams independent of device replacement cycles.
For Market Incumbents: Harden firmware engineering capabilities through acquisition of Boston or Tel Aviv embedded systems specialists to secure ultra-low-power sensor development talent. Consolidate EHR integration partnerships with Epic and Cerner to lock out competitors from health system procurement cycles. Vertical integration into MEMS packaging through joint ventures with South Korean foundries mitigates single-source sensor vulnerability.
For New Entrants and Emerging Players: Pursue pediatric asthma management white space in German school-based care settings and Japanese municipal health programs, where tamper-resistant dose tracking with parental notification features remains underpenetrated. Target pharmacy channel integration in United States specialty networks building remote monitoring capabilities, bypassing hospital procurement gatekeepers through direct-to-patient distribution models.
For Investors and Strategic Acquirers: Long-term, this sits as a data platform play because real-world evidence generation contracts with pharmaceutical manufacturers create durable revenue moats beyond device hardware margins. Acquisition target archetype: connectivity-platform specialists with validated FDA 510(k) clearances and existing Epic EHR integrations. Watch PMDA accelerated review pathway expansion for digital therapeutics paired with inhalable biologics as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Combination Product Submission | Simultaneous device and software validation under 21 CFR 3.2(e) unlocks CMS reimbursement codes. |
| CE Marking Pathway under EU MDR | Streamlined evidence requirements for digital health features reduce time-to-market for sensor-integrated inhalers. |
| Hospital System Partnership | Integrated delivery network contracts in Texas and California lock in multi-year data licensing agreements. |
| Software Companion Development | HL7 FHIR connectivity with Epic and Cerner systems enables seamless EHR workflow integration. |
| Reimbursement Strategy | G-BA framework in Germany and CMS codes in the United States accelerate pulmonology clinic procurement cycles. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured interviews with pulmonologists, hospital procurement managers, biomedical engineers, and GPO contracts specialists, supplemented by secondary validation against FDA 510(k) filings, CMS reimbursement code databases, EMA MDR submission records, and hospital procurement contract repositories. Bottom-up unit shipment estimates triangulated against top-down pharmaceutical device revenue disclosures.
Calibration against historical adoption curves for connected medical devices informed growth trajectory assumptions across the projection horizon. Segmentation dimensions modeled include device architecture, wireless protocol tier, disease application severity, and end-user procurement authority. CAGRs were derived from fitted adoption curves weighted by reimbursement policy implementation timelines and regulatory approval pathway velocity, with specific inputs from MEMS sensor supply constraints and EHR integration deployment schedules.
Macroeconomic conditions sit as an overlay; deviation in semiconductor foundry utilization rates, reimbursement policy continuity, or cybersecurity certification harmonization would shift the trajectory. Forecasts reflect documented assumptions about regulatory pathway stability and supply chain input availability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Dermatology Diagnostic Equipment Market
Diagnostic and Therapeutic Devices
Global Aspiration and Biopsy Needles Market
Diagnostic and Therapeutic Devices
Nanobiosensors in Healthcare Market
Diagnostic and Therapeutic Devices
Pelvic Congestion Syndrome Treatment Market
Diagnostic and Therapeutic Devices
Phototherapy Device Market
Diagnostic and Therapeutic Devices
Smart Drug Delivery Systems Market
Diagnostic and Therapeutic Devices
Sustained Acoustic Medicine Market
Diagnostic and Therapeutic Devices
Heat Therapy Lamp Market
Diagnostic and Therapeutic Devices
Dissolving Microneedles Market
Diagnostic and Therapeutic Devices
Global Acoustic Medicine and Ultrasound Therapy Market
Diagnostic and Therapeutic Devices
Fully Automated Coagulometer Market
Diagnostic and Therapeutic Devices
Automated Immunoassay Analyzers Market
Diagnostic and Therapeutic Devices
RF Microneedling Market
Diagnostic and Therapeutic Devices
Electroceuticals Bioelectric Medicine Market
Diagnostic and Therapeutic Devices
Middle-East and Africa Stroke Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Intracranial Hemorrhage Diagnosis and Treatment Market