
 Cruciate Ligament Diagnosis Treatment Market | 2026-2036
Cruciate Ligament Diagnosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Cruciate Ligament Diagnosis Treatment Market Analysis
Professional sports medicine is decoupling from general orthopedic volume as dedicated athlete-care centers multiply. Stryker leverages integrated arthroscopy-to-implant workflows across hospital networks. Arthrex anchors the allograft and fixation portfolio through proprietary suture anchor designs. Smith & Nephew competes in radiofrequency ablation and joint preservation adjacent to ligament repair.
Cruciate ligament diagnosis treatment encompasses imaging, surgical intervention, and post-operative rehabilitation for torn anterior or posterior cruciate ligaments, typically involving arthroscopic visualization, tunnel drilling, and graft fixation with resorbable or metallic interference screws. MRI technology leads diagnostic throughput due to soft-tissue contrast resolution, while arthroscopy dominates procedural revenue as the operative gateway for ACL reconstruction. Rehabilitation equipment represents the fastest-growing segment as accelerated return-to-play protocols extend device utilization into outpatient and home settings.
FDA 510(k) pathways govern graft fixation devices and arthroscopic instruments in the United States, while the EU Medical Device Regulation imposes clinical evidence requirements on ligament repair systems sold in Europe. The Centers for Medicare & Medicaid Services shapes demand through bundled payment models for outpatient ACL reconstruction. Stakeholders must monitor reimbursement shifts between inpatient and ambulatory surgical center settings as site-of-service economics redefine procurement authority.
Market Dynamics
Site-of-service economics is fragmenting procurement authority across hospital systems, ambulatory surgical centers, and dedicated athlete-care facilities, forcing device manufacturers to restructure account management and pricing discipline around procedure volume rather than institutional contracts.
Growth Catalysts
- FDA 510(k) Pathway Acceleration:Streamlined clearance for arthroscopic instruments and graft fixation devices compresses time-to-market for next-generation sterilization protocols, expanding allograft availability.
- Collegiate Sports Infrastructure:NCAA Division I athletic programs sustain high-volume ACL reconstruction throughput, driving recurring demand for arthroscopic repair systems and rehabilitation equipment.
- Resorbable Interference Screws:Bioabsorbable polymer fixation eliminates secondary removal procedures, reducing long-term complication rates and extending device utilization into outpatient settings.
Market Restraints
- Allograft Supply Concentration:Tissue bank consolidation in the United States creates single-source dependency for sterilized ligament grafts, amplifying disruption risk from processing facility closures.
- EU MDR Clinical Evidence Burden:The European Union Medical Device Regulation imposes retrospective clinical data requirements on legacy ligament repair systems, delaying market access for updated product lines.
- Allograft-versus-Autograft Cost Differential:Patellar tendon and hamstring autograft harvesting avoids tissue procurement fees but extends operative time, creating unresolved cost-accounting friction in bundled payment models.
Strategic Opportunities
- Home-Based Rehabilitation Monitoring:Wearable motion sensors and telerehabilitation platforms extend post-operative care beyond clinic walls, capturing value from accelerated return-to-play protocols.
- CMS Bundled Payment Expansion:Centers for Medicare & Medicaid Services outpatient ACL reimbursement models create incentive alignment for device-procedure-rehabilitation integration.
- Hybrid Fixation Convergence:Suture anchor and interference screw combination systems address graft slippage in high-tension athletic applications, opening premium positioning in professional sports medicine.
Industry Challenges
- Arthroscopic Technician Pipeline Shortage:Specialized instrument processing and sterilization expertise concentrates in tertiary hospital systems, constraining ASC expansion.
- Allograft Traceability Compliance:FDA tissue tracking regulations impose documentation burdens across procurement, processing, and implantation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cruciate Ligament Diagnosis Treatment Market |
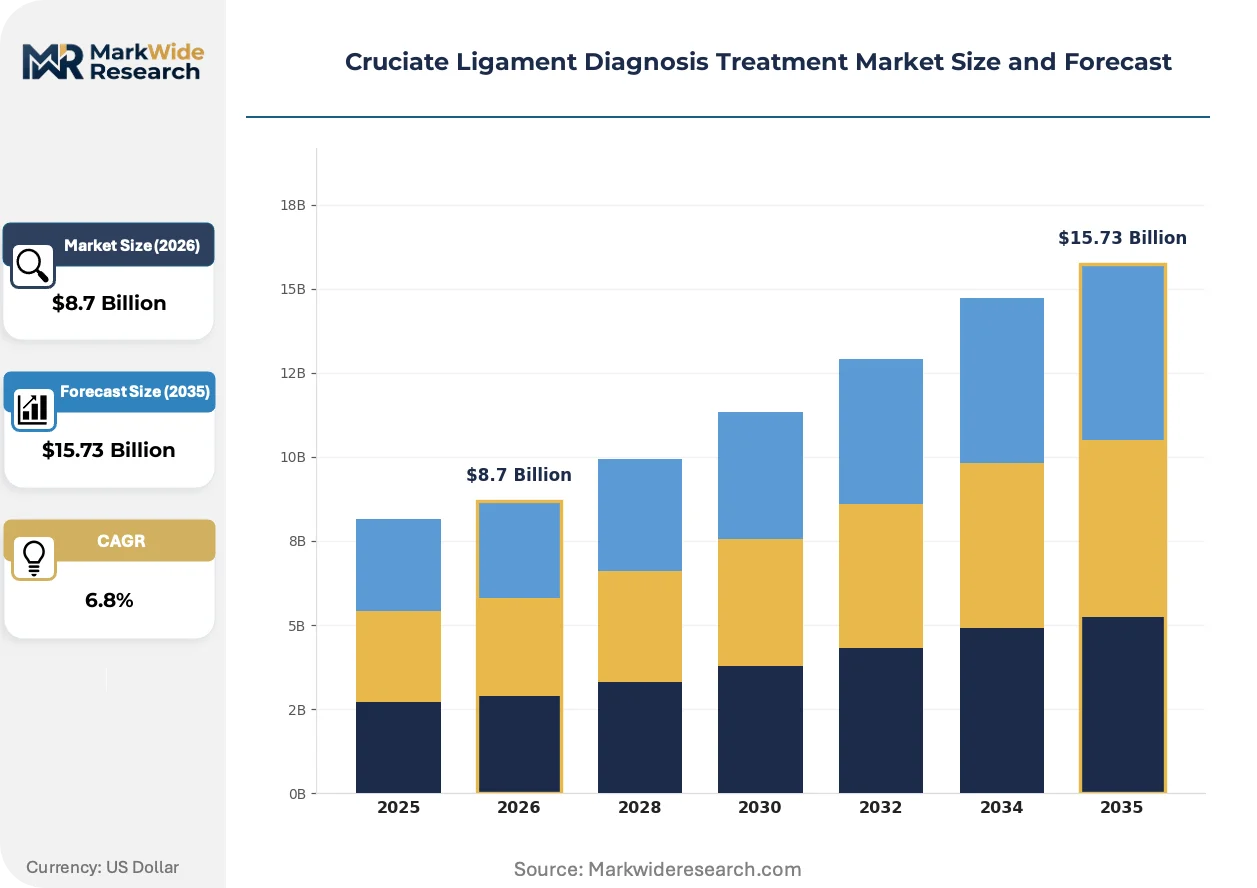
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Imaging, Surgical Systems, Rehabilitation Equipment, Orthopedic Braces Application: ACL Reconstruction, PCL Repair, Meniscus Surgery, Rehabilitation Technology: Arthroscopy, MRI, CT Scan, Ultrasound End User: Hospitals, Clinics, Rehabilitation Centers, Sports Facilities |
| Companies Covered | Arthrex, Stryker, Smith & Nephew, Zimmer Biomet, CONMED Corporation, Johnson & Johnson (DePuy Synthes), Medtronic, DJO Global, Bauerfeind AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cruciate Ligament Diagnosis Treatment Market Emerging Trajectories
Biological augmentation and intelligent instrumentation are compressing recovery timelines while regulatory frameworks force evidence generation earlier in product lifecycles. These shifts favor integrated solution providers over standalone device vendors.
Biological scaffold reinforcement is electrifying graft incorporation biology. Extracellular matrix patches and platelet-rich plasma adjuncts accelerate ligament-bone tunnel healing. Professional athletic programs and military medical centers are adopting these biologics ahead of general orthopedics. The technology is electrifying premium pricing tiers and forcing traditional fixation manufacturers into partnership or acquisition strategies.
The EU Medical Device Regulation is tightening clinical evidence requirements for ligament repair systems marketed in Europe. Legacy products face retrospective data collection obligations or market withdrawal. High-risk class III device reclassifications are compressing notified body capacity and extending review timelines. European orthopedic distributors are consolidating supplier portfolios to concentrate regulatory management resources.
Athlete-care centers are unbundling rehabilitation equipment procurement from hospital supply chains. Dedicated sports medicine facilities now source cryotherapy systems, continuous passive motion devices, and neuromuscular electrical stimulation units through direct manufacturer relationships. This channel disintermediation is most visible in the United States, where private equity-backed orthopedic platforms aggregate purchasing power across multi-site networks.
Cruciate Ligament Diagnosis Treatment Market Segmentation
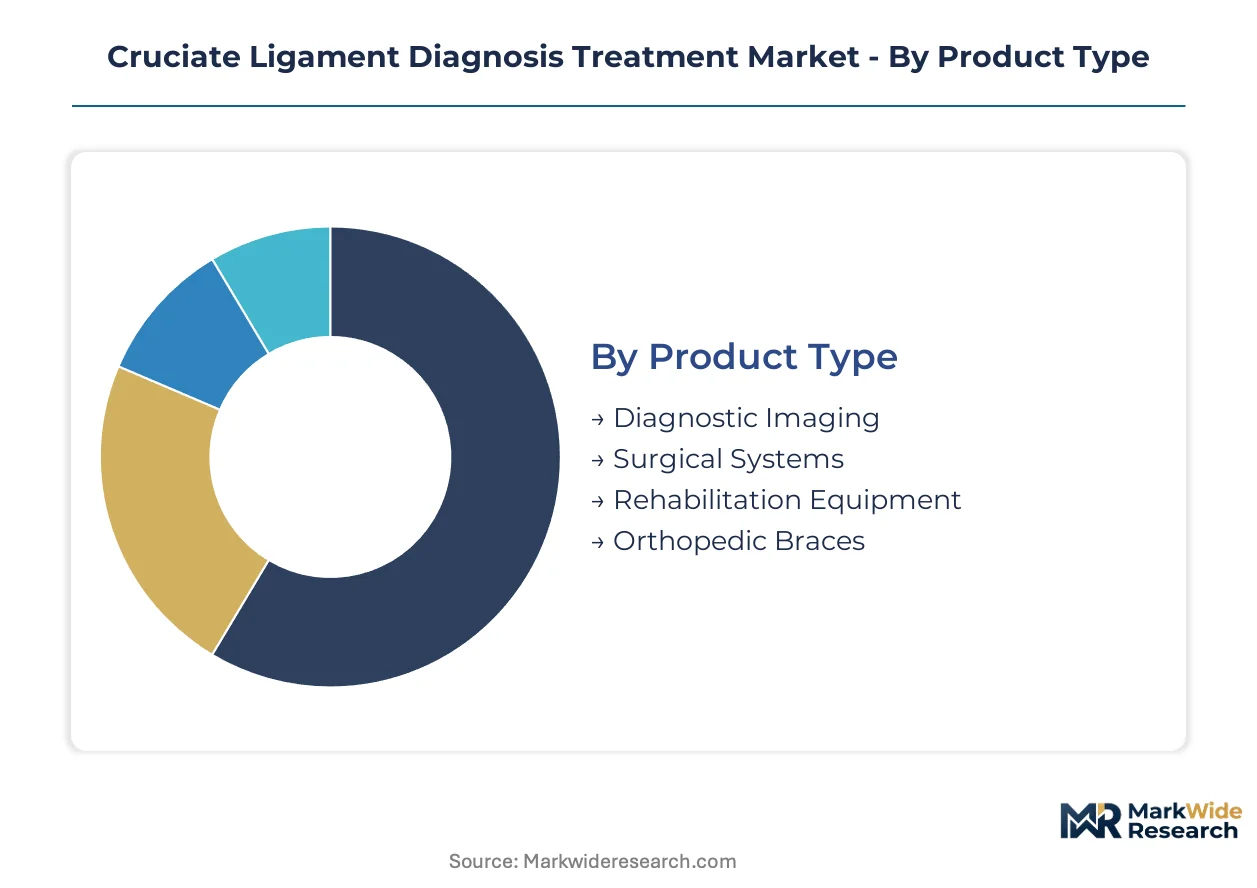
Cruciate ligament care spans acute diagnosis, operative intervention, and extended recovery phases. Segmentation reveals how procurement authority fragments across imaging suites, operating theaters, and outpatient rehabilitation settings.
Product Type:
Hospital procurement committees weight capital intensity against procedure volume when allocating budgets across diagnostic and therapeutic modalities.
- Diagnostic Imaging:MRI systems deliver superior soft-tissue contrast for ligament tear grading and concomitant meniscal assessment. United States academic medical centers prioritize 3.0 Tesla magnet upgrades to reduce scan times for athletic populations.
- Surgical Systems:Arthroscopic visualization towers, shaver consoles, and fluid management pumps constitute the operative backbone. NCAA Division I training facilities drive demand for portable all-in-one arthroscopy units enabling sideline surgical suites.
- Rehabilitation Equipment:Continuous passive motion devices and cryotherapy systems extend care into outpatient settings.
- Orthopedic Braces:Post-operative hinged knee braces and functional ACL prevention braces serve distinct recovery phases.
Diagnostic imaging leads volumes today; rehabilitation equipment is gaining share fastest.
Application:
Procedure mix varies by patient demographics, with athletic populations driving reconstruction volume and aging populations requiring more conservative approaches.
- ACL Reconstruction:Arthroscopic tunnel drilling with hamstring or patellar tendon graft fixation dominates sports medicine throughput. Bundled payment models in United States ambulatory surgical centers compress device selection to standardized implant sets.
- PCL Repair:Posterior cruciate injuries occur less frequently but demand specialized posterior portal techniques. Military medical centers accumulate surgical expertise given mechanism-of-injury patterns in service members.
- Meniscus Surgery:Concomitant meniscal repair or debridication accompanies most cruciate procedures.
- Rehabilitation:Accelerated return-to-play protocols extend device utilization timelines.
ACL reconstruction commands procedure volume; rehabilitation application shows steepest expansion trajectory.
Technology:
Imaging and operative technologies compete for capital allocation based on throughput economics and reimbursement alignment.
- Arthroscopy:Minimally invasive visualization enables tunnel placement accuracy and graft tensioning under direct view. Professional sports franchises invest in dedicated arthroscopy suites to minimize athlete downtime.
- MRI:Non-invasive soft-tissue characterization guides surgical candidacy and graft selection. United States radiology groups deploy dedicated extremity coils to improve throughput for knee-specific protocols.
- CT Scan:Bony tunnel assessment and osteotomy planning applications.
- Ultrasound:Dynamic ligament evaluation and guided injection procedures.
Arthroscopy anchors procedural revenue; MRI expands most quickly in outpatient diagnostic settings.
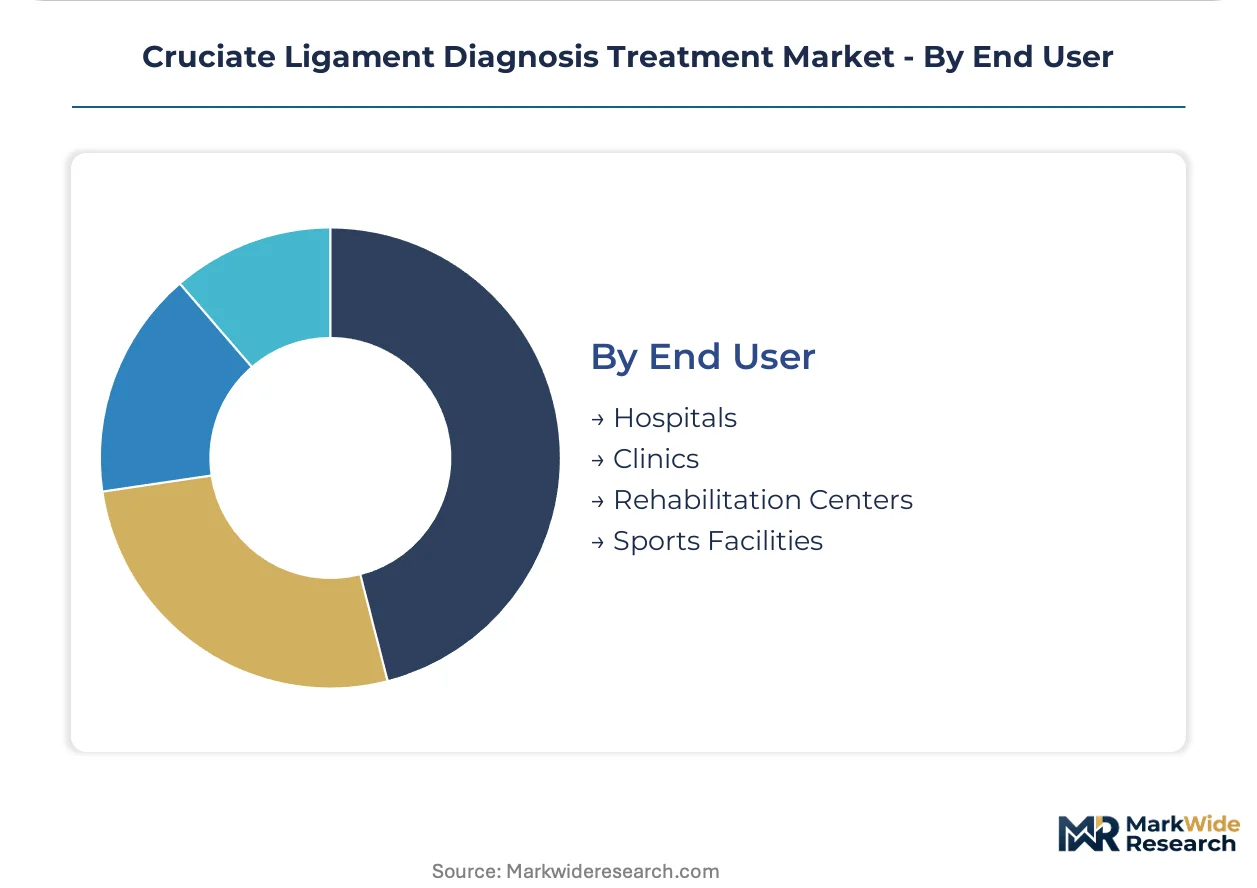
End User:
Site-of-service economics fragment procurement authority across institutional and distributed care settings.
- Hospitals:Tertiary academic centers concentrate complex multi-ligament reconstruction and revision surgery. Operating room block scheduling and sterile processing capacity constrain expansion.
- Clinics:Ambulatory surgical centers capture straightforward primary ACL reconstruction under CMS bundled payment models. Physician ownership structures drive device standardization around preferred vendor relationships.
- Rehabilitation Centers:Dedicated physical therapy facilities manage post-operative protocol adherence.
- Sports Facilities:Collegiate and professional athletic programs maintain on-site diagnostic and acute care capabilities.
Hospitals retain high-acuity volume; ambulatory surgical centers are climbing the fastest in procedure migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping cruciate ligament device manufacturing as sterilization protocol costs diverge between FDA and EU MDR jurisdictions. Production capacity migrates toward lower compliance-cost environments while clinical demand concentrates in high-procedure-volume markets.
United States
NCAA Division I athletic programs and professional sports franchises sustain the world's highest ACL reconstruction throughput per capita. FDA 510(k) pathways accelerate arthroscopic instrument clearance, compressing time-to-market for next-generation fixation devices. The Texas Medical Center in Houston anchors multi-site orthopedic platforms aggregating procurement power across ambulatory surgical center networks.
Germany
Industrial automation expertise in Baden-Württemberg supports precision manufacturing of arthroscopic shaver consoles and fluid management pumps. EU MDR clinical evidence requirements delay market access for legacy ligament repair systems, forcing retrospective data collection investments. The Stuttgart-Tübingen corridor concentrates sports medicine research clusters developing biological augmentation therapies.
Japan
Aging demographics and recreational sports participation drive diagnostic imaging demand for soft-tissue injury assessment. PMDA regulatory frameworks emphasize clinical evidence quality over procedural volume in device approvals. The Kansai region around Osaka hosts specialized arthroscopy training centers serving East Asian surgical education markets.
United Kingdom
NHS bundled payment pilots for outpatient orthopedic procedures accelerate site-of-service migration from tertiary hospitals to ambulatory settings. MHRA post-Brexit regulatory autonomy creates divergence from EU MDR timelines for ligament repair system certifications. London's Harley Street medical district concentrates private athlete-care facilities sourcing rehabilitation equipment through direct manufacturer relationships.
Australia
AFL and rugby league injury patterns sustain high-volume anterior cruciate ligament reconstruction demand in seasonal clusters. TGA regulatory alignment with FDA 510(k) pathways streamlines market access for US-manufactured fixation devices. Melbourne's Olympic Park sports medicine precinct integrates diagnostic imaging, surgical suites, and rehabilitation facilities in single-site athlete-care campuses.
Cruciate Ligament Diagnosis Treatment Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated arthroscopy-to-implant workflows commanding premium positioning in hospital networks while standalone rehabilitation equipment vendors compete on price in distributed care settings. The vendor base concentrates around three strategic archetypes: full-solution orthopedic conglomerates, sports-focused device specialists, and biological augmentation innovators. M&A activity targets biological scaffold capabilities and regional distribution footprints.
Within the full-solution tier, Stryker and Zimmer Biomet anchor integrated hospital system contracts spanning diagnostic imaging through post-operative care. Arthrex exemplifies the sports-specialist archetype through proprietary fixation designs and direct surgeon education programs. Smith & Nephew occupies a position bridging radiofrequency ablation technology with joint preservation adjacencies to ligament repair.
| Leading Market Players |
|---|
| Arthrex |
| Stryker |
| Smith & Nephew |
| Zimmer Biomet |
| CONMED Corporation |
| Johnson & Johnson (DePuy Synthes) |
| Medtronic |
| DJO Global |
| Bauerfeind AG |
| Others |
Supply Flow & Price Mechanics
EU MDR sterilization validation requirements gate qualified allograft supply and premium-tier pricing access, as tissue banks bearing retrospective clinical evidence costs pass compliance premiums through to arthroscopic repair system manufacturers while ASC procurement committees demand economy-tier alternatives.
Pricing Analysis
Distributor margins on arthroscopic instruments compress as direct manufacturer relationships with athlete-care centers disintermediate traditional hospital supply chains. Pricing stratifies across premium biologics-augmented fixation systems, standard allograft-implant sets, and economy autograft-dependent configurations. Cost compression in standard-tier screw and anchor portfolios intensifies as bundled payment models force device standardization. Ambulatory surgical centers exhibit highest price sensitivity; professional sports franchises demonstrate lowest sensitivity given return-to-play timeline premiums.
Supply Chain Analysis
Regional distribution centers in Memphis and Louisville anchor hub-and-spoke patterns for sterile tissue grafts, with secondary nodes in Stuttgart and Osaka serving EU and East Asian markets. Allograft processing concentrates in United States tissue banks, German precision manufacturing clusters, and Japanese sterilization facilities. Raw material dependencies span cadaveric tissue procurement, bioabsorbable polymer resins, and titanium alloy stock. Single-source vulnerability in FDA-registered tissue banks creates disruption risk. Distribution runs through GPO contracts at hospital systems and direct-to-facility shipments for dedicated sports medicine centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cruciate ligament device manufacturing operates as a geographic-arbitrage play, with EU MDR clinical evidence burdens driving production migration toward FDA 510(k) jurisdictions where sterilization protocol costs remain lower.
For Market Incumbents: Deploy backward integration into allograft tissue processing to secure supply continuity against tissue bank consolidation threats. Capture ambulatory surgical center volume through standardized implant sets that reduce operative variability. Lock in long-term GPO contracts before bundled payment expansion accelerates price transparency. For New Entrants and Emerging Players: Home-based rehabilitation monitoring represents an underserved buyer archetype with minimal incumbent presence. Penetrate the wearable motion sensor segment through telerehabilitation platform partnerships with NCAA athletic programs. Establish direct manufacturer relationships with private equity-backed orthopedic platforms bypassing hospital supply chain intermediaries. For Investors and Strategic Acquirers: Roll-up economics work for biological augmentation specialists because regulatory evidence requirements favor scaled clinical data generation over fragmented trial investments. Biological scaffold capabilities and regional EU distribution footprints represent priority acquisition targets. Watch FDA allograft sterilization protocol amendments as inflection indicators for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Expansion | Accelerated clearance timelines compress time-to-market for next-generation fixation devices against EU MDR delays. |
| Biological Scaffold Acquisition | Extracellular matrix patch capabilities differentiate premium-tier positioning in professional sports medicine segments. |
| ASC Network Partnership | Direct relationships with ambulatory surgical centers capture procedure migration from tertiary hospital settings. |
| Home Rehabilitation Platform Launch | Wearable sensor integration extends device utilization into post-operative care beyond clinic walls. |
| EU MDR Regulatory Consulting | Retrospective clinical data management services address legacy product compliance burdens for European market access. |
Methodological Framework
Multiple input streams — orthopedic surgeon interviews, hospital procurement database analysis, and regulatory filing review — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged arthroscopy specialists, GPO contracts managers, biomedical engineers, and tissue bank operations directors. Secondary validation drew from FDA 510(k) databases, CMS Medicare reimbursement schedules, hospital procurement records, and EU MDR notified body guidance documents.
Data-stream reconciliation anchored volume projections across product type, application, technology, and end-user segmentation dimensions. CAGRs were derived from procedure volume trends, reimbursement trajectory modeling, and technology adoption curve analysis. Forecast inputs incorporated NCAA athletic program expansion plans, ambulatory surgical center site-of-service migration rates, and biological augmentation therapy penetration assumptions.
Inputs from CMS bundled payment pilots and EU MDR implementation timelines were available through the study window; gaps in private-pay athlete-care facility pricing data introduce uncertainty bands around premium-tier revenue forecasts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Global Needle Free Injection Systems Market
Diagnostic and Therapeutic Devices
Dermatology Diagnostic Equipment Market
Diagnostic and Therapeutic Devices
Intracranial Hemorrhage Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Crohn's Disease Diagnostic and Therapeutic Market
Diagnostic and Therapeutic Devices
Automated Immunoassay Analyzers Market
Diagnostic and Therapeutic Devices
Magnetic Therapy Devices Market
Diagnostic and Therapeutic Devices
Dissolving Microneedles Market
Diagnostic and Therapeutic Devices
Smart Inhalers Market
Diagnostic and Therapeutic Devices
Breast Lesion Localization Market
Diagnostic and Therapeutic Devices
Dental Surgical and Diagnostic Devices Market
Diagnostic and Therapeutic Devices
Leukocytapheresis Device Market
Diagnostic and Therapeutic Devices
Microneedle Drug Delivery Systems Market
Diagnostic and Therapeutic Devices
US Cancer Contrast Media Market
Diagnostic and Therapeutic Devices
Therapeutic Hypothermia Systems Market
Diagnostic and Therapeutic Devices
RF Microneedling Market
Diagnostic and Therapeutic Devices
Global Far Infrared Therapy Device Market