
 Global Acute Ischemic Stroke Diagnosis and Treatment Market | 2026-2036
Global Acute Ischemic Stroke Diagnosis and Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acute Ischemic Stroke Diagnosis and Treatment Market Foresight
North American neurointerventional device production is realigning around advanced catheter manufacturing and robotic-assisted thrombectomy platforms. Stryker Corporation leverages its endovascular portfolio to sustain leadership in mechanical thrombectomy systems across major stroke centers. Medtronic plc anchors its position through integrated neurovascular access and clot retrieval technologies. Siemens Healthineers differentiates via high-resolution CT angiography and perfusion imaging systems that guide treatment decisions.
Acute ischemic stroke diagnosis and treatment encompasses the clinical identification of cerebral artery occlusion through neuroimaging and the subsequent restoration of cerebral blood flow via pharmacological or mechanical intervention, with tissue plasminogen activator remaining the standard thrombolytic agent administered within defined therapeutic windows. The primary purpose is to minimize irreversible neuronal damage and reduce long-term disability burden. Imaging Systems and Endovascular Devices command the dominant share of product type revenue as hospitals prioritize rapid diagnostic confirmation and mechanical thrombectomy capability. Stroke Centers represent the fastest-expanding end user category as regional networks consolidate acute care and interventional expertise. Telemedicine Platforms are gaining structural importance in deployment models by extending specialist consultation to underserved geographies.
FDA breakthrough device designation and EMA conditional approval pathways are accelerating market access for novel neurointerventional technologies, while ISO 13485 quality management standards govern manufacturing compliance across jurisdictions. These regulatory frameworks elevate barriers for entrants lacking clinical evidence packages but reward manufacturers with robust quality systems. Stakeholders must monitor evolving reimbursement policies for thrombectomy procedures and digital health integration requirements that will reshape competitive positioning.
Market Dynamics
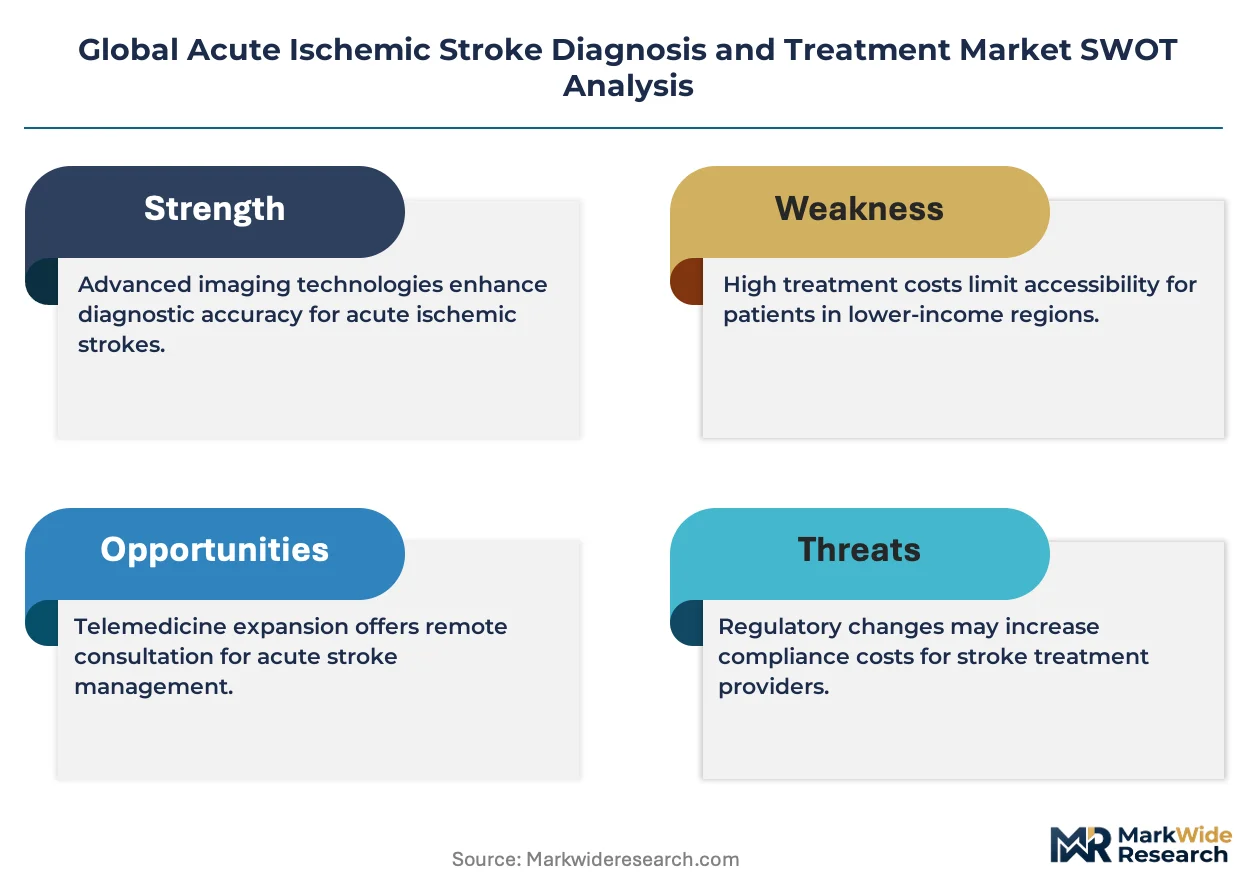
Mechanical thrombectomy is compressing treatment windows and displacing intravenous thrombolysis as first-line intervention across certified stroke centers, forcing capital redeployment toward angiography suites and interventional neuroradiology staffing.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review timelines for novel stent retrievers and aspiration catheters compress time-to-market for neurointerventional manufacturers. Stroke centers in the United States prioritize devices with this designation.
- Comprehensive Stroke Center Certification:Joint Commission accreditation requirements mandate 24/7 thrombectomy capability, driving capital expenditure on biplane angiography systems across hospital networks.
- Artificial Intelligence Triage:FDA-cleared large vessel occlusion detection algorithms are automating image interpretation, reducing door-to-groin time and expanding treatable patient populations.
Market Restraints
- Platinum-Iridium Alloy Supply Concentration:Microcatheter and guidewire manufacturing depends on South African and Russian feedstock, exposing producers to geopolitical supply disruption and price volatility.
- Interventional Neuroradiologist Scarcity:Fellowship-trained operators remain concentrated in academic medical centers, limiting thrombectomy rollout to community hospitals regardless of device availability.
- Reimbursement Compression:CMS inpatient prospective payment system adjustments for mechanical thrombectomy have tightened margin structures for hospitals performing high volumes of procedures.
Strategic Opportunities
- Mobile Stroke Units:Prehospital CT angiography and telemedicine-equipped ambulances enable field-based triage, extending thrombectomy candidacy to rural and exurban patient populations.
- EU MDR Article 117 Convergence:Drug-device combination product pathways for intra-arterial thrombolytics create regulatory harmonization opportunities for manufacturers with existing pharmaceutical partnerships.
- Japan PMDA Sakigake Priority Review:Expedited approval for AI-powered perfusion imaging software rewards early entrants with six-month market exclusivity premiums.
Industry Challenges
- Interventional Suite Construction Timelines:Lead times for shielded angiography installations extend 18-24 months, delaying stroke center certification and competitive positioning.
- ISO 13485 Audit Backlogs:Notified body capacity constraints in Europe extend quality management recertification cycles, freezing product launches for manufacturers in renewal windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acute Ischemic Stroke Diagnosis and Treatment Market |
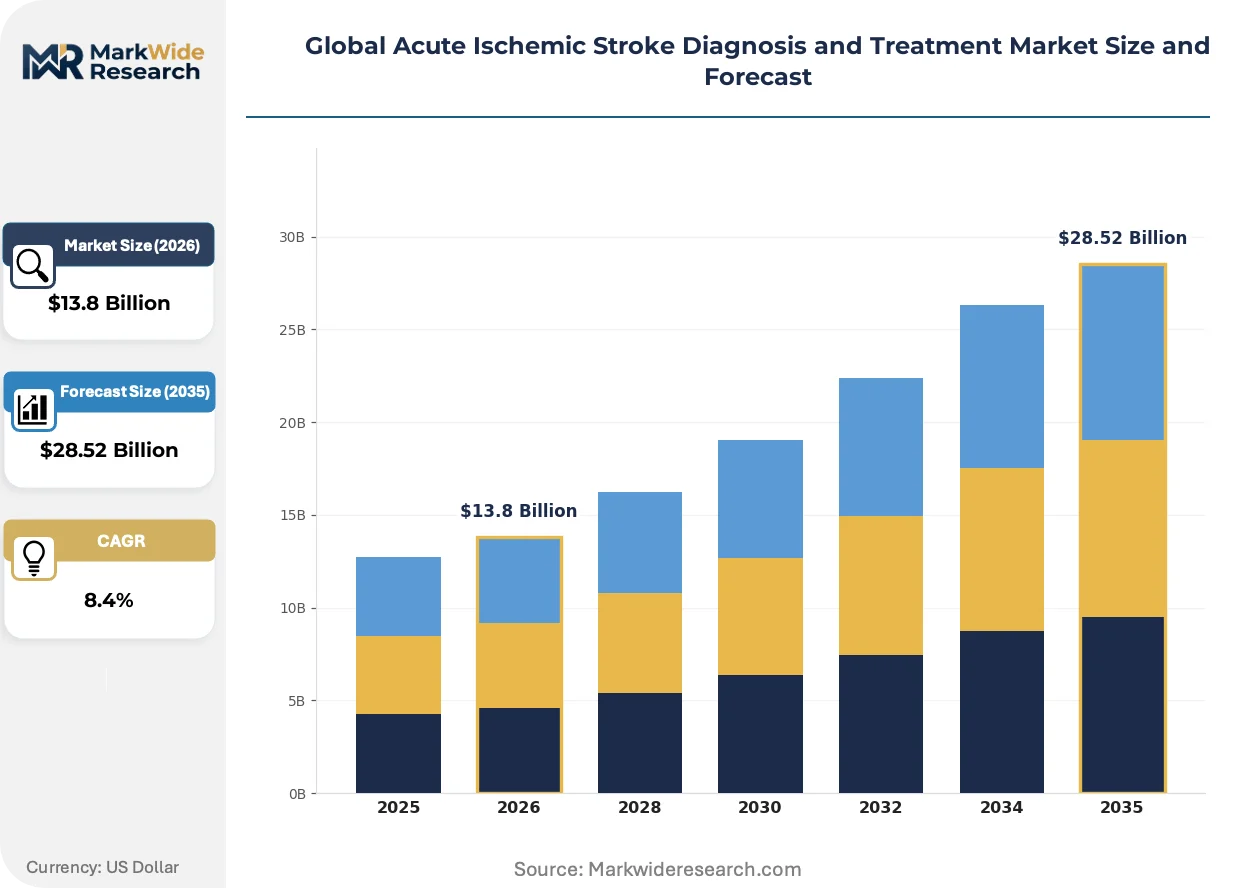
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Systems, Thrombolytic Agents, Endovascular Devices, Diagnostic Kits, Supportive Care Equipment Therapy Area: Neurological Assessment, Blood Flow Restoration, Neuroprotection, Rehabilitation, Acute Care Management End User: Emergency Medical Services, Stroke Centers, Diagnostic Laboratories, Rehabilitation Facilities, Neurology Clinics Deployment Model: Inpatient Settings, Outpatient Clinics, Mobile Units, Telemedicine Platforms, Ambulatory Services |
| Companies Covered | Abbott Laboratories, GE Healthcare, Stryker Corporation, Penumbra, Inc., Philips Healthcare, Johnson & Johnson, Siemens Healthineers, Boston Scientific Corporation, Medtronic plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acute Ischemic Stroke Diagnosis and Treatment Market Shifts & Advancements
Robotic catheter navigation and AI-powered imaging interpretation are converging to reduce operator variability and enable thrombectomy expansion beyond major academic centers.
Robotic-assisted thrombectomy platforms are automating distal navigation and device deployment, reducing fluoroscopy exposure and procedural time. Comprehensive stroke centers in Germany and the United States are piloting these systems for overnight coverage. The technology is automating aspects of operator-dependent skill, enabling community hospital adoption where specialist availability is limited.
EMA's MDR transition and FDA's Software as Medical Device guidance are tightening clinical evidence requirements for AI-enabled diagnostic tools. Manufacturers must now submit prospective validation data from multi-center registries rather than retrospective single-site studies. Perfusion imaging software vendors face the steepest compliance burden, with several products delayed in pre-submission phases.
Hospital procurement is consolidating neurointerventional device purchasing through integrated delivery networks and group purchasing organizations. Stroke centers increasingly demand bundled pricing spanning aspiration catheters, stent retrievers, and access platforms. This concentration is most pronounced in the United States, where IDN-affiliated hospitals command 15-20% price concessions versus independent facilities.
Global Acute Ischemic Stroke Diagnosis and Treatment Market Segmentation
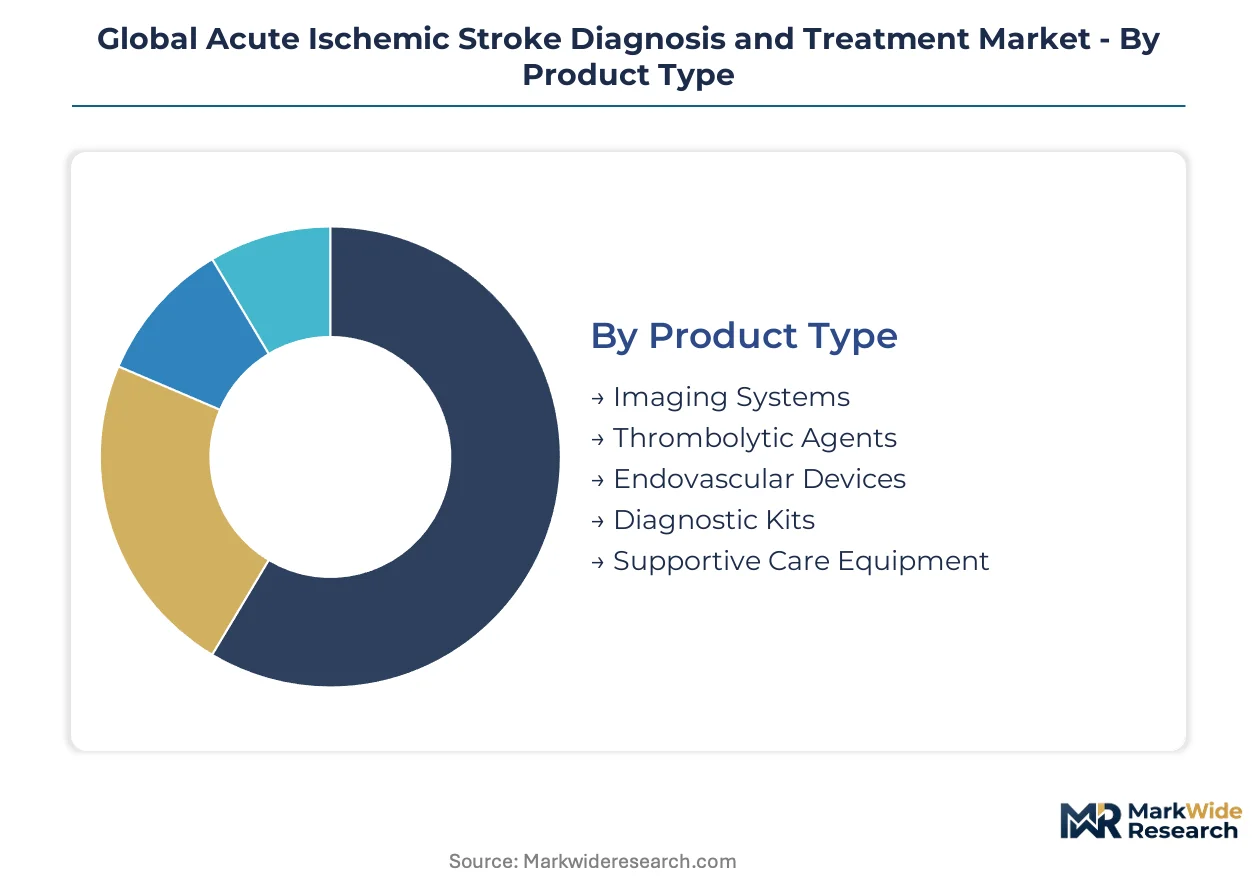
Segmentation in acute ischemic stroke markets reveals how capital flows cluster around high-throughput intervention sites versus distributed diagnostic networks. Understanding these divisions exposes where procurement leverage concentrates and which modalities face reimbursement pressure.
Product Type:
Supply concentration in catheter manufacturing and imaging componentry shapes competitive dynamics across hardware categories.
- Imaging Systems:CT angiography and perfusion imaging platforms integrate AI-powered large vessel occlusion detection. Demand clusters in United States comprehensive stroke centers where Joint Commission mandates 24/7 capability and biplane angiography suites command premium capital budgets.
- Endovascular Devices:Stent retrievers, aspiration catheters, and access platforms constitute the intervention backbone. German and Japanese stroke centers drive adoption of next-generation distal access technologies as regulatory pathways under EMA MDR and PMDA Sakigake compress approval timelines.
- Thrombolytic Agents:Recombinant tissue plasminogen activator formulations remain standard pharmacological intervention.
- Diagnostic Kits:Point-of-care coagulation and biomarker assays support rapid triage decisions.
- Supportive Care Equipment:Neurocritical monitoring and ventilation systems manage post-intervention stabilization.
Imaging Systems and Endovascular Devices absorb the bulk of installed capacity; Diagnostic Kits are expanding most quickly through prehospital deployment models.
Therapy Area:
Reimbursement intensity varies sharply between time-critical intervention and longitudinal recovery services.
- Blood Flow Restoration:Mechanical thrombectomy and intravenous thrombolysis command the highest procedural reimbursement codes. United States CMS payment adjustments and German DRG structures prioritize rapid revascularization over alternative modalities.
- Neurological Assessment:NIH Stroke Scale standardization and automated severity scoring integrate into electronic health records. Japanese university hospitals and United Kingdom NHS trusts deploy these systems for protocol-driven triage consistency.
- Neuroprotection:Cytoprotective agents and temperature modulation therapies remain investigational.
- Acute Care Management:ICU protocols and complication prevention frameworks support post-intervention outcomes.
- Rehabilitation:Motor and speech therapy services extend care timelines beyond acute episodes.
Blood Flow Restoration captures dominant reimbursement share; Neurological Assessment is climbing the fastest through AI-enabled standardization.
End User:
Site certification requirements create tiered purchasing authority and device specification power.
- Stroke Centers:Comprehensive and primary stroke center designations under Joint Commission, German stroke unit certification, and Japan Stroke Society accreditation mandate specific device inventories. These facilities consolidate thrombectomy volume and negotiate bundled procurement contracts.
- Emergency Medical Services:Prehospital stroke identification and transport protocols determine patient routing to intervention-capable sites. Mobile stroke units in Houston, Berlin, and Tokyo pilot CT-equipped ambulances for field-based triage.
- Diagnostic Laboratories:Reference labs process biomarker panels and genetic risk stratification.
- Neurology Clinics:Outpatient settings manage secondary prevention and follow-up imaging.
- Rehabilitation Facilities:Post-acute care centers coordinate long-term functional recovery.
Stroke Centers concentrate device purchasing authority; Emergency Medical Services is gaining share fastest through mobile diagnostic expansion.
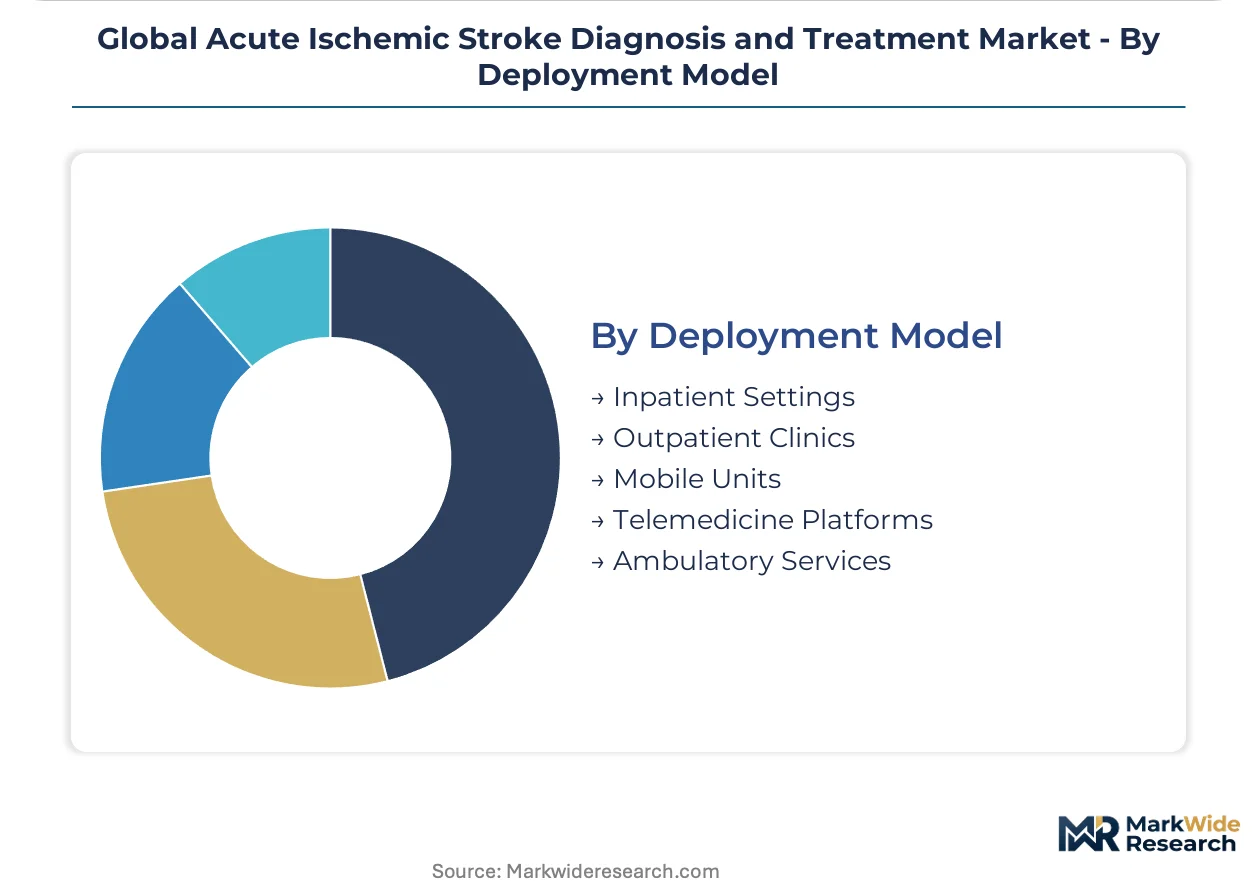
Deployment Model:
Capital intensity and regulatory jurisdiction shift across care settings from fixed infrastructure to distributed access.
- Inpatient Settings:Hospital-based angiography suites and neurocritical care units require shielded construction and specialized staffing. Lead times for United States and German facility installations extend 18-24 months, freezing competitive positioning until certification completion.
- Telemedicine Platforms:FDA-cleared and EMA-notified remote consultation systems extend specialist coverage to underserved geographies. Rural United States hospitals and Nordic regional networks deploy these for 24/7 large vessel occlusion confirmation.
- Mobile Units:CT-equipped ambulances enable field diagnosis and direct thrombectomy center routing.
- Outpatient Clinics:TIA assessment and risk factor management occur in lower-acuity settings.
- Ambulatory Services:Same-day discharge protocols for selected post-thrombectomy patients.
Inpatient Settings retain dominant capital deployment; Telemedicine Platforms are expanding most quickly through regulatory clearance acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platinum-iridium alloy feedstock from South African and Russian sources anchors device manufacturing geography, concentrating catheter and guidewire production in Germany, the United States, and Japan where fabrication capabilities align with regulatory clearance pathways.
United States
FDA breakthrough device designation for stent retrievers and aspiration catheters accelerates manufacturer time-to-market. Joint Commission comprehensive stroke center certification mandates 24/7 thrombectomy capability, driving capital expenditure across hospital networks. Houston and Los Angeles stroke centers pilot mobile CT-equipped ambulances for field-based triage.
Germany
German stroke unit certification under the German Stroke Society standardizes device inventory requirements across academic medical centers. EMA MDR Article 117 convergence for drug-device combination products creates regulatory harmonization opportunities for intra-arterial thrombolytic partnerships. Berlin and Munich comprehensive stroke centers drive adoption of next-generation distal access technologies.
Japan
PMDA Sakigake priority review delivers six-month market exclusivity premiums for AI-powered perfusion imaging software entrants. Japan Stroke Society accreditation requirements concentrate thrombectomy volume in designated comprehensive stroke centers. Tokyo and Osaka university hospitals deploy automated NIH Stroke Scale standardization systems for protocol-driven triage consistency.
United Kingdom
NHS England stroke service reconfiguration consolidates thrombectomy referrals into hyper-acute stroke units, concentrating device procurement authority. MHRA post-Brexit regulatory autonomy maintains alignment with EMA MDR quality management standards for neurointerventional devices. London and Greater Manchester regional networks deploy telemedicine platforms for 24/7 large vessel occlusion confirmation.
Switzerland
Swissmedic expedited review pathways for software as medical device applications reward manufacturers with prospective multi-center registry data. ISO 13485 quality management recertification cycles govern manufacturing compliance for catheter and guidewire producers. Basel and Zurich medical technology clusters anchor precision component fabrication for neurovascular access platforms.
Global Acute Ischemic Stroke Diagnosis and Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-powered imaging interpretation and robotic catheter navigation. The market structure consolidates around integrated neurovascular portfolios, with device manufacturers competing on regulatory clearance speed and bundled procurement contracts. Three archetypes dominate: diversified medtech conglomerates with endovascular divisions, pure-play neurointerventional specialists, and imaging system vendors integrating AI triage. Competitive moves center on M&A for catheter manufacturing capabilities and strategic partnerships for platinum-iridium supply security.
Among diversified medtech conglomerates, Stryker Corporation and Medtronic plc exemplify the integrated portfolio archetype, anchoring positions through mechanical thrombectomy systems and neurovascular access technologies. Siemens Healthineers occupies a distinct tier at the imaging-software convergence point, representing vendors who differentiate via CT angiography and perfusion imaging platforms that guide treatment decisions. These three entities collectively illustrate how competitive positioning stratifies across intervention hardware, diagnostic systems, and integrated care pathways.
| Leading Market Players |
|---|
| Abbott Laboratories |
| GE Healthcare |
| Stryker Corporation |
| Penumbra, Inc. |
| Philips Healthcare |
| Johnson & Johnson |
| Siemens Healthineers |
| Boston Scientific Corporation |
| Medtronic plc |
| Others |
Supply & Pricing Matrix
Platinum-iridium alloy price volatility from South African and Russian mining output cascades through catheter manufacturing into three-tier pricing structures across premium, standard, and economy levels for neurointerventional devices. This raw material cost pressure concentrates in German and United States fabrication facilities, where ISO 13485-certified producers pass feedstock fluctuations into bundled procurement contracts with comprehensive stroke centers.
Pricing Analysis
Warranty and service-bundling separates premium-tier stent retrievers with 24/7 technical support from unbundled standard offerings. Pricing stratifies across premium, standard, and economy tiers based on FDA breakthrough designation status and procedural volume commitments. Cost compression in economy-tier aspiration catheters is intensifying because integrated delivery networks command 15-20% price concessions through consolidated purchasing. Community hospitals exhibit highest price sensitivity due to constrained capital budgets, while academic medical centers prioritize clinical outcomes over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Japan anchor hub-and-spoke patterns for finished neurointerventional devices. Microcatheter and guidewire production draws from South African platinum-iridium feedstock and Japanese nitinol wire suppliers. Single-source vulnerability in Russian palladium exports exposes manufacturers to geopolitical disruption. Distribution runs through hospital procurement departments and group purchasing organizations rather than traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EMA MDR quality management recertification cycles create barrier-to-entry moats for manufacturers with established notified body relationships.
For Market Incumbents: Deepen backward integration into platinum-iridium supply channels to offset South African and Russian feedstock concentration. Fortify ISO 13485 audit readiness to exploit notified body capacity constraints freezing competitor product launches. Expand captive catheter manufacturing in Germany to compress lead times for EMA MDR Article 117 combination product pathways. For New Entrants and Emerging Players: Telemedicine platform partnerships offer the most penetrable entry vector for AI-powered large vessel occlusion detection software. Target rural United States hospitals and Nordic regional networks where specialist scarcity creates urgent demand for remote consultation capabilities. Pursue FDA Software as Medical Device clearance with prospective multi-center registry data rather than retrospective single-site studies. For Investors and Strategic Acquirers: Distressed-cycle entries favor AI-enabled perfusion imaging specialists in Japan where PMDA Sakigake priority review delivers six-month exclusivity premiums. Long-term viability hinges on regulatory clearance velocity rather than manufacturing scale. Watch for ISO 13485 recertification backlogs as inflection indicator for acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR Article 117 harmonization accelerates drug-device combination product launches. |
| Hospital System Partnership | Integrated delivery network contracts secure 15-20% price premiums over independent facilities. |
| Software Companion Development | FDA-cleared AI triage algorithms reduce door-to-groin time for thrombectomy candidacy. |
| Reimbursement Strategy | CMS inpatient prospective payment system navigation protects margin structures for high-volume centers. |
| Backward Integration | Captive platinum-iridium supply hedges South African and Russian geopolitical exposure. |
Research Methodology
Independent corroboration across primary interviews with interventional neuroradiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers underwrites the qualitative findings. Secondary validation draws from FDA 510(k) filings, EMA MDR technical documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchor volume and value estimates.
Comparable-period anchoring to historical neurointerventional device adoption curves and thrombectomy procedure volumes structures the forecast framework across the analysis window. Segmentation dimensions span product type, therapy area, end user certification tier, and deployment model. CAGRs derive from procedural volume trajectories, regulatory approval timelines, and reimbursement policy shifts rather than extrapolated trend lines.
The model holds under stable platinum-iridium supply conditions and sustained FDA breakthrough designation velocity; deviation in notified body capacity constraints or CMS payment adjustments would shift competitive positioning. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Vacuum Therapy Devices Market
Diagnostic and Therapeutic Devices
Global Far Infrared Therapy Device Market
Diagnostic and Therapeutic Devices
Therapeutic Hypothermia Systems Market
Diagnostic and Therapeutic Devices
Nanobiosensors in Healthcare Market
Diagnostic and Therapeutic Devices
Robotic Surgery System Haptic Feedback Test Platforms Market
Diagnostic and Therapeutic Devices
Microneedle Drug Delivery Systems Market
Diagnostic and Therapeutic Devices
Global Needle Free Injection Systems Market
Diagnostic and Therapeutic Devices
Crohn's Disease Diagnostic and Therapeutic Market
Diagnostic and Therapeutic Devices
Positive Patient Identification Market
Diagnostic and Therapeutic Devices
Fully Automated Coagulometer Market
Diagnostic and Therapeutic Devices
Venous Diseases Treatment Market
Diagnostic and Therapeutic Devices
Breast Lesion Localization Market
Diagnostic and Therapeutic Devices
Skin Biopsy Market
Diagnostic and Therapeutic Devices
Anti Neurofilament L Antibody Market
Diagnostic and Therapeutic Devices
Global Smart Healthcare Products Market
Diagnostic and Therapeutic Devices
Therapeutic Support Surface Market