
 Pelvic Congestion Syndrome Treatment Market | 2026-2036
Pelvic Congestion Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Pelvic Congestion Syndrome Treatment Market Analytics
Hospital procurement for pelvic congestion syndrome interventions is collapsing as ambulatory surgical centers capture a growing share of embolization procedures. Boston Scientific anchors the interventional device segment through its established venous embolization portfolio. Pfizer competes in the pharmaceutical management layer with hormone-modulating therapies that address underlying venous dilation. TOLMAR specializes in depot formulations that sustain symptom control between procedural interventions.
Pelvic congestion syndrome treatment encompasses minimally invasive embolization, pharmacological suppression of ovarian vein reflux, and advanced diagnostic imaging to identify venous incompetence; embolic agents typically consist of synthetic polymers or mechanical coils delivered via transcatheter access to occlude dilated pelvic veins, restoring normal hemodynamics and alleviating chronic pelvic pain. Minimally invasive surgery commands the dominant value share due to superior recurrence prevention versus medication alone, while diagnostic imaging experiences rapid expansion as ultrasound-based screening protocols shorten time-to-diagnosis. Sclerotherapy technology leads procedural volume in European centers, though MRI-guided mapping captures premium pricing in complex recurrent cases.
The FDA regulates embolic device safety and efficacy under PMA and 510(k) pathways, while the EU MDR imposes strengthened clinical evidence requirements for permanent implantable agents used in pelvic venous interventions. HIPAA compliance constraints shape how U.S. outpatient clinics share imaging data across referral networks. Stakeholders must monitor reimbursement coding evolution for office-based venous embolization as site-of-service economics redraw competitive boundaries.
Market Dynamics
Site-of-service economics is restructuring pelvic congestion syndrome treatment as ambulatory surgical centers capture embolization volume from hospitals, compressing reimbursement differentials and forcing equipment manufacturers to redesign delivery systems for outpatient workflows.
Growth Catalysts
- EU MDR clinical evidence mandates:Strengthened post-market surveillance requirements for permanent implantable embolic agents are accelerating adoption of well-documented synthetic polymer formulations over experimental alternatives.
- Germany's integrated vein center model:Specialized pelvic vein facilities in Munich and Hamburg combine duplex ultrasound diagnostics with same-day therapeutic intervention, shortening patient pathways.
- Contrast-enhanced ultrasound protocols:Refinements in microbubble imaging technology enable office-based venous incompetence screening without MRI scheduling delays.
Market Restraints
- Reimbursement coding fragmentation:CMS site-of-service differentials create arbitrage incentives that destabilize hospital-based interventional programs.
- Embolic agent supply concentration:Specialty polymer production clusters in Switzerland and Germany expose the market to single-source dependency risks.
- Diagnostic specificity limitations:Pelvic venography's invasive nature restricts definitive confirmation to tertiary referral centers.
Strategic Opportunities
- India's underpenetrated gynecology clinic network:Urban private hospital chains in Mumbai and Delhi lack dedicated chronic pelvic pain interventional services.
- AI-assisted venous mapping:Machine learning algorithms applied to Doppler ultrasound sequences reduce operator-dependent diagnostic variability.
- Office-based sclerotherapy expansion:Foam sclerosant formulations enable procedure migration from operating rooms to outpatient suites.
Industry Challenges
- Interventional radiology workforce gaps:Fellowship-trained pelvic venous specialists remain concentrated in academic medical centers.
- Dual-coding complexity:Separate diagnostic and therapeutic billing requirements complicate revenue cycle management for integrated vein centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pelvic Congestion Syndrome Treatment Market |
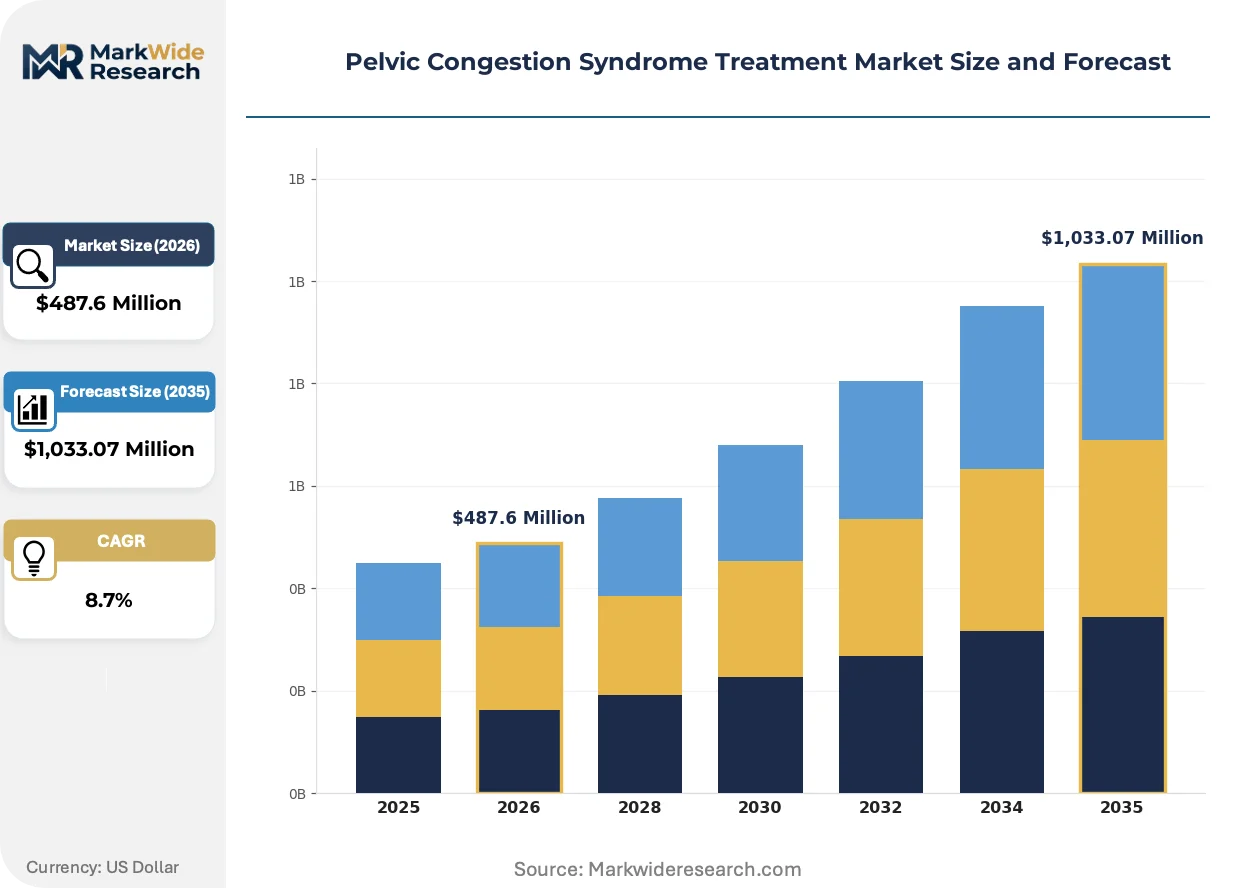
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Minimally Invasive Surgery, Medication, Diagnostic Imaging, Lifestyle Modification Technology: Ultrasound, CT Scan, MRI, Sclerotherapy End User: Hospitals, Clinics, Home Care, Ambulatory Surgical Centers Application: Therapeutic, Diagnostic, Preventive, Follow-up Care |
| Companies Covered | Pfizer, AbbVie, Sanofi, Novartis, AstraZeneca, TOLMAR, Debiopharm Group, Johnson & Johnson, Boston Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pelvic Congestion Syndrome Treatment Market Evolving Landscape
Convergence between advanced imaging modalities and minimally invasive delivery systems is compressing the diagnostic-to-treatment interval, while regulatory frameworks on both sides of the Atlantic recalibrate evidence thresholds for permanent implants.
Mechanical detachable coil systems are decomposing the traditional trade-off between procedural precision and permanent occlusion reliability. Interventional radiologists in US ambulatory surgical centers are adopting these devices for complex ovarian vein anatomy. The technology is decomposing market share concentration among legacy embolic platforms by enabling safer distal deployment.
The FDA's evolving guidance on embolic devices for venous indications is tightening predicate device comparability standards for 510(k) submissions. Manufacturers now face expanded clinical data requirements demonstrating sustained occlusion rates beyond twelve months. Transcatheter delivery system developers are responding by embedding radio-opaque markers that enable real-time position confirmation under fluoroscopy.
Patient self-referral patterns are accelerating as direct-to-consumer imaging platforms advertise pelvic vein screening. Gynecology practices in Germany and the United States are establishing dedicated chronic pelvic pain clinics to capture this demand. The shift compresses traditional primary-care-to-specialist referral cycles and pressures diagnostic imaging providers to offer same-day result interpretation.
Pelvic Congestion Syndrome Treatment Market Segmentation
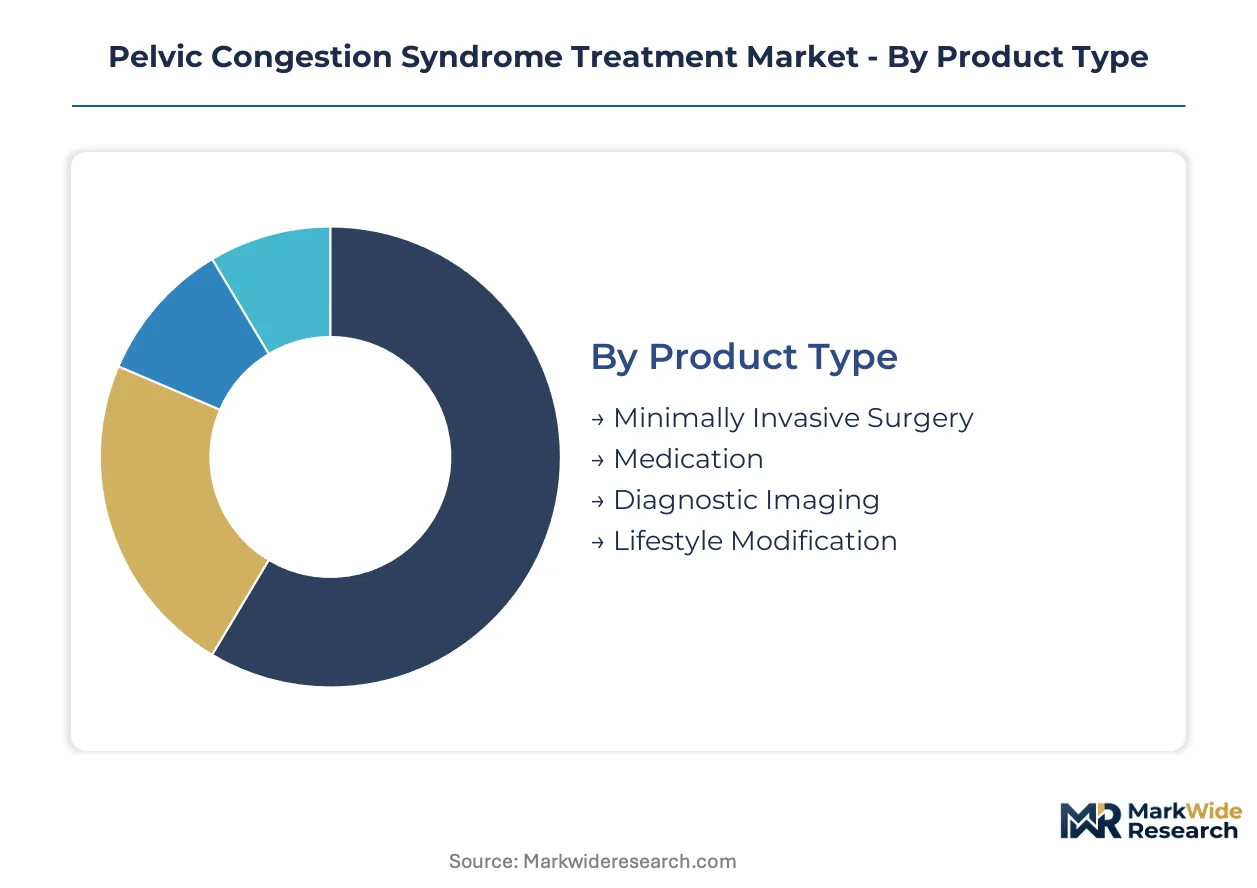
Segmentation in pelvic congestion syndrome treatment reveals how site-of-service economics and diagnostic modality preferences split purchasing decisions across care settings. Treatment pathways diverge sharply between procedural intervention and pharmaceutical management, with reimbursement codes reinforcing these boundaries.
Product Type:
Substitution pressure runs strongest against lifestyle modification as minimally invasive surgery proves cost-effective for recurrent cases and medication offers lower upfront commitment for initial management.
- Minimally Invasive Surgery:Embolization and sclerotherapy procedures deliver permanent venous occlusion through transcatheter access. Demand concentrates in ambulatory surgical centers across Germany and the United States as site-of-service economics compress hospital reimbursement. The FDA's evolving PMA pathway requirements favor established device platforms with twelve-month occlusion data.
- Medication:Hormone-modulating therapies suppress ovarian vein reflux through estrogen suppression or progesterone modulation. Pfizer's portfolio and TOLMAR's depot formulations dominate prescribing patterns in gynecology clinics seeking non-procedural alternatives for mild-to-moderate presentations.
- Diagnostic Imaging:Contrast-enhanced ultrasound and MRI protocols enable definitive venous incompetence identification. Microbubble imaging refinements support office-based screening without MRI scheduling delays.
- Lifestyle Modification:Compression garments and activity recommendations serve adjunctive roles. Limited reimbursement codes restrict commercial viability outside integrated vein centers bundling conservative management with procedural options.
Minimally invasive surgery retains volume leadership; diagnostic imaging holds the steepest expansion curve.
Technology:
Cost tier differentiation separates premium MRI-guided mapping from standard ultrasound screening, with CT scan occupying a mid-tier position for complex anatomy assessment.
- Ultrasound:Duplex and contrast-enhanced modalities enable office-based venous incompetence screening. Germany's integrated vein centers in Munich and Hamburg deploy same-day ultrasound-to-treatment workflows that compress patient pathways.
- Sclerotherapy:Foam sclerosant formulations enable procedure migration from operating rooms to outpatient suites. European centers lead procedural volume adoption as office-based protocols reduce facility fees.
- MRI:Magnetic resonance venography captures premium pricing in complex recurrent cases requiring three-dimensional pelvic vein mapping. HIPAA compliance constraints shape how U.S. outpatient clinics share imaging data across referral networks.
- CT Scan:Computed tomography venography serves tertiary referral centers requiring rapid anatomical assessment. Radiation exposure limits limit deployment in fertility-preserving patient populations.
Ultrasound retains volume leadership; sclerotherapy gains share fastest through office-based expansion.
End User:
Customer type stratification reflects procurement authority divergence between hospital-based interventional radiology departments and independently purchasing ambulatory surgical centers.
- Ambulatory Surgical Centers:Independent facilities capture embolization volume from hospitals through site-of-service reimbursement differentials. Equipment manufacturers redesign delivery systems for outpatient workflows.
- Hospitals:Academic medical centers retain complex recurrent cases and fellowship training programs. Interventional radiology workforce gaps concentrate specialists in these settings.
- Clinics:Gynecology practices establish dedicated chronic pelvic pain clinics to capture patient self-referral demand. Same-day result interpretation pressures diagnostic imaging providers.
- Home Care:Post-procedural monitoring and conservative management support limited device and service deployment. Reimbursement fragmentation constrains scalable business models.
Ambulatory surgical centers retain volume leadership; clinics hold the steepest expansion curve.
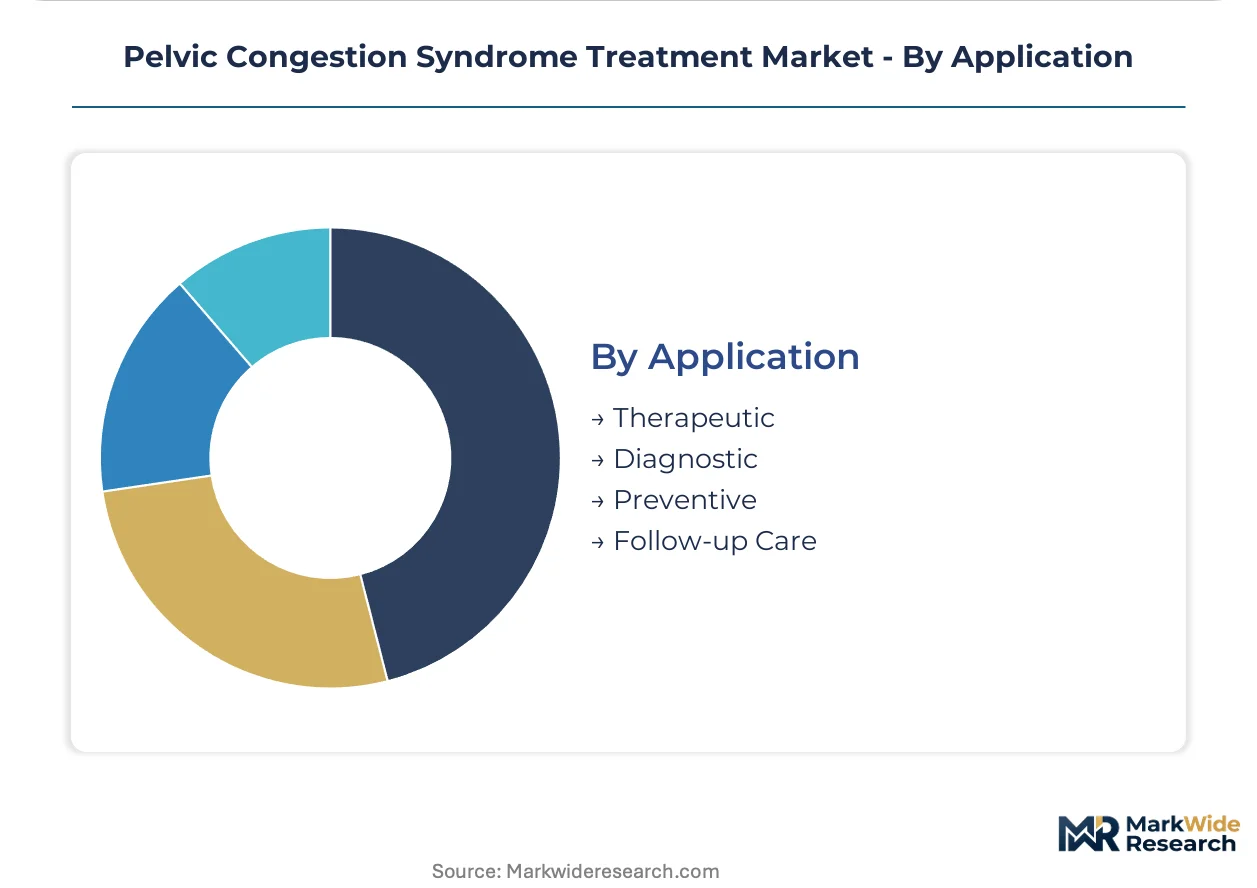
Application:
Volume distribution across the care continuum favors therapeutic intervention over preventive screening, though diagnostic application growth accelerates with direct-to-consumer imaging platform advertising.
- Therapeutic:Embolization and sclerotherapy procedures address confirmed venous incompetence. Boston Scientific's venous embolization portfolio anchors hospital and ambulatory purchasing.
- Diagnostic:Venography and imaging protocols enable definitive pelvic vein assessment. AI-assisted venous mapping applied to Doppler ultrasound sequences reduces operator-dependent variability.
- Follow-up Care:Surveillance imaging and symptom monitoring protocols support recurrence detection. Integrated vein centers bundle follow-up into procedural episode payments.
- Preventive:Screening protocols for high-risk multiparous populations remain underdeveloped. Patient self-referral patterns compress traditional primary-care-to-specialist referral cycles.
Therapeutic application retains volume leadership; diagnostic application climbs the fastest as screening protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers of embolic devices supply ambulatory surgical centers across the United States and Western Europe, while Swiss polymer producers anchor specialty material flows into catheter delivery systems worldwide.
United States
Patient self-referral patterns accelerate demand for office-based pelvic vein screening, while the FDA tightens predicate device comparability standards for 510(k) submissions. HIPAA compliance constraints reshape how outpatient clinics share imaging data across referral networks. Interventional radiology workforce gaps concentrate fellowship-trained specialists in academic medical centers in Boston and Baltimore.
Germany
Integrated vein centers in Munich and Hamburg combine duplex ultrasound diagnostics with same-day therapeutic intervention, compressing patient pathways significantly. The EU MDR imposes strengthened clinical evidence requirements for permanent implantable embolic agents used in pelvic venous interventions. Specialized pelvic vein facilities anchor European procedural volume leadership and drive adoption of contrast-enhanced ultrasound protocols.
Switzerland
Specialty polymer production for embolic agents clusters around Basel and Zurich, creating single-source dependency risks for global supply chains. Swissmedic maintains rigorous post-market surveillance standards for permanent implantable devices. The country's precision chemical manufacturing base supports consistent quality in synthetic polymer formulations for venous occlusion.
United Kingdom
Gynecology practices in London and Manchester establish dedicated chronic pelvic pain clinics to capture direct-to-consumer imaging demand. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR transition timelines for device approvals. Private hospital chains in the Southeast expand interventional radiology capacity for outpatient embolization procedures.
India
Urban private hospital chains in Mumbai and Delhi lack dedicated chronic pelvic pain interventional services, creating penetration opportunities for procedural training programs. The Central Drugs Standard Control Organization regulates embolic device imports under medical device rules. Diagnostic imaging providers in Bangalore and Hyderabad deploy AI-assisted venous mapping to reduce operator-dependent variability in Doppler ultrasound interpretation.
Pelvic Congestion Syndrome Treatment Market Competitive Landscape
Listed leaders compete with private specialists across device and pharmaceutical layers, creating a tiered structure where scale-driven multinationals anchor interventional portfolios while focused firms occupy hormone-modulating niches. The market separates into three strategic archetypes: diversified medical device conglomerates with venous embolization platforms, pharmaceutical majors with gynecology prescribing relationships, and specialty formulation developers with depot delivery expertise. Competitive moves center on site-of-service workflow redesign for ambulatory settings and clinical evidence generation for twelve-month occlusion durability.
Within the device archetype, Boston Scientific occupies a position exemplifying established venous embolization portfolio breadth, while TOLMAR represents specialty formulation developers focused on sustained-release hormone therapies. Pfizer sits within the pharmaceutical tier, anchoring hormone-modulating prescribing patterns in gynecology clinics. These three firms collectively illustrate how competitive positioning splits between procedural intervention and pharmacological management layers.
| Leading Market Players |
|---|
| Pfizer |
| AbbVie |
| Sanofi |
| Novartis |
| AstraZeneca |
| TOLMAR |
| Debiopharm Group |
| Johnson & Johnson |
| Boston Scientific |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day lead times for specialty polymer embolic agents concentrate pricing power among Swiss and German manufacturers, while ambulatory surgical centers exploit site-of-service reimbursement differentials to compress hospital procurement premiums. This inventory dynamic ties catheter delivery system costs to Basel-Zurich polymer availability and shapes how device makers negotiate long-term supply agreements against fluctuating resin prices.
Pricing Analysis
Current-generation mechanical detachable coil systems command 40-60% premiums over legacy foam sclerosant formulations, while next-generation MRI-compatible markers face development-cost recapture pressures. Three-tier pricing structure across premium coil platforms, standard sclerosant procedures, and economy-tier diagnostic bundles separates academic medical center procurement from ambulatory surgical center volume discounts. Cost compression in standard embolization tiers is intensifying because Boston Scientific and Johnson & Johnson deploy direct-to-ASC distribution models that bypass GPO markups. Gynecology clinics in Germany and the United States exhibit highest price sensitivity due to bundled episode-payment constraints, while tertiary referral centers in Switzerland and the United Kingdom show lowest sensitivity given complex-case premium allowances.
Supply Chain Analysis
Container availability constraints on Rotterdam-Hamburg trade lanes delay specialty polymer shipments from Basel manufacturing clusters, forcing device assemblers to hold elevated safety stock. Geographic supply concentration centers on Switzerland for embolic agent polymers, Germany for catheter extrusion and coil winding, and the United States for final device sterilization and packaging. Raw material dependencies include medical-grade polyurethane resins, platinum-iridium alloy wire for radiopacity, and nitinol shape-memory elements for detachable coil systems. Single-source vulnerability runs through Swiss polymer producers exposed to Swissmedic batch-release delays. Distribution runs through specialized medical device distributors serving hospital interventional radiology departments and direct manufacturer-to-ASC logistics partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ambulatory surgical center consolidation into national chains across Germany and the United States is shifting procurement leverage toward buyers capable of multi-site volume commitments, fragmenting hospital-based purchasing power.
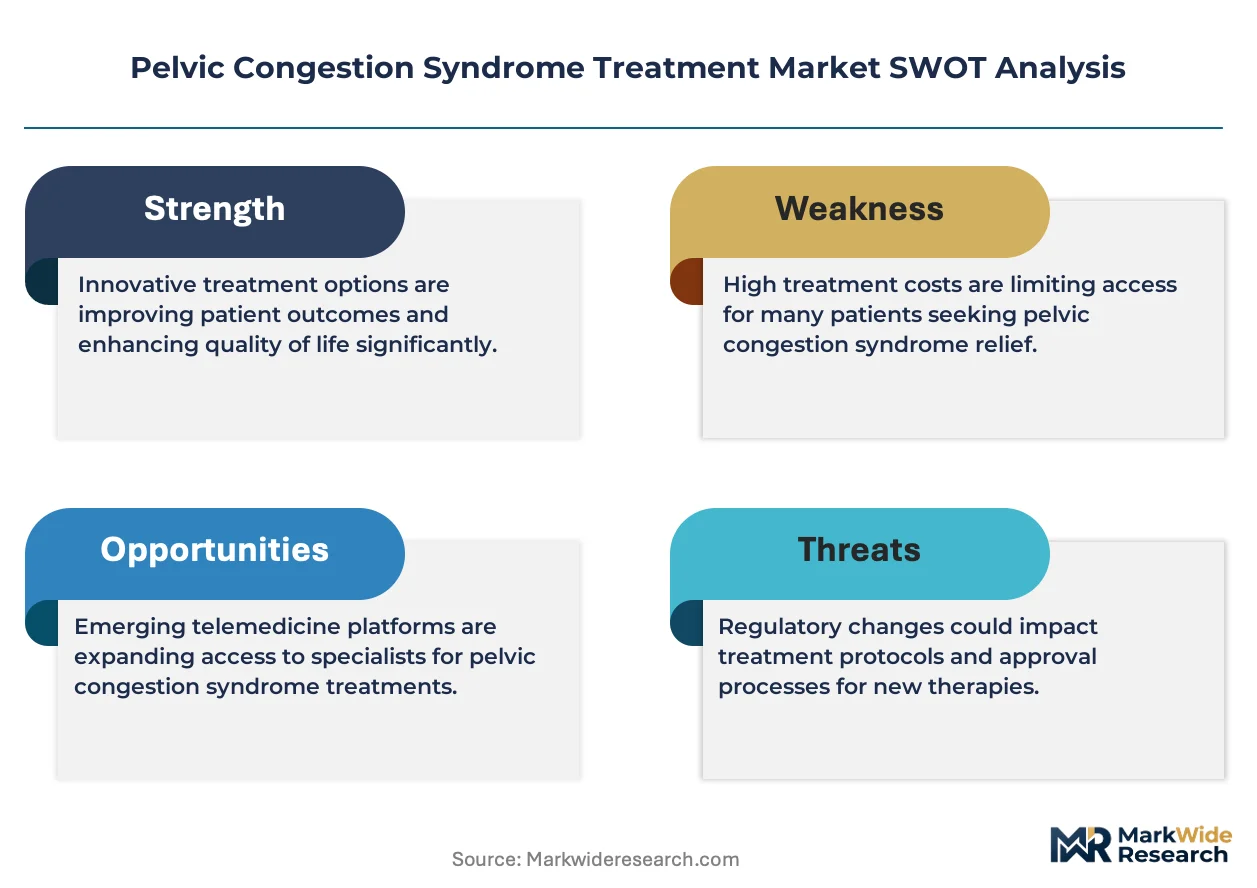
For Market Incumbents: Secure twelve-month occlusion durability data ahead of FDA PMA pathway tightening to defend against mechanical detachable coil substitutes eroding legacy platform share. Deepen backward integration into nitinol wire production to offset platinum-iridium cost volatility and protect margin structure against Swiss polymer supply shocks. For New Entrants and Emerging Players: Post-procedural monitoring services represent an underdeveloped layer where incumbents under-serve ASCs seeking bundled episode accountability. Target India's urban private hospital chains in Mumbai and Delhi for interventional radiology training partnerships, deploying AI-assisted venous mapping as a differentiated go-to-market anchor against operator-dependent diagnostic variability. For Investors and Strategic Acquirers: Long-term, this sits as a site-of-service migration play because reimbursement economics irreversibly favor outpatient procedural migration over hospital-based intervention. Acquisition focus should center on device makers with CE-marked platforms and established German vein center relationships, monitoring CMS site-of-service differential adjustments as the critical inflection signal for valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Pathway Optimization | Twelve-month occlusion data requirements under evolving PMA guidance favor established synthetic polymer platforms over experimental alternatives. |
| CE Marking Pathway Investment | EU MDR post-market surveillance mandates accelerate adoption of well-documented embolic agents in German integrated vein centers. |
| Hospital System Partnership | Academic medical centers in Boston and Baltimore retain complex recurrent cases requiring fellowship-trained pelvic venous specialist access. |
| Software Companion Development | AI-assisted venous mapping applied to Doppler ultrasound sequences reduces operator-dependent diagnostic variability in Bangalore and Hyderabad deployments. |
| Reimbursement Strategy Alignment | CMS site-of-service differential tracking enables manufacturers to redesign delivery systems for ASC workflow capture ahead of coding shifts. |
Research Methodology
Initial hypotheses were tested against primary input from interventional radiologists, hospital purchasing committee members, gynecology clinic directors, and GPO contracts managers and refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up procedure volume estimates from ambulatory surgical centers and hospitals across Germany, Switzerland, the United Kingdom, and the United States were triangulated against top-down market sizing derived from manufacturer shipment data and polymer import customs records.
Variance decomposition across the projection horizon isolates volume drivers by treatment modality, technology generation, and end-user procurement authority. Segmentation dimensions modeled include procedural intervention versus pharmaceutical management, ultrasound versus sclerotherapy versus MRI technology tiers, and ASC versus hospital versus clinic site-of-service economics. CAGRs were derived from logarithmic trend fitting to procedure volume trajectories, incorporating EU MDR implementation timelines and FDA guidance evolution as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FDA PMA/510(k) pathways and EU MDR post-market surveillance regimes; material policy shifts would require re-modeling. Specific risk factors include Swissmedic batch-release disruptions for embolic polymers, CMS site-of-service reimbursement recalibration, and interventional radiology fellowship pipeline contraction. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Pressure Ulcer Relief Products Market
Diagnostic and Therapeutic Devices
Nanobiosensors in Healthcare Market
Diagnostic and Therapeutic Devices
Therapeutic Hypothermia Systems Market
Diagnostic and Therapeutic Devices
Global Acoustic Medicine and Ultrasound Therapy Market
Diagnostic and Therapeutic Devices
Fully Automated Coagulometer Market
Diagnostic and Therapeutic Devices
Therapeutic Bed Market
Diagnostic and Therapeutic Devices
Therapeutic Support Surface Market
Diagnostic and Therapeutic Devices
Disposable Negative Pressure Wound Therapy Devices Market
Diagnostic and Therapeutic Devices
Upper GI Series Market
Diagnostic and Therapeutic Devices
Smart Infusion System Market
Diagnostic and Therapeutic Devices
Magnetic Therapy Devices Market
Diagnostic and Therapeutic Devices
Automated Immunoassay Analyzers Market
Diagnostic and Therapeutic Devices
Phototherapy Device Market
Diagnostic and Therapeutic Devices
Electroceuticals Bioelectric Medicine Market
Diagnostic and Therapeutic Devices
Positive Patient Identification Market
Diagnostic and Therapeutic Devices
Intracranial Hemorrhage Diagnosis and Treatment Market