
 Asia-Pacific Digital Therapeutic (Dtx) Market | 2026-2036
Asia-Pacific Digital Therapeutic (Dtx) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Digital Therapeutic (Dtx) Market Outlook
Telemedicine distribution is fragmenting across the Asia-Pacific Digital Therapeutic (Dtx) landscape as national reimbursement systems diverge. CureApp leverages its Japan-centric regulatory expertise to anchor premium positioning in smoking cessation and hypertension management. Ping An Good Doctor competes through integrated insurer-provider platforms that bundle DTx modules with primary care access across mainland China.
Asia-Pacific Digital Therapeutic denotes clinically validated software interventions delivered through apps, platforms, wearables, or online programs to prevent, manage, or treat medical conditions, requiring regulatory clearance as software-as-medical-device in most jurisdictions. These systems employ algorithm-driven personalization, biometric feedback loops, and remote patient monitoring to achieve measurable health outcomes reimbursable by payers. Diabetes management leads therapy area penetration due to established glucose monitoring integration and payer familiarity with chronic disease digital protocols. Mobile-based delivery dominates installation volumes, though hybrid architectures that combine cloud analytics with local device processing are capturing margin pools in enterprise hospital deployments.
Japan's PMDA, Australia's TGA, and South Korea's MFDS each maintain distinct software-as-medical-device classification pathways that determine market access timelines and clinical evidence burdens for DTx developers. China's NMPA has tightened algorithm transparency requirements for AI-enabled therapeutic software, reshaping product development priorities for vendors targeting the mainland. Stakeholders must monitor divergence between national reimbursement catalogs and software registration standards to prioritize market entry sequencing across the region.
Market Dynamics
Reimbursement fragmentation across Japan, Australia, and South Korea is forcing DTx vendors to build parallel regulatory capabilities rather than scalable regional platforms. Each national health technology assessment body applies distinct evidentiary standards for software-as-medical-device qualification, creating duplicative clinical trial burdens and delayed commercialization timelines for products seeking multi-market presence.
Growth Catalysts
- PMDA's SaMD Fast-Track Pathway:Japan's streamlined software-as-medical-device review compresses pre-market timelines for DTx products with predicate device equivalents, accelerating revenue recognition for developers with existing FDA or TGA clearances.
- Diabetes Management Integration:Continuous glucose monitor manufacturers in South Korea and Australia are opening API ecosystems to DTx platforms, enabling closed-loop therapeutic algorithms that qualify for chronic disease management reimbursement codes.
- Employer-Sponsored Mental Health:Large enterprise purchasers across Singapore and Hong Kong are adding prescription digital therapeutics to employee assistance program benefits, creating direct-to-payer channels bypassing traditional hospital procurement.
Market Restraints
- Algorithm Transparency Mandates:China's NMPA requires full disclosure of machine-learning model architectures for AI-enabled therapeutic software, exposing proprietary training methodologies to competitive replication.
- Clinical Evidence Cost Concentration:Randomized controlled trials for DTx reimbursement qualification in Australia consume 40-60% of pre-revenue development budgets, concentrating viable product pipelines among well-capitalized developers.
- Substitution by Wellness Apps:Non-regulated mental health and chronic disease management applications distributed through consumer app stores capture price-sensitive demand that might otherwise convert to prescription DTx.
Strategic Opportunities
- Indonesia's National Health Insurance Expansion:BPJS Kesehatan's digitization roadmap creates first-mover advantage for DTx platforms that localize hypertension and diabetes management protocols ahead of formal software-as-medical-device classification.
- Thailand's Medical Hub Policy:Board of Investment incentives for digital health infrastructure attract DTx developers establishing regional clinical trial and manufacturing operations serving Southeast Asian markets.
- Remote Patient Monitoring Convergence:Integration of wearable biosensors with cloud-based therapeutic algorithms enables hospital-at-home service models reimbursable under Australia's Hospital in the Home programs.
Industry Challenges
- Digital Therapeutics Specialist Scarcity:Clinical evidence generation for DTx requires hybrid expertise spanning regulatory science, health economics, and software engineering that remains concentrated in Tokyo, Sydney, and Seoul talent pools.
- Multi-Jurisdictional Compliance Burden:Simultaneous navigation of Japan's PMDA, Australia's TGA, and South Korea's MFDS software-as-medical-device frameworks demands dedicated regulatory affairs infrastructure that mid-scale developers struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Digital Therapeutic (Dtx) Market |
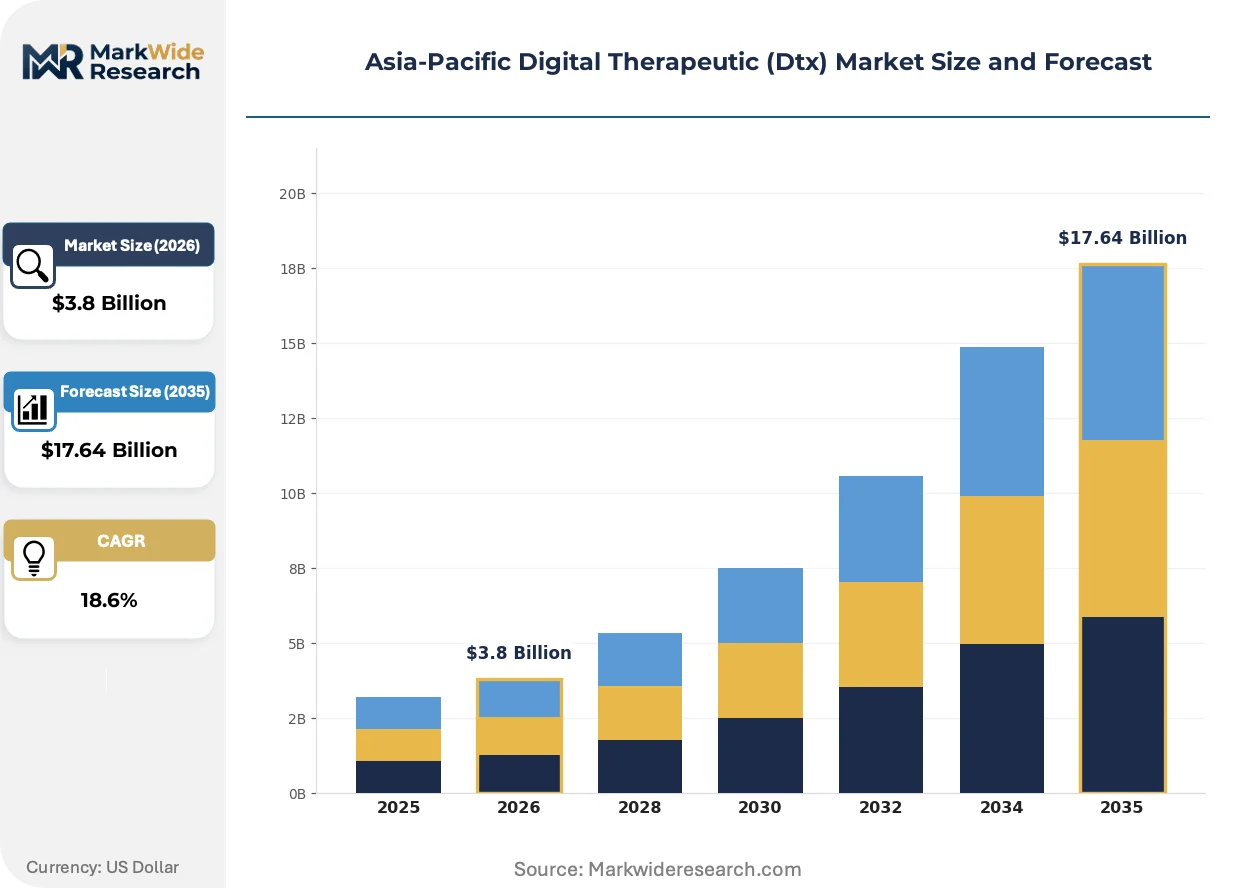
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apps, Platforms, Wearables, Online Programs Therapy Area: Mental Health, Diabetes Management, Cardiovascular, Chronic Pain End User: Patients, Providers, Payers, Caregivers Delivery Mode: Web-based, Mobile-based, Cloud-based, Hybrid |
| Companies Covered | CureApp, Ping An Good Doctor, Alibaba Health Information Technology Limited, Omron Healthcare, Doctor Anywhere, Lybrate, Wellthy Therapeutics, Zesty, GlucoMe, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Digital Therapeutic (Dtx) Market Strategic Shifts
Algorithmic personalization engines are displacing static protocol-based interventions across the Asia-Pacific DTx landscape, requiring developers to rearchitect products around real-time biometric feedback rather than pre-programmed content delivery schedules.
Edge computing architectures is hybridizing with cloud-based analytics in enterprise hospital deployments across Australia and Japan. Large tertiary care networks are adopting hybrid processing models that execute sensitive therapeutic algorithms on local servers while transmitting aggregated outcome data to centralized quality registries. This architecture compresses latency for acute intervention protocols while satisfying TGA and PMDA data sovereignty requirements that restrict cross-border patient information flows.
Australia's TGA has expanded its software-as-medical-device classification rules to encompass machine-learning-enabled diagnostic algorithms that adapt based on patient-specific data. This regulatory expansion captures previously unregulated clinical decision support tools, forcing developers to submit retrospective clinical validation studies or withdraw from the Australian market. Diabetes management platforms with adaptive insulin dosing recommendations face the most immediate compliance pressure.
Enterprise procurement teams at Singaporean and South Korean hospital networks are unbundling DTx modules from comprehensive electronic health record contracts, creating standalone purchasing decisions evaluated on outcomes-based metrics rather than system integration convenience. This behavioral shift fragments vendor relationships that previously concentrated through single-platform deals, enabling specialized DTx developers to compete against incumbent health IT suppliers on therapeutic efficacy rather than workflow integration breadth.
Asia-Pacific Digital Therapeutic (Dtx) Market Segmentation
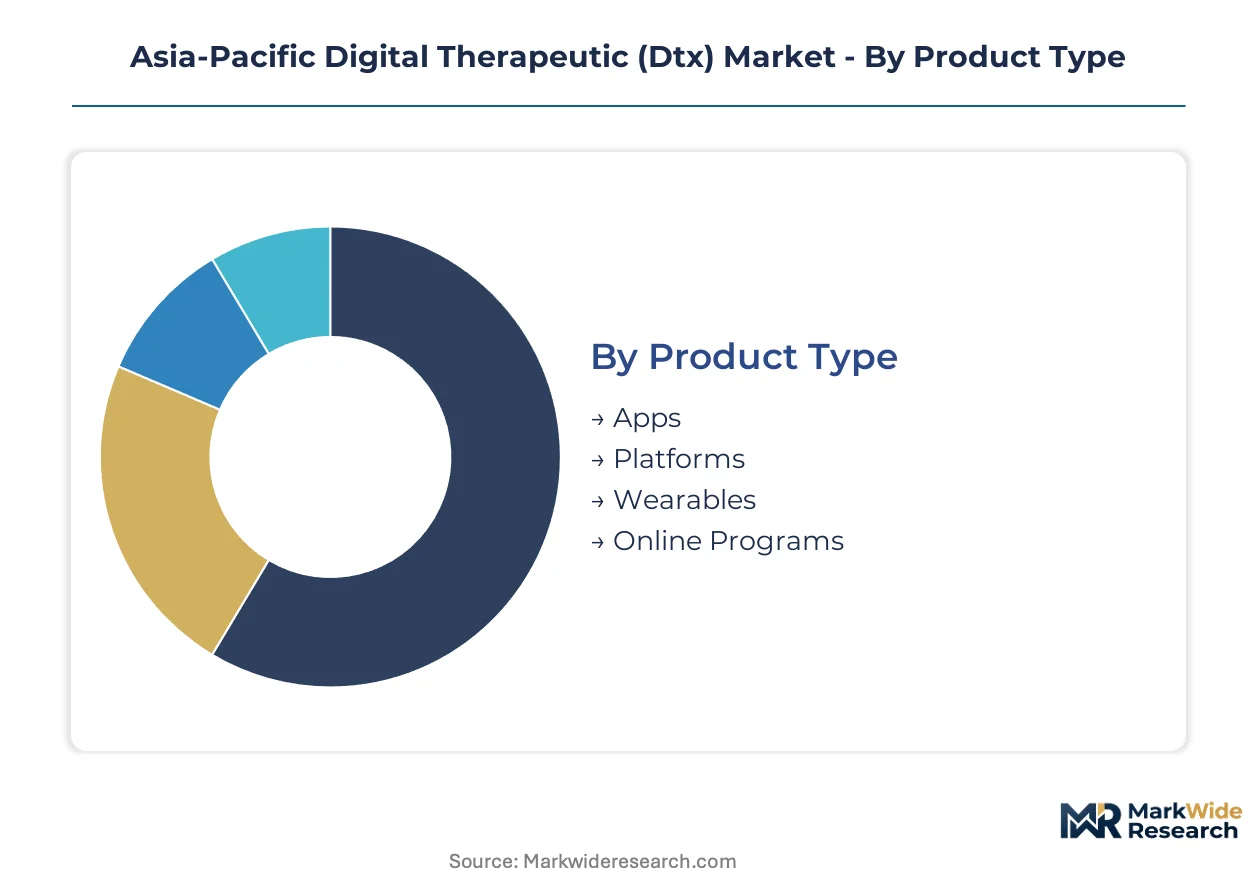
Segmentation in the Asia-Pacific DTx market reveals how reimbursement pathways, clinical evidence requirements, and technology infrastructure vary across product architectures and stakeholder groups. Vendors must align development priorities with specific national regulatory frameworks rather than pursuing uniform regional platforms.
Product Type:
Software delivery mechanisms span the use-case spectrum from consumer-grade wellness interfaces to prescription-grade therapeutic systems requiring PMDA or TGA clearance.
- Apps:Smartphone-native software with embedded biometric capture and algorithm-driven intervention protocols. Demand concentrates in Japan and South Korea where mobile-first healthcare consumption patterns dominate chronic disease management reimbursement pathways.
- Platforms:Enterprise-scale systems integrating electronic health record connectivity with therapeutic content delivery. Australia's Hospital in the Home programs and Singaporean employer-sponsored mental health schemes drive procurement of these comprehensive architectures.
- Wearables:Biosensor-integrated devices enabling continuous physiological monitoring with embedded therapeutic feedback loops.
- Online Programs:Browser-accessible structured interventions delivered through scheduled modules with clinician oversight capabilities.
The dominant share belongs to Apps, while Platforms are closing the gap fastest as Australian and Japanese hospital networks consolidate procurement decisions.
Therapy Area:
Clinical application focus determines evidentiary burden and payer familiarity across national health technology assessment frameworks.
- Diabetes Management:Glucose monitoring integration with closed-loop insulin dosing algorithms represents the most mature reimbursement category. South Korean continuous glucose monitor manufacturers are opening API ecosystems to DTx developers, enabling therapeutic platforms that qualify for chronic disease management codes.
- Mental Health:Cognitive behavioral therapy protocols delivered through prescription digital therapeutics face substitution pressure from non-regulated wellness applications. Singaporean and Hong Kong enterprise purchasers are creating direct-to-payer channels through employee assistance program benefits.
- Cardiovascular:Hypertension management protocols with connected blood pressure monitoring and medication adherence tracking.
- Chronic Pain:Neuromodulation guidance and behavioral pain management interventions requiring specialized clinical validation.
Diabetes Management commands the largest installed base, though Mental Health is expanding most quickly as employer-sponsored coverage normalizes across Southeast Asian commercial centers.
End User:
Stakeholder purchasing authority reflects divergent incentive structures across fee-for-service and value-based care environments.
- Patients:Direct consumers accessing prescription DTx through pharmacy benefits or out-of-pocket payment, concentrated in markets with established software-as-medical-device reimbursement catalogs.
- Providers:Hospital systems and physician practices procuring DTx as clinical workflow extensions, particularly Australian tertiary networks unbundling modules from comprehensive electronic health record contracts.
- Payers:National health insurers and private carriers evaluating outcomes-based coverage for validated therapeutic software.
- Caregivers:Family members and professional care coordinators utilizing DTx for remote patient monitoring and adherence support.
Providers currently drive the majority of enterprise revenue, while Payers are gaining procurement influence fastest as Japan and Australia expand national reimbursement catalogs.
Delivery Mode:
Technical architecture choices trade latency performance against data sovereignty compliance and infrastructure deployment costs.
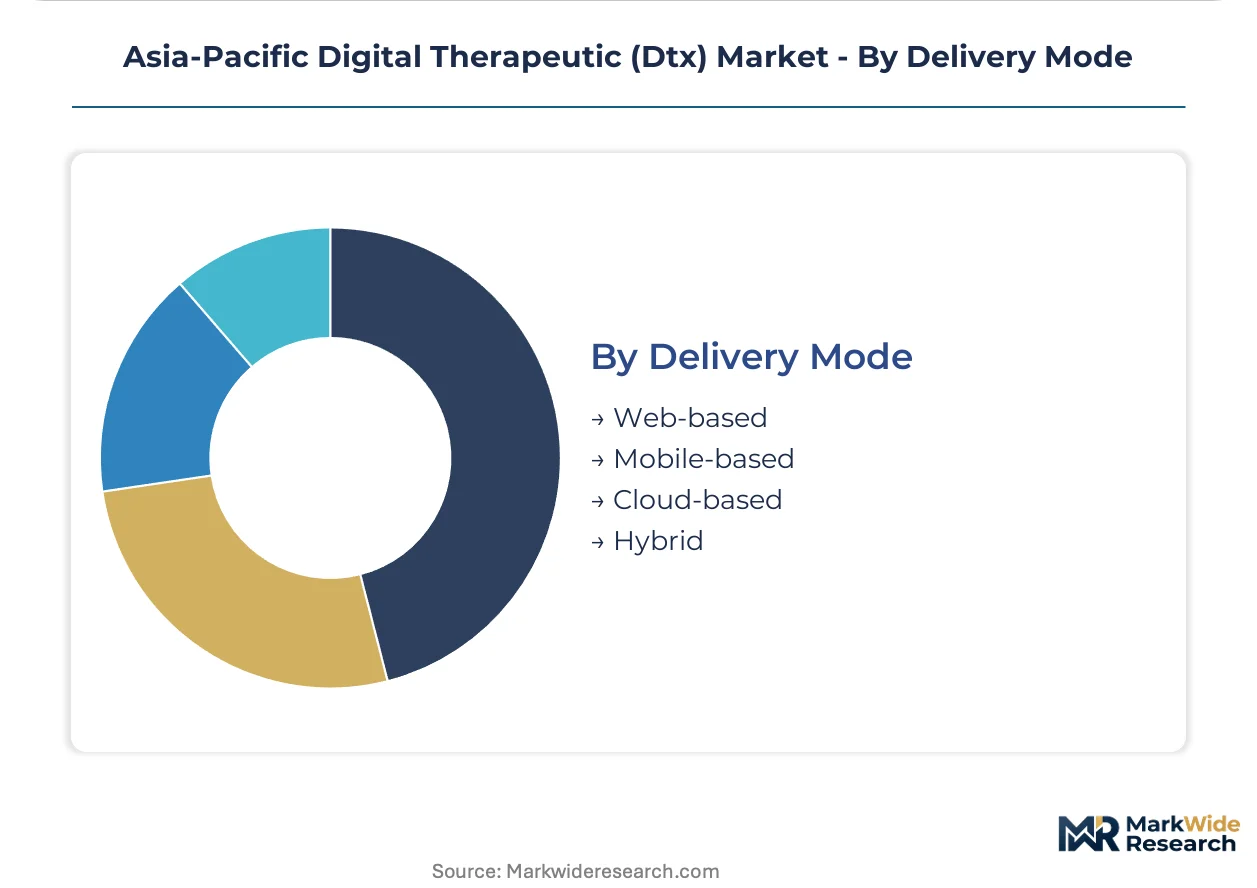
- Mobile-based:Native smartphone applications dominating installation volumes across the region. Japanese and South Korean markets exhibit particularly high penetration due to mature mobile health ecosystems and consumer comfort with app-based clinical interactions.
- Hybrid:Edge computing architectures executing sensitive algorithms on local servers while transmitting aggregated outcomes to centralized registries. Australian hospital networks are adopting these models to satisfy TGA data sovereignty requirements while compressing latency for acute interventions.
- Web-based:Browser-delivered interventions accessible across device types with reduced development overhead.
- Cloud-based:Fully centralized processing enabling rapid algorithm updates but requiring cross-border data flow compliance.
Mobile-based delivery holds the dominant position, though Hybrid architectures are climbing the fastest as enterprise hospital deployments prioritize data localization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese and Australian markets where PMDA and TGA software-as-medical-device frameworks command premium reimbursement rates, while Chinese and Indonesian markets compete on volume accessibility with lighter regulatory burdens and narrower coverage catalogs.
Japan
Smoking cessation and hypertension management applications drive procurement from enterprise purchasers and municipal health insurers. PMDA's SaMD Fast-Track Pathway compresses pre-market timelines for developers holding FDA or TGA clearances. Tokyo's Shibuya and Minato wards host concentrated DTx venture clusters where CureApp anchors regulatory expertise.
Australia
Hospital in the Home programs and employer-sponsored mental health benefits expand addressable demand beyond traditional hospital procurement. TGA's expanded software-as-medical-device classification now captures adaptive diagnostic algorithms, forcing retrospective clinical validation. Melbourne and Sydney tertiary networks unbundle DTx modules from comprehensive electronic health record contracts.
South Korea
Continuous glucose monitor manufacturers open API ecosystems to DTx platforms, enabling closed-loop therapeutic algorithms qualifying for chronic disease management codes. MFDS maintains distinct software-as-medical-device pathways with evidence requirements diverging from PMDA and TGA standards. Seoul's Digital Healthcare Cluster concentrates developer talent and clinical trial infrastructure.
China
Integrated insurer-provider platforms bundle DTx modules with primary care access across tier-one cities. NMPA's algorithm transparency mandates for AI-enabled therapeutic software expose proprietary training methodologies to competitive replication. Shanghai and Shenzhen health tech corridors attract venture capital despite regulatory tightening on machine-learning model disclosure.
Indonesia
BPJS Kesehatan's digitization roadmap creates first-mover positioning for hypertension and diabetes management protocols ahead of formal software-as-medical-device classification. The national health insurer's expansion targets 250 million covered lives by 2028. Jakarta's health tech ecosystem concentrates localization partnerships bridging international DTx platforms with Bahasa-language clinical content.
Asia-Pacific Digital Therapeutic (Dtx) Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying algorithm modules and biometric capture layers. Market structure fragments across national regulatory silos rather than consolidating around scalable regional architectures. Three archetypes dominate: Japan-centric regulatory specialists, China-scale platform bundlers, and Australia-focused hospital system integrators. Competitive moves concentrate on parallel regulatory capability building and hybrid edge-cloud technology licensing.
Among Japan-based developers, CureApp exemplifies the regulatory-first archetype through PMDA pathway expertise. Ping An Good Doctor occupies a position within the China-scale platform tier, bundling DTx modules with insurer-provider infrastructure. Omron Healthcare represents the device-origin diversification pattern, extending from hardware manufacturing into software-as-medical-device qualification.
| Leading Market Players |
|---|
| CureApp |
| Ping An Good Doctor |
| Alibaba Health Information Technology Limited |
| Omron Healthcare |
| Doctor Anywhere |
| Lybrate |
| Wellthy Therapeutics |
| Zesty |
| GlucoMe |
| Others |
Value Chain & Pricing Dynamics
Algorithm engineering talent clusters in Tokyo, Sydney, and Seoul concentrate upstream development costs, pushing margin capture toward clinical evidence generation and regulatory affairs capabilities downstream. Pricing power accrues to vendors that internalize PMDA, TGA, and MFDS parallel clearance pathways rather than outsourcing compliance to regional partners.
Pricing Analysis
Configured-to-order pricing for enterprise hospital deployments commands 40-60% premiums over standard SaaS subscriptions for direct-to-consumer mental health applications. The dominant structure runs through tiered subscription models segmented by clinical oversight intensity, with diabetes management platforms benefiting from chronic disease reimbursement codes that insulate against price erosion. Certification grade at PMDA or TGA level serves as the primary differentiation driver, while wellness app substitution intensifies cost compression in the direct-to-patient tier. Large Australian hospital networks exhibit lowest price sensitivity due to unbundled procurement authority, whereas Indonesian BPJS channels face acute budget constraints.
Supply Chain Analysis
Biometric sensor feedstock concentrates in South Korean and Japanese component manufacturing, with cloud infrastructure anchored in Singapore and Australian data sovereignty zones. DTx platforms draw from continuous glucose monitor APIs, edge computing hardware, and localized server clusters as critical inputs. Single-source vulnerability sits with MFDS-certified algorithm validation partners in Seoul, where clinical trial capacity constraints create bottlenecks for multi-market clearance timelines. Distribution runs through hospital procurement committees in Australia, employer benefits administrators in Singapore and Hong Kong, and national insurer formularies in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across PMDA, TGA, and MFDS frameworks fragments competitive positions, creating specialist niches for vendors that master single-jurisdiction clearance before scaling. Employer-sponsored mental health benefits in Southeast Asian commercial centers represent the fastest-expanding demand pool.
For Market Incumbents: Build regulatory moats through captive clinical evidence generation infrastructure in Tokyo and Sydney, insulating against mid-scale competitors that cannot sustain parallel trial burdens. Deepen backward integration into biometric sensor partnerships with South Korean CGM manufacturers to secure API access for closed-loop algorithms. Prioritize TGA adaptive algorithm classification compliance ahead of competitors facing retrospective validation deadlines. For New Entrants and Emerging Players: Pursue white-space positioning in Indonesia's BPJS Kesehatan digitization roadmap before formal software-as-medical-device classification hardens barriers. Target hypertension management protocols for the 250 million covered lives expansion, leveraging Bahasa-language localization as the primary go-to-market wedge against Japan-centric incumbents. Anchor initial revenue through direct employer contracts in Singapore and Hong Kong, bypassing hospital procurement cycles entirely. For Investors and Strategic Acquirers: Capital is best deployed toward hybrid edge-cloud technology licensors with existing PMDA or TGA clearances and established hospital system relationships in Australia or Japan. Long-term viability hinges on regulatory asset durability rather than user growth metrics, given reimbursement qualification timelines. Watch MFDS fast-track pathway announcements as the inflection signal for South Korean market access acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA SaMD Fast-Track Clearance | Compresses pre-market timelines for developers holding FDA or TGA predicate clearances. |
| CGM API Ecosystem Integration | Enables closed-loop therapeutic algorithms qualifying for chronic disease reimbursement codes. |
| Hybrid Edge-Cloud Architecture Licensing | Satisfies TGA data sovereignty requirements while reducing latency for acute interventions. |
| Employer Benefits Channel Partnership | Creates direct-to-payer revenue bypassing traditional hospital procurement committees. |
| Retrospective Clinical Validation Investment | Addresses TGA expanded classification capturing previously unregulated adaptive diagnostic tools. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of PMDA software-as-medical-device registration databases, TGA classification rulings, and MFDS approval records. Interviews with regulatory affairs directors at DTx developers, hospital procurement managers at Australian tertiary networks, and payer formulary specialists at Japan's municipal health insurers inform qualitative assessments. Secondary sources include national health technology assessment body publications, GPO contract disclosures, and CMS international reimbursement comparisons. Bottom-up installation estimates triangulate against top-down addressable patient population calculations.
Forecast inputs span therapy area penetration curves, reimbursement catalog expansion timelines, and regulatory pathway efficiency differentials across the projection horizon. Segmentation dimensions include product architecture, clinical application focus, stakeholder purchasing authority, and technical delivery mode. CAGRs derive from fitted adoption curves benchmarked against historical software-as-medical-device clearance velocity. Algorithm personalization engine deployment rates and employer-sponsored benefit enrollment trajectories serve as industry-specific demand indicators.
Macroeconomic conditions sit as an overlay; deviation in national health insurance budget allocations or cross-border data flow restrictions would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory harmonization pace and clinical evidence cost inflation. Cross-checking against hospital procurement database trends and payer coverage decision timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Global Surgical Preoperative Planning Software Market
Digital Health Solutions
US Patient Engagement Solutions Market
Digital Health Solutions
Asia-Pacific Eclinical Solutions Market
Digital Health Solutions
Digital Health Market
Digital Health Solutions
Distance Health Technologies Market
Digital Health Solutions
UAE Mhealth Market
Digital Health Solutions
Global Plastic Surgery Software Market
Digital Health Solutions
Pharmacovigilance (PV) and Drug Safety Software Market
Digital Health Solutions
Behavioral Mental Health Care Software Market
Digital Health Solutions
Global Patient Centric Healthcare App Market
Digital Health Solutions
Middle East and Africa Heart Failure Software Market
Digital Health Solutions
Mhealth Services Market
Digital Health Solutions
Digital Health Tracking Apps Market
Digital Health Solutions
North America Mobile Health (Mhealth) Market
Digital Health Solutions
Healthcare Digital Signage Market
Digital Health Solutions
Global Metaverse in Healthcare Market