
 Middle East Secure Messaging in Healthcare Market | 2026-2036
Middle East Secure Messaging in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Secure Messaging in Healthcare Market Foresight
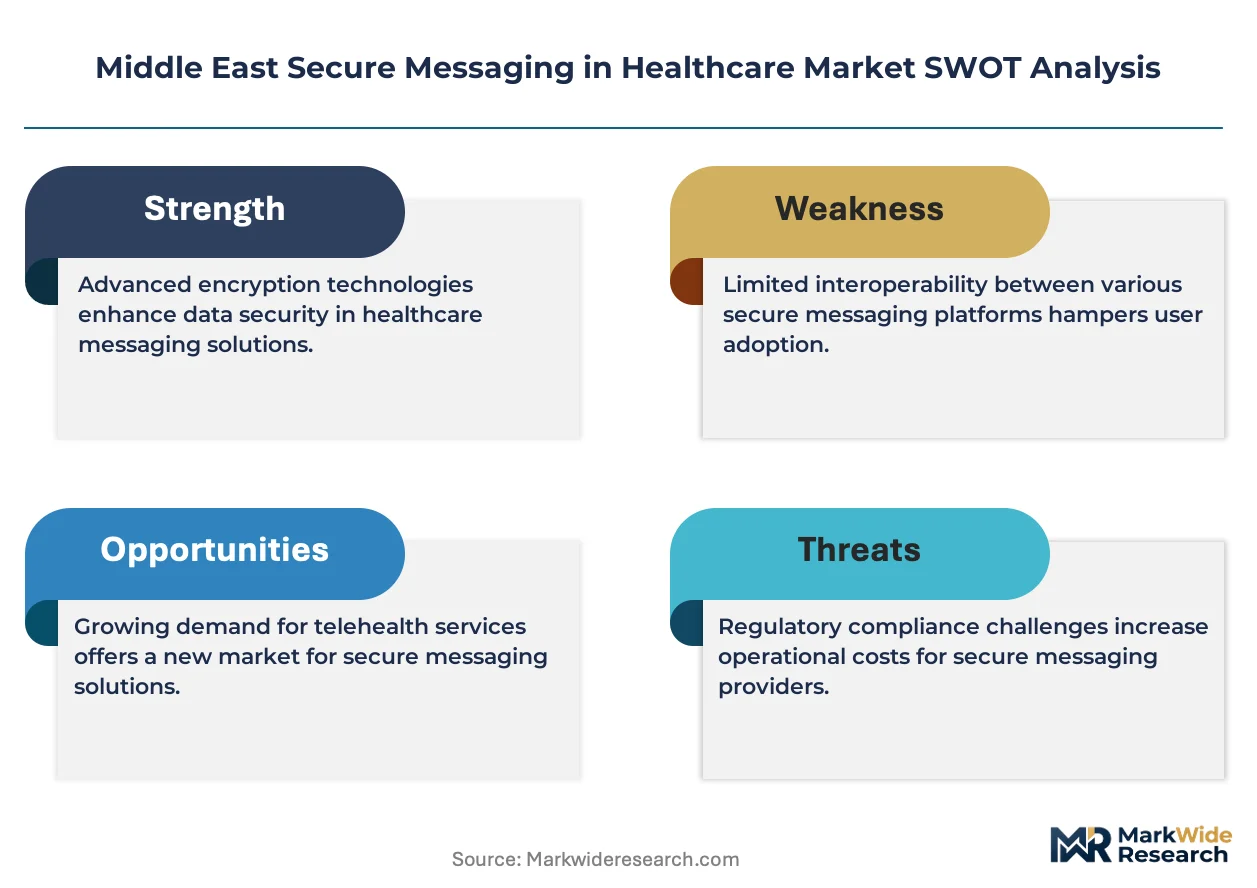
Clinical informatics talent is rotating from legacy hospital IT departments toward specialized health data security firms, tightening the labor pool for enterprise-grade secure messaging deployments. Imprivata Inc. leverages its privileged access management heritage to anchor credentialing workflows inside Gulf hospital networks. Cerner Corporation sustains deep electronic health record integration that positions its messaging layer as a default choice for integrated delivery systems. Siemens Healthineers competes through imaging-to-message workflow unification that reduces clinical handoff friction.
Secure messaging in healthcare denotes encrypted, HIPAA-grade and locally compliant communication infrastructure that transmits patient identifiers, lab results, and care coordination notes between clinicians, devices, and health information systems. Core technical specifications include end-to-end AES-256 encryption, role-based access control with multi-factor authentication, and audit-log retention aligned to national data sovereignty laws. Cloud-based systems lead technology adoption as Gulf health ministries favor scalable infrastructure with centralized oversight, while blockchain-enabled verification represents the fastest-growing segment for credentialing and prescription authentication. Among end users, hospitals dominate current procurement volumes, though telehealth providers constitute the most rapid expansion channel as virtual-first care models proliferate across the region.
MOHAP in the UAE and SFDA in Saudi Arabia enforce health data localization and cross-border transfer restrictions that directly shape vendor qualification and deployment architecture. The UAE's NESA cybersecurity standards and Saudi Arabia's National Data Management Office policies further mandate encryption certification and incident reporting protocols for clinical communication platforms. Stakeholders must monitor evolving data residency enforcement and interoperability certification timelines to align product roadmaps with procurement eligibility requirements.
Market Dynamics
Gulf health ministries are consolidating procurement authority under centralized digital transformation offices, compressing vendor qualification timelines while tightening technical compliance requirements for encrypted clinical communication infrastructure.
Growth Catalysts
- MOHAP Data Localization Mandates:UAE hospitals must store patient identifiers within national borders, creating captive demand for locally hosted secure messaging architectures that vendors must engineer to specification.
- Telehealth Platform Expansion:Virtual-first care models across Saudi Arabia and Qatar are embedding encrypted messaging as a core workflow layer, pulling deployment volumes beyond traditional hospital IT budgets.
- Blockchain Credential Verification:Prescription authentication and clinician identity validation are converging on distributed ledger protocols, opening new revenue streams for platform providers with cryptographic expertise.
Market Restraints
- SFDA Cross-Border Transfer Restrictions:Saudi regulations block patient data routing through non-domestic cloud nodes, fragmenting vendor infrastructure strategies and raising operational complexity.
- Clinical Informatics Talent Scarcity:Health data security specialists are migrating from hospital IT departments to specialized cybersecurity firms, thinning the labor pool available for enterprise deployment projects.
- Legacy EHR Integration Friction:Proprietary messaging protocols from established electronic health record vendors create technical lock-in that complicates third-party secure messaging adoption.
Strategic Opportunities
- Imaging-to-Message Workflow Unification:Radiology departments across the UAE are demanding seamless handoff between diagnostic systems and clinical communication platforms, rewarding vendors with PACS integration capabilities.
- Blockchain-Enabled Prescription Authentication:Saudi Arabia's National Data Management Office policies are creating regulatory tailwinds for cryptographic verification of controlled substance prescriptions.
- Telehealth Provider Channel Expansion:Virtual care startups in Qatar and Kuwait represent underpenetrated demand segments with faster procurement cycles than established hospital networks.
Industry Challenges
- Interoperability Certification Timelines:MOHAP and NESA cybersecurity standards require extensive third-party validation that delays product launches by quarters.
- Multi-Factor Authentication Deployment Complexity:Biometric and hardware token integration with existing hospital identity systems demands specialized integration expertise that remains scarce in the Gulf labor market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Secure Messaging in Healthcare Market |
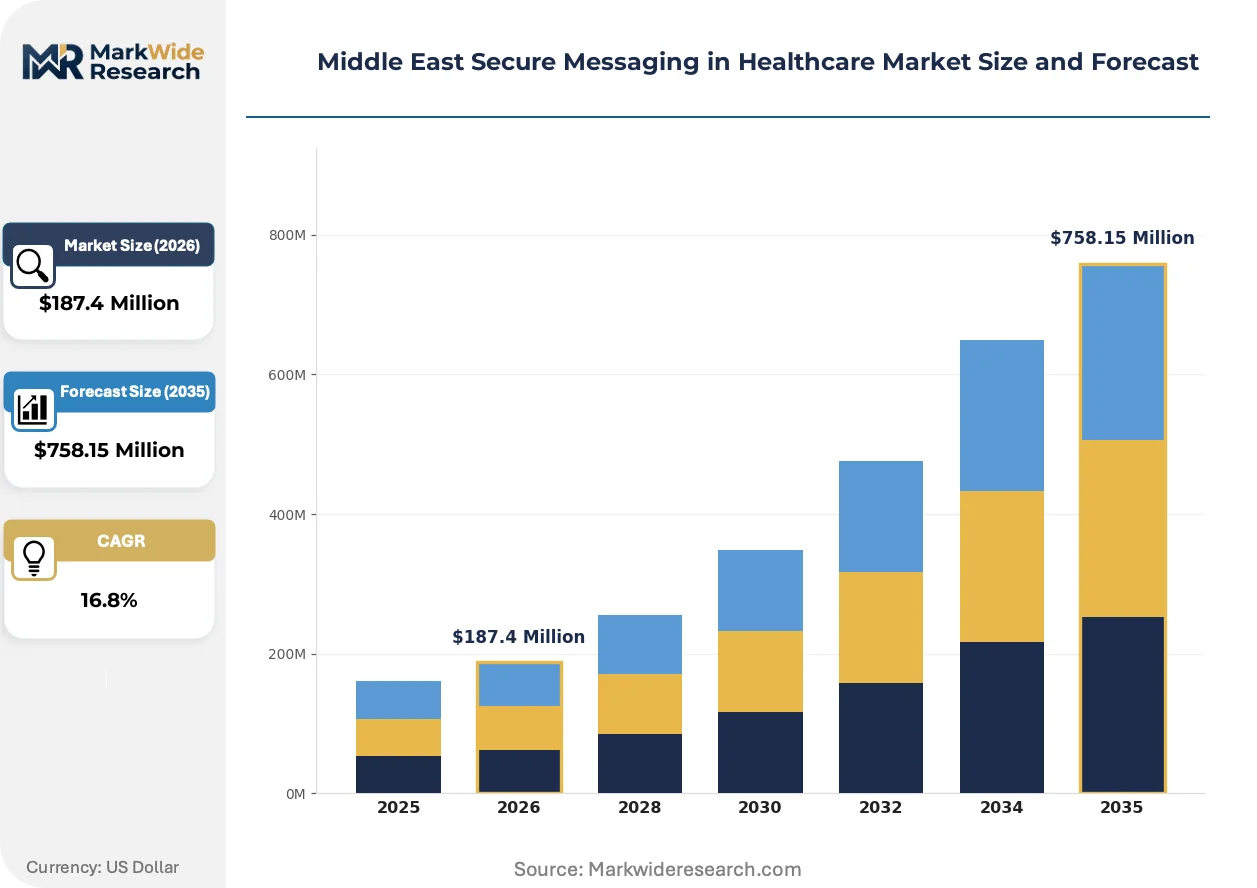
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $758.15 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patient Portals, Compliance Solutions, Messaging Apps, Data Encryption Tools End User: Hospitals, Clinics, Laboratories, Telehealth Providers Technology: Cloud-Based Systems, On-Premises Solutions, Hybrid Solutions, Blockchain Deployment: Web-Based, Mobile Applications, Desktop Clients, Others |
| Companies Covered | Cerner Corporation, Imprivata Inc., OnPage, Spok Inc., Athenahealth, Allscripts Healthcare Solutions, Siemens Healthineers, Philips Healthcare, Oracle, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Secure Messaging in Healthcare Market Shifts & Advancements
Clinical communication infrastructure is fragmenting into modular, API-first architectures that separate encryption layers from workflow applications, enabling faster customization without core platform redevelopment.
Cloud-native secure messaging platforms are decomposing monolithic hospital communication systems into containerized microservices that Gulf health ministries can scale independently. Saudi hospital networks are migrating fastest, driven by MOHAP-mandated infrastructure modernization programs. This decomposition is compressing deployment timelines from years to months while fragmenting vendor revenue models toward subscription-based consumption.
SFDA and MOHAP are tightening health data localization enforcement, requiring domestic data center presence for any platform handling patient identifiers. Vendors must now maintain sovereign cloud instances in Saudi Arabia and the UAE, raising capital requirements but creating defensive moats against non-compliant competitors. Imaging-heavy hospital departments face the steepest compliance burdens due to large file transfer requirements.
Subscription-based procurement is displacing perpetual licensing across Gulf hospital procurement offices, compressing upfront revenue recognition while extending customer lifetime value calculations. Telehealth providers are driving this shift fastest, preferring operational expenditure models that align costs with patient volume fluctuations. Kuwaiti and Qatari health systems are adopting this pattern most aggressively among regional peers.
Middle East Secure Messaging in Healthcare Market Segmentation
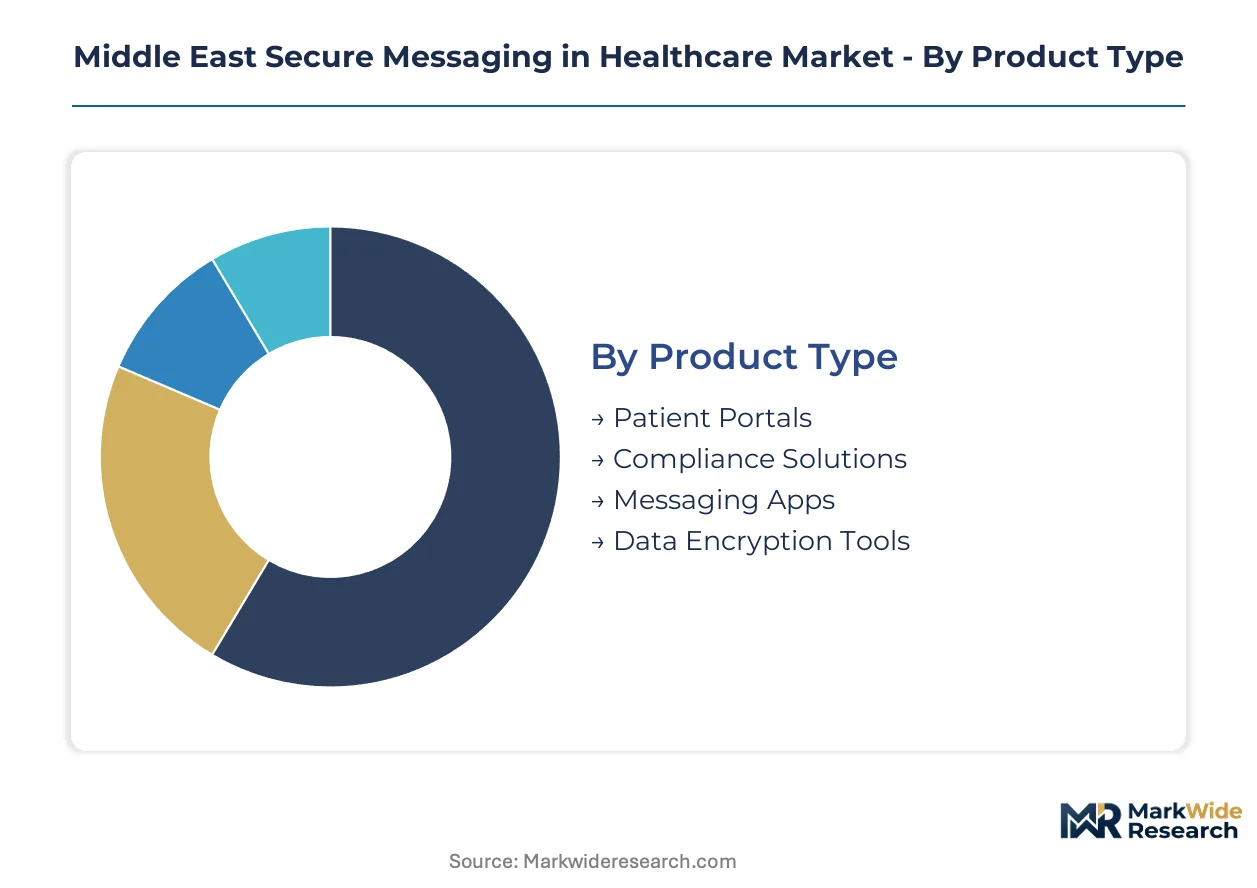
Regulatory fragmentation across Gulf health ministries forces vendors to engineer segment-specific compliance architectures. Procurement patterns diverge sharply between centralized hospital networks and distributed telehealth operators, requiring distinct go-to-market configurations.
Product Type:
MOHAP and SFDA certification requirements vary materially by product category, with patient-facing interfaces facing stricter validation timelines than backend infrastructure.
- Patient Portals:Web and mobile interfaces enabling direct patient-clinician communication with embedded consent management. Saudi hospital networks concentrate procurement here due to MOHAP-mandated patient engagement targets, though integration with legacy EHR systems creates deployment friction.
- Compliance Solutions:Audit logging, consent tracking, and breach notification modules engineered to NESA and SFDA technical specifications. UAE health systems prioritize these for centralized oversight capabilities, with demand accelerating as enforcement actions intensify.
- Messaging Apps:Clinical-grade instant messaging with role-based routing and escalation protocols.
- Data Encryption Tools:Standalone cryptographic modules for file transfer and API security.
Compliance Solutions handles the majority of throughput; Patient Portals is climbing the fastest on share.
End User:
Customer procurement maturity spans from centralized Gulf ministry tenders to agile telehealth startup contracts, reshaping vendor sales motion economics.
- Hospitals:Integrated delivery systems with multi-department workflow requirements and stringent uptime SLAs. Saudi Arabia's MOHAP-directed consolidation concentrates demand among the largest networks, compressing vendor qualification cycles while raising technical compliance thresholds.
- Telehealth Providers:Virtual-first care platforms requiring lightweight, API-first deployment models. Qatar and Kuwaiti startups drive the steepest expansion trajectory here, favoring subscription pricing over capital-intensive perpetual licenses.
- Clinics:Outpatient facilities with limited IT staff and standardized workflow needs.
- Laboratories:Diagnostic centers prioritizing secure result distribution and specimen chain-of-custody documentation.
Hospitals anchor current revenue concentration; Telehealth Providers is gaining share fastest.
Technology:
Data sovereignty enforcement is segmenting infrastructure choices between scalable cloud architectures and tightly controlled on-premises deployments.
- Cloud-Based Systems:Scalable, multi-tenant platforms with centralized security patching and elastic compute allocation. UAE health ministries favor these for oversight consolidation, though SFDA cross-border restrictions force Saudi-specific instance isolation.
- Blockchain:Distributed ledger protocols for credential verification and prescription authentication. Saudi Arabia's National Data Management Office policies create regulatory tailwinds here, with controlled substance tracking driving pilot deployments.
- On-Premises Solutions:Single-tenant deployments within hospital data centers for maximum data control.
- Hybrid Solutions:Split architectures routing sensitive identifiers locally while leveraging cloud for non-clinical workloads.
Cloud-Based Systems captures the dominant deployment volume; Blockchain shows the steepest expansion trajectory.
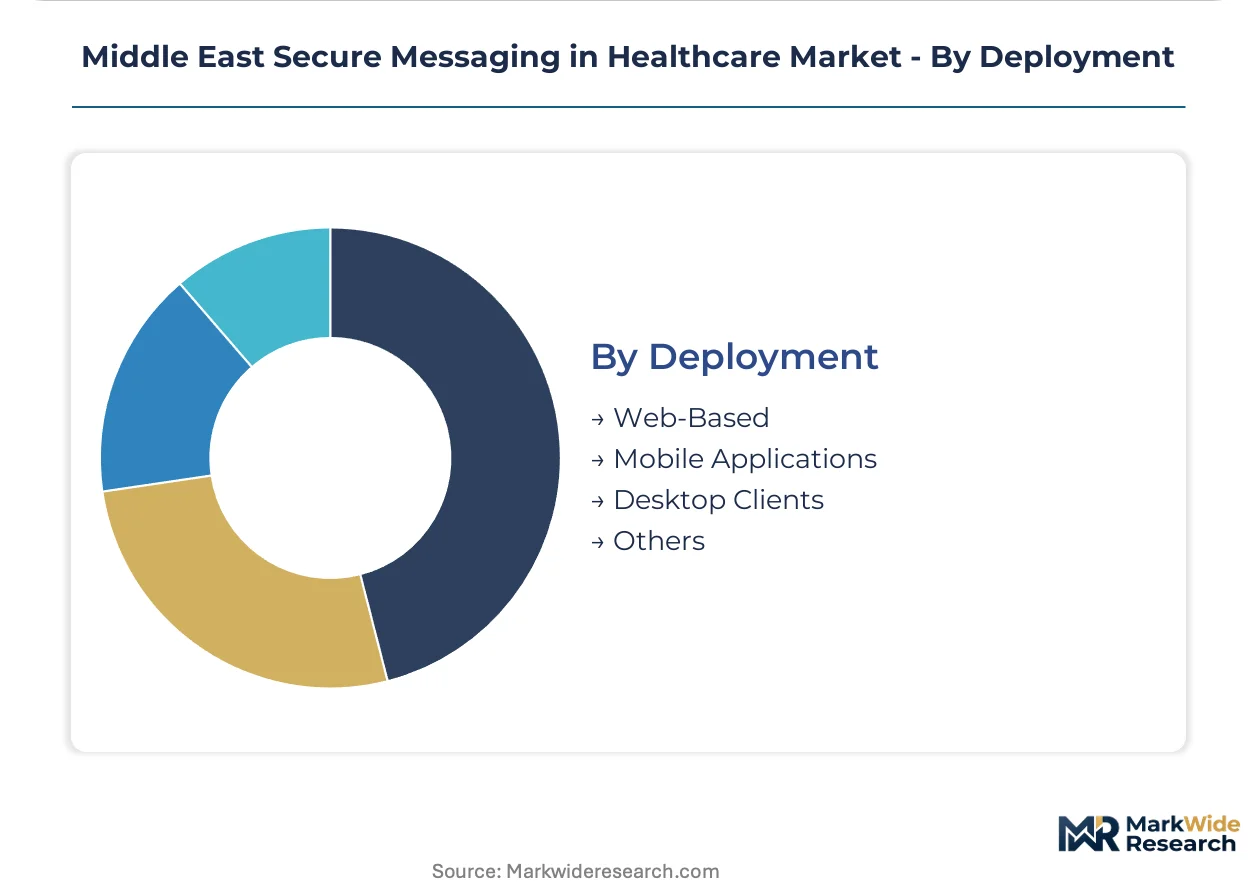
Deployment:
Clinical workflow patterns and device policies within Gulf health systems determine interface prioritization across access modalities.
- Mobile Applications:Native iOS and Android clients with biometric authentication and offline message queuing. UAE nursing staff and Saudi emergency departments concentrate demand here, driven by ward mobility requirements and MOHAP-mandated response time targets.
- Web-Based:Browser-accessible platforms requiring no local installation and enabling rapid cross-device access. Telehealth providers in Qatar and Kuwait default to this modality for patient-facing interactions, minimizing friction in virtual care onboarding.
- Desktop Clients:Thick applications for radiology workstations and administrative heavy users.
- Others:Embedded messaging within medical devices and specialized clinical equipment.
Mobile Applications dominates clinician-facing throughput; Web-Based is expanding most quickly for patient engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Saudi hospital procurement offices while UAE health systems extract steeper vendor concessions through consolidated ministry tenders. This asymmetry shapes deployment economics across the Gulf Cooperation Council corridor.
Saudi Arabia
MOHAP-directed hospital network consolidation and SFDA data localization mandates drive captive demand for sovereign cloud architectures. The National Data Management Office enforces cross-border transfer restrictions that fragment vendor infrastructure strategies. Riyadh's King Faisal Specialist Hospital anchors regional deployment volumes for encrypted clinical communication platforms.
United Arab Emirates
NESA cybersecurity standards and MOHAP patient engagement targets compress vendor qualification timelines while tightening technical compliance thresholds. The Dubai Health Authority mandates centralized digital transformation oversight for all clinical communication procurement. Dubai's Sheikh Mohammed bin Rashid Academic Medical Center exemplifies imaging-to-message workflow unification adoption.
Qatar
Virtual-first care models and telehealth platform expansion pull deployment volumes beyond traditional hospital IT budgets. The country's national health regulator enforces interoperability certification timelines that delay product launches. Doha's Sidra Medicine drives demand for lightweight API-first deployment models among specialty care networks.
Kuwait
Subscription-based procurement preferences and agile telehealth startup contracts reshape vendor sales motion economics. The Ministry of Health's centralized procurement authority favors operational expenditure models that align costs with patient volume fluctuations. Kuwait City's specialized outpatient networks concentrate demand for mobile-native clinical communication interfaces.
Middle East Secure Messaging in Healthcare Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Gulf health system vendor base. EHR-integrated incumbents anchor hospital procurement through workflow lock-in, while specialized cybersecurity firms capture premium pricing for credentialing and encryption modules. Three archetypes dominate: integrated health IT platforms with messaging layers, standalone secure communication specialists, and imaging-to-workflow unification providers. Competitive moves concentrate on interoperability certification racing and sovereign cloud instance deployment.
Within the integrated platform tier, Cerner Corporation and Siemens Healthineers occupy positions shaped by deep electronic health record penetration in Saudi and UAE hospital networks. Imprivata Inc. exemplifies the privileged access management specialist archetype, anchoring credentialing workflows inside Gulf health systems. These three companies represent distinct competitive vectors—EHR integration depth, imaging workflow unification, and identity security specialization—that vendors must navigate to qualify for ministry tenders.
| Leading Market Players |
|---|
| Cerner Corporation |
| Imprivata Inc. |
| OnPage |
| Spok Inc. |
| Athenahealth |
| Allscripts Healthcare Solutions |
| Siemens Healthineers |
| Philips Healthcare |
| Oracle |
| Others |
Supply & Pricing Matrix
Ninety-day certification lead times for MOHAP and SFDA compliance create inventory-like bottlenecks that concentrate pricing power among vendors with pre-qualified sovereign cloud instances, while compressing margins for late entrants forced into accelerated validation cycles.
Pricing Analysis
The customization-premium spread runs wide in this market, with configured-to-order deployments for imaging-to-message workflow unification commanding substantial premiums over standard messaging app implementations. Subscription-based SaaS tiers now dominate hospital procurement, though telehealth providers in Qatar and Kuwait drive aggressive price compression through volume-negotiated operational expenditure models. Price differentiation hinges on NESA certification grade and after-sales service bundling, with full-managed-service contracts capturing the least price-sensitive buyers among Saudi Arabia's consolidated hospital networks. Cost compression in standard cloud deployments is intensifying because vendor qualification timelines have shortened under centralized Gulf ministry procurement authority.
Supply Chain Analysis
The United States and Israel anchor cryptographic module and biometric authentication hardware production, while India and the Philippines supply clinical informatics talent for implementation and integration services. Sovereign cloud infrastructure draws from domestic data center construction in Saudi Arabia and the UAE, with hyperscaler partnerships resting on MOHAP-mandated instance isolation requirements. Single-source vulnerability concentrates in qualified encryption certification providers, where only a handful of auditors meet NESA and SFDA technical specifications. Distribution runs through centralized health ministry digital transformation offices that consolidate procurement authority and compress vendor qualification timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates durable competitive positioning. SFDA and MOHAP certification requirements impose switching costs that lock hospital networks into validated vendor relationships.
For Market Incumbents: Consolidate around sovereign cloud instance expansion in Riyadh and Dubai to preempt competitor qualification. Deepen imaging-to-message workflow unification capabilities to defend against specialized PACS-integrated entrants. Channel control through exclusive partnerships with King Faisal Specialist Hospital and Sheikh Mohammed bin Rashid Academic Medical Center reinforces ministry tender eligibility.
For New Entrants and Emerging Players: SFDA fast-track certification for blockchain-enabled prescription authentication modules opens immediate procurement eligibility in Saudi Arabia's controlled substance tracking pilots. Telehealth providers in Qatar and Kuwait represent the most penetrable segment, with API-first deployment models and subscription pricing aligning to their capital constraints. A channel partnership with Sidra Medicine's specialty care network accelerates referenceability.
For Investors and Strategic Acquirers: Carve-out targets emerge from health IT divisions of industrial conglomerates seeking to monetize non-core clinical communication assets. Long-term viability centers on regulatory entrenchment depth rather than technology differentiation alone. The signal to watch is MOHAP enforcement action frequency, which would accelerate replacement demand for non-compliant legacy installations.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Instance Deployment | MOHAP and SFDA data localization mandates require domestic data center presence for patient identifier handling. |
| Blockchain Credential Verification | Saudi Arabia's National Data Management Office policies create regulatory tailwinds for prescription authentication pilots. |
| Imaging-to-Message Integration | Radiology departments at Dubai's Sheikh Mohammed bin Rashid Academic Medical Center demand seamless PACS handoff. |
| Telehealth Channel Partnership | Virtual-first care models in Qatar and Kuwait pull deployment volumes beyond traditional hospital IT budgets. |
| Compliance Solutions Modularization | Audit logging and consent tracking modules engineered to NESA specifications capture UAE centralized oversight demand. |
Research Methodology
The analysis maps cloud-based systems, blockchain-enabled verification, patient portals, and compliance solutions, each validated through hospital CIOs, clinical informatics directors, health ministry procurement officers, and telehealth platform architects. Primary interviews with these stakeholders combined with secondary validation from SFDA regulatory filings, MOHAP procurement databases, NESA cybersecurity standards documentation, and GPO contract repositories. Bottom-up deployment volume estimates triangulated against top-down health system digitization budget allocations from Gulf Cooperation Council ministries.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models technology type, end user segment, deployment modality, and regional regulatory cluster dimensions throughout the forecast period. CAGRs were derived from segment-specific adoption curves calibrated to MOHAP-mandated infrastructure modernization timelines and telehealth platform expansion trajectories. Forecast inputs include health ministry budget allocation patterns and interoperability certification pipeline visibility.
Underlying assumptions cover sustained MOHAP and SFDA enforcement of data localization requirements, with deviation risk concentrated in regulatory relaxation or cross-border transfer liberalization. Forecasts reflect these assumptions without guarantee of policy continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
US Medical Coding Market
Medical Information Systems
Medical Software Market
Medical Information Systems
Global Medical Document Management Systems Market
Medical Information Systems
Healthcare Information Governance Solution Market
Medical Information Systems
Master Patient Index Software Market
Medical Information Systems
Global Medical Writing Market
Medical Information Systems
Anesthesia Information Management Systems Market
Medical Information Systems
OBGYN EHR Market
Medical Information Systems
Dentistry EMR Software Market
Medical Information Systems
Donor Management Software Market
Medical Information Systems
Artificial Intelligence in Medical Software Market
Medical Information Systems
Global Healthcare Information Systems Market
Medical Information Systems
Global Clinical Documentation Improvement Market
Medical Information Systems
Urology EMR Software Market
Medical Information Systems
Global Clinical EHR Systems Market
Medical Information Systems
Global Laboratory Information Management System for Forensic Science Market