
 Smart Infusion System Market | 2026-2036
Smart Infusion System Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Infusion System Market Insights
Biomedical engineering talent scarcity is reorganizing how manufacturers staff firmware and safety-validation teams. Becton, Dickinson and Company leverages its vertically integrated pump manufacturing to sustain supply continuity for high-acuity care settings. Baxter International anchors its position through dedicated fluid-management R&D facilities across multiple continents. Fresenius Kabi AG competes by specializing in infusion therapy systems tailored to oncology and parenteral nutrition workflows.
A smart infusion system integrates electromechanical pumping mechanisms with dose-error reduction software, drug library databases, and network connectivity to deliver precise, programmable administration of fluids and medications into a patient's circulatory system. These systems typically operate with flow-rate accuracy within plus or minus five percent and incorporate anti-free-flow mechanisms to prevent uncontrolled gravity infusions. Electronic pumps dominate current installed bases due to their versatility across care settings, while wireless connectivity represents the fastest-expanding technology segment as hospitals pursue centralized fleet monitoring and remote alarm management. Software integration commands premium positioning as health systems prioritize interoperability with electronic health records and pharmacy information systems.
The FDA enforces 510(k) premarket clearance and ongoing adverse-event reporting through its MAUDE database, compelling manufacturers to maintain rigorous post-market surveillance infrastructures. The EU Medical Device Regulation mandates clinical evidence and notified-body conformity assessment for infusion pumps marketed in Europe, elevating compliance costs for non-European suppliers. Stakeholders must monitor evolving cybersecurity guidance from both regulators as connected-device vulnerabilities attract heightened enforcement attention and liability exposure.
Market Dynamics
Hospital consolidation in the United States is compressing vendor negotiation cycles and mandating interoperable pump fleet architectures, forcing manufacturers to prioritize software integration over standalone hardware differentiation.
Growth Catalysts
- Oncology Workflow Integration:Closed-loop infusion platforms are gaining traction in cancer treatment centers as precision dosing protocols reduce medication errors during chemotherapy administration.
- 510(k) Software Pathway:The FDA's streamlined premarket notification process for algorithmic dosing systems accelerates commercialization timelines for AI-enabled safety features.
- Wireless Fleet Monitoring:Centralized alarm management and remote pump oversight are expanding adoption across integrated delivery networks seeking operational efficiency.
Market Restraints
- Semiconductor Supply Concentration:Pump controller chip sourcing remains concentrated among East Asian foundries, exposing manufacturers to geopolitical disruption risks.
- EU MDR Compliance Burden:The Medical Device Regulation's clinical evidence requirements elevate certification costs and extend timelines for non-European suppliers entering European markets.
- Gravity Infusion Substitution:Low-cost gravity drip systems persist in resource-constrained settings, limiting premium pump penetration in price-sensitive care environments.
Strategic Opportunities
- Ambulatory Care Expansion:Home infusion therapy growth creates demand for portable, patient-operated pumps with cellular connectivity and simplified interfaces.
- Cybersecurity Service Layer:Connected-device vulnerability management offers recurring revenue streams through subscription-based threat monitoring and patch deployment.
- India PLI Scheme:Production-linked incentives for medical device manufacturing attract localized assembly investments serving South Asian and Middle Eastern markets.
Industry Challenges
- Firmware Engineering Talent Scarcity:Safety-critical software validation expertise remains concentrated among a narrow pool of biomedical specialists, inflating recruitment costs.
- Legacy EHR Integration Complexity:Proprietary data formats in existing hospital information systems impede seamless interoperability with next-generation infusion platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Infusion System Market |
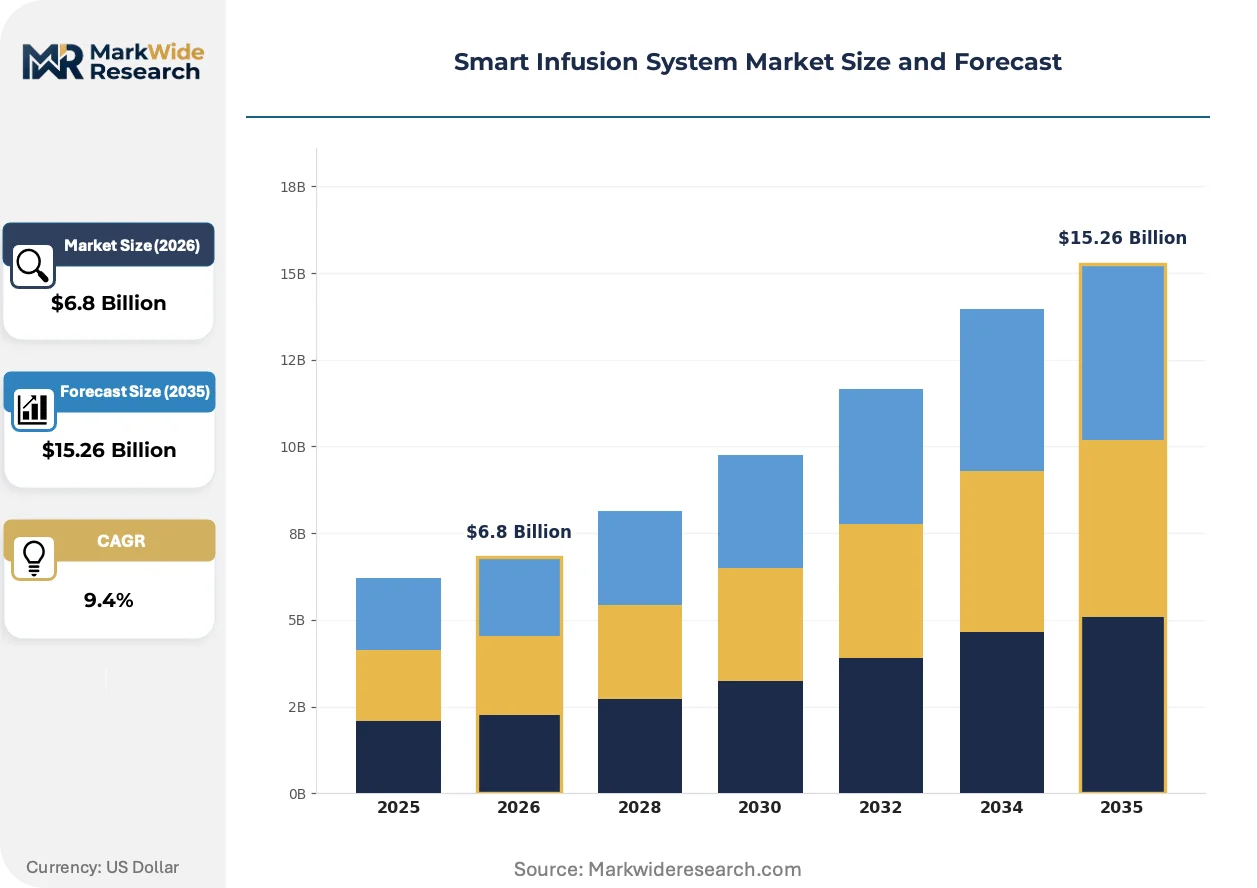
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Pumps, Syringe Pumps, Volumetric Pumps, Infusion Sets End User: Hospitals, Home Care, Clinics, Rehabilitation Centers Technology: Smart Monitoring, Wireless Connectivity, Automated Dosing, Software Integration Application: Pain Management, Chemotherapy, Nutritional Support, Anesthesia |
| Companies Covered | Becton, Dickinson and Company, Baxter International, Fresenius Kabi AG, B. Braun SE, ICU Medical, Inc., Medtronic, Terumo Corporation, Q-Core Medical, Eitan Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Infusion System Market Trends and Innovations
Algorithmic dosing and connected-device architectures are displacing electromechanical pump conventions, compressing development cycles and redefining competitive advantage around software reliability rather than hardware durability.
MEMS-based flow sensors are replacing traditional piston and peristaltic mechanisms in next-generation infusion platforms. Neonatal intensive care units and ambulatory infusion centers are piloting these compact modules for high-precision low-volume delivery. The technology is miniaturizing pump form factors while maintaining flow-rate accuracy within clinical tolerances.
The EU AI Act's risk classification framework is imposing conformity assessment obligations on machine-learning dosing algorithms deployed in European hospitals. Manufacturers must now document training data provenance and algorithmic transparency for high-risk medical AI applications. Oncology and anesthesia segments face the steepest compliance adaptation costs.
Health system procurement committees are consolidating vendor relationships around enterprise-wide pump fleet standardization. Group purchasing organizations are displacing individual hospital negotiations, compressing supplier margins while demanding multi-year service commitments. This concentration is most pronounced in United States metropolitan markets undergoing hospital merger waves.
Smart Infusion System Market Segmentation
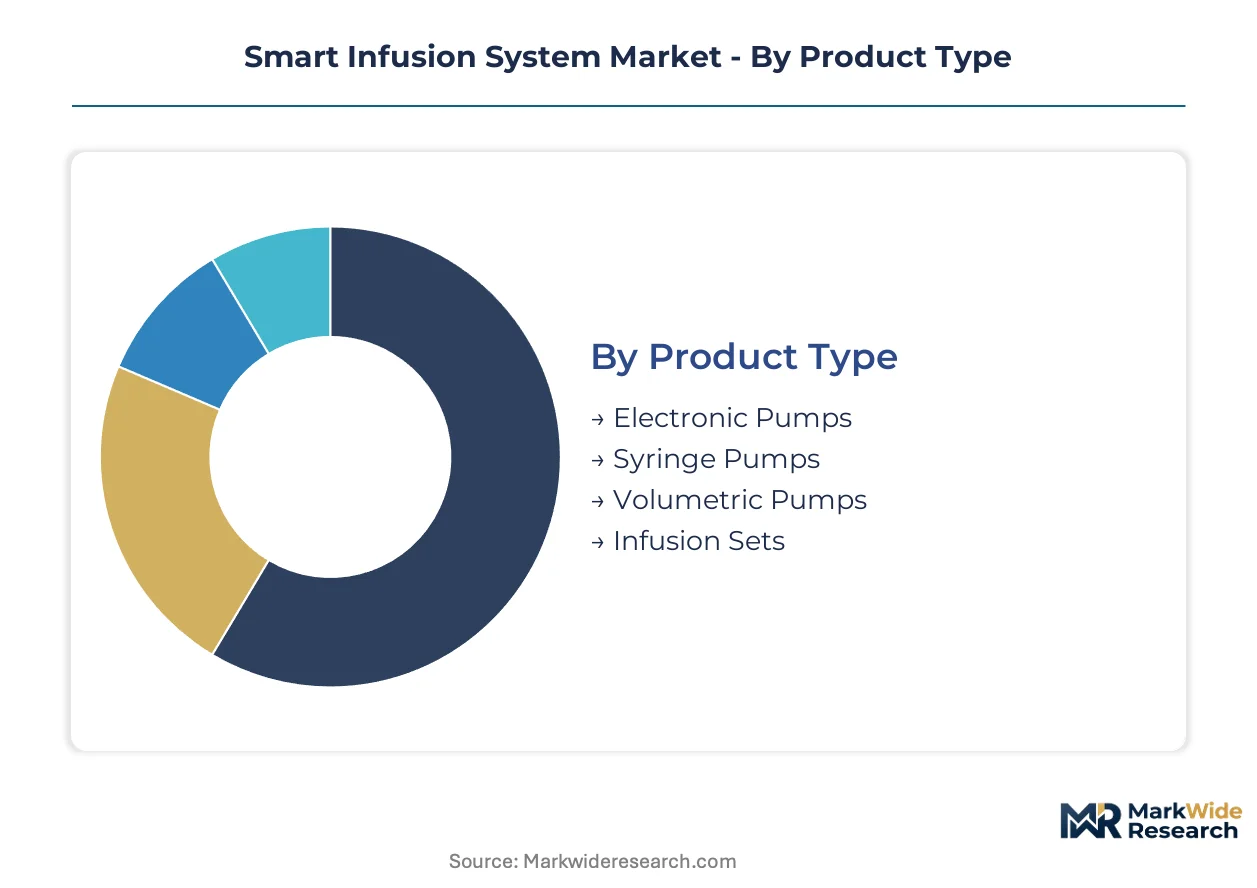
Smart infusion system procurement channels vary sharply by care setting and technology sophistication. Hospital supply chains favor enterprise fleet contracts with embedded software subscriptions, while home care channels prioritize portable hardware with cellular connectivity and patient-facing interfaces.
Product Type:
Channel mix diverges by acuity level: electronic pumps flow through integrated delivery network tenders, syringe pumps concentrate in oncology clinic direct sales, volumetric pumps dominate group purchasing organization contracts, and infusion sets replenish through distributor stock orders.
- Electronic Pumps:Multi-therapy platforms with programmable flow rates and drug library databases serve high-acuity hospital wards. Demand concentrates in United States metropolitan health systems consolidating pump fleets under single-vendor enterprise agreements driven by interoperability mandates.
- Syringe Pumps:Compact electromechanical devices deliver precise low-volume infusions for neonatal and pediatric applications. Oncology clinics in Germany and France are expanding adoption for chemotherapy protocols requiring milliliter-per-hour accuracy.
- Volumetric Pumps:Gravity-fed mechanisms with drop sensors administer large-volume fluid replacement in surgical suites.
- Infusion Sets:Disposable tubing assemblies with anti-free-flow valves connect pumps to vascular access devices.
By volume, infusion sets lead. By growth pace, syringe pumps are climbing the fastest.
End User:
Cost tier stratification separates capital-intensive hospital installations from patient-purchased home care devices and mid-range clinic deployments.
- Hospitals:Acute care facilities deploy centralized fleet management systems with wireless alarm integration and EHR connectivity. United States hospital consolidation is compressing vendor negotiation cycles and mandating interoperable architectures across merged entities.
- Home Care:Patients or caregivers operate portable pumps with simplified interfaces and cellular remote monitoring. Demand is expanding in Japan and Australia as aging populations shift infusion therapy from institutional to residential settings.
- Clinics:Outpatient facilities balance acquisition cost against therapy-specific functionality for chemotherapy and hydration.
- Rehabilitation Centers:Long-term care settings utilize durable pumps with extended battery operation for mobility-restricted patients.
By installed base, hospitals dominate. By expansion trajectory, home care is gaining share fastest.
Technology:
Margin concentration follows software depth: basic monitoring commands commodity pricing, while integrated dosing algorithms and wireless platforms capture premium positioning.
- Smart Monitoring:Real-time flow sensors and occlusion detection algorithms prevent adverse events during infusion. Neonatal intensive care units in the United Kingdom and Netherlands are piloting MEMS-based flow modules for high-precision low-volume delivery.
- Wireless Connectivity:Network-enabled pumps transmit operational data to centralized monitoring stations and EHR systems. Integrated delivery networks across the United States are prioritizing this capability for remote alarm management and fleet oversight.
- Automated Dosing:Closed-loop control systems adjust flow rates based on patient physiological feedback.
- Software Integration:Interoperability layers connect pump operations with pharmacy information systems and electronic health records.
By revenue concentration, software integration leads. By adoption velocity, wireless connectivity is expanding most quickly.
Application:
Maturity curves separate established pain management protocols from emerging precision dosing requirements in chemotherapy and anesthesia.
- Pain Management:Patient-controlled analgesia systems with programmable bolus limits and lockout intervals manage post-operative and chronic pain. General wards in United States community hospitals represent the largest installed base for these devices.
- Chemotherapy:Closed-loop infusion platforms with dose-error reduction software administer cytotoxic agents. Oncology centers in Switzerland and Belgium are adopting these systems as the EU AI Act imposes conformity assessment obligations on machine-learning dosing algorithms.
- Nutritional Support:Enteral and parenteral feeding pumps deliver formula and micronutrient solutions.
- Anesthesia:Target-controlled infusion systems automate intravenous anesthetic delivery based on pharmacokinetic models.
By procedure volume, pain management leads. By regulatory investment, chemotherapy commands the steepest compliance adaptation costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States metropolitan health systems while procurement cost sensitivity dominates Indian clinic networks. German hospital networks command premium positioning for interoperable fleet architectures. Japanese home care channels absorb portable pump premiums for aging-in-place therapy delivery.
United States
Hospital consolidation across metropolitan markets compresses vendor negotiation cycles and mandates interoperable pump fleet architectures. The FDA enforces 510(k) premarket clearance and MAUDE adverse-event reporting for connected infusion platforms. Integrated delivery networks in Texas and California prioritize wireless fleet monitoring and centralized alarm management.
Germany
Oncology clinics in Bavaria and North Rhine-Westphalia expand adoption of closed-loop infusion platforms for precision chemotherapy dosing. The EU Medical Device Regulation mandates clinical evidence and notified-body conformity assessment for algorithmic dosing systems. Medical technology clusters around Stuttgart and Munich host validation facilities for MEMS-based flow sensor integration.
Japan
Aging demographics shift infusion therapy demand from institutional to residential settings across Kanto and Kansai regions. The PMDA oversees software-as-medical-device approvals under harmonized IMDRF guidelines. Tokyo-based home care providers pilot portable pumps with cellular connectivity for patient-operated parenteral nutrition.
India
Price-sensitive clinic networks in Maharashtra and Karnataka limit premium pump penetration while absorbing basic electronic infusion platforms. The Production-Linked Incentive scheme for medical device manufacturing attracts localized assembly investments. Ahmedabad and Chennai production hubs serve South Asian and Middle Eastern distributor networks.
Switzerland
Oncology centers in Zurich and Geneva adopt closed-loop platforms as the EU AI Act imposes conformity assessment obligations on machine-learning dosing algorithms. Swissmedic regulates high-risk medical AI applications with documentation requirements for training data provenance. Basel-area pharmaceutical clusters influence precision dosing protocol development for cytotoxic agent administration.
Smart Infusion System Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the smart infusion system landscape. Vertically integrated multinationals command premium positioning through captive manufacturing and software integration capabilities. Mid-tier specialists compete on oncology workflow customization and regional service density. The dominant competitive moves center on enterprise fleet contract consolidation and cybersecurity service layer subscription models.
Among diversified medical technology conglomerates, Becton, Dickinson and Company and Baxter International occupy positions exemplifying scale-driven supply continuity and multi-continental R&D infrastructure. Fresenius Kabi AG represents the therapy-specialist archetype with concentrated focus on oncology and parenteral nutrition workflows.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Baxter International |
| Fresenius Kabi AG |
| B. Braun SE |
| ICU Medical, Inc. |
| Medtronic |
| Terumo Corporation |
| Q-Core Medical |
| Eitan Medical |
| Others |
Pricing and Supply Chain Analysis
MEMS-based flow sensors displacing traditional piston mechanisms are redrawing procurement geography and compressing component cost structures as manufacturers source compact modules from East Asian foundries while pricing legacy electromechanical platforms at steeper discounts.
Pricing Analysis
Metropolitan United States health systems command 40-60% premiums over Indian clinic networks for equivalent pump hardware. Three-tier pricing structure across premium interoperable fleets, standard electronic platforms, and economy gravity-fed systems stratifies by software depth and certification tier. Cost compression in the mid-tier is intensifying because group purchasing organizations consolidate contract volumes and demand multi-year service bundling. Home care channels in Japan and Australia absorb portable pump premiums, while resource-constrained settings in South Asia remain highly price-sensitive.
Supply Chain Analysis
Controller chip inventory cycles stretching 26-52 weeks are forcing manufacturers to pre-position safety stock and dual-source critical semiconductors. Pump controller chip sourcing draws from Taiwan, South Korea, and China, while precision motors and medical-grade polymers rest on German and Japanese suppliers. Single-source vulnerability in East Asian foundry capacity exposes manufacturers to geopolitical disruption and tariff exposure. Distribution runs through integrated delivery network tenders in the United States, direct oncology clinic sales in Germany, and distributor stock orders for disposable infusion sets across South Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital consolidation across United States metropolitan markets has shifted bargaining power decisively toward buyers, compressing vendor margins and mandating enterprise-wide fleet standardization as a precondition for contract participation.
For Market Incumbents: Compound software subscription revenue through cybersecurity service layers and predictive maintenance contracts to offset hardware margin erosion. Deepen captive manufacturing of MEMS flow sensors to reduce East Asian foundry dependency. Prioritize FDA 510(k) clearance for algorithmic dosing modules to defend against AI-enabled entrants.
For New Entrants and Emerging Players: Lead with ambulatory home care platforms featuring cellular connectivity and simplified patient interfaces, where incumbent presence remains sparse. Target Japan's aging-in-place infusion therapy shift and India's PLI-subsidized manufacturing hubs. Pursue direct-to-patient subscription models bypassing hospital procurement committees.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier specialists with concentrated oncology workflow expertise and regional service density in underserved European markets. Long-term viability hinges on EU MDR and AI Act compliance infrastructure rather than hardware scale. Watch FDA adverse-event reporting spikes in the MAUDE database as an early indicator of algorithmic safety failures reshaping competitive standing.
| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Service Layer Development | Recurring revenue streams from threat monitoring address FDA's heightened enforcement attention on connected-device vulnerabilities. |
| MEMS Flow Sensor Integration | Miniaturized modules enable neonatal and ambulatory applications while reducing dependency on East Asian electromechanical component suppliers. |
| EU MDR Conformity Pathway Investment | Clinical evidence infrastructure unlocks premium positioning in German and Swiss oncology clinics facing steep compliance barriers. |
| Home Care Platform Launch | Portable cellular-connected pumps capture Japan's demographic shift from institutional to residential infusion therapy settings. |
| Hospital System Partnership | Enterprise fleet standardization contracts with Texas and California integrated delivery networks secure multi-year revenue visibility. |
Research Methodology
The analysis maps electronic pump, syringe pump, volumetric pump, and infusion set sub-sectors, each validated through biomedical engineers, hospital purchasing committee members, GPO contracts managers, and oncology clinic administrators. Primary interviews with firmware validation specialists and pharmacy information system integrators combined with secondary validation against FDA 510(k) filings, EU MDR notified-body assessment records, hospital procurement databases, and GPO contract repositories. Bottom-up installed base modeling and top-down healthcare capital expenditure triangulation anchored market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, end-user acuity tier, technology sophistication level, application protocol, and regional regulatory cluster. CAGRs derived from weighted average of historical procurement patterns and forward-looking adoption curves for wireless connectivity and algorithmic dosing. Industry-specific forecast inputs incorporated semiconductor lead time fluctuations and EU AI Act compliance cost trajectories.
Underlying assumptions cover hospital consolidation velocity, foundry capacity allocation, and regulatory enforcement intensity, with deviation risk concentrated in cybersecurity incident frequency and geopolitical disruption of East Asian chip supply. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Vacuum Therapy Devices Market
Diagnostic and Therapeutic Devices
Smart Drug Delivery Systems Market
Diagnostic and Therapeutic Devices
Magnetic Therapy Devices Market
Diagnostic and Therapeutic Devices
Automated Immunoassay Analyzers Market
Diagnostic and Therapeutic Devices
Therapeutic Support Surface Market
Diagnostic and Therapeutic Devices
Nanobiosensors in Healthcare Market
Diagnostic and Therapeutic Devices
Dermatology Diagnostic Equipment Market
Diagnostic and Therapeutic Devices
Leukocytapheresis Device Market
Diagnostic and Therapeutic Devices
Robotic Surgery System Haptic Feedback Test Platforms Market
Diagnostic and Therapeutic Devices
Skin Biopsy Market
Diagnostic and Therapeutic Devices
Therapeutic Hypothermia Systems Market
Diagnostic and Therapeutic Devices
Crohn's Disease Diagnostic and Therapeutic Market
Diagnostic and Therapeutic Devices
Venous Diseases Treatment Market
Diagnostic and Therapeutic Devices
Localized Temperature Therapy Products Market
Diagnostic and Therapeutic Devices
Therapeutic Medical Guidewire Market
Diagnostic and Therapeutic Devices
Cruciate Ligament Diagnosis Treatment Market