
 Global Acoustic Medicine and Ultrasound Therapy Market | 2026-2036
Global Acoustic Medicine and Ultrasound Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acoustic Medicine and Ultrasound Therapy Market Foresight
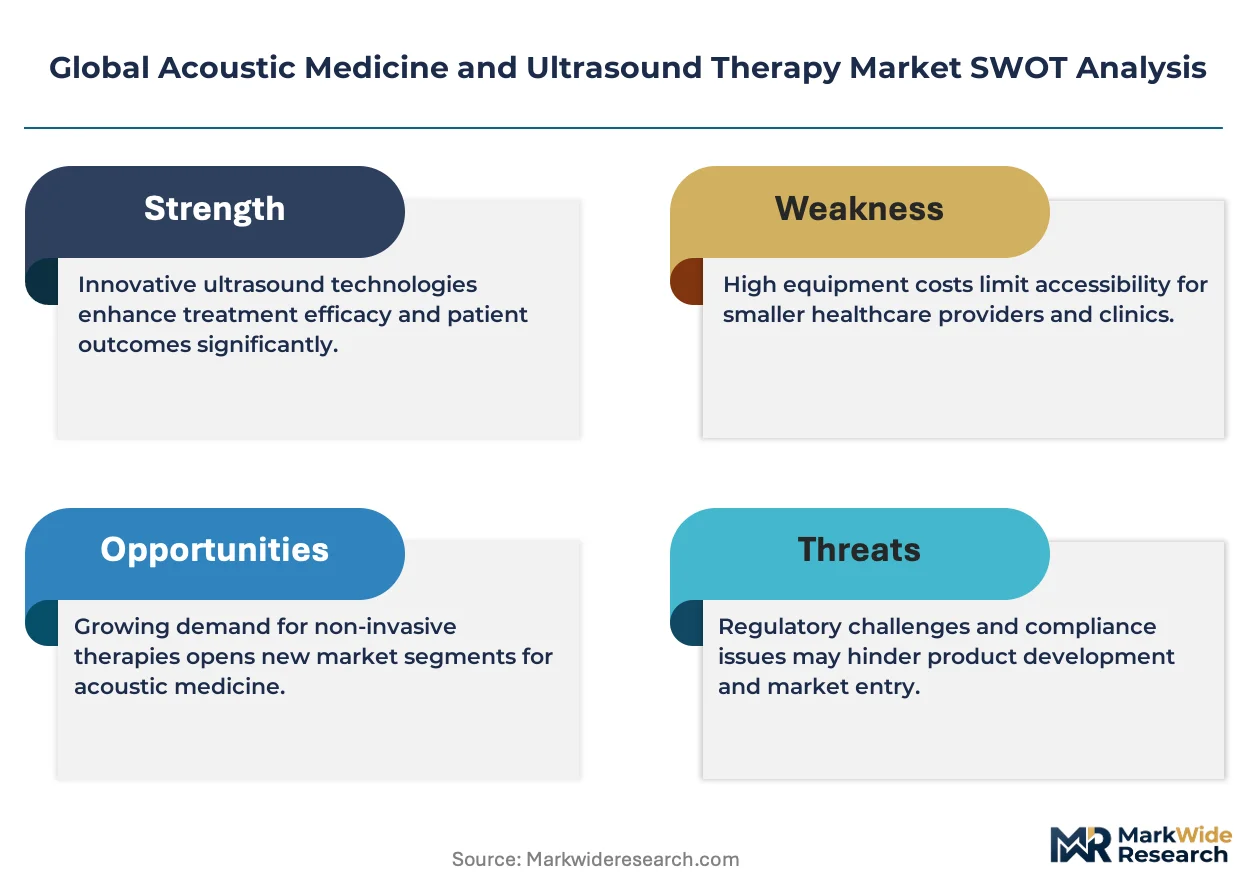
ISO 13485 certification cycles for medical device quality management is unwinding competitive entry barriers across the acoustic therapy supply base. Danaher Corporation leverages its diagnostics platform breadth to sustain integrated ultrasound-therapy workflows in clinical settings. GE Healthcare anchors its position through deep imaging-therapy convergence in hospital radiology departments. Koninklijke Philips N.V. competes by extending its patient monitoring ecosystem into portable therapeutic ultrasound for post-acute care.
Acoustic medicine and ultrasound therapy encompass mechanical wave-based interventions operating at frequencies from 20 kHz to several MHz, with intensity parameters calibrated for thermal, cavitation, or non-thermal bioeffects in tissue repair and pain modulation. High-intensity focused ultrasound concentrates energy at precise tissue depths for ablative or neuromodulatory outcomes, while portable devices and wearable ultrasound formats are gaining traction in ambulatory and home settings where reimbursement flexibility and patient compliance drive preference. Piezoelectric transduction still dominates installed equipment bases, though capacitive micromachined ultrasonic transducers are emerging in miniaturized formats for continuous wearable delivery.
FDA 510(k) premarket notification requirements and EU MDR technical documentation obligations shape product development timelines and commercialization costs for manufacturers targeting the United States and European Economic Area. Japan's PMDA and METI coordinate standards alignment for therapeutic ultrasound devices entering the second-largest aged-care market. China's NMPA accelerates review pathways for innovative acoustic therapy devices under priority review channels. Stakeholders must monitor divergence between regional electromagnetic compatibility and biological safety testing protocols when scaling multi-territory product registrations.
Market Dynamics
Portable therapeutic ultrasound devices are compressing the traditional hospital-centric delivery model, with reimbursement flexibility in outpatient settings accelerating volume migration away from fixed radiology departments.
Growth Catalysts
- EU MDR CE marking pathways:Streamlined conformity assessment for therapeutic ultrasound equipment is shortening time-to-market for manufacturers targeting the European Economic Area.
- Musculoskeletal therapy clinics:Germany's physiotherapy networks are expanding device procurement for non-invasive pain management protocols.
- Capacitive micromachined ultrasonic transducers:CMUT fabrication advances are enabling wearable form factors for continuous acoustic delivery in home healthcare.
Market Restraints
- Piezoelectric ceramic supply concentration:Specialty piezoelectric material production clusters in East Asia, creating input vulnerability for transducer manufacturers elsewhere.
- FDA 510(k) documentation burden:Premarket notification requirements for therapeutic indications impose substantial compliance costs on mid-scale device developers.
- Pharmacological substitution:Oral analgesics and corticosteroid injections retain preference in acute pain protocols where ultrasound therapy lacks immediate symptomatic relief.
Strategic Opportunities
- Japan's aged-care infrastructure:METI-coordinated standards alignment opens priority review channels for neuromodulatory HIFU devices in geriatric applications.
- Reimbursement expansion:United States Medicare Advantage plans are adding therapeutic ultrasound coverage for post-acute home recovery.
- Imaging-therapy convergence:Real-time MRI guidance integration with focused ultrasound ablation is creating premium intervention workflows in oncology departments.
Industry Challenges
- ISO 13485 audit compression:Medical device quality management certification cycles are extending due to notified body capacity constraints.
- Legacy PACS integration:Therapeutic ultrasound workstations require custom interoperability layers with hospital radiology information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acoustic Medicine and Ultrasound Therapy Market |
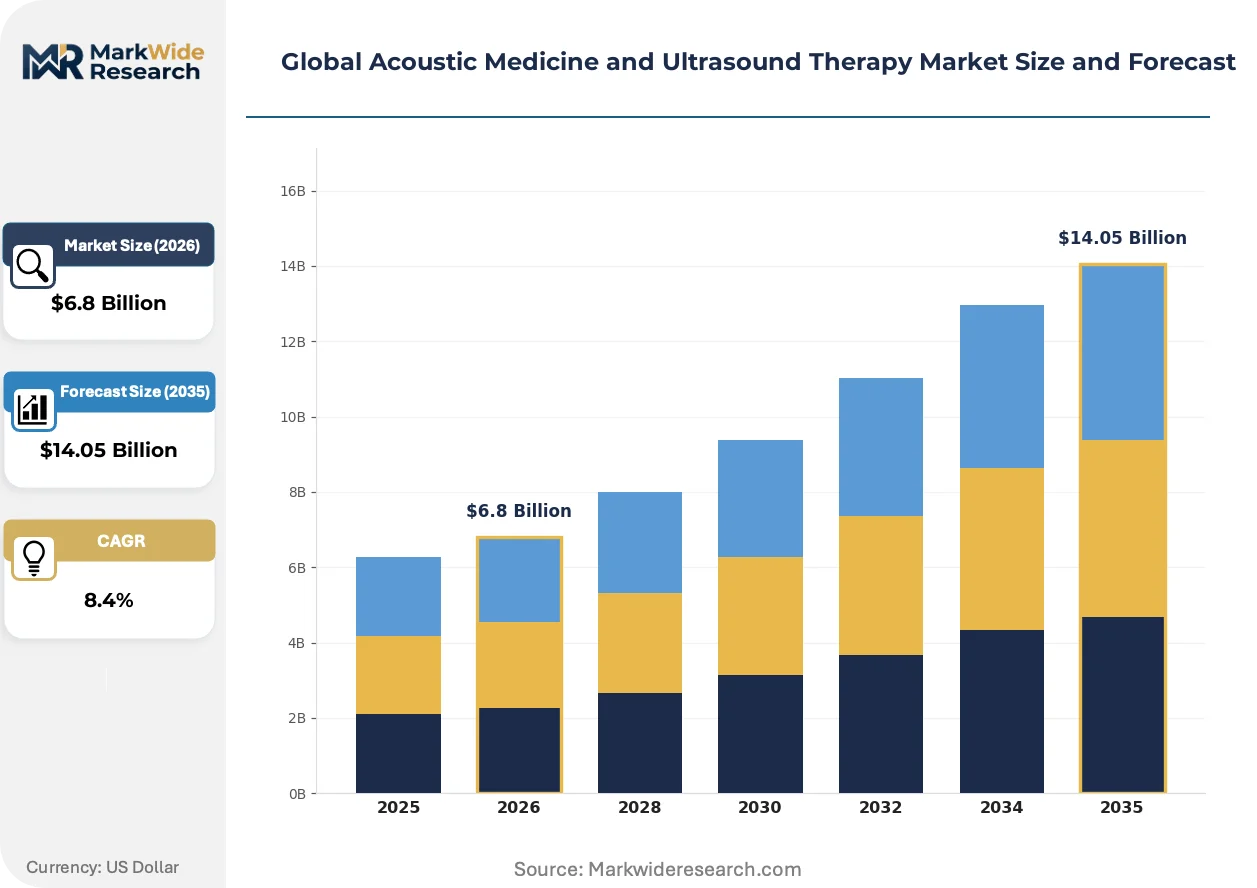
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Intensity Ultrasound, High-Intensity Focused Ultrasound, Portable Devices, Stationary Equipment, Wearable Ultrasound Technology: Piezoelectric, Capacitive Micromachined Ultrasonic Transducers, Laser-Generated Ultrasound, Magnetostrictive, Optical Ultrasound Application: Musculoskeletal Therapy, Wound Healing, Pain Management, Neurological Rehabilitation, Sports Injury Recovery End User: Physiotherapy Clinics, Rehabilitation Centers, Sports Medicine Facilities, Outpatient Care Centers, Home Healthcare Providers |
| Companies Covered | Mettler Electronics Corp., Danaher Corporation, BTL, GE Healthcare, NanoVibronix Corporation, ZetrOZ Systems, Compass Health Brands, Koninklijke Philips N.V., Dynatronics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acoustic Medicine and Ultrasound Therapy Market Shifts & Advancements
Wearable acoustic delivery formats are fragmenting the installed base of cart-based systems, with miniaturization and reimbursement coding changes enabling point-of-care deployment outside traditional clinical settings.
Capacitive micromachined ultrasonic transducer arrays are decomposing the cost structure of continuous therapeutic monitoring. Post-acute care providers in the United States are piloting CMUT-based wearable patches for musculoskeletal recovery. This transducer architecture is decomposing the distinction between diagnostic imaging and therapeutic delivery hardware, compressing capital requirements for ambulatory service lines.
Japan's PMDA has accelerated priority review designation for innovative acoustic therapy devices targeting neurological indications. Domestic manufacturers are recalibrating clinical trial designs to capture this regulatory pathway. The aged-care sector, where Japan holds the second-largest market position globally, is experiencing the most pronounced product registration timeline compression.
Home healthcare providers are unbundling after-sales service from device procurement contracts. Durable medical equipment suppliers in Germany and the United States are shifting toward subscription-based maintenance models. This restructuring is most visible in physiotherapy networks where device utilization intensity varies significantly across clinic locations.
Global Acoustic Medicine and Ultrasound Therapy Market Segmentation
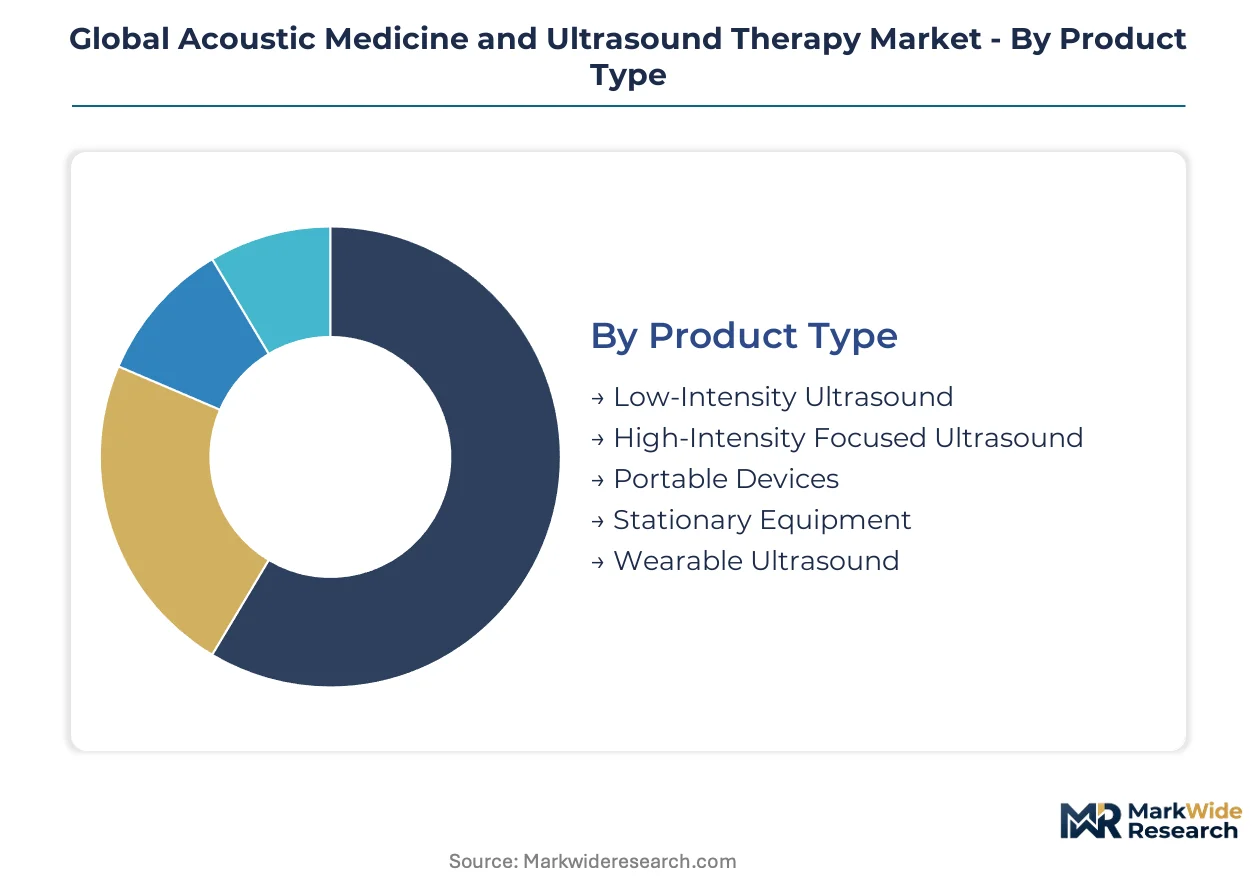
Acoustic medicine markets fragment across therapeutic intensity levels, transducer architectures, and care delivery settings. Each dimension carries distinct regulatory pathways, reimbursement codes, and capital intensity profiles that reshape competitive positioning.
Product Type:
FDA 510(k) clearance timelines diverge sharply between high-intensity ablative systems and low-intensity portable formats, compressing entry windows for the latter.
- High-Intensity Focused Ultrasound:Concentrates acoustic energy at precise tissue depths for thermal ablation and neuromodulation. United States oncology departments and Japan's geriatric care facilities are the primary demand clusters, driven by MRI-guided intervention workflows and METI-coordinated priority review channels.
- Portable Devices:Battery-powered units operating at sub-ablative intensities for musculoskeletal therapy. German physiotherapy networks and United States outpatient care centers are scaling procurement, enabled by reimbursement flexibility in ambulatory settings.
- Low-Intensity Ultrasound:Continuous-wave devices for tissue repair and pain modulation.
- Stationary Equipment:Cart-based systems with integrated imaging guidance for hospital radiology departments.
- Wearable Ultrasound:Patch-form devices enabling continuous acoustic delivery in home healthcare.
Stationary equipment handles the majority of throughput; wearable ultrasound is expanding most quickly on share.
Technology:
Cost tiers separate legacy ceramic fabrication from semiconductor-process transducer manufacturing.
- Piezoelectric:Ceramic-based transduction dominates installed equipment bases through mature supply chains and established calibration protocols. East Asian material production clusters create input concentration for manufacturers elsewhere.
- Capacitive Micromachined Ultrasonic Transducers:Silicon-fabricated arrays enabling miniaturization and continuous monitoring formats. United States post-acute care providers are piloting CMUT-based wearable patches for musculoskeletal recovery.
- Magnetostrictive:Alloy-based transduction for high-power industrial and medical applications.
- Laser-Generated Ultrasound:Optical excitation methods for non-contact therapeutic delivery.
- Optical Ultrasound:Fiber-coupled acoustic generation for integrated diagnostic-therapeutic platforms.
Piezoelectric platforms anchor current revenue; CMUT architectures are climbing the fastest on adoption curves.
Application:
Volume concentrates where reimbursement codes align with procedure volume and clinical evidence requirements.
- Musculoskeletal Therapy:Non-invasive treatment of soft-tissue injuries and chronic pain conditions. German physiotherapy clinics and United States outpatient centers are the primary volume drivers, supported by expanding Medicare Advantage coverage for post-acute recovery.
- Pain Management:Acoustic modulation of neural signaling for chronic and acute pain protocols. Japan's aged-care infrastructure is prioritizing neuromodulatory HIFU applications under PMDA accelerated review.
- Wound Healing:Low-intensity delivery for tissue regeneration in diabetic and pressure ulcers.
- Neurological Rehabilitation:Focused ultrasound for functional recovery in stroke and neurodegenerative conditions.
- Sports Injury Recovery:Portable and wearable formats for athletic training facilities.
Musculoskeletal therapy commands the largest procedure volume; pain management is gaining share fastest on regulatory tailwinds.
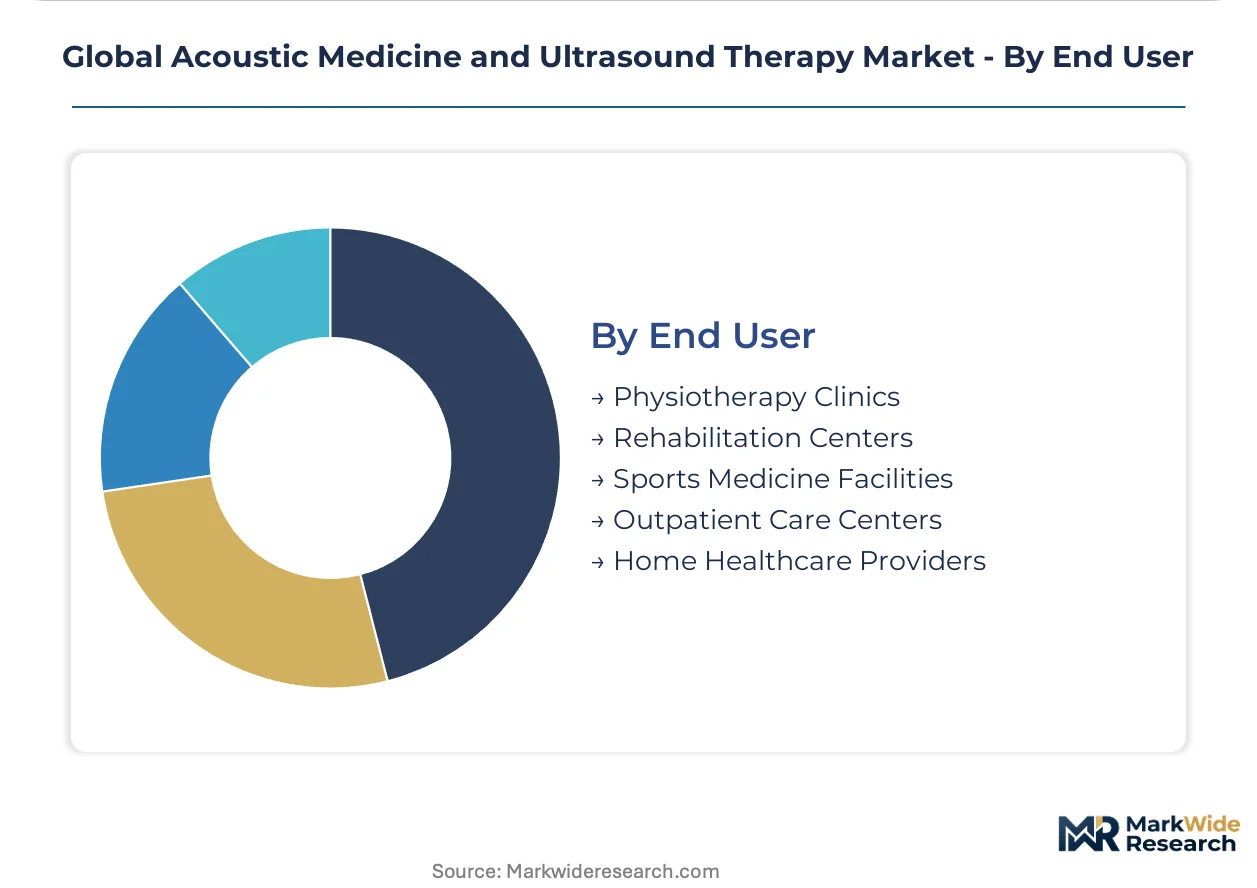
End User:
Customer type determines procurement authority, service contract structures, and device utilization intensity.
- Home Healthcare Providers:Durable medical equipment suppliers scaling subscription-based maintenance models. United States and German markets are unbundling after-sales service from device procurement, with utilization intensity varying significantly across patient populations.
- Outpatient Care Centers:Freestanding facilities capturing volume migration from hospital radiology departments. Reimbursement coding changes are accelerating point-of-care deployment outside traditional clinical settings.
- Physiotherapy Clinics:Independent and network-affiliated practices in Germany and Japan.
- Rehabilitation Centers:Post-acute facilities integrating therapeutic ultrasound into recovery protocols.
- Sports Medicine Facilities:Athletic training and performance centers deploying portable formats.
Outpatient care centers process the highest device throughput; home healthcare providers are expanding most rapidly on reimbursement restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's medical technology logistics corridor underwrites Germany's distribution dominance across European acoustic therapy supply chains, connecting North Sea shipping lanes to Central European physiotherapy networks.
United States
Outpatient care centers in Texas and Florida are scaling portable ultrasound procurement for post-acute musculoskeletal recovery. FDA 510(k) premarket notification pathways are tightening documentation requirements for therapeutic indication claims. The Minneapolis medical device cluster houses engineering centers where imaging-therapy convergence platforms undergo clinical validation.
Germany
Bavarian physiotherapy networks are expanding device procurement for non-invasive pain management protocols under statutory health insurance reimbursement. EU MDR CE marking technical documentation obligations are extending notified body audit cycles for transducer manufacturers. The Stuttgart industrial corridor concentrates piezoelectric ceramic supply relationships for premium equipment fabricators.
Japan
Tokyo's aged-care infrastructure is prioritizing neuromodulatory HIFU applications for geriatric neurological conditions. METI coordinates standards alignment with PMDA accelerated review channels for innovative acoustic therapy devices. The Osaka-Kobe manufacturing belt hosts precision transducer fabrication facilities serving domestic and export markets.
China
Shanghai's hospital procurement consortia are expanding tender volumes for domestic therapeutic ultrasound equipment. NMPA priority review channels compress registration timelines for innovative acoustic therapy devices under national medical device reform directives. The Shenzhen electronics corridor supplies capacitive micromachined ultrasonic transducer components for wearable form factor development.
Global Acoustic Medicine and Ultrasound Therapy Market Competitive Landscape
Listed leaders compete with private specialists across integrated diagnostics and pure-play therapeutic equipment segments. The vendor base stratifies between diversified conglomerates with imaging platforms and focused device developers serving physiotherapy networks. Three archetypes dominate: imaging-therapy convergers, portable specialists, and component-integrated manufacturers. Consolidation pressure is accelerating through strategic licensing arrangements and geographic expansion into reimbursement-favorable markets.
Among diversified healthcare conglomerates, Danaher Corporation and GE Healthcare occupy positions spanning diagnostic imaging through therapeutic delivery workflows. Koninklijke Philips N.V. sits within the patient monitoring ecosystem extension archetype, leveraging ambulatory care connectivity for post-acute therapeutic ultrasound deployment. Dynatronics Corporation exemplifies the mid-scale specialist tier focused on physiotherapy clinic procurement channels.
| Leading Market Players |
|---|
| Mettler Electronics Corp. |
| Danaher Corporation |
| BTL |
| GE Healthcare |
| NanoVibronix Corporation |
| ZetrOZ Systems |
| Compass Health Brands |
| Koninklijke Philips N.V. |
| Dynatronics Corporation |
| Others |
Supply & Pricing Matrix
Capacitive micromachined ultrasonic transducer adoption is displacing legacy piezoelectric ceramic procurement across portable and wearable device tiers, simultaneously shifting fabrication geography toward East Asian semiconductor corridors and compressing per-unit cost structures for continuous acoustic delivery formats.
Pricing Analysis
Certification level (ISO 13485/CE/FDA-grade) creates the primary spread between premium hospital-grade systems and economy-tier portable units. Three-tier pricing structure across premium, standard, and economy levels stratifies by transducer architecture sophistication and after-sales service bundling. Pricing pressure stems from CMUT-based miniaturization enabling lower-cost wearable entrants. Outpatient care centers exhibit highest price sensitivity; oncology departments purchasing MRI-guided HIFU systems show lowest.
Supply Chain Analysis
Strait of Malacca transit underwrites piezoelectric ceramic supply security for Western transducer manufacturers, with bulk material flows originating from Chinese and Japanese specialty ceramic producers. CMUT fabrication draws from Taiwan and South Korea semiconductor foundries, while final assembly concentrates in China's Shenzhen electronics corridor and Germany's Stuttgart industrial belt. Single-source vulnerability in PZT ceramic feedstock creates exposure to export licensing shifts. Distribution runs through hospital procurement consortia and durable medical equipment suppliers with subscription-based service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oral analgesics and corticosteroid injections pose persistent substitution pressure that acoustic therapy incumbents must counter through outcome differentiation and reimbursement expansion.
For Market Incumbents: Fortify CMUT fabrication partnerships in Taiwan and South Korea to secure miniaturization capacity ahead of wearable format migration. Deepen backward integration into piezoelectric ceramic supply through captive relationships with Japanese material specialists, insulating against East Asian supply concentration. Prioritize FDA 510(k) pathway expertise as a barrier against mid-scale competitors facing documentation burden.
For New Entrants and Emerging Players: Post-acute home recovery service gaps in United States Medicare Advantage networks offer white-space entry where reimbursement coding is expanding. Target German physiotherapy clinic procurement channels where statutory health insurance coverage is widening. Deploy subscription-based maintenance models to unbundle after-sales service from device capital expenditure, matching durable medical equipment supplier restructuring.
For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors component-integrated manufacturers with CMUT fabrication capabilities over legacy piezoelectric specialists. Long-term viability over the next decade hinges on imaging-therapy convergence platform development and ambulatory care connectivity. Watch PMDA priority review designation velocity for neuromodulatory HIFU devices as inflection indicator for geriatric application scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR streamlined conformity assessment accelerates European Economic Area market entry timelines. |
| Hospital System Partnership | Radiology department integration secures imaging-therapy convergence workflows and capital equipment placement. |
| Software Companion Development | Real-time MRI guidance integration enables premium oncology ablation procedures with precise tissue targeting. |
| Reimbursement Strategy | Medicare Advantage coverage expansion in post-acute home recovery unlocks wearable ultrasound volume. |
| CMUT Fabrication Scale-Up | Silicon-process transducer manufacturing reduces cost structure for continuous monitoring patch formats. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) premarket notification databases, EU MDR technical documentation filings, and hospital procurement contract registries. Conversations with biomedical engineers, GPO contracts managers, physiotherapy clinic procurement leads, and PMDA regulatory consultants inform demand and competitive dynamics. CMS Medicare reimbursement data and Japanese METI standards alignment publications provide secondary validation. Bottom-up device shipment analysis triangulates against top-down healthcare expenditure modeling.
Segmentation dimensions modeled span therapeutic intensity level, transducer architecture, care delivery setting, and regional regulatory cluster across the analysis window. CAGRs derive from installed base replacement cycles, reimbursement code expansion trajectories, and CMUT adoption curve penetration. Forecast inputs incorporate PMDA priority review timeline compression and EU MDR notified body audit capacity constraints.
Underlying assumptions cover sustained reimbursement expansion for outpatient ultrasound therapy, with deviation risk concentrated in FDA documentation burden escalation and piezoelectric ceramic supply disruption. Practitioners should keep alternative scenarios live as METI-PMDA coordination depth and Medicare Advantage plan coverage evolution unfold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
One-Step ELISA Market
Diagnostic and Therapeutic Devices
Pelvic Congestion Syndrome Treatment Market
Diagnostic and Therapeutic Devices
Therapeutic Support Surface Market
Diagnostic and Therapeutic Devices
Dermatology Diagnostic Equipment Market
Diagnostic and Therapeutic Devices
Skin Biopsy Market
Diagnostic and Therapeutic Devices
Global Needle Free Injection Systems Market
Diagnostic and Therapeutic Devices
Smart Infusion System Market
Diagnostic and Therapeutic Devices
Smart Inhalers Market
Diagnostic and Therapeutic Devices
Cruciate Ligament Diagnosis Treatment Market
Diagnostic and Therapeutic Devices
Automated Immunoassay Analyzers Market
Diagnostic and Therapeutic Devices
Crohn's Disease Diagnostic and Therapeutic Market
Diagnostic and Therapeutic Devices
Venous Diseases Treatment Market
Diagnostic and Therapeutic Devices
Therapeutic Hypothermia Systems Market
Diagnostic and Therapeutic Devices
Therapeutic Apheresis Market
Diagnostic and Therapeutic Devices
Germany Smart Healthcare Market
Diagnostic and Therapeutic Devices
Dissolving Microneedles Market