
 Thailand Folding Cartons and Corrugated Packaging Market | 2026-2036
Thailand Folding Cartons and Corrugated Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Folding Cartons and Corrugated Packaging Market Analytics
Modular multi-pack configurations are rebalancing how Thai beverage and personal care brands specify secondary packaging. Siam Kraft Industry Co. leverages integrated pulp-to-box operations across its Samut Prakan complex to secure raw material continuity. Oji Holdings Corporation anchors regional supply through its Thai manufacturing base, serving Japanese automotive transplants with just-in-time corrugated delivery. Thai Containers Group dominates containerboard production with captive access to SCG Packaging's recycling network.
Thailand folding cartons and corrugated packaging encompasses paper-based convert-to-shape containers engineered from kraft linerboard, recycled fluting, and clay-coated folding boxboard, typically formed through rotary die-cutting, flexo-gluing, and hot-melt sealing processes to protect goods through distribution and retail display. Corrugated boxes lead volume throughput due to e-commerce fulfillment expansion and agricultural export crating, while folding cartons capture premium margin pools in cosmetics and pharmaceutical blister packs where lithographic print quality governs shelf appeal. Recycled paper feedstock competes aggressively with virgin kraft as Thai mills modernize de-inking lines to meet brand sustainability procurement standards.
Thailand's Ministry of Industry enforces packaging material labeling rules through the Thai Industrial Standards Institute, while the Pollution Control Department administers extended producer responsibility frameworks that elevate recycled content mandates. Board of Investment promotional privileges for green manufacturing projects are redirecting capital toward water-based ink conversion and biomass boiler retrofits. Stakeholders must monitor how rapidly Bangkok's municipal waste sorting infrastructure scales, since collection purity directly determines whether domestic recycled fiber can displace imported pulp at scale.
Market Dynamics
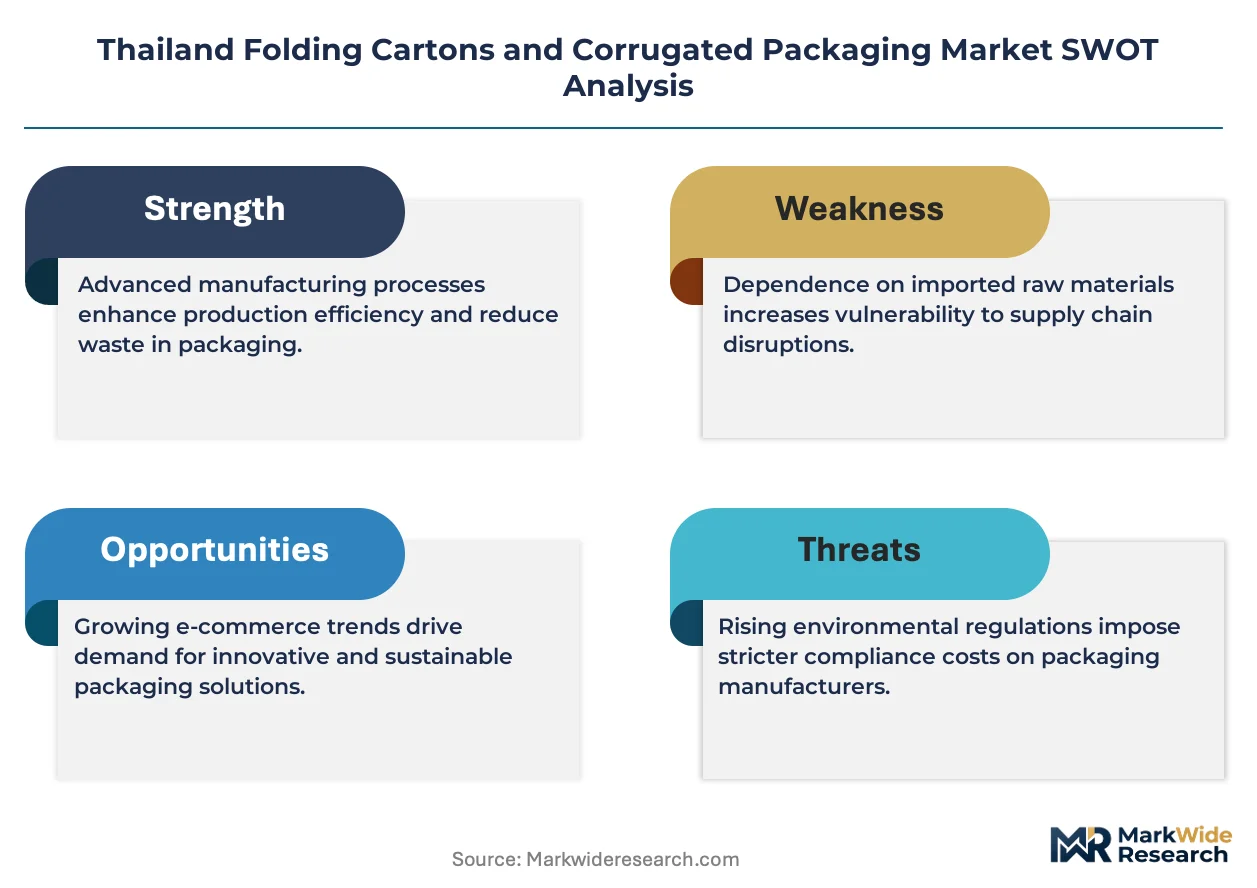
Thailand's packaging sector is compressing around Board of Investment incentives that reward fiber-based conversion and biomass energy retrofits, redirecting capital away from plastic-dependent legacy assets toward integrated pulp-to-box complexes.
Growth Catalysts
- Extended Producer Responsibility Mandates:Thailand's Pollution Control Department enforces recycled content thresholds that elevate demand for de-inked fiber. Domestic mills are scaling water-based ink conversion lines to qualify.
- Automotive Export Clustering:Japanese transplants in the Eastern Economic Corridor source just-in-time corrugated from co-located packaging facilities, compressing lead times and locking in volume commitments.
- Agricultural Export Crating:Durian and longan shippers in Chanthaburi and Rayong are specifying moisture-resistant corrugated for cold-chain logistics to China, displacing wooden crates.
Market Restraints
- Recycled Pulp Import Dependence:Bangkok's municipal sorting infrastructure yields insufficient collection purity, forcing mills to import OCC from Vietnam and Indonesia at volatile price spreads.
- Energy Cost Concentration:Natural gas-fired drying dominates Samut Prakan and Prachin Buri mill complexes, exposing margin structures to PTT price fluctuations without biomass fallback.
- Fluting Substitution:Honeycomb paperboard from Chinese suppliers undercuts domestic B-flute on weight-sensitive electronics shipments, compressing specification ranges.
Strategic Opportunities
- Underpenetrated Northeast Corridor:Khon Kaen and Udon Thani lack integrated box plants, creating white space for regional corrugated conversion serving processed food exporters.
- Pharmaceutical Blister Integration:Folding carton converters can capture value-add by pairing clay-coated boxboard with cold-form foil laminates for Bangkok's generic drug manufacturers.
- Biomass Boiler Incentives:Board of Investment promotional privileges for green manufacturing projects subsidize rice husk and bagasse boiler retrofits, cutting fossil fuel exposure.
Industry Challenges
- Rotary Die-Cutting Skill Scarcity:Thai vocational institutes graduate insufficient flexo-gluing technicians, forcing Samut Prakan plants to poach from regional competitors at wage premiums.
- Thai Industrial Standards Certification Lag:TISI labeling compliance for food-contact board requires 14-18 month validation timelines, delaying new product launches for export-ready brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Folding Cartons and Corrugated Packaging Market |
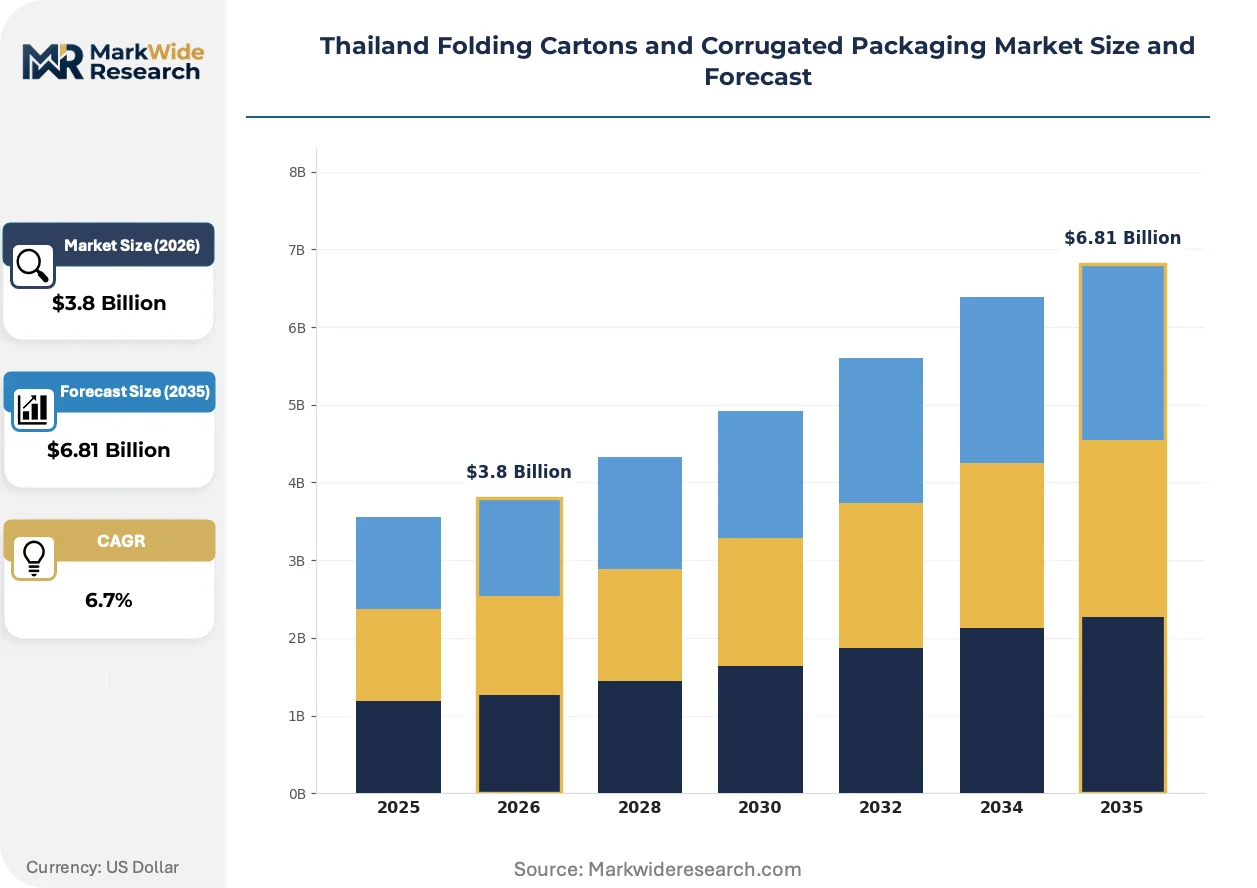
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding Cartons, Corrugated Boxes, Rigid Boxes, Paperboard Containers Material: Paperboard, Recycled Paper, Fluted Plastic, Kraft Paper End User: Food & Beverage, Personal Care, Healthcare, Electronics Printing Technology: Flexographic, Digital, Lithographic, Offset |
| Companies Covered | Continental Packaging (Thailand) Co. Ltd, Siam Kraft Industry Co., Siam Toppan Packaging Co. Ltd, International Paper (Thailand), Thai Utility Packaging Co., Thai Containers Group (SCG Packaging), Oji Holdings Corporation, ASA Group Company Limited, Thung Hua Sinn Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Folding Cartons and Corrugated Packaging Market Evolving Landscape
Water-based barrier coatings and digital print insertion are resequencing how Thai converters specify equipment and qualify substrates for brand-direct contracts.
High-performance fluorine-free grease barriers are expanding into ready-to-eat noodle and fried snack applications where polyethylene lamination previously dominated. Bangkok-based food processors are qualifying these coatings for 180-day shelf-life exports to Australia. The technology is expanding into specification ranges that were exclusively plastic-dependent five years ago.
Thailand's Pollution Control Department is tightening extended producer responsibility frameworks for packaging waste, compelling converters to document post-consumer recycled content through chain-of-custody audits. Folding carton suppliers serving Tesco Lotus and 7-Eleven private labels must now submit third-party verification. Cosmetics and pharmaceutical blister pack segments are responding fastest, accelerating lithographic press upgrades to handle lower-brightness recycled substrates.
Direct-to-retailer procurement contracts are consolidating formerly fragmented buyer bases, compressing distributor margins in Bangkok metropolitan wholesale channels. Major beverage brands now specify carton geometry and print registration directly with Samut Prakan converters, bypassing traditional packaging trading houses. This pattern is most visible in energy drink and ready-to-drink coffee segments where shelf differentiation drives specification control.
Thailand Folding Cartons and Corrugated Packaging Market Segmentation
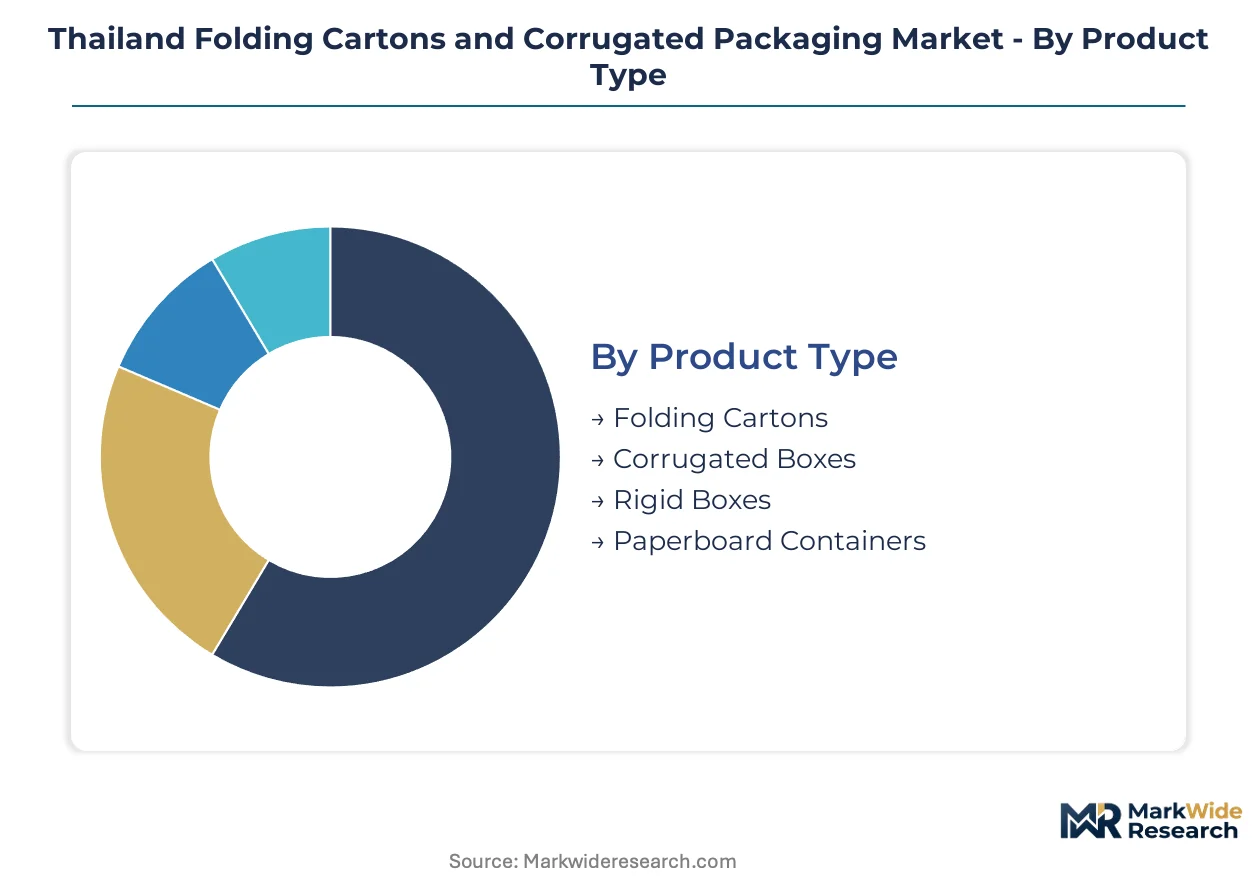
Packaging converters in Thailand calibrate equipment and substrate specifications against four intersecting dimensions: product geometry, fiber source, end-use performance requirements, and print quality thresholds. Each segmentation axis carries distinct margin structures and capital intensity profiles that determine competitive positioning.
Product Type:
Equipment upgrade cycles across Samut Prakan and Chonburi conversion facilities are resequencing capacity allocation between folding and corrugated formats as brands consolidate supplier bases.
- Folding Cartons:Clay-coated boxboard structures formed through rotary die-cutting and hot-melt gluing serve pharmaceutical blister packs and cosmetics where lithographic registration governs shelf appeal. Bangkok-based generic drug manufacturers are specifying cold-form foil laminates paired with folding cartons for ASEAN export compliance.
- Corrugated Boxes:Kraft linerboard and recycled fluting combinations dominate agricultural export crating and e-commerce fulfillment through the Eastern Economic Corridor. Durian and longan shippers in Chanthaburi specify moisture-resistant C-flute for cold-chain logistics to China, displacing wooden crate alternatives.
- Rigid Boxes:Thick paperboard constructions with wrapped edges capture premium personal care and gift packaging segments where unboxing experience drives specification.
- Paperboard Containers:Liquid packaging board applications for UHT milk and ready-to-drink coffee are expanding through Thai Containers Group's integrated pulp-to-box operations.
Corrugated Boxes sits at the top of the volume ranking, with Folding Cartons climbing the fastest as pharmaceutical and cosmetics brands upgrade print specifications.
Material:
Cost tier differentiation between virgin and recycled fiber streams is compressing as Bangkok's municipal sorting infrastructure scales and de-inking technology improves.
- Paperboard:Virgin kraft and bleached chemical pulp substrates deliver consistent caliper and brightness for high-end folding carton applications where color fidelity is non-negotiable.
- Recycled Paper:Post-consumer OCC and de-inked pulp compete aggressively on price for corrugated medium and linerboard, though import dependence from Vietnam and Indonesia creates volatility.
- Fluted Plastic:Polypropylene and polyethylene corrugated alternatives penetrate electronics and agricultural applications requiring moisture immunity beyond paper-based barriers.
- Kraft Paper:Unbleached virgin fiber from Thai eucalyptus plantations supplies linerboard for heavy-duty export crating and industrial protective packaging.
Paperboard commands the highest unit margins, while Recycled Paper is gaining share fastest as Extended Producer Responsibility mandates tighten.
End User:
Customer type concentration in the Eastern Economic Corridor is pulling corrugated capacity toward automotive and electronics clusters while folding carton investment tracks toward pharmaceutical and food processing zones.
- Food & Beverage:Ready-to-eat noodle exporters and energy drink brands in Bangkok metropolitan area specify water-based barrier coatings for 180-day shelf-life exports to Australia, displacing polyethylene lamination.
- Personal Care:Cosmetics brands serving Tesco Lotus and 7-Eleven private labels demand folding cartons with third-party verified post-consumer recycled content and lithographic print quality.
- Healthcare:Generic drug manufacturers require cold-form foil integration with clay-coated boxboard for blister pack compliance with Thai Industrial Standards Institute labeling rules.
- Electronics:Japanese automotive transplants in Rayong and Chonburi source just-in-time corrugated from co-located packaging facilities, compressing lead times.
Food & Beverage holds the largest volume position, with Healthcare expanding most quickly as pharmaceutical exports to ASEAN markets accelerate.
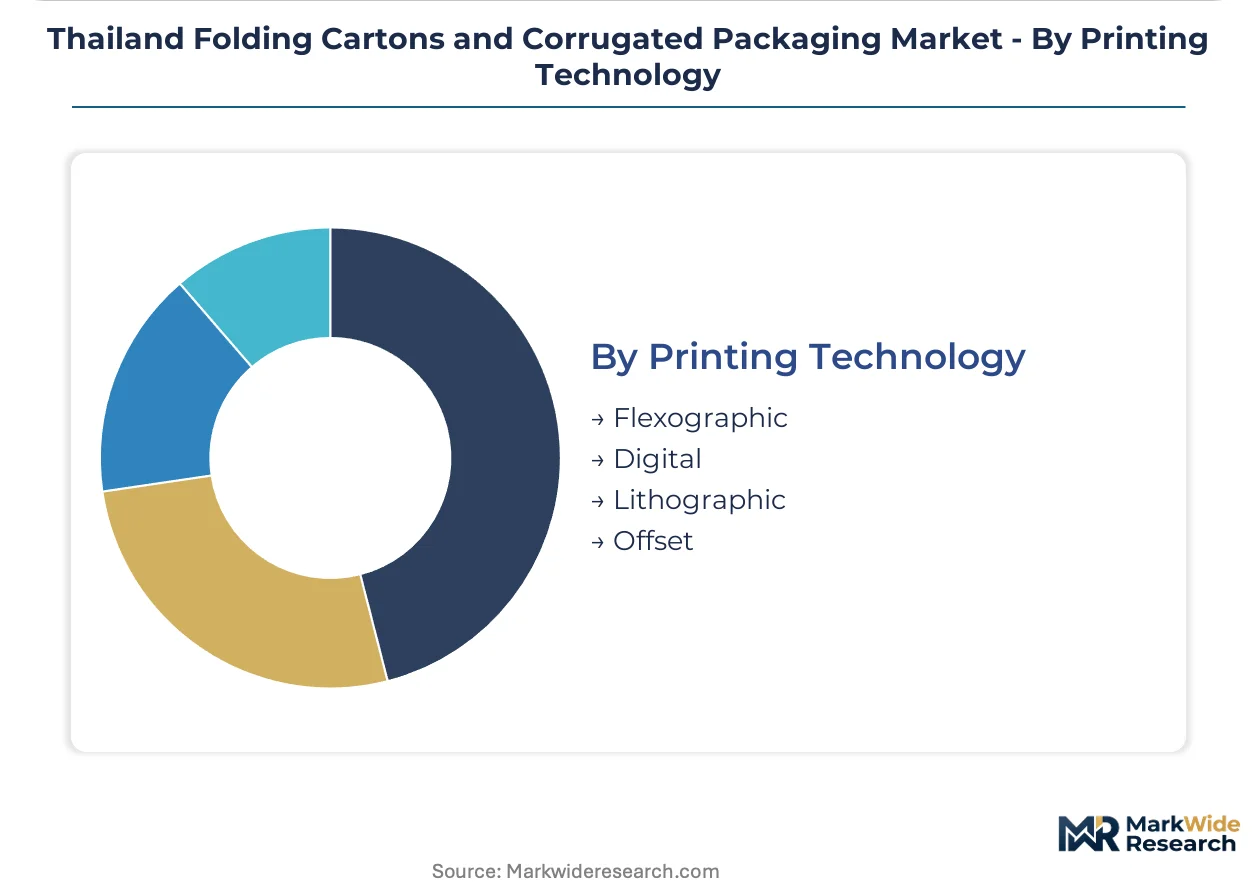
Printing Technology:
Margin stratification across print methods is sharpening as brand-direct procurement contracts bypass traditional distributors and specify registration tolerances directly.
- Flexographic:Water-based ink systems on corrugated substrates dominate high-volume beverage and agricultural export applications where speed outweighs fine-line detail.
- Digital:Variable data and short-run personalization capabilities are penetrating promotional packaging and regional SKU fragmentation for multinational brands testing Thai market entry.
- Lithographic:Offset litho on clay-coated folding boxboard governs pharmaceutical and premium cosmetics segments where 175-line screen resolution differentiates shelf presence.
- Offset:Sheet-fed offset presses handle medium-run folding carton work for processed food brands requiring consistent PMS color matching across batch sizes.
Flexographic retains the highest throughput volume, with Digital gaining share fastest as brand SKU proliferation and personalization demands intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pulp-to-box manufacturing in Thailand traces its modern scale to Japanese industrial investment waves of the 1980s-90s, when packaging capacity clustered around Bangkok's emerging export processing zones. Today's capacity geography reflects that legacy, with integrated mills and conversion plants concentrated in specific industrial corridors.
Bangkok Metropolitan Region
Ready-to-eat food exporters and beverage brands in Samut Prakan drive specification-intensive folding carton demand. The Thai Industrial Standards Institute enforces food-contact labeling rules that extend validation timelines. Japanese packaging transplants co-locate with automotive assemblers in Lat Krabang industrial estates for just-in-time corrugated supply.
Eastern Economic Corridor
Rayong and Chonburi host the densest concentration of corrugated conversion serving electronics and automotive clusters. Board of Investment promotional privileges for green manufacturing projects subsidize biomass boiler retrofits in this zone. Durian and longan exporters in Chanthaburi specify moisture-resistant C-flute for cold-chain logistics to China.
Central Plains
Prachin Buri and Saraburi mill complexes process recycled OCC into linerboard for agricultural crating. Natural gas-fired drying exposes margin structures to PTT price volatility without sufficient biomass fallback. The Pollution Control Department's extended producer responsibility frameworks elevate recycled content mandates for converters serving domestic distribution.
Northeast Region
Khon Kaen and Udon Thani lack integrated box plants despite processed food exporter growth. White space exists for regional corrugated conversion serving Isaan-based agribusiness. Bangkok-based distributors currently cover this territory with extended lead times and higher logistics costs.
Southern Peninsula
Surat Thani and Songkhla handle rubber and palm oil export packaging with lower specification requirements than Bangkok. Thai Containers Group's recycling network extends collection into this region. Port proximity to Malaysia creates cross-border fiber sourcing opportunities for border-zone converters.
Thailand Folding Cartons and Corrugated Packaging Market Competitive Landscape
Premium-margin players sit above commodity-margin players across print quality tiers and substrate certification levels. Siam Prakan complexes house integrated pulp-to-box operators alongside independent converters serving spot markets. Three archetypes dominate: integrated multinational anchors with captive fiber supply, domestic conglomerate divisions leveraging group recycling networks, and independent specialists competing on short-run flexibility. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with biomass retrofit partnerships and brand-direct procurement contracts reshaping channel structures.
Among Japanese-anchored multinationals, Oji Holdings Corporation exemplifies the integrated archetype through its Thai manufacturing base. Siam Kraft Industry Co. occupies a position within the domestic conglomerate tier, leveraging group pulp assets across its Samut Prakan complex. Thai Containers Group anchors the recycling-integrated archetype through its access to SCG Packaging's fiber recovery network. These three represent distinct strategic positions rather than comparable operational models.
| Leading Market Players |
|---|
| Continental Packaging (Thailand) Co. Ltd |
| Siam Kraft Industry Co. |
| Siam Toppan Packaging Co. Ltd |
| International Paper (Thailand) |
| Thai Utility Packaging Co. |
| Thai Containers Group (SCG Packaging) |
| Oji Holdings Corporation |
| ASA Group Company Limited |
| Thung Hua Sinn Group |
| Others |
Value Network & Pricing Analysis
Natural gas-fired drying costs cascade from PTT pricing volatility through Samut Prakan mill complexes into three-tier pricing stratification across premium lithographic folding cartons, standard flexographic corrugated, and economy-grade recycled medium. This cost transmission splits margin structures between biomass-retrofitted integrated operators and fossil-dependent independent converters.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs Thailand's packaging procurement. Premium lithographic folding cartons for pharmaceutical blister packs command spreads based on Thai Industrial Standards Institute certification timelines and cold-form foil integration complexity. Standard flexographic corrugated for agricultural exports faces compression from honeycomb paperboard substitution on weight-sensitive electronics shipments. Economy-grade recycled medium for domestic distribution absorbs the sharpest price erosion as Vietnamese and Indonesian OCC imports fluctuate. Brand-direct procurement contracts in energy drink and ready-to-drink coffee segments exhibit lowest price sensitivity; bulk agricultural exporters in Chanthaburi show highest sensitivity to linerboard cost swings.
Supply Chain Analysis
Direct-to-brand procurement channels now handle specification-intensive folding carton demand from Bangkok's generic drug manufacturers and cosmetics exporters, bypassing traditional packaging trading houses. Raw material flows draw from Thai eucalyptus plantations for virgin kraft linerboard, Vietnamese and Indonesian OCC imports for recycled medium, and Chinese honeycomb paperboard for electronics protective applications. Distribution runs through co-located packaging facilities in the Eastern Economic Corridor for Japanese automotive transplants requiring just-in-time delivery. Single-source vulnerability concentrates in Bangkok's municipal waste sorting infrastructure, whose insufficient collection purity forces mills to import de-inked fiber at volatile spreads.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's packaging sector offers margin expansion through biomass boiler retrofits subsidized by Board of Investment promotional privileges, converting fossil fuel exposure into cost-down advantage while locking in green manufacturing credentials.
For Market Incumbents: Hedge against honeycomb paperboard substitution by accelerating water-based barrier coating qualification for ready-to-eat noodle exporters. Secure backward integration into de-inking capacity before Extended Producer Responsibility mandates tighten recycled content thresholds. Prioritize cold-form foil laminate partnerships with Bangkok generic drug manufacturers to defend specification control in pharmaceutical blister packs. For New Entrants and Emerging Players: The 180-day shelf-life export specification gap between polyethylene-laminated legacy formats and fluorine-free grease barrier alternatives opens white space in Australian-bound ready-to-eat segments. Khon Kaen and Udon Thani's absence of integrated box plants creates regional corrugated conversion opportunity serving Isaan-based agribusiness. Lead with digital print insertion capabilities for promotional packaging and multinational brand SKU fragmentation testing Thai market entry. For Investors and Strategic Acquirers: Roll-up economics work for independent corrugated specialists with biomass retrofit eligibility because Board of Investment green manufacturing subsidies create immediate cost-structure separation from fossil-dependent competitors. Target converters with Thai Industrial Standards Institute certification pipelines and established brand-direct relationships. Watch Bangkok municipal waste sorting infrastructure scaling as the inflection signal determining whether domestic recycled fiber can displace imported OCC at sufficient purity grades.| Strategic Initiative | Industry Significance |
|---|---|
| Biomass Boiler Retrofit | Board of Investment subsidies cut PTT price exposure for Samut Prakan mill operators. |
| Water-Based Barrier Coating Qualification | Bangkok food processors qualify 180-day shelf-life exports to Australia without polyethylene lamination. |
| Cold-Form Foil Integration | Thai Industrial Standards Institute compliance locks in pharmaceutical blister pack specification control. |
| Digital Print Insertion Capability | Variable data personalization captures promotional packaging from multinational brand SKU proliferation. |
| Northeast Corridor Regional Conversion | Khon Kaen and Udon Thani white space reduces logistics costs for Isaan agribusiness exporters. |
Research Methodology
Multiple input streams — primary interviews with folding carton procurement managers at Bangkok pharmaceutical manufacturers, corrugated supply chain directors at Eastern Economic Corridor automotive facilities, and Board of Investment project approval officers — were reconciled against secondary validation from Thai Industrial Standards Institute labeling compliance databases, Pollution Control Department extended producer responsibility filings, and SCG Packaging recycling network disclosures. Bottom-up capacity and production estimates from Samut Prakan and Chonburi conversion facilities were cross-referenced with top-down demand aggregation across food and beverage, personal care, healthcare, and electronics end-use segments.
Historical volume trajectories were cross-referenced against panel input from mill operations managers and brand procurement leads to anchor projection assumptions across the analysis window. Segmentation modeling incorporated product type, fiber source, end-use performance requirements, and print quality thresholds. CAGRs were derived from reconciled demand-supply balances rather than extrapolated trend lines. Forecast inputs included Board of Investment incentive uptake rates, municipal waste sorting infrastructure deployment timelines, and water-based barrier coating qualification velocities at Bangkok ready-to-eat exporters.
The model assumes a particular technology adoption path; alternative pathways for fluorine-free grease barrier penetration or digital print insertion acceleration would alter the outlook. Forecasts reflect base-case assumptions about Extended Producer Responsibility mandate enforcement timing and Bangkok collection purity improvement rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Carton Form Fill Seal Machine Market
Cartons
Child-Resistant Carton Box Market
Cartons
Shaped Liquid Cartons Market
Cartons
Global Hand Carton Sealers Market
Cartons
Fully Enclosed Cartons Market
Cartons
Pizza Cartons Market
Cartons
Cupcake Box Market
Cartons
Global Beverage Carton Packaging Machinery Market
Cartons
Box and Carton Overwrapping Machines Market
Cartons
Beverage Cartoners Market
Cartons
Metallized PET Cartons Market
Cartons
Round Corrugated Box Market
Cartons
Carton Serialization Machine Market
Cartons
Global Open Top Cartons Market
Cartons
Cartoning Machines Market
Cartons
Folding Cartons Market