
 Polyethylene Corrugated Packaging Market | 2026-2036
Polyethylene Corrugated Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Polyethylene Corrugated Packaging Market Analytics
ISO 18606 compliance for packaging recyclability is redrawing competitive boundaries across the polyethylene corrugated sector. DS Smith leverages its European recycling infrastructure to secure closed-loop supply agreements with major retailers. Smurfit Kappa anchors its position through integrated paper and plastics operations spanning multiple continents. Amcor differentiates via advanced barrier coextrusion technologies embedded within corrugated sheet production.
Polyethylene corrugated packaging comprises extruded twin-wall plastic sheets formed from high-density or low-density polyethylene resins, typically manufactured through profile extrusion with corrugated flute structures ranging from 3mm to 10mm thickness. These lightweight, moisture-resistant structures serve primarily as protective shipping containers, layer pads, and reusable material handling systems across manufacturing and distribution chains. The boxes segment dominates current volume flows, driven by e-commerce fulfillment requirements for stackable, returnable containers. Sheets and dividers represent the fastest-expanding category, as electronics manufacturers adopt custom-cut inserts to replace foam-based protective packaging. Trays occupy a specialized niche within pharmaceutical cold chain logistics, where washdown compatibility and dimensional stability command premium positioning.
The EPA's recycled content guidelines under the National Recycling Strategy interact with FDA food-contact material regulations to shape product formulation requirements for U.S.-bound polyethylene corrugated packaging. REACH compliance within the European Union restricts certain additive chemistries, compelling reformulation of UV stabilizers and colorants used in extruded sheet production. Stakeholders must monitor evolving extended producer responsibility frameworks across multiple jurisdictions, as these programs will determine cost structures for post-consumer collection and reprocessing infrastructure.
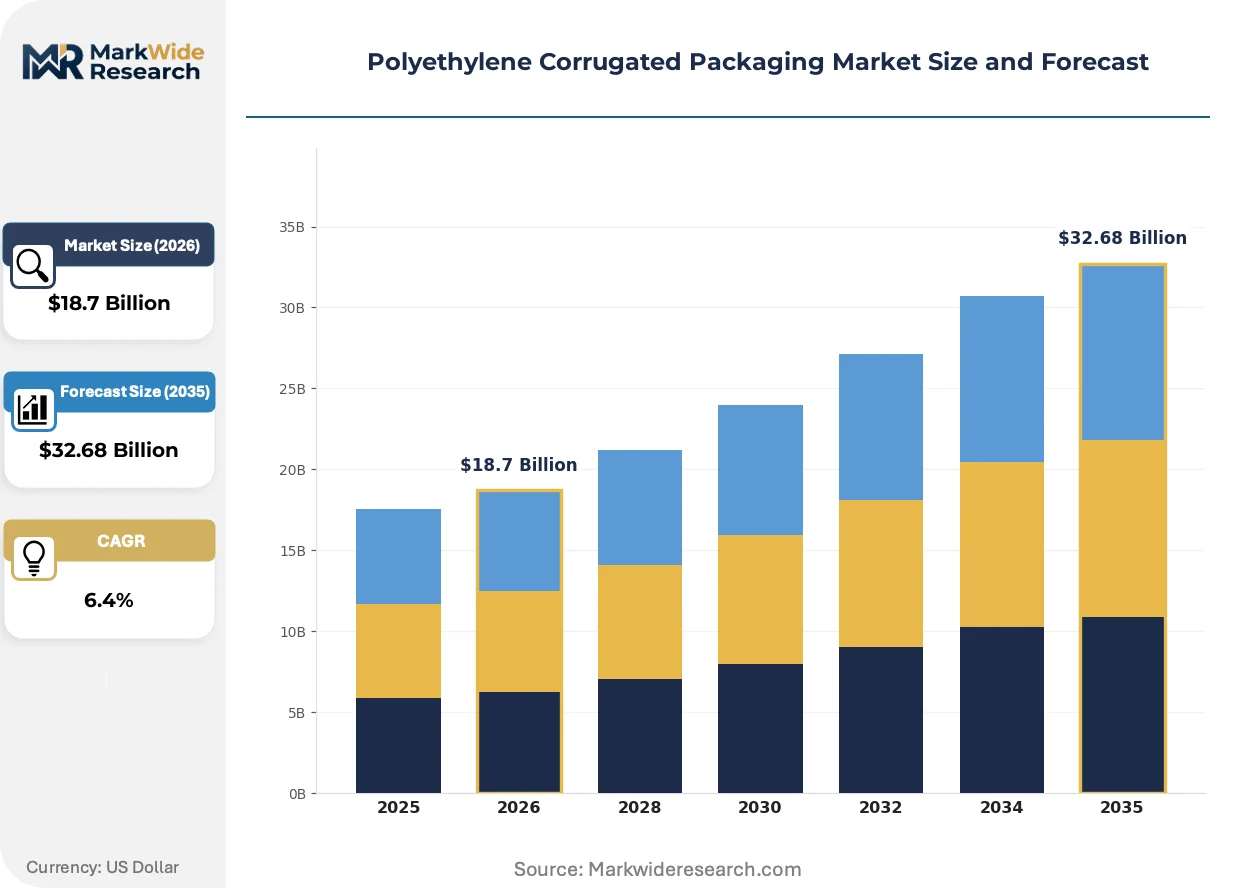
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are compressing formulation timelines for extruded sheet producers while simultaneously opening premium positioning for closed-loop supply networks. Recycled content thresholds now function as competitive moats rather than compliance checkboxes.
Growth Catalysts
- E-commerce fulfillment standardization:Third-party logistics operators in Germany's industrial corridor are mandating returnable totes for automotive parts distribution, creating captive demand for high-cycle-life containers.
- REACH additive reformulation:Restrictions on legacy UV stabilizers and colorants are accelerating adoption of bio-based alternatives that meet both compliance and performance specifications.
- ISO 18606 recyclability certification:Retailers with European recycling infrastructure are awarding exclusive supply contracts to certified producers, locking in volume commitments through 2030.
Market Restraints
- HDPE resin price volatility:Feedstock cost swings tied to naphtha cracking economics compress extrusion margins and deter long-term capacity commitments.
- German automotive supply concentration:Overreliance on Stuttgart-Munich corridor demand creates geographic vulnerability to single-sector downturns.
- Foam substitution persistence:Expanded polystyrene retains cost advantage in one-way protective applications where return logistics are uneconomical.
Strategic Opportunities
- Pharmaceutical cold chain expansion:Washdown-compatible trays for temperature-controlled distribution represent underpenetrated premium segment with 40% gross margin potential.
- Electronics custom insert adoption:Precision-cut corrugated dividers are capturing share from molded pulp in semiconductor shipping applications.
- Extended producer responsibility frameworks:France's Citeo and Germany's Der Grüne Punkt are creating funded collection infrastructure that reduces post-consumer reprocessing costs.
Industry Challenges
- Extrusion die engineering scarcity:Profile design expertise for multi-wall flute structures is concentrated among retiring specialists with limited knowledge transfer.
- FDA food-contact certification timelines:Migration testing protocols for recycled content formulations extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyethylene Corrugated Packaging Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Sheets, Trays, Dividers End Use Industry: Food & Beverage, Electronics, Pharmaceuticals, Consumer Goods Design Type: Flat, Foldable, Rigid, Custom Thickness: 3mm, 5mm, 7mm, 10mm |
| Companies Covered | DS Smith, Smurfit Kappa, Amcor, Sealed Air, Mondi, Pregis, NEFAB, Coroplast, Universal Package, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyethylene Corrugated Packaging Market Evolving Landscape
Active coextrusion barrier technologies and digital print integration are redefining value capture in protective packaging. Material science advances now enable functional performance previously reserved for multi-material laminates.
Multi-layer barrier coextrusion is displacing conventional single-polymer sheets in moisture-sensitive electronics applications. Tier-one semiconductor shippers in South Korea and Taiwan are specifying oxygen transmission rates below 0.5 cc/m²/day, forcing extruders to adopt ethylene vinyl alcohol interlayers. This capability compression is marginalizing commodity producers without captive film lamination assets.
REACH Annex XVII restrictions on phthalate plasticizers are compelling reformulation of flexible connecting elements in reusable tote systems. German automotive logistics operators now require third-party certification of additive compliance before contract renewal. Suppliers with pre-validated material libraries are capturing specification authority earlier in buyer decision cycles.
Direct-to-sheet digital printing is compressing minimum order quantities and lead times for branded retail packaging. E-commerce fulfillment networks in the Netherlands and Belgium are adopting lot-size-one customization for seasonal campaigns, displacing pre-printed corrugate with on-demand production. This shift favors extruders with inline print stations over conventional screen-printing subcontractors.
Polyethylene Corrugated Packaging Market Segmentation
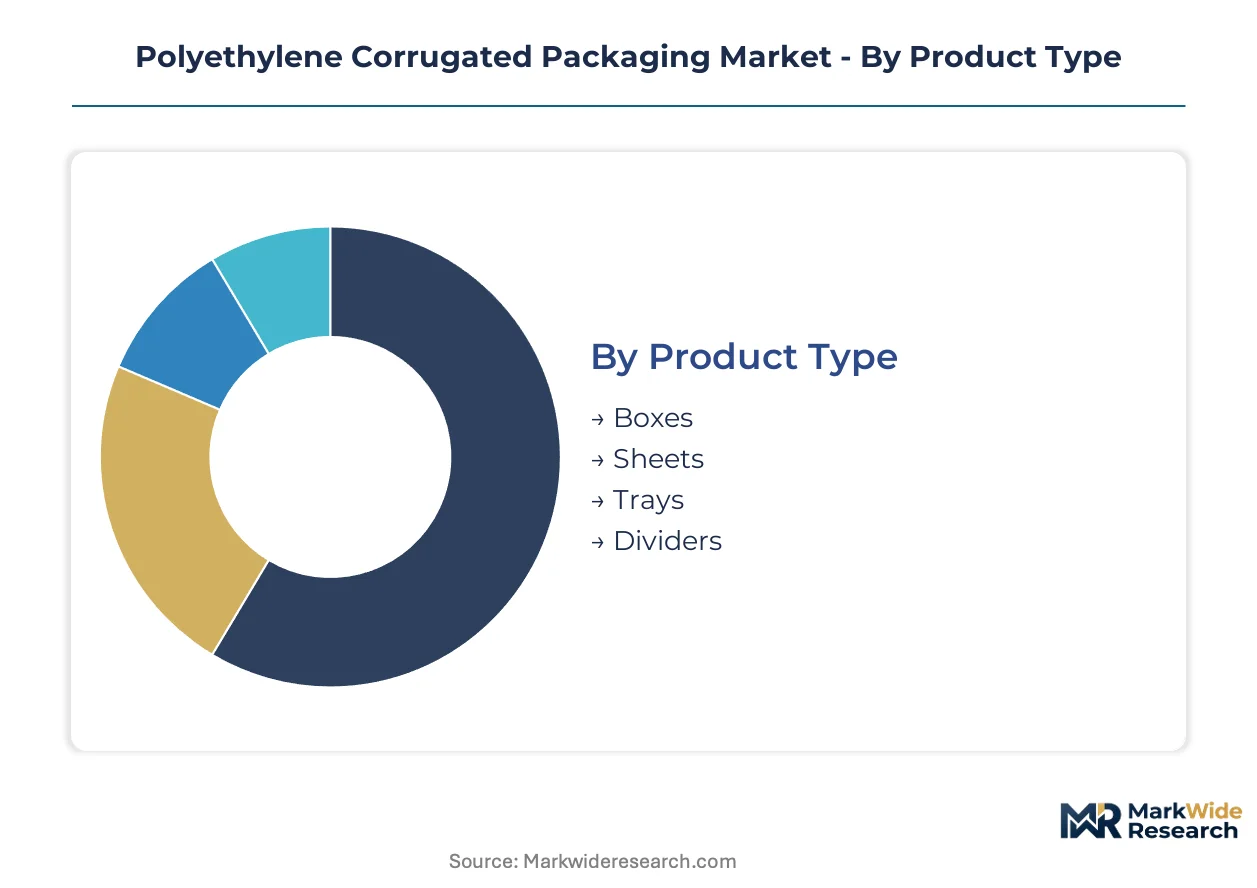
Segmentation in polyethylene corrugated packaging reveals how resin formulation, flute geometry, and end-use durability requirements fragment both procurement patterns and margin structures. Buyers in automotive logistics and pharmaceutical cold chains operate under fundamentally different total-cost-of-ownership calculations than commodity e-commerce fulfillment operators.
Product Type:
Premium positioning concentrates in returnable systems with cycle-life guarantees above 500 rotations, while single-use protective applications compete primarily on unit cost.
- Boxes:Extruded twin-wall containers with integrated stacking features dominate captive pool programs for German automotive parts distributors. Stuttgart-Munich corridor logistics operators mandate ISO 18606-certified boxes with RFID tracking compatibility for closed-loop supply networks.
- Sheets:Flat corrugated panels serve as layer pads and pallet slip sheets in high-velocity distribution centers. Demand from Netherlands e-commerce fulfillment networks is accelerating adoption of direct-to-sheet digital printing for lot-size-one seasonal campaigns.
- Trays:Washdown-compatible formats with dimensional stability specifications command pharmaceutical cold chain positioning.
- Dividers:Precision-cut inserts are displacing molded pulp in semiconductor shipping applications where static control and moisture resistance converge.
The dominant share belongs to Boxes, while Sheets is closing the gap fastest.
End Use Industry:
Regulatory intensity and damage-cost exposure determine willingness to pay for performance-graded formulations across vertical applications.
- Food & Beverage:FDA food-contact certification requirements extend product launch cycles for recycled-content formulations. Migration testing protocols and extended producer responsibility frameworks in France and Germany are reshaping supplier qualification criteria.
- Electronics:Tier-one semiconductor shippers in South Korea and Taiwan specify oxygen transmission rates below 0.5 cc/m²/day, forcing extruders toward multi-layer barrier coextrusion with ethylene vinyl alcohol interlayers.
- Pharmaceuticals:Temperature-controlled distribution networks require trays with washdown compatibility and dimensional stability across freeze-thaw cycles.
- Consumer Goods:Branded retail packaging drives direct-to-sheet digital printing adoption for seasonal campaign flexibility.
Electronics commands the steepest expansion trajectory as barrier specifications tighten, though Food & Beverage retains volume leadership through replenishment-cycle ubiquity.
Design Type:
Engineering complexity and tooling amortization create tiered margin pools that separate custom specification work from catalog standard formats.
- Flat:Unformed sheet stock serves as raw material for downstream converting operations and direct-cut applications.
- Foldable:Score-line integration enables flat-ship efficiency with on-site assembly, reducing return logistics costs in reusable tote networks.
- Rigid:Fixed-geometry containers with reinforced corners target high-cycle-life applications in automotive parts distribution.
- Custom:Application-specific engineering with captive die design captures specification authority early in buyer decision cycles.
Foldable formats hold the largest installed base, yet Custom design is gaining share fastest as semiconductor and pharmaceutical shippers tighten performance specifications.
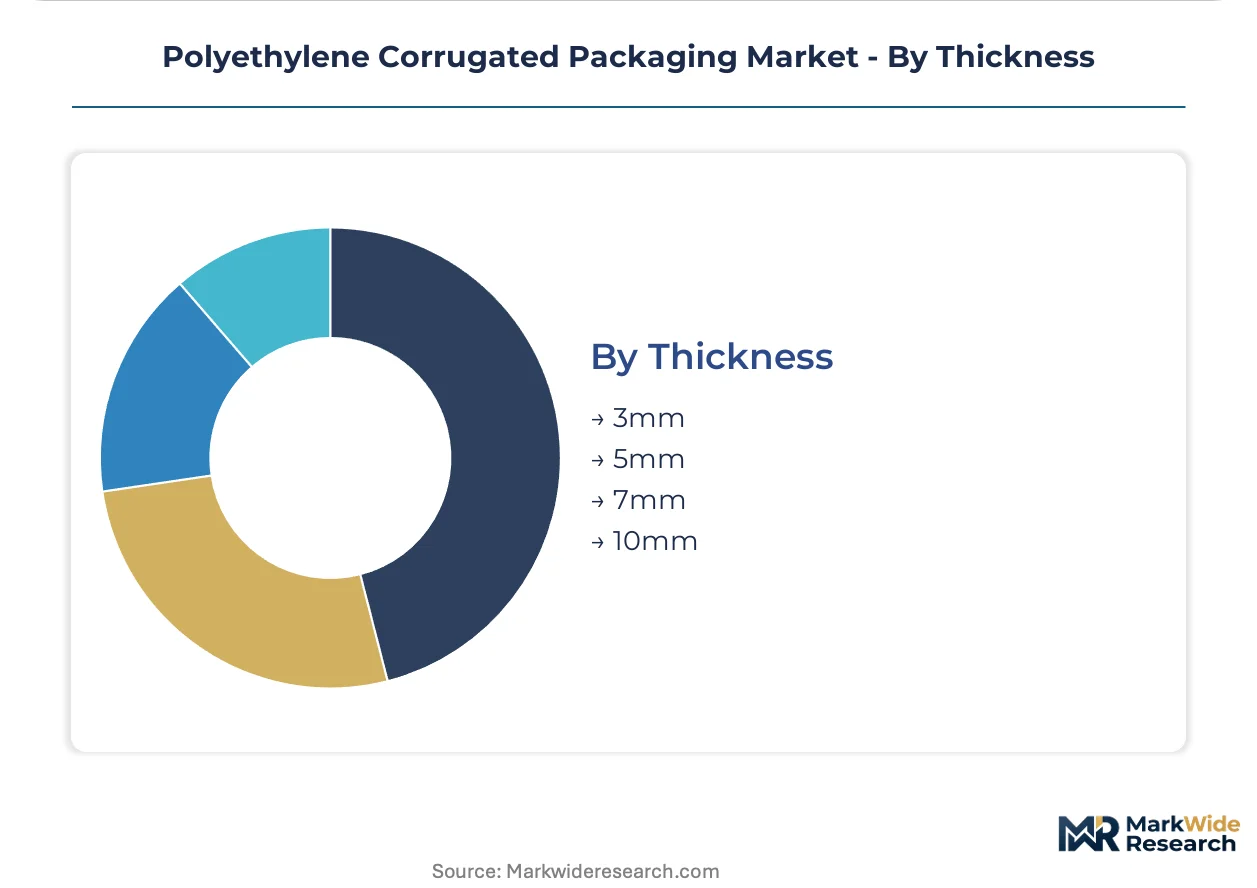
Thickness:
Material intensity and structural load-bearing capacity scale non-linearly with flute height, creating distinct cost-performance tradeoffs across handling scenarios.
- 3mm:Lightweight single-trip protective layers for consumer goods and document shipping applications.
- 5mm:General-purpose workhorse specification balancing stack strength and material efficiency in e-commerce fulfillment.
- 7mm:Reinforced grade for medium-duty returnable systems with 200-500 cycle life targets in industrial distribution.
- 10mm:Heavy-duty structural grade for automotive powertrain components and pharmaceutical palletized loads requiring maximum impact absorption.
5mm thickness dominates current procurement volumes, while 7mm formats are climbing the fastest as returnable system adoption accelerates across European logistics networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive logistics operators in Germany's industrial corridor and semiconductor shippers across East Asia dominate procurement volumes for high-durability polyethylene corrugated systems. E-commerce fulfillment networks in the Netherlands and Belgium are accelerating demand for digitally printed, lot-size-one customization capabilities.
Germany
Stuttgart-Munich corridor distributors mandate ISO 18606-certified returnable totes with RFID tracking for closed-loop automotive parts networks. REACH Annex XVII restrictions on legacy additives compel reformulation of UV stabilizers before contract renewals. Bavarian logistics hubs are consolidating supplier qualification around pre-validated bio-based material libraries.
United States
FDA food-contact certification requirements extend launch cycles for recycled-content formulations serving temperature-sensitive distribution. EPA recycled content guidelines under the National Recycling Strategy interact with state-level extended producer responsibility proposals. Midwest automotive assembly plants are adopting captive pool programs for powertrain component shipping.
Netherlands
E-commerce fulfillment operators specify direct-to-sheet digital printing for seasonal campaign flexibility at lot-size-one minimums. EU Packaging and Packaging Waste Regulation mandates compress formulation timelines while opening premium positioning for closed-loop supply networks. Rotterdam-Antwerp distribution corridors are displacing pre-printed corrugate with on-demand production.
South Korea
Tier-one semiconductor shippers specify oxygen transmission rates below 0.5 cc/m²/day, forcing extruders toward multi-layer barrier coextrusion with ethylene vinyl alcohol interlayers. The country's national chemical regulator enforces migration testing protocols for electronics-grade packaging materials. Busan-Ulsan manufacturing clusters are integrating active barrier technologies into moisture-sensitive component shipping.
China
Domestic e-commerce platforms drive volume demand for 5mm general-purpose containers balancing stack strength and material efficiency. GB standards for packaging recyclability interact with provincial extended producer responsibility pilots. Yangtze River Delta converting operations are expanding capacity for precision-cut corrugated dividers displacing molded pulp in electronics applications.
Polyethylene Corrugated Packaging Market Competitive Landscape
Player mix skews toward integrated packaging conglomerates with captive recycling infrastructure and specialized extrusion houses serving regional automotive clusters. Consolidation pressure intensifies as ISO 18606 certification becomes a competitive moat rather than a compliance checkbox. Three archetypes dominate: European closed-loop operators leveraging continent-wide collection networks, Asian barrier-technology specialists serving semiconductor logistics, and North American food-contact certified producers navigating FDA migration protocols. Dominant competitive moves include strategic partnerships with third-party logistics operators for captive tote pool management and technology licensing agreements for multi-layer coextrusion capabilities.
Within the integrated conglomerate tier, DS Smith and Smurfit Kappa occupy positions anchored by continent-spanning recycling infrastructure and paper-plastics integration. Amcor represents the advanced-technology archetype through its positioning in barrier coextrusion applications. These three companies exemplify how certification authority and material science capabilities are concentrating specification influence among producers with validated compliance libraries and captive film lamination assets.
| Leading Market Players |
|---|
| DS Smith |
| Smurfit Kappa |
| Amcor |
| Sealed Air |
| Mondi |
| Pregis |
| NEFAB |
| Coroplast |
| Universal Package |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts with naphtha-indexed resin clauses lock in both HDPE supply access and margin visibility for extruders serving German automotive logistics networks. These structures transfer feedstock volatility risk downstream while securing volume commitments through ISO 18606 certification renewal cycles.
Pricing Analysis
Cost-plus contracts with monthly naphtha indexation dominate procurement between extruders and resin suppliers across the European market. Price differentiation separates ISO 18606-certified premium grades from uncertified commodity sheet, with certification investment amortized across multi-year automotive supply agreements. Pricing pressure stems from HDPE resin volatility tied to cracking economics, compressing extrusion margins for non-integrated producers. Commodity e-commerce fulfillment operators exhibit highest price sensitivity, while pharmaceutical cold chain buyers prioritize washdown compatibility and dimensional stability over unit cost.
Supply Chain Analysis
Germany and China anchor extruded sheet production, with Germany specializing in high-cycle-life returnable systems and China dominating 5mm general-purpose container output. Raw material dependencies center on HDPE resin from naphtha cracking, ethylene vinyl alcohol interlayers for barrier grades, and bio-based UV stabilizers for REACH compliance. Supply chain risk concentrates in single-source vulnerability for EVOH interlayer supply from Asian petrochemical complexes. Distribution runs through captive pool programs managed by third-party logistics operators in the Stuttgart-Munich corridor and direct-to-converter shipments in the Yangtze River Delta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Closed-loop packaging economics are shifting toward platform-based interoperability, with RFID-tracked tote pools creating ecosystem lock-in that favors incumbent scale players over point-product competitors.
For Market Incumbents: Consolidate specification authority by acquiring regional extrusion houses with captive die design expertise, as retiring specialists create knowledge transfer gaps. Deepen backward integration into post-consumer HDPE collection infrastructure to secure recycled content thresholds under EU Packaging and Packaging Waste Regulation mandates. Prioritize certification investment in ISO 18606 and FDA food-contact libraries to extend contract renewal timelines. For New Entrants and Emerging Players: Precision-cut corrugated divider services for semiconductor shippers represent an under-served niche where barrier coextrusion requirements have marginalised commodity producers. Target South Korean and Taiwanese electronics manufacturers with oxygen transmission specifications below 0.5 cc/m²/day, where incumbent capacity constraints create qualification windows. Lead with application-specific engineering partnerships rather than catalog standard formats to capture specification authority early in buyer cycles. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap extruders with validated bio-based material libraries and pre-certified additive formulations, as REACH Annex XVII restrictions accelerate reformulation timelines. Long-term viability hinges on closed-loop supply network scale rather than commodity sheet volume. Watch for inflection signals in extended producer responsibility framework implementation across France, Germany, and Netherlands, which will restructure post-consumer collection economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycling Infrastructure | Captive HDPE supply secures EU recycled content thresholds and reduces feedstock cost volatility exposure. |
| Multi-Layer Barrier Coextrusion Licensing | Technology transfer agreements enable EVOH interlayer capability for semiconductor logistics specifications. |
| ISO 18606 Certification Investment | Third-party recyclability validation unlocks exclusive supply contracts with European retail closed-loop networks. |
| Direct-to-Sheet Digital Print Integration | Inline print stations capture lot-size-one demand from Netherlands e-commerce seasonal campaigns. |
| Captive Tote Pool Management Partnerships | Third-party logistics operator alliances lock in multi-year volume commitments for automotive returnable systems. |
Research Methodology
Operator-level perspectives from extrusion plant managers, automotive parts procurement leads, pharmaceutical cold chain logistics directors, and third-party logistics operators anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade data, EU Packaging and Packaging Waste Regulation filings, ECHA REACH registration databases, and SEC disclosures from integrated packaging conglomerates. Bottom-up volume modeling across product types, thickness grades, and end-use industries triangulated against top-down macroeconomic drivers.
Sensitivity analysis tested forecast robustness across resin price volatility scenarios, regulatory timeline acceleration, and substitution elasticity from expanded polystyrene alternatives. Segmentation dimensions modeled include product type, thickness specification, end-use industry vertical, design format, and regional regulatory cluster. CAGRs were derived from regression analysis of historical volume trajectories and elasticity-adjusted demand projections. Industry-specific inputs incorporated naphtha cracking margin cycles, REACH Annex XVII restriction implementation schedules, and e-commerce fulfillment network expansion rates.
Underlying assumptions cover sustained EU regulatory enforcement, stable naphtha-to-polyethylene margin structures, and incremental rather than disruptive substitution from alternative protective materials, with deviation risk concentrated in feedstock cost spikes and accelerated extended producer responsibility fee implementation. Recalibration cycles align with material shifts in EU Packaging and Packaging Waste Regulation secondary legislation and major automotive platform standardization announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Asia Pacific Plastic Bottles Market
Plastic Packaging
India Plastic Bottles Market
Plastic Packaging
North America Plastic Bottles Market
Plastic Packaging
PET Preforms Market
Plastic Packaging
United Arab Emirates Plastic Packaging Market
Plastic Packaging
United States Plastic Packaging Films Market
Plastic Packaging
Latin America Single-Use Plastic Packaging Market
Plastic Packaging
Canada Plastic Bottles Market
Plastic Packaging
Plastic Water Storage Tank Market
Plastic Packaging
Malaysia and Thailand Thermoformed Plastic Market
Plastic Packaging
Spain Plastic Bottles Market
Plastic Packaging
Plastic Carboy Market
Plastic Packaging
Plastic Lab Totes Market
Plastic Packaging
GCC Plastic Packaging Market
Plastic Packaging
Polypropylene Corrugated Packaging Market
Plastic Packaging
Low Density Polyethylene (LDPE) Packaging Market