
 Beverage Cartoners Market | 2026-2036
Beverage Cartoners Market Size, Share, and Industry Trends Forecast 2026-2036
Beverage Cartoners Market Analysis
Soft drink manufacturers is restructuring procurement priorities across emerging markets, shifting capital toward aseptic carton lines that extend shelf life without refrigeration. Tetra Pak leverages its integrated processing and packaging systems to dominate turnkey line installations. SIG Combibloc competes through standardized machine platforms that reduce changeover times for mid-sized juice producers.
Beverage cartoners are automated machines that erect, fill, and seal paperboard-based containers at speeds typically ranging from 6,000 to 24,000 units per hour, serving the primary purpose of protecting liquid contents from contamination while enabling efficient shelf-stable distribution. Aseptic cartoners anchor the highest-margin segment due to sterilization complexity and barrier-laminate precision requirements. Tray cartoners occupy a mature, cost-driven niche where dairy producers prioritize throughput over package differentiation.
FDA food-contact regulations in the United States and EU Green Deal packaging directives collectively shape material compliance timelines, with both frameworks pushing manufacturers toward fiber-based and recyclable laminate structures. ISO hygiene standards for food machinery further constrain machine design choices in export-oriented markets. Stakeholders must monitor how rapidly evolving extended producer responsibility rules in the European Union and state-level packaging laws across the United States alter total cost of ownership calculations for carton material selections.
Market Dynamics
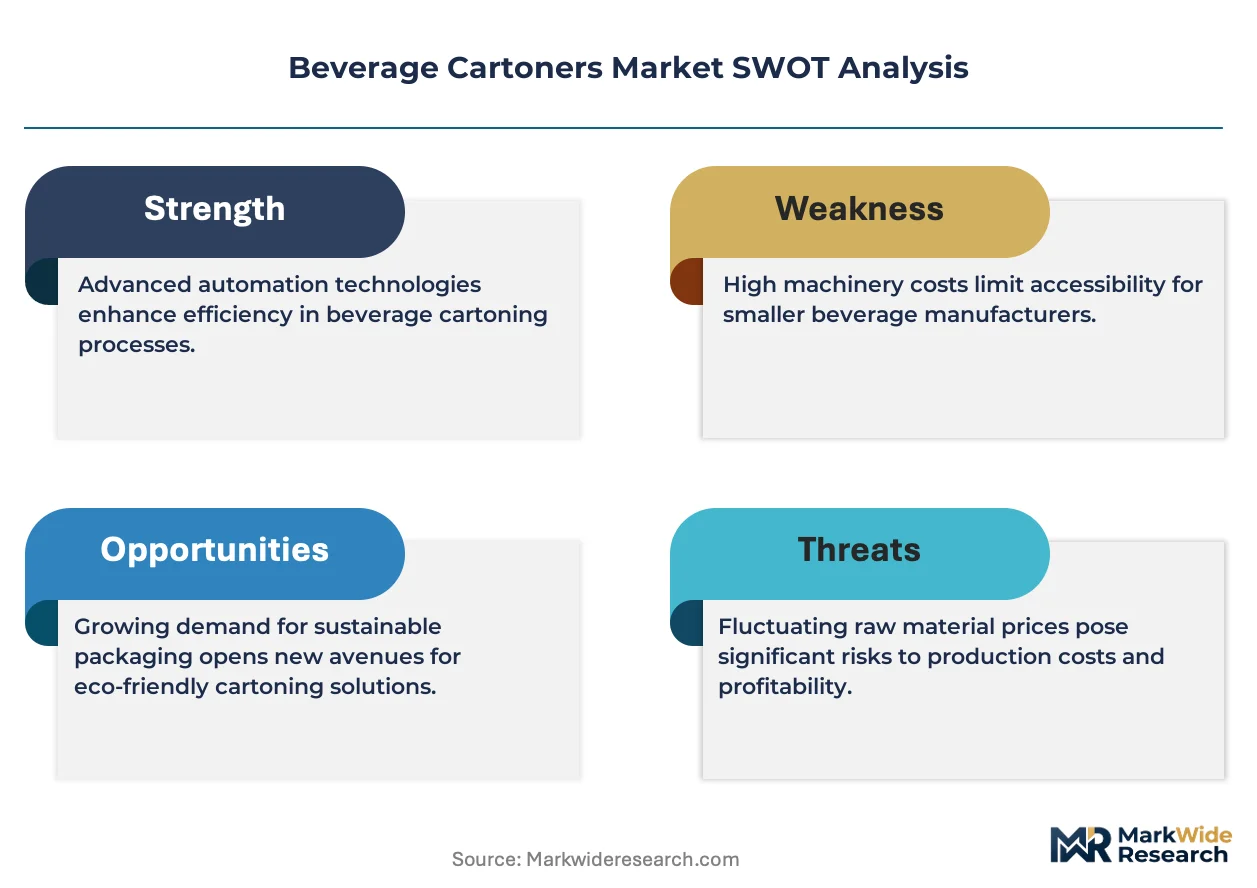
Aseptic filling complexity is concentrating procurement decisions among fewer turnkey integrators capable of delivering sterilization, barrier lamination, and high-speed sealing in unified platforms. This technical bundling reshapes how dairy and juice producers evaluate total cost of ownership across multi-year equipment lifecycles.
Growth Catalysts
- EU Green Deal packaging mandates:Extended producer responsibility rules in the European Union accelerate fiber-based laminate transitions, forcing beverage bottlers to replace plastic-heavy formats with recyclable paperboard structures ahead of compliance deadlines.
- Southeast Asia dairy expansion:Indonesia and Vietnam bottlers upgrade filling lines to meet cold-chain-free distribution requirements, driving aseptic carton adoption for ambient-stable milk and yogurt drinks.
- Barrier-laminate precision gains:Advances in aluminum oxide and ethylene vinyl alcohol co-extrusion enable thinner protective layers without shelf-life degradation, reducing material costs for high-volume juice producers.
Market Restraints
- Aluminum and polymer input volatility:Aseptic carton multilayer structures depend on aluminum foil and petroleum-derived plastics, exposing converters to commodity price swings that compress margin predictability.
- Equipment supplier concentration:Turnkey aseptic line installation capability clusters among a handful of European and Japanese integrators, creating bottleneck risk for emerging market bottlers seeking localized service support.
- Tray carton commoditization:Mature gable-top and open-tray formats face substitution pressure from PET and rHDPE bottles in cost-sensitive dairy segments where refrigeration infrastructure is adequate.
Strategic Opportunities
- India ambient dairy penetration:Ultra-high-temperature milk remains underpenetrated relative to total liquid dairy consumption, creating white space for aseptic carton lines as FSSAI hygiene standards tighten.
- Plant-based beverage diversification:Oat, almond, and soy milk producers require aseptic filling to achieve shelf-stable distribution without preservatives, opening new end-use verticals beyond traditional dairy.
- Digital line integration:Convergence of machine vision inspection with predictive maintenance software enables remote monitoring of seal integrity and sterilization performance, reducing unplanned downtime for multi-shift operations.
Industry Challenges
- Aseptic validation timelines:FDA and EFSA food-contact certification for new laminate structures requires 18-24 month testing cycles, delaying commercialization of sustainable material innovations.
- Electromechanical skill scarcity:Servo-driven carton forming and high-speed filling lines demand technicians proficient in both mechanical alignment and programmable logic controller programming, a combination scarce in emerging manufacturing clusters.
- Legacy wet-end integration:Retrofitting aseptic cartoners into existing beverage processing halls requires reconfiguring CIP systems and sterile buffer tanks, complicating brownfield deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beverage Cartoners Market |
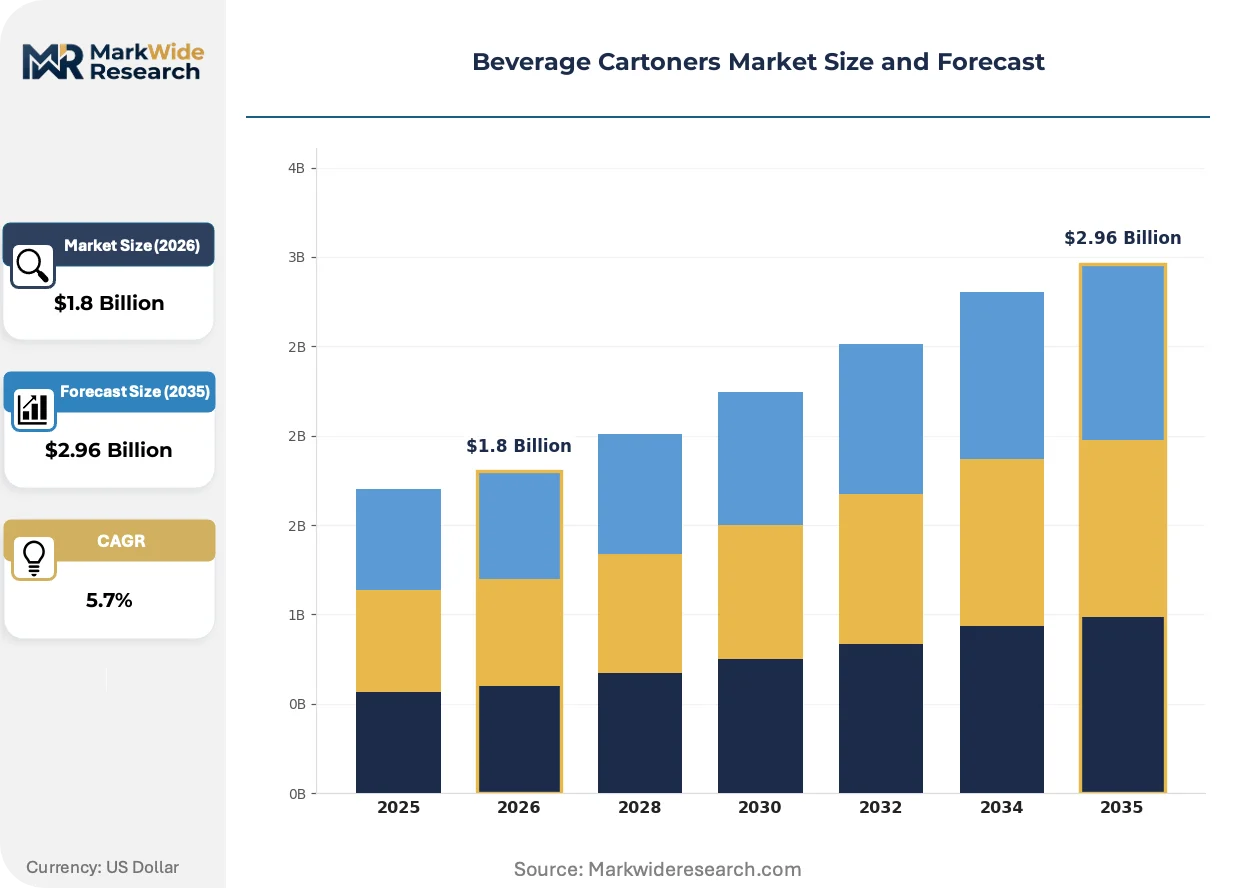
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aseptic Cartoners, Tray Cartoners, Vertical Cartoners, Inline Cartoners End User: Soft Drink Manufacturers, Juice Producers, Dairy Producers, Alcoholic Beverage Companies Material: Cardboard, Plastic, Glass, Composite Packaging Type: Carton, Tetra Pak, Pouch, Bottle |
| Companies Covered | Tetra Pak, SIG Combibloc, Elopak, Greatview Aseptic Packaging, Visy, Mondi, WestRock, Stora Enso, Pactiv Evergreen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverage Cartoners Market Emerging Trajectories
Digitalization of packaging lines is compressing changeover intervals and enabling lot-level traceability from filler to palletizer. This shift rewards machinery investments that unify mechanical performance with data architecture.
Ultrasonic sealing technology is consolidating position as the dominant alternative to hot-air and induction methods for aseptic carton closure. Dairy processors in Germany and the Netherlands adopt ultrasonic systems to eliminate thermal deformation of thin barrier laminates. The technology is consolidating market share among premium ambient milk producers seeking reduced energy consumption and hermetic seal reliability at 24,000 units per hour.
EU Green Deal packaging directives now mandate minimum recycled content thresholds and recyclability-by-design standards for beverage containers sold in member states. Carton converters must requalify adhesive and print chemistries under ECHA substance restrictions while maintaining FDA compliance for export-bound production. Aseptic juice cartons face the steepest reformulation burden due to multilayer complexity and food-contact safety requirements.
Buying committees at multinational beverage groups now consolidate capital expenditure authority at regional hubs rather than granting plant-level procurement autonomy. This centralization compresses vendor evaluation cycles and elevates total cost of ownership models over upfront equipment pricing. The pattern is most visible in Latin America and Southeast Asia where bottling groups standardize on single machinery platforms across multiple country operations.
Beverage Cartoners Market Segmentation
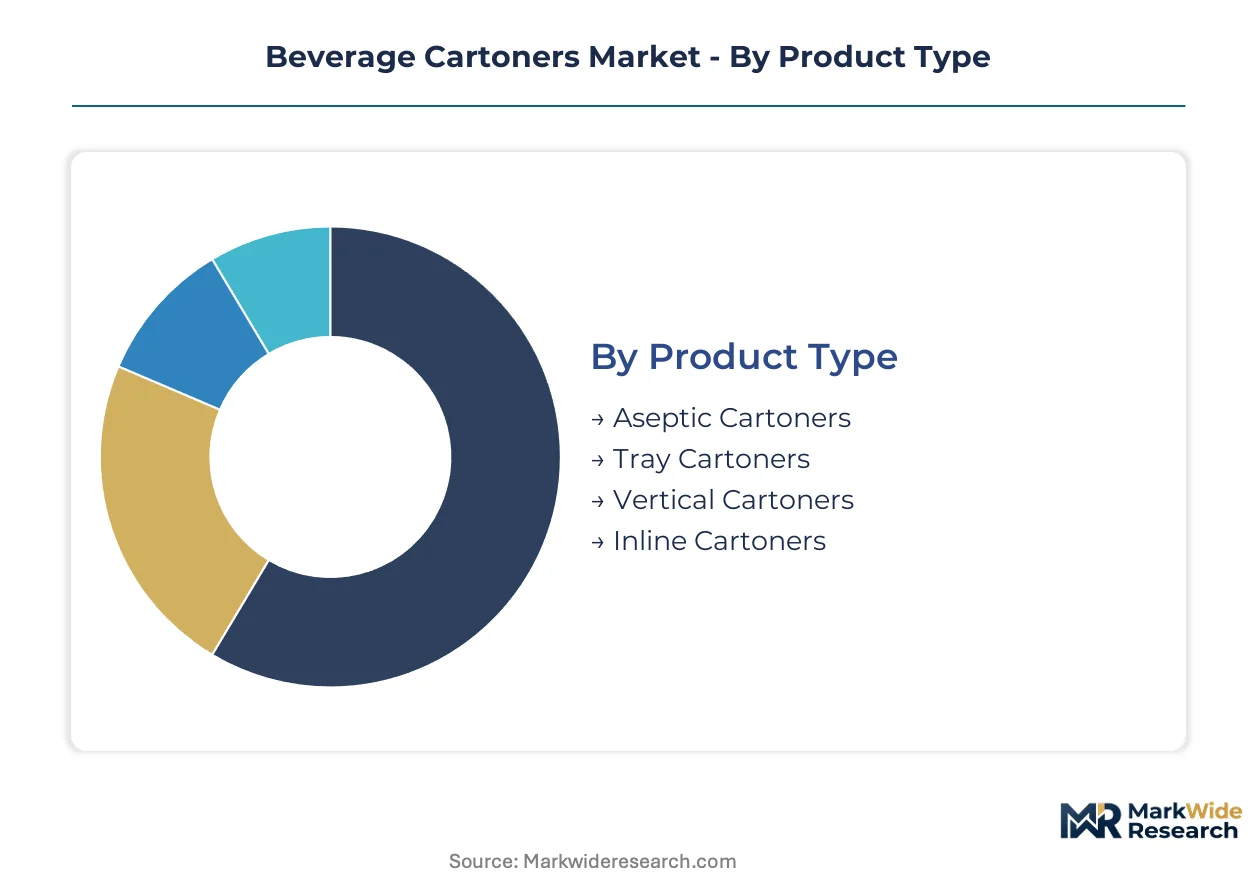
Segmentation in beverage cartoners reveals how capital allocation, regulatory pressure, and shelf-life requirements split demand across machine architectures. Procurement committees weigh sterilization complexity against throughput economics when matching equipment categories to product portfolios.
Product Type:
Aseptic cartoners command the steepest upfront capital outlays due to integrated sterilization tunnels, hydrogen peroxide vapor systems, and barrier-laminate precision modules that push installed costs well above conventional lines.
- Aseptic Cartoners:These systems combine hydrogen peroxide sterilization, sterile air overpressure chambers, and multilayer laminate sealing to achieve commercial sterility without refrigeration. Dairy processors in Indonesia and Vietnam prioritize these lines for ambient distribution networks where cold-chain infrastructure remains fragmented.
- Tray Cartoners:Mechanical forming and glue-sealing operations dominate this mature category, with servo-driven pick-and-place mechanisms handling open-tray formats at lower capital intensity. German dairy cooperatives favor tray systems for refrigerated short-shelf-life milk where barrier properties matter less than throughput speed.
- Vertical Cartoners:Gravity-fed filling from top-mounted nozzles suits viscous products and single-serve formats with minimal foaming.
- Inline Cartoners:Linear conveyor arrangements reduce footprint for brownfield retrofit installations where floor space constraints limit rotary system deployment.
Aseptic cartoners absorb the bulk of installed capacity; vertical cartoners are expanding most quickly in single-serve beverage applications.
End User:
Customer type determines service intensity and line configuration complexity, with dairy and juice operations driving the most demanding technical specifications.
- Soft Drink Manufacturers:Carbonated and still beverage bottlers require high-speed filling heads capable of handling CO₂ retention and minimal product degradation. Bottlers in Thailand and the Philippines are converting PET lines to aseptic carton formats to meet EU export requirements for fiber-based packaging.
- Juice Producers:Acidic, pulp-containing, and enzyme-sensitive formulations demand precise temperature control and oxygen exclusion during filling. Brazilian orange juice processors invest in aseptic carton upgrades to extend export shelf life without preservative addition.
- Dairy Producers:Milk, yogurt drinks, and lactose-free variants dominate ambient dairy carton demand across Southeast Asian markets.
- Alcoholic Beverage Companies:Wine and ready-to-drink cocktail cartons remain niche, constrained by oxygen permeability limits and consumer acceptance barriers.
Dairy producers absorb the bulk of installed capacity; juice producers are climbing the fastest as aseptic technology penetrates tropical fruit processing.
Material:
Substrate selection shapes machine tooling, sealing temperature profiles, and compliance pathways across regulatory jurisdictions.
- Cardboard:Fiber-based substrates with polyethylene and aluminum oxide barrier layers constitute the dominant sustainable packaging trajectory. EU Green Deal mandates are forcing rapid qualification of recyclable laminate structures under EFSA food-contact protocols.
- Plastic:PET and PP cartons serve cost-sensitive segments where refrigeration infrastructure supports shorter shelf-life distribution.
- Glass:Premium positioning and inert barrier properties sustain limited carton-adjacent applications in specialty alcoholic beverages.
- Composite:Multilayer structures combining fiber, polymer, and metallized films balance shelf-life extension with material reduction goals.
Cardboard absorbs the bulk of installed capacity; composite materials are gaining share fastest as converters optimize barrier-to-weight ratios.
Packaging Type:
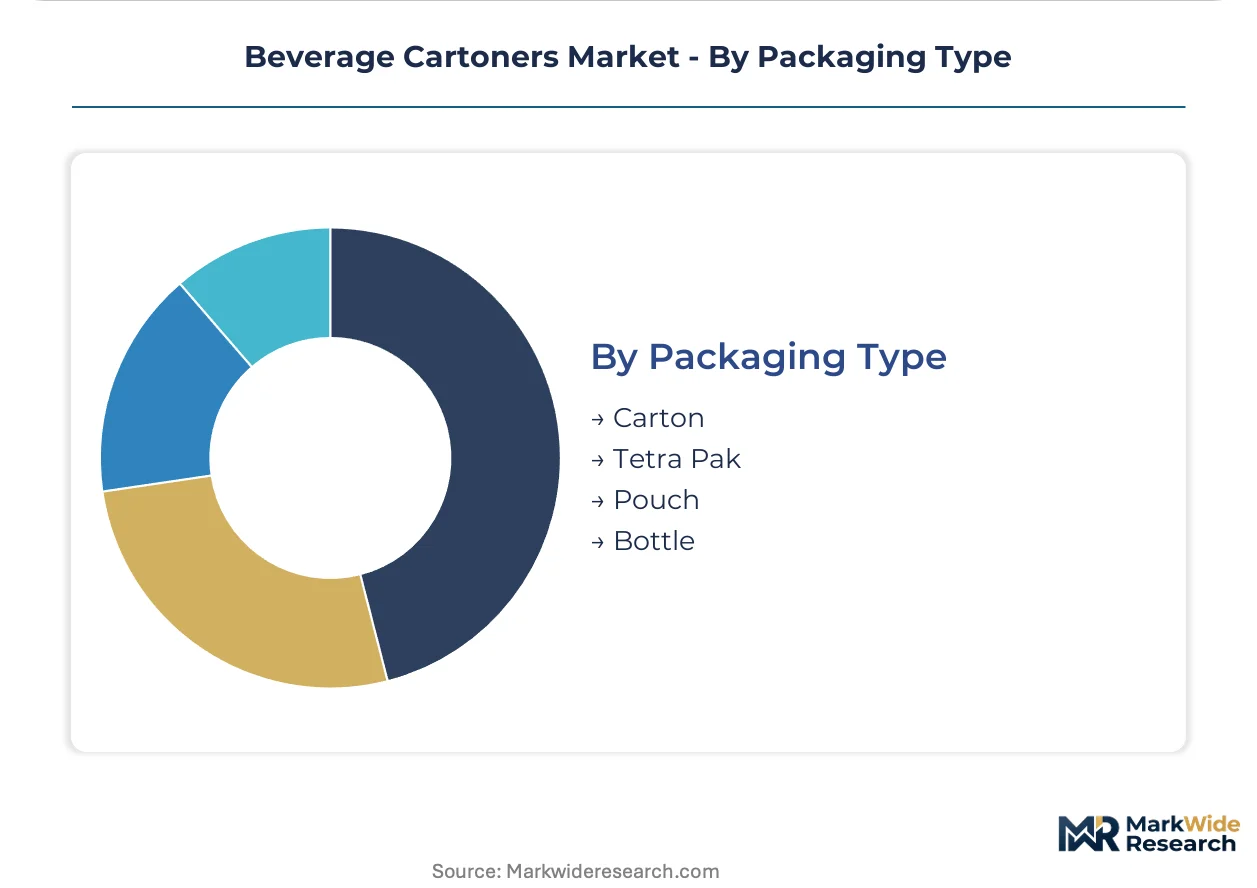
Format geometry determines machine forming mechanisms, sealing technology, and downstream handling compatibility.
- Carton:Gable-top and rectangular prism formats dominate liquid dairy and juice applications with established filling line ecosystems. Standardized blank sizes enable rapid changeover across product variants in multi-SKU operations.
- Tetra Pak:Proprietary brick and wedge geometries with integrated straw-hole punching require dedicated forming mandrels and sealing stations.
- Pouch:Flexible spouted and fitment-equipped formats compete for single-serve beverage share with lower material intensity than rigid cartons.
- Bottle:Carton-sleeved and paper-wrapped bottle alternatives bridge fiber-based sustainability claims with familiar handling ergonomics.
Carton formats absorb the bulk of installed capacity; bottle alternatives are expanding most quickly as brands seek differentiation in premium water and functional beverages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's Batam Free Trade Zone and Vietnam's Chu Lai Open Economic Zone concentrate aseptic carton line investments as Southeast Asian dairy processors seek tariff-advantaged import channels for European and Japanese machinery.
United States
FDA food-contact regulations for multilayer laminates drive 18-24 month validation cycles for sustainable material transitions. The EPA's evolving extended producer responsibility guidance shapes state-level packaging mandates in California and New York. Chicago and Dallas manufacturing corridors host dairy cooperatives retrofitting tray carton lines for fiber-based formats ahead of compliance deadlines.
Germany
EU Green Deal packaging directives enforce minimum recycled content thresholds for beverage containers sold across member states. ECHA substance restrictions force requalification of adhesive and print chemistries under REACH protocols. Bavarian dairy processors adopt ultrasonic sealing systems to eliminate thermal deformation of thin barrier laminates at 24,000 units per hour.
China
NMPA food-contact safety standards and MIIT industrial upgrading programs accelerate domestic aseptic carton machinery development. Yangtze River Delta clusters in Shanghai and Jiangsu province concentrate turnkey line installations for juice processors serving export markets. Local fabricators compete on standardized platforms that reduce changeover times for mid-sized producers.
India
FSSAI hygiene standard tightening creates white space for aseptic carton penetration in ultra-high-temperature milk segments. The PLI scheme for food processing machinery supports domestic manufacturing capacity expansion. Maharashtra and Gujarat dairy cooperatives upgrade filling lines to achieve ambient-stable distribution without cold-chain infrastructure.
Brazil
ANVISA food-contact certification requirements align with FDA export protocols for orange juice processors serving North American markets. São Paulo state bottling groups centralize capital expenditure authority at regional hubs rather than granting plant-level procurement autonomy. Southeastern industrial corridors concentrate aseptic carton upgrades to extend export shelf life without preservative addition.
Beverage Cartoners Market Vendor Landscape
Top-tier vendors anchor turnkey aseptic line integration, while mid-tier specialists compete on standardized machine platforms and regional service proximity. The market structure concentrates procurement decisions among European and Japanese integrators capable of delivering sterilization, barrier lamination, and high-speed sealing in unified platforms. Two strategic archetypes dominate: integrated processing-packaging system providers and component-specialized machinery fabricators. Competitive moves center on geographic licensing agreements and backward integration into barrier laminate material supply.
Among Switzerland-based packaging system providers, Tetra Pak occupies a position exemplifying integrated processing and packaging dominance. SIG Combibloc, a Germany-based limited company, represents the standardized platform archetype competing on changeover efficiency. Chinese fabricators including Greatview Aseptic Packaging sit within the regional service-specialist tier, anchoring cost-competitive positioning for emerging market dairy and juice processors.
| Leading Market Players |
|---|
| Tetra Pak |
| SIG Combibloc |
| Elopak |
| Greatview Aseptic Packaging |
| Visy |
| Mondi |
| WestRock |
| Stora Enso |
| Pactiv Evergreen |
| Others |
Supply Flow & Price Mechanics
Ultrasonic sealing adoption across Bavarian dairy processors is compressing energy costs per unit while concentrating procurement leverage among turnkey integrators capable of delivering sterilization, barrier lamination, and high-speed sealing in unified platforms. This technical bundling simultaneously reshapes total cost of ownership calculations and supplier consolidation dynamics across European and Southeast Asian bottling corridors.
Pricing Analysis
Short lead-time premiums dominate aseptic carton line procurement, with Indonesian and Vietnamese bottlers paying substantial markups for accelerated delivery of hydrogen peroxide sterilization modules against EU Green Deal compliance deadlines. Three-tier pricing structure across premium, standard, and economy levels stratifies by sterilization complexity, after-sales service bundling, and geographic proximity of technical support. Pricing pressure stems from aluminum and petroleum-derived polymer input volatility compressing margin predictability for multilayer laminate converters. Mid-sized juice producers in Brazil and Thailand exhibit highest price sensitivity, prioritizing standardized machine platforms over integrated processing-packaging systems.
Supply Chain Analysis
India's PLI scheme for food processing machinery and China's MIIT industrial upgrading programs are reshaping sourcing patterns, compelling European and Japanese integrators to establish localized assembly or licensing partnerships. Component fabrication concentrates in Germany, Switzerland, and Japan for precision sterilization tunnels; barrier laminate supply draws from Swedish and Finnish fiber specialists. Single-source vulnerability persists for hydrogen peroxide vapor generation systems and servo-driven forming mandrels. Distribution runs through regional machinery hubs in Shanghai, Mumbai, and São Paulo before final installation at bottling facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Beverage cartoners market evolution tracks a vertical-integration race, with machinery vendors pursuing captive supply of barrier laminate materials to secure margin control against commodity input volatility.
For Market Incumbents: Hedge against Chinese fabricator encroachment by deepening backward integration into aluminum oxide co-extrusion capabilities and ultrasonic sealing module production. Prioritize certification investment for EU Green Deal recyclability-by-design compliance ahead of ECHA substance restriction timelines. Anchor capacity addition in India's PLI-subsidized manufacturing corridors to offset emerging market service proximity disadvantages. For New Entrants and Emerging Players: Capture white space in India's ultra-high-temperature milk segment where FSSAI hygiene standard tightening outpaces installed aseptic line capacity. Target plant-based beverage diversification verticals—oat, almond, and soy milk producers requiring preservative-free shelf-stable distribution. Deploy digital line integration capabilities as primary go-to-market angle, converging machine vision inspection with predictive maintenance software to differentiate against legacy European incumbents. For Investors and Strategic Acquirers: Exit pathways concentrate in regional service-specialist acquisitions by tier-one integrators seeking emerging market proximity. Five-to-ten year viability hinges on barrier-laminate material science capabilities and sterile-air overpressure chamber engineering depth. Monitor EFSA food-contact certification timeline compression as inflection indicator—accelerated validation cycles would unlock sustainable material innovation premiums and reshape competitive moats.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barrier Laminate Supply | Captures margin from aluminum oxide co-extrusion and reduces polymer input volatility exposure. |
| Digital Line Integration Platform Launch | Enables remote seal integrity monitoring and predictive maintenance for multi-shift Southeast Asian operations. |
| EU Green Deal Compliance Certification Program | Accelerates EFSA food-contact approval for recyclable fiber-based structures ahead of mandate deadlines. |
| Geographic Licensing Agreement Expansion | Establishes localized assembly partnerships in India's PLI corridors and Vietnam's Chu Lai Open Economic Zone. |
| Ultrasonic Sealing Technology Scale-Up | Eliminates thermal deformation risks for thin barrier laminates at 24,000 units per hour in German dairy processing. |
Methodological Framework
Document review covered EU Green Deal packaging directives, FDA food-contact regulations, FSSAI hygiene standards, and ECHA substance restriction databases, complemented by interviews with dairy processing executives, juice producer procurement leads, machinery OEM technical directors, and barrier laminate converter R&D heads. Secondary validation drew from SEC filings of packaging system providers, MIIT industrial upgrading program disclosures, and customs data on aseptic line imports into Indonesia and Vietnam. Bottom-up equipment installation tracking and top-down beverage production volume modeling were triangulated against regional regulatory compliance timelines.
Installed base projections and revenue estimates across the modeling period reflect segmentation by machine architecture (aseptic, tray, vertical, inline), end-user category (dairy, juice, soft drink, plant-based), and material substrate trajectory. CAGRs were derived from historical capital expenditure patterns, regulatory mandate enforcement schedules, and cold-chain infrastructure development curves. Key inputs included hydrogen peroxide sterilization system deployment rates, ultrasonic sealing adoption curves in German and Dutch processing facilities, and PLI scheme uptake among Indian dairy cooperatives.
The model holds under sustained EU Green Deal enforcement and stable aluminum-polymer input cost corridors; deviation in EFSA food-contact certification timelines or acute commodity price spikes would shift machinery procurement prioritization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Pick and Place Carton Packers Market
Cartons
GCC Folding Carton Market
Cartons
Africa Folding Carton Market
Cartons
Carton Sealer Market
Cartons
Global Printed Cartons Market
Cartons
Global Crash Lock Bottom Cartons Market
Cartons
Box and Carton Overwrapping Machines Market
Cartons
North America Corrugated Boxes Market
Cartons
Metallized PET Cartons Market
Cartons
Metallized Folding Cartons Market
Cartons
Carton Serialization Machine Market
Cartons
Asia Pacific Folding Carton Market
Cartons
Tuck Top Box Market
Cartons
Child-Resistant Carton Box Market
Cartons
Twist Opening Cartons Market
Cartons
Carton Display Market