
 Box and Carton Overwrapping Machines Market | 2026-2036
Box and Carton Overwrapping Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Box and Carton Overwrapping Machines Market Outlook
China's manufacturing belt is tilting toward higher-speed overwrapping systems as export-oriented consumer goods producers expand capacity. IMA Group leverages its pharmaceutical packaging heritage to anchor premium automated lines across European and Asian installations. Sollas Holland BV specializes in compact, modular overwrapping units that compete effectively in mid-volume cosmetics and electronics segments. Coesia Group controls an extensive portfolio of end-of-line packaging technologies that extends its influence from film feeding through final palletisation.
Box and carton overwrapping machines apply a tight, transparent or printed film layer around pre-formed rigid containers using heat-sealing, cold-sealing, or adhesive-based methods, typically operating at speeds between 30 and 600 cycles per minute depending on format complexity and automation level. These systems serve primarily to tamper-evidence, moisture-barrier, and aesthetically finish products for retail shelf presentation. Automatically operated systems dominate installed base value due to pharmaceutical and food safety throughput requirements, while integrated systems represent the fastest-growing configuration as converters seek to collapse multiple packaging stations into single-footprint lines. Heat sealing technology leads technology adoption in regulated industries demanding hermetic seal integrity, whereas shrink wrapping maintains strong positions in mass-market beverage and personal care applications where material cost minimisation shapes procurement decisions.
FDA cGMP guidelines and EU MDR traceability requirements shape validation protocols and machine qualification documentation for pharmaceutical overwrapping installations in the United States and Europe. China's SAMR enforces GB standards for food contact materials that directly influence film specification and sealing temperature parameter windows in domestic equipment design. Japan's METI energy efficiency benchmarks now filter into equipment sourcing criteria across East Asian packaging operations. Stakeholders must monitor how evolving extended producer responsibility frameworks in the European Union and pending state-level packaging legislation in the United States redirect material choices from conventional polyolefins toward certified recyclable or paper-based barrier structures.
Market Dynamics
Heat-sealing technology upgrades across European pharmaceutical lines are compressing replacement cycles as contract packagers race to meet EU Falsified Medicines Directive serialisation mandates before enforcement deadlines tighten.
Growth Catalysts
- EU Falsified Medicines Directive:Serialisation mandates in Germany and Switzerland force automated overwrapping retrofits across contract packaging facilities, pulling forward capital expenditure timelines.
- Automotive export logistics:The Stuttgart-to-Nuremberg industrial corridor concentrates OEM demand for tamper-evident film wrapping of precision components bound for Asian markets.
- Heat-sealing parameter control:Advanced temperature modulation systems enable hermetic seal validation required for moisture-sensitive pharmaceutical formulations.
Market Restraints
- Polyolefin film cost volatility:Crude-linked resin prices swing packaging material budgets, compressing margin visibility for machinery purchasers with long depreciation horizons.
- German integrator concentration:End-of-line system sourcing clusters around a narrow corridor of Stuttgart-Nuremberg OEMs, creating bottleneck risk for spare parts and service response.
- Cold-sealing adhesive limitations:Pressure-sensitive alternatives fail to achieve the hermetic integrity demanded by EU MDR traceability protocols for sterile barrier applications.
Strategic Opportunities
- China's manufacturing belt expansion:Export-oriented consumer goods producers in Guangdong and Zhejiang provinces seek higher-speed systems to match throughput targets for North American retail contracts.
- Extended Producer Responsibility frameworks:EU Green Deal packaging rules redirect film specifications toward certified recyclable structures, opening retrofit demand for heat-sealing systems with broader temperature windows.
- Paper-based barrier convergence:Fiber-based packaging films hybridizing with conventional substrates create white space for sealing equipment makers capable of dual-parameter control.
Industry Challenges
- Validation documentation burden:FDA cGMP qualification protocols for pharmaceutical installations extend commissioning timelines and strain technical writing capacity at mid-tier machinery builders.
- Legacy line integration friction:Brownfield sites in mature European markets struggle to synchronize new overwrapping stations with existing cartoners and checkweighers without full line reconstruction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Box and Carton Overwrapping Machines Market |
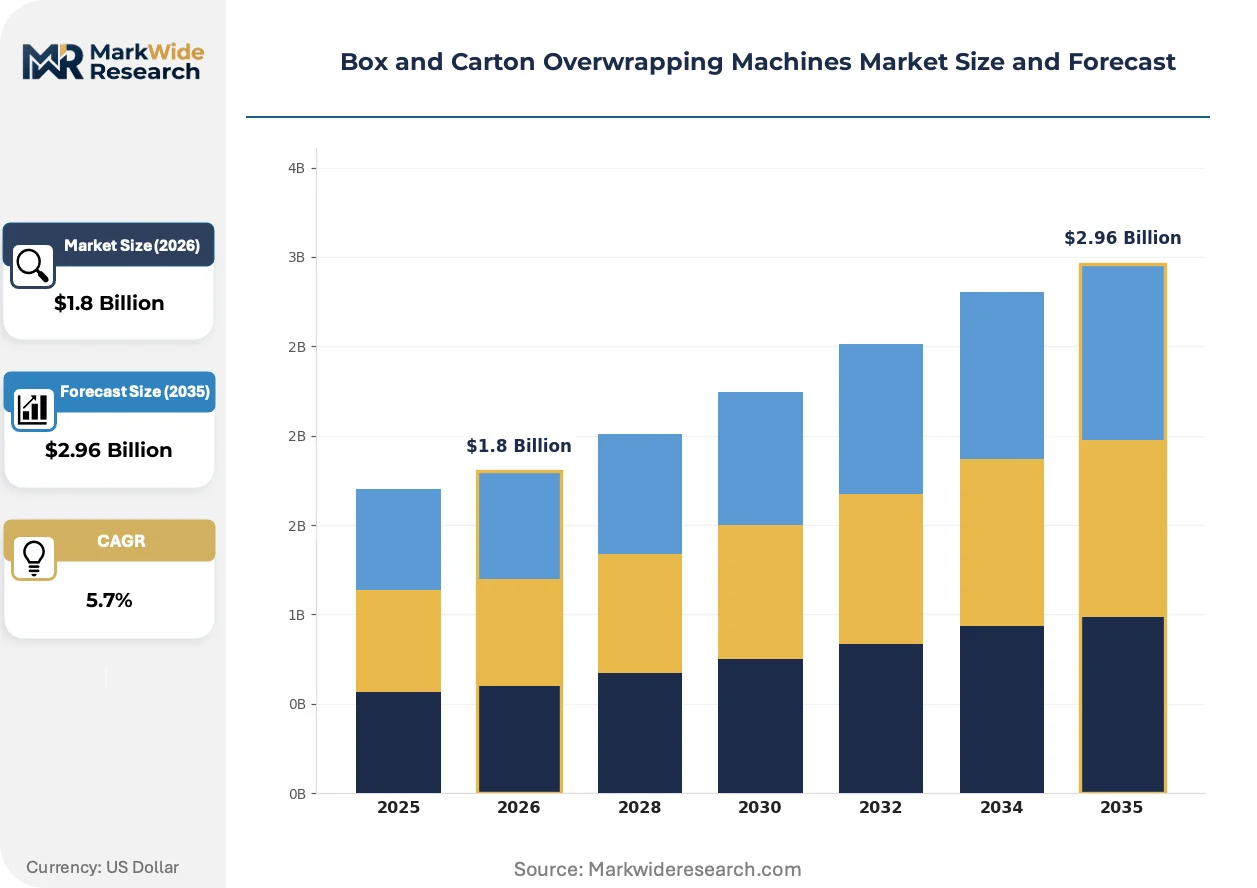
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatically Operated, Semi-Automatically Operated, Manual, Integrated Systems End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Technology: Heat Sealing, Cold Sealing, Adhesive-Based, Shrink Wrapping Packaging Material: Plastic Films, Paperboard, Polyethylene, BOPP |
| Companies Covered | IMA Group, Marchesini Group, CAM Packaging, Sollas Holland BV, Uhlmann Packaging, Coesia Group, Syntegon, Krones AG, Multivac Sepp Haggenmüller, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Box and Carton Overwrapping Machines Market Strategic Shifts
Film substrate engineering and sealing control systems are converging to enable hermetic performance from non-polyolefin materials, while regulatory pressure on traceability accelerates automation depth across pharmaceutical installations.
Heat-sealing control architecture is hybridizing with machine vision feedback loops to enable real-time seal integrity verification without destructive testing. Pharmaceutical contract packagers in Germany and Switzerland are deploying these systems at pilot scale ahead of full EU MDR enforcement. The technology is compressing the validation burden for sterile barrier applications while raising the technical floor for competitive participation.
EU MDR traceability requirements are mandating machine-level data logging that feeds directly into batch record systems, eliminating manual transcription steps. This regulatory pressure forces machinery builders to embed OPC-UA connectivity and audit-trail functionality as standard rather than optional features. Pharmaceutical overwrapping installations in the German industrial corridor are experiencing the most acute compliance-driven retrofit activity.
Service unbundling from hardware procurement is accelerating as end-users seek to decouple capital budgets from maintenance obligations. Mid-volume cosmetics and electronics producers are driving this shift, preferring performance-based contracts with guaranteed uptime metrics over traditional warranty structures. This behavioral change is most visible among export-oriented manufacturers in China's coastal provinces seeking operational expenditure predictability.
Box and Carton Overwrapping Machines Market Segmentation
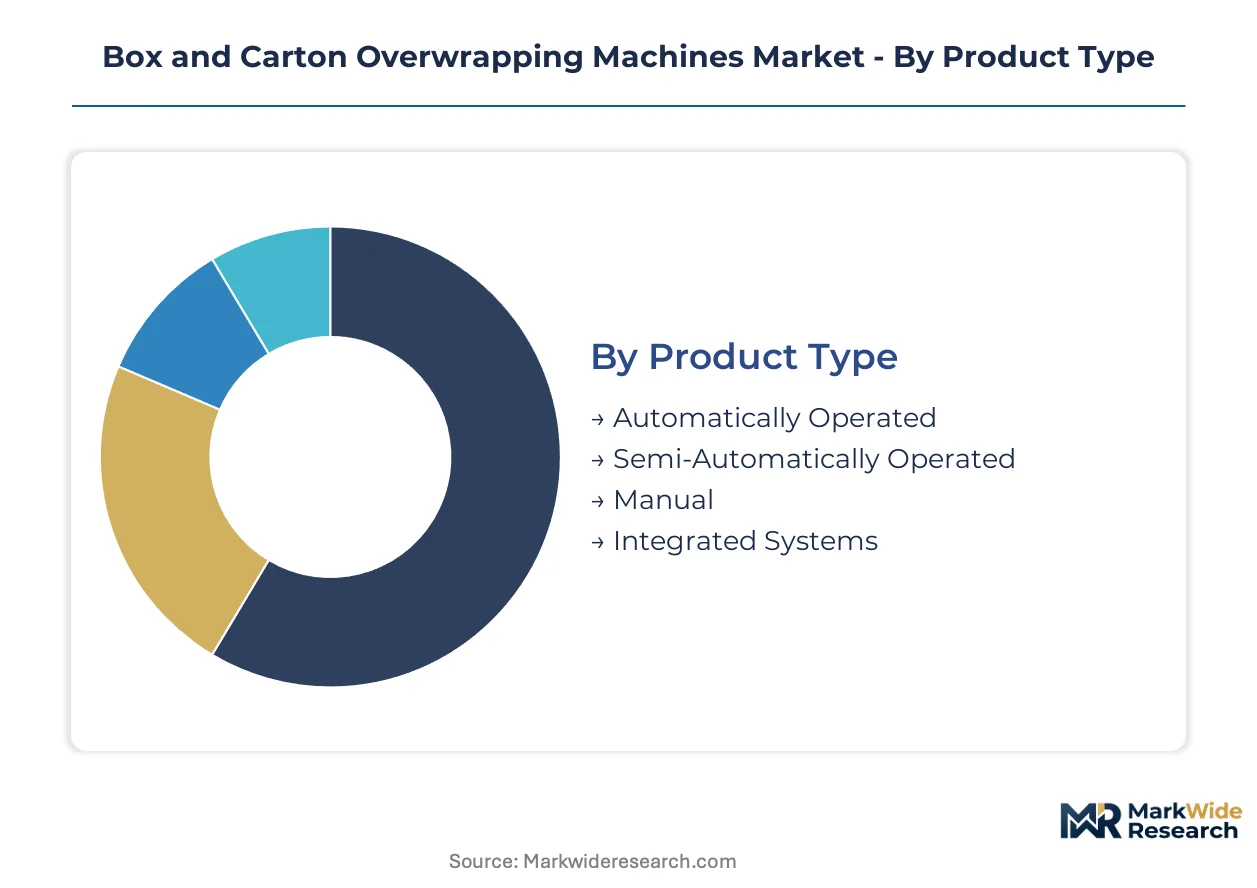
Overwrapping machine segmentation reveals how automation depth, regulatory pressure, and substrate innovation create divergent investment profiles across pharmaceutical, food, and consumer goods packaging lines. Each dimension carries distinct technical and commercial logic that shapes procurement decisions and vendor positioning.
Product Type:
Automation intensity spans from manual bench units for artisan producers to fully integrated lines that collapse cartoning, overwrapping, and palletizing into single-footprint systems.
- Automatically Operated:These systems execute film feeding, cutting, sealing, and discharge without operator intervention, typically achieving 200-600 cycles per minute. Pharmaceutical contract packagers in Germany and Switzerland prioritize these units to satisfy EU MDR traceability mandates requiring machine-level data logging and audit trails.
- Integrated Systems:Configurations merge overwrapping stations with upstream cartoners and downstream checkweighers through centralized control architecture. Export-oriented manufacturers in China's Guangdong province deploy these to minimize labor touchpoints and meet throughput guarantees for North American retail contracts.
- Semi-Automatically Operated:Hybrid designs requiring manual loading but automated sealing cycles serve mid-volume cosmetics producers seeking flexibility across SKU proliferation without full automation capital commitment.
- Manual:Bench-mounted units dominate artisan food producers and small-batch electronics assemblers where changeover frequency and format variability outweigh speed requirements.
Established volume favors Automatically Operated; emerging adoption favors Integrated Systems.
End User:
Demand concentration tracks regulatory stringency and export exposure, with pharmaceutical and food safety requirements pulling technology upgrades while cosmetics and electronics prioritize operational flexibility.
- Pharmaceuticals:Moisture-sensitive formulations and sterile barrier requirements drive hermetic seal validation protocols. FDA cGMP guidelines and EU MDR traceability mandates compress replacement cycles as contract packagers retrofit for serialization compliance.
- Food & Beverage:Shelf-life extension and tamper-evidence dominate procurement criteria. China's SAMR enforces GB standards for food contact materials that directly constrain film specification and sealing temperature windows in domestic equipment design.
- Cosmetics:Premium presentation and SKU proliferation favor modular systems with rapid changeover capability. Mid-volume producers increasingly prefer performance-based service contracts over traditional capital procurement.
- Electronics:Anti-static film handling and precision component protection shape specifications for semiconductor and automotive parts packaging.
Regulatory compliance concentrates investment in Pharmaceuticals; operational flexibility drives Cosmetics adoption.
Technology:
Sealing methodology selection hinges on hermetic integrity requirements, energy cost structures, and material compatibility with evolving substrate portfolios.
- Heat Sealing:Temperature-controlled jaw systems deliver hermetic seals essential for pharmaceutical moisture barriers and extended shelf-life food applications. Advanced parameter control with machine vision feedback enables real-time integrity verification without destructive testing.
- Shrink Wrapping:Heat tunnel systems using polyolefin films maintain strong positions in mass-market beverage and personal care where material cost minimization shapes procurement decisions.
- Cold Sealing:Pressure-sensitive adhesive methods suit temperature-sensitive substrates but fail to achieve hermetic integrity required for EU MDR sterile barrier protocols.
- Adhesive-Based:Hot-melt and cold-glue systems serve paperboard-focused applications where fiber-based barrier films are displacing conventional plastics.
Regulated industries anchor Heat Sealing demand; cost-driven segments sustain Shrink Wrapping volume.
Packaging Material:
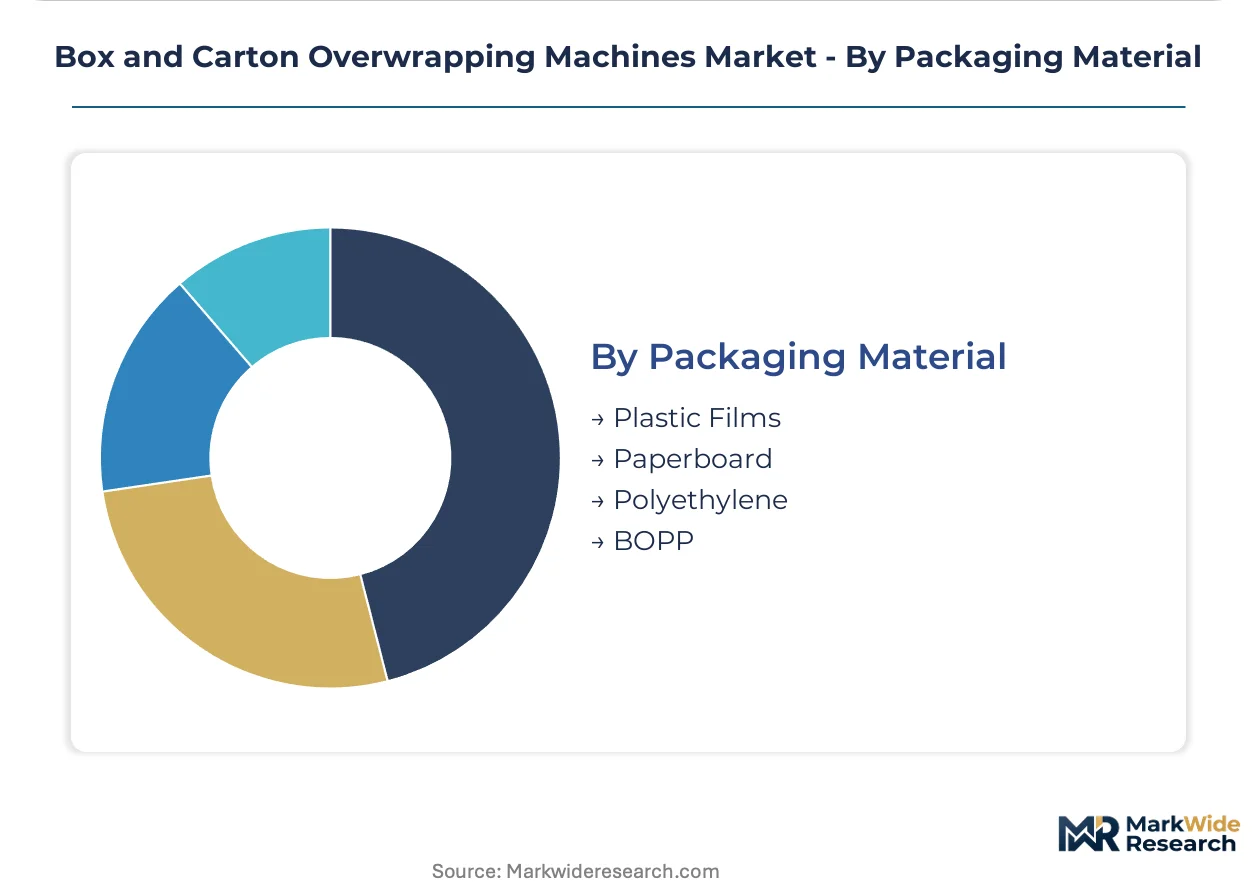
Substrate selection increasingly reflects extended producer responsibility frameworks and recyclability mandates rather than pure performance optimization.
- Plastic Films:Conventional polyolefin structures face pressure from EU Green Deal packaging rules redirecting specifications toward certified recyclable alternatives.
- BOPP:Biaxially oriented polypropylene offers clarity and stiffness for retail presentation but requires heat-sealing systems with precise temperature windows.
- Polyethylene:Lower-density variants dominate cost-sensitive beverage and personal care applications where seal strength requirements are moderate.
- Paperboard:Fiber-based barrier structures hybridizing with conventional substrates create retrofit demand for sealing equipment capable of dual-parameter control.
Conventional polymers retain Plastic Films dominance; sustainability pressures accelerate Paperboard development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA serialization mandates and EU MDR traceability requirements anchor pharmaceutical overwrapping demand across Germany, Switzerland, and adjacent markets. Automotive export corridors and food safety regulations drive parallel investments in tamper-evident packaging systems.
Germany
Contract packagers in the Stuttgart-to-Nuremberg industrial corridor retrofit automated overwrapping lines to meet EU Falsified Medicines Directive deadlines. KBA automotive standards and export logistics requirements pull tamper-evident film wrapping for precision components bound for Asian markets. The Baden-Württemberg and Bavaria manufacturing belts concentrate OEM and integrator clusters around pharmaceutical and automotive packaging.
Switzerland
Swissmedic pharmaceutical regulations enforce sterile barrier validation protocols that compress machinery replacement cycles. Precision manufacturing heritage drives premium automated line adoption for moisture-sensitive formulations. The Basel-Zurich corridor hosts contract packaging facilities expanding capacity ahead of EU MDR full enforcement.
China
Export-oriented consumer goods producers in Guangdong and Zhejiang provinces deploy higher-speed overwrapping systems for North American retail contracts. SAMR GB standards for food contact materials constrain film specification and sealing temperature parameters in domestic equipment design. The Yangtze River Delta and Pearl River Delta manufacturing belts lead capacity expansion for electronics and cosmetics packaging.
United States
FDA cGMP guidelines shape validation protocols and machine qualification documentation for pharmaceutical overwrapping installations. State-level extended producer responsibility legislation redirects material choices toward recyclable film structures. The Midwest pharmaceutical corridor and Southeast automotive packaging hubs drive regional demand concentration.
Japan
METI energy efficiency benchmarks filter into equipment sourcing criteria across pharmaceutical and food packaging operations. PMDA traceability requirements align with EU MDR standards for export-oriented manufacturers. The Kanto and Kansai industrial regions concentrate precision machinery demand for moisture-barrier applications.
Box and Carton Overwrapping Machines Market Competitive Environment
Full-line integrators and specialized machinery builders split the market into distinct competitive spheres. European pharmaceutical heritage anchors premium automated system supply, while Asian fabricators compete on speed and footprint optimization. Three archetypes dominate: diversified packaging conglomerates with end-of-line portfolios, mid-cap specialists in modular compact units, and precision-engineering houses serving regulated industries. Competitive dynamics center on technology licensing partnerships and geographic expansion through distributor networks rather than outright consolidation.
Within the diversified conglomerate tier, IMA Group and Coesia Group occupy positions spanning film feeding through final palletization. Sollas Holland BV exemplifies the modular specialist archetype, competing in mid-volume cosmetics and electronics segments where rapid changeover capability commands premium positioning. These three anchors represent divergent strategic bets on automation depth versus operational flexibility.
| Leading Market Players |
|---|
| IMA Group |
| Marchesini Group |
| CAM Packaging |
| Sollas Holland BV |
| Uhlmann Packaging |
| Coesia Group |
| Syntegon |
| Krones AG |
| Multivac Sepp Haggenmüller |
| Others |
Value Chain & Pricing Dynamics
The Rhine-Alpine freight corridor's volatile container rates ripple through overwrapping machinery supply chains, compressing margins for European OEMs while amplifying price differentiation between Stuttgart-Nuremberg integrators and Asian fabricators. This logistics chokepoint concentrates supply-side bargaining power among heat-sealing component specialists who serve both pharmaceutical contract packagers and automotive export logistics clusters.
Pricing Analysis
Geographic price spreads between German precision-engineered systems and Chinese high-speed alternatives now exceed fifty percent at equivalent automation tiers. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth, with FDA-validated pharmaceutical lines commanding substantial premiums over food-grade equivalents. Pricing pressure stems from polyolefin film cost volatility linked to crude-linked resin swings. Mid-volume cosmetics producers exhibit highest price sensitivity, while Swiss pharmaceutical contract packagers prioritize hermetic seal validation over procurement cost.
Supply Chain Analysis
Contract manufacturing capacity for precision heat-sealing jaws and temperature control modules concentrates among specialized German and Swiss metalworking firms. Component sourcing draws from Italy for servo-drive systems, Japan for machine vision sensors, and Taiwan for control electronics. Raw material dependencies include specialty steel alloys, ceramic heating elements, and polyimide insulation films. Single-source vulnerability persists for hermetic seal validation equipment qualified under EU MDR protocols. Distribution runs through OEM direct sales for pharmaceutical lines and regional distributor networks for mid-volume cosmetics and electronics segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Box and carton overwrapping machinery sits in early-cycle expansion as EU MDR traceability mandates force retrofit waves across European pharmaceutical installations before enforcement deadlines tighten.
For Market Incumbents: Harden service contract penetration to lock recurring revenue against Asian speed competitors entering through Guangdong manufacturing belt expansion. Deepen backward integration into heat-sealing jaw production to defend margin position against specialty steel alloy cost volatility. Prioritize OPC-UA connectivity certification investment to maintain pharmaceutical qualification pipeline access. For New Entrants and Emerging Players: Modular retrofit kits for brownfield European pharmaceutical lines represent the most penetrable entry point, bypassing full-system validation burdens that favor established incumbents. China's export-oriented cosmetics producers seeking operational expenditure predictability offer second-tier opportunity through performance-based service contracts rather than capital sales. Target distributor partnerships in the Pearl River Delta manufacturing belt for initial geographic anchoring. For Investors and Strategic Acquirers: Precision-engineering houses with embedded pharmaceutical validation expertise and Swissmedic qualification track records offer strongest long-term viability through the regulatory compliance cycle. Monitor EU Green Deal packaging rule implementation timelines as inflection indicator for paper-based barrier film sealing equipment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Sealing Parameter Control Upgrade | Advanced temperature modulation enables real-time seal integrity verification for EU MDR sterile barrier compliance. |
| Backward Integration into Ceramic Heating Elements | Captive supply of precision components insulates margin from specialty materials cost volatility. |
| OPC-UA Connectivity Standardization | Embedded audit-trail functionality satisfies pharmaceutical batch record system integration mandates. |
| Paper-Based Barrier Film Capability Development | Dual-parameter control systems capture EU Green Deal-driven substrate transition demand. |
| Performance-Based Service Contract Expansion | Guaranteed uptime metrics align revenue model with mid-volume cosmetics producer preference shifts. |
Study Parameters
A standing panel of pharmaceutical packaging engineers, contract manufacturing operations directors, heat-sealing technology specialists, and aftermarket service heads provided ongoing calibration across primary interview rounds. Secondary validation drew from FDA cGMP guidance documents, EMA serialization mandate filings, SAMR GB standards publications, and METI energy efficiency benchmark disclosures. Bottom-up equipment shipment analysis triangulated against top-down pharmaceutical capital expenditure tracking.
Scenario-bracketing framed demand projections across automation intensity tiers, technology adoption curves, and regulatory compliance deadlines throughout the forecast period. Segmentation modeling spanned product type, end-user industry vertical, sealing technology methodology, and packaging material substrate evolution. CAGRs derived from unit economics analysis of replacement cycle compression and greenfield capacity expansion patterns. Forecast inputs incorporated EU MDR enforcement timeline scenarios and extended producer responsibility framework implementation trajectories.
Practitioners should monitor resin price volatility indices, EU MDR audit intensity trends, and paper-based barrier film qualification timelines for early signals of forecast revision necessity. Quarterly review of pharmaceutical contract packager capital expenditure announcements and SAMR food contact materials regulatory updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Carton Bottle Market
Cartons
XXL Packaging Market
Cartons
Global Aseptic Paper Packaging for Flat Top Carton Market
Cartons
Metallized PET Cartons Market
Cartons
Indonesia Folding Carton Packaging Market
Cartons
MET-PET Cartons Market
Cartons
Mailers Market
Cartons
Self - Adhesive Carton Window Patch Machine Market
Cartons
Digital Printed Cartons Market
Cartons
Folding Carton in Healthcare Market
Cartons
Global Beverage Carton Packaging Machinery Market
Cartons
Liquid Packaging Cartons Market
Cartons
Global Crash Lock Bottom Cartons Market
Cartons
Braille Cartons Packaging Market
Cartons
Carton Sealer Market
Cartons
Global Folding Carton Packaging Market