
 CINV Treatment Market | 2026-2036
CINV Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
CINV Treatment Market Outlook
Oncology infusion centers are broadening their antiemetic formularies beyond standard 5-HT3 blockade. Merck & Co., Inc. anchors its position through deep NK1 receptor antagonist expertise. Helsinn Holding S.A. specializes in supportive care oncology portfolios across European and North American channels. Heron Therapeutics, Inc. differentiates via extended-release injectable formulations that reduce administration burden in outpatient settings.
CINV treatment encompasses pharmaceutical interventions targeting chemotherapy-induced nausea and vomiting through modulation of neurokinin-1, serotonin 5-HT3, and corticosteroid pathways, with modern formulations emphasizing single-dose extended-release injectables to maintain therapeutic plasma concentrations over 72-120 hours. Oral aprepitant and ondansetron dominate current prescription volumes, yet subcutaneous administration routes are capturing faster expansion as homecare settings seek alternatives to intravenous infusion. The hospital end-user segment retains the largest revenue pool, though outpatient settings and homecare channels are deepening their share through reimbursement shifts toward ambulatory chemotherapy delivery.
The FDA governs new drug approvals and label expansions for antiemetic combinations, while the EMA's centralized marketing authorization process shapes commercial access across European Union member states. REACH and MDR frameworks in Europe impose escalating purity and device standards on combination drug-device products such as subcutaneous injectors. Stakeholders must monitor evolving biosimilar entry timelines for granisetron and ondansetron, as these will compress pricing power in commoditized segments while preserving premiums for novel extended-release mechanisms.
Market Dynamics
Subcutaneous extended-release injectables are compressing administration frequency from multi-day IV schedules to single-dose outpatient protocols, restructuring site-of-care economics and reimbursement flows across oncology networks.
Growth Catalysts
- FDA Label Expansions:Broadened indications for NK1 receptor antagonist combinations in highly emetogenic regimens are extending prophylactic coverage to patient populations previously managed with inferior 5-HT3 monotherapy.
- Homecare Infusion Migration:Payer pressure to reduce hospital day costs is accelerating ambulatory chemotherapy delivery, creating demand for self-administered antiemetic formulations that eliminate nursing supervision.
- Granisetron Transdermal Patches:Sustained-release dermal delivery systems are capturing patient preference in pediatric and needle-averse populations, expanding addressable volume beyond traditional IV-dependent cohorts.
Market Restraints
- API Concentration in India and China:Active pharmaceutical ingredient manufacturing for ondansetron and granisetron concentrates in South Asian and East Asian contract suppliers, exposing formulators to geopolitical disruption and export control volatility.
- REACH and MDR Compliance Burden:European device-drug combination regulations impose escalating purity documentation and post-market surveillance requirements on subcutaneous injector systems, extending time-to-market by 18-24 months.
- Oral Generic Substitution:Commoditized 5-HT3 blockers face accelerating biosimilar and generic entry, compressing reimbursement rates and diverting pharmacy benefit manager preference away from branded antiemetics.
Strategic Opportunities
- Brazil and Mexico Outpatient Buildout:Latin American oncology center expansion is outpacing IV infrastructure, creating first-mover advantage for subcutaneous depot formulations in markets with limited infusion nursing capacity.
- AI-Enabled Emesis Prediction:Machine learning algorithms analyzing chemotherapy regimen, patient genotype, and prior cycle response are enabling personalized antiemetic pre-selection, opening software-as-a-service revenue streams alongside pharmaceutical sales.
- IRA Price Negotiation Exemption Pathways:Small-molecule supportive care drugs with orphan indications or limited competition may qualify for delayed Medicare price negotiation timelines, preserving premium pricing windows.
Industry Challenges
- Cold Chain Integrity for Biologic Combinations:Temperature-sensitive NK1 antagonist formulations require validated 2-8°C distribution networks that many regional oncology distributors lack, forcing manufacturers to absorb logistics infrastructure investment.
- Interchangeability Study Requirements:Demonstrating therapeutic equivalence between reference listed drugs and proposed biosimilars demands large-scale emesis control trials with substantial patient recruitment costs and extended clinical timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CINV Treatment Market |
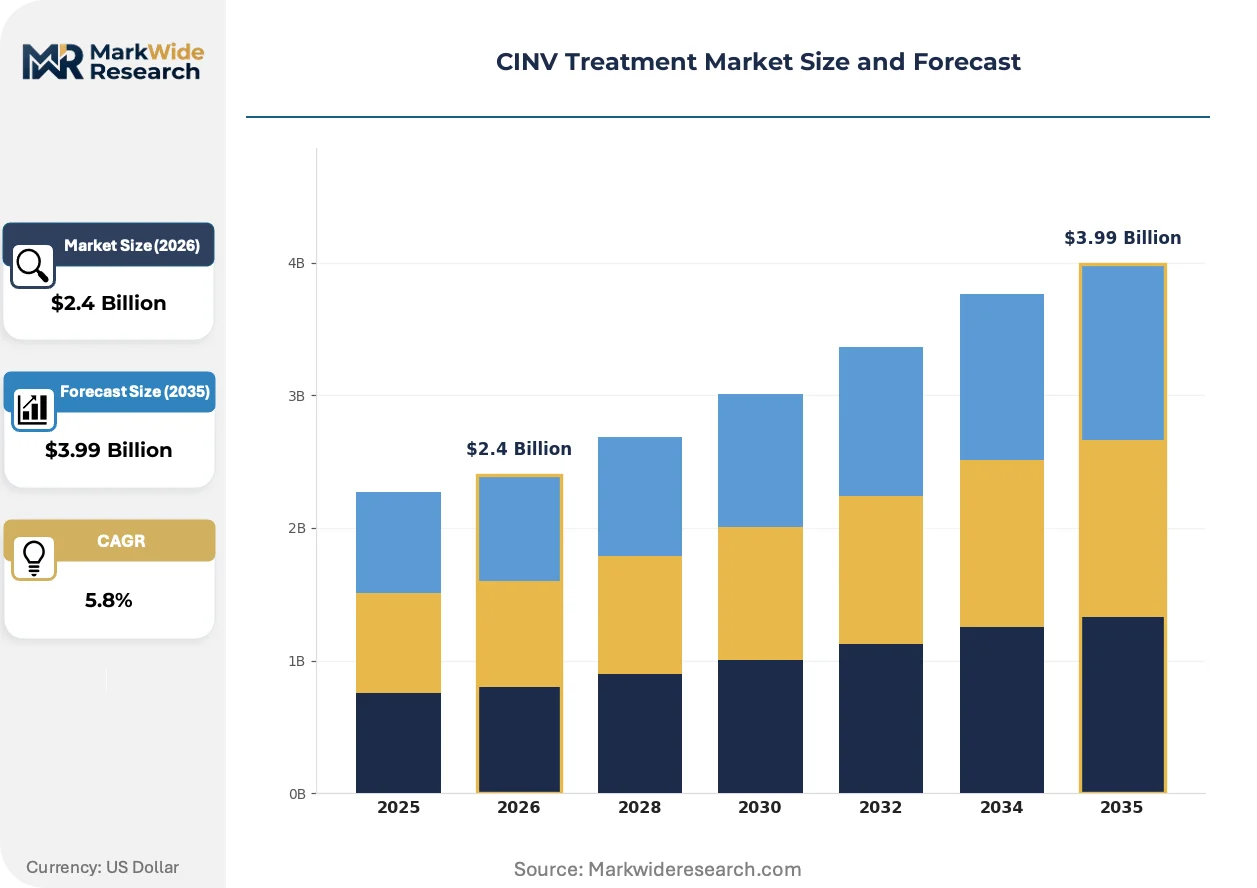
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aprepitant, Ondansetron, Granisetron, Dexamethasone Administration Route: Oral, Intravenous, Subcutaneous, Intramuscular Indication: Chemotherapy-Induced Nausea, Radiation-Induced Nausea, Postoperative Nausea, Motion Sickness End User: Hospitals, Clinics, Homecare, Outpatient Settings |
| Companies Covered | Merck & Co., Inc., Helsinn Holding S.A., GlaxoSmithKline plc, Heron Therapeutics, Inc., Pfizer Inc., Roche Holding AG, Novartis AG, Teva Pharmaceutical Industries Ltd., AstraZeneca plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CINV Treatment Market Strategic Shifts
Formulation science and site-of-care migration are converging to redefine how antiemetic coverage is delivered, with extended-release mechanisms and ambulatory administration models displacing traditional hospital-based IV protocols.
Subcutaneous polylactic-co-glycolic acid depot formulations are unifying multi-day plasma concentration maintenance into single injections, enabling 72-120 hour therapeutic windows. Oncology outpatient centers in the United States are adopting these systems at accelerating rates to reduce chair time and nursing labor allocation. This unifying technology is compressing revenue per patient episode while expanding total addressable patient volume through capacity liberation.
EMA's Medical Device Regulation is tightening clinical evidence requirements for drug-device combination products including subcutaneous injectors and transdermal delivery systems. Manufacturers must now submit biocompatibility, mechanical reliability, and human factors data beyond traditional pharmaceutical dossiers. European launch timelines for next-generation antiemetic devices are extending as firms reconfigure regulatory strategies to address MDR Annex I general safety and performance requirements.
Hospital purchasing committees are consolidating antiemetic procurement under oncology service line budgets rather than pharmacy silos, shifting vendor selection criteria toward total cost of care metrics. Integrated delivery networks in the United States are replacing fragmented formulary decisions with standardized pathway protocols that favor extended-release injectables reducing emergency department visits. This behavioral pivot is most visible in Medicare Advantage-contracted systems where readmission penalties amplify economic incentives for prophylactic efficacy.
CINV Treatment Market Segmentation
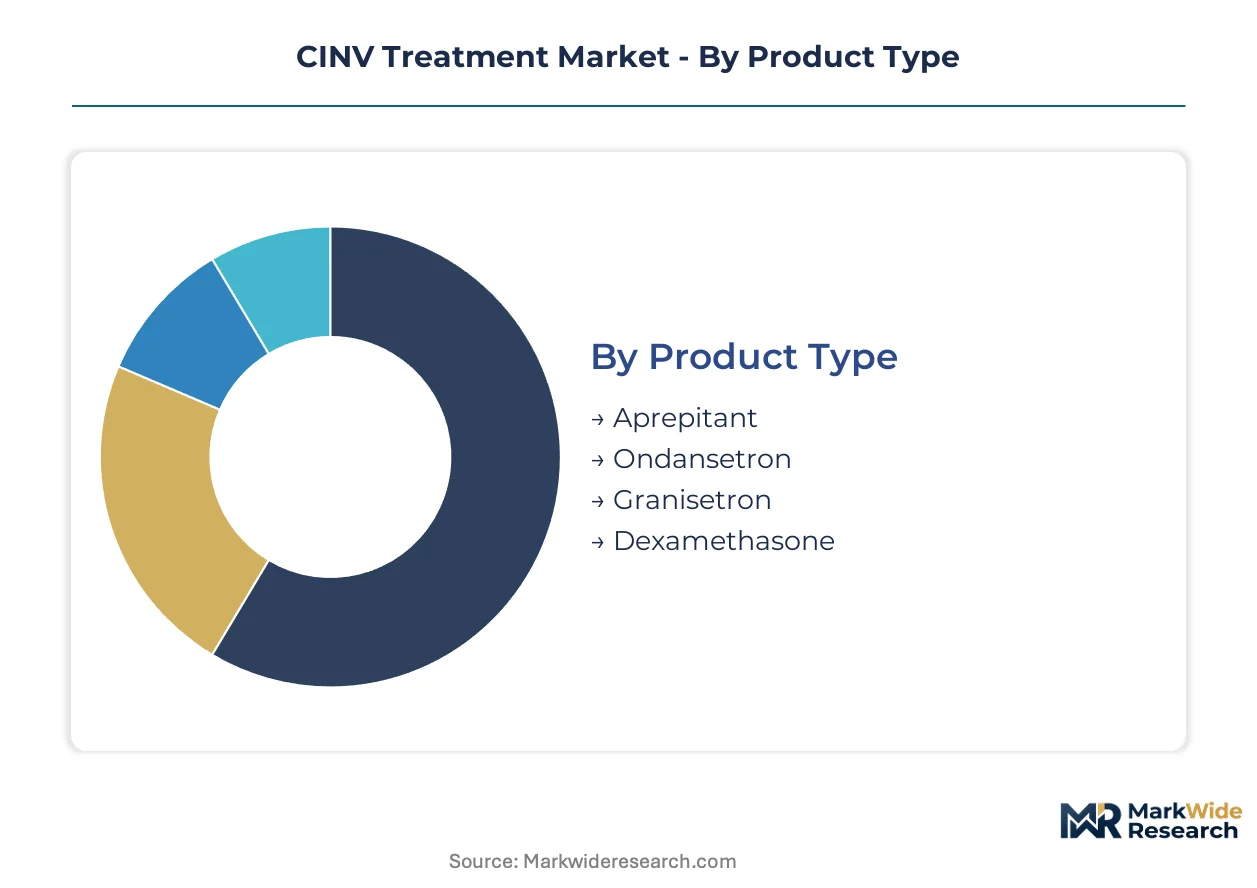
Antiemetic procurement patterns diverge sharply across clinical settings and patient acuity levels. Product formulators must align molecular characteristics with site-of-care capabilities and reimbursement pathways to capture volume.
Product Type:
Prescriber preference hinges on emetogenic risk stratification and prior-cycle response history rather than cost alone.
- Aprepitant:NK1 receptor antagonist with established efficacy in highly emetogenic chemotherapy regimens. Demand concentrates in United States oncology infusion centers where triple-drug prophylaxis is standard-of-care for cisplatin-based protocols.
- Ondansetron:First-generation 5-HT3 antagonist available in oral disintegrating tablets and IV formulations. Volume sits with generic substitution in hospital formularies; growth tilts toward orally disintegrating formats in ambulatory settings.
- Granisetron:Longer-acting 5-HT3 blocker with transdermal patch delivery extending coverage to 5-7 days.
- Dexamethasone:Corticosteroid backbone of combination antiemetic protocols, typically co-administered with 5-HT3 or NK1 agents.
Volume sits with ondansetron; growth tilts toward aprepitant combinations in high-risk regimens.
Administration Route:
Site-of-care economics and nursing labor availability dictate route selection more than patient preference.
- Oral:Tablets and capsules enabling self-administration outside clinical supervision. Demand concentrates in homecare channels where reimbursement favors eliminating infusion chair time.
- Intravenous:Immediate bioavailability for acute emesis control in supervised settings. Volume concentrates in hospital oncology units with established IV infrastructure and pharmacy compounding capabilities.
- Subcutaneous:Extended-release depot formulations reducing administration frequency to single-dose protocols.
- Intramuscular:Alternative parenteral route for patients with compromised venous access or IV incompatibility.
Revenue concentrates in IV administration; capacity expansion is shifting fastest toward subcutaneous depot systems.
Indication:
Clinical evidence requirements and payer coverage policies create divergent commercialization pathways across nausea etiologies.
- Chemotherapy-Induced Nausea:Primary reimbursed indication with established prophylactic protocols across emetogenic risk categories. Demand anchors in United States hospital outpatient departments where Medicare reimbursement rates shape formulary placement.
- Radiation-Induced Nausea:Secondary indication with narrower evidence base and more restrictive coverage determinations.
- Postoperative Nausea:Surgical suite application with distinct competitive dynamics including acupressure device alternatives.
- Motion Sickness:Over-the-counter and prescription overlap with antihistamine competition outside oncology therapeutic focus.
Prescription volume clusters in chemotherapy-induced nausea; label expansion efforts target radiation-induced indications.
End User:
Capital intensity and reimbursement model determine antiemetic procurement sophistication across delivery settings.
- Hospitals:Integrated delivery networks with pharmacy and therapeutics committees standardizing formulary decisions. Volume concentrates in Medicare-certified cancer centers with 340B drug pricing program participation.
- Clinics:Community oncology practices with limited infusion capacity seeking to extend patient throughput.
- Homecare:Infusion nursing services and specialty pharmacies managing oral and subcutaneous administration.
- Outpatient Settings:Ambulatory surgery centers and hospital outpatient departments with compressed recovery protocols.
Revenue generation remains anchored in hospitals; patient volume is migrating fastest toward homecare channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oncology corridor development in Research Triangle Park, North Carolina concentrates Phase III trial infrastructure for antiemetic developers seeking FDA validation pathways.
United States
Hospital outpatient infusion centers in Texas and Florida drive volume for extended-release injectable protocols. Medicare reimbursement shifts under the Hospital Outpatient Prospective Payment System favor single-dose administration models. MD Anderson Cancer Center in Houston anchors emetogenic regimen research that shapes national antiemetic guidelines.
Germany
Community oncology networks in Bavaria and Baden-Württemberg prioritize homecare-compatible formulations to reduce hospital day costs. EMA centralized marketing authorization timelines for combination drug-device products extend commercialization planning horizons. Heidelberg University Hospital anchors NK1 antagonist clinical trial recruitment across Central European sites.
Japan
Aging demographics and high chemotherapy penetration in Kanto and Kansai regions sustain demand for prophylactic antiemetic coverage. PMDA's Sakigake designation system accelerates review for novel extended-release mechanisms addressing unmet supportive care needs. National Cancer Center Hospital in Tokyo coordinates multi-site emesis control studies informing JSCO guideline revisions.
Brazil
Public health system oncology expansion in São Paulo and Minas Gerais outpaces IV infrastructure deployment. ANVISA's reliance on FDA and EMA prior approvals streamlines registration for subcutaneous depot formulations already validated in reference markets. Hospital de Câncer de Barretos anchors regional training for ambulatory chemotherapy delivery without dedicated infusion nursing.
India
Contract manufacturing concentration in Hyderabad and Ahmedabad supplies API for ondansetron and granisetron to global formulators. CDSCO's accelerated approval pathway for drugs addressing critical unmet needs in oncology supportive care reduces time-to-market for novel formulations. Tata Memorial Hospital in Mumbai anchors emetogenic risk stratification research applicable to resource-limited settings.
CINV Treatment Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with formulation innovators capturing premium positioning in extended-release injectables while generic API suppliers compete on cost in commoditized oral segments. Market structure tilts toward concentrated leadership in NK1 receptor antagonist combinations alongside fragmented supply for 5-HT3 blockers. Three archetypes dominate: large-cap pharmaceutical developers with oncology franchise depth, mid-cap supportive care specialists, and regional generic manufacturers with API backward integration. Competitive dynamics center on M&A to acquire depot formulation capabilities and strategic partnerships to secure distribution in emerging ambulatory channels.
Within the large-cap pharmaceutical tier, Merck & Co., Inc. and Pfizer Inc. occupy positions anchored by established NK1 receptor antagonist portfolios and oncology therapeutic area infrastructure. Among supportive care specialists, Helsinn Holding S.A. and Heron Therapeutics, Inc. exemplify focused strategies targeting extended-release mechanisms and reduced administration burden. GlaxoSmithKline plc represents the diversified pharmaceutical archetype with historical 5-HT3 presence now navigating generic substitution pressures.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Helsinn Holding S.A. |
| GlaxoSmithKline plc |
| Heron Therapeutics, Inc. |
| Pfizer Inc. |
| Roche Holding AG |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd. |
| AstraZeneca plc |
| Others |
Value Chain & Pricing Dynamics
API manufacturing labor costs in Hyderabad and Ahmedabad flow through contract formulator margins into hospital formulary pricing tiers, with purity-grade differentials separating branded extended-release injectables from commoditized oral generics.
Pricing Analysis
Short lead-time premiums for cold-chain NK1 antagonist formulations command hospital procurement preference over spot-inventory 5-HT3 generics facing biosimilar compression. Three-tier pricing structure across premium extended-release depot, standard IV combination therapy, and economy oral generic levels stratifies by administration route complexity and emetogenic protocol intensity. Pricing pressure stems from granisetron and ondansetron biosimilar entry diverting pharmacy benefit manager volume toward interchangeable substitutes. Community oncology clinics exhibit highest price sensitivity; academic medical centers with 340B participation preserve branded preference.
Supply Chain Analysis
Reverse-logistics networks for temperature-compromised biologic antiemetics remain underdeveloped across regional oncology distributors, forcing manufacturers to absorb write-downs or establish direct-to-site cold chain redundancy. Active pharmaceutical ingredient production concentrates in India, China, and Italy, with South Asian suppliers dominating ondansetron base material and European facilities anchoring NK1 antagonist synthesis. Formulation inputs draw from polylactic-co-glycolic acid resin suppliers in Germany and specialized injection device manufacturers in Switzerland. Single-source vulnerability for subcutaneous injector components exposes extended-release formulators to MDR compliance delays. Distribution runs through integrated delivery network central pharmacies and specialty oncology distributors with validated cold storage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Depot formulation manufacturing capacity constraints in North America and Western Europe prop pricing power for incumbents with validated subcutaneous production lines, while API oversupply in South Asia compresses margins for oral generic competitors.
For Market Incumbents: Lock in exclusive supply agreements with polylactic-co-glycolic acid resin suppliers in Germany and Switzerland to defend against emerging depot formulation entrants. Secure backward integration into cold-chain distribution infrastructure across Medicare Advantage-contracted oncology networks. Prioritize MDR Annex I clinical evidence dossiers for combination drug-device products ahead of European label expansion. For New Entrants and Emerging Players: ANVISA's reliance on FDA prior approvals in Brazil opens a window for subcutaneous depot formulations already validated in reference markets, bypassing lengthy local clinical trial requirements. Target community oncology practices in São Paulo and Minas Gerais with limited IV nursing capacity. Pursue white-label manufacturing partnerships with Hyderabad-based API suppliers to compress development timelines for oral 5-HT3 combinations. For Investors and Strategic Acquirers: FDA label expansions for NK1 receptor antagonist combinations in highly emetogenic regimens is the leading indicator that extended-release mechanism premiums will persist against oral generic substitution. Focus acquisition screening on mid-cap supportive care specialists with depot formulation capabilities and orphan indication positioning. Monitor IRA price negotiation exemption pathway determinations for small-molecule supportive care drugs as inflection signals for premium pricing durability.| Strategic Initiative | Industry Significance |
|---|---|
| Extended-Release Formulation Development | Single-dose subcutaneous depot systems reduce chair time and nursing labor allocation across outpatient infusion centers. |
| Regulatory Approval Pathway | EMA MDR compliance for drug-device combinations extends European commercialization timelines by 18-24 months. |
| Backward Integration into API Supply | Captive ondansetron and granisetron base material production insulates against Indian export control volatility. |
| Reimbursement Strategy | Medicare Advantage risk-contract alignment favors prophylactic efficacy metrics reducing emergency department utilization. |
| Strategic Partnership | Homecare infusion nursing networks enable patient self-administration eliminating supervised clinical settings. |
Study Parameters
Independent corroboration across FDA Orange Book filings, EMA centralized marketing authorization decisions, and ClinicalTrials.gov recruitment data underwrites the qualitative findings on NK1 antagonist development pipelines. Primary interviews with oncology formulary directors, hospital procurement managers, payer access specialists, and regulatory affairs leads at extended-release formulation developers were cross-referenced against secondary validation from CMS Medicare reimbursement databases, 340B drug pricing program reports, and GPO contract repositories. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored segmentation outputs.
Rate-of-change decomposition across the analysis window separates volume effects from price mix shifts within administration route and emetogenic risk stratification dimensions. The analytical framework models treatment line, dosage form, administration route, and regional regulatory cluster segments throughout the forecast period. CAGRs were derived from patient population projections, chemotherapy regimen penetration curves, and site-of-care migration patterns. Forecast inputs incorporate biosimilar entry timelines for 5-HT3 blockers and MDR implementation pacing for combination drug-device products.
The model assumes a particular technology adoption path; alternative pathways for subcutaneous polylactic-co-glycolic acid depot formulations would alter the outlook if oral NK1 antagonist bioavailability improves substantially. Forecasts reflect assumptions regarding IRA price negotiation exemption qualification and EMA MDR enforcement consistency. Practitioners should monitor FDA label expansion decisions for highly emetogenic regimen coverage and ANVISA registration pathway streamlining for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Kidney Stones Management Market
Medical Treatment
Rotator Cuff Injury Treatment Market
Medical Treatment
Hemorrhoids Treatment Market
Medical Treatment
Allergic Rhinitis Treatment Market
Medical Treatment
Disseminated Intravascular Coagulation (DIC) Treatment Market
Medical Treatment
Secondary Hyperparathyroidism Treatment Market
Medical Treatment
Cysticercosis (Taeniasis) Treatment Market
Medical Treatment
US Direct Anterior Approach (Total Hip Replacement) Market
Medical Treatment
Refsum Disease Treatment Market
Medical Treatment
Radiotherapy Induced Oral Mucositis Treatment Market
Medical Treatment
Gunshot Injuries Treatment Market
Medical Treatment
Dementia Treatment Market
Medical Treatment
US Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
Peri-Implantitis Treatment Market
Medical Treatment
Anaphylaxis Treatment Market
Medical Treatment
Radiation Therapy Market