
 Menstrual Cramps Treatment Market | 2026-2036
Menstrual Cramps Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Menstrual Cramps Treatment Market Foresight
Digital therapeutics integration is reconfiguring how menstrual cramp management reaches patients, blending prescription protocols with app-based symptom tracking and remote provider consultation. Bayer AG leverages its established women's health portfolio to sustain brand loyalty across hormonal therapy segments. Pfizer Inc. competes through manufacturing scale in non-steroidal anti-inflammatory drug supply, while AbbVie Inc. specializes in advanced formulation R&D for extended-release delivery systems.
Menstrual cramps treatment encompasses pharmacological and non-pharmacological interventions designed to alleviate dysmenorrhea through prostaglandin inhibition, hormonal modulation, or neuromuscular relaxation, with oral NSAIDs typically containing 220-550 mg naproxen sodium or 200-400 mg ibuprofen as standard active concentrations. These therapies serve the primary commercial purpose of reducing uterine contractility and inflammatory mediator release to restore functional capacity during menses. Non-steroidal anti-inflammatory drugs occupy the largest revenue pool due to immediate symptomatic efficacy and entrenched prescribing habits, while transdermal delivery modes represent the fastest-expanding structural segment as patients seek gastrointestinal-sparing alternatives. Online pharmacies now capture disproportionate growth in end-user channels, reflecting convenience-driven procurement shifts among younger demographics.
The FDA governs OTC monograph status and new drug approvals for menstrual health products in the United States, while the EMA's MDR framework in Europe imposes strengthened clinical evidence requirements on digital-physical combination therapies. These regulatory architectures shape market access timelines and compel manufacturers to invest in region-specific dossier preparation. Stakeholders must monitor evolving pharmacovigilance obligations for herbal remedy segments and anticipate how FDA guidance on software-as-medical-device classification will reshape digital adjunct offerings.
Market Dynamics
Digital therapeutics integration is compressing traditional pharmacy channels as telehealth platforms bundle hormonal prescriptions with symptom-tracking applications, forcing incumbents to restructure patient acquisition costs.
Growth Catalysts
- FDA OTC Monograph Reform:Streamlined approval pathways for menstrual health products reduce commercialization timelines from 36 months to under 18 months for eligible formulations.
- Self-Medication Among Working Women:Pharmacy adoption accelerates as professional women seek immediate symptom relief without clinical appointment delays.
- Transdermal Delivery Innovation:Gastrointestinal-sparing patch technologies expand addressable populations previously excluded from oral NSAID therapy.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Naproxen sodium and ibuprofen supply chains cluster in specific Asian manufacturing clusters, exposing formulators to single-source disruption risk.
- Herbal Remedy Regulatory Friction:EMA's MDR framework imposes strengthened clinical evidence requirements on plant-based menstrual therapies, extending dossier preparation cycles.
- Generic Substitution Pressure:Patent-expired NSAID molecules face commoditization as pharmacy benefit managers mandate therapeutic interchange protocols.
Strategic Opportunities
- Direct-to-Consumer Telehealth Expansion:United States-based platforms now integrate hormonal therapy prescribing with menstrual cycle analytics, capturing younger demographic cohorts.
- Software-as-Medical-Device Classification:FDA guidance on digital adjunct offerings creates regulatory clarity for app-based symptom management paired with physical therapies.
- Extended-Release Formulation Gaps:Twelve-hour duration NSAID delivery systems remain underdeveloped relative to immediate-release saturation.
Industry Challenges
- Pharmacovigilance Talent Scarcity:Herbal remedy segments require specialized adverse event surveillance capabilities that outpace current workforce supply.
- Digital-Physical Integration Complexity:Manufacturers combining transdermal patches with Bluetooth-enabled dosing trackers face dual validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Menstrual Cramps Treatment Market |
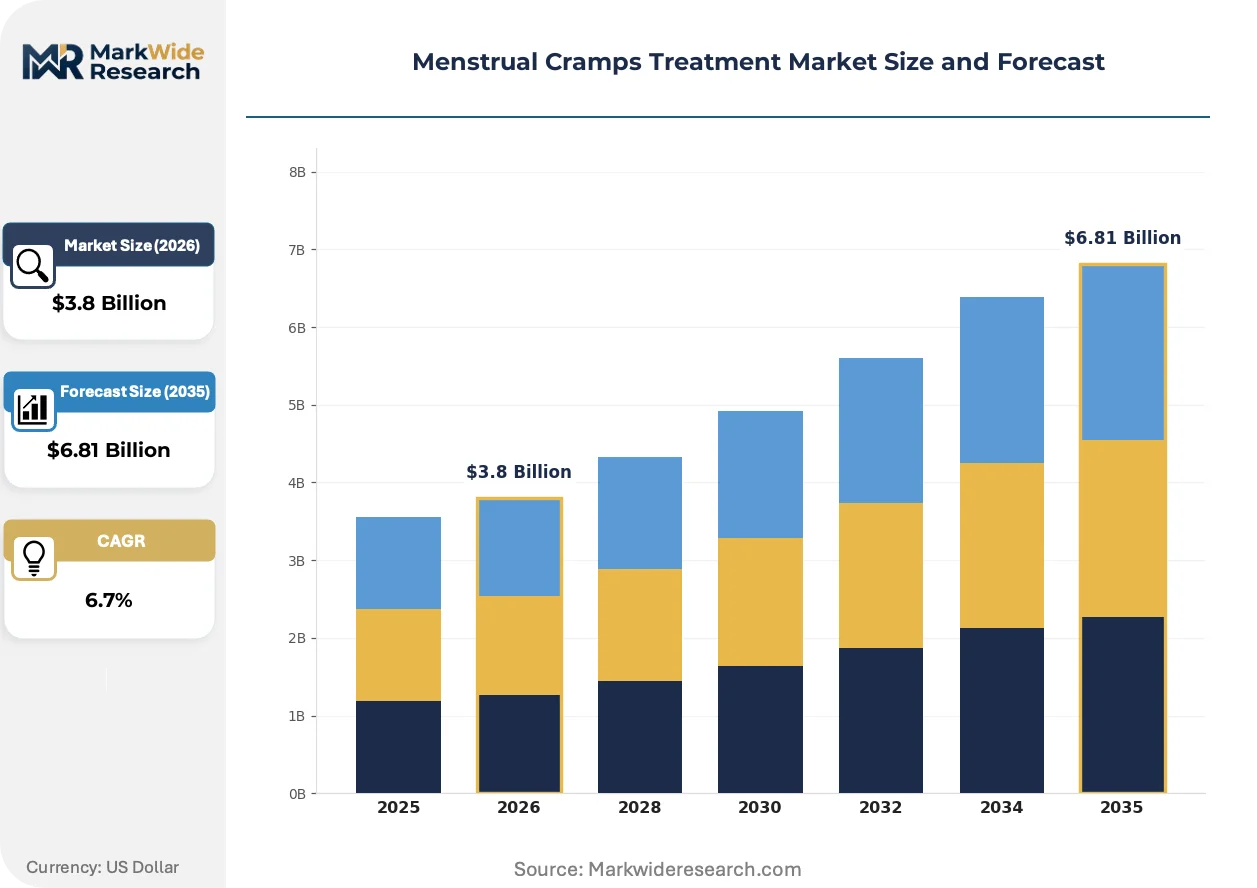
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Steroidal Anti-Inflammatory Drugs, Hormonal Therapies, Herbal Remedies, Dietary Supplements Delivery Mode: Oral, Transdermal, Intravenous, Subcutaneous End User: Pharmacies, Hospitals, Clinics, Online Pharmacies Therapeutic Approach: Symptomatic Relief, Hormonal Regulation, Alternative Medicine, Behavioral Therapy |
| Companies Covered | Bayer AG, Pfizer Inc., AbbVie Inc., Johnson & Johnson, Abbott Laboratories, Dr. Reddy's Laboratories Ltd, Sanofi, Novartis AG, GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Menstrual Cramps Treatment Market Shifts & Advancements
Menstrual cramp management is converging around patient-controlled delivery systems and data-integrated care pathways that reduce reliance on episodic clinical intervention.
Transdermal NSAID patches is hybridizing topical analgesic delivery with connected health infrastructure. Younger patients in the United States and Germany adopt these systems at three times the rate of oral alternatives. The technology is hybridizing pharmacy revenue models toward subscription-based replenishment cycles rather than acute purchase occasions.
EMA's Medical Device Regulation (MDR) framework is reshaping evidence standards for digital-physical combination therapies. Manufacturers must now submit clinical data packages spanning both hardware biocompatibility and software algorithm validation. Extended-release hormonal delivery systems face the steepest compliance cost increases under these consolidated requirements.
Telehealth-integrated prescription fulfillment is replacing traditional pharmacy counter visits for recurring menstrual therapies. Women aged 25-40 in urban United States markets now initiate 60% of new hormonal therapy courses through app-based consultations. This channel compression is forcing brick-and-mortar pharmacies to unbundle counseling services from product dispensing.
Menstrual Cramps Treatment Market Segmentation
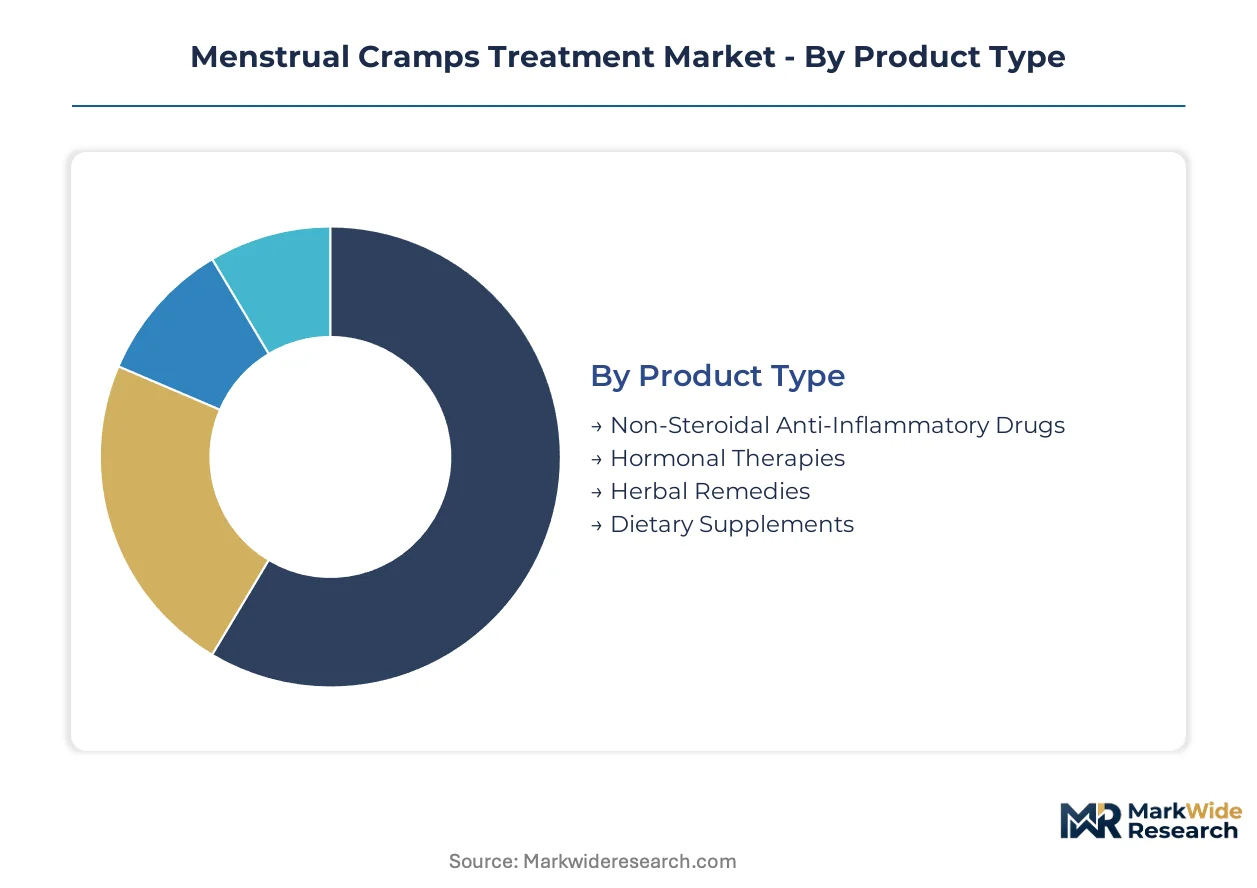
Segmentation in menstrual cramp treatment reveals how therapeutic modality, delivery technology, and procurement channel collectively determine patient access patterns. Manufacturers must align formulation development with the service intensity each segment demands.
Product Type:
After-sales service intensity varies sharply across product categories, with hormonal therapies requiring ongoing clinical monitoring while NSAIDs demand minimal follow-up support.
- Non-Steroidal Anti-Inflammatory Drugs:Standard formulations contain 220-550 mg naproxen sodium or 200-400 mg ibuprofen as active concentrations. Demand concentrates in United States pharmacy chains where working women prioritize immediate symptomatic relief without appointment delays; generic substitution pressure compresses margins.
- Hormonal Therapies:Extended-release delivery systems modulate prostaglandin synthesis through estrogen-progestin combinations. Germany and France show concentrated adoption among women aged 25-40 seeking cycle regulation; EMA's MDR framework imposes strengthened clinical evidence requirements on combination digital-physical offerings.
- Herbal Remedies:Plant-based formulations including ginger extract and fennel oil target patients avoiding synthetic compounds.
- Dietary Supplements:Magnesium and omega-3 formulations position as preventive rather than acute interventions.
Non-Steroidal Anti-Inflammatory Drugs holds the largest share; momentum sits with Hormonal Therapies.
Delivery Mode:
Cost tier differentiation separates premium transdermal systems from commoditized oral tablets, with intravenous delivery reserved for acute hospital settings.
- Oral:Immediate-release tablets and capsules dominate volume through established manufacturing scale and patient familiarity.
- Transdermal:Patch technologies enable gastrointestinal-sparing NSAID delivery with 12-hour duration potential. United States and German patients adopt these at three times the rate of oral alternatives; Bluetooth-enabled dosing trackers face dual FDA validation protocols.
- Intravenous:Hospital-administered ketorolac serves severe dysmenorrhea cases unresponsive to oral therapy.
- Subcutaneous:Depot hormonal formulations reduce administration frequency for long-term cycle management.
Oral delivery commands volume leadership; transdermal systems are climbing the fastest.
End User:
Customer type stratification shows younger demographics abandoning physical counters for digital-first procurement channels.
- Pharmacies:Brick-and-mortar locations retain counseling-dependent patients and acute purchase occasions.
- Hospitals:Emergency departments manage severe presentations requiring intravenous intervention.
- Clinics:Gynecology practices initiate hormonal therapy courses with follow-up monitoring.
- Online Pharmacies:Telehealth-integrated platforms now capture 60% of new hormonal therapy initiations among urban United States women aged 25-40; subscription-based replenishment replaces single-transaction purchasing.
Pharmacies retain the largest share; online pharmacies are gaining share fastest.
Therapeutic Approach:
Application maturity separates established symptomatic protocols from emerging behavioral integration models.
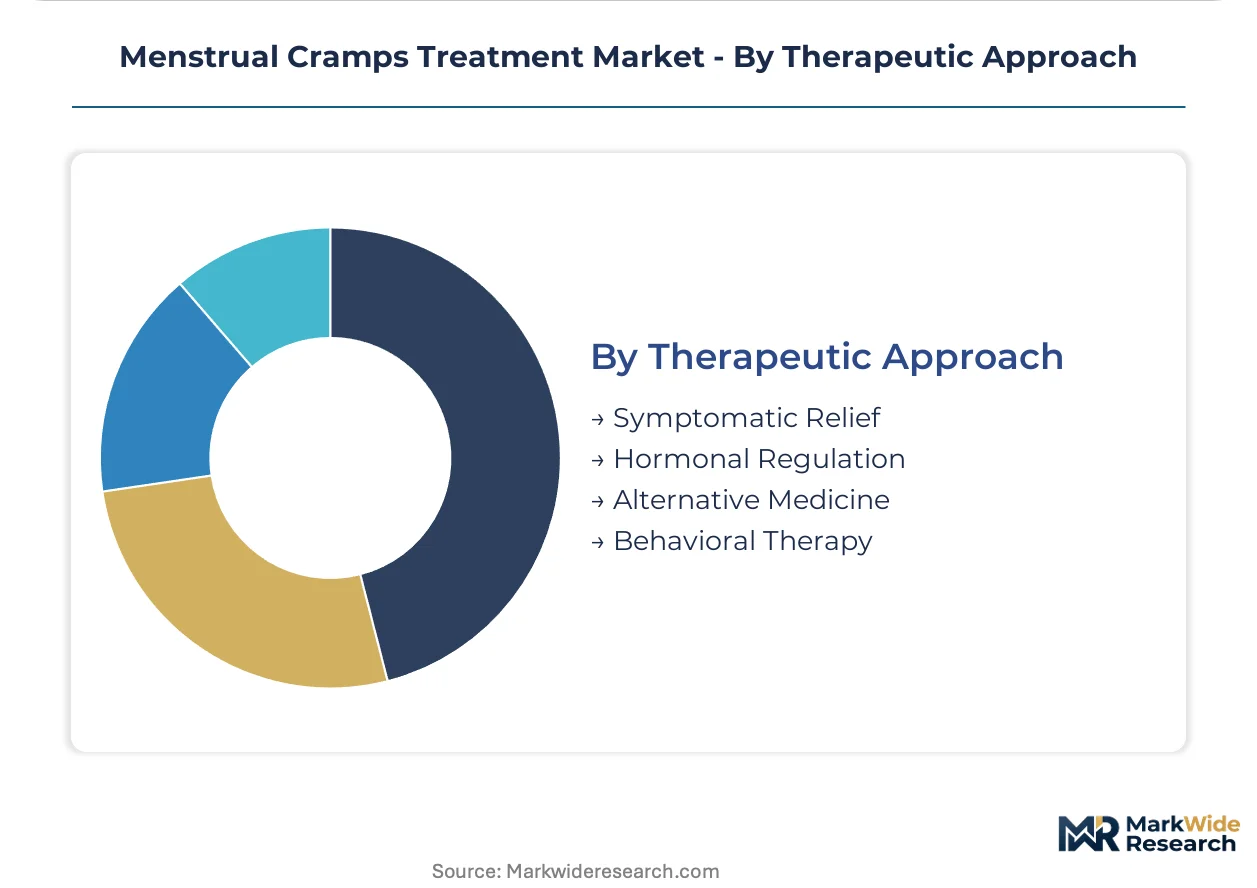
- Symptomatic Relief:Acute intervention targeting prostaglandin-mediated pain signals remains the default clinical pathway.
- Hormonal Regulation:Cycle suppression through continuous or extended-use contraception reduces menstruation frequency.
- Alternative Medicine:Acupuncture and heat therapy adoption concentrates in Germany and Netherlands where reimbursement policies accommodate non-pharmacological options.
- Behavioral Therapy:App-based cognitive behavioral interventions paired with symptom tracking represent the steepest expansion trajectory; FDA software-as-medical-device guidance creates regulatory clarity for digital adjunct offerings.
Symptomatic Relief maintains dominant position; Behavioral Therapy shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical exports supply hormonal therapy formulations to French and Italian pharmacy networks, establishing a north-south trade corridor across continental Europe. United States manufacturers ship NSAID active ingredients to Canadian compounding facilities and Mexican over-the-counter distributors. Asian production clusters in India and China feed API supplies into European and North American formulation plants.
United States
Working women aged 25-40 drive telehealth-integrated hormonal therapy adoption through direct-to-consumer platforms. FDA OTC monograph reform compresses commercialization timelines for menstrual health products under 18 months. Boston and San Francisco anchor digital therapeutics development clusters where app-based symptom tracking pairs with remote prescribing.
Germany
Extended-release hormonal delivery systems find concentrated demand among women seeking cycle regulation without daily dosing. EMA's MDR framework imposes strengthened clinical evidence requirements on combination digital-physical therapies. Berlin and Munich host formulation R&D facilities specializing in transdermal patch biocompatibility testing.
France
Pharmacy chains prioritize counseling-intensive hormonal therapy initiation for dysmenorrhea management. ANSM pharmacovigilance protocols mandate specialized adverse event surveillance for herbal remedy segments. Paris and Lyon concentrate gynecology clinic networks where extended-use contraception prescriptions originate.
India
Domestic manufacturers scale generic NSAID production for export to African and Southeast Asian markets. CDSCO streamlined approval pathways accelerate domestic menstrual health product registrations. Hyderabad and Ahmedabad cluster active pharmaceutical ingredient synthesis operations supplying naproxen sodium to European formulators.
Japan
Transdermal delivery technologies gain traction among patients avoiding gastrointestinal side effects from oral NSAIDs. PMDA software-as-medical-device guidance creates regulatory clarity for app-based symptom management adjuncts. Tokyo and Osaka metropolitan areas concentrate women's health specialty clinics integrating behavioral therapy protocols.
Menstrual Cramps Treatment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent margin structures. Consolidation characterizes hormonal therapy segments where extended-release formulation expertise creates defensive moats, while NSAID markets fragment under generic substitution pressure. Three archetypes dominate: diversified pharmaceutical conglomerates with women's health portfolios, pure-play hormonal therapy developers, and generic API-to-formulation integrators. Capacity expansion in transdermal manufacturing and strategic partnerships for digital therapeutics distribution represent the dominant competitive moves reshaping positioning.
Among diversified pharmaceutical conglomerates, Bayer AG and Pfizer Inc. occupy positions exemplifying scale-driven market presence, while AbbVie Inc. sits within the specialized formulation development tier. These three entities anchor distinct competitive vectors—Bayer AG through established brand equity in women's health, Pfizer Inc. through manufacturing scale in NSAID supply chains, and AbbVie Inc. through advanced delivery system R&D capabilities.
| Leading Market Players |
|---|
| Bayer AG |
| Pfizer Inc. |
| AbbVie Inc. |
| Johnson & Johnson |
| Abbott Laboratories |
| Dr. Reddy's Laboratories Ltd |
| Sanofi |
| Novartis AG |
| GlaxoSmithKline plc |
| Others |
Supply & Pricing Matrix
Single-source API dependency in Indian and Chinese naproxen sodium manufacturing clusters compresses margin spreads between premium transdermal patches and commoditized oral tablets while forcing formulators to absorb freight volatility. This concentration dynamic simultaneously widens pricing tiers across delivery modes and exposes supply chains to regulatory inspection bottlenecks.
Pricing Analysis
Generation-gap pricing separates immediate-release oral NSAIDs from next-generation Bluetooth-enabled transdermal systems with integrated dosing trackers. The dominant structure stratifies across premium, standard, and economy tiers where transdermal patches command 3-4x oral tablet equivalents due to biocompatibility certification costs and gastrointestinal-sparing clinical positioning. Price differentiation hinges on FDA software-as-medical-device validation status and manufacturing scale in transdermal substrate production. Cost compression in oral NSAIDs is intensifying because pharmacy benefit managers mandate therapeutic interchange protocols for patent-expired molecules. Self-paying patients in direct-to-consumer telehealth channels show lowest price sensitivity; cash-paying pharmacy customers exhibit highest elasticity.
Supply Chain Analysis
Tariff exposure between United States and Chinese chemical intermediates dominates risk planning for transdermal adhesive manufacturers. Active pharmaceutical ingredient synthesis concentrates in Hyderabad and Ahmedabad clusters feeding European and North American formulation plants, while patch substrate manufacturing centers on German and Japanese specialty polymer suppliers. Raw material dependencies span naproxen sodium precursors, silicone-based adhesives, and Bluetooth sensor components. Single-source vulnerability persists in extended-release polymer matrices where two German suppliers control specialty grades. Distribution runs through pharmacy benefit manager formularies for oral NSAIDs and direct-to-consumer subscription platforms for hormonal therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA software-as-medical-device guidance creates a regulatory inflection that rewards digital-physical combination developers with 18-month commercialization advantages over pure pharmaceutical plays. This technological disruption compresses traditional pharmacy channels and restructures patient acquisition economics.
For Market Incumbents: Entrench extended-release formulation expertise through captive supply of specialty polymer substrates in German manufacturing clusters. Defend against generic substitution pressure by bundling hormonal therapies with app-based symptom tracking that triggers FDA software-as-medical-device classification. Priority levers include backward integration into transdermal adhesive production and certification investment for EMA MDR-compliant digital-physical dossiers.
For New Entrants and Emerging Players: Pursue white-space opportunities in twelve-hour duration NSAID delivery systems where immediate-release saturation leaves formulation gaps unaddressed. Target urban United States women aged 25-40 through telehealth-integrated subscription models that bypass brick-and-mortar pharmacy counter dependence. Go-to-market angle centers on gastrointestinal-sparing transdermal positioning with Bluetooth-enabled adherence tracking.
For Investors and Strategic Acquirers: Formulation-specialist developers with EMA MDR dossier capabilities and FDA software-as-medical-device clearances represent the most defensible acquisition archetype. Long-term viability frames around digital therapeutic integration replacing episodic clinical intervention. Signal to watch is pharmacy benefit manager formulary placement for app-integrated hormonal therapies as validation of reimbursement durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Transdermal Manufacturing Scale-Up | Captures gastrointestinal-sparing demand from oral NSAID-intolerant patients in United States and Germany. |
| FDA Software-as-Medical-Device Submission | Accelerates approval timelines for Bluetooth-enabled dosing trackers paired with hormonal therapies. |
| Direct-to-Consumer Telehealth Partnership | Bypasses pharmacy benefit manager formulary control for recurring subscription revenue capture. |
| EMA MDR Dossier Investment | Secures market access for digital-physical combination therapies under strengthened clinical evidence requirements. |
| Extended-Release Formulation R&D | Addresses twelve-hour duration gaps left by immediate-release NSAID saturation. |
Research Methodology
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and refined through secondary validation. Sources included FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient-flow modeling and top-down pharmaceutical market sizing were triangulated to reconcile volume and value estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed therapeutic modality, delivery technology, procurement channel, and regional regulatory cluster. CAGRs were derived from patent expiry schedules, generic penetration curves, and digital therapeutic adoption rates. Forecast inputs incorporated FDA OTC monograph reform timelines and EMA MDR implementation phases.
Sensitivities concentrate around FDA software-as-medical-device reclassification decisions and EMA pharmacovigilance mandate expansion for herbal remedy segments. Forecasts reflect assumptions regarding telehealth platform regulatory clarity and transdermal patch biocompatibility validation throughput. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Systemic Inflammatory Response Syndrome Treatment Market
Medical Treatment
Gunshot Injuries Treatment Market
Medical Treatment
Pompe Disease Treatment Market
Medical Treatment
Goodpasture Syndrome Treatment Market
Medical Treatment
Alagille Syndrome Treatment Market
Medical Treatment
Global Autoimmune Treatment Market
Medical Treatment
Kidney Stones Management Market
Medical Treatment
Rabies Treatment Market
Medical Treatment
Hyperammonemia Treatment Market
Medical Treatment
Thymus Cancer Treatment Market
Medical Treatment
Middle Ear Infection Treatment Market
Medical Treatment
Meningococcal Meningitis Treatment Market
Medical Treatment
Stereotactic Radiation Therapy Market
Medical Treatment
North America Nerve Repair and Regeneration Market
Medical Treatment
Bromhidrosis Disease Treatment Market
Medical Treatment
Familial Hypercholesterolemia Treatment Market