
 Hypercalcemia Treatment Market | 2026-2036
Hypercalcemia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hypercalcemia Treatment Market Outlook
Targeted biologic manufacturing is reconfiguring how calcimimetic therapies reach hypercalcemia patients, shifting from small-molecule dominance toward precision receptor modulation. Amgen Inc. leverages its biologics infrastructure to sustain leadership in parathyroid hormone pathway modulation. Novartis AG anchors its position through nephrology-focused channel control, while Pfizer Inc. competes via injectable formulation scale across hospital networks.
Hypercalcemia treatment encompasses pharmacological interventions that restore calcium homeostasis by inhibiting bone resorption, enhancing renal excretion, or suppressing parathyroid hormone secretion, with intravenous bisphosphonates requiring precise infusion timing to prevent nephrotoxicity in malignancy-associated cases. Bisphosphonates dominate current prescribing patterns due to established oncology protocols and broad payer coverage, while calcimimetics represent the fastest-expanding segment as cinacalcet generics and etelcalcetide adoption reshape the reimbursement landscape. The injectable route captures the deepest margin pools in hospital settings, though oral calcimimetics extend into dialysis clinic channels where self-administration reduces staffing costs.
FDA orphan drug designations and EMA conditional marketing authorizations shape how developers prioritize indication sequencing, with malignancy-associated hypercalcemia qualifying for expedited review pathways that compress development timelines. The EU MDR's tightened clinical evidence requirements for high-risk devices indirectly elevates scrutiny of drug-device combination products used in subcutaneous calcimimetic delivery. Stakeholders must monitor how CMS's evolving hospital outpatient prospective payment system reclassifies infusion-administered therapies versus physician-administered drugs, as this distinction determines site-of-care economics and manufacturer contracting leverage.
Market Dynamics
The shift from small-molecule bisphosphonates toward precision calcimimetic biologics is restructuring competitive advantage around manufacturing infrastructure and nephrology channel control rather than oncology sales force scale alone.
Growth Catalysts
- FDA Orphan Drug Designation:Expedited review pathways for malignancy-associated hypercalcemia compress development timelines and reduce capital requirements for novel calcimimetic entrants.
- Dialysis Clinic Channel Expansion:Self-administered oral calcimimetics reduce staffing costs in outpatient nephrology settings, extending addressable patient populations beyond hospital infusion centers.
- Biologics Manufacturing Scale:Contract development and manufacturing organizations with mammalian cell culture capacity enable mid-tier developers to compete in parathyroid hormone pathway modulation without captive facilities.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Bisphosphonate API production clusters in India and China, exposing formulation sponsors to geopolitical supply disruptions and import inspection backlogs.
- Infusion Timing Protocols:Precise hydration and infusion rate requirements for zoledronic acid in renal-impaired patients limit protocol standardization across oncology networks.
- Generic Cinacalcet Entry:Patent expiration of first-generation calcimimetics compresses pricing power for oral segment incumbents and redirects R&D budgets toward injectable differentiation.
Strategic Opportunities
- Subcutaneous Delivery Innovation:Drug-device combination products for outpatient calcimimetic administration could shift site-of-care economics away from hospital infusion centers toward home healthcare.
- EU MDR Alignment:Tighter clinical evidence requirements for high-risk devices create first-mover advantage for developers with robust subcutaneous delivery pharmacokinetic data packages.
- Pediatric Indication Expansion:Primary hyperparathyroidism in adolescent populations represents an underserved segment with limited approved therapeutic options and favorable payer tolerance for premium pricing.
Industry Challenges
- Nephrotoxicity Risk Management:Bisphosphonate infusion protocols require specialized nursing protocols and real-time creatinine monitoring that strain staffing in community oncology settings.
- Reimbursement Coding Fragmentation:CMS site-of-care classification distinctions between hospital outpatient and physician-administered drug reimbursement create contracting complexity for multi-channel product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hypercalcemia Treatment Market |
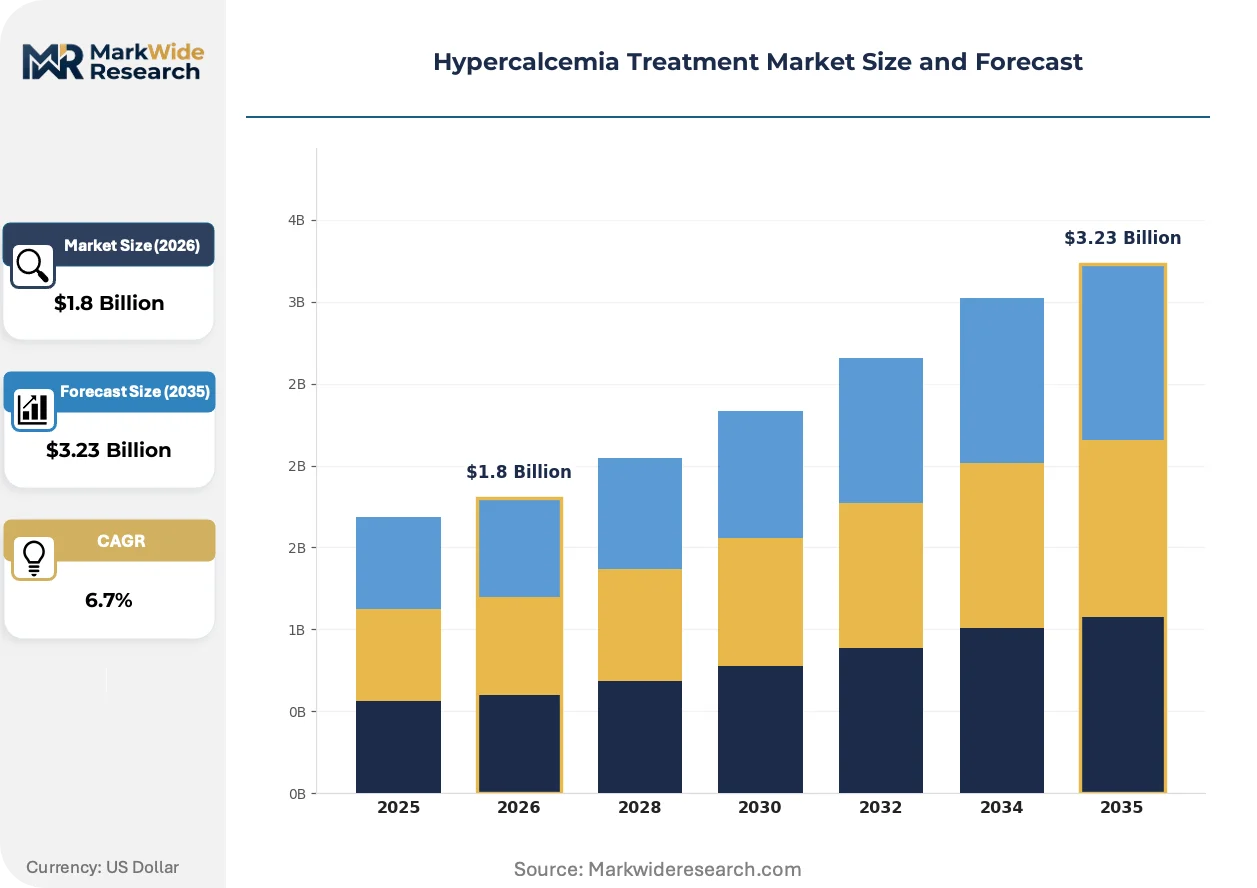
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Calcimimetics, Bisphosphonates, Corticosteroids, Diuretics Administration Route: Oral, Injectable, Intravenous, Subcutaneous Patient Demographics: Elderly, Adults, Pediatrics, Geriatrics Indication: Primary Hyperparathyroidism, Malignancy, Vitamin D Toxicity, Paget's Disease |
| Companies Covered | Amgen Inc., Novartis AG, Pfizer Inc., AbbVie Inc., Sun Pharmaceutical Industries Ltd., Mylan N.V., Dr. Reddy's Laboratories Ltd., Kyowa Kirin Co. Ltd., Cipl Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hypercalcemia Treatment Market Strategic Shifts
Calcimimetic development is pivoting toward receptor selectivity engineering and alternative administration routes that reduce dependence on hospital-based infusion infrastructure.
Next-generation calcimimetics are migrating from pan-calcium-sensing receptor agonism toward allosteric modulators with tissue-selective pharmacology. Nephrology-focused biotech developers are advancing these compounds through Phase II trials with dialysis-sparing endpoints. The technology is migrating from inpatient infusion dependence toward outpatient self-administration models that compress total cost of care.
EMA conditional marketing authorization frameworks for rare disease therapies are accelerating access to calcimimetic innovations in European Union member states. Manufacturers are structuring rolling review submissions that align with FDA breakthrough therapy designation timelines. Oncology clinics in Germany and France are adapting infusion capacity planning around these accelerated approval schedules.
Hospital networks are consolidating hypercalcemia treatment procurement under pharmacy benefit managers with specialty drug expertise. Group purchasing organizations are displacing individual hospital formulary negotiations for intravenous bisphosphonates. This concentration is most visible in United States integrated delivery networks where Medicare reimbursement rate standardization drives vendor consolidation.
Hypercalcemia Treatment Market Segmentation
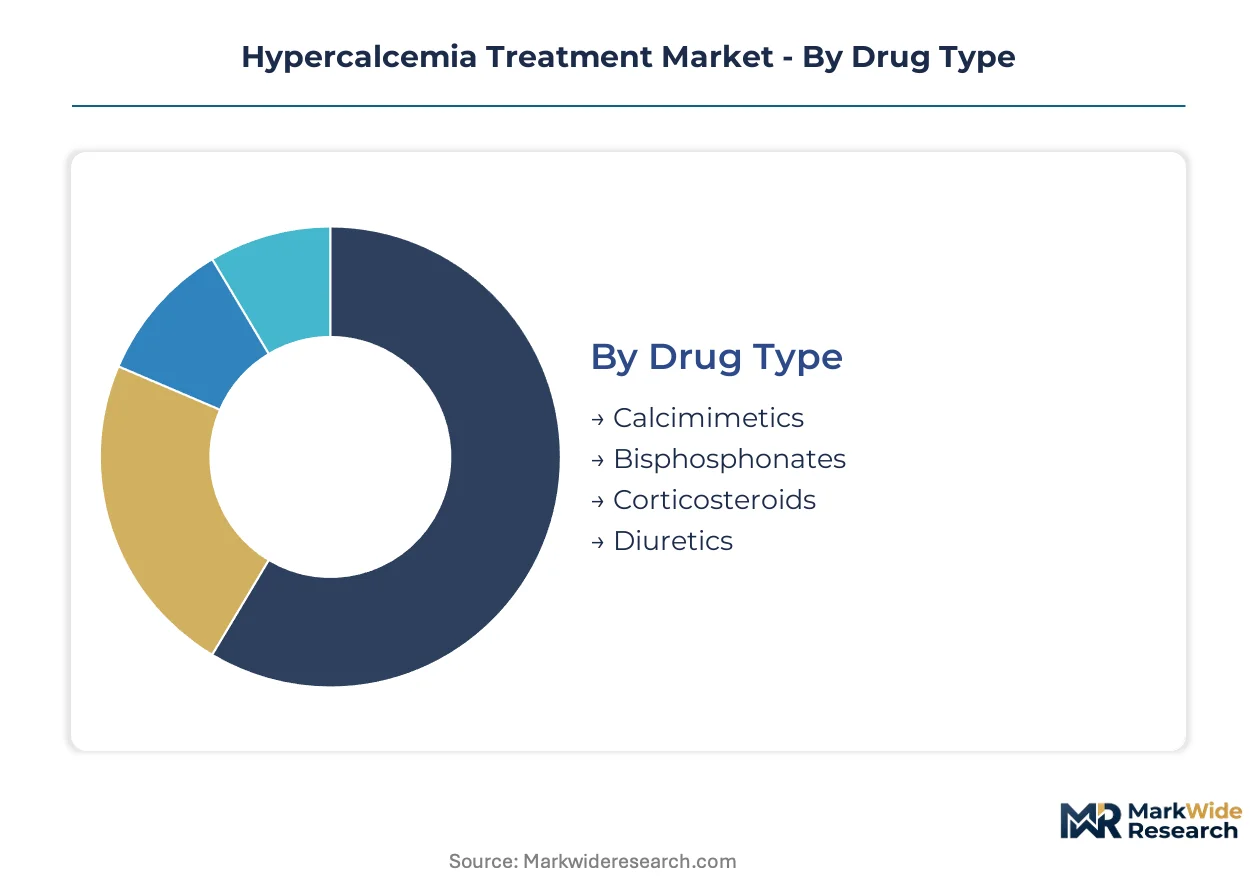
Hypercalcemia treatment segmentation reveals how site-of-care economics and patient acuity reshape commercial strategy across drug classes and delivery modalities. Pharmaceutical manufacturers calibrate portfolio investments based on whether therapies target hospital infusion centers, dialysis clinics, or outpatient self-administration channels.
Drug Type:
Cost tier stratification across pharmacological classes determines reimbursement negotiation leverage and gross-to-net pricing dynamics for manufacturers.
- Calcimimetics:Allosteric modulators of the calcium-sensing receptor suppress parathyroid hormone secretion through precision receptor targeting. Dialysis clinic demand concentrates in the United States where Medicare bundled payments favor oral cinacalcet over intravenous alternatives. The segment is rotating up the share rankings.
- Bisphosphonates:Pyrophosphate analogs inhibit osteoclast-mediated bone resorption through farnesyl diphosphate synthase inhibition. Oncology infusion centers in Germany and France anchor volume for zoledronic acid formulations requiring precise hydration protocols. This category holds installed capacity.
- Corticosteroids:Glucocorticoid therapy reduces intestinal calcium absorption and bone resorption in granulomatous disease-associated hypercalcemia.
- Diuretics:Loop diuretics enhance renal calcium excretion in acute hypercalcemic crises through inhibition of the Na-K-2Cl cotransporter.
Bisphosphonates hold installed capacity. Calcimimetics are rotating up the share rankings.
Administration Route:
Application context—hospital versus home, acute versus chronic—drives route selection and determines site-of-care reimbursement classification.
- Intravenous:Direct vascular delivery enables rapid serum calcium reduction in malignancy-associated emergencies requiring inpatient monitoring. United States hospital outpatient departments capture the deepest margin pools through Medicare reimbursement rate differentials versus physician office settings.
- Oral:Self-administered tablets and capsules extend therapy into chronic outpatient management with reduced staffing overhead. Dialysis clinic channels in Japan favor oral calcimimetics where METI reimbursement frameworks reward patient self-management.
- Injectable:Intramuscular and depot formulations bridge acute and chronic care transitions.
- Subcutaneous:Drug-device combination products enable outpatient administration with pharmacokinetic profiles approaching intravenous bioavailability.
Intravenous holds installed capacity. Subcutaneous is rotating up the share rankings.
Patient Demographics:
Volume concentration across age strata reflects disease etiology patterns and comorbidity burden driving treatment intensity.
- Elderly:Patients aged 65-79 years present with primary hyperparathyroidism and malignancy-associated hypercalcemia requiring polypharmacy management. United States Medicare Part B reimbursement anchors access to intravenous bisphosphonate therapy in this cohort.
- Geriatrics:Adults over 80 years exhibit heightened nephrotoxicity risk requiring modified infusion protocols and enhanced creatinine monitoring. Japanese super-aging demographics concentrate demand for dialysis-sparing calcimimetic regimens.
- Adults:Patients aged 18-64 years with vitamin D toxicity or granulomatous disease represent acute intervention cases.
- Pediatrics:Adolescent primary hyperparathyroidism remains underserved with limited approved therapeutic options and orphan drug development incentives.
Elderly holds installed capacity. Pediatrics is rotating up the share rankings.
Indication:
Customer type segmentation—oncology versus nephrology versus endocrinology practices—shapes prescribing patterns and channel strategy.
- Malignancy:Paraneoplastic hypercalcemia of malignancy demands rapid intervention through intravenous bisphosphonates or calcitonin in hospitalized patients. FDA orphan drug designation pathways compress development timelines for novel calcimimetic entrants targeting this indication.
- Primary Hyperparathyroidism:Autonomous parathyroid hormone secretion drives chronic management through calcimimetics or surgical referral. EMA conditional marketing authorization frameworks accelerate European access to etelcalcetide in dialysis-dependent patients.
- Vitamin D Toxicity:Exogenous or endogenous vitamin D excess requires glucocorticoid therapy and hydration protocols.
- Paget's Disease:Disordered bone remodeling with secondary hypercalcemia responds to bisphosphonate suppression of osteoclast activity.
Malignancy holds installed capacity. Primary Hyperparathyroidism is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical exports supply calcimimetic APIs to dialysis clinic networks across France and the United Kingdom. United States-based biologics manufacturers ship finished etelcalcetide formulations to Japanese hospital consortia under METI-negotiated procurement frameworks.
United States
Medicare Part B reimbursement anchors intravenous bisphosphonate access through hospital outpatient departments. FDA accelerated approval pathways compress development timelines for malignancy-associated hypercalcemia therapies. Oncology infusion centers in Texas and Florida concentrate volume for zoledronic acid protocols requiring specialized nursing staff.
Germany
EMA conditional marketing authorization frameworks accelerate European access to novel calcimimetics. EMA orphan drug designation reduces regulatory capital requirements for developers targeting rare parathyroid disorders. Nephrology-focused hospital networks in Bavaria and North Rhine-Westphalia pilot dialysis-sparing calcimimetic regimens.
Japan
METI reimbursement frameworks reward patient self-management through oral calcimimetic adoption in dialysis clinics. PMDA streamlined review pathways compress approval timelines for parathyroid hormone pathway modulators. Super-aging demographics in Tokyo and Osaka concentrate demand for nephrotoxicity-sparing treatment alternatives.
India
CDSCO manufacturing facility inspections shape API export capacity for bisphosphonate active pharmaceutical ingredients. Generic cinacalcet production clusters in Hyderabad and Ahmedabad supply formulation sponsors across Southeast Asia and Africa. Cost-competitive contract manufacturing attracts mid-tier calcimimetic developers seeking mammalian cell culture partnerships.
Hypercalcemia Treatment Market Competitive Environment
Channel-controlling players compete with product-specialist players across nephrology and oncology treatment settings. The vendor base separates into three tiers: integrated biologics manufacturers with captive mammalian cell culture infrastructure, generic formulation specialists with API backward integration, and regional distributors with dialysis clinic procurement relationships. Competitive positioning depends on site-of-care economics mastery and Medicare reimbursement classification expertise. Dominant moves include strategic partnerships with contract development and manufacturing organizations and portfolio diversification into subcutaneous delivery formats.
Within the integrated biologics tier, Amgen Inc. and Novartis AG exemplify channel-control strategies through nephrology-focused distribution networks. Pfizer Inc. occupies a position exemplifying injectable formulation scale across United States hospital networks. These three entities anchor competitive dynamics through manufacturing infrastructure ownership and site-of-care contracting leverage.
| Leading Market Players |
|---|
| Amgen Inc. |
| Novartis AG |
| Pfizer Inc. |
| AbbVie Inc. |
| Sun Pharmaceutical Industries Ltd. |
| Mylan N.V. |
| Dr. Reddy's Laboratories Ltd. |
| Kyowa Kirin Co. Ltd. |
| Cipl Inc. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in mammalian cell culture facilities across the United States and Germany is compressing calcimimetic API availability while simultaneously elevating pricing power for contract manufacturers with spare bioreactor capacity. This utilization squeeze forces formulation sponsors into longer-term offtake commitments that lock in cost structures across the forecast window.
Pricing Analysis
The pricing gap between first-generation oral cinacalcet, intravenous etelcalcetide, and next-generation allosteric modulators spans three distinct technology tiers. A contract-based long-term offtake model dominates hospital procurement, with price differentiation driven by FDA orphan drug designation status and volume scale commitments. Pricing pressure stems from generic cinacalcet entry compressing oral segment margins. Dialysis clinic buyers exhibit highest price sensitivity due to Medicare bundled payment constraints, while oncology infusion centers demonstrate lowest sensitivity given emergency intervention protocols.
Supply Chain Analysis
Extended payment terms from Indian and Chinese API manufacturers are stabilizing working capital for formulation sponsors facing reimbursement delays. Bisphosphonate active pharmaceutical ingredients concentrate in Hyderabad and Ahmedabad, while calcimimetic biologics production centers on Massachusetts and Bavaria. Raw material dependencies span recombinant protein media, farnesyl diphosphate synthase inhibitors, and calcium-sensing receptor ligands. Single-source vulnerability in zoledronic acid precursor supply creates exposure to CDSCO inspection backlogs. Distribution runs through hospital pharmacy benefit managers with specialty drug expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against calcimimetic substitution eroding bisphosphonate volume in malignancy-associated hypercalcemia as next-generation receptor modulators demonstrate superior dialysis-sparing profiles.
For Market Incumbents: Harden nephrology channel control through exclusive dialysis clinic contracting that locks out calcimimetic competitors. Deepen backward integration into mammalian cell culture capacity to secure API supply against CDSCO disruption. The priority lever rests on site-of-care economics mastery rather than oncology sales force expansion alone.
For New Entrants and Emerging Players: Build out pediatric primary hyperparathyroidism indications where orphan drug incentives and limited competition create favorable pricing corridors. Target subcutaneous drug-device combination formats that shift administration away from hospital infusion centers toward home healthcare. A nephrology-focused go-to-market angle leverages dialysis clinic self-administration demand.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biologics manufacturing infrastructure as mammalian cell culture capacity scarcity elevates asset valuations. Long-term viability centers on developers with captive production facilities and EMA conditional marketing authorization track records. Acquisition targets should display robust subcutaneous delivery pharmacokinetic data packages. The signal to monitor is FDA breakthrough therapy designation velocity for novel calcimimetic entrants.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive mammalian cell culture capacity insulates against Indian and Chinese API supply disruptions. |
| Regulatory Approval Pathway | FDA orphan drug designation compresses development timelines for malignancy-associated hypercalcemia therapies. |
| Pipeline Diversification | Pediatric indication expansion accesses underserved primary hyperparathyroidism populations with premium pricing tolerance. |
| Strategic Partnership | CDMO alliances enable mid-tier developers to compete in parathyroid hormone pathway modulation without facility ownership. |
| Reimbursement Strategy | Medicare Part B classification expertise determines hospital outpatient versus physician-administered drug contracting leverage. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers; and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov, and CMS Medicare reimbursement databases. Bottom-up prescription volume modeling and top-down market sizing triangulated segment estimates across the analysis window.
Forecast inputs considered drug type segmentation by calcimimetic, bisphosphonate, corticosteroid, and diuretic classes; administration route including intravenous, oral, and subcutaneous modalities; and patient demographics spanning elderly, geriatric, adult, and pediatric populations. CAGRs were derived from indication-specific prescription trends and site-of-care reimbursement evolution. Pipeline progression probability and regulatory approval velocity shaped biologics segment projections.
Stress conditions across API supply disruption, CMS reimbursement reclassification, and generic entry timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about clinical trial success rates and regulatory pathway timelines. Macroeconomic contraction, regulatory pathway extension, or calcimimetic technology disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Epiglottitis Treatment Market
Medical Treatment
Pompe Disease Treatment Market
Medical Treatment
Global Rotator Cuff Treatment Market
Medical Treatment
Transplantation Market
Medical Treatment
Iron Deficiency Anemia Treatment Market
Medical Treatment
CINV Treatment Market
Medical Treatment
Peanut Allergy Treatment Market
Medical Treatment
Anorectal Malformation Treatment Market
Medical Treatment
Global Medication Management Market
Medical Treatment
Kidney Stones Management Market
Medical Treatment
Global Thyroid Disorder Treatment Market
Medical Treatment
Thymus Cancer Treatment Market
Medical Treatment
Radiation Therapy Market
Medical Treatment
Encephalitis Treatment Market
Medical Treatment
Familial Hypercholesterolemia Treatment Market
Medical Treatment
Refsum Disease Treatment Market