
 Hyperkalemia Treatment Market | 2026-2036
Hyperkalemia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hyperkalemia Treatment Market Foresight
Active pharmaceutical ingredient production in India is decoupling from traditional European supply chains as domestic fermentation capacity expands. AstraZeneca leverages its sodium zirconium cyclosilicate manufacturing scale to anchor European distribution. CSL Vifor sustains competitive positioning through backward integration into ion-exchange resin production. Ardelyx specializes in novel non-absorbed small molecule mechanisms that differentiate its portfolio from conventional binder therapies.
Hyperkalemia treatment encompasses pharmacological interventions that modulate serum potassium levels through binding, redistribution, or enhanced elimination, with sodium zirconium cyclosilicate functioning as a selective potassium ion trap with a 0.25 mmol/L mean reduction in serum potassium over 48 hours. The primary commercial purpose is preventing fatal cardiac arrhythmias in patients with chronic kidney disease or heart failure on renin-angiotensin-aldosterone system inhibitors. Intravenous delivery modes still dominate emergency settings where rapid potassium reduction is critical, though oral formulations are capturing margin pools in outpatient nephrology. Hospital end users command the largest revenue share due to acute hyperkalemia admissions, while homecare channels are expanding fastest as payer pressure shifts stable patients away from infusion centers.
The FDA's cardiovascular and renal drug division shapes trial endpoints for hyperkalemia therapies, while the EMA's Committee for Medicinal Products for Human Use enforces divergent safety monitoring standards that fragment European launch timelines. Japan's PMDA maintains distinct pharmacokinetic requirements for ethnic bridging studies that delay market entry for foreign developers. Stakeholders must monitor how CMS reimbursement coding for oral potassium binders evolves against hospital-based infusion alternatives.
Market Dynamics
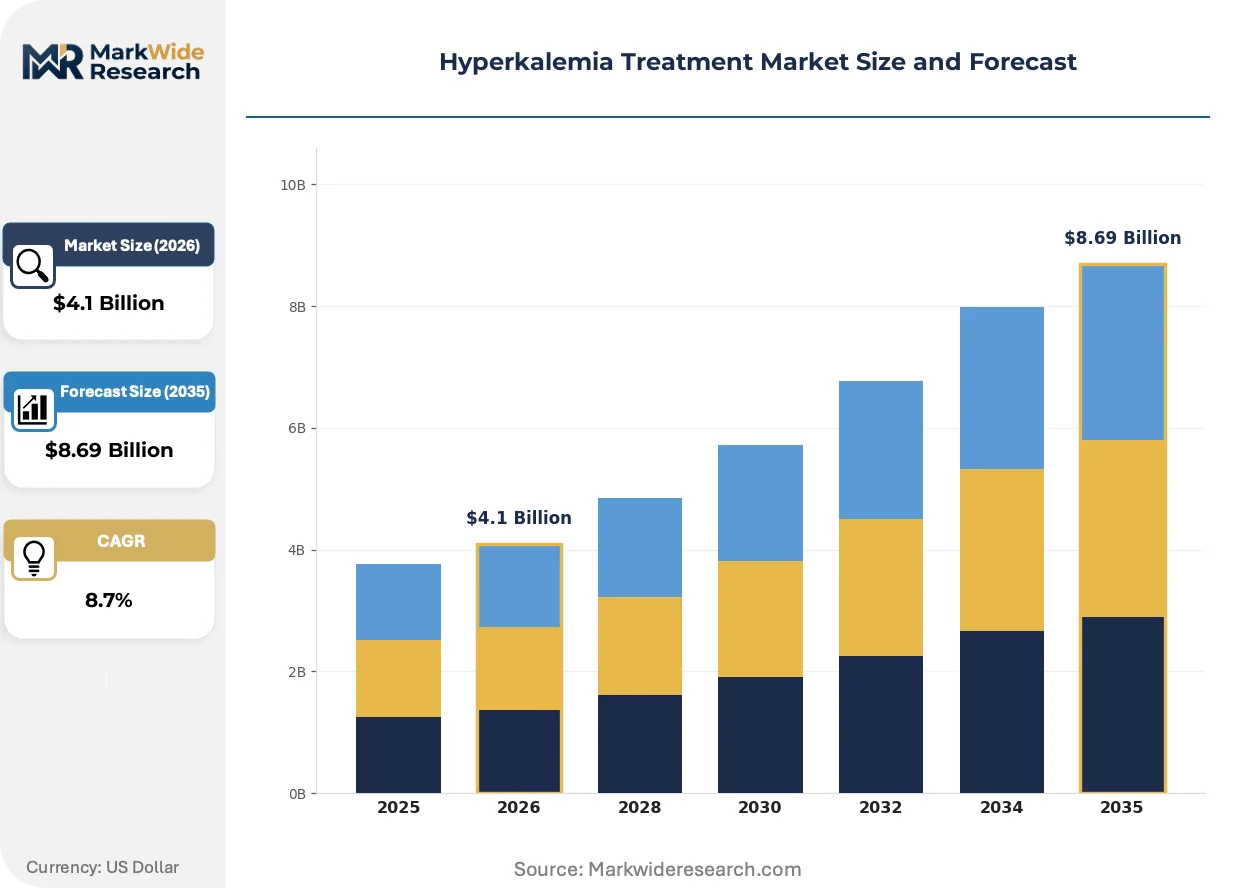
The Hyperkalemia Treatment Market pivots on dialysis infrastructure buildout and payer migration toward oral outpatient therapies, compressing acute care revenue pools while expanding chronic management margins.
Growth Catalysts
- RAAS Inhibitor Expansion:Cardiology guidelines in the United States now mandate broader renin-angiotensin-aldosterone system inhibitor use in heart failure, expanding the addressable patient pool requiring potassium management.
- EMA Orphan Designation Pathways:Accelerated review timelines for rare disease indications in Europe compress development cycles for novel binder mechanisms targeting refractory hyperkalemia subsets.
- Home Hemodialysis Growth:CMS reimbursement parity for home-based renal replacement therapy in the United States creates adjacent demand for patient-administered potassium control agents.
Market Restraints
- Ion-Exchange Resin Supply Concentration:European specialty chemical producers dominate pharmaceutical-grade resin feedstock, exposing formulation capacity to cross-border logistics friction.
- PMDA Bridging Study Requirements:Japan's ethnic pharmacokinetic mandates impose 18-24 month delays on foreign developers seeking market entry, fragmenting launch sequencing.
- Calcium Polystyrene Sulfonate Substitution:Legacy cation exchange resins retain formulary preference in cost-sensitive hospital systems, constraining uptake of higher-efficacy alternatives.
Strategic Opportunities
- Germany's Ambulatory Nephrology Networks:Integrated care contracts between statutory insurers and dialysis chains create dedicated channels for oral binder substitution protocols.
- Wearable Potassium Monitoring Convergence:Integration of continuous ion-selective sensors with smartphone-enabled dosing algorithms opens preventive intervention models ahead of symptomatic onset.
- India's PLI Scheme for APIs:Domestic fermentation capacity expansion under production-linked incentive frameworks enables cost-competitive active pharmaceutical ingredient sourcing for export formulation.
Industry Challenges
- Biostatistician Scarcity in Renal Endpoints:FDA cardiovascular and renal drug division expectations for time-to-event analyses outpace available trial design expertise, extending study timelines.
- Legacy EHR Integration Complexity:Hospital system electronic health record architectures require custom middleware development to embed real-time potassium alert protocols, delaying protocol deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyperkalemia Treatment Market |
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $8.69 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, Diuretics, Sodium Bicarbonate, Calcium Gluconate Delivery Mode: Intravenous, Oral, Subcutaneous, Inhalation End User: Hospitals, Clinics, Homecare, Specialty Centers Application: Cardiology, Nephrology, Emergency Care, Endocrinology |
| Companies Covered | Perrigo Company plc, Baxter International, AstraZeneca, CSL Vifor, OPKO Health, Vifor Pharma, Ardelyx, Fresenius Kabi, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyperkalemia Treatment Market Shifts & Advancements
Oral potassium binder development is diverging from acute intravenous rescue paradigms toward chronic disease management platforms, with formulation science and digital adherence tools converging on outpatient nephrology workflows.
Submicron particle engineering of sodium zirconium cyclosilicate is decentralizing compounding authority from hospital pharmacies to retail specialty distributors. Nephrology clinic chains in the United States are adopting direct-to-patient shipment models for stable chronic kidney disease populations. This shift compresses infusion center revenue while capturing pharmacy benefit manager margin pools previously reserved for acute care settings.
REACH authorization requirements for polymer-based pharmaceuticals are tightening residual monomer thresholds across European manufacturing sites. EMA's Committee for Medicinal Products for Human Use now mandates extended impurity profiling for ion-exchange resins intended for chronic administration. German and French contract manufacturers are responding by retrofitting purification trains ahead of compliance deadlines.
Renal dietitian staffing models are pivoting toward telehealth-enabled medication therapy management, unbundling traditional dialysis center bundled payments. Large United States payers are piloting per-patient-per-month capitation for hyperkalemia-prone populations, replacing fee-for-service potassium testing. This restructuring concentrates purchasing authority with insurer-affiliated pharmacy benefit managers rather than individual nephrology practices.
Hyperkalemia Treatment Market Segmentation
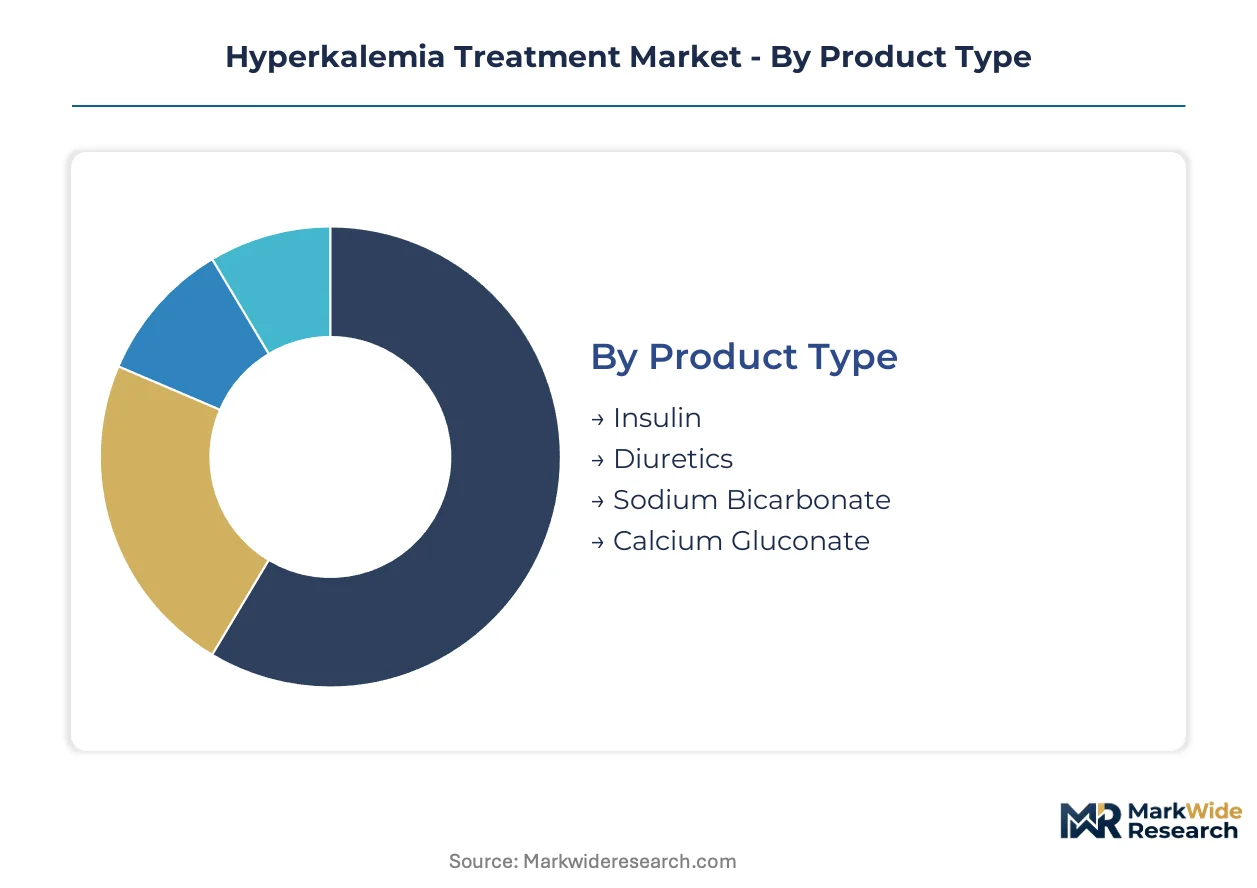
Potassium-binding therapies fragment across four structural dimensions that determine reimbursement pathways and manufacturing scale. Each category reflects distinct supply chain configurations and clinical workflow integration points.
Product Type:
Active pharmaceutical ingredient sourcing concentrates fermentation capacity in India and specialty chemical production in Germany, shaping cost structures across therapeutic categories.
- Insulin:Recombinant human and analog formulations redistribute potassium intracellularly through enhanced Na+/K+-ATPase activity. United States emergency departments command the majority of acute administration volume due to RAAS inhibitor expansion in heart failure protocols.
- Diuretics:Loop and thiazide agents enhance renal potassium excretion through inhibition of sodium-chloride cotransporters. Nephrology clinics in Germany are standardizing oral diuretic protocols within integrated care contracts for chronic kidney disease populations.
- Sodium Bicarbonate:Alkalinizing agent shifts potassium into cells via pH-dependent membrane exchange. Hospital pharmacy compounding dominates supply given intravenous administration requirements.
- Calcium Gluconate:Cardiac membrane stabilizer antagonizes potassium-induced depolarization without altering serum levels. Emergency care settings in Japan maintain formulary preference for immediate arrhythmia prophylaxis.
Diuretics absorb the bulk of installed capacity; insulin is expanding most quickly.
Delivery Mode:
Formulation technology investments cluster around patient-administered platforms that capture outpatient pharmacy benefit manager margins.
- Intravenous:Rapid-acting administration in acute hyperkalemia requires hospital infrastructure and infusion center staffing. United States dialysis chains are consolidating purchasing authority for centralized compounding.
- Oral:Potassium-binding resins and exchange polymers enable chronic disease management outside institutional settings. Germany's statutory insurers are piloting direct-to-patient shipment models for stable nephrology populations.
- Subcutaneous:Emerging delivery format for insulin-based redistribution therapies in pre-hospital emergency medical services. Regulatory pathways remain fragmented across EMA and FDA jurisdictions.
- Inhalation:Experimental albuterol delivery for acute potassium shift in resource-constrained emergency settings. Limited commercial penetration due to bronchodilator primary indication.
Intravenous delivery absorbs the bulk of installed capacity; oral formulations are gaining share fastest.
End User:
Site-of-care migration is restructuring procurement authority from hospital systems toward insurer-affiliated pharmacy networks.
- Hospitals:Emergency department admissions for acute hyperkalemia generate the highest per-episode reimbursement. CMS coding distinctions between observation and inpatient status shape binder selection.
- Clinics:Nephrology and cardiology outpatient settings manage chronic potassium elevation through scheduled monitoring. United States clinic chains are embedding medication therapy management into bundled renal care payments.
- Homecare:Patient-administered oral binders reduce infusion center utilization for stable chronic kidney disease. PMDA reimbursement pathways in Japan lag FDA and EMA in recognizing home-based potassium management.
- Specialty Centers:Dialysis facilities integrate potassium control into renal replacement therapy protocols. India's expanding dialysis infrastructure is adopting cost-optimized calcium polystyrene sulfonate regimens.
Hospitals absorb the bulk of installed capacity; homecare channels show the steepest expansion trajectory.
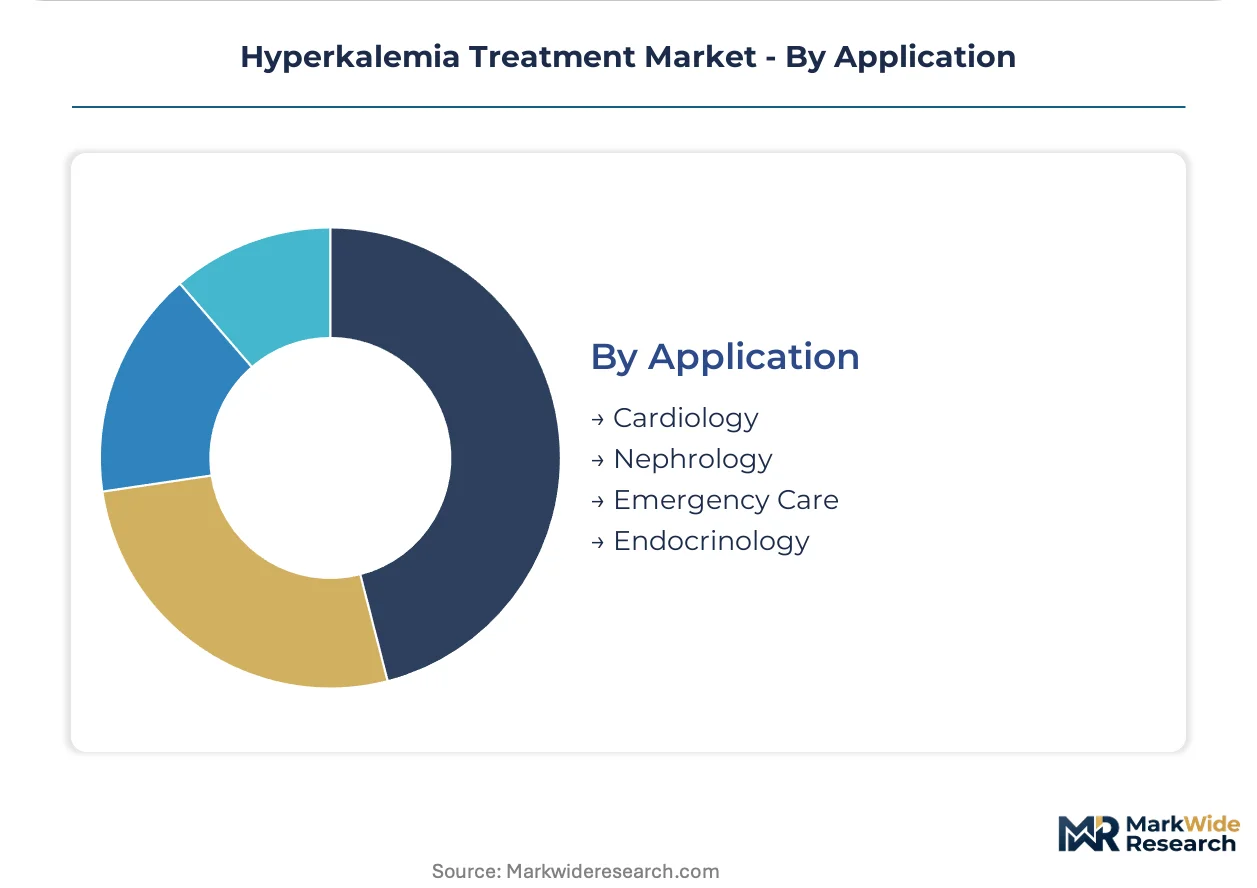
Application:
Clinical specialty alignment determines prescriber targeting and continuing medical education investment priorities.
- Cardiology:Heart failure patients on guideline-directed RAAS inhibitors require systematic potassium surveillance. American College of Cardiology quality metrics are embedding hyperkalemia risk assessment into performance programs.
- Nephrology:Chronic kidney disease progression and dialysis dependence create persistent hyperkalemia burden. German ambulatory nephrology networks are standardizing sodium zirconium cyclosilicate substitution protocols.
- Emergency Care:Acute presentations with electrocardiographic changes demand rapid potassium reduction algorithms. United States emergency medicine residency curricula are emphasizing insulin-glucose combination therapy.
- Endocrinology:Diabetic ketoacidosis and adrenal insufficiency generate secondary hyperkalemia requiring hormonal correction. Limited dedicated binder prescribing compared to organ-specialist counterparts.
Nephrology absorbs the bulk of installed capacity; cardiology is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty chemical feedstock production in Germany and pharmaceutical-grade resin manufacturing in Switzerland anchor European supply chains for potassium-binding therapies. Fermentation capacity expansion in India is decoupling active pharmaceutical ingredient sourcing from traditional Western suppliers. Dialysis infrastructure buildout in Japan and the United States is concentrating demand for chronic disease management platforms.
United States
RAAS inhibitor expansion in heart failure protocols and CMS reimbursement parity for home hemodialysis drive demand for outpatient potassium management. The FDA's cardiovascular and renal drug division shapes trial endpoints through evolving guidance on chronic kidney disease drug development. Nephrology clinic chains in Texas and Florida are embedding direct-to-patient shipment models for stable chronic kidney disease populations.
Germany
Integrated care contracts between statutory insurers and dialysis chains create dedicated channels for oral binder substitution protocols. REACH authorization requirements for polymer-based pharmaceuticals tighten residual monomer thresholds across manufacturing sites. The Rhine-Ruhr metropolitan region hosts contract manufacturers retrofitting purification trains ahead of EMA compliance deadlines.
Japan
PMDA ethnic pharmacokinetic bridging study requirements impose 18-24 month delays on foreign developers seeking market entry. Homecare reimbursement pathways lag FDA and EMA in recognizing patient-administered potassium management. The Kanto region around Tokyo concentrates dialysis center networks adopting cost-optimized calcium polystyrene sulfonate regimens.
India
Domestic fermentation capacity expansion under production-linked incentive frameworks enables cost-competitive active pharmaceutical ingredient sourcing for export formulation. CDSCO regulatory pathways for novel potassium binders remain less prescriptive than FDA or EMA standards. Maharashtra and Gujarat host expanding API production facilities serving European and North American formulation markets.
Switzerland
Specialty chemical producers dominate pharmaceutical-grade ion-exchange resin feedstock, exposing formulation capacity to cross-border logistics friction. Swissmedic maintains distinct pharmacovigilance requirements for chronic administration of polymer-based therapies. The Basel region anchors backward integration into resin production for major therapy developers.
Hyperkalemia Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue novel non-absorbed small molecule mechanisms that differentiate from conventional binder therapies. The market structure concentrates around three strategic archetypes: large-cap pharmaceutical manufacturers with manufacturing scale advantages, mid-cap specialists with backward integration into resin production, and clinical-stage developers with differentiated mechanisms. Dominant competitive moves include capacity expansion in fermentation and specialty chemical production, plus strategic partnerships to secure distribution channels in nephrology and cardiology settings.
Among the named participants, AstraZeneca and CSL Vifor exemplify scale-driven incumbents with integrated manufacturing footprints, while Ardelyx occupies a position within the mechanism-differentiation tier. AstraZeneca leverages sodium zirconium cyclosilicate production scale to anchor European distribution networks. CSL Vifor sustains competitive positioning through captive supply of ion-exchange resin feedstock. Ardelyx represents the clinical-stage archetype pursuing novel therapeutic mechanisms outside conventional binder chemistry.
| Leading Market Players |
|---|
| Perrigo Company plc |
| Baxter International |
| AstraZeneca |
| CSL Vifor |
| OPKO Health |
| Vifor Pharma |
| Ardelyx |
| Fresenius Kabi |
| Sanofi |
| Others |
Supply & Pricing Matrix
Pharmaceutical-grade ion-exchange resin feedstock indices in Switzerland and Germany cascade through formulation tiers, compressing margins on chronic administration therapies while rewarding backward-integrated manufacturers with captive resin production. This raw material cost structure stratifies pricing across emergency intravenous rescue formulations, chronic oral binder maintenance regimens, and compounded hospital pharmacy alternatives.
Pricing Analysis
Service bundling separates acute rescue protocols from chronic disease management platforms, with emergency department administration commanding premium reimbursement unbundled from medication acquisition costs. Three-tier pricing structure across premium sodium zirconium cyclosilicate, standard calcium polystyrene sulfonate, and economy-tier compounded alternatives reflects patent status and manufacturing scale. Cost compression in the standard tier intensifies as Indian API producers expand fermentation capacity and European contract manufacturers retrofit purification trains. Dialysis chains demonstrate highest price sensitivity through centralized purchasing authority, while hospital emergency departments retain lowest sensitivity due to unbundled reimbursement codes.
Supply Chain Analysis
India's production-linked incentive schemes for active pharmaceutical ingredients are reshaping sourcing patterns for fermentation-derived inputs, displacing traditional European supply dependencies. Pharmaceutical-grade resin production concentrates in Switzerland and Germany, with specialty chemical capacity anchored in the Basel and Rhine-Ruhr regions. Raw material dependencies span ion-exchange resin feedstock, sodium zirconium cyclosilicate precursors, and recombinant insulin fermentation substrates. Single-source vulnerability in European resin manufacturing exposes formulation capacity to cross-border logistics friction under REACH authorization requirements. Distribution runs through nephrology clinic chains and dialysis center networks consolidating purchasing authority, with direct-to-patient shipment models emerging in Germany and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hyperkalemia treatment market is transitioning from acute rescue paradigms toward chronic disease management platforms, with oral potassium binder formulations displacing intravenous infusion dependence in stable patient populations.
For Market Incumbents: Hedge against resin feedstock cost volatility through backward integration into ion-exchange polymer production or long-term offtake agreements with Swiss and German specialty chemical producers. Defend formulary positioning against calcium polystyrene sulfonate substitution by embedding real-world evidence generation into integrated care contracts with United States nephrology clinic chains. Capacity addition in Indian API fermentation provides cost insulation against European supply disruption. For New Entrants and Emerging Players: Capture white space in wearable potassium monitoring convergence with smartphone-enabled dosing algorithms, targeting preventive intervention models ahead of symptomatic onset in home hemodialysis populations. Japan's lagging homecare reimbursement pathways represent the most penetrable geography for patient-administered platform introduction. Go-to-market execution should prioritize pharmacy benefit manager partnership structures over direct nephrology practice engagement. For Investors and Strategic Acquirers: The window for entry favors clinical-stage developers with novel non-absorbed small molecule mechanisms differentiated from conventional binder chemistry. Long-term viability centers on platforms spanning acute-to-chronic care continuum with digital adherence integration. Acquisition target archetype: mid-cap specialists with backward integration into resin production and established European distribution infrastructure. The signal to watch is CMS reimbursement coding evolution for oral potassium binders against hospital-based infusion alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | AstraZeneca's sodium zirconium cyclosilicate production anchors European distribution networks against supply disruption. |
| Backward Integration | CSL Vifor's captive ion-exchange resin production insulates margins from Swiss and German feedstock cost volatility. |
| Regulatory Approval Pathway | EMA orphan designation accelerates review timelines for novel binder mechanisms targeting refractory hyperkalemia subsets. |
| Clinical Trial Advancement | FDA cardiovascular and renal drug division guidance on chronic kidney disease endpoints shapes trial design investment priorities. |
| Strategic Partnership | Nephrology clinic chain alliances embed oral binder protocols into bundled renal care payments in Germany and the United States. |
Research Methodology
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone, supplemented by formulary database audits and CMS reimbursement coding records. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers validated demand assumptions and pricing dynamics. Bottom-up and top-down triangulation reconciled patient population estimates with manufacturer shipment data across the analysis window.
Bottom-up modeling anchored volume projections in dialysis center capacity expansion, RAAS inhibitor prescribing trends, and oral binder substitution protocol adoption rates. Top-down validation cross-checked against statutory insurer integrated care contract values and pharmacy benefit manager expenditure patterns. Segmentation dimensions spanned product type, delivery mode, end user, and application, with regional regulatory clusters capturing FDA, EMA, PMDA, and CDSCO pathway divergences. CAGRs were derived from slope analysis of annualized volume trajectories adjusted for patent expiry and generic entry assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PMDA bridging study timeline revisions, CMS reimbursement coding shifts, and ion-exchange resin supply disruption under evolving REACH authorization thresholds. Forecasts reflect documented assumptions regarding RAAS inhibitor guideline expansion, home hemodialysis reimbursement parity, and wearable monitoring technology convergence timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Aspergillosis Treatment Market
Medical Treatment
Hyponatremia Treatment Market
Medical Treatment
Secondary Hyperparathyroidism Treatment Market
Medical Treatment
Phototherapy Treatment Market
Medical Treatment
Spain Hair Transplant Market
Medical Treatment
Anorectal Malformation Treatment Market
Medical Treatment
Systemic Mastocytosis Treatment Market
Medical Treatment
Single Dose Radiotherapy Services Market
Medical Treatment
Microwave Ablation Market
Medical Treatment
Molluscum Contagiosum (MC) Treatment Market
Medical Treatment
Infertility Treatment Market
Medical Treatment
Alagille Syndrome Treatment Market
Medical Treatment
Lice Treatment Market
Medical Treatment
Global Sex Reassignment Surgery Market
Medical Treatment
Achalasia Treatment Market
Medical Treatment
Avian Flu Treatment Market