
 Tetanus Market | 2026-2036
Tetanus Market Size, Share, and Industry Trends Forecast 2026-2036
Tetanus Market Analytics
WHO prequalification standards is recalibrating the cost-of-entry calculus for tetanus vaccine manufacturers, raising compliance thresholds for cold-chain documentation and potency stability. Sanofi leverages its integrated antigen production network to sustain supply security across multiple WHO-prequalified formulations. GlaxoSmithKline anchors its position through deep R&D investment in combination vaccine platforms, while Serum Institute of India dominates volume manufacturing for UNICEF procurement channels.
Tetanus refers to a vaccine-preventable bacterial disease caused by Clostridium tetani toxin, with immunization products typically containing formalin-inactivated tetanus toxoid adsorbed onto aluminum salts to induce protective antibody levels. The tetanus-diphtheria-pertussis combination occupies the largest value share due to universal pediatric schedule inclusion, while tetanus immunoglobulin commands premium positioning in post-exposure settings where rapid passive immunity is clinically required. Intramuscular delivery leads by volume, though intradermal administration is gaining traction in cost-constrained national immunization programs seeking dose-sparing advantages.
FDA, EMA, and WHO prequalification frameworks collectively shape product standards, with WHO PQ serving as the de facto passport for developing-country procurement and FDA compliance unlocking higher-margin US hospital contracts. National regulators in India and Indonesia enforce local cGMP alignment with WHO benchmarks, tightening market access for non-compliant suppliers. Stakeholders must monitor evolving combination vaccine preferences and shifting procurement centralization to anticipate where manufacturing investments will yield sustainable returns.
Market Dynamics
WHO prequalification recalibration is compressing the supplier base by elevating cold-chain documentation and potency stability thresholds, forcing manufacturers to absorb compliance costs or exit developing-country procurement channels entirely.
Growth Catalysts
- Pediatric schedule expansion:National immunization programs in low-income countries are adding booster doses, creating sustained volume demand for tetanus-diphtheria-pertussis combinations through Gavi and UNICEF procurement frameworks.
- Post-exposure prophylaxis protocols:Emergency medicine guidelines now mandate tetanus immunoglobulin for wound management in unvaccinated patients, expanding hospital pharmacy stocking requirements across trauma centers.
- Aluminum adjuvant optimization:Improved adsorption chemistry is reducing antigen dose requirements per vial, enabling dose-sparing intradermal administration in cost-constrained national programs.
Market Restraints
- Plasma-derived immunoglobulin supply:Tetanus immunoglobulin production depends on human plasma fractionation capacity concentrated in US and European collection networks, creating geographic supply vulnerability.
- Formalin inactivation energy costs:Toxoid manufacturing requires sustained temperature-controlled detoxification processes, exposing margins to natural gas and electricity price volatility in European production facilities.
- Single-antigen displacement:Combination vaccines containing tetanus toxoid are displacing standalone tetanus products in procurement tenders, eroding addressable market for monovalent formulations.
Strategic Opportunities
- Microneedle patch delivery:Dissolving microarray technology eliminates cold-chain requirements and enables community health worker administration without needle disposal infrastructure.
- Maternal and neonatal tetanus elimination:WHO-targeted campaigns in remaining endemic districts of sub-Saharan Africa and South Asia create surge procurement windows for tetanus toxoid single-dose presentations.
- Travel medicine clinic networks:Pre-travel consultation protocols for adventure tourism and medical mission work are expanding private-pay booster demand in urban outpatient settings.
Industry Challenges
- Reference standard harmonization:Discrepancies between FDA potency units and WHO International Units complicate multi-market registration dossiers and delay approval timelines.
- Fill-finish capacity allocation:Multi-product vaccine facilities must balance tetanus toxoid campaigns against pandemic preparedness manufacturing commitments, creating scheduling conflicts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tetanus Market |
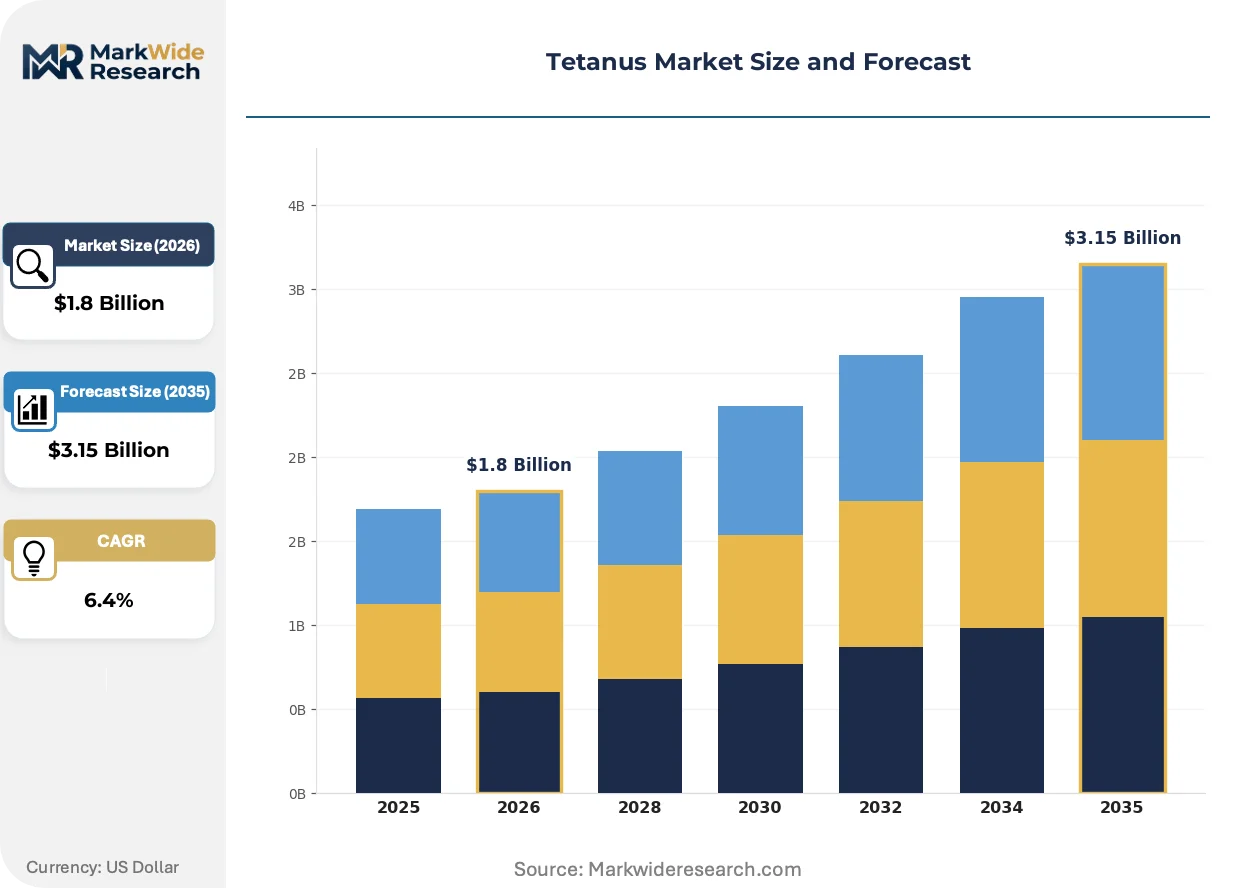
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tetanus Toxoid, Tetanus-Diphtheria Vaccine, Tetanus-Diphtheria-Pertussis Vaccine, Tetanus Immunoglobulin End User: Hospitals, Clinics, Public Health Agencies, Pharmacists Delivery Mode: Intramuscular, Subcutaneous, Oral, Intradermal Application: Prevention, Post-Exposure Prophylaxis, Immunization Programs, Travel Health |
| Companies Covered | Sanofi, GlaxoSmithKline, Merck & Co., Inc., Pfizer Inc., Serum Institute of India, Bharat Biotech, PT Bio Farma, Emergent BioSolutions, Biological E, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tetanus Market Evolving Landscape
Antigen-sparing formulation strategies and novel delivery platforms are compressing per-dose manufacturing costs while expanding access in last-mile distribution settings previously excluded from cold-chain reach.
Intradermal microinjection devices are expanding into national immunization programs seeking dose conservation without efficacy compromise. Bangladesh and Thailand health ministries have piloted ID administration in rural clinics, reducing antigen volume requirements by sixty percent per recipient. This platform is expanding into procurement specifications for Gavi-eligible countries, pressuring manufacturers to validate reduced-dose labeling.
EMA's revised stability testing guidelines for adsorbed vaccines now require real-time potency data at elevated temperature excursions, extending registration timelines for new tetanus-containing combinations. Manufacturers must demonstrate antigen recovery rates following controlled temperature chain exposure, adding six to twelve months to dossier preparation. European suppliers with legacy stability databases retain advantage, while emerging market applicants face retrospective study costs.
Hospital formulary committees now bundle tetanus immunoglobulin procurement with trauma surgery supply contracts, consolidating purchasing authority and compressing supplier margins through volume guarantees. This consolidation replaces fragmented pharmacy-level ordering in US and Western European acute care networks. Academic medical centers with Level I trauma designations are negotiating multi-year sole-source agreements, displacing spot-market purchasing.
Tetanus Market Segmentation
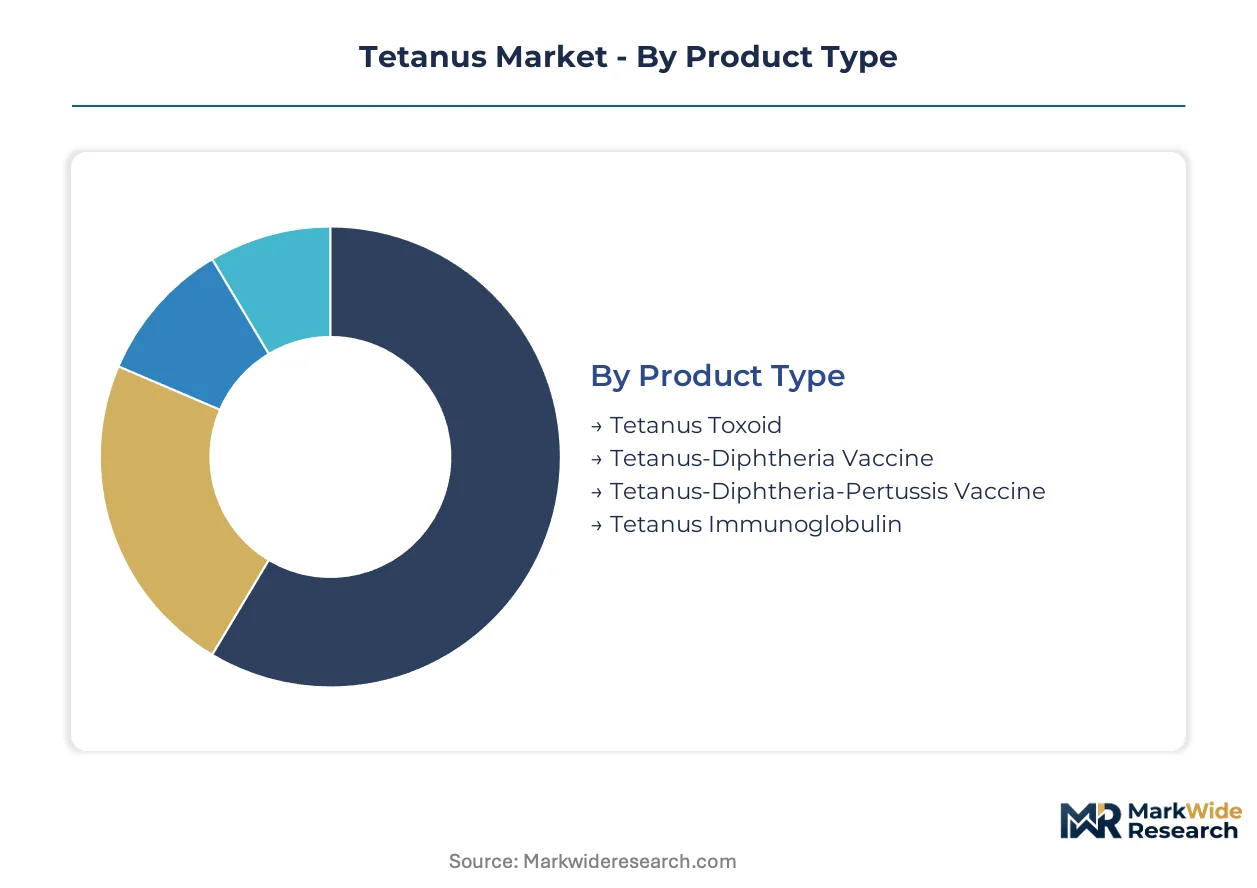
Tetanus market segmentation reveals distinct regulatory pathways and procurement channels that shape manufacturer strategy. Each category carries specific certification burdens from WHO prequalification, FDA approval, or national immunization program inclusion that determine commercial viability.
Product Type:
WHO prequalification applies differentially across product types, with combination vaccines facing the most stringent stability documentation while immunoglobulins require separate plasma-sourcing audits.
- Tetanus Toxoid:Formalin-inactivated antigen adsorbed onto aluminum hydroxide or phosphate adjuvants, supplied as monovalent presentations for maternal neonatal elimination campaigns and booster programs. Demand concentrates in India's public health infrastructure where Serum Institute of India and Bharat Biotech manufacture for domestic EPI schedules and UNICEF export commitments. Single-antigen formulations face procurement displacement as national programs shift toward combination products.
- Tetanus-Diphtheria-Pertussis Vaccine:Triple-antigen combination containing pertussis whole-cell or acellular components alongside tetanus and diphtheria toxoids, representing the standard pediatric immunization platform. WHO prequalification for this formulation unlocks Gavi and PAHO procurement channels; Sanofi and GlaxoSmithKline hold the dominant prequalified positions. Demand is accelerating in sub-Saharan African countries expanding their primary immunization series.
- Tetanus-Diphtheria Vaccine:Adult-formulated combination with reduced diphtheria toxoid content for adolescent and adult boosters.
- Tetanus Immunoglobulin:Human plasma-derived antibody concentrate for immediate passive immunity in wound management.
Leading the category by volume: Tetanus-Diphtheria-Pertussis Vaccine. Growing fastest: Tetanus Immunoglobulin in trauma center pharmacy contracts.
End User:
Procurement centralization varies sharply by end-user type, with public health agencies consolidating tenders while hospital purchasing fragments across formulary committees.
- Public Health Agencies:National immunization programs and Gavi-eligible country ministries operating through centralized procurement with WHO prequalification requirements. UNICEF Supply Division and PAHO Revolving Fund aggregate demand across dozens of countries, creating volume concentration that favors manufacturers with validated cold-chain documentation. India's Universal Immunization Programme represents the single largest national procurement channel.
- Hospitals:Acute care networks managing emergency department wound protocols and trauma surgery prophylaxis, particularly in US Level I trauma centers and European university hospitals. Formulary committees now bundle tetanus immunoglobulin with surgical supply contracts, compressing supplier margins through multi-year volume guarantees. FDA compliance unlocks higher-margin contracts in this channel.
- Clinics:Outpatient settings administering routine boosters and pre-travel consultations.
- Pharmacists:Retail and community pharmacy networks expanding into vaccination services in jurisdictions with scope-of-practice expansions.
Public Health Agencies command the highest procurement volumes. Hospital pharmacy contracts are expanding most quickly as trauma networks consolidate purchasing.
Delivery Mode:
Route selection drives manufacturing fill-finish configuration and cold-chain requirements, with intradermal formats demanding specialized device partnerships.
- Intramuscular:Standard deltoid or anterolateral thigh administration using conventional syringes, dominating pediatric immunization program specifications. Aluminum-adsorbed toxoids require intramuscular deposition for optimal immune response; WHO and national regulators enforce route-specific labeling. This mode anchors UNICEF procurement tenders and represents the baseline manufacturing configuration.
- Intradermal:Dose-sparing administration into the dermal layer using microinjection devices or mantoux technique, reducing antigen volume requirements substantially. Bangladesh and Thailand health ministries have validated this approach in rural clinic pilots, pressuring manufacturers to develop reduced-dose labeling. EMA's revised stability guidelines now require real-time potency data for temperature-exposed intradermal presentations.
- Subcutaneous:Alternative route for specific combination vaccines and immunoglobulin presentations.
- Oral:Experimental and limited-current-use route for mucosal immunization approaches.
Intramuscular delivery leads by absolute dose volume. Intradermal administration is gaining share fastest in Gavi-eligible country specifications.
Application:
Application context determines pricing tier and procurement urgency, with post-exposure protocols commanding premium positioning against routine prevention.
- Prevention:Routine immunization through pediatric schedules and adult booster programs, representing the foundational demand base. National immunization programs in India, Nigeria, and Indonesia anchor volume; WHO prequalification serves as the de facto procurement passport. Combination vaccines displace standalone products in this application.
- Post-Exposure Prophylaxis:Emergency wound management combining tetanus immunoglobulin with toxoid administration for unvaccinated or under-immunized patients. Clinical guidelines from emergency medicine societies mandate hospital pharmacy stocking, creating surge demand tied to trauma center admission patterns. Plasma-derived immunoglobulin supply constraints create geographic vulnerability in this segment.
- Immunization Programs:Campaign-style delivery for maternal neonatal tetanus elimination in remaining endemic districts.
- Travel Health:Pre-departure booster consultations for adventure tourism and medical mission work in urban outpatient settings.
Prevention dominates by dose volume. Post-Exposure Prophylaxis shows the steepest expansion trajectory as trauma networks formalize stocking protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's vaccine special economic zones in Pune and Hyderabad concentrate bulk antigen manufacturing, attracting multinational fill-finish partnerships and WHO prequalification investment. These zones offer tax holidays and duty exemptions that lower cost-of-entry for export-oriented production.
India
Pediatric immunization expansion and maternal-neonatal tetanus elimination campaigns drive procurement volumes. The Universal Immunization Programme mandates domestic sourcing through CDSCO-licensed facilities. Serum Institute of India and Bharat Biotech anchor production clusters in Pune and Hyderabad, supplying UNICEF tenders and African export markets.
United States
Trauma center consolidation and hospital formulary bundling reshape post-exposure prophylaxis demand. FDA enforces cGMP standards for aluminum-adsorbed vaccines and plasma-derived immunoglobulins. Emergent BioSolutions maintains manufacturing presence in Maryland, serving military and civilian stockpile contracts with validated cold-chain infrastructure.
Indonesia
National immunization program scale-up and Gavi transition financing expand combination vaccine procurement. BPOM alignment with WHO prequalification benchmarks tightens import licensing for non-compliant suppliers. PT Bio Farma operates state-owned production in Bandung, supplying domestic EPI schedules and ASEAN export commitments.
France
Travel medicine clinic networks and pre-departure consultation protocols boost private-pay booster demand. ANSM enforces EMA stability guidelines requiring real-time potency data for temperature-exposed presentations. Sanofi leverages integrated antigen production in Lyon to sustain WHO-prequalified formulation supply across Francophone Africa.
Brazil
Adolescent booster program expansion and subnational procurement centralization concentrate purchasing authority. ANVISA harmonizes stability testing with WHO International Units, streamlining multi-market registration for regional suppliers. Butantan Institute in São Paulo manufactures tetanus toxoid for PAHO Revolving Fund distribution across Latin America.
Tetanus Market Competitive Landscape
European and North American producers anchor premium-tier positions through EMA and FDA compliance; Indian manufacturers hold volume-driven procurement channels through WHO prequalification economies. The supplier base compresses as prequalification recalibration elevates cold-chain documentation thresholds. Three archetypes dominate: integrated multinational pharmaceutical conglomerates with antigen production networks; emerging market volume specialists with UNICEF-optimized manufacturing; and state-owned biological institutes serving regional immunization sovereignty. Competitive moves center on combination vaccine platform diversification and microneedle delivery partnerships.
Within the multinational tier, Sanofi and GlaxoSmithKline exemplify integrated antigen production strategies, while Serum Institute of India occupies the volume-specialist position. These three entities represent distinct competitive anchors: Sanofi leverages European manufacturing heritage for WHO-prequalified stability documentation, GlaxoSmithKline anchors R&D-intensive combination platforms, and Serum Institute of India concentrates on UNICEF procurement scale. Their positioning illustrates how regulatory geography and procurement channel specialization segment competitive opportunity.
| Leading Market Players |
|---|
| Sanofi |
| GlaxoSmithKline |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Serum Institute of India |
| Bharat Biotech |
| PT Bio Farma |
| Emergent BioSolutions |
| Biological E |
| Others |
Value Network & Pricing Analysis
Aluminum hydroxide spot pricing volatility cascades through tetanus toxoid manufacturing tiers, compressing margins on economy-grade UNICEF tenders while premium FDA-validated formulations absorb input swings through multi-year supply agreements with trauma networks.
Pricing Analysis
Short lead-time premiums command substantial markups in hospital pharmacy procurement, where Level I trauma centers pay contract rates for immunoglobulin stockpiles against spot-market purchases by smaller acute care facilities. Three-tier pricing structure across premium, standard, and economy levels separates WHO-prequalified combination vaccines from single-antigen presentations and non-prequalified regional suppliers. Cost compression in economy tiers is intensifying because Indian manufacturers compete for UNICEF volume commitments. Public health agencies exhibit highest price sensitivity; private hospital networks demonstrate lowest sensitivity due to bundled surgical supply contracts.
Supply Chain Analysis
Single-source vulnerability sits with human plasma fractionation capacity concentrated in US and European collection networks, constraining tetanus immunoglobulin availability during surge demand periods. Bulk antigen production clusters in India, China, and France, with fill-finish operations distributed across Brazil and Indonesia. Manufacturing draws from formalin, aluminum salts, and specialized cell culture media as core inputs. Tariff exposure on plasma-derived intermediates threatens supply continuity for developing-country procurement channels. Distribution runs through UNICEF Supply Division and PAHO Revolving Fund for public health agencies, with direct manufacturer contracts serving consolidated hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over cold-chain logistics and plasma-sourcing networks determines sustainable margin capture across procurement tiers.
For Market Incumbents: Deepen backward integration into aluminum adjuvant production to insulate margins from commodity volatility, while expanding WHO-prequalified stability documentation to defend against emerging Indian volume specialists. Threat substitution by intradermal microinjection devices demands accelerated device partnership investments. Capacity addition in Pune and Hyderabad vaccine special economic zones anchors procurement scale leverage. For New Entrants and Emerging Players: E-procurement platforms for Gavi-eligible country ministries offer the most penetrable entry vector, bypassing entrenched UNICEF supplier relationships. Target maternal-neonatal tetanus elimination campaigns in sub-Saharan African districts where surge procurement windows lack prequalified supplier coverage. Partner with Bangladesh and Thailand health ministries for intradermal administration validation studies to secure reduced-dose labeling advantages. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale plasma fractionators in Eastern European geographies where collection network modernization lags Western capacity. Long-term viability hinges on securing captive immunoglobulin supply before hospital formulary consolidation completes. Watch WHO prequalification recalibration timelines as the inflection signal for supplier base compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Investment | Unlocks UNICEF and Gavi procurement channels for combination vaccine formulations. |
| Plasma Collection Network Expansion | Secures captive immunoglobulin supply against US and European fractionation bottlenecks. |
| Intradermal Device Partnership | Validates dose-sparing labeling for Gavi-eligible country specifications in Bangladesh pilots. |
| Cold-Chain Infrastructure Buildout | Satisfies EMA stability guidelines requiring real-time potency data at temperature excursions. |
| Combination Platform Diversification | Displaces standalone tetanus products in national immunization program procurement tenders. |
Research Methodology
Independent corroboration across regulatory affairs directors at tetanus toxoid manufacturers, procurement managers at UNICEF Supply Division, and hospital pharmacy directors at Level I trauma centers underwrites the qualitative findings. Primary interviews with Gavi country coordination officers, plasma fractionation specialists, and CDSCO licensing officials combined with secondary validation from WHO prequalification databases, EMA stability guideline submissions, and PAHO Revolving Fund procurement records. Bottom-up demand modeling across pediatric schedule expansion and top-down supply assessment through manufacturing capacity databases ensured triangulation integrity.
Historical reference periods anchored the projection horizon to documented procurement volumes and prequalification timelines across the analysis window. Segmentation dimensions modeled include product type, delivery mode, end-user procurement channel, and regional regulatory cluster. CAGRs derived from volume-weighted average growth trajectories across UNICEF tender awards and hospital formulary contract expansions. Industry-specific forecast inputs incorporated maternal-neonatal tetanus elimination campaign schedules and intradermal administration adoption curves.
Inputs from WHO prequalification status reports and national immunization program procurement disclosures were available through the study window; gaps in real-time hospital formulary contract terms introduce uncertainty bands around post-exposure prophylaxis demand trajectories. Forecasts reflect documented assumptions on regulatory timeline adherence and procurement centralization velocity. Deviation in WHO prequalification recalibration implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Hedgehog Pathway Inhibitors Market
Pharmaceuticals
Anti-Inflammatory Biologics Market
Pharmaceuticals
Lansoprazole API Market
Pharmaceuticals
Latin America Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Estonia Pharmaceutical Market
Pharmaceuticals
North America Adenomyosis Drugs Market
Pharmaceuticals
Inhalable Drug Market
Pharmaceuticals
Europe Sodium-Dependent Glucose Cotransporter 2 Market
Pharmaceuticals
Global Oxytocic Pharmaceuticals Market
Pharmaceuticals
Middle East and Africa Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Articaine Hydrochloride Market
Pharmaceuticals
Famotidine Market
Pharmaceuticals
Adapalene Market
Pharmaceuticals
Dyslipidemia Therapeutics Market
Pharmaceuticals
Global Tetanus Toxoid Vaccine Market
Pharmaceuticals
Global Acne Medication Market