
 Diphtheria Tetanus Pertussis Vaccine Market | 2026-2036
Diphtheria Tetanus Pertussis Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Diphtheria Tetanus Pertussis Vaccine Market Insights
Aftermarket service revenue from cold-chain logistics and vaccination program support is rewriting how suppliers capture lifetime value from each dose. GSK plc leverages its platform licensing strength across multiple combination formats to sustain recurring institutional contracts. Serum Institute of India Pvt. Ltd. anchors global supply security through massive manufacturing scale in Pune. Sanofi competes on pediatric formulation specialization, particularly in hexavalent and pentavalent combinations.
Diphtheria Tetanus Pertussis vaccines are formaldehyde-inactivated or toxoid-based biological preparations administered primarily to induce active immunity against Corynebacterium diphtheriae, Clostridium tetani, and Bordetella pertussis, with aluminum salts serving as standard adjuvants to enhance immunogenicity. Their primary commercial purpose is population-level disease prevention through routine immunization programs and outbreak response stockpiles. Combination vaccines dominate procurement volumes because health systems prioritize antigen bundling to reduce injection burden and cold-chain complexity. Pediatric care channels represent the fastest-growing end-user segment as national programs extend reach into rural clinics. Intramuscular administration remains the standard route, though intranasal delivery research is gaining traction in adolescent trial populations.
FDA batch release protocols, WHO prequalification standards, and EMA good manufacturing practice inspections collectively shape product standards, facility investment requirements, and market access timelines for DTP vaccine manufacturers. India's CDSCO and the country's PLI scheme for pharmaceuticals are accelerating domestic capacity expansion while tightening quality benchmarks for export eligibility. Stakeholders must monitor how evolving WHO policy recommendations on pertussis antigen composition will redirect R&D spending and procurement specifications across national immunization programs.
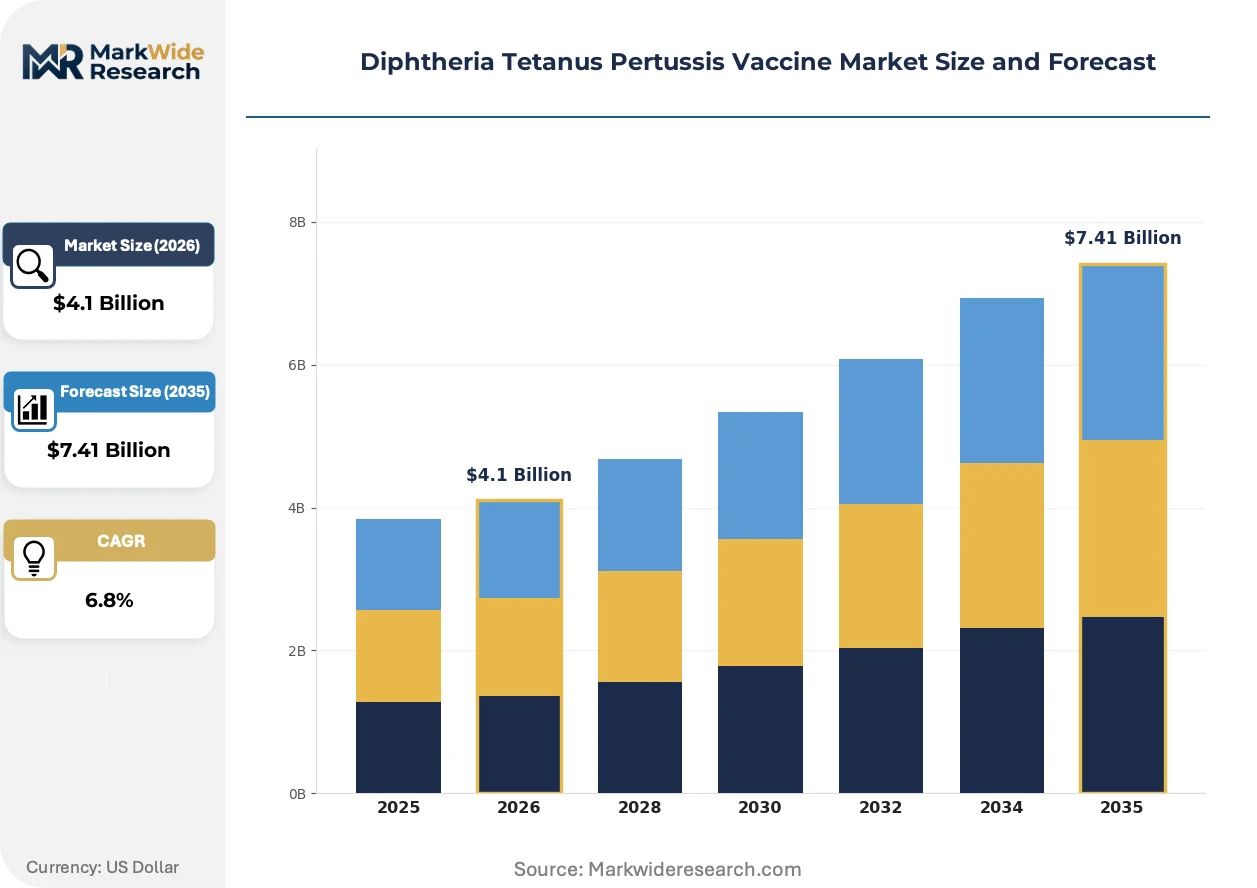
Market Dynamics
Combination vaccine formats are compressing procurement cycles as health systems prioritize antigen bundling over standalone doses, forcing manufacturers to reconfigure platform licensing strategies and cold-chain logistics networks simultaneously.
Growth Catalysts
- WHO Prequalification Pathways:Streamlined assessment protocols for combination vaccines are accelerating market access timelines for suppliers targeting low- and middle-income country immunization programs.
- India's PLI Scheme:Domestic pharmaceutical manufacturing incentives are expanding Pune-based production capacity and tightening export quality benchmarks for regional supply security.
- Pediatric Care Expansion:Rural clinic integration into national immunization schedules is extending dose delivery infrastructure into previously underserved districts.
Market Restraints
- Aluminum Salt Input Volatility:Adjuvant raw material sourcing concentration creates formulation cost instability for toxoid-based biological preparations.
- Cold-Chain Infrastructure Gaps:Last-mile refrigeration deficits in tropical climates limit effective vaccine potency preservation during distribution.
- Pertussis Antigen Composition Uncertainty:Evolving WHO policy recommendations on acellular versus whole-cell formulations create R&D redirection risk and procurement specification ambiguity.
Strategic Opportunities
- Intranasal Delivery Development:Adolescent trial populations for non-intramuscular administration routes offer differentiation potential in booster dose segments.
- Aftermarket Service Unbundling:Cold-chain logistics and vaccination program support contracts enable recurring revenue capture beyond per-dose sales.
- Hexavalent Format Adoption:Expanded antigen bundling in pediatric formulations reduces injection burden and commands premium positioning in institutional procurement.
Industry Challenges
- Batch Release Protocol Complexity:FDA, EMA, and WHO inspection synchronization demands specialized regulatory affairs talent and extended facility qualification timelines.
- Platform Licensing Integration:Multi-format combination vaccine development requires coordination across toxoid, conjugate, and recombinant protein manufacturing competencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diphtheria Tetanus Pertussis Vaccine Market |
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inactivated Vaccine, Combination Vaccine, Monovalent Vaccine, Pentavalent Vaccine End User: Hospitals, Clinics, Pediatric Care, Public Health Agencies Administration Route: Intramuscular, Subcutaneous, Oral, Intranasal Age Group: Infants, Children, Adolescents, Adults |
| Companies Covered | Serum Institute of India Pvt. Ltd., Boryung Biopharma Co., Ltd., GSK plc, Bio Farma, BioNet-Asia, Sanofi, Wuhan Institute of Biological Products Co., Ltd., Biological E Limited, Merck & Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diphtheria Tetanus Pertussis Vaccine Market Trends and Innovations
Antigen bundling architectures and delivery route diversification are compressing traditional dose administration models while regulatory convergence pressures reshape manufacturing investment priorities across supplier networks.
Adjuvant formulation advances incorporating novel immunostimulatory compounds are enhancing immunogenicity profiles for acellular pertussis components. Pediatric specialists in European and North American markets are adopting these enhanced formats for primary series completion. Conventional aluminum-only adjuvant systems are rendering obsolete in premium procurement segments where efficacy differentiation commands contract preference.
EMA good manufacturing practice inspections are harmonizing facility standards with WHO prequalification benchmarks, collapsing previously separate compliance pathways. This convergence reduces duplicate audit burdens for suppliers serving multiple regulatory jurisdictions. Indian manufacturers targeting CDSCO export certification are responding by consolidating quality management systems under unified documentation frameworks.
Institutional buyers are consolidating procurement through long-term supply agreements that bundle dose delivery with cold-chain infrastructure provision. National immunization programs in South Asia and sub-Saharan Africa are displacing spot-market purchasing with performance-linked contracts. This transition is most visible in India's Universal Immunization Programme, where domestic manufacturers now compete on integrated service scope rather than per-dose pricing alone.
Diphtheria Tetanus Pertussis Vaccine Market Segmentation
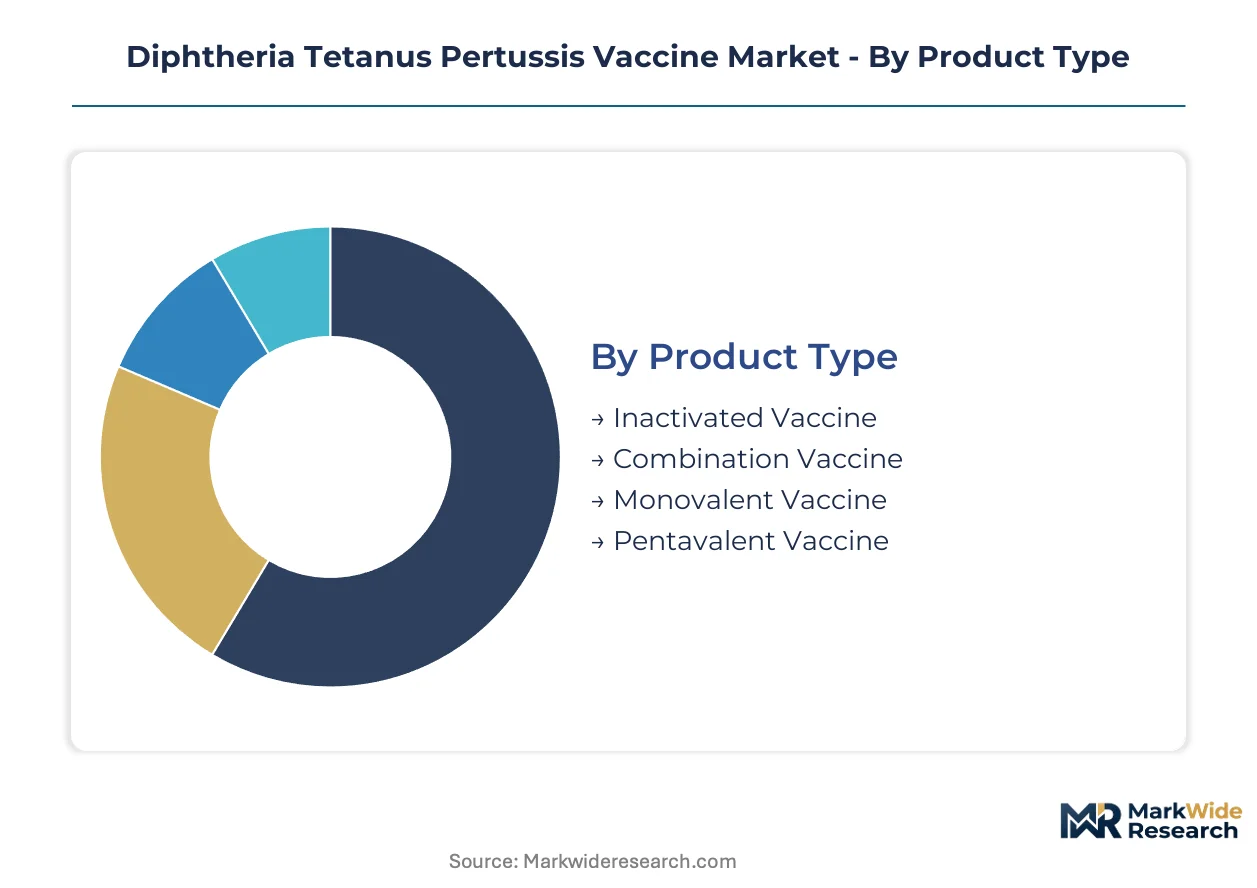
DTP vaccine procurement stratifies sharply across product formats, with combination architectures commanding institutional preference for injection burden reduction. Age-group targeting and administration route specifications further differentiate supplier positioning across national immunization programs and private pediatric channels.
Product Type:
Combination formats turn procurement cycles fastest as health systems consolidate antigens, while monovalent stocks rotate more slowly for outbreak response and specialized indications.
- Combination Vaccine:Bundles diphtheria, tetanus, and pertussis antigens with optional Hib, hepatitis B, or polio components in single-dose presentations. India's Universal Immunization Programme and Gavi-aligned procurement channels concentrate demand here, driven by cold-chain simplification mandates and injection burden reduction targets in rural clinic networks.
- Pentavalent Vaccine:Incorporates DTP with hepatitis B and Hib antigens in five-valent formulations standard across WHO prequalified supplier portfolios. Sub-Saharan African national programs and Southeast Asian immunization schedules anchor procurement volumes, constrained by aluminum adjuvant formulation stability requirements during tropical distribution.
- Inactivated Vaccine:Formaldehyde-inactivated bacterial preparations using whole-cell or acellular pertussis fractions remain foundational for primary series completion.
- Monovalent Vaccine:Standalone diphtheria, tetanus, or pertussis doses serve outbreak response stockpiles and specialized revaccination protocols.
Combination vaccines dominate installed base. Pentavalent formats are where expansion concentrates.
End User:
Pediatric channels operate on accelerated replenishment cycles compared to institutional stockpiles, while public health agencies manage multi-year supply agreements with extended delivery horizons.
- Pediatric Care:Dedicated pediatric clinics and primary care networks administer scheduled doses across primary series and booster intervals. India's rural clinic integration and sub-Saharan African community health worker programs concentrate demand expansion, shaped by last-mile cold-chain infrastructure investments and caregiver accessibility improvements.
- Public Health Agencies:National immunization programs, Gavi procurement mechanisms, and WHO strategic stockpile managers coordinate population-level dose distribution. India's Ministry of Health and Family Welfare, Nigeria's National Primary Health Care Development Agency, and Indonesia's Ministry of Health anchor procurement scale, constrained by budget allocation cycles and donor funding volatility.
- Hospitals:Tertiary facilities manage birth-dose administration and adverse event management requiring inpatient capacity.
- Clinics:General practice and community health centers handle routine immunization catch-up and traveler vaccination services.
Pediatric Care commands the steepest expansion trajectory. Public Health Agencies retain volume concentration.
Administration Route:
Intramuscular delivery dominates current procurement with established cold-chain protocols, while intranasal development programs promise route diversification for adolescent booster segments.
- Intramuscular:Deltoid or anterolateral thigh injection remains standard for all age groups across inactivated and combination formulations. WHO prequalified supply chains and FDA batch release protocols validate this route universally, with aluminum-adjuvanted suspensions requiring strict temperature control during transport.
- Intranasal:Non-invasive mucosal delivery systems under adolescent trial evaluation target needle-averse populations and potential mucosal immunity enhancement. European and North American booster dose markets concentrate development investment, constrained by formulation stability and spray device standardization challenges.
- Subcutaneous:Alternative injection depth for specific combination products and patient populations with muscle mass limitations.
- Oral:Experimental delivery research for pertussis components remains preclinical with no commercial procurement traction.
Intramuscular administration anchors supply security. Intranasal development is where differentiation investment flows.
Age Group:
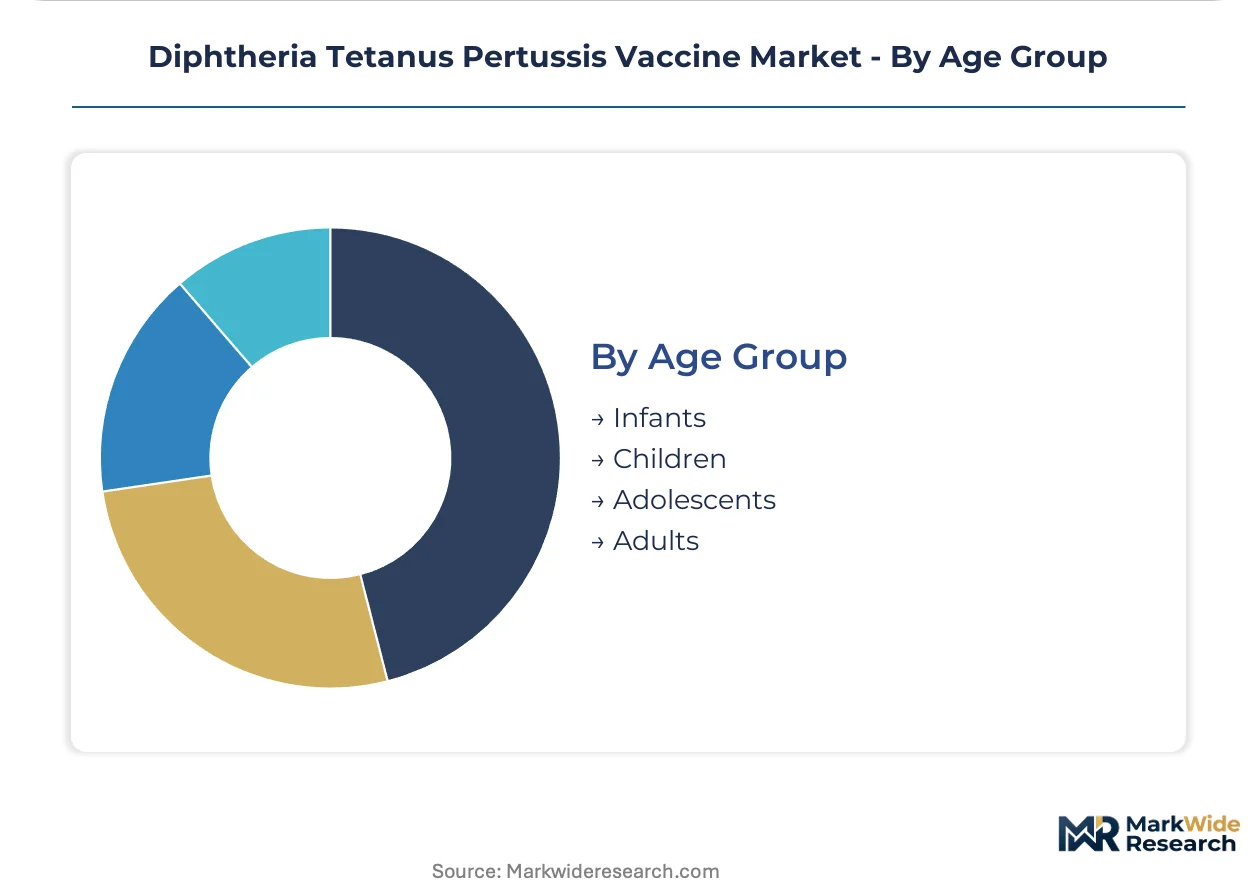
Infant dosing schedules drive highest-frequency procurement with six-week, ten-week, and fourteen-week intervals, while adult segments operate on decennial tetanus booster cycles.
- Infants:Birth through twelve months receive primary series doses at prescribed intervals with highest per-capita dose density. India's 26 million annual births and Nigeria's expanding immunization coverage anchor demand concentration, driven by pentavalent format adoption in national programs.
- Adolescents:Ten-through-nineteen-year populations receive Tdap boosters and catch-up doses in school-based and private clinic channels. US adolescent immunization platforms and European school health programs concentrate procurement, shaped by acellular pertussis antigen preference and combination booster convenience.
- Children:One-through-nine-year schedules include primary series completion and preschool boosters.
- Adults:Decennial tetanus revaccination and travel medicine indications sustain lower-frequency demand.
Infants dominate dose volume. Adolescents are where format innovation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters heavily in India, where Pune-based facilities supply WHO prequalified doses across Gavi-aligned procurement channels. Serum Institute of India Pvt. Ltd. and Biological E Limited anchor this concentration, supported by CDSCO export certification pathways and the PLI scheme's domestic capacity incentives.
India
Universal Immunization Programme expansion drives dose volumes through rural clinic networks, with Maharashtra's Pune district hosting the dominant manufacturing cluster. CDSCO tightened quality benchmarks for export eligibility under 2023 amendments, accelerating consolidation among domestic suppliers. Serum Institute of India Pvt. Ltd. operates at massive scale from its Hadapsar facility, supplying pentavalent formats across sub-Saharan African national programs.
United States
FDA batch release protocols shape procurement specifications for acellular pertussis boosters in adolescent and adult segments. The Inflation Reduction Act's pharmaceutical pricing provisions indirectly pressure institutional contracting structures for combination vaccines. Massachusetts and Pennsylvania host formulation specialists serving pediatric care networks and school-based immunization platforms.
France
Sanofi anchors hexavalent and pentavalent development from its Lyon-based biologicals division, targeting European pediatric care premium positioning. EMA good manufacturing practice inspections harmonize with WHO benchmarks, reducing duplicate audit burdens for export-oriented production. The Auvergne-Rhône-Alpes region concentrates adjuvant formulation expertise and clinical trial infrastructure for next-generation delivery routes.
Indonesia
Bio Farma's state-owned manufacturing serves national immunization schedules across the archipelago's 17,000 islands, constrained by last-mile cold-chain gaps. The Ministry of Health coordinates Gavi transition financing as the country moves from donor-supported to self-financed procurement. Bandung hosts the primary production complex, with distribution challenges in Papua and eastern provinces driving investment in passive cooling technologies.
South Korea
Boryung Biopharma Co., Ltd. represents domestic manufacturing capability targeting regional export markets in Southeast Asia. MFDS accelerated combination vaccine approval pathways in 2022, aligning review timelines with WHO prequalification standards. The Seoul Capital Area concentrates regulatory affairs expertise and clinical research organizations supporting intranasal delivery development programs.
Diphtheria Tetanus Pertussis Vaccine Market Competitive Landscape
Platform licensors and manufacturing-scale specialists split the market into distinct competitive territories. Consolidation pressures operate selectively: institutional procurement favors suppliers with integrated cold-chain service capabilities, while R&D-intensive segments reward adjuvant formulation differentiation. Three archetypes dominate—multinational pharmaceutical conglomerates with combination vaccine platforms, emerging market manufacturers leveraging cost-optimized scale, and regional specialists targeting niche delivery formats. Capacity expansion and strategic platform licensing represent the primary competitive moves, with aftermarket service unbundling emerging as a secondary vector for recurring revenue capture.
Within the manufacturing-scale tier, Serum Institute of India Pvt. Ltd. and Biological E Limited exemplify Pune-based production concentration serving WHO prequalified procurement channels. GSK plc occupies a position among platform licensors with multi-format combination capabilities spanning toxoid and conjugate manufacturing competencies. Sanofi represents formulation specialization in hexavalent pediatric presentations, anchoring premium-tier positioning across European and North American institutional contracts.
| Leading Market Players |
|---|
| Serum Institute of India Pvt. Ltd. |
| Boryung Biopharma Co., Ltd. |
| GSK plc |
| Bio Farma |
| BioNet-Asia |
| Sanofi |
| Wuhan Institute of Biological Products Co., Ltd. |
| Biological E Limited |
| Merck & Co., Inc. |
| Others |
Pricing and Supply Chain Analysis
Pune's manufacturing cluster concentration funnels pricing power toward Serum Institute of India and Biological E Limited, while downstream margin pools concentrate with institutional buyers bundling cold-chain services into long-term performance contracts.
Pricing Analysis
WHO prequalification standards dictate the pricing tier structure across pentavalent and hexavalent formats, separating Gavi-aligned procurement volumes from premium pediatric formulations in private European and North American channels. Price differentiation rests on adjuvant formulation sophistication and integrated service bundling rather than per-dose commodity trading. Cost compression in economy-tier pentavalent supply is intensifying because India's PLI scheme accelerates domestic capacity expansion. Public health agencies exhibit highest price sensitivity through consolidated tender mechanisms, while private pediatric clinics demonstrate lowest sensitivity for enhanced acellular pertussis presentations.
Supply Chain Analysis
Aluminum salt feedstock sourcing draws from bauxite processing concentrations in Australia, Guinea, and China, with formulation stability requirements tethering adjuvant supply security to tropical distribution viability. Corynebacterium diphtheriae and Clostridium tetani toxoid production rests on specialized fermentation capacity clustered in India, France, and South Korea. Single-source vulnerability permeates the pertussis antigen tier, where acellular component suppliers face WHO policy uncertainty on whole-cell reversion. Distribution runs through WHO prequalified cold-chain networks extending from Pune to sub-Saharan African national immunization programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Diphtheria Tetanus Pertussis Vaccine Market is recovering from pandemic-era immunization backlogs, with pediatric care expansion and Gavi replenishment cycles providing the cyclical momentum.
For Market Incumbents: Build regulatory moat depth through synchronized FDA-EMA-WHO qualification pathways that emerging manufacturers cannot replicate within viable investment horizons. Serum Institute of India anchors this defensive posture by consolidating Pune-based capacity under unified quality management systems. Threat vectors concentrate in intranasal delivery platforms that could displace intramuscular administration for adolescent boosters. Priority leverage sits with backward integration into aluminum adjuvant production to buffer raw material volatility. For New Entrants and Emerging Players: Pursue white-space positioning in intranasal formulation development for European and North American adolescent booster segments, where needle-averse populations and mucosal immunity research create penetrable demand pockets. Southeast Asian national immunization programs transitioning from Gavi support offer secondary entry terrain through cost-optimized combination formats. Go-to-market execution should anchor on MFDS-accelerated approval pathways in South Korea as a regional regulatory beachhead. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional manufacturers possessing CDSCO export certification but lacking integrated cold-chain service capabilities. Long-term viability over the mid-decade horizon favors platform licensors with multi-format toxoid and conjugate manufacturing competencies. The signal to watch is WHO policy resolution on acellular versus whole-cell pertussis composition, which would redirect R&D capital allocation and procurement specifications simultaneously.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway Advancement | Accelerates market access for Pune-based manufacturers serving Gavi procurement channels. |
| Intranasal Delivery Clinical Development | Positions suppliers for adolescent booster differentiation in European and North American markets. |
| Hexavalent Format Manufacturing Scale-Up | Captures premium procurement positioning through expanded antigen bundling in pediatric formulations. |
| Cold-Chain Service Integration | Transforms transactional dose sales into recurring revenue through performance-linked institutional contracts. |
| Adjuvant Formulation Backward Integration | Insulates margin stability against aluminum salt input volatility in toxoid-based production. |
Research Methodology
Cross-validation between regulatory filing databases and procurement contract registries anchors the qualitative findings on manufacturer positioning and institutional buyer behavior. Primary interviews with vaccine development executives, regulatory affairs leads at CDSCO and EMA, national immunization program managers, and hospital procurement directors combined with secondary analysis of WHO prequalification records, Gavi disbursement reports, FDA batch release protocols, and EMA GMP inspection documentation. Bottom-up dose volume modeling triangulates against top-down procurement expenditure tracking across national program budgets.
Calibration against historical immunization coverage trajectories and Gavi transition financing schedules shapes the projection framework across the analysis window. Segmentation dimensions encompass product format architecture, end-user channel structure, administration route technology, and age-group targeting strategy. CAGRs derive from dose demand elasticity modeling tied to birth cohort projections and booster interval compliance patterns. Forecast inputs incorporate PLI scheme capacity incentives and evolving WHO pertussis antigen policy scenarios.
Macroeconomic conditions sit as an overlay; deviation in donor funding flows, currency volatility in import-dependent markets, or aluminum commodity price spikes would shift the trajectory. Forecasts reflect documented assumptions on immunization program expansion rates and regulatory convergence timelines. Cross-checking against WHO Strategic Advisory Group of Experts immunization coverage benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Otic Drugs Market
Pharmaceuticals
Global Chickenpox Vaccine Market
Pharmaceuticals
Retinal Drugs Market
Pharmaceuticals
Tumor Necrosis Factor Alpha Inhibitors Market
Pharmaceuticals
Global Plasma Derived Therapy Market
Pharmaceuticals
Asia-Pacific Aneurysmal Subarachnoid Hemorrhage Drugs Market
Pharmaceuticals
Tuberculosis Vaccine Treatment Market
Pharmaceuticals
Global Antipyretic Drugs for Children Market
Pharmaceuticals
Cryptococcosis Therapeutics Market
Pharmaceuticals
Synthetic Drugs Market
Pharmaceuticals
Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Injectable Cytotoxic Drugs Market
Pharmaceuticals
Dyslipidemia Therapeutics Market
Pharmaceuticals
Acetaminophen Injection Market
Pharmaceuticals
Global Caspofungin Market
Pharmaceuticals
Nasal Vaccines Market